
 Oil Storage Terminal Market | 2026-2036
Oil Storage Terminal Market Size, Share, and Industry Trends Forecast 2026-2036
Oil Storage Terminal Market Intelligence
Specialized welding and corrosion engineering talent is reorganizing construction timelines across the oil storage terminal sector. Enbridge Inc. leverages its North American pipeline network to anchor integrated storage-to-transport offerings. Royal Vopak dominates international tankage with specialized terminals in chemical and biofuel hubs. Kinder Morgan sustains Gulf Coast storage leadership through its extensive Houston Ship Channel footprint.
An oil storage terminal is a fixed facility designed to receive, store, and distribute crude oil and refined petroleum products, typically featuring welded steel tanks with capacity ratings from 10,000 to over 500,000 barrels and incorporating fire suppression, vapor recovery, and secondary containment systems. Its primary purpose is to balance supply chain timing between production, marine transport, and downstream refining or distribution. Above ground steel tankage leads global installed capacity due to lower capital cost and faster deployment, while floating storage represents the fastest-growing segment as traders exploit contango structures and offshore logistics flexibility. Underground salt cavern storage anchors strategic petroleum reserve programs where energy security mandates long-duration inventory holding.
The US EPA enforces Spill Prevention, Control, and Countermeasure rules that mandate secondary containment and integrity testing for above ground tanks exceeding threshold volumes. The EU Industrial Emissions Directive and REACH frameworks impose vapor recovery and material traceability requirements on European terminal operators. India's Petroleum and Natural Gas Regulatory Board sets technical standards for cross-country storage and pipeline connectivity. Stakeholders must monitor how carbon border adjustments and methane intensity benchmarks reshape terminal investment criteria and asset valuation models.
Market Dynamics
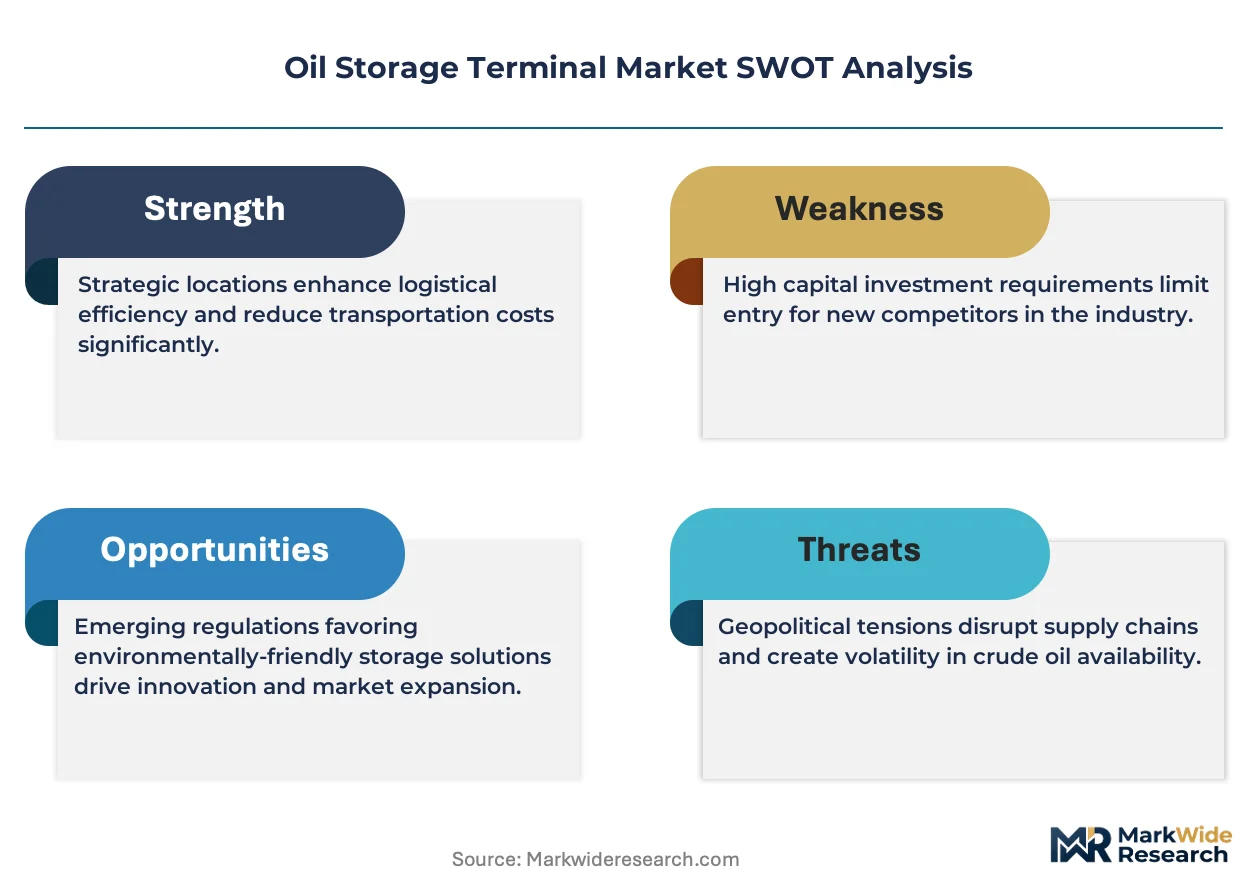
Refinery expansion across Asia-Pacific and tightening methane emission standards are forcing terminal operators into accelerated retrofit cycles. Specialized welding and corrosion engineering talent shortages are compressing construction timelines and inflating project costs.
Growth Catalysts
- Strategic Petroleum Reserve Programs:India's Petroleum and Natural Gas Regulatory Board mandates expanded crude storage capacity to buffer supply disruptions. Underground salt cavern construction accelerates across Gujarat and Karnataka.
- Vapor Recovery Mandates:The EU F-Gas Regulation and Industrial Emissions Directive compel secondary containment retrofits. Terminal operators in Rotterdam and Antwerp invest in closed-loop systems to capture fugitive emissions.
- Floating Storage Arbitrage:Contango structures in crude futures are pulling traders toward offshore tanker storage. Singapore and Fujairah anchor the fastest-growing segment as logistics flexibility commands premium pricing.
Market Restraints
- Specialized Labor Scarcity:API-certified welders and NACE corrosion engineers concentrate in the US Gulf Coast and Middle East. Project delays in India and Southeast Asia stem from talent poaching and training pipeline gaps.
- Steel Price Volatility:Hot-rolled coil and specialized tank-grade plate fluctuate with energy input costs. Above-ground steel tankage, which dominates installed capacity, faces margin compression when raw material spikes coincide with fixed-price contracts.
- Secondary Containment Retrofit Burden:The US EPA Spill Prevention, Control, and Countermeasure rules mandate integrity testing and berm expansion for aging tank farms. Legacy terminals in California and Texas face capital-intensive compliance without revenue uplift.
Strategic Opportunities
- Biofuel Hub Conversion:Vopak's Rotterdam and Singapore terminals demonstrate repurposing chemical tankage for renewable diesel and sustainable aviation fuel. Hydrotreater co-location with storage creates integrated biofuel logistics.
- Carbon Border Adjustment Preparation:The EU's impending carbon border mechanism rewards terminals with verified low-methane intensity. Early certification creates preferential access for Middle Eastern and African crude streams.
- Digital Twin Integration:IoT sensor networks and predictive analytics converge to optimize tank turnaround scheduling. Real-time inventory visibility attracts commodity traders seeking collateralized financing structures.
Industry Challenges
- API 653 Inspector Certification Bottlenecks:Above-ground storage tank integrity assessment requires certified personnel. Inspection backlogs in India and Brazil delay operational license renewals.
- Legacy SCADA Integration Friction:Cybersecurity-hardened control systems must interface with decades-old distributed control architectures. Patchwork upgrades create operational vulnerability windows during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil Storage Terminal Market |
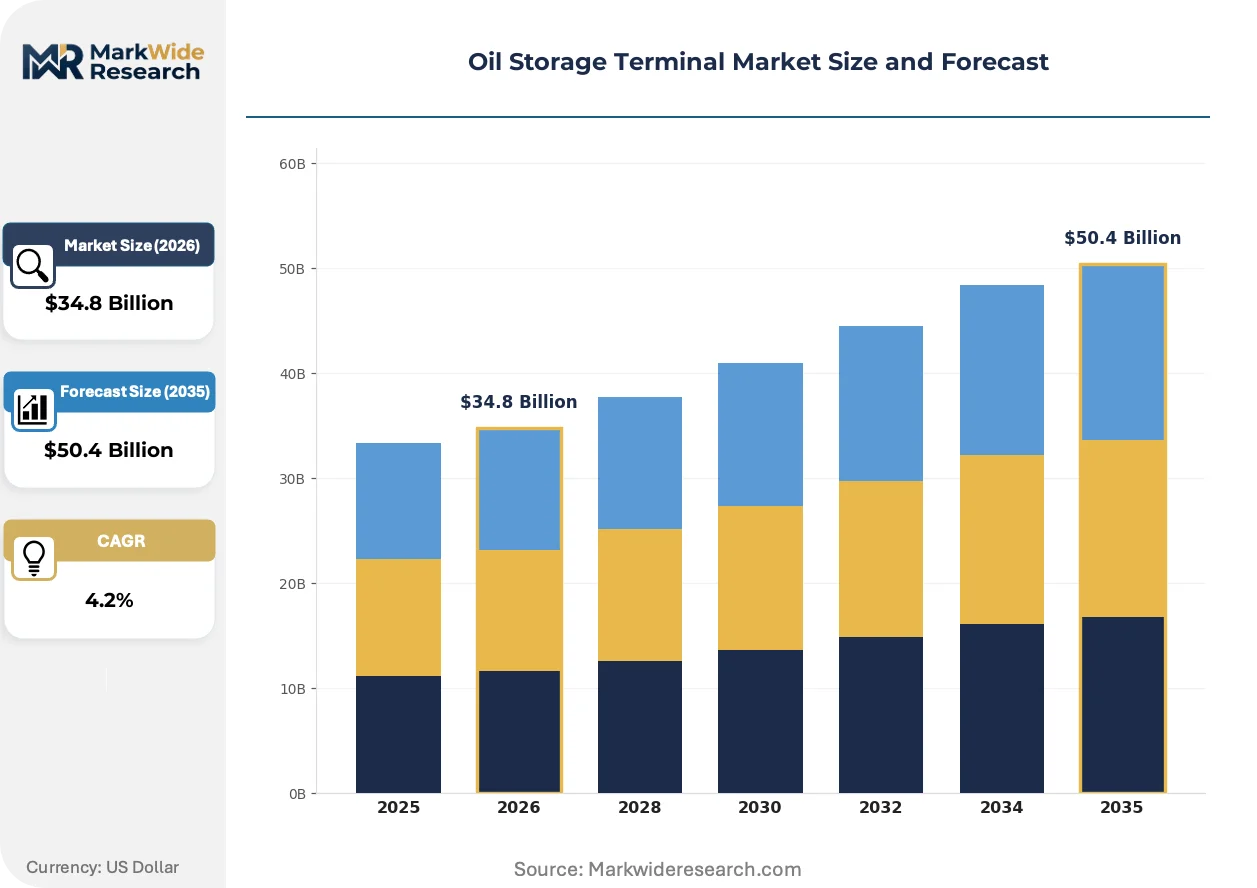
| Market Size in 2026 | $34.8 Billion |
| Market Size in 2035 | $50.4 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Floating Storage, Underground Storage, Above Ground Storage, Tanker Storage Tank Material: Steel, Concrete, Fiberglass, Aluminium End User: Refineries, Oil Companies, Trading Firms, Logistics Providers Distribution Channel: Direct Sales, Brokers, Online Platforms, Third-Party Distributors |
| Companies Covered | Enbridge Inc., Vitol, Royal Vopak, Buckeye Partners, NuStar Energy, Oiltanking GmbH, Gibson Energy, Magellan Midstream Partners, Kinder Morgan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil Storage Terminal Market Strategic Shifts & Innovations
Digital automation and emission monitoring technologies are compressing operational margins for terminals that fail to modernize. Three distinct vectors are redrawing competitive boundaries.
Advanced corrosion monitoring systems using ultrasonic thickness sensors and robotic crawlers are fragmenting the traditional manual inspection model. Major traders and integrated oil companies in the US Gulf Coast and Singapore are deploying continuous monitoring at a pace that sidelines periodic shutdown-based assessment. This technology is fragmenting the inspection services market into predictive analytics providers versus conventional NDT contractors.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon-based refrigeration is forcing vapor recovery system redesigns across Rotterdam, Antwerp, and Hamburg terminals. Industrial consequence includes accelerated replacement of mechanical vapor recovery units with membrane separation and carbon adsorption alternatives. Chemical and LPG storage segments face the steepest compliance curves, with operators pre-buying equipment ahead of 2027 quota restrictions.
Commodity traders are consolidating procurement around terminals offering integrated inventory financing and title transfer automation. The open-book cost-plus contracting model is displacing traditional throughput fee structures in crude and middle distillate segments. This behavioral shift is most visible in Singapore and Fujairah, where banks and trading houses prioritize collateral visibility over pure storage rates.
Oil Storage Terminal Market Segmentation
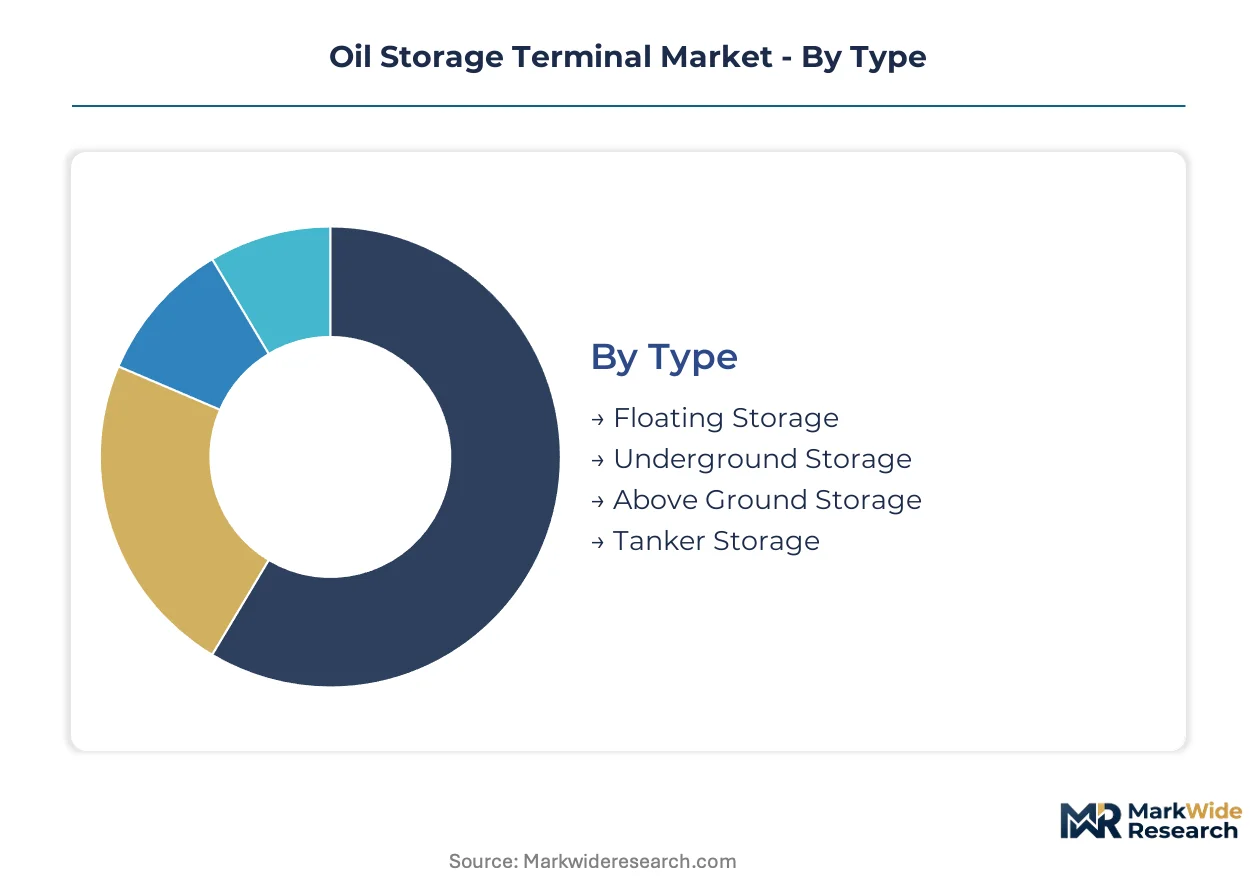
Storage terminal segmentation reveals how capital deployment, regulatory exposure, and operational flexibility distribute across facility types and customer bases. Channel and material choices directly determine project timelines, emission compliance burdens, and financing structures.
Type:
Floating storage and underground caverns flow through trading houses and strategic reserve programs, while above-ground tankage dominates direct refinery procurement channels.
- Above Ground Storage:Welded steel tanks ranging from 10,000 to 500,000 barrels anchor Gulf Coast and Rotterdam terminal networks. Refineries in India and Texas prioritize this format for rapid deployment and lower capital intensity, though EPA SPCC secondary containment mandates inflate retrofit costs for aging farms.
- Underground Storage:Salt cavern construction enables long-duration crude holding with minimal surface footprint. India's Petroleum and Natural Gas Regulatory Board mandates expansion across Gujarat and Karnataka for strategic petroleum reserve programs, where energy security overrides pure commercial returns.
- Floating Storage:Offshore tanker configurations exploit crude futures contango structures. Singapore and Fujairah trading hubs command premium pricing for logistics flexibility.
- Tanker Storage:Dedicated vessel-based capacity serves short-term arbitrage and emergency offtake. Charter rates fluctuate with freight derivatives and inventory financing spreads.
Above ground storage dominates installed base. Underground salt cavern construction is where expansion concentrates.
Tank Material:
Material selection stratifies by cost tier: steel anchors mass-market terminals, while fiberglass and aluminum serve specialized chemical and aviation fuel niches demanding corrosion resistance.
- Steel:Hot-rolled coil and tank-grade plate constitute the dominant construction input for welded above-ground tanks. Price volatility in steel inputs compresses margins on fixed-price EPC contracts, particularly for terminals in India and Southeast Asia facing procurement delays.
- Concrete:Reinforced concrete construction anchors large-scale strategic reserve caverns and secondary containment berms. European terminals in Antwerp and Hamburg deploy concrete for fire suppression integration and vapor recovery system anchoring under EU Industrial Emissions Directive requirements.
- Fiberglass:Corrosion-resistant composite tanks serve biofuel and chemical storage segments. Vopak's Rotterdam terminals demonstrate fiberglass deployment for renewable diesel handling.
- Aluminium:Lightweight alloy construction supports aviation fuel and high-purity product storage. Middle Eastern terminals leverage aluminum for rapid modular deployment.
Steel tankage commands volume leadership. Fiberglass and aluminum are gaining share fastest in biofuel and specialty chemical segments.
End User:
Customer type determines contract structure: refineries negotiate long-term throughput agreements, while trading firms prioritize short-term flexibility and collateralized inventory financing.
- Refineries:Integrated downstream operators anchor base-load storage demand with 10-20 year lease structures. Reliance Industries and Indian Oil Corporation drive capacity expansion across Gujarat and Karnataka with crude intake capacity increases for heavier sour grades.
- Trading Firms:Commodity merchants and banks prioritize terminals offering real-time inventory visibility and title transfer automation. Singapore and Fujairah hubs attract trading consolidation through integrated financing structures.
- Oil Companies:Majors and national oil companies blend strategic reserve mandates with commercial operations. Saudi Aramco and ADNOC leverage captive storage for export logistics optimization.
- Logistics Providers:Third-party terminal operators like Vopak and Kinder Morgan aggregate multi-customer throughput. Houston Ship Channel and Rotterdam clusters maximize intermodal connectivity.
Refinery direct contracting dominates revenue stability. Trading firm demand is climbing the fastest as collateralized financing reshapes procurement priorities.
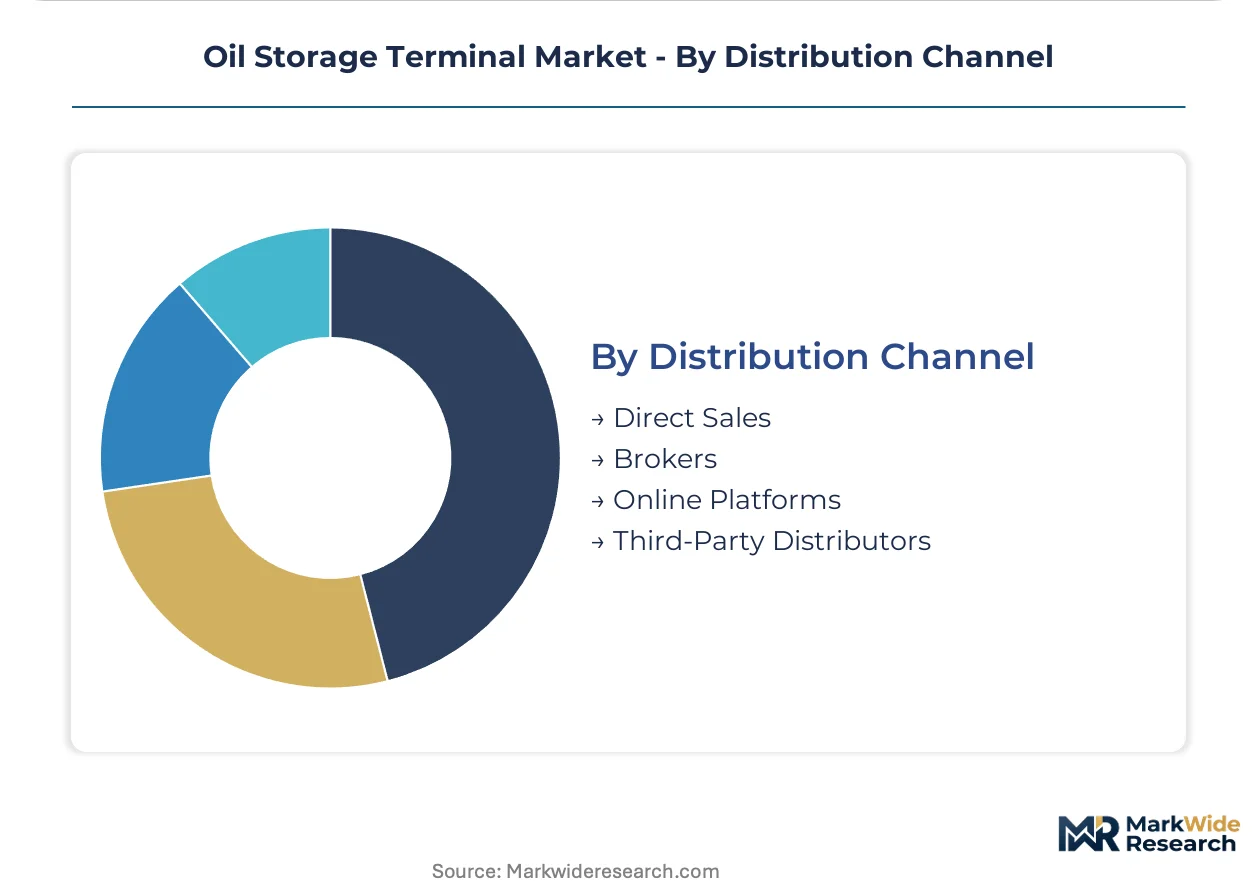
Distribution Channel:
Channel maturity varies by geography: direct sales prevail in established markets, while broker networks accelerate penetration in fragmented developing regions.
- Direct Sales:Terminal operators contract directly with refineries and oil majors for dedicated tankage. This channel captures long-term revenue visibility in the US Gulf Coast and Northwest Europe.
- Brokers:Intermediary networks match surplus capacity with spot demand in fragmented Asian and African markets. Broker fees compress margins but accelerate utilization for greenfield terminals.
- Third-Party Distributors:Logistics integrators bundle storage with transport and customs clearance. This channel concentrates in Singapore and Dubai for transshipment arbitrage.
- Online Platforms:Digital marketplaces for spot storage contracting remain nascent. Platform pilots in Rotterdam and Houston target small traders seeking short-term capacity.
Direct sales anchor contracted revenue. Broker and third-party channels are expanding most quickly in India and Southeast Asia's fragmented terminal networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Spill Prevention, Control, and Countermeasure rules anchor terminal construction standards across the largest storage market, while India's Petroleum and Natural Gas Regulatory Board mandates parallel capacity expansion for strategic petroleum reserves.
United States
Gulf Coast refineries and export terminals drive above-ground tankage demand for Permian Basin crude logistics. EPA SPCC secondary containment mandates inflate retrofit costs for aging California and Texas tank farms. Houston Ship Channel clusters anchor integrated storage-to-pipeline networks.
India
Reliance Industries and Indian Oil Corporation expand crude intake capacity for heavier sour grade processing. The Petroleum and Natural Gas Regulatory Board mandates underground salt cavern construction across Gujarat and Karnataka. Gujarat terminals concentrate strategic petroleum reserve expansion.
Netherlands
Rotterdam terminals retrofit vapor recovery systems under EU F-Gas Regulation phasedown schedules. The EU Industrial Emissions Directive compels closed-loop emission capture investments. Antwerp-Rotterdam-Amsterdam clusters anchor biofuel hub conversion for renewable diesel storage.
Singapore
Commodity traders exploit contango structures through floating storage arbitrage. The Maritime and Port Authority enforces bunker fuel quality standards affecting terminal product specifications. Jurong Island terminals command premium pricing for logistics flexibility and inventory financing integration.
United Arab Emirates
ADNOC leverages captive storage for export logistics optimization and crude blend customization. The Supreme Petroleum Council mandates capacity expansion for strategic reserve diversification. Fujairah terminals anchor Middle East transshipment with specialized tankage for fuel oil and middle distillates.
Oil Storage Terminal Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with pipeline-network operators and independent tankage providers occupying distinct competitive positions. The market structure rewards scale in hub locations and regulatory compliance capability in mature markets. Three archetypes dominate: integrated midstream operators with captive pipeline networks, independent terminal specialists with multi-customer throughput models, and trading-house affiliates with inventory financing integration. Capacity expansion and vapor recovery retrofit partnerships represent the dominant competitive moves as operators respond to methane emission standards.
Among North American pipeline-integrated operators, Enbridge Inc. and Kinder Morgan exemplify the hub-and-spoke storage-to-transport model, while Royal Vopak occupies a position as the independent international tankage specialist with chemical and biofuel hub concentration. These three represent contrasting strategic postures: captive infrastructure leverage versus multi-customer terminal aggregation versus specialized niche positioning.
| Leading Market Players |
|---|
| Enbridge Inc. |
| Vitol |
| Royal Vopak |
| Buckeye Partners |
| NuStar Energy |
| Oiltanking GmbH |
| Gibson Energy |
| Magellan Midstream Partners |
| Kinder Morgan |
| Others |
Cost & Logistics Intelligence
EPA Spill Prevention, Control, and Countermeasure certification gates terminal operator qualification while simultaneously stratifying storage rates across compliant and non-compliant tank farms. Buyers with crude throughput exceeding threshold volumes face mandatory secondary containment investments that compress operating margins and amplify price differentiation between legacy and retrofitted facilities.
Pricing Analysis
Singapore and Fujairah command storage premiums over Rotterdam and Houston by fifteen to twenty-five percent for equivalent crude grades, reflecting logistics flexibility and inventory financing integration. Contract-based long-term offtake dominates refinery procurement, while spot-market trading firms prioritize terminals with real-time collateral visibility. Price differentiation rests on vapor recovery system certification under EU F-Gas Regulation tiers and API 653 inspection currency. Cost compression in standard-grade tankage is intensifying because steel input volatility coincides with fixed-price EPC contracts. Trading firms exhibit lowest price sensitivity, absorbing premium rates for title transfer automation and integrated financing structures.
Supply Chain Analysis
Inventory strategy bifurcates between trading houses exploiting just-in-time floating storage arbitrage and strategic reserve programs mandating multi-year salt cavern stockpiles. Hot-rolled coil and tank-grade plate supply concentrates in China, South Korea, and Japan, with specialized corrosion-resistant alloys sourcing from Germany and the United States. Raw material dependencies include nickel-bearing steel plate, epoxy coating systems, and vapor recovery membrane components. Single-source vulnerability runs through API-certified welding consumables concentrated in the US Gulf Coast. Distribution feeds from integrated midstream networks anchored in Houston, Rotterdam, and Singapore toward fragmented broker-mediated markets in India and Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Terminal market fragmentation creates white-space opportunities as biofuel hub conversion and carbon border compliance splinter demand across specialized facility archetypes.
For Market Incumbents: Compound storage-to-transport integration advantages by expanding pipeline connectivity at Houston Ship Channel and Rotterdam clusters. Defend position against independent terminal specialists through captive vapor recovery retrofit partnerships that lock in refinery customers under extended lease structures. Prioritize API 653 inspector certification programs to preempt operational license bottlenecks in India and Brazil.
For New Entrants and Emerging Players: Anchor in Gujarat and Karnataka underground salt cavern construction, where Petroleum and Natural Gas Regulatory Board mandates outrun incumbent capacity deployment. Target fiberglass tankage for renewable diesel and sustainable aviation fuel segments underserved by steel-dominant legacy operators. Pursue hydrotreater co-location partnerships with biofuel producers seeking integrated logistics.
For Investors and Strategic Acquirers: EU F-Gas Regulation phasedown reshapes the acquisition landscape toward terminals with membrane separation and carbon adsorption vapor recovery systems already deployed. Five-to-ten year viability favors independent specialists with chemical and biofuel hub concentration over pure crude tankage exposed to contango volatility. Signal to watch: carbon border adjustment mechanism implementation accelerating preferential terminal access for verified low-methane intensity crude streams.
| Strategic Initiative | Industry Significance |
|---|---|
| Vapor Recovery Retrofit Partnership | EU F-Gas Regulation compliance locks in Rotterdam and Antwerp refinery customers through closed-loop emission capture investments. |
| Underground Salt Cavern Buildout | Petroleum and Natural Gas Regulatory Board mandates in Gujarat and Karnataka create captive demand for strategic petroleum reserve contractors. |
| Biofuel Hub Conversion | Vopak's Rotterdam terminals demonstrate renewable diesel and sustainable aviation fuel repurposing of chemical tankage with hydrotreater integration. |
| Digital Twin Integration | IoT sensor networks at Singapore and Fujairah terminals attract commodity traders through real-time inventory visibility and collateralized financing. |
| API 653 Inspector Certification Program | Inspection backlogs in India and Brazil delay operational license renewals, creating competitive advantage for certified personnel pipelines. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EPA enforcement databases, EU Industrial Emissions Directive filings, Petroleum and Natural Gas Regulatory Board project registrations, and steel trade flow customs records. Terminal operators, EPC contractors, API-certified welding inspectors, and commodity trading house logistics directors contributed structured interviews. Secondary validation drew from FERC storage capacity reports, EIA terminal utilization data, and SEC filings of publicly traded midstream operators. Bottom-up project pipeline aggregation triangulates against top-down regional capacity assessments.
Segmentation dimensions modeled span storage type, tank material grade, end-user contract structure, and distribution channel maturity across the analysis window. CAGRs derive from capacity expansion timelines, regulatory compliance cost curves, and trading firm inventory financing penetration rates. Forecast inputs incorporate steel price volatility indices and API 653 inspector supply elasticity.
Decision-makers should treat outputs as directional under assumptions of sustained refinery expansion in India and phased EU F-Gas Regulation implementation; material deviation would warrant model refresh. Forecasts reflect base-case regulatory enforcement intensity and labor certification pipeline recovery. Revision becomes warranted when steel input cost spikes or inspector training bottlenecks cross thresholds that compress project viability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Small Scale LNG Terminal Market
Oil & Gas
Whipstocks Market
Oil & Gas
Seismic Survey Equipment Market
Oil & Gas
Oil and Gas Fabrication Market
Oil & Gas
Oil and Gas Storage Market
Oil & Gas
United States Liner Hanger System Market
Oil & Gas
Europe Oil and Gas Storage Tank Market
Oil & Gas
Oil Hose Market
Oil & Gas
Frac Stack Market
Oil & Gas
Spacer Fluid Market
Oil & Gas
Egypt Oil and Gas Midstream Market
Oil & Gas
Swellable Packers Market
Oil & Gas
Cased Hole Logging Services Market
Oil & Gas
Turkmenistan Oil and Gas Market
Oil & Gas
Wireline Logging Services Market
Oil & Gas
Crude Oil Desalter and Electrostatic Dehydrator Market