
 Europe Oil and Gas Storage Tank Market | 2026-2036
Europe Oil and Gas Storage Tank Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Oil and Gas Storage Tank Market Foresight
API 653 tank inspection certification is redrawing competitive boundaries across Europe, as terminal operators face escalating compliance costs and shorter recertification windows. Royal Vopak N.V. leverages its Rotterdam and Antwerp footprint to dominate large-scale petroleum storage economics. Eisenbau Heilbronn GmbH specializes in custom steel fabrication for pressure-rated vessels serving chemical corridor clients.
Europe oil and gas storage tanks are cylindrical or spherical pressure vessels constructed from carbon steel plate with welded seams, designed to contain crude oil, refined products, or natural gas liquids at atmospheric or elevated pressures for inventory management and supply security. Steel remains the dominant tank material across the region, though composite linings gain traction in corrosive chemical service applications. Above-ground floating roof configurations lead capacity additions due to lower evaporative losses and tighter emission controls. Underground salt cavern storage for strategic petroleum reserves represents a mature, capital-intensive segment with limited new entrants.
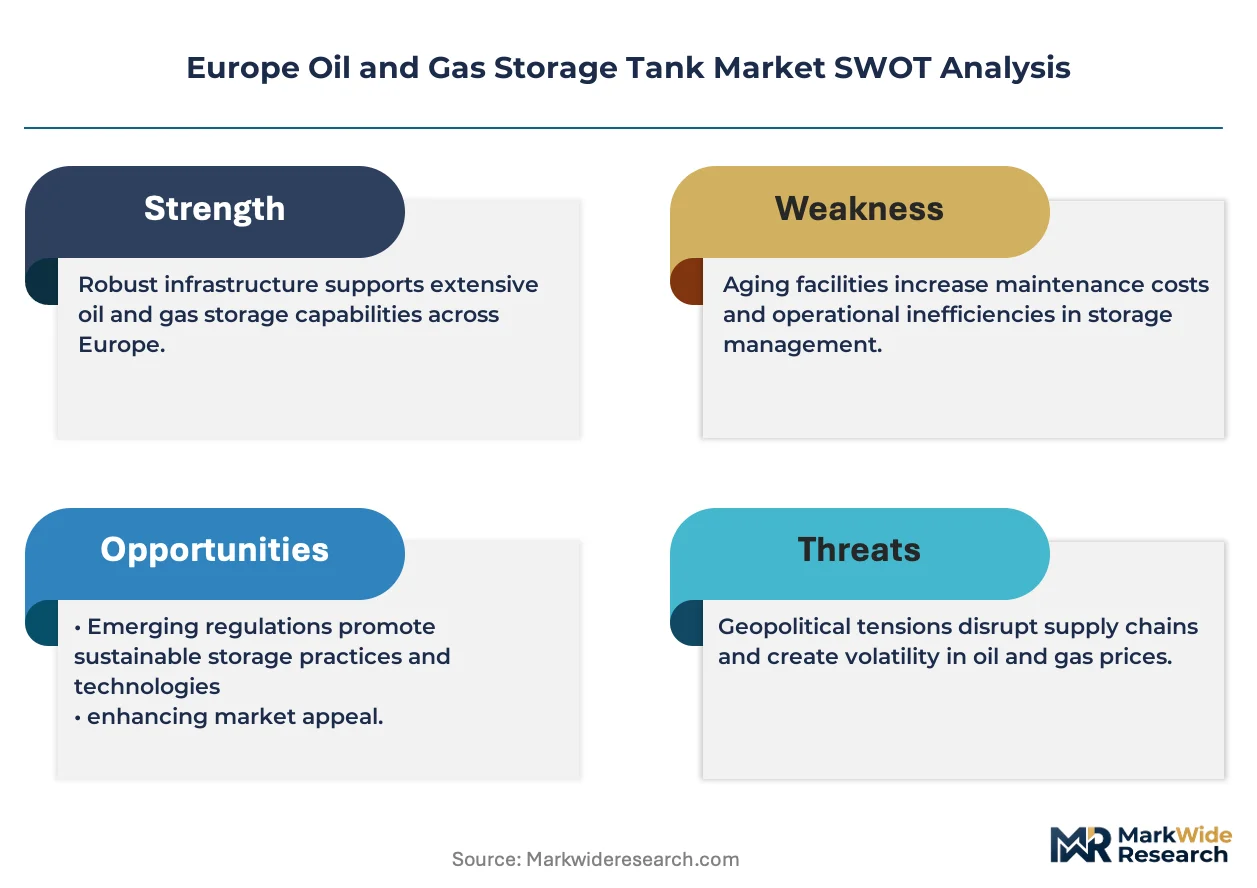
REACH chemical safety rules and the EU F-Gas Regulation constrain coating systems and seal materials used in tank construction and retrofit projects. ECHA substance authorization requirements are extending project timelines for terminal expansions in Hamburg and Marseille. Stakeholders must monitor how the EU Emissions Trading System carbon price trajectory reshapes the operating cost structure of heated heavy crude storage.
Market Dynamics
The EU Green Deal's methane emission mandates are forcing terminal operators to replace legacy floating roof seals and vapor recovery systems, compressing project timelines while expanding the addressable market for emission-control retrofits across the ARA cluster.
Growth Catalysts
- Crude sourcing diversification:Refinery operators in Germany and the Netherlands are expanding tank farm capacity to handle Russian supply displacement and US shale arbitrage flows.
- REACH chemical authorization:ECHA substance restrictions on legacy coating systems are accelerating replacement cycles for tank linings and seal materials.
- Floating roof adoption:Above-ground floating roof configurations are capturing capacity additions due to evaporative loss reductions and tighter EU emission controls.
Market Restraints
- Carbon steel price volatility:Plate steel input costs fluctuate with energy-intensive European smelter economics and import tariff exposure.
- API 653 certification concentration:Qualified inspection contractors cluster in the ARA region, creating bottlenecks for terminal operators in peripheral markets.
- Salt cavern substitution limits:Underground strategic petroleum reserve capacity offers minimal expansion potential due to geological constraints and capital intensity.
Strategic Opportunities
- Polish corridor expansion:Baltic terminal operators in Gdansk are capturing redirected Russian crude flows and building blending infrastructure.
- EU F-Gas Regulation retrofit wave:Refrigerated LPG and NGL storage terminals must replace high-GWP seal materials, opening specialty polymer demand.
- Digital twin convergence:Integration of IoT corrosion monitoring with predictive maintenance platforms is reducing unplanned tank outages for chemical corridor clients.
Industry Challenges
- Welder certification scarcity:API 650 and EN 14025 pressure vessel welding qualifications face training pipeline gaps across Eastern European fabrication yards.
- Legacy system integration:Vapor recovery unit retrofits must interface with decades-old tank farm SCADA architectures without disrupting throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Oil and Gas Storage Tank Market |
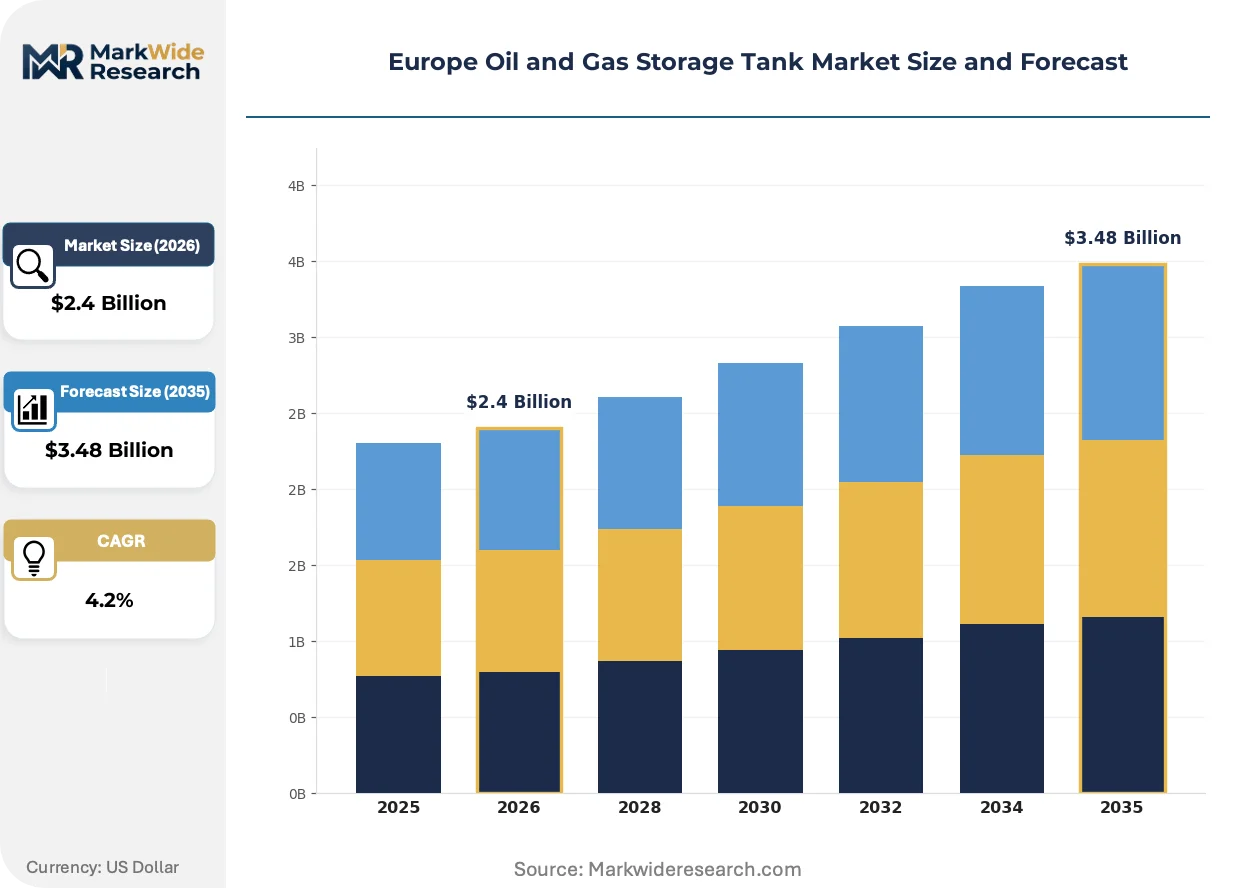
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Storage Type: Above Ground, Underground, Floating Roof, Fixed Roof Tank Material: Steel, Aluminum, Concrete, Composite End User: Oil Refineries, Chemical Plants, Power Plants, Utilities Compliance Standard: API, ASTM, ISO, NFPA |
| Companies Covered | Royal Vopak N.V., Oiltanking GmbH, Vitol Tank Terminals International BV (VTTI), Rubis Terminal, HES International BV, HOYER GmbH, Eisenbau Heilbronn GmbH, CLH, Odfjell, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Oil and Gas Storage Tank Market Shifts & Advancements
Steel tank construction is fragmenting into parallel technology tracks, with emission-control hardware and digital monitoring systems capturing disproportionate engineering investment relative to basic vessel fabrication.
Composite lining systems are decomposing the dominance of carbon steel in corrosive chemical service. Specialty chemical terminals in the ARA cluster are specifying glass-reinforced epoxy and vinyl ester linings for sulfuric acid and caustic storage. This material shift is decomposing traditional steel fabricator margins while expanding the addressable market for polymer engineering specialists.
EU F-Gas Regulation phase-down schedules are compressing seal material specifications across refrigerated storage applications. Terminal operators in Hamburg and Marseille face extended procurement timelines for low-GWP fluoropolymer alternatives. The chemical storage segment is absorbing the steepest compliance cost increases as ECHA substance authorization requirements layer onto existing construction standards.
Refinery procurement departments are consolidating tank inspection and maintenance contracts under multi-year framework agreements. Integrated service providers are displacing fragmented local contractors in the ARA region and German chemical corridor. This vendor consolidation is most visible among Rotterdam-based terminal operators seeking single-accountability emission compliance.
Europe Oil and Gas Storage Tank Market Segmentation
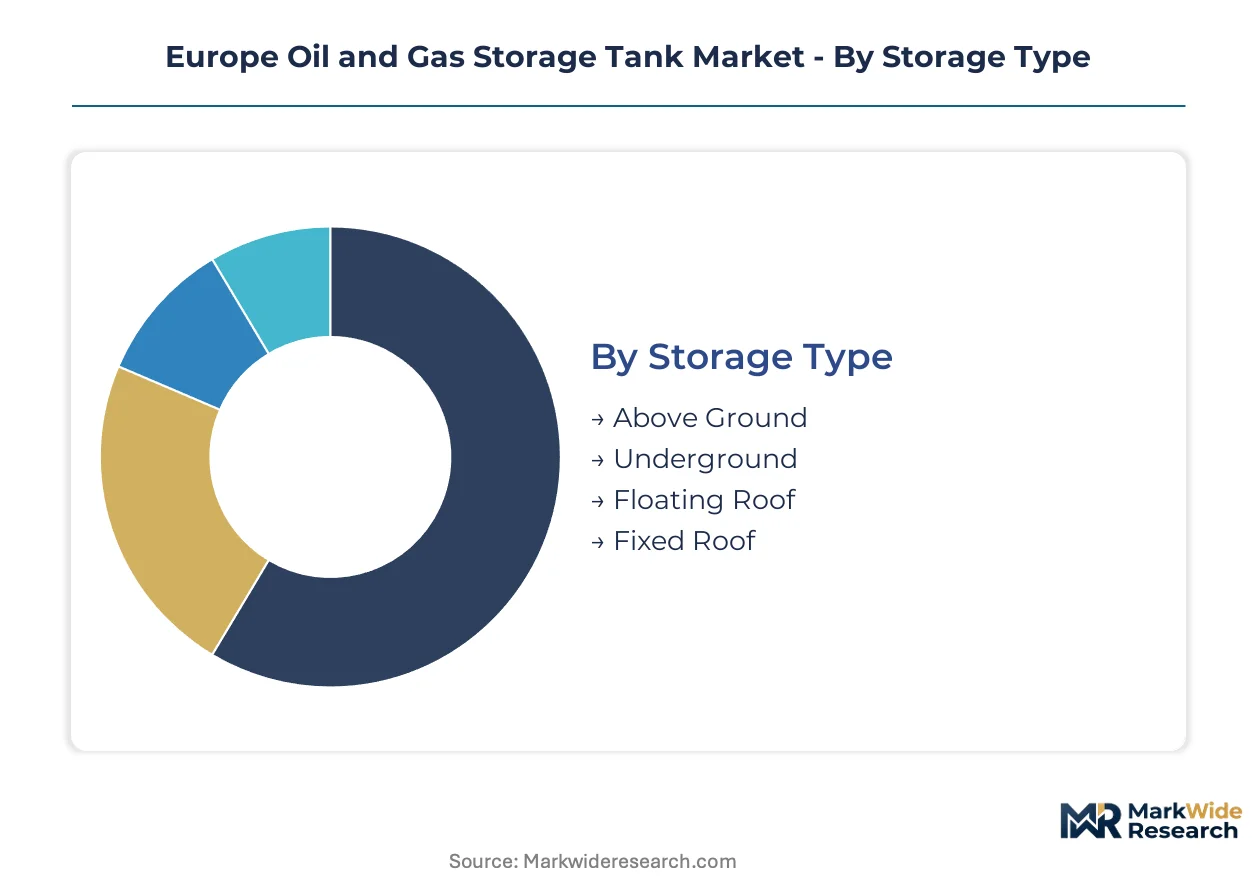
Storage tank procurement decisions in Europe diverge sharply across material specifications and regulatory compliance tiers. Refinery operators in the ARA cluster prioritize floating roof configurations for emission control, while chemical terminals weigh corrosion resistance against capital recovery timelines.
Storage Type:
Above-ground configurations face intensifying substitution pressure from underground salt cavern alternatives for strategic petroleum reserve applications, though geological constraints limit this threat to specific North Sea formations.
- Above Ground:Cylindrical steel vessels erected at grade level with welded seam construction, designed for atmospheric or low-pressure service. Demand concentrates in Rotterdam and Antwerp terminals where blending flexibility and rapid throughput justify higher evaporative loss exposure. API 653 inspection cycles compress asset life economics for older riveted designs.
- Underground:Salt cavern and hard rock excavations leveraging geologically stable formations for pressurized hydrocarbon containment. German and Polish operators exploit Permian and Zechstein salt domes for strategic crude reserves, though capital intensity and brine disposal constraints deter new entrants.
- Floating Roof:Pontoon-supported decks riding directly on liquid surfaces to minimize vapor space and evaporative emissions. Netherlands refiners specify these for gasoline and naphtha service under EU Green Deal methane reduction mandates.
- Fixed Roof:Dome or cone-topped vessels with permanent vapor space, common in heated heavy crude service and chemical storage. Marseille terminals retain these for bitumen and residual fuel oils where emission controls matter less than thermal efficiency.
Above Ground retains volume leadership; Floating Roof holds the steepest expansion curve.
Tank Material:
Cost tier stratification separates commodity carbon steel from premium corrosion-resistant alternatives, with project budgets determining specification thresholds across the chemical corridor.
- Steel:Carbon and low-alloy plate grades per EN 10025 and API 650 specifications, welded into cylindrical shells with annular bottom plates. German fabrication yards in Heilbronn and Dortmund dominate pressure-rated vessel supply, though welder certification scarcity extends delivery timelines.
- Aluminum:5xxx-series alloys specified for cryogenic and low-temperature LNG service, offering weight reduction and corrosion resistance. Rotterdam LPG terminals deploy aluminum dome roofs on concrete-walled tanks to reduce seismic load.
- Concrete:Prestressed or reinforced structures for large-volume water and firewater service, occasionally specified for refrigerated hydrocarbon containment with internal steel liners. Limited penetration in petroleum service due to permeability concerns.
- Composite:Glass-reinforced epoxy and vinyl ester linings applied to steel substrates for sulfuric acid and caustic chemical storage. ARA specialty terminals specify these for aggressive service where steel alone would require excessive corrosion allowance.
Steel dominates installed base; Composite gains share fastest in corrosive chemical applications.
End User:
Customer type fragmentation separates capital-intensive refinery investments from utility-scale operational expenditure models, with procurement authority residing in distinct organizational functions.
- Oil Refineries:Integrated downstream operators specifying large-diameter tanks for crude receipt, intermediate storage, and finished product blending. German refiners in Leuna and Schwedt expand capacity to accommodate diversified sourcing from US shale and Caspian corridors.
- Chemical Plants:BASF, INEOS, and Lanxess facilities along the Rhine and Antwerp chemical corridors demanding pressure-rated vessels for feedstock and intermediate storage. REACH authorization requirements extend procurement cycles for specialty linings and seal materials.
- Power Plants:Heavy fuel oil and diesel storage for peak shaving and grid stabilization, predominantly in Southern European markets with weaker gas infrastructure.
- Utilities:Municipal and regional energy distributors maintaining strategic distillate reserves for heating oil and emergency generator supply.
Oil Refineries command the largest single-unit capacities; Chemical Plants drive the most complex specification requirements.
Compliance Standard:
Maturity differentiation separates legacy API specifications from emerging European norms, with project location and insurer requirements determining standard selection.
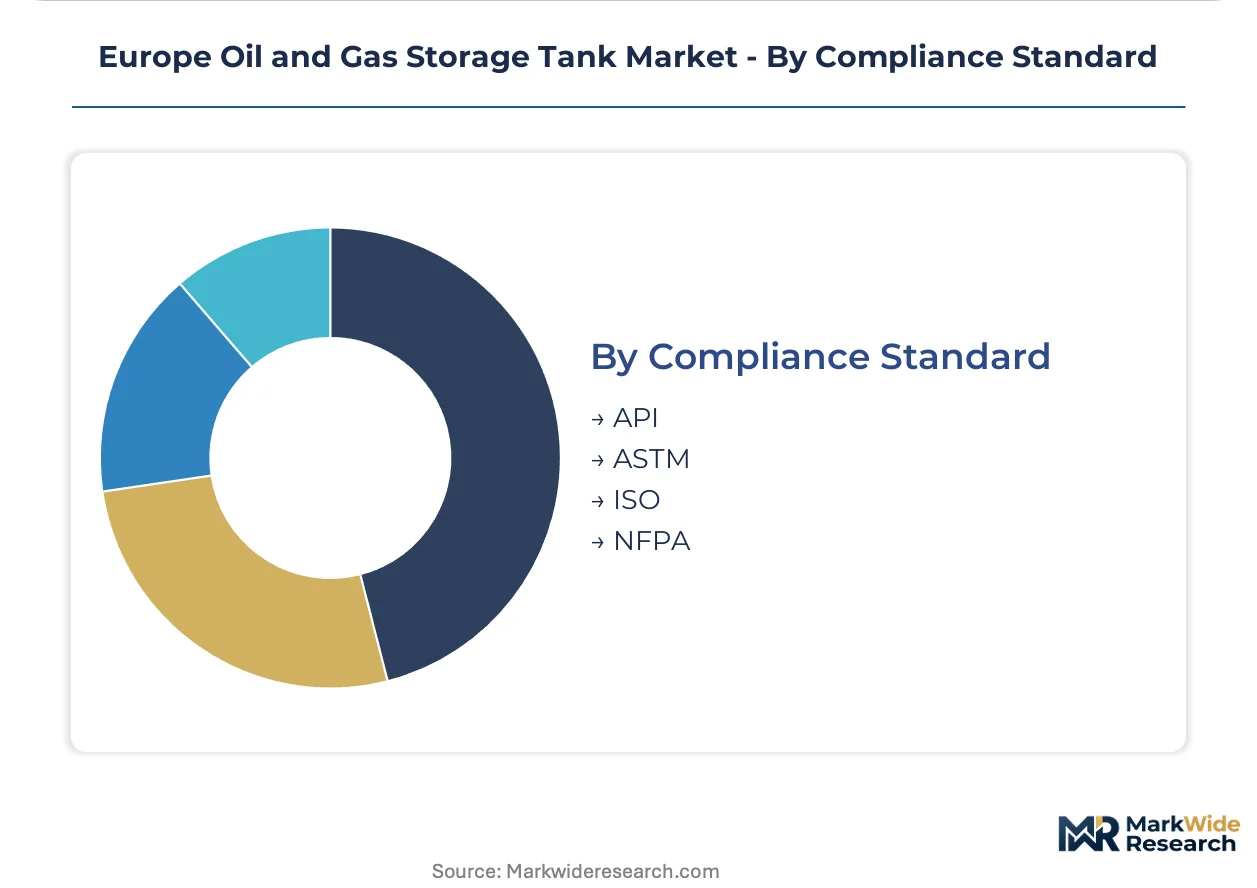
- API:American Petroleum Institute standards 650, 653, and 620 governing welded tank construction, inspection, and pressure-rated design. Rotterdam and Antwerp terminal operators treat API certification as baseline qualification for international trading house acceptance.
- ASTM:Material specification standards for steel plate, coatings, and seal elastomers referenced within European construction contracts. A283 and A516 pressure vessel grades predominate in German fabrication.
- ISO:International standards for quality management and specific tank technologies, increasingly specified by multinational operators seeking portfolio standardization.
- NFPA:Fire protection standards for flammable liquid storage, referenced in site permitting and insurer risk assessments for above-ground facilities.
API retains contractual dominance; ISO gains traction among pan-European terminal operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam-Botlek pipeline corridor and Amsterdam-Rotterdam-Antwerp (ARA) waterway network anchor northwest Europe's petroleum storage economics, with tank farm capacity tied directly to Brent benchmark trading and blending arbitrage.
Germany
Refinery operators in Leuna and Schwedt are expanding tank farm capacity to accommodate diversified crude flows from US shale and Caspian corridors. The country's Federal Emissions Control Act (BImSchG) mandates vapor recovery upgrades for gasoline storage terminals. Heilbronn fabrication yards supply pressure-rated vessels to the Rhine chemical corridor under tight welder certification constraints.
Netherlands
Royal Vopak N.V. dominates large-scale petroleum storage economics through its Rotterdam and Antwerp terminal footprint. EU Green Deal methane reduction targets are forcing floating roof seal replacements across Maasvlakte tank farms. The Port of Rotterdam's CO₂ capture infrastructure investments are reshaping heated heavy crude storage operating costs.
Belgium
Antwerp's chemical corridor demands corrosion-resistant composite linings for sulfuric acid and caustic storage applications. REACH chemical authorization requirements extend procurement timelines for specialty seal materials. The Port of Antwerp-Bruges consolidation is driving terminal automation investments among storage operators.
Poland
Baltic terminal operators in Gdansk are capturing redirected Russian crude flows and constructing blending infrastructure. The country's national energy security programs support strategic petroleum reserve expansion. Płock refinery operators are negotiating API 653 inspection contracts with ARA-based specialists facing capacity bottlenecks.
France
Marseille-Fos terminals retain fixed roof configurations for bitumen and residual fuel oil storage where thermal efficiency outweighs emission controls. ECHA substance restrictions on legacy coating systems are accelerating replacement cycles for tank linings. The Grand Port Maritime de Marseille is evaluating refrigerated LPG storage expansion under EU F-Gas Regulation compliance deadlines.
Europe Oil and Gas Storage Tank Market Competitive Landscape
Listed leaders compete with private specialists across terminal ownership and vessel fabrication segments, creating a tiered structure where scale-driven storage operators coexist with regional fabrication shops. The vendor base separates into three strategic archetypes: integrated terminal operators controlling ARA waterway capacity, custom steel fabricators serving chemical corridor pressure vessel demand, and inspection contractors consolidating API 653 certification resources. Dominant competitive moves include multi-year framework agreement consolidation for inspection and maintenance services, and emission-control retrofit bundling across aging tank farms.
Among Dutch-listed storage operators, Royal Vopak N.V. and Vitol Tank Terminals International BV (VTTI) occupy positions at the scale-driven end of terminal ownership, exemplifying the integrated operator archetype through ARA waterway dominance. Eisenbau Heilbronn GmbH represents the custom fabrication specialist tier, anchoring German pressure-rated vessel supply to Rhine chemical corridor clients. Oiltanking GmbH sits within the private terminal operator category, competing on blending flexibility and throughput economics.
| Leading Market Players |
|---|
| Royal Vopak N.V. |
| Oiltanking GmbH |
| Vitol Tank Terminals International BV (VTTI) |
| Rubis Terminal |
| HES International BV |
| HOYER GmbH |
| Eisenbau Heilbronn GmbH |
| CLH |
| Odfjell |
| Others |
Supply & Pricing Matrix
Composite lining substitution for bare carbon steel is redrawing procurement geography across the ARA cluster, pulling polymer engineering specialists into tank construction while compressing traditional German fabricator margins on corrosive chemical service contracts.
Pricing Analysis
Certification level (API 653/EN 14025-grade) creates the primary spread between Rotterdam terminal operators and peripheral market bidders. Three-tier pricing structure across premium certified, standard compliant, and economy uninspected levels governs large-diameter vessel procurement. Cost compression in the economy tier is intensifying because Polish and Baltic terminal operators face welder certification scarcity. Chemical corridor buyers show least price sensitivity for corrosion-resistant specifications.
Supply Chain Analysis
Inventory lead times for low-GWP fluoropolymer seal materials now extend procurement cycles by 30-40% for Hamburg and Marseille refrigerated storage projects. German, Dutch, and Belgian fabrication yards anchor European pressure-rated vessel supply. Raw material feeds draw from Swedish plate steel, Italian coating systems, and German polymer engineering. Single-source vulnerability concentrates in qualified API 653 inspection contractors clustering around Rotterdam. Distribution runs through ARA waterway terminals and Rhine barge networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe oil and gas storage tank market rewards operators who control scarce welding certification pipelines and emission-control retrofit capabilities, with API 653-qualified inspection capacity emerging as the binding constraint on terminal expansion timelines.
For Market Incumbents: Shield Rotterdam and Antwerp market share by locking multi-year framework agreements with ARA-based inspection contractors before peripheral competitors secure scarce certification resources. Deepen backward integration into low-GWP seal material supply chains to capture EU F-Gas Regulation retrofit margins. Prioritize vapor recovery unit bundling across aging Maasvlakte tank farms to entrench single-accountability relationships. For New Entrants and Emerging Players: Differentiate on rapid-deployment floating roof seal replacement services targeting German refinery operators facing compressed BImSchG compliance deadlines. White-space opportunities concentrate in Polish Baltic terminals redirecting Russian crude flows and constructing blending infrastructure. Pursue asset-light inspection contracting models to bypass capital-intensive fabrication barriers. For Investors and Strategic Acquirers: The market sits at a regulatory-acceleration phase that favors vertically integrated terminal operators with captive API 653 certification resources. Long-term viability hinges on emission-control retrofit bundling capability and ARA waterway access. Acquisition targets should demonstrate proven low-GWP material procurement relationships. Watch ETS carbon price trajectory as the inflection signal for heated heavy crude storage economics.| Strategic Initiative | Industry Significance |
|---|---|
| API 653 Certification Expansion | Captures scarce inspection capacity before competitors lock multi-year terminal contracts. |
| Low-GWP Seal Material Backward Integration | Secures fluoropolymer supply chains for EU F-Gas Regulation compliance deadlines. |
| Floating Roof Retrofit Bundling | Creates single-accountability emission compliance packages for Rotterdam terminal operators. |
| Polish Corridor Blending Infrastructure | Captures redirected Russian crude flows through Gdansk terminal capacity additions. |
| Digital Twin Corrosion Monitoring | Reduces unplanned tank outages for BASF and INEOS chemical corridor clients. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with terminal operations directors, EPC procurement managers, tank fabrication yard supervisors, and API 653 inspection contractors; and secondary validation through EU ETS carbon price registries, ECHA substance authorization databases, Port of Rotterdam throughput statistics, and German Federal Network Agency storage capacity reports. Bottom-up project pipeline tracking triangulated against top-down regional capacity assessments.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation across storage type, tank material, end-user industry, and compliance standard tiers. CAGRs were derived from regression analysis of historical capacity additions against Brent benchmark trading intensity and EU regulatory phase-in schedules. Industry-specific inputs included welder certification pipeline constraints and ETS carbon price elasticity for heated storage operating costs.
Forecasts assume regulatory continuity in EU Green Deal methane mandates and ECHA REACH authorization regimes; material policy acceleration or relaxation would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Vietnam Oil and Gas Midstream Market
Oil & Gas
Digital Oil Rigs Market
Oil & Gas
Digital Twin in Oil and Gas Market
Oil & Gas
Sand Screen Sales Market
Oil & Gas
Delayed Coker Unit Market
Oil & Gas
Geothermal Drill Bits Market
Oil & Gas
Leak Detection for Oil & Gas Market
Oil & Gas
Oil and Gas Storage Market
Oil & Gas
China Oil and Gas Market
Oil & Gas
Digital Oil Field Technology Market
Oil & Gas
United States Oil and Gas Upstream Market
Oil & Gas
Asia Pacific Upstream Oil and Gas Services Market
Oil & Gas
Oil Well Cement Market
Oil & Gas
Oil and Gas Automation Market
Oil & Gas
South America Intelligent Pigging Market
Oil & Gas
Oil Country Tubular Goods (OCTG) Market