
 Frac Stack Market | 2026-2036
Frac Stack Market Size, Share, and Industry Trends Forecast 2026-2036
Frac Stack Market Analysis
North American pressure-pumping capacity is broadening as drillers return idled horsepower to the field. The Weir Group PLC leverages its foundry-to-field vertical integration to control lead times on high-pressure valves. Halliburton Company sustains the largest deployed fleet of frac stacks across the Permian and Eagle Ford. Baker Hughes Company differentiates through digital monitoring systems embedded in its stack manifolds.
A frac stack is an assembled array of high-pressure valves, chokes, and isolation tools rated typically to 15,000 psi, mounted atop a wellhead to manage hydraulic fracturing flowback and intervention operations. The assembly enables controlled diversion of proppant-laden fluids while protecting the master valve from erosion. Onshore configurations dominate installed base volume, though portable skid-mounted units command premium pricing due to reduced rig-up time. Shale gas applications anchor current demand, while tight oil formations in the Permian and Bakken represent the fastest-growing application segment as lateral lengths extend. Maintenance services capture recurring revenue streams, with original equipment manufacturers increasingly bundling predictive analytics into service contracts.
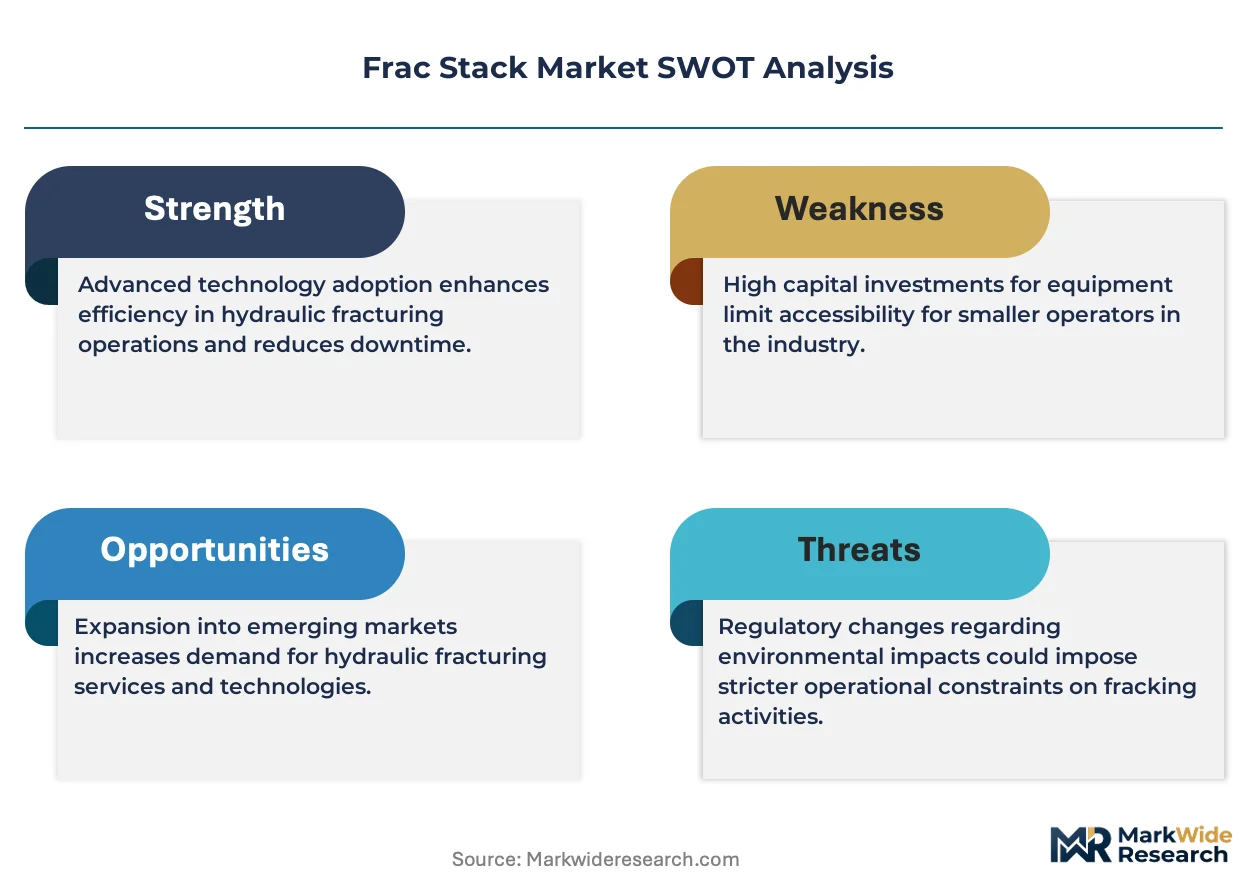
EPA methane rules and OSHA pressure-vessel standards shape equipment specifications, mandating enhanced sealing systems and documented pressure-testing protocols for stack assemblies. The Pipeline and Hazardous Materials Safety Administration oversees interstate transport of pressurized components, influencing regional inventory positioning. Stakeholders must monitor how state-level flaring restrictions in Texas and New Mexico reshape frac stack utilization rates and replacement cycles.
Market Dynamics
The frac stack market is being restructured by the collision of EPA methane emissions mandates with pad drilling intensification in the Permian Basin, forcing rapid equipment redeployment cycles and compressing replacement timelines for high-pressure assemblies.
Growth Catalysts
- EPA Methane Regulations:Tightened emissions standards under the Clean Air Act are compelling shale operators to upgrade sealing systems and replace legacy stacks with certified high-pressure configurations.
- Pad Drilling Intensity:Multi-well pad development in the Permian Basin and Eagle Ford is accelerating frac stack turnover as crews cycle equipment between wells on compressed timelines.
- Extended Lateral Lengths:Tight oil formations in the Bakken and Delaware Basin are demanding higher-pressure-rated assemblies capable of sustaining longer stimulation stages without degradation.
Market Restraints
- Alloy Supply Concentration:Forged high-pressure valve bodies depend on specialty steel mills concentrated in the US and Germany, creating input bottlenecks during demand spikes.
- OSHA Pressure-Vessel Certification:Documented pressure-testing protocols and welder qualification requirements extend manufacturing lead times for certified assemblies.
- Used Equipment Arbitrage:Refurbished frac stacks from decommissioned fleets in mature plays are capturing price-sensitive demand in secondary markets.
Strategic Opportunities
- Predictive Maintenance Bundles:Original equipment manufacturers are embedding sensor arrays and analytics platforms into service contracts to capture recurring revenue streams.
- Portable Skid-Mounted Units:Reduced rig-up time configurations command premium pricing in the Permian Basin where day-rate economics dominate contractor selection.
- Argentina Vaca Muerta:Underdeveloped shale infrastructure in Neuquén Province presents white-space demand for import-qualified high-pressure stack systems.
Industry Challenges
- Welder Certification Backlogs:Qualified ASME Section IX welders for high-pressure vessel fabrication are in short supply, constraining OEM production capacity.
- Legacy System Integration:Digital monitoring retrofits on installed base stacks face compatibility gaps with analog wellhead control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frac Stack Market |
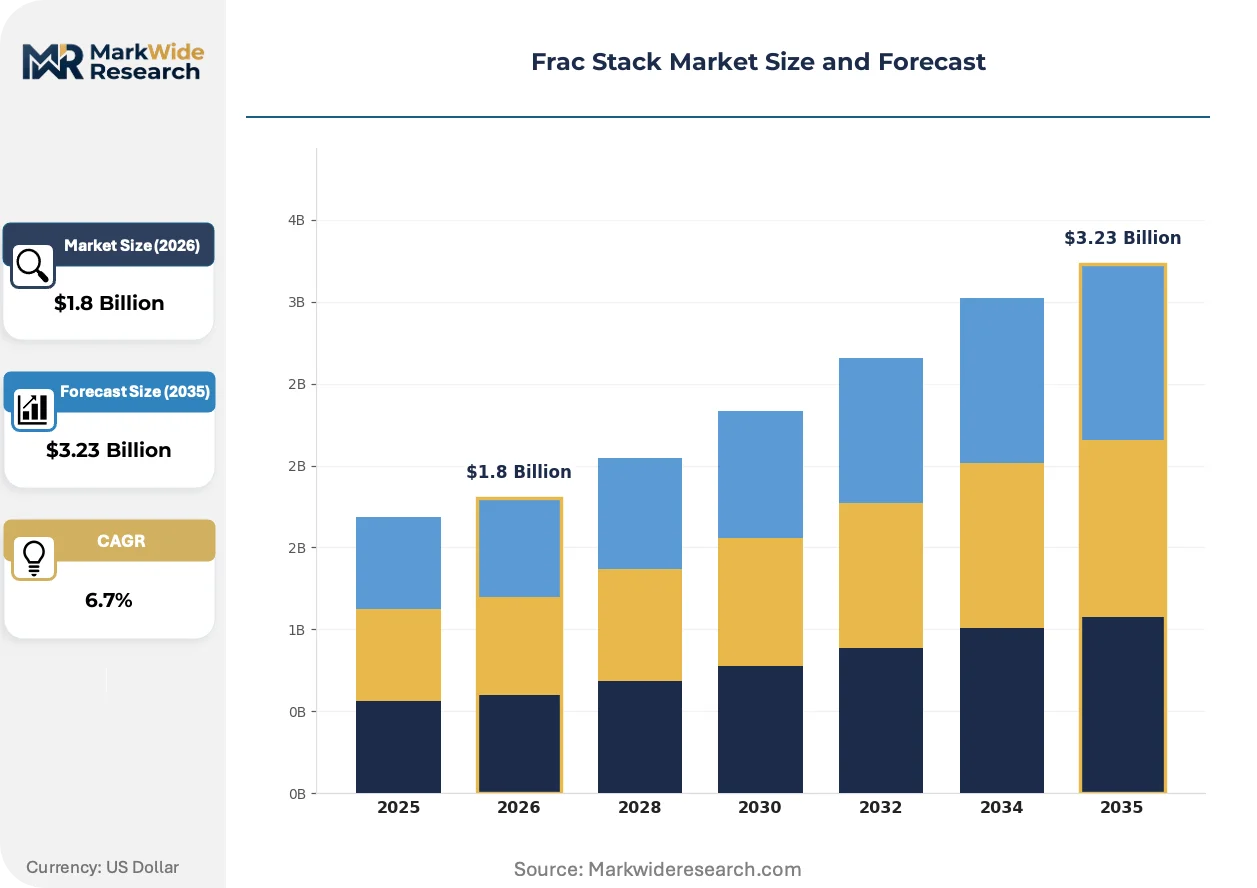
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
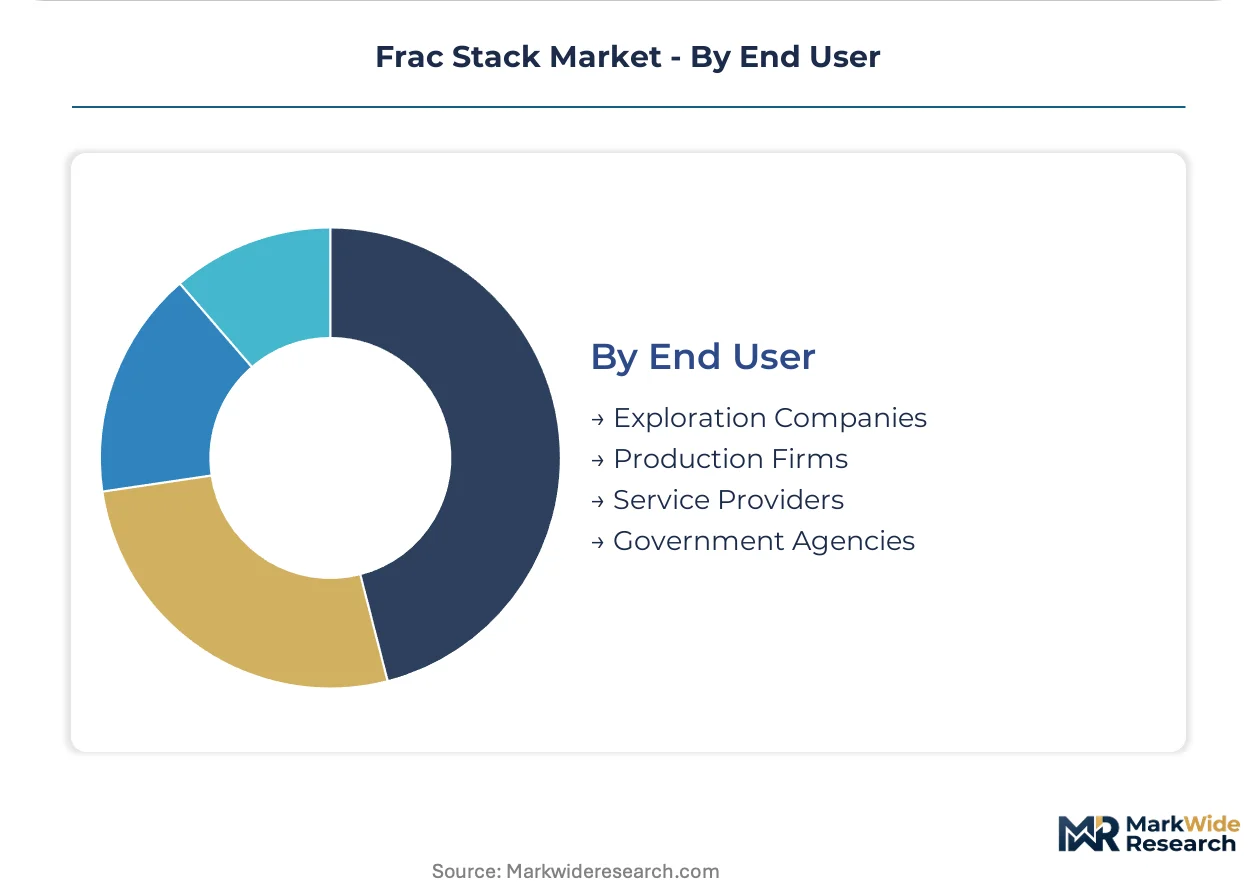
| Segmentation | Product Type: Onshore, Offshore, Hybrid, Portable Application: Shale Gas, Tight Oil, Coalbed Methane, Enhanced Oil Recovery Service Type: Consulting, Installation, Maintenance, Operations End User: Exploration Companies, Production Firms, Service Providers, Government Agencies |
| Companies Covered | The Weir Group PLC, Halliburton Company, Oil States Energy Services, NOV Inc., Baker Hughes Company, CCSC Petroleum Equipment Ltd Co, Covenant Testing Technologies LLC, Calfrac Well Services Ltd., Schlumberger Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frac Stack Market Emerging Trajectories
Digital instrumentation and modular architecture are displacing conventional frac stack designs, while regulatory pressure on methane containment is accelerating material upgrades across the installed base.
Composite valve trim assemblies incorporating tungsten carbide coatings are absorbing erosive wear from proppant-laden flowback fluids. Operators in the Permian Basin are specifying these configurations on new builds to extend maintenance intervals. The technology is absorbing replacement demand that previously cycled through standard alloy trim every 90 days.
EPA's supplemental methane rule under the Clean Air Act is mandating continuous monitoring and repair protocols for wellhead equipment. Stack manufacturers must now certify sealing systems to tighter fugitive emissions standards. The regulation is compressing design cycles as engineering teams redesign bonnet seals and stem packing for compliance.
Contractors are consolidating procurement around OEM-integrated service packages that bundle equipment, maintenance, and analytics. The spot-rental model for individual stack components is losing share to multi-year fleet management agreements. This concentration is most visible in the Delaware Basin where supermajors are reducing vendor counts to simplify compliance documentation.
Frac Stack Market Segmentation

Frac stack procurement patterns diverge sharply across operational contexts. Capital allocation, deployment frequency, and regulatory exposure vary by product configuration, application geology, and service model.
Product Type:
Capital intensity peaks with permanent offshore installations requiring subsea-rated metallurgy and corrosion-resistant coatings.
- Onshore:Fixed wellhead-mounted assemblies rated to 15,000 psi dominate the installed base. Permian Basin pad drilling compresses redeployment cycles to 48-hour rig-up windows, accelerating wear on isolation valves and chokes.
- Offshore:Platform-integrated stacks demand API 6A PR2 certification and duplex stainless steel construction. Gulf of Mexico operators specify these for subsea tiebacks where intervention vessel day rates exceed $500,000.
- Hybrid:Modular configurations bridge onshore portability with offshore pressure ratings. Bakken producers deploy these for temporary waterflood conversions.
- Portable:Skid-mounted units with pre-assembled manifolds reduce rig-up time by 60%. Delaware Basin contractors pay 25-40% premiums for rapid deployment capability.
Onshore configurations absorb the bulk of installed capacity; portable units are expanding most quickly.
Application:
Application selection correlates directly with formation pressure gradients and proppant intensity requirements.
- Shale Gas:Marcellus and Haynesville operators run extended stage counts exceeding 60 per lateral. Stack assemblies face thermal cycling stress from repeated pressure pulsing during zipper frac operations.
- Tight Oil:Permian Wolfcamp and Bakken Three Forks formations drive demand for 20,000 psi-rated components. Delaware Basin laterals now average 12,000 feet, demanding sustained pressure integrity across longer stimulation intervals.
- Coalbed Methane:Lower-pressure formations in Powder River Basin utilize simplified 10,000 psi stacks. CBM operators prioritize cost minimization over premium metallurgy.
- Enhanced Oil Recovery:CO2 flood operations in Permian mature fields require corrosion-resistant trim materials. EOR stacks incorporate monel alloy seats to withstand supercritical CO2 exposure.
Tight oil applications command the highest unit pricing; shale gas maintains the largest fleet deployment.
Service Type:
Revenue recurrence distinguishes asset-light service models from capital-heavy equipment ownership.
- Consulting:Engineering firms advise on stack specification for high-pressure/high-temperature wells. Bakken operators engage consultants for zipper frac manifold optimization.
- Installation:Rig-up crews handle pressure testing and commissioning. Permian Basin labor shortages have extended installation lead times by 30%.
- Maintenance:Predictive service contracts now bundle sensor monitoring with scheduled rebuilds. OEMs capture recurring revenue through valve trim replacement programs.
- Operations:Managed pressure drilling contractors assume full stack operation liability. Supermajors in Eagle Ford outsource operations to reduce insurance exposure.
Maintenance services generate the most predictable revenue streams; operations contracts are climbing the fastest.
End User:
Procurement authority concentrates with entities controlling drilling schedules and capital budgets.
- Exploration Companies:Wildcatters in emerging shale plays prioritize rental flexibility over ownership. Appalachia independents lease stacks on 90-day terms.
- Production Firms:Mature field operators in Permian Delaware Basin own fleet assets outright. These firms specify API 6A latest edition for new purchases.
- Service Providers:Halliburton and Baker Hughes maintain captive frac stack inventories for bundled pumping services. Pressure pumpers capture margin through equipment utilization optimization.
- Government Agencies:State oil companies in Argentina and Mexico import certified stacks for Vaca Muerta and offshore development. Pemex procurement requires local content compliance.
Production firms hold the largest owned fleet; service providers are gaining share fastest through integrated offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty steel mills in Pittsburgh and Essen supply forged valve bodies to frac stack fabricators worldwide. Demand geography tracks shale basin development density and regulatory enforcement intensity across North America, South America, and the Middle East.
United States
Permian Basin pad drilling and Delaware Basin extended laterals drive stack turnover. EPA methane rules under the Clean Air Act mandate certified sealing systems. Midland-Odessa contractors pay premiums for portable skid-mounted units with sub-48-hour rig-up windows.
Canada
Montney Formation operators specify cold-weather-rated assemblies for winter stimulation programs. The country's national energy regulator enforces pressure-equipment registration for interprovincial transport. Calgary-based service providers maintain captive inventories for bundled pressure-pumping contracts.
Mexico
Pemex procurement for onshore mature fields creates demand for corrosion-resistant EOR configurations. Local content requirements shape import qualification for certified high-pressure systems. Burgos Basin development concentrates activity near Reynosa manufacturing clusters.
Argentina
Vaca Muerta shale infrastructure gaps present white-space demand for import-qualified 20,000 psi-rated stacks. The national hydrocarbons regulator oversees wellhead equipment certification for unconventional development. Neuquén Province drilling activity centers on Loma Campana and La Amarga Chica blocks.
Saudi Arabia
Unconventional gas targets in Jafurah Basin require high-pressure assemblies for tight gas stimulation. The national oil company mandates API 6A latest edition for all wellhead equipment procurement. Eastern Province fabrication yards near Dammam supply regional offshore and onshore projects.
Frac Stack Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue digital instrumentation and predictive maintenance bundles. The vendor base clusters around three archetypes: integrated oilfield services conglomerates with captive equipment fleets, specialized pressure-control fabricators with foundry-to-field integration, and regional rental specialists optimizing utilization rates. Competitive moves center on multi-year fleet management agreements and backward integration into specialty steel forging.
Among UK-based engineering groups, The Weir Group PLC exemplifies foundry-to-field vertical integration. Halliburton Company and Baker Hughes Company anchor the integrated services tier with captive frac stack inventories deployed across Permian and Eagle Ford operations. These three entities represent distinct strategic positions: upstream manufacturing control, bundled service provision, and digital monitoring differentiation.
| Leading Market Players |
|---|
| The Weir Group PLC |
| Halliburton Company |
| Oil States Energy Services |
| NOV Inc. |
| Baker Hughes Company |
| CCSC Petroleum Equipment Ltd Co |
| Covenant Testing Technologies LLC |
| Calfrac Well Services Ltd. |
| Schlumberger Limited |
| Others |
Supply Flow & Price Mechanics
Specialty steel forgings from Pittsburgh and Essen flow through three pricing tiers determined by pressure certification and service bundling intensity. Buyers in the Permian Basin absorb 25-40% premiums for portable skid-mounted units where rapid rig-up windows compress contractor selection criteria.
Pricing Analysis
Warranty and predictive maintenance bundling separate premium OEM service contracts from spot-rental component transactions. Three-tier pricing structure across premium, standard, and economy levels tracks API 6A certification grade and geographic delivery logistics. Cost compression in the refurbished equipment tier intensifies as secondary markets absorb decommissioned fleet assets from mature plays. Exploration companies leasing on 90-day terms exhibit highest price sensitivity; production firms owning captive fleets prioritize certification compliance over unit economics.
Supply Chain Analysis
Refurbishment and remanufacturing flows from decommissioned Permian and Bakken fleets feed secondary market channels with recertified assemblies. Forged valve bodies draw from specialty steel mills concentrated in the United States and Germany, with tungsten carbide coatings sourced from industrial ceramics suppliers. Single-source vulnerability in ASME Section IX welder certification creates production bottlenecks during demand spikes. Distribution runs through OEM-integrated service packages and regional rental specialists optimizing utilization rates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where foundry-to-field control over specialty steel forging and high-pressure valve production determines margin capture. Players pursue upstream control over alloy supply and downstream service bundling to lock in fleet management agreements.
For Market Incumbents: Hedge against refurbished equipment arbitrage by embedding sensor arrays and predictive analytics into multi-year service contracts. Secure captive supply of forged valve bodies through backward integration into specialty steel mills. Defensive moves must address welder certification backlogs constraining OEM production capacity.
For New Entrants and Emerging Players: Enter via Argentina's Vaca Muerta shale infrastructure gaps where import-qualified 20,000 psi-rated systems face limited qualified competition. White-space demand concentrates in Neuquén Province drilling activity around Loma Campana and La Amarga Chica blocks. Digital monitoring retrofits on analog wellhead control systems offer a technical wedge for service bundling.
For Investors and Strategic Acquirers: EPA supplemental methane rule enforcement is the leading indicator that sealing system redesign cycles will accelerate, favoring OEMs with compliant engineering bandwidth. Long-term viability hinges on recurring revenue from maintenance services rather than transactional equipment sales. Acquisition targets should demonstrate foundry-to-field integration or captive predictive analytics platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Steel Forging | Pittsburgh and Essen mill partnerships secure valve body supply during demand spikes. |
| Predictive Maintenance Platform Development | Sensor-embedded service contracts capture recurring revenue from Permian operators. |
| API 6A PR2 Certification Investment | Gulf of Mexico platform specifications require subsea-rated metallurgy compliance. |
| Portable Skid-Mounted Configuration Expansion | Delaware Basin contractors pay premiums for sub-48-hour rig-up capability. |
| Vaca Muerta Market Entry Partnership | Argentina's national hydrocarbons regulator oversees unconventional development certification. |
Methodological Framework
Multi-period observation of frac stack deployment cycles, pressure-rating specifications, and service contract structures anchored the trend analysis, supplemented by interviews with pressure-pumping operations directors, wellhead equipment procurement managers, aftermarket service heads, and shale play drilling superintendents. Secondary validation drew from SEC 10-K filings of integrated oilfield services firms, EIA drilling productivity reports, EPA regulatory dockets on methane emissions standards, and API certification registries. Bottom-up fleet inventory counts triangulated against top-down pressure-pumping capacity estimates across the Permian, Eagle Ford, Bakken, and Marcellus basins.
Input-output matrices mapped pressure-rating tier demand against alloy supply constraints and welder certification capacity across the projection horizon. Segmentation dimensions modeled include product configuration, application geology, service model, and end-user procurement authority. CAGRs were derived from equipment replacement cycle compression and pad drilling intensity trajectories. Forecast inputs incorporated EPA regulatory compliance timelines and lateral length extension patterns in tight oil formations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt alloy price volatility or accelerated state-level flaring restrictions. Practitioners should monitor welder certification queue lengths and EPA methane rule enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Fabrication Market
Oil & Gas
Well Completion Market
Oil & Gas
GCC Oil and Gas Separation Market
Oil & Gas
Global Oil and Gas Analytics Market
Oil & Gas
Africa Drilling and Completion Fluids Market
Oil & Gas
Vietnam Oil and Gas Market
Oil & Gas
Oil and Gas Pipeline and Transportation Automation Market
Oil & Gas
Asia-Pacific AI in Oil and Gas Market
Oil & Gas
United States Coiled Tubing Market
Oil & Gas
Australia Oil and Gas Market
Oil & Gas
Drilling Mud Desander and Desilter Market
Oil & Gas
Kazakhstan Oil and Gas Market
Oil & Gas
Spacer Fluid Market
Oil & Gas
Wireline Logging Services Market
Oil & Gas
Casing Centralizer Market
Oil & Gas
Malaysia Oil and Gas Market