
 Egypt Oil and Gas Midstream Market | 2026-2036
Egypt Oil and Gas Midstream Market Size, Share, and Industry Trends Forecast 2026-2036
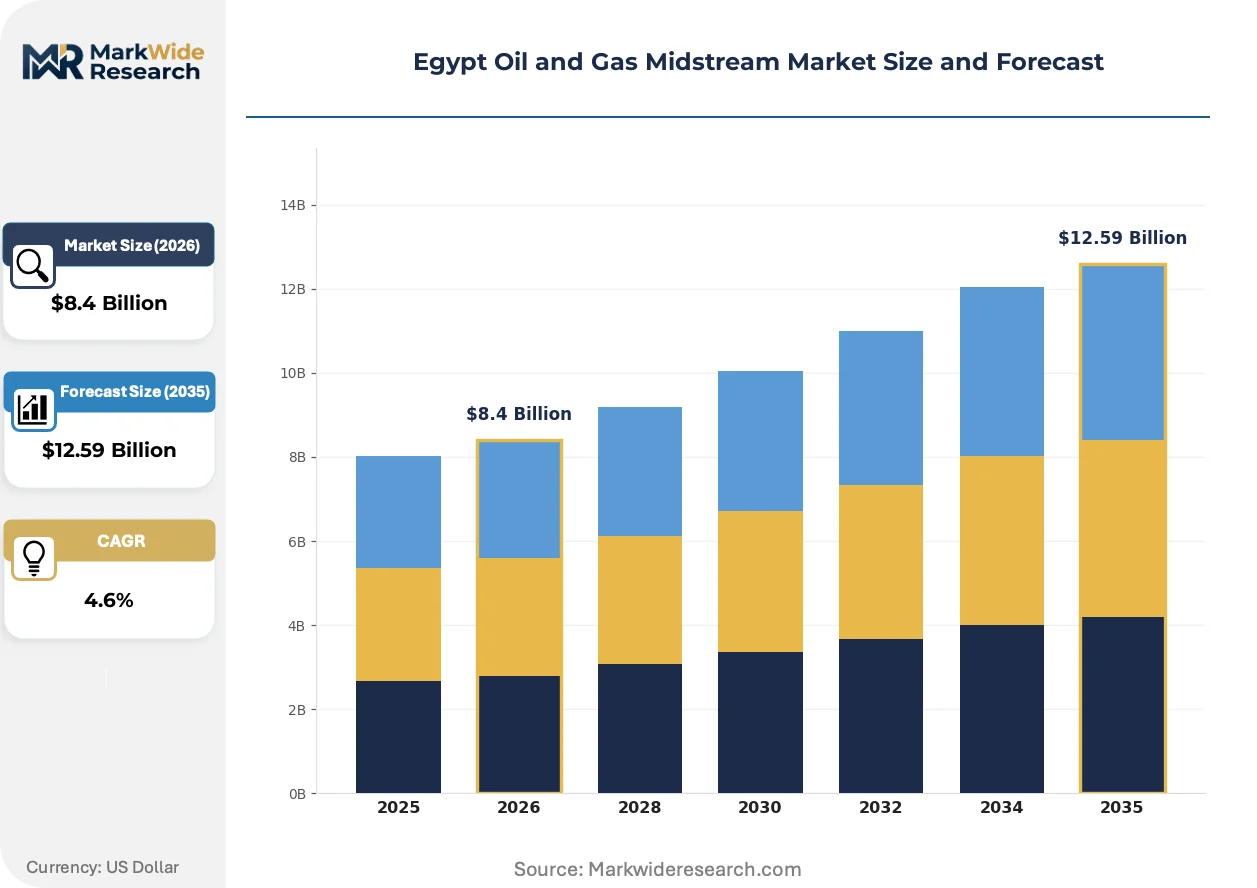
Egypt Oil and Gas Midstream Market Foresight
Pipeline transportation margins is narrowing as storage and terminal services capture higher returns in Egypt's gas corridor. Egyptian Natural Gas Holding Company anchors the national backbone through its control of transmission networks across the Nile Valley. Eni S.p.A. leverages its offshore gas linkages to sustain feedstock flows into Egyptian processing facilities. BP plc competes through its integrated position spanning upstream extraction and midstream handling at key coastal terminals.
Egypt Oil and Gas Midstream encompasses the processing, storage, and transportation infrastructure bridging upstream extraction with downstream refining and distribution, operating through steel pipelines rated for pressures exceeding 70 bar and cryogenic storage systems maintaining LNG at minus 162 degrees Celsius to preserve methane in liquid phase for efficient vessel loading. Pipelines dominate service type revenue given Egypt's 7,000-kilometer transmission grid connecting Western Desert fields to Mediterranean export points, while Storage infrastructure is expanding fastest at Ain Sokhna and Damietta to buffer seasonal demand swings. Infrastructure type segmentation shows Terminals commanding premium margins due to LNG bunkering and transshipment growth through the Suez Canal corridor.
Egypt's Petroleum Regulatory Authority governs third-party access tariffs and technical standards for pipeline interconnectivity, while the Egyptian General Petroleum Corporation sets strategic priorities for national infrastructure prioritization. The Gas Regulatory Authority implements safety protocols for compressor stations and metering facilities under Egypt's energy sector modernization program. Stakeholders must monitor how regulatory rulings on open-access pricing reshape competitive entry for independent operators and infrastructure investors.
Market Dynamics
Third-party access regulations from Egypt's Petroleum Regulatory Authority are fragmenting infrastructure control and forcing incumbents to monetize stranded capacity through open-tariff frameworks.
Growth Catalysts
- Nile Delta gas production surge:Offshore field development is expanding feedstock availability for processing facilities along Egypt's northern coastline.
- Suez Canal Economic Zone clustering:LNG bunkering demand from maritime traffic is creating dedicated storage and terminal investment corridors.
- Petroleum Regulatory Authority open-access framework:Mandatory third-party pipeline tariffs are enabling independent traders to secure transport contracts without legacy offtake agreements.
Market Restraints
- Steel input cost volatility:Pipeline grade steel price fluctuations compress fabrication margins for new transmission line projects.
- Western Desert supply concentration:Upstream production clustering in remote basins extends gathering line distances and elevates compression energy costs.
- Cryogenic equipment technical limitation:LNG storage tank fabrication requires specialized welding certifications that constrain local contractor capacity.
Strategic Opportunities
- Damietta LNG terminal expansion:Underutilized regasification capacity offers conversion pathways for small-scale LNG distribution to industrial zones.
- Red Sea coastal bunkering corridor:Emerging application for LNG-fueled vessels transiting Egypt's southern maritime gateway.
- Petroleum Regulatory Authority storage licensing stream:Fast-track permitting for strategic reserve facilities is accelerating investor entry timelines.
Industry Challenges
- Compressor station automation skill gap:SCADA systems integration requires control systems engineers with cross-vendor certification experience.
- Legacy pipeline metallurgy assessment:Corrosion monitoring protocol updates demand specialized inspection crews familiar with API 1163 standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Oil and Gas Midstream Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.59 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Pipelines, Storage, Transportation, Distribution Infrastructure Type: Refineries, Terminals, Compressor Stations, Pumping Stations Delivery Mode: Liquid, Gaseous, Pressurized, Vacuum Client Type: Energy Companies, Government Agencies, Independent Operators, Infrastructure Investors |
| Companies Covered | Egyptian Natural Gas Holding Company, Egyptian General Petroleum Corporation, Eni S.p.A., Shell PLC, BP plc, Petronas Gas Bhd, Egyptian Fajr Natural Gas Co., Union Fenosa Gas S.A., Spanish Egyptian Gas Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Oil and Gas Midstream Market Shifts & Advancements
Digital infrastructure monitoring and modular processing units are compressing deployment timelines across Egypt's gas corridor. These shifts are reconfiguring how operators balance fixed-asset intensity against operational flexibility.
Digital twin simulation for pipeline integrity management is collapsing the gap between predictive maintenance cycles and actual failure events. Egyptian Natural Gas Holding Company subsidiaries are deploying these systems across high-pressure transmission segments. The technology is collapsing traditional inspection intervals from annual physical surveys to continuous virtual monitoring.
Egypt's Petroleum Regulatory Authority third-party access tariff methodology is mandating cost-reflective pricing for pipeline interconnectivity. This framework is forcing incumbents to disclose operational expenditure benchmarks previously treated as proprietary. Coastal terminal operators are responding by unbundling storage from transport services to maintain margin capture.
Power generation utilities are consolidating gas procurement through long-term offtake agreements directly with midstream terminal operators. This disintermediation is bypassing traditional aggregator intermediaries that historically managed delivery scheduling. The shift is most visible in the Suez Canal Economic Zone where independent power producers require guaranteed feedstock security.
Egypt Oil and Gas Midstream Market Segmentation
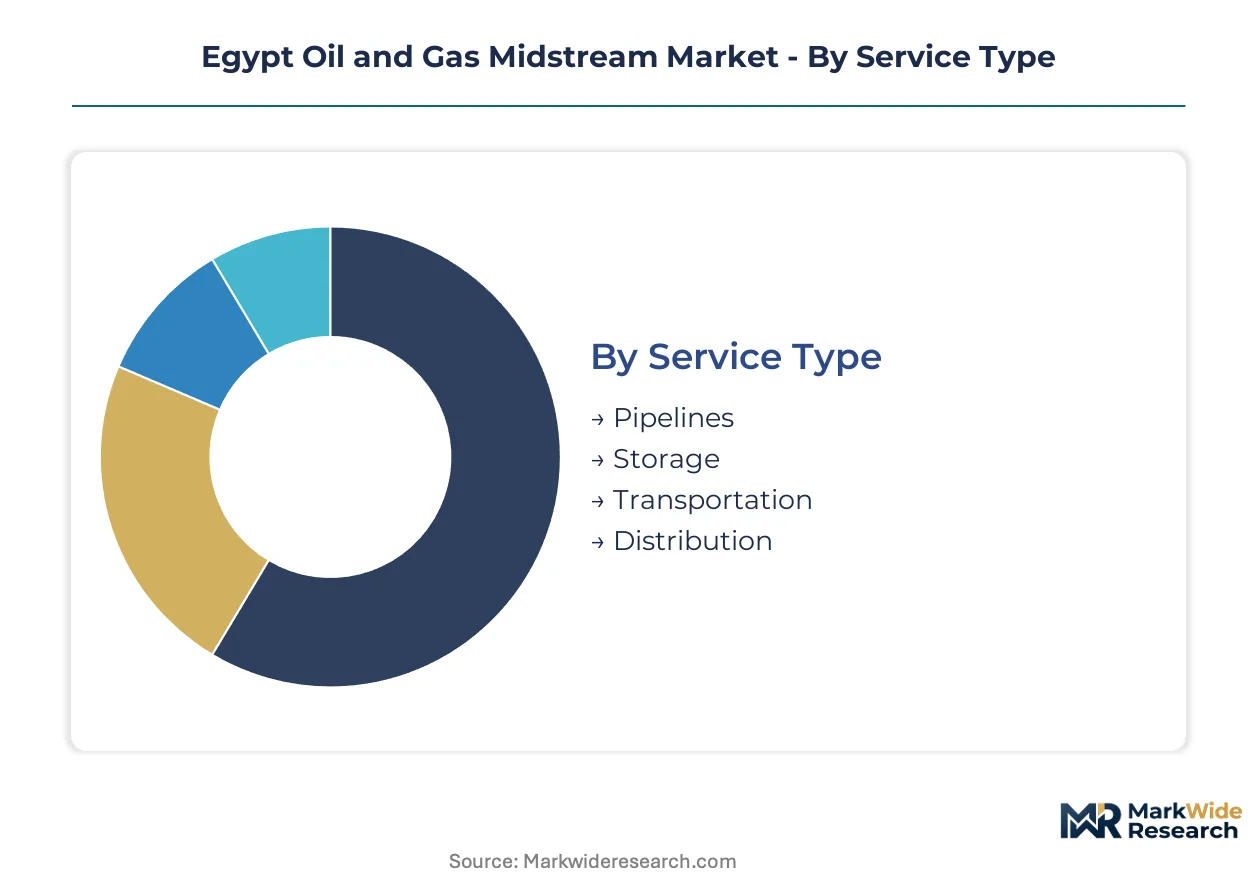
Egypt's midstream infrastructure serves distinct operational requirements across the Nile Valley corridor. Service configurations vary by pressure ratings, throughput volumes, and regulatory compliance tiers.
Service Type:
Pipelines anchor bulk hydrocarbon movement while storage buffers seasonal demand swings across Egypt's gas network.
- Pipelines:Steel transmission lines rated above 70 bar connect Western Desert production to Mediterranean export terminals. Egyptian Natural Gas Holding Company controls the backbone grid linking offshore fields to coastal processing.
- Storage:Cryogenic tanks and underground salt caverns maintain strategic reserves at Ain Sokhna and Damietta. The Petroleum Regulatory Authority's fast-track licensing is accelerating capacity additions for LNG export buffering.
- Transportation:Marine vessel chartering and railcar fleets handle liquid petroleum movements to Red Sea terminals.
- Distribution:Last-mile networks deliver processed gas to industrial zones and power generation utilities clustered in the Suez Canal Economic Zone.
The dominant share belongs to Pipelines, while Storage is closing the gap fastest.
Infrastructure Type:
Facility economics diverge sharply between processing-intensive assets and flow-control installations.
- Refineries:Catalytic cracking and hydrotreating units convert crude into refined products for domestic consumption. Most capacity concentrates around Cairo-Alexandria corridor demand centers.
- Terminals:LNG loading berths and bunkering facilities command premium margins through Suez Canal transshipment traffic. Coastal operators are unbundling storage from transport to defend margin capture.
- Compressor Stations:Gas turbine-driven units maintain pressure across Egypt's 7,000-kilometer transmission grid. SCADA automation upgrades face skill gaps in cross-vendor control systems.
- Pumping Stations:Crude oil pipeline boosters serve Western Desert gathering networks with extended distances elevating energy costs.
Terminals generate the highest returns per throughput unit, with Compressor Stations seeing the steepest modernization investment.
Delivery Mode:
Phase-state selection determines equipment specifications and safety protocols throughout the value chain.
- Liquid:Crude oil and refined products move through insulated pipelines to Red Sea export points.
- Gaseous:Natural gas dominates Nile Delta offtake volumes for power generation feedstock.
- Pressurized:High-density methane transport enables efficient pipeline throughput across long-distance transmission segments.
- Vacuum:Specialized applications in certain processing and maintenance operations.
Pressurized delivery handles the largest volume throughput, while Liquid maintains steady demand from Mediterranean export commitments.
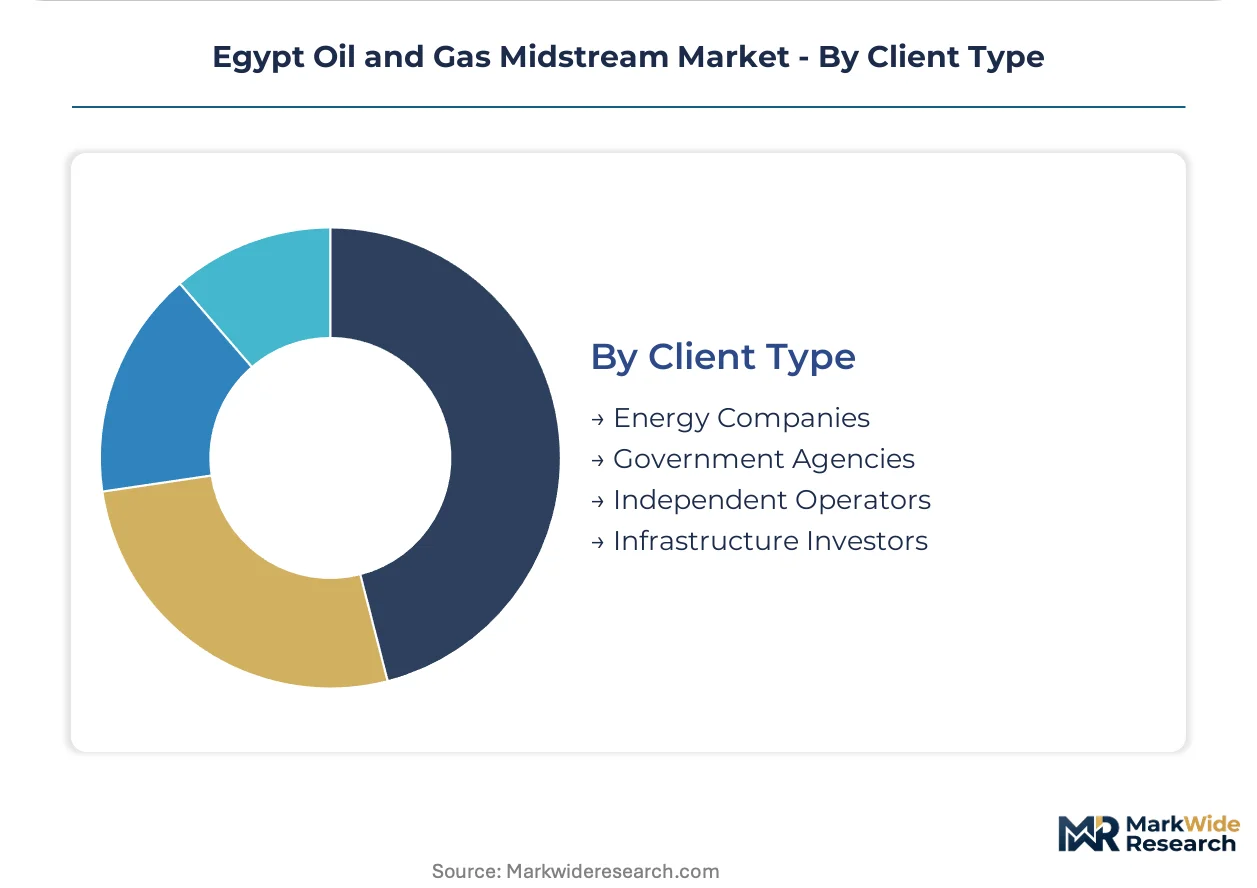
Client Type:
Procurement authority shapes contract structures and infrastructure access priorities.
- Energy Companies:Integrated majors like Eni and BP secure dedicated pipeline capacity through legacy offtake agreements.
- Government Agencies:Egyptian General Petroleum Corporation sets national infrastructure prioritization and strategic reserve mandates.
- Independent Operators:Third-party access tariffs from the Petroleum Regulatory Authority are enabling new entrants without historical aggregator relationships.
- Infrastructure Investors:Private capital targets terminal and storage assets with predictable revenue streams under open-access frameworks.
Energy Companies retain the largest contracted capacity, though Independent Operators are expanding share fastest under regulatory reform.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial buyers in the Nile Delta corridor show the highest price elasticity, while Suez Canal Economic Zone operators absorb premium tariffs for guaranteed throughput security. Egypt's Petroleum Regulatory Authority third-party access framework is redistributing infrastructure control across distinct sub-regional demand profiles.
Cairo-Alexandria Corridor
Power generation utilities anchor gas offtake volumes along this northern axis. The Petroleum Regulatory Authority mandates cost-reflective tariffs for pipeline interconnectivity across the urbanized belt. Refinery complexes at Mostorod and Alexandria process crude feedstock for domestic distribution networks.
Suez Canal Economic Zone
LNG bunkering demand from maritime traffic drives terminal investment clustering at Ain Sokhna. The General Authority for Suez Canal Economic Zone fast-tracks permitting for strategic storage facilities. Independent power producers secure long-term offtake agreements directly with coastal terminal operators.
Nile Delta Offshore
Offshore field development expands feedstock availability for processing facilities at Damietta and Port Said. The Gas Regulatory Authority implements safety protocols for compressor stations serving high-pressure transmission segments. Eni S.p.A. leverages subsea linkages to sustain flows into Egyptian processing infrastructure.
Western Desert
Remote basin production extends gathering line distances and elevates compression energy costs for operators. Egyptian General Petroleum Corporation sets infrastructure prioritization for connecting isolated fields to the national grid. BP plc maintains integrated positions spanning extraction and handling at key coastal terminals.
Red Sea Coastal Zone
Emerging LNG-fueled vessel traffic creates bunkering corridor potential at Safaga and Hurghada. The Petroleum Regulatory Authority storage licensing stream accelerates investor entry timelines for strategic reserve facilities. Marine vessel chartering handles liquid petroleum movements to export terminals.
Egypt Oil and Gas Midstream Market Competitive Landscape
National incumbents and international majors split the market along infrastructure control lines. Egyptian Natural Gas Holding Company anchors the backbone transmission grid through state-mandated ownership of critical pipeline segments. Three archetypes dominate: state-controlled national champions, integrated international oil companies with upstream-midstream positions, and independent operators exploiting third-party access frameworks. Competitive moves concentrate on unbundling storage from transport services and securing long-term offtake agreements with power utilities.
Within the national champion tier, Egyptian Natural Gas Holding Company and Egyptian General Petroleum Corporation exemplify state-controlled infrastructure dominance. Among international operators, Eni S.p.A. and BP plc occupy positions bridging offshore production with coastal terminal access. These entities represent the integrated model where upstream extraction rights translate into dedicated midstream capacity allocation.
| Leading Market Players |
|---|
| Egyptian Natural Gas Holding Company |
| Egyptian General Petroleum Corporation |
| Eni S.p.A. |
| Shell PLC |
| BP plc |
| Petronas Gas Bhd |
| Egyptian Fajr Natural Gas Co. |
| Union Fenosa Gas S.A. |
| Spanish Egyptian Gas Company |
| Others |
Supply & Pricing Matrix
Steel input cost volatility compresses fabrication margins for Egyptian pipeline projects while simultaneously widening spreads between spot-indexed and long-term contract tariffs. Egyptian Natural Gas Holding Company's tariff unbundling under Petroleum Regulatory Authority mandates forces operators to disclose operational expenditure benchmarks, collapsing traditional pricing opacity and reshaping how supply chain participants negotiate capacity allocation.
Pricing Analysis
After-sales service contracts for SCADA maintenance and compressor station automation anchor lifetime value capture for Egyptian midstream operators. Long-term offtake agreements with power generation utilities dominate pricing structures, with contract-based frameworks separating guaranteed feedstock security from spot-indexed flexibility. Price differentiation hinges on volume scale and certification tier under Gas Regulatory Authority safety protocols, with independent operators facing compression from legacy incumbents' bundled service offerings. Cost compression in cryogenic tank fabrication intensifies as specialized welding certification scarcity elevates contractor premiums, while Suez Canal Economic Zone operators absorb premium tariffs for guaranteed throughput security.
Supply Chain Analysis
Export-control restrictions on high-pressure pipeline steel and cryogenic equipment limit technology flows into Egyptian fabrication yards. Supply concentration centers on China, South Korea, and Germany for specialized compressor turbines, cryogenic storage tanks, and SCADA control systems. Raw material dependencies include pipeline-grade steel, nickel-based alloys for LNG containment, and gas turbine components. Single-source vulnerability runs through specialized welding certification programs that constrain local contractor capacity. Distribution runs through Red Sea maritime corridors and Nile Valley rail networks connecting Western Desert production to Mediterranean terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Egyptian midstream sector rewards operators who control scarce automation engineering capabilities and cryogenic fabrication certifications, with skill gaps in SCADA integration and API 1163 inspection standards creating persistent entry barriers.
For Market Incumbents: Entrench control over high-pressure transmission corridors by accelerating SCADA automation deployment across Nile Delta segments before independent operators secure Petroleum Regulatory Authority interconnectivity approvals. Deepen backward integration into cryogenic equipment maintenance capabilities to capture service revenue streams that third-party access tariffs threaten to commoditize. Prioritize compressor station modernization at Damietta and Ain Sokhna to defend margin position against emerging terminal competitors. For New Entrants and Emerging Players: Red Sea coastal bunkering corridors at Safaga and Hurghada offer underpenetrated entry points where LNG-fueled vessel traffic growth outpaces incumbent infrastructure deployment. Target small-scale LNG distribution to industrial zones bypassing Egyptian Natural Gas Holding Company's backbone grid through Damietta's underutilized regasification capacity. Secure fast-track storage licensing from the Petroleum Regulatory Authority to accelerate facility commissioning timelines relative to legacy permit processes. For Investors and Strategic Acquirers: Petroleum Regulatory Authority tariff methodology rulings reshape the acquisition landscape by forcing operational expenditure disclosure that enables precise asset valuation. Terminal and storage assets with predictable revenue streams under open-access frameworks offer viable long-term holds, particularly where unbundled service models separate transport from storage margins. Monitor Gas Regulatory Authority safety protocol updates as inflection indicators for compressor station modernization investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Compressor Station Automation Upgrade | SCADA deployment across Nile Delta segments addresses skill gaps flagged by Gas Regulatory Authority safety mandates. |
| Cryogenic Equipment Certification Investment | Specialized welding programs unlock local LNG tank fabrication capacity constrained by contractor scarcity. |
| Third-Party Interconnectivity Agreement | Petroleum Regulatory Authority open-tariff frameworks enable independent operators to secure transport contracts. |
| Red Sea Bunkering Infrastructure Buildout | LNG-fueled vessel traffic through Safaga and Hurghada creates dedicated storage and terminal investment corridors. |
| Strategic Reserve Storage Licensing | Fast-track permitting accelerates investor entry timelines for Ain Sokhna and Damietta capacity additions. |
Research Methodology
Operator-level perspectives from pipeline control room engineers, terminal operations managers, EPC contractors, and Petroleum Regulatory Authority licensing officers anchored the qualitative base for this analysis. Primary interviews with Egyptian Natural Gas Holding Company subsidiaries and independent storage developers combined with secondary validation from Egyptian General Petroleum Corporation strategic planning documents, Gas Regulatory Authority safety filings, and Suez Canal Economic Zone development authority permits. Bottom-up capacity assessments across the 7,000-kilometer transmission grid triangulated against top-down infrastructure investment forecasts from national energy modernization program disclosures.
Scenario-bracketing framed the analytical approach across the projection horizon, modeling demand trajectories under varying Nile Delta production expansion assumptions and Suez Canal maritime traffic growth paths. Segmentation dimensions included service type, infrastructure category, delivery mode phase-state, and client procurement authority, with regional clustering across Cairo-Alexandria, Suez Canal Economic Zone, Nile Delta Offshore, Western Desert, and Red Sea Coastal sub-markets. CAGRs derived from throughput volume modeling against tariff rate evolution under third-party access frameworks, incorporating compressor station efficiency assumptions and LNG export terminal utilization benchmarks.
Practitioners should monitor Petroleum Regulatory Authority tariff rulings, Gas Regulatory Authority safety protocol amendments, and Nile Delta offshore field development timelines for early signals requiring forecast revision. Cross-checking against Egyptian General Petroleum Corporation infrastructure prioritization announcements and international LNG spot price indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
South and Central America Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Europe Oil and Gas Drones Market
Oil & Gas
Europe Completion Equipment and Services Market
Oil & Gas
Drilling and Completion Fluids Market
Oil & Gas
United States Oil and Gas Market
Oil & Gas
Global Drilling Jars Market
Oil & Gas
Oil and Gas Separator Market
Oil & Gas
Argentina Oil and Gas Upstream Market
Oil & Gas
Oil and Gas Automation Market
Oil & Gas
Oil and Gas Processing Seals Market
Oil & Gas
Middle East and Africa Early Production Facility Market
Oil & Gas
Oman Oil and Gas Upstream Market
Oil & Gas
Asia-Pacific Well Intervention Market
Oil & Gas
Middle East and Africa Pipeline Maintenance Market
Oil & Gas
Middle-East Oilfield Services Market
Oil & Gas
Tricone Bits Market