
 China Bunker Fuel Market | 2026-2036
China Bunker Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
China Bunker Fuel Market Outlook
China's Maritime Safety Administration low-sulfur fuel mandate is shifting the cost-of-entry calculus for regional bunker suppliers. Sinopec leverages its integrated refinery network to capture coastal demand from bonded storage terminals. CNOOC anchors its position through LNG bunkering investments at Shenzhen and Tianjin port zones. UNIPEC competes via direct procurement contracts with state-owned shipping conglomerates.
China bunker fuel denotes marine-grade residual oil and distillate products meeting ISO 8217 specifications, with sulfur content capped at 0.50% mass fraction for international voyages and 0.10% within designated emission control areas; these fuels power main and auxiliary engines aboard oceangoing vessels. IFO380 and IFO180 remain the volume backbone for deep-sea commercial shipping, though margin pools are migrating toward MGO and LNG as scrubber economics deteriorate. The supply chain stage dimension reveals refiners capturing value through captive blending capacity while distributors face compression from port authority direct sourcing programs.
MIIT emissions standards, MEE marine fuel quality protocols, and SAMR product certification requirements collectively tighten product specifications and market access for non-compliant importers. China's GB standards for marine distillates now align with IMO 2020 sulfur limits, forcing traders to verify laboratory documentation at each bonded transfer. Stakeholders must monitor whether Ningbo-Zhoushan's LNG bunkering pilot expands into enforceable quota systems that reshape fuel procurement portfolios.
Market Dynamics
China's bunker fuel market is being restructured by the Maritime Safety Administration's low-sulfur fuel mandate, which has compressed scrubber economics and redirected capital toward LNG bunkering infrastructure at Yangtze River Delta port clusters.
Growth Catalysts
- Dual Carbon Goals:China's national carbon neutrality targets are accelerating port authority investment in LNG receiving and bunkering terminals at Ningbo-Zhoushan and Shanghai.
- MEE Marine Fuel Quality Protocols:Stricter enforcement timelines for sulfur content verification are consolidating demand around bonded storage terminals with in-house laboratory certification.
- Yangtze River Delta Container Expansion:Transshipment volume concentration along this corridor is pulling low-sulfur fuel procurement forward ahead of regulatory deadlines.
Market Restraints
- Refinery Gate Control:Sinopec's captive blending capacity limits independent distributor access to ISO 8217-compliant residual oil feedstock.
- Crude Sourcing Volatility:Heavy sour crude price swings directly compress margin pools for IFO380 and IFO180 production.
- Scrubber Retrofit Stranding:Open-loop scrubber bans at Chinese ports have eroded the investment case for high-sulfur fuel oil compatibility.
Strategic Opportunities
- Guangdong-Hong Kong-Macao Greater Bay Area:Shenzhen's underdeveloped LNG bunkering capacity relative to container throughput offers first-mover positioning.
- Direct Port Authority Sourcing:Tianjin and Qingdao port zones are piloting procurement programs that bypass traditional distributor layers.
- MEE Quota System Expansion:Ningbo-Zhoushan's LNG bunkering pilot could harden into enforceable fuel-mix mandates, reshaping procurement portfolios.
Industry Challenges
- GB Standards Laboratory Certification:Traders face documentation verification burdens at each bonded transfer point under SAMR product certification requirements.
- LNG Cold-Ironing Integration:Shore power compatibility conflicts with dual-fuel engine commissioning timelines at retrofit yards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Bunker Fuel Market |
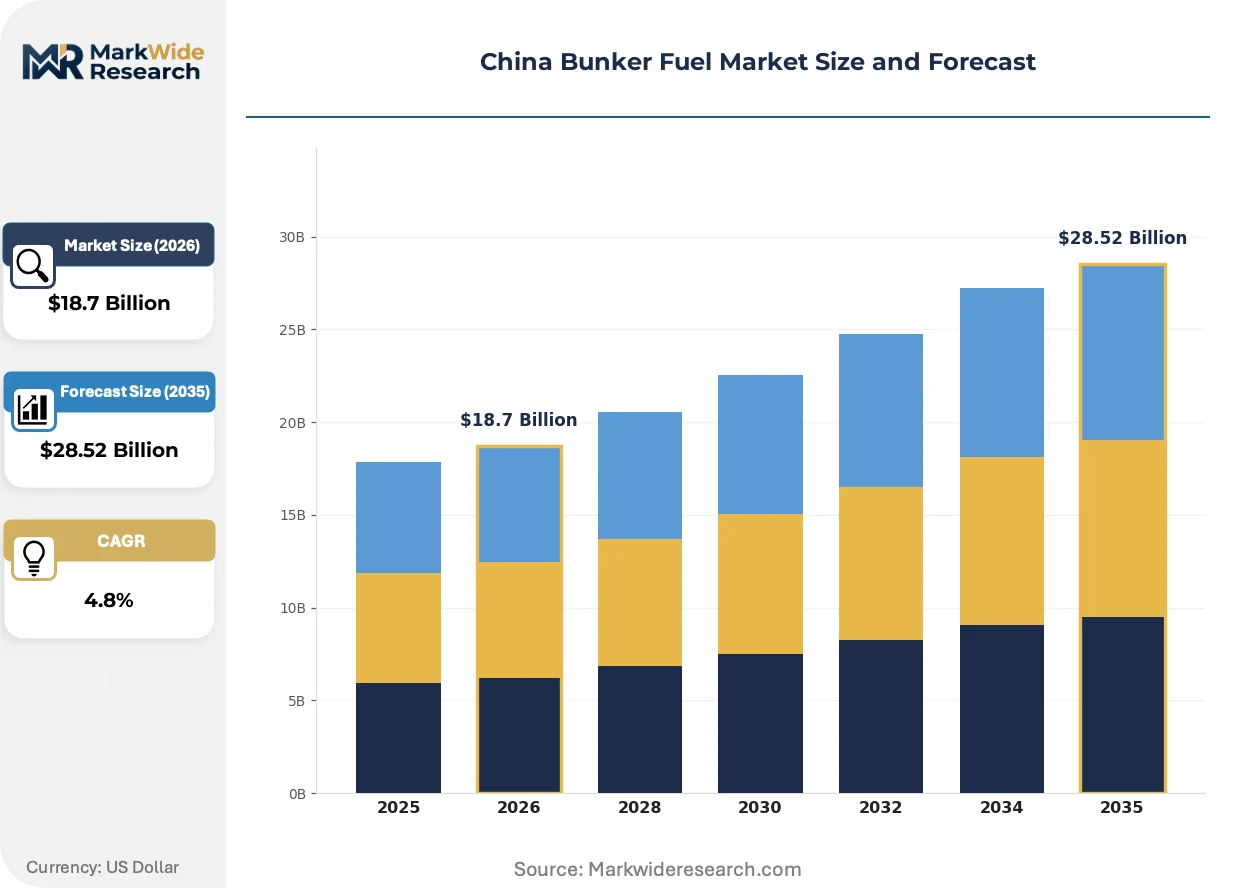
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: IFO380, IFO180, MGO, LNG End User: Shipping Lines, Offshore Vessels, Fishing Industry, Tugboats Supply Chain Stage: Refiners, Distributors, Traders, Retailers Application: Commercial Shipping, Recreational Boating, Fishing Operations, Offshore Activities |
| Companies Covered | CNOOC, UNIPEC, Sinopec, Shanghai PEARL BUNKER, China Changjiang Bunker, CNPC, China Oilfield Services, Guangzhou Port Group, Zhejiang Petrochemical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Bunker Fuel Market Strategic Shifts
LNG bunkering infrastructure is displacing conventional residual oil dependency as the primary vector of competitive differentiation among Chinese port operators. Technology convergence, regulatory tightening, and procurement centralization are compressing legacy supply chain configurations.
Biofuel blending is expanding into marine distillate formulations as refiners seek carbon intensity reductions without full infrastructure replacement. State-owned shipping conglomerates are testing B24 and B30 blends on intra-Asia routes. This transition is expanding into MGO supply contracts that previously excluded alternative fuel clauses.
MIIT emissions standards now align marine engine testing protocols with GB fuel quality specifications, creating unified compliance checkpoints. Engine manufacturers must certify against both hardware efficiency and fuel sulfur content simultaneously. Coastal provinces are responding by consolidating bonded bunker licensing under provincial environmental bureaus.
Container lines are consolidating fuel procurement through direct refinery offtake agreements rather than spot market purchases. This behavior compresses distributor margins while locking in sulfur-compliant supply. The shift is most visible among state-owned shipping conglomerates operating Yangtze River Delta feeder services.
China Bunker Fuel Market Segmentation
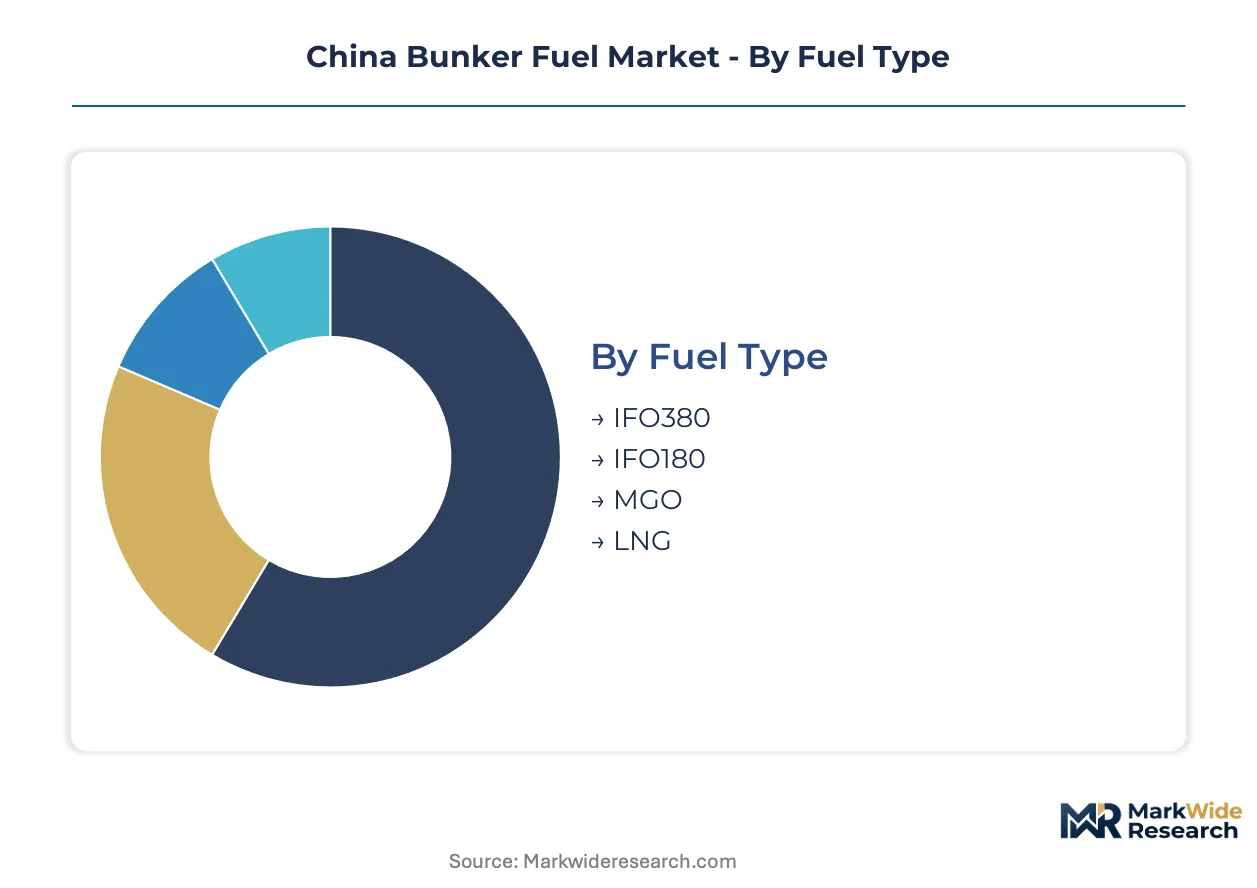
China's bunker fuel segmentation reflects divergent infrastructure requirements across fuel chemistries and supply chain positions. Refiner-captive blending capacity concentrates margin capture in residual oil grades while LNG bunkering demands entirely separate terminal investments. End-use fragmentation between deep-sea container lines and coastal auxiliary fleets creates distinct procurement behaviors.
Fuel Type:
Integration depth separates residual oil grades that flow through existing refinery infrastructure from LNG requiring dedicated cryogenic handling systems.
- IFO380:High-viscosity residual fuel oil meeting ISO 8217 RMG380 specifications serves deep-sea commercial shipping with scrubber-equipped vessels. Yangtze River Delta container terminals anchor demand as MEE sulfur enforcement tightens bonded storage requirements.
- MGO:Marine gasoil provides 0.10% sulfur compliance without exhaust gas cleaning systems, commanding premium pricing in emission control areas. Shenzhen and Tianjin port clusters show fastest uptake among distributors lacking scrubber servicing capabilities.
- IFO180:Lower-viscosity residual grade suits medium-speed auxiliary engines on coastal feeders.
- LNG:Liquefied natural gas bunkering requires specialized cryogenic infrastructure at Ningbo-Zhoushan and Shanghai pilot terminals.
IFO380 leads volumes today; LNG is gaining share fastest.
End User:
Customer scale determines procurement sophistication, with state-owned shipping conglomerates bypassing distributor layers that smaller coastal operators still require.
- Shipping Lines:Container and bulk carriers operating international routes drive bonded bunker demand through direct refinery offtake agreements. COSCO and China Merchants Energy consolidate procurement across Yangtze River Delta feeder networks under MEE quality protocols.
- Tugboats:Harbor auxiliary fleets require high-frequency, small-volume bunkering at port authority terminals.
- Offshore Vessels:Supply boats and drilling support units demand weather-resistant fuel logistics at Tianjin and Qingdao offshore bases.
- Fishing Industry:Coastal trawlers and distant-water fleets source through provincial fishery cooperatives with limited ISO 8217 compliance verification.
Shipping lines dominate revenue concentration; tugboat electrification pilots are expanding fastest.
Supply Chain Stage:
Backward integration intensity varies dramatically, with refiners capturing blending margins that distributors cannot replicate.
- Refiners:Sinopec and CNOOC operate captive ISO 8217 blending capacity at coastal terminals, controlling feedstock access for IFO380 and MGO production. MIIT emissions standards alignment with GB fuel specifications reinforces their certification advantages.
- Distributors:Independent bunker suppliers face margin compression as port authorities pilot direct sourcing programs at Tianjin and Qingdao.
- Traders:UNIPEC and commodity houses manage international arbitrage for heavy sour crude feedstocks.
- Retailers:Terminal operators handle last-mile delivery to vessel manifold connections.
Refiners control upstream margins today; port authority direct sourcing is expanding most quickly.
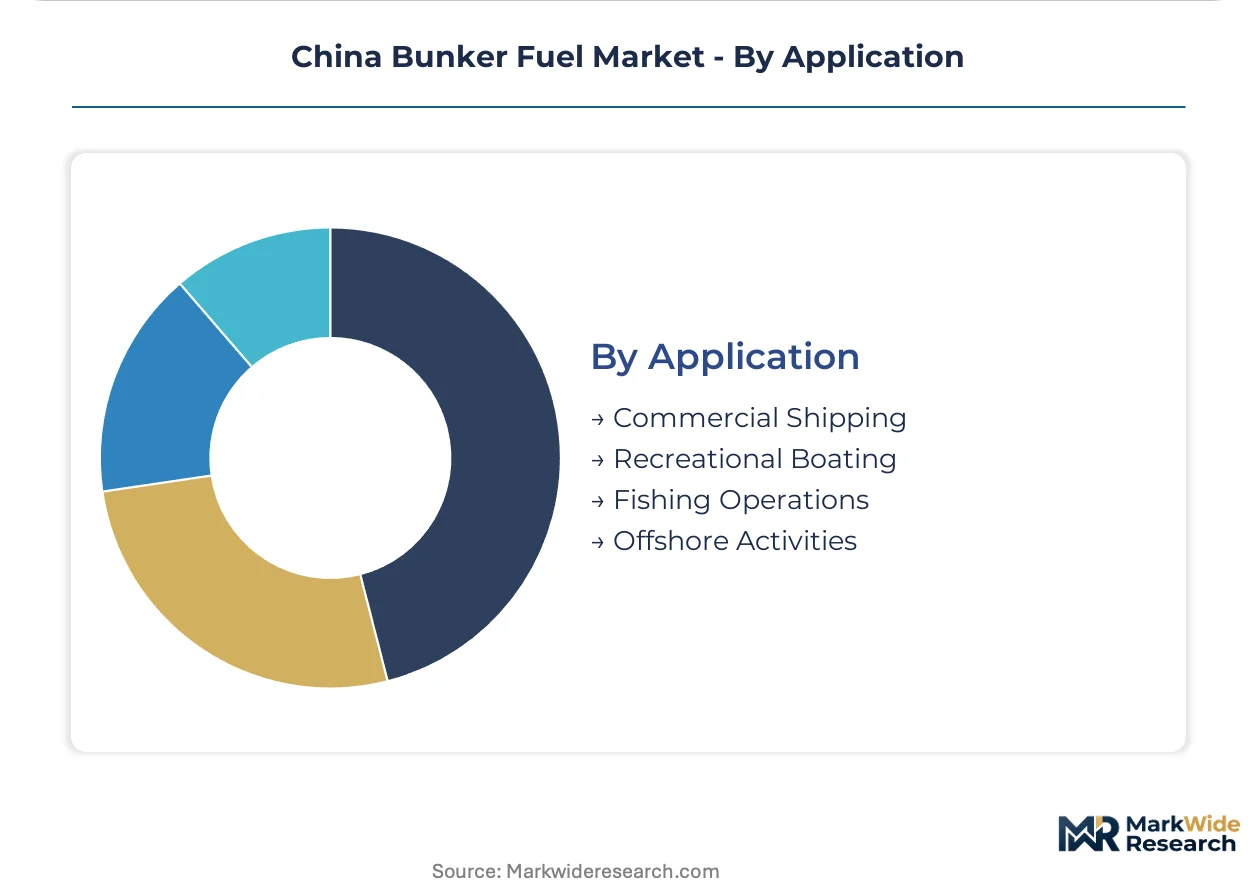
Application:
Regulatory exposure intensity separates internationally traded routes subject to IMO 2020 from domestic coastal operations under evolving MEE timelines.
- Commercial Shipping:Container, bulk, and tanker fleets on international voyages require 0.50% sulfur compliance through bonded bunker supply chains. Ningbo-Zhoushan's transshipment volume concentration pulls low-sulfur procurement forward ahead of enforcement deadlines.
- Offshore Activities:Exploration and production support vessels demand continuous fuel availability at remote operating locations.
- Fishing Operations:Distant-water fleets face fragmented procurement across Pacific and Indian Ocean port networks.
- Recreational Boating:Marina-based leisure craft represent minimal volume but higher MGO specification tolerance.
Commercial shipping anchors demand scale; offshore LNG dual-fuel retrofits show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized refinery technicians and marine logistics professionals concentrate along China's coastal industrial corridors, anchoring regional bunker fuel distribution networks. Port authority engineers and ISO certification specialists cluster at bonded terminal zones, enabling quality-compliant fuel transfers. This workforce geography shapes supply chain configuration across China's maritime provinces.
Guangdong Province
Shenzhen's container throughput expansion and Pearl River Delta transshipment growth drive low-sulfur fuel demand. MEE marine fuel quality protocols enforce sulfur verification at bonded storage terminals. Guangzhou Port Group anchors supply chain coordination across the province's deep-water anchorages.
Zhejiang Province
Ningbo-Zhoushan's LNG bunkering pilot and international transshipment volume concentrate procurement activity. Dual carbon goals accelerate cryogenic infrastructure investment at Zhoushan port clusters. Bonded bunker licensing consolidation under provincial environmental bureaus streamlines compliance verification.
Shanghai Municipality
Yangtze River Delta container feeder networks and scrubber-equipped vessel retrofits reshape fuel procurement patterns. MIIT emissions standards align marine engine testing with GB fuel quality specifications. Shanghai port authority direct sourcing programs compress traditional distributor margins.
Tianjin Municipality
Bohai Rim offshore vessel support and northern container gateway functions sustain residual oil demand. SAMR product certification requirements tighten laboratory documentation at each bonded transfer. Tianjin port zones pilot procurement programs that bypass distributor intermediaries.
Shandong Province
Qingdao's crude oil receiving capacity and independent refinery blending operations supply IFO380 feedstock. Heavy sour crude price volatility directly compresses margin pools for residual fuel production. Shandong Peninsula refiners leverage captive ISO 8217 blending capacity to capture coastal demand.
China Bunker Fuel Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across China's bunker fuel supply chain. State-owned energy majors leverage integrated refinery networks to control feedstock access and blending margins. Independent distributors face compression from port authority direct sourcing initiatives. Three archetypes dominate: upstream-integrated refiners, terminal-captive distributors, and commodity trading houses. Competitive moves concentrate on backward integration into blending capacity and LNG bunkering infrastructure partnerships.
Among state-owned integrated energy groups, Sinopec and CNOOC exemplify the refiner-captive archetype through coastal terminal control. UNIPEC occupies a position representing commodity trading specialists managing international arbitrage. Shanghai PEARL BUNKER and China Changjiang Bunker sit within the regional distributor tier, anchoring last-mile delivery networks at Yangtze River Delta port clusters. These named entities collectively illustrate how supply chain position determines margin capture potential.
| Leading Market Players |
|---|
| CNOOC |
| UNIPEC |
| Sinopec |
| Shanghai PEARL BUNKER |
| China Changjiang Bunker |
| CNPC |
| China Oilfield Services |
| Guangzhou Port Group |
| Zhejiang Petrochemical |
| Others |
Value Chain & Pricing Dynamics
Captive refinery blending at Sinopec and CNOOC terminals anchors both supply security and pricing power for residual fuel grades. This backward integration into ISO 8217 production capacity shields integrated players from feedstock volatility that compresses independent distributor margins.
Pricing Analysis
Bundled fuel-procurement contracts dominate container line relationships while unbundled spot transactions persist for coastal auxiliary fleets. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels reflects GB standards laboratory verification burdens. Cost compression in the standard tier is intensifying because port authority direct sourcing programs eliminate distributor markups. Coastal fishing cooperatives exhibit highest price sensitivity; state-owned shipping conglomerates absorb certification premiums without volume reduction.
Supply Chain Analysis
Specialized refinery technicians and marine logistics professionals cluster along Shandong Peninsula and Yangtze River Delta industrial corridors. China, South Korea, and Singapore anchor geographic supply concentration for heavy sour crude feedstocks. The supply chain draws from residual oil blending components, marine distillate base stocks, and LNG cryogenic handling systems. Single-source vulnerability runs through Sinopec's captive terminal network. Distribution runs through bonded storage terminals with in-house laboratory certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder. China's dual carbon goals and MEE enforcement timelines generate predictable infrastructure replacement cycles that sustain steady growth.
For Market Incumbents: To counter port authority direct sourcing programs, deepen backward integration into LNG bunkering infrastructure at Ningbo-Zhoushan and Shenzhen. Secure SAMR product certification advantages through captive laboratory investments that independent distributors cannot replicate. For New Entrants and Emerging Players: LNG cold-ironing compatibility technology offers entry into retrofit yard partnerships before dual-fuel engine commissioning timelines harden. Target Shenzhen's underdeveloped LNG bunkering capacity relative to container throughput. Pursue equipment-leasing go-to-market models that bypass capital-intensive terminal ownership requirements. For Investors and Strategic Acquirers: Roll-up economics work for regional distributors with bonded terminal licenses because MEE quality protocols are consolidating licensing under provincial environmental bureaus. The five-to-ten year viability window favors acquisition of independent distributors with ISO 8217 laboratory certification in Tianjin and Qingdao port zones. Watch whether Ningbo-Zhoushan's LNG bunkering pilot expands into enforceable quota systems as the inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| LNG Bunkering Infrastructure Buildout | Ningbo-Zhoushan pilot terminal expansion captures dual carbon goal subsidies from MEE. |
| Backward Integration into Blending Capacity | Shandong independent refiners leverage captive ISO 8217 production to bypass Sinopec gate control. |
| Direct Port Authority Sourcing Partnership | Tianjin procurement programs that bypass distributor intermediaries reshape margin capture. |
| GB Standards Laboratory Certification | SAMR compliance verification at bonded transfer points creates defensive moat against unverified imports. |
| Biofuel Blending Supply Agreement | B24 and B30 marine distillate formulations open COSCO procurement contracts to alternative fuel clauses. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement covered refinery operations managers, port authority fuel procurement officers, shipping line bunker buyers, ISO certification laboratory directors, and MEE regulatory enforcement leads. Secondary validation drew from MIIT emissions standard filings, SAMR product certification registries, bonded bunker transfer documentation, and customs trade data for heavy sour crude feedstocks. Bottom-up volume modeling and top-down market sizing triangulated segment-level outputs.
Historical reference periods anchored the projection horizon through trend extrapolation and elasticity calibration. Segmentation dimensions spanned fuel chemistry grades, supply chain integration depth, end-user scale categories, and coastal province regulatory clusters. CAGRs derived from fitted growth curves applied to volume and value baselines. Forecast inputs incorporated scrubber retrofit stranding rates and LNG bunkering infrastructure commissioning timelines.
The model holds under continued MEE enforcement progression and stable heavy sour crude sourcing; deviation in dual carbon goal acceleration or open-loop scrubber ban expansion would shift trajectory. Forecasts reflect documented assumptions about regulatory timeline adherence and refinery capacity utilization. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Middle-East and Africa Defense Aircraft Aviation Fuel Market
Fuels
Europe Bunker Fuel Market
Fuels
UAE Chemical Logistics Market
Fuels
United Kingdom Bunker Fuel Market
Fuels
Industrial Fuel Filter Market
Fuels
Underground Coal Gasification Market
Fuels
Europe Commercial Aircraft Aviation Fuel Market
Fuels
Global Gas Cylinder Market
Fuels
United States Coal Market
Fuels
Renewable Fuel Quality and Regulatory Compliance Test Instruments Market
Fuels
Gasoline Market
Fuels
Coal Gasification Market
Fuels
Singapore Bunker Fuel Market
Fuels
Pyrolysis Gas Market
Fuels
Marine Fuel Filter Market
Fuels
Hybrid Propellants Market