
 Equatorial Guinea Oil and Gas Downstream Market | 2026-2036
Equatorial Guinea Oil and Gas Downstream Market Size, Share, and Industry Trends Forecast 2026-2036
Equatorial Guinea Oil and Gas Downstream Market Foresight
Maintenance and reliability service contracts is recalibrating what downstream operators sell in Equatorial Guinea. Sonagas leverages its state-backed position to anchor national infrastructure control across refining and distribution nodes. ExxonMobil competes through deep operational experience at the Zafiro complex. TotalEnergies differentiates via integrated LNG-to-power project execution along the coast.
The Equatorial Guinea Oil and Gas Downstream sector encompasses refining, storage, distribution, and retailing of petroleum products derived from crude oil and natural gas liquids. Facilities typically process feedstocks through atmospheric distillation, hydrotreating, and fluid catalytic cracking to produce transport fuels and industrial feedstocks serving domestic and regional West African demand. Diesel and jet fuel command structural priority within the product mix, reflecting aviation growth through Malabo International Airport and marine bunkering activity at the Luba Freeport. Advanced refining technology represents the fastest-expanding capability segment, as operators face pressure to meet tighter sulfur specifications and process associated gas more efficiently.
The Ministry of Mines and Hydrocarbons and the national standards body shape fuel specification compliance and local content requirements for downstream investments. Environmental directives from the Economic Community of Central African States influence regional product standards and cross-border trade protocols. Stakeholders must monitor how biofuel blending mandates and carbon accounting frameworks evolve to determine capital allocation between conventional refining upgrades and alternative fuel infrastructure.
Market Dynamics
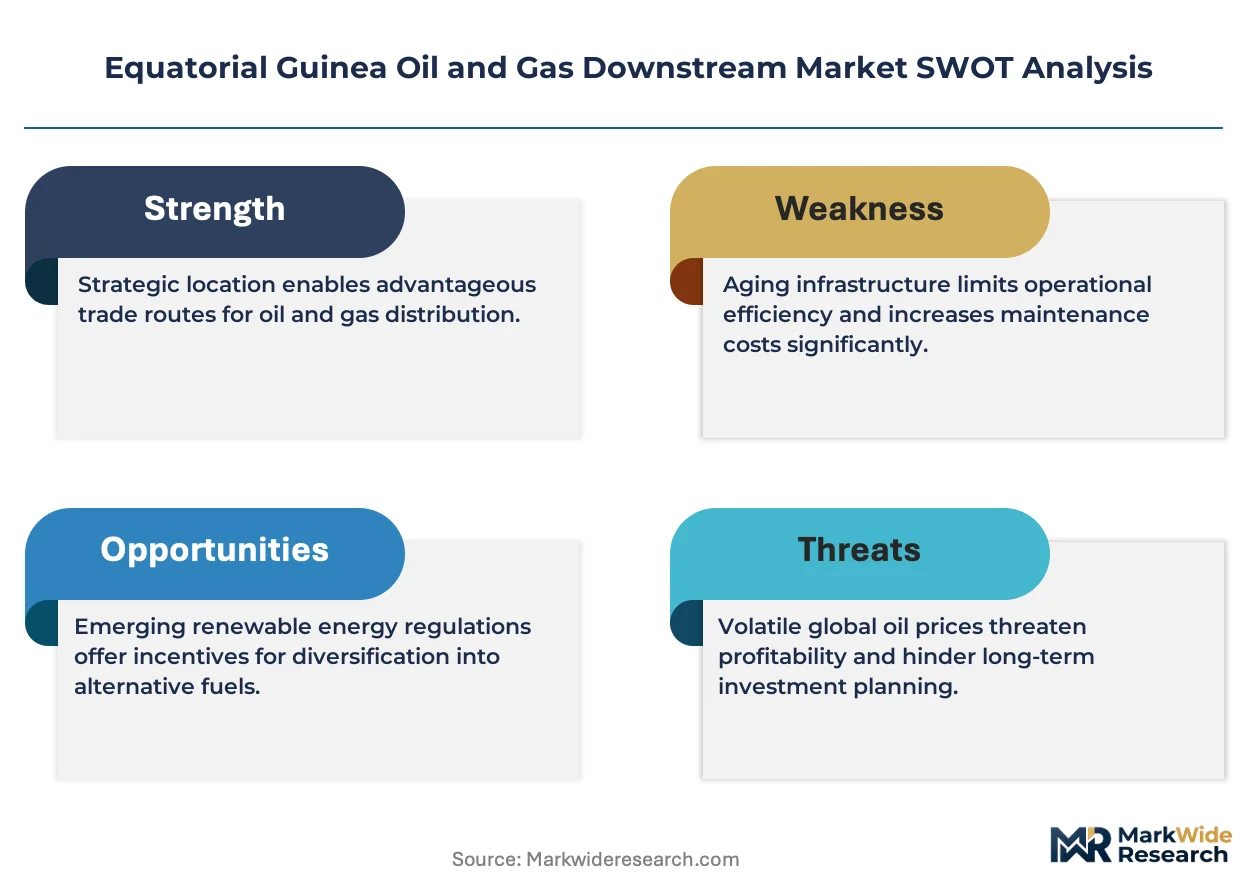
The Equatorial Guinea downstream sector faces structural recalibration as the Ministry of Mines and Hydrocarbons tightens sulfur content specifications for transport fuels. Refineries must now absorb higher capex for hydrotreating upgrades while maintaining throughput at aging facilities.
Growth Catalysts
- Marine bunkering expansion:The Luba Freeport is attracting larger vessels seeking compliant low-sulfur fuel oil. Port infrastructure investments enable deeper draft access for VLCCs.
- Aviation fuel demand:Malabo International Airport's passenger volume trajectory drives jet fuel offtake. The terminal's storage capacity expansion supports longer-haul routes.
- Regional product export protocols:Economic Community of Central African States harmonization is reducing cross-border friction. Nigerian and Cameroonian buyers increasingly source refined products from Bioko Island.
Market Restraints
- Crude feedstock concentration:Zafiro complex output dominates domestic supply. Pipeline disruptions to Punta Europa facilities create single-point vulnerability.
- Associated gas processing limits:Existing amine treatment capacity constrains NGL recovery rates. Stranded gas volumes require flaring or reinjection.
- Import dependency for specialty products:Lubricant base oils and bitumen arrive via maritime routes. Freight cost volatility compresses downstream margins.
Strategic Opportunities
- Bioko Island industrial corridor:LNG-to-power integration offers captive demand for fuel gas. Petrochemical feedstock linkages remain underdeveloped.
- Local content mandate expansion:Ministry procurement rules now favor domestic service providers. Maintenance and engineering contracts increasingly flow to Equatoguinean-registered entities.
- Small-scale LNG distribution:Cryogenic road tanker networks could reach interior population centers. Remote mining and forestry operations present anchor demand.
Industry Challenges
- Specialized welding and pressure vessel certification:ASME and API-qualified technicians remain scarce. Training programs at the National Polytechnic University require multiyear ramp periods.
- Legacy DCS migration complexity:Refinery control systems from the 1990s resist cybersecurity hardening. Phased replacement threatens operational continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Equatorial Guinea Oil and Gas Downstream Market |
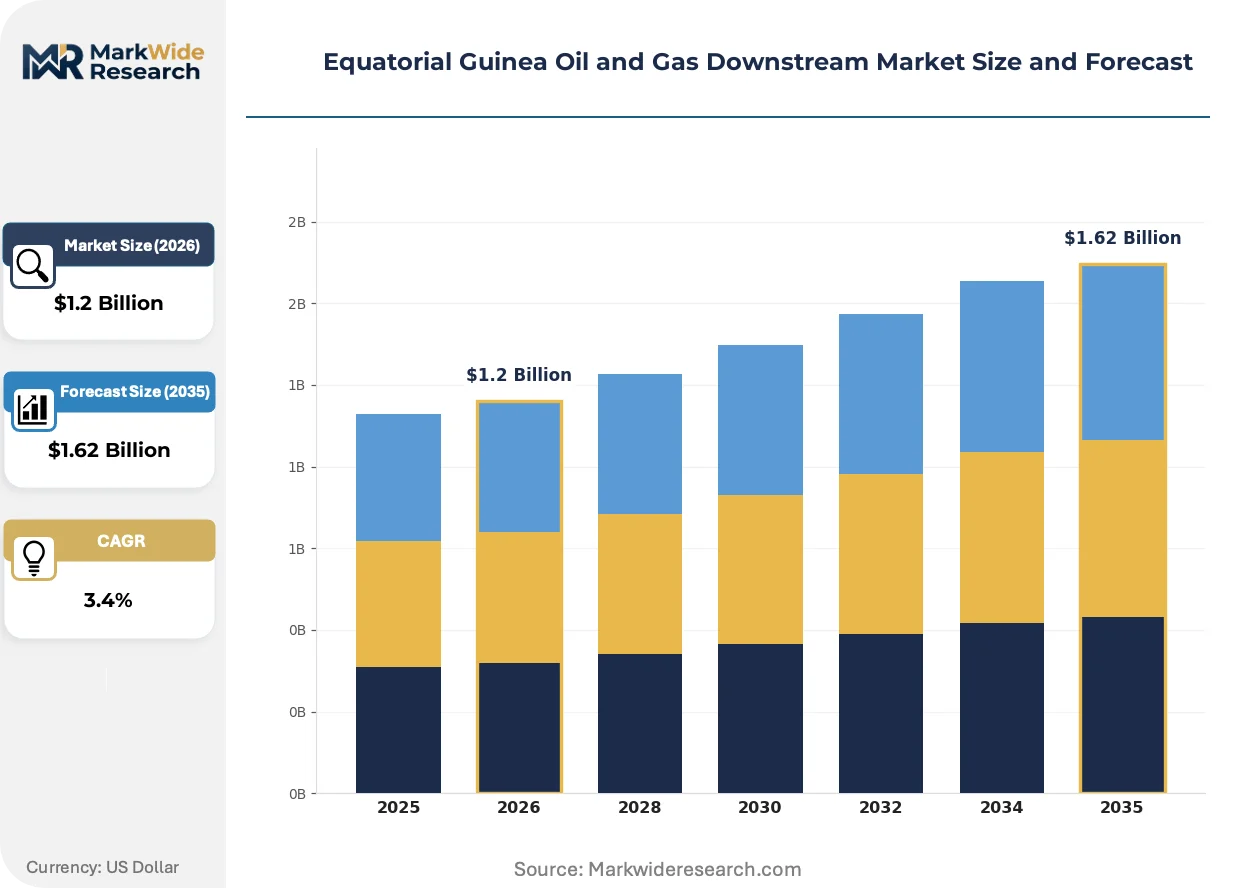
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $1.62 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Refining, Distribution, Transportation, Retailing Product Type: Gasoline, Diesel, Jet Fuel, Lubricants End User: Automotive, Aviation, Marine, Industrial Technology: Conventional, Advanced, Biofuel Processing, LNG Technology |
| Companies Covered | ExxonMobil, Petrobras, Sonagas, Eni, Repsol, TotalEnergies, Glencore, Oryx Energies, Chevron, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Equatorial Guinea Oil and Gas Downstream Market Shifts & Advancements
Digital instrumentation and predictive maintenance protocols are penetrating downstream assets. Operators now prioritize real-time corrosion monitoring over scheduled turnaround cycles.
Hydrotreating catalyst formulations with higher nickel-molybdenum loadings are absorbing sulfur from heavier crude slates. Punta Europa refiners are retrofitting fixed-bed reactors to handle Zafiro's rising acid gas content. This upgrade trajectory is compressing the viable lifespan of earlier-generation catalyst systems.
The Ministry of Mines and Hydrocarbons is implementing phased sulfur reduction mandates for gasoline and diesel. Refineries must achieve sub-50 ppm specifications by statutory deadlines. Coastal storage terminals are pre-positioning compliant product blends to avoid supply discontinuities during changeover periods.
After-sales service unbundling is separating equipment supply from long-term maintenance obligations. Compressor and pump OEMs now compete with independent reliability contractors. This pattern is most visible at the Zafiro onshore processing facility where Sonagas evaluates third-party service bids against captive technical teams.
Equatorial Guinea Oil and Gas Downstream Market Segmentation
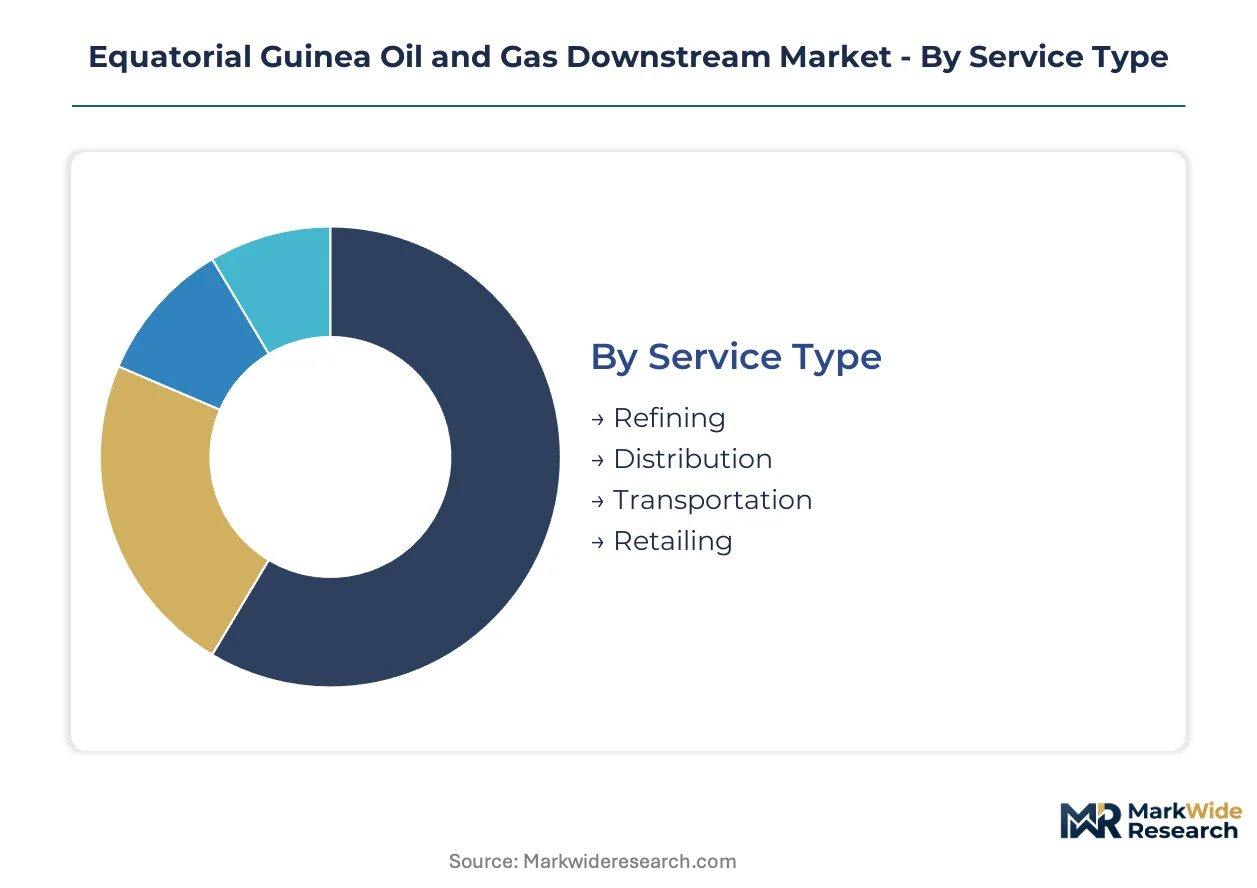
Downstream segmentation in Equatorial Guinea reflects the tension between aging Punta Europa infrastructure and emerging LNG-to-power integration. Each axis reveals distinct capital allocation priorities as Sonagas and international operators navigate sulfur specification mandates and local content requirements.
Service Type:
Refining technology and logistics capabilities determine competitive positioning across the service spectrum.
- Refining:Atmospheric distillation and hydrotreating units at Punta Europa process Zafiro crude into transport fuels. The Ministry of Mines and Hydrocarbons' sulfur reduction mandates are forcing reactor upgrades and catalyst replacement cycles.
- Distribution:Coastal storage terminals at Bioko Island and mainland coastal depots handle product blending and batch transfers. Cross-border protocols with Cameroon and Gabon are expanding addressable market radius.
- Transportation:Marine tankers and coastal barges move products between Bioko Island and mainland terminals. Road tanker fleets serve interior population centers with limited pipeline penetration.
- Retailing:Service station networks concentrate in Malabo and Bata urban corridors. Independent operators compete with Sonagas-affiliated retail sites on price and location access.
Mature deployment sits with Refining infrastructure anchored at Punta Europa. Newer deployment is concentrated in Retailing network expansion toward secondary cities.
Product Type:
Product margins track sulfur specification compliance costs and regional export arbitrage opportunities.
- Gasoline:Motor gasoline blending incorporates imported components to achieve octane ratings and sub-50 ppm sulfur targets. Domestic demand concentrates in private vehicle fleets and government motor pools.
- Diesel:Automotive and industrial diesel represents the highest volume product category. Marine bunkering at Luba Freeport and mining operations in Rio Muni drive offtake concentration.
- Jet Fuel:Aviation turbine kerosene serves Malabo International Airport and regional carriers. Storage capacity expansion enables longer-haul route refueling.
- Lubricants:Finished lubricants and base oil imports fill domestic demand as local blending capacity remains limited. Mining and power generation equipment maintenance drives premium product uptake.
Volume leadership sits with Diesel across automotive and marine applications. Steepest expansion trajectory is emerging in Jet Fuel as aviation connectivity deepens.
End User:
End-use concentration patterns reflect Bioko Island's commercial centrality versus mainland industrial development.
- Automotive:Private vehicle ownership in Malabo and Bata urban corridors drives gasoline and diesel consumption. Government fleet procurement follows local content mandates favoring domestic fuel suppliers.
- Aviation:International carriers and regional operators refuel at Malabo International Airport. Terminal infrastructure investments support code-share agreements with European and African hubs.
- Marine:Deep-draft vessels at Luba Freeport seek compliant low-sulfur fuel oil for IMO 2020 adherence. Bunkering volume climbs with port modernization and VLCC accessibility improvements.
- Industrial:Power generation, cement production, and mining operations consume diesel and fuel oil. Bioko Island's LNG-to-power projects are displacing liquid fuel demand in the electricity sector.
Established demand concentration sits with Automotive fueling networks. Emerging demand is concentrating in Marine bunkering as Luba Freeport captures transshipment flows.
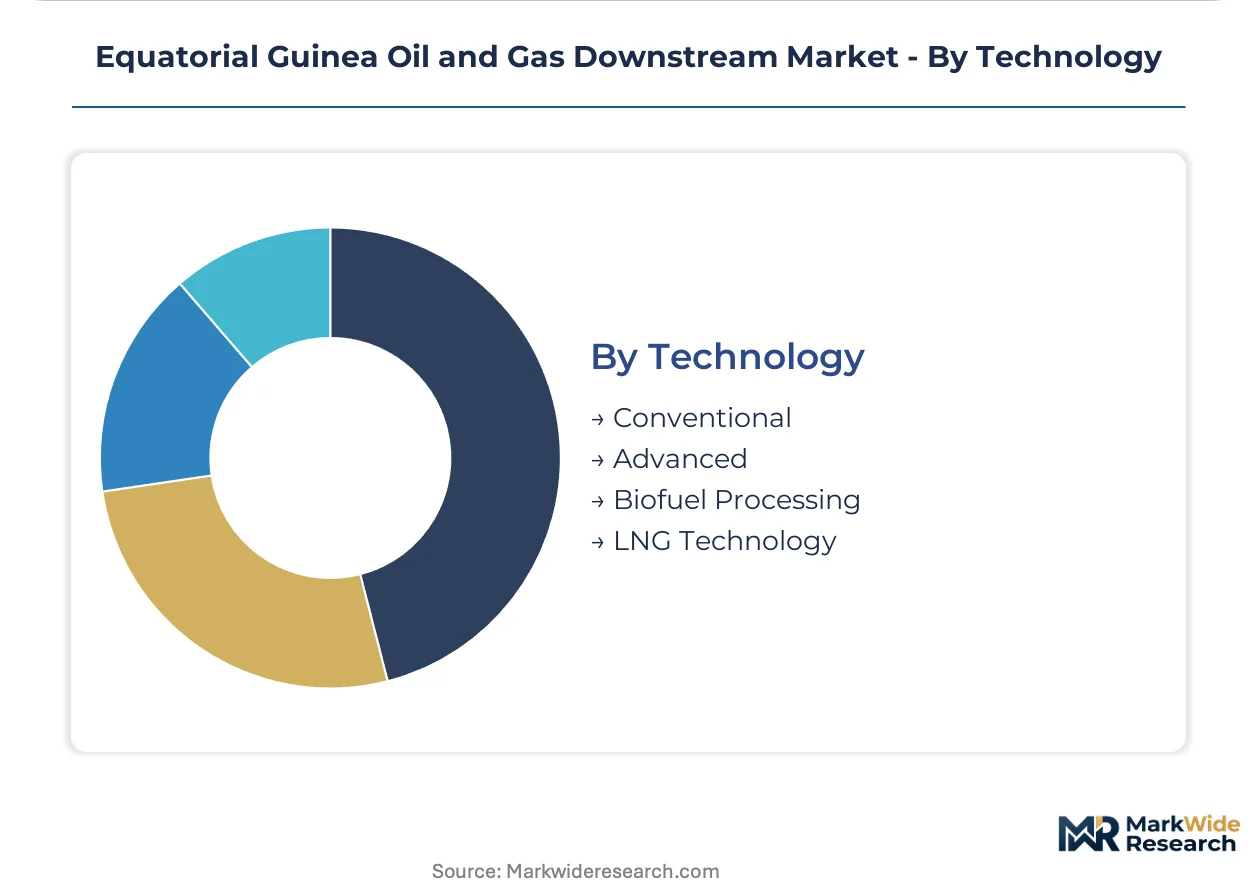
Technology:
Technology segmentation captures the transition from legacy refinery configurations toward gas monetization and cleaner fuel processing.
- Conventional:Fixed-bed hydrotreaters and atmospheric distillation units from the 1990s remain operational at Punta Europa. Catalyst degradation and corrosion monitoring absorb disproportionate maintenance resources.
- Advanced:High-pressure hydrotreating and residue upgrading technologies process heavier Zafiro crude slates. Capital intensity limits deployment to Sonagas-operated facilities with state-backed financing.
- Biofuel Processing:Limited blending infrastructure exists for ethanol or biodiesel incorporation. Ministry mandates remain under development without statutory enforcement timelines.
- LNG Technology:Liquefaction trains at Punta Europa and small-scale distribution systems serve power generation and industrial offtake. Cryogenic logistics networks could extend to remote mining camps.
Operational scale sits with Conventional processing infrastructure. Investment momentum is concentrating in LNG Technology as associated gas monetization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equatorial Guinea's downstream sector processes roughly 13,000 barrels per day at Punta Europa, yet domestic fuel consumption barely exceeds 5,000 barrels daily. This production surplus positions Bioko Island as a regional supply hub for West and Central African markets.
Cameroon
Cameroon's Sonara refinery in Limbe processes 42,000 barrels daily, serving as the primary alternative to Equatorial Guinean supply. The country's national hydrocarbons company, SNH, enforces local content requirements that favor regional product sourcing. Douala's industrial zone absorbs diesel volumes from cross-border maritime routes.
Gabon
Gabon's Sogara refinery in Port-Gentil produces 21,000 barrels daily, creating competitive pressure on Equatorial Guinean gasoline exports. The Ministry of Petroleum and Hydrocarbons maintains sulfur specifications aligned with ECCAS regional standards. Libreville's urban corridor depends on coastal barge deliveries from Bioko Island during maintenance turnarounds.
Nigeria
Nigeria's Dangote refinery at Lekki Free Zone now processes 650,000 barrels daily, reshaping West African product flows. The Nigerian Midstream and Downstream Petroleum Regulatory Authority enforces strict import licensing for refined products. Lagos-anchored trading houses increasingly arbitrage between Nigerian and Equatorial Guinean supply.
São Tomé and Príncipe
São Tomé and Príncipe lacks refining capacity entirely, importing all petroleum products via maritime routes. The national fuel pricing committee regulates retail margins through administered price mechanisms. The port of São Tomé receives regular coastal tanker shipments from Luba Freeport.
Equatorial Guinea Oil and Gas Downstream Market Competitive Landscape
Capital-heavy producers compete with asset-light trading houses across Equatorial Guinea's downstream value chain. State-backed Sonagas controls terminal infrastructure and regulatory access, while international majors leverage operational experience at legacy production complexes. Three archetypes dominate: integrated IOCs with full-chain presence, national oil companies with infrastructure control, and independent traders with flexible offtake arrangements. Competitive moves center on maintenance contract capture and LNG-to-power integration partnerships.
Within the integrated IOC tier, ExxonMobil, TotalEnergies, and Eni exemplify contrasting approaches to asset stewardship. ExxonMobil's position reflects decades of operational continuity at the Zafiro complex. TotalEnergies anchors its presence through coastal LNG infrastructure and power sector linkages. Eni occupies a specialized position focused on associated gas monetization and regional trading optimization.
| Leading Market Players |
|---|
| ExxonMobil |
| Petrobras |
| Sonagas |
| Eni |
| Repsol |
| TotalEnergies |
| Glencore |
| Oryx Energies |
| Chevron |
| Others |
Supply & Pricing Matrix
Sulfur specification mandates from the Ministry of Mines and Hydrocarbons are forcing refiners to absorb hydrotreating upgrade costs, compressing margins and pushing supply toward operators with state-backed financing capacity. This regulatory pressure reshapes competitive positioning around capital access rather than operational efficiency alone.
Pricing Analysis
Margin tightening in automotive diesel reflects hydrotreater catalyst replacement cycles and imported blending component costs. Contract-based long-term offtake dominates, with price differentiation tracking sulfur compliance grades and volume scale. Sonagas-affiliated terminals command premium positioning due to regulatory access, while independent retailers compete on location convenience. Marine bunkering buyers at Luba Freeport show lowest price sensitivity due to IMO 2020 compliance requirements.
Supply Chain Analysis
Regional distribution centers at Bioko Island anchor hub-and-spoke patterns reaching Cameroon, Gabon, and São Tomé and Príncipe. Feedstock draws from Zafiro complex output, with hydrotreating catalysts and specialty lubricant base oils sourced from European and Asian suppliers. Single-source vulnerability concentrates around Punta Europa pipeline infrastructure. Distribution runs through coastal marine tankers and limited road tanker penetration into Rio Muni interior.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equatorial Guinea's downstream sector is consolidating around state-backed operators as sulfur mandates and LNG-to-power integration squeeze capital-constrained independents. The Ministry of Mines and Hydrocarbons' procurement rules accelerate this concentration.
For Market Incumbents: Cement control over maintenance and reliability service contracts through National Polytechnic University training partnerships. Lock in LNG-to-power integration partnerships before Bioko Island industrial corridor saturation. Hydrotreater catalyst supply agreements represent a critical defensive lever against emerging trading house competition. For New Entrants and Emerging Players: The gap between premium Sonagas-affiliated retail sites and economy-tier independent stations offers white-space entry. Small-scale LNG distribution to remote mining camps in Rio Muni presents the most penetrable segment. Partner with cryogenic logistics specialists to bypass coastal terminal infrastructure barriers. For Investors and Strategic Acquirers: The window for entry favors asset-light trading houses with flexible offtake arrangements and regional West African networks. Long-term viability hinges on LNG-to-power project execution capability rather than refining asset ownership. Watch for Ministry local content mandate enforcement intensity as the inflection signal for service provider acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrotreater Capacity Upgrade | Punta Europa refiners meet Ministry sulfur mandates while processing heavier Zafiro crude slates. |
| LNG-to-Power Integration | Bioko Island industrial corridor captures captive fuel gas demand from electricity sector displacement. |
| Small-Scale LNG Distribution | Cryogenic road tanker networks reach Rio Muni mining camps beyond pipeline infrastructure. |
| Local Content Partnership | Equatoguinean-registered service providers capture maintenance contracts under Ministry procurement rules. |
| Regional Export Protocol Expansion | ECCAS harmonization enables cross-border product flows to Cameroon and Gabon terminals. |
Research Methodology
Multi-period observation of refinery utilization rates, sulfur specification compliance timelines, and LNG-to-power project milestones anchored the trend analysis, supplemented by interviews with downstream operations directors, Ministry regulatory affairs officers, EPC contractors, and coastal terminal logistics managers. Secondary validation drew from customs trade records, national hydrocarbons company disclosures, ECCAS regulatory directives, and project finance databases. Bottom-up capacity modeling and top-down demand estimation were triangulated against Ministry consumption surveys.
The input-output matrix framed projections across service type, product grade, end-use sector, and technology deployment segments throughout the forecast period. CAGRs were derived from segment-level capacity expansion schedules and demand elasticity assumptions. Hydrotreater upgrade capex cycles and LNG liquefaction train utilization rates served as primary forecast inputs.
Inputs from Ministry of Mines and Hydrocarbons publications and national standards body filings were available through the study window; gaps in real-time refinery maintenance turnaround schedules introduce uncertainty bands around throughput assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Southeast Asia Offshore Seismic Survey Market
Offshore Oil and Gas
Central Asia Oil and Gas Upstream Market
Offshore Oil and Gas
India Oil and Gas Upstream Market
Offshore Oil and Gas
South America Oil and Gas Downstream Market
Offshore Oil and Gas
East Africa Oil and Gas Downstream Market
Offshore Oil and Gas
Oman Oil and Gas Market
Offshore Oil and Gas
Global Mobile Offshore Drilling Units Market
Offshore Oil and Gas
FPSO Market
Offshore Oil and Gas
North America Floating Offshore Wind Power Market
Offshore Oil and Gas
Kuwait Oil and Gas Downstream Market
Offshore Oil and Gas
Global Offshore Oil and Gas Seismic Equipment and Acquisitions Market
Offshore Oil and Gas
Argentina Oil and Gas Downstream Market
Offshore Oil and Gas
Europe Jackup Rig Market
Offshore Oil and Gas
Turkmenistan Oil and Gas Upstream Market
Offshore Oil and Gas
Middle East Offshore MRO Market
Offshore Oil and Gas
Abyssinian Oil Market