
 Whipstocks Market | 2026-2036
Whipstocks Market Size, Share, and Industry Trends Forecast 2026-2036
Whipstocks Market Analytics
Oilfield equipment distribution through integrated service companies is fragmenting as independent drilling contractors seek direct procurement channels. Weatherford International leverages its global rental fleet to sustain whipstock availability across North American shale plays. Schlumberger anchors premium directional drilling packages with proprietary whipstock integration. Baker Hughes competes through advanced metallurgy for high-pressure, high-temperature applications.
A whipstock is a tapered steel or composite wedge inserted into a wellbore to deflect the drill bit and initiate a sidetrack or lateral section, typically manufactured from alloy steel grades meeting API 5CT specifications with hardened cutting faces or milled windows to ensure controlled directional deviation. Steel whipstocks dominate capital budgets for deepwater applications where load-bearing capacity is non-negotiable, while composite whipstocks capture fastest-growing demand in onshore coalbed methane and shallow horizontal wells where weight reduction accelerates rig-time savings. Directional drilling applications command the largest share of whipstock consumption as operators extend laterals beyond fifteen thousand feet in unconventional reservoirs.
API standards, ISO 15156 sour service requirements, and BSEE well control regulations govern whipstock design, material certification, and operational deployment in US federal waters. The EPA's methane emissions rules and state-level casing integrity programs in Texas and North Dakota further constrain product qualification timelines. Stakeholders must monitor evolving regulatory thresholds for cement bond verification and whipstock anchor reliability as abandonment obligations expand across mature basins.
Market Dynamics
Directional drilling contractors in the Permian Basin are extending lateral lengths beyond fifteen thousand feet, forcing whipstock manufacturers to redesign anchor systems for higher torsional loads and multi-stage sidetrack reliability.
Growth Catalysts
- API 5CT specification tightening:Sour service requirements under ISO 15156 are mandating upgraded alloy grades for hydrogen sulfide resistance, expanding replacement cycles for legacy inventory in Texas shale plays.
- Multi-well pad development:Operators in North Dakota's Bakken formation are drilling eight to twelve wells per pad, multiplying whipstock consumption per surface location.
- Composite material advances:Weight-reduced whipstocks are cutting rig-time by thirty minutes per run in coalbed methane operations across Wyoming's Powder River Basin.
Market Restraints
- Alloy steel price volatility:Chromium and molybdenum input costs swing with stainless steel futures, compressing fabrication margins for API-certified grades.
- Deepwater supply concentration:Steel whipstock production for subsea applications clusters around Gulf Coast fabrication yards, creating hurricane exposure and single-source risk.
- Regulatory friction from BSEE:Well control verification rules for federal waters are lengthening qualification timelines for new anchor designs by four to six months.
Strategic Opportunities
- Abandonment obligation expansion:Texas Railroad Commission casing integrity programs are creating whipstock demand for plugged-well sidetrack remediation in mature Permian fields.
- Direct procurement channels:Independent drilling contractors in Oklahoma's SCOOP-STACK are bypassing integrated service companies, opening vendor relationships with specialized manufacturers.
- EPA methane rules:Emissions monitoring requirements are accelerating replacement of whipstock windows with sealed composite designs that reduce gas venting during installation.
Industry Challenges
- Directional drilling specialist shortage:Toolhand expertise for whipstock orientation and anchor setting is thinning as experienced crews retire from Permian and Bakken operations.
- Cement bond verification complexity:Whipstock anchor reliability now requires ultrasonic logging confirmation, adding procedural steps and rig-time before sidetrack initiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Whipstocks Market |
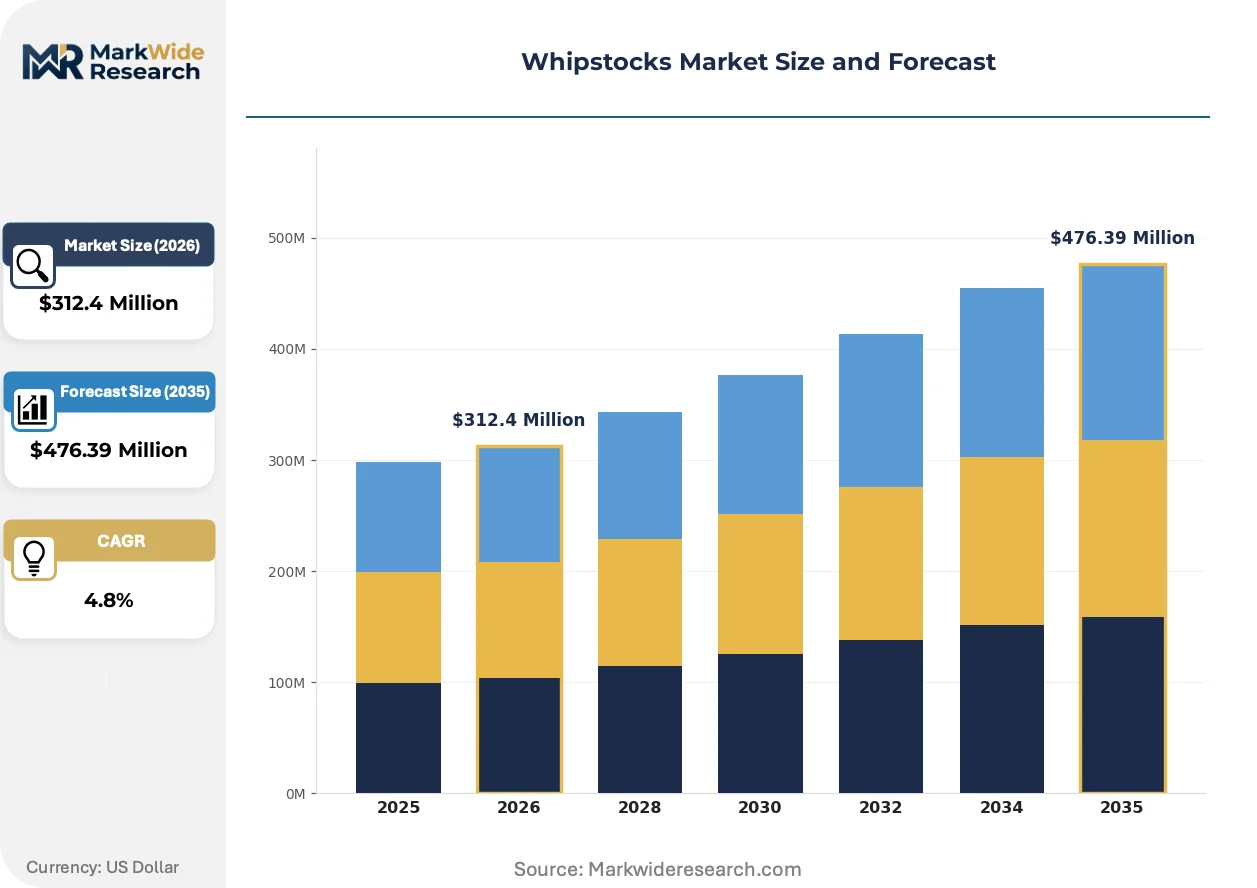
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Whipstocks, Composite Whipstocks, Hybrid Whipstocks, Casing Whipstocks Application: Wellbore Construction, Directional Drilling, Sidetracking, Plugging & Abandonment End User: Oil & Gas Companies, Drilling Contractors, Service Providers, Exploration Firms Installation Type: Onshore, Offshore, Coastal, Deepwater |
| Companies Covered | Weatherford International, Rubicon Oilfield International, Schlumberger, Cougar Drilling Solutions, D-Tech Rotary Steerable, Halliburton, National Oilwell Varco, Gyrodata, Baker Hughes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Whipstocks Market Evolving Landscape
Material science advances and regulatory pressure on well integrity are compressing traditional product lifecycles, while procurement fragmentation opens channel space for specialized manufacturers.
Composite whipstocks reinforced with high-strength glass fiber are collapsing the weight differential that previously favored steel in shallow horizontal applications. Coalbed methane operators in Wyoming and Colorado are adopting these designs for faster trip times. The technology is collapsing rig-day costs in wells under eight thousand feet measured depth.
ISO 15156-3 sour service testing protocols are tightening material certification requirements for hydrogen sulfide exposure above 0.05 psi partial pressure. Fabricators must now submit full mechanical property traceability for each heat lot. Offshore Gulf of Mexico operators are responding by consolidating supplier lists to vendors with in-house metallurgy laboratories.
Drilling contractors are unbundling whipstock procurement from bundled directional drilling packages. Independent operators in the Permian's Delaware sub-basin are negotiating direct volume agreements with manufacturers. This channel shift is most visible among private equity-backed producers seeking to reduce day-rate markups on consumable downhole equipment.
Whipstocks Market Segmentation
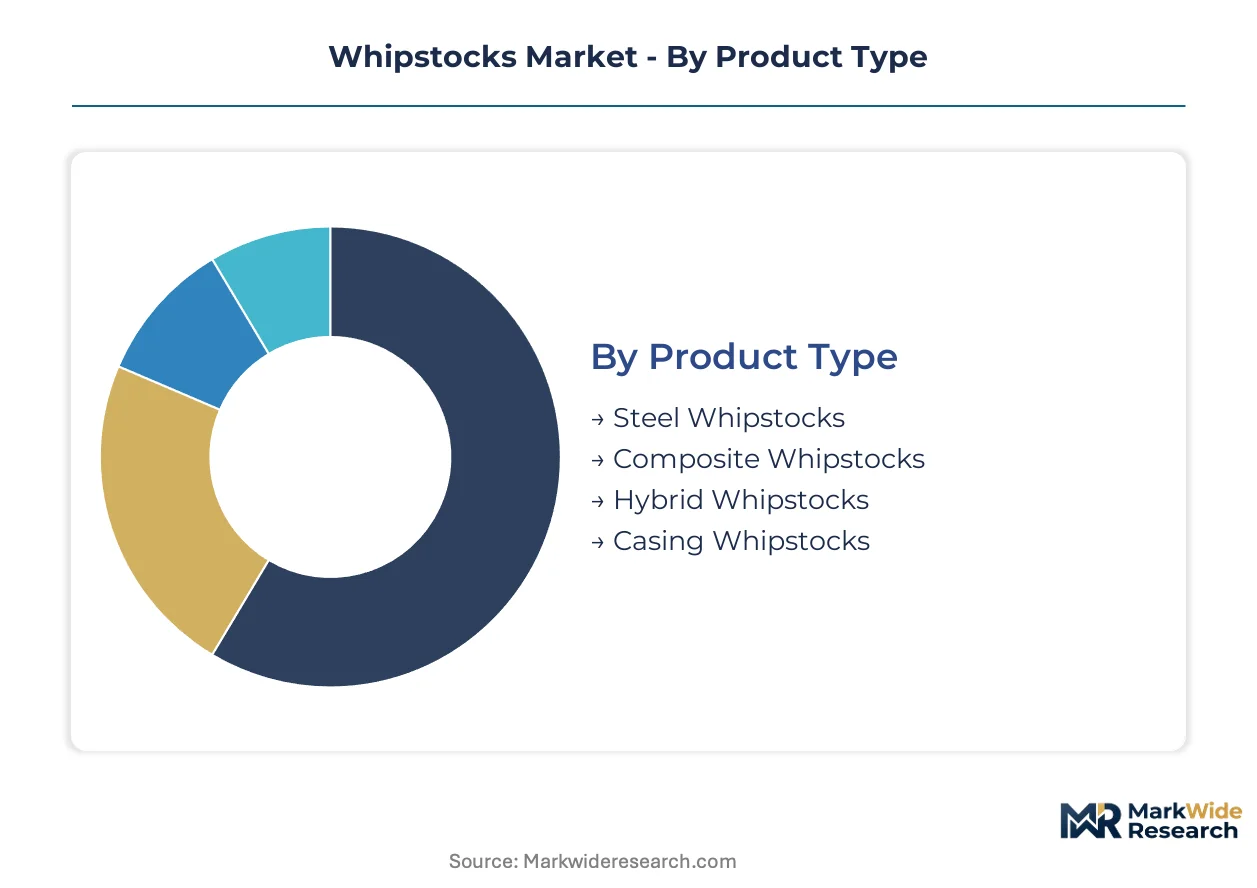
Whipstock segmentation reveals divergent service intensity across product categories. Steel whipstocks demand intensive metallurgical certification support, while composite designs shift value toward rapid-deployment training and field engineering.
Product Type:
After-sales-service intensity varies sharply by material composition, with alloy-grade products requiring ongoing hydrogen sulfide monitoring and composite systems needing specialized handling protocols.
- Steel Whipstocks:Manufactured from API 5CT-certified alloy grades with chromium-molybdenum hardening for sour service resistance. Demand concentrates in Texas deepwater projects where BSEE well control regulations mandate full traceability documentation and anchor system recertification every deployment cycle.
- Composite Whipstocks:Reinforced with high-strength glass fiber matrices delivering sixty-percent weight reduction versus steel equivalents. Operators in Wyoming's Powder River Basin coalbed methane fields prioritize these for thirty-minute rig-time savings per trip, though specialized toolhand training requirements elevate service costs.
- Hybrid Whipstocks:Combine steel load-bearing cores with composite outer layers for intermediate applications.
- Casing Whipstocks:Integrate directly with casing strings for permanent sidetrack installations.
By volume, Steel Whipstocks leads. By growth pace, Composite Whipstocks is ahead.
Application:
Cost tier stratification separates capital-intensive wellbore construction from recurring sidetracking operations, with directional drilling commanding premium pricing through bundled service packages.
- Directional Drilling:Deflects drill bits to initiate lateral sections beyond fifteen thousand feet in unconventional reservoirs. Permian Basin contractors in Texas consume the majority of whipstock deployments as multi-well pad complexity escalates.
- Wellbore Construction:Establishes primary well architecture with whipstock-assisted window milling for branch connections. North Dakota Bakken operators deploy these during initial spudding, though extended-reach designs are compressing standalone demand.
- Sidetracking:Re-routes existing wellbores around obstructions or depleted zones.
- Plugging & Abandonment:Creates access for remedial cementing in Texas Railroad Commission-mandated casing integrity programs.
Directional Drilling generates the highest revenue per unit. Plugging & Abandonment is expanding most quickly.
End User:
Customer type determines procurement channel structure, with integrated oil companies favoring long-term rental agreements and independent contractors pursuing direct manufacturer relationships.
- Drilling Contractors:Execute directional programs under day-rate contracts with bundled equipment provisions. Oklahoma SCOOP-STACK independents are unbundling whipstock procurement to reduce service company markups.
- Oil & Gas Companies:Operate as asset owners specifying whipstock standards for contractor deployment. Private equity-backed Permian producers negotiate volume-direct agreements to control consumable costs.
- Service Providers:Rent whipstocks as part of integrated directional drilling packages.
- Exploration Firms:Purchase for wildcat drilling with high sidetrack probability.
Drilling Contractors move the highest unit volumes. Oil & Gas Companies are gaining procurement control fastest.
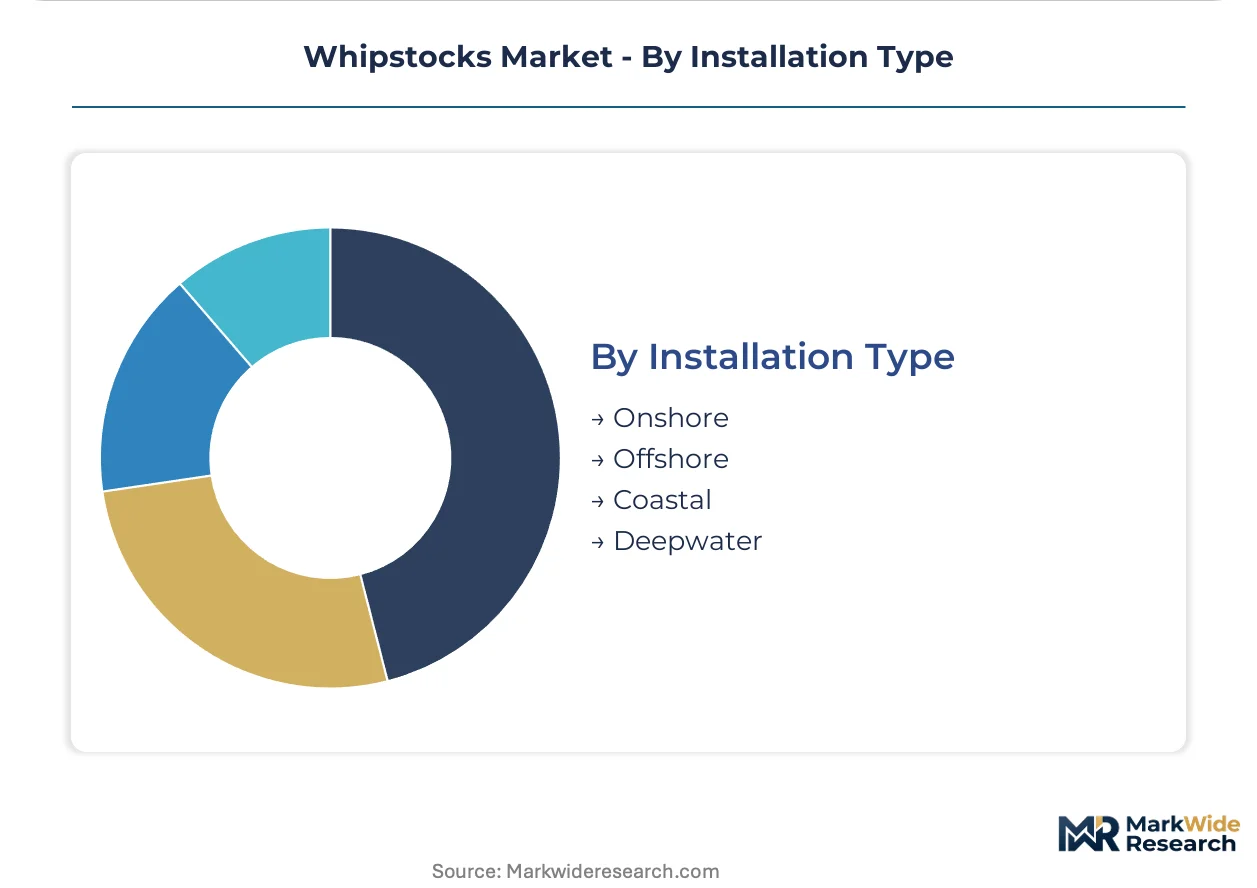
Installation Type:
Supply concentration clusters fabrication capacity around hurricane-exposed Gulf Coast yards, creating geographic risk concentration for deepwater steel whipstock availability.
- Onshore:Encompasses Texas shale plays, North Dakota Bakken, and Wyoming coalbed methane fields where composite whipstocks dominate shallow horizontal applications. EPA methane rules are accelerating sealed-window composite adoption across these basins.
- Deepwater:Requires steel whipstocks with subsea anchor systems rated for high-pressure, high-temperature conditions. Gulf of Mexico fabrication yards in Louisiana and Texas produce the majority of units, with ISO 15156-3 certification timelines extending four to six months.
- Offshore:Covers platform-based installations in federal waters.
- Coastal:Addresses marsh and bay environments with mixed steel-composite deployment.
Onshore dominates absolute deployment count. Deepwater commands the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deepwater steel whipstock fabrication in the United States commands premium pricing power against onshore composite alternatives in Australia, where Powder River Basin-style coalbed methane economics favor weight-reduced designs. This pricing asymmetry reflects divergent regulatory burdens and anchor system complexity rather than raw material costs alone. Regional procurement patterns track closely to basin maturity and abandonment obligation timelines.
United States
Permian Basin directional drilling contractors consume the majority of whipstock deployments as lateral lengths exceed fifteen thousand feet. EPA methane emissions rules and Texas Railroad Commission casing integrity programs tighten material certification requirements for sealed-window designs. Gulf Coast fabrication yards in Louisiana and Texas concentrate deepwater steel production, with BSEE well control regulations extending qualification timelines four to six months.
Canada
Alberta's oil sands and Saskatchewan's Bakken-equivalent formations drive whipstock demand for extended-reach horizontal drilling. Provincial regulators enforce API 5CT and ISO 15156 compliance for sour service environments in the Western Canadian Sedimentary Basin. Calgary-based drilling contractors increasingly unbundle procurement from integrated service packages, negotiating direct manufacturer agreements.
Australia
Queensland's Surat and Bowen basin coalbed methane operators prioritize composite whipstocks for thirty-minute rig-time savings in shallow horizontal wells. The country's national petroleum regulator mandates well integrity verification for plugged-well sidetrack remediation programs. Perth and Brisbane service hubs distribute weight-reduced designs to onshore fields under eight thousand feet measured depth.
Norway
North Sea subsea developments require steel whipstocks with subsea anchor systems rated for high-pressure, high-temperature conditions. The Norwegian Petroleum Directorate enforces stringent well control documentation for HPHT applications. Stavanger and Bergen fabrication clusters specialize in alloy-grade production with full mechanical property traceability for each heat lot.
Brazil
Pre-salt carbonate reservoirs in the Santos Basin drive demand for sour service-resistant whipstock designs. The national petroleum regulator ANP mandates ISO 15156-3 certification for hydrogen sulfide exposure above threshold partial pressures. Rio de Janeiro and Macaé service corridors anchor deepwater supply chains, though fabrication capacity remains concentrated around hurricane-exposed Gulf of Mexico yards.
Whipstocks Market Competitive Landscape
Integrated service conglomerates and specialized directional drilling boutiques split the market through divergent channel strategies. Rental fleet operators sustain availability across North American shale plays through asset-heavy balance sheets. Fabricators with in-house metallurgy laboratories capture offshore consolidation as ISO 15156-3 testing requirements intensify. Dominant competitive moves include procurement unbundling by independent contractors and supplier list consolidation by Gulf of Mexico operators.
Among Houston-based oilfield service giants, Weatherford International, Schlumberger, and Baker Hughes occupy positions representing the integrated service archetype. These entities anchor premium directional drilling packages through proprietary whipstock integration and advanced metallurgy capabilities. Halliburton exemplifies the diversified energy services model with broad downhole equipment portfolios. Independent specialists including Rubicon Oilfield International and Cougar Drilling Solutions sit within the focused manufacturing tier, serving unbundled procurement channels in Oklahoma's SCOOP-STACK and the Permian's Delaware sub-basin.
| Leading Market Players |
|---|
| Weatherford International |
| Rubicon Oilfield International |
| Schlumberger |
| Cougar Drilling Solutions |
| D-Tech Rotary Steerable |
| Halliburton |
| National Oilwell Varco |
| Gyrodata |
| Baker Hughes |
| Others |
Value Network & Pricing Analysis
Hurricane exposure across Gulf Coast fabrication yards compresses pricing power for deepwater steel whipstocks while expanding the premium commanded by onshore composite alternatives. This geographic risk concentration forces buyers into longer-term contracting structures that embed inventory carrying costs and qualification timeline premiums.
Pricing Analysis
Configured-to-order pricing for API 5CT-certified alloy grades with full sour service traceability commands substantial premiums over standard catalog whipstocks. Price differentiation hinges on ISO 15156-3 certification tier and volume scale, with integrated service companies extracting markups through bundled directional drilling packages. Cost compression in standard steel grades is intensifying as chromium-molybdenum input volatility squeezes fabrication margins. Independent drilling contractors in Oklahoma and Texas exhibit the highest price sensitivity, while Gulf of Mexico operators prioritizing BSEE compliance demonstrate the least.
Supply Chain Analysis
Extended payment terms from integrated service companies to Gulf Coast fabricators are reshaping working capital structures across the supplier base. Supply concentrates in the United States, with secondary fabrication capacity in Norway and Brazil serving regional offshore markets. Raw material procurement draws from chromium and molybdenum suppliers tied to stainless steel futures, with high-strength glass fiber sourcing for composite variants. Single-source vulnerability clusters around Louisiana and Texas fabrication yards exposed to Atlantic hurricane patterns. Distribution runs through integrated service company rental fleets and direct procurement channels serving independent contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Whipstock procurement unbundling represents a platform-economics inflection as interoperability between manufacturer-native designs and third-party directional drilling systems improves. This ecosystem shift enables independent contractors to mix equipment suppliers without package-lock penalties.
For Market Incumbents: Pre-empt procurement fragmentation by anchoring proprietary whipstock designs within integrated directional drilling platforms. Invest in in-house metallurgy laboratories to capture ISO 15156-3 certification consolidation among Gulf of Mexico operators. Deepen backward integration into alloy steel supply to defend margin position against commodity volatility.
For New Entrants and Emerging Players: Pursue direct procurement relationships with private equity-backed Permian producers seeking to reduce day-rate markups on consumable downhole equipment. Target coalbed methane applications in Wyoming and Queensland where composite whipstock adoption outpaces incumbent service bundling. Lead with thirty-minute rig-time savings demonstrations to bypass established rental fleet relationships.
For Investors and Strategic Acquirers: EPA methane rules reshaping sealed-window composite demand reshape the acquisition landscape toward manufacturers with EPA-compliant design portfolios. Five-to-ten year viability favors specialized fabricators with captive metallurgy capabilities over asset-heavy rental fleet operators. Monitor Texas Railroad Commission casing integrity program expansion as the signal for plugged-well sidetrack remediation demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Metallurgy Laboratory Certification | ISO 15156-3 compliance capability captures offshore supplier consolidation as traceability requirements intensify. |
| Composite Material Scale-Up | High-strength glass fiber manufacturing expansion addresses coalbed methane operator demand for weight-reduced designs. |
| Direct Procurement Channel Development | Independent contractor relationships in Oklahoma SCOOP-STACK bypass integrated service company markups. |
| Sealed-Window Design Portfolio | EPA methane rule compliance positions manufacturers for accelerated replacement of vented legacy whipstocks. |
| Anchor System Recertification Service | BSEE well control documentation requirements create recurring revenue from deepwater deployment cycles. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with directional drilling contractors, whipstock manufacturing engineers, procurement leads at independent oil and gas companies, and regulatory compliance officers at BSEE and state-level agencies. Secondary validation drew from API specification documentation, EPA methane emissions rulemaking records, Texas Railroad Commission casing integrity program filings, and SEC disclosures from integrated oilfield service companies. Bottom-up deployment estimates triangulated against top-down capital expenditure patterns across North American shale plays.
Calibration against historical deployment cycles and alloy steel price volatility informed the analytical framework across the projection horizon. Segmentation dimensions modeled include material composition, application type, end-user procurement structure, and installation environment. CAGRs derived from regression analysis of lateral length extension trends and multi-well pad development intensity. Forecast inputs incorporated whipstock consumption per wellbore, replacement cycle acceleration from sour service requirements, and channel shift velocity toward direct procurement.
Macroeconomic conditions sit as an overlay; deviation in crude oil price trajectories, interest rate environments affecting private equity-backed producer drilling programs, or alloy steel futures volatility would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Canada LNG Market
Oil & Gas
FTIR Oil Condition Monitoring Market
Oil & Gas
Asia Pacific Upstream Oil and Gas Services Market
Oil & Gas
Gold Mining Market
Oil & Gas
Electric Fracking Market
Oil & Gas
Casing and Cementation Hardware Market
Oil & Gas
Qatar Oilfield Service Market
Oil & Gas
Latin America Drilling Fluids Market
Oil & Gas
Oil Breather Tank Market
Oil & Gas
Romania Oil and Gas Upstream Market
Oil & Gas
Rig and Oilfield Mats Market
Oil & Gas
India Oil and Gas Market
Oil & Gas
Europe Hydraulic Fracturing Fluids Market
Oil & Gas
Oil, Gas and Chemicals Software Market
Oil & Gas
Subsea Boosting Systems Market
Oil & Gas
Oilfield Market