
 Turkmenistan Oil and Gas Market | 2026-2036
Turkmenistan Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Turkmenistan Oil and Gas Market Analytics
Digital reservoir management is fragmenting traditional upstream workflows across Turkmenistan's supergiant gas fields. CNPC (Turkmenistan) leverages seismic imaging partnerships to anchor its position in the Bagtyyarlyk contract area. Dragon Oil PLC sustains heavy oil output from the Cheleken Peninsula through extended-reach drilling programs. Türkmengaz dominates the onshore Galkynysh field development, controlling the largest single gas reserve base in Central Asia.
Turkmenistan oil and gas encompasses hydrocarbon exploration, production, processing, and transport operations centered on supergiant carbonate reservoirs with depths exceeding 4,500 meters and sulfur content reaching 6% in some Galkynysh formations, primarily serving power generation and export markets via pipeline and planned liquefaction routes. Crude oil extraction competes with mature field decline as operators deploy enhanced recovery methods to sustain plateau rates from legacy Turkmennebit assets. Natural gas transportation systems represent the fastest-growing infrastructure category as TAPI and Turkmenistan-Afghanistan-Pakistan pipeline negotiations advance alongside domestic processing expansion.
The country's national energy regulator mandates local content thresholds for all production-sharing contracts, while the State Standards Committee enforces GB-aligned technical specifications for imported drilling equipment and pipeline steel. These frameworks force international contractors to establish joint ventures with Turkmen entities or forfeit access to the Galkynysh and Dauletabad development tenders. Stakeholders must weigh the trade-off between reserve scale and capital repatriation constraints before committing to greenfield upstream commitments.
Market Dynamics
Digital reservoir management is fragmenting traditional upstream workflows across Turkmenistan's supergiant gas fields, forcing contractors to restructure field development sequences around real-time data analytics rather than static geological models.
Growth Catalysts
- Power generation expansion:Gas-fired capacity additions in the western Balkan province drive upstream drilling commitments to feed new turbine installations.
- Local content mandates:The national energy regulator's production-sharing contract thresholds compel international operators to transfer drilling technology through Turkmen joint ventures.
- Carbonate reservoir characterization:Seismic imaging partnerships at depths exceeding 4,500 meters unlock development of high-sulfur formations previously classified as non-commercial.
Market Restraints
- Capital repatriation constraints:Currency controls limit dividend flows from Galkynysh and Dauletabad production, extending project payback periods for foreign investors.
- Sulfur handling costs:Processing infrastructure for 6% sulfur content gas requires specialized amine units not manufactured within Turkmenistan, creating import dependency.
- Pipeline route uncertainty:TAPI negotiations with Afghanistan and Pakistan remain unresolved, blocking firm offtake agreements for new field developments.
Strategic Opportunities
- Caspian LNG export pivot:Planned liquefaction routes offer price arbitrage against pipeline-dependent European and Asian contracts.
- Enhanced recovery deployment:Mature Turkmennebit assets present brownfield redevelopment potential using polymer flooding and gas injection methods.
- GB-aligned equipment localization:The State Standards Committee's technical specifications create incentive for Chinese and Russian manufacturers to establish domestic assembly partnerships.
Industry Challenges
- Deep drilling competency gaps:Extended-reach programs at Cheleken Peninsula require directional drilling specialists scarce in Central Asian labor markets.
- Legacy system integration:Supervisory control and data acquisition upgrades at Soviet-era processing plants conflict with proprietary digital twin architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turkmenistan Oil and Gas Market |
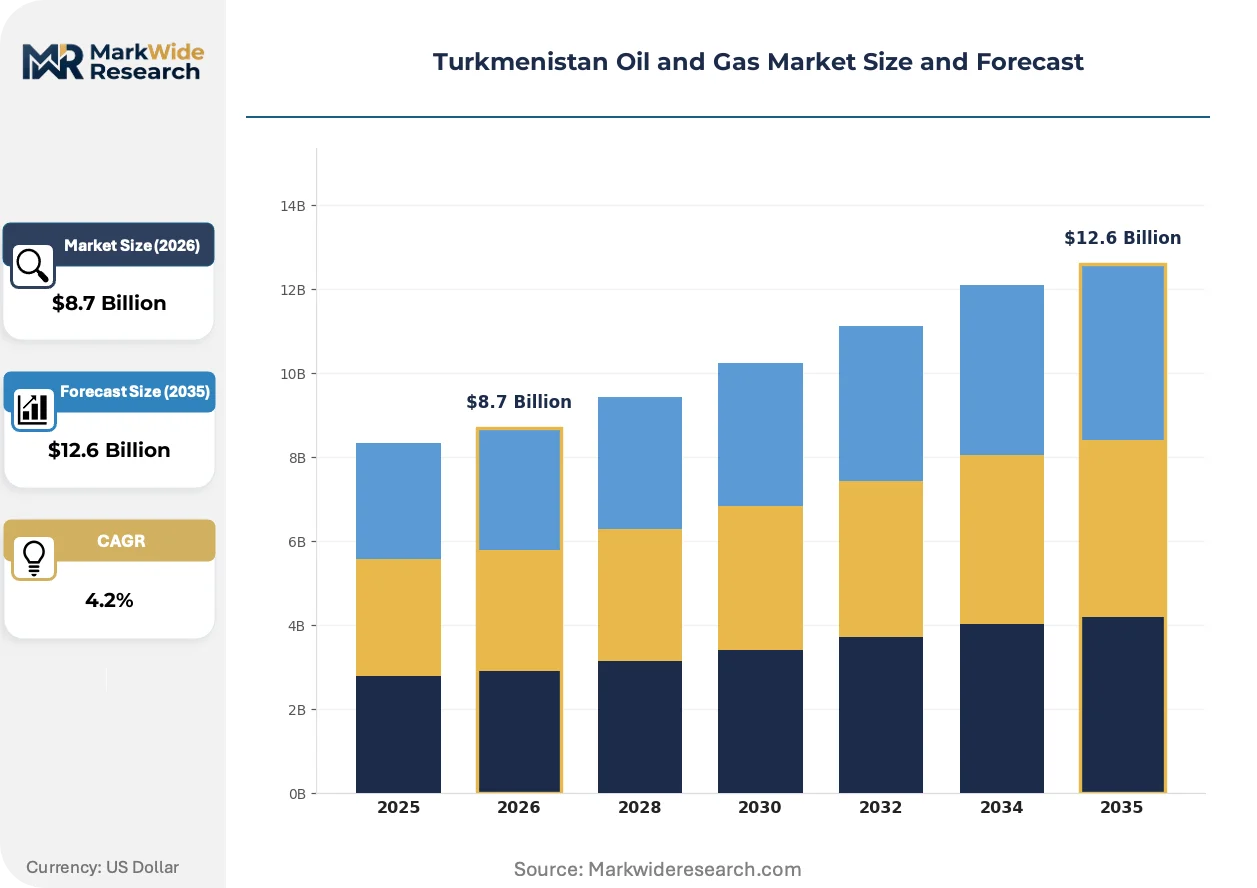
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.6 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crude Oil, Natural Gas, Refined Products, LNG End User: Industrial Sector, Power Generation, Residential, Commercial Technology: Extraction Methods, Transportation Systems, Refining Processes, Storage Solutions Service Type: Exploration Services, Drilling Services, Maintenance, Consulting |
| Companies Covered | Dragon Oil PLC, Eni Turkmenistan, JSC Türkmengaz, ADNOC XRG, Hyundai Engineering Co., JSC Türkmennebit, Petronas Carigali, Çalik Enerji, CNPC (Turkmenistan), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turkmenistan Oil and Gas Market Evolving Landscape
Upstream operators are compressing decision cycles through real-time subsurface monitoring, while regulatory pressure on sulfur emissions reshapes processing investments and export contract terms.
Seismic imaging is virtualizing traditional well logging workflows across the Bagtyyarlyk contract area. CNPC deploys distributed acoustic sensing to reduce physical well interventions by half. This virtualization collapses the time between exploration and development planning from months to weeks.
The State Standards Committee enforces GB-aligned technical specifications for imported drilling equipment and pipeline steel. Foreign contractors must recertify entire toolstrings to access Galkynysh tenders. Chinese manufacturers have responded fastest, redesigning blowout preventers to meet Turkmen pressure ratings.
Power utilities now contract gas supply on interruptible terms rather than baseload commitments. This procurement rotation forces upstream operators to build storage buffer capacity at processing facilities. The western Balkan province sees the most volatile nomination patterns due to its concentration of new combined-cycle plants.
Turkmenistan Oil and Gas Market Segmentation
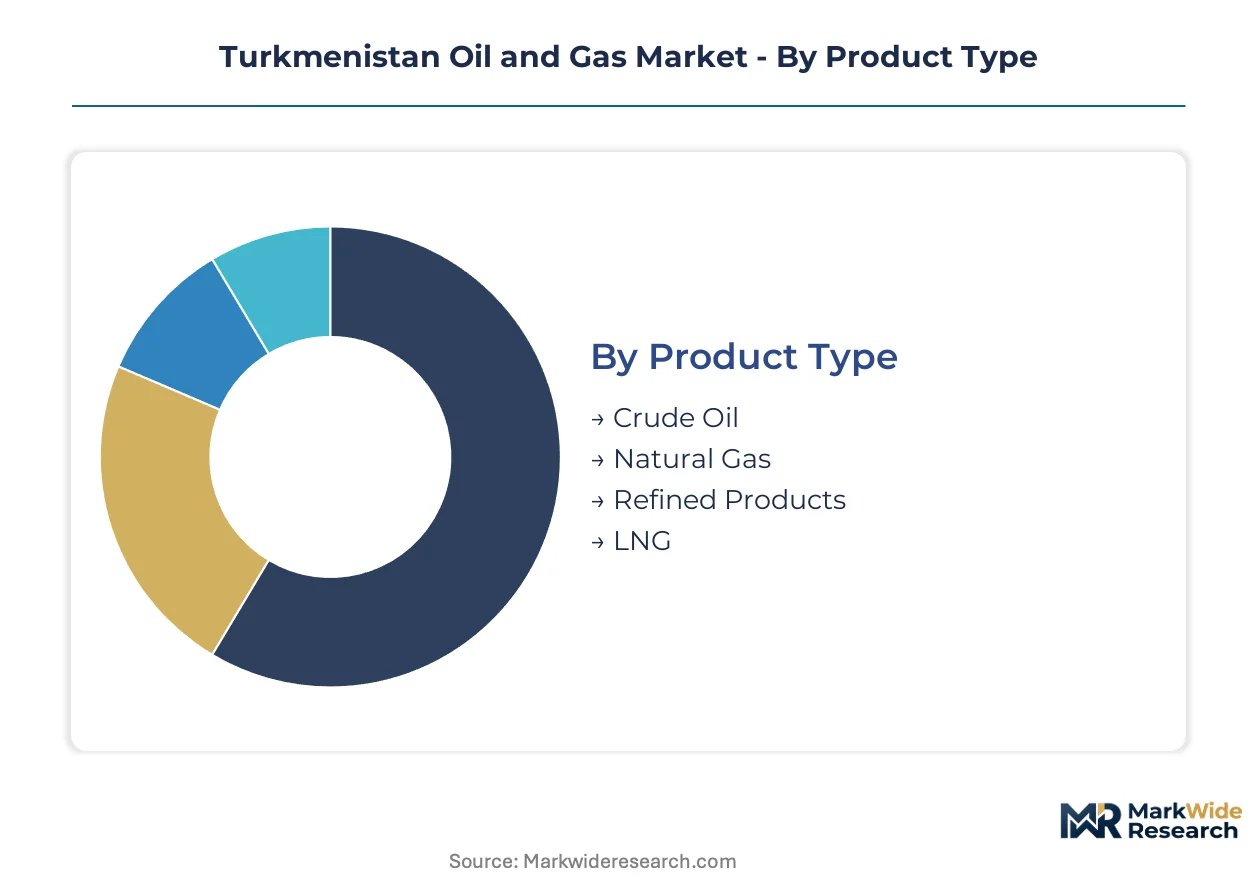
Turkmenistan's oil and gas market segments along four functional dimensions that shape capital allocation and contractor selection. Product type determines infrastructure requirements across supergiant carbonate reservoirs. End user concentration in the western Balkan province drives field development sequencing. Technology and service categories reflect the tension between Soviet-era legacy assets and digital reservoir management adoption.
Product Type:
Volume concentration across product categories tracks reserve geology and export route viability.
- Natural Gas:Sourced from Galkynysh and Dauletabad supergiant fields at depths exceeding 4,500 meters with sulfur content reaching 6%. Demand concentrates in power generation utilities across the western Balkan province where new combined-cycle plants require interruptible supply contracts.
- Crude Oil:Extracted from mature Turkmennebit assets facing natural decline, requiring enhanced recovery methods including polymer flooding and gas injection to sustain plateau rates. Dragon Oil PLC sustains heavy oil output from Cheleken Peninsula through extended-reach drilling programs.
- Refined Products:Processed at Soviet-era facilities undergoing supervisory control upgrades to accommodate volatile utility nomination patterns.
- LNG:Planned liquefaction routes offer price arbitrage against pipeline-dependent contracts pending Caspian export infrastructure completion.
Natural gas commands the established base. The steepest expansion runs through LNG.
End User:
Customer type segmentation reveals procurement pattern shifts reshaping upstream investment timelines.
- Power Generation:Gas-fired capacity additions in the western Balkan province drive drilling commitments to feed turbine installations. Utilities now contract on interruptible terms rather than baseload, forcing operators to build storage buffer capacity at processing facilities.
- Industrial Sector:Petrochemical and fertilizer producers anchor offtake from Galkynysh processing trains. The State Standards Committee's GB-aligned specifications enforce quality thresholds that filter supplier eligibility.
- Residential:Distribution networks serve urban centers with subsidized tariff structures.
- Commercial:Smaller volume accounts with seasonal demand fluctuations.
Power generation anchors capacity commitments. Industrial offtake is climbing the fastest.
Technology:
Maturity gradients across technology categories separate legacy asset remediation from greenfield development approaches.
- Extraction Methods:Extended-reach drilling at Cheleken Peninsula requires directional specialists scarce in Central Asian labor markets. CNPC deploys distributed acoustic sensing across Bagtyyarlyk to compress exploration-to-development cycles from months to weeks.
- Transportation Systems:Pipeline infrastructure dominates with TAPI route negotiations unresolved, blocking firm offtake agreements. Domestic processing expansion proceeds faster than cross-border commitments.
- Refining Processes:Amine units for 6% sulfur content gas create import dependency as specialized equipment is not manufactured within Turkmenistan.
- Storage Solutions:Buffer capacity construction accelerates to accommodate interruptible power utility contracts.
Transportation systems carry the largest capital deployment. Extraction methods are gaining share fastest through digital adoption.
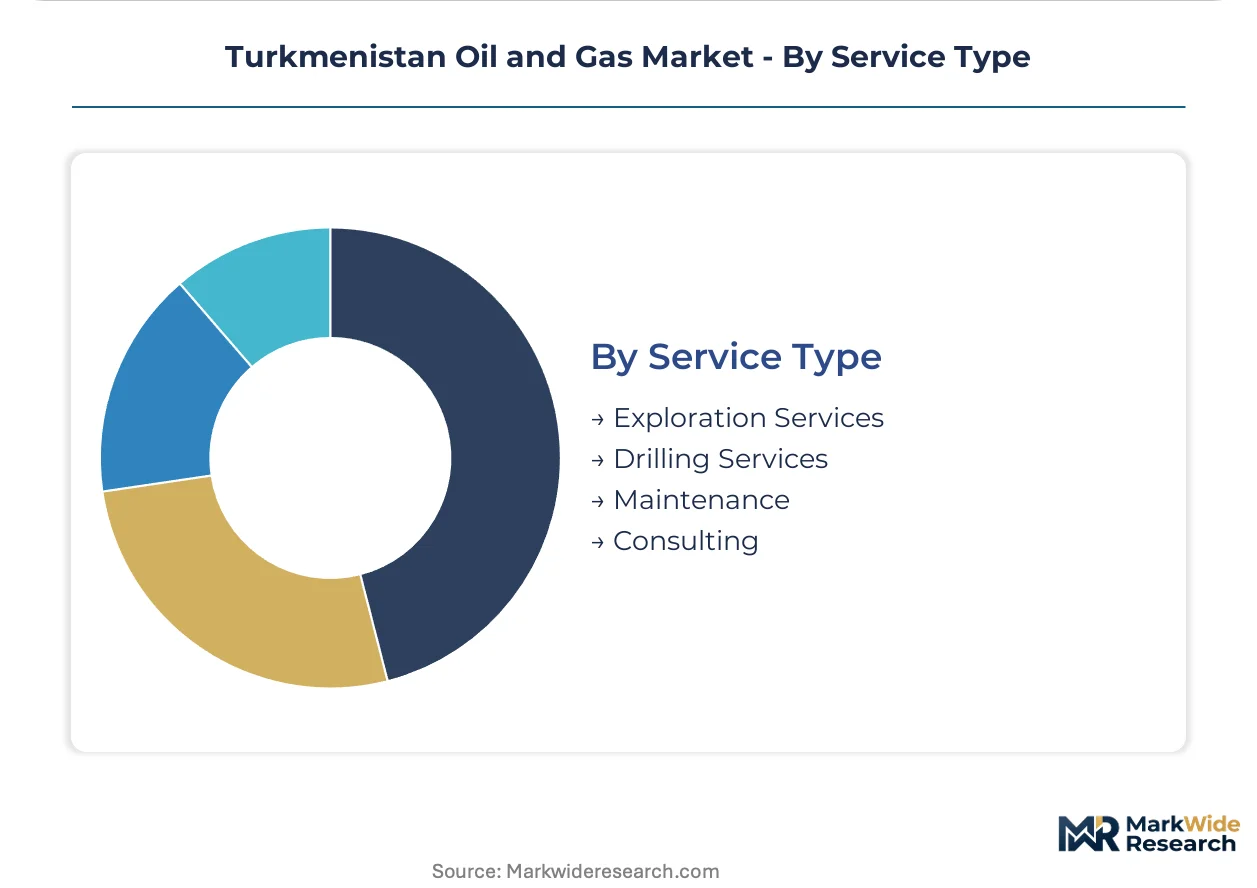
Service Type:
Margin structure across service categories reflects local content mandates and technology transfer obligations.
- Drilling Services:Joint ventures with Turkmen entities are compulsory under national energy regulator production-sharing contract thresholds. Chinese manufacturers have recertified blowout preventers fastest to meet GB-aligned pressure ratings.
- Exploration Services:Seismic imaging partnerships anchor international contractor positioning, with real-time subsurface monitoring replacing static geological models.
- Maintenance:Soviet-era plant upgrades conflict with proprietary digital twin architectures, creating integration bottlenecks.
- Consulting:Advisory scope concentrates on navigating capital repatriation constraints and currency control compliance.
Drilling services command the established revenue base. Exploration services show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turkmenistan's gas exports flow predominantly eastward through the Central Asia-China pipeline corridor, anchoring Beijing's diversification away from maritime LNG routes. The western Balkan province clusters the largest onshore fields and processing infrastructure. Regional dynamics hinge on Caspian export route competition and domestic power generation expansion.
Western Balkan Province
The western Balkan province concentrates Turkmenistan's gas-fired power generation expansion and Galkynysh field infrastructure. The national energy regulator enforces local content thresholds for all production-sharing contracts in this zone. Turkmenabat and surrounding clusters host combined-cycle plants driving interruptible supply contracts.
Bagtyyarlyk Contract Area
Seismic imaging partnerships anchor upstream activity in the Bagtyyarlyk contract area near the Uzbek border. CNPC deploys distributed acoustic sensing here to compress exploration-to-development cycles. The State Standards Committee's GB-aligned specifications filter drilling equipment eligibility for this zone.
Cheleken Peninsula
Extended-reach drilling programs sustain heavy oil output from mature Turkmennebit assets on the Cheleken Peninsula. Dragon Oil PLC operates here where directional drilling specialists remain scarce in Central Asian labor markets. Offshore processing upgrades conflict with proprietary digital twin architectures.
Dauletabad Field Zone
The Dauletabad field zone faces capital repatriation constraints that extend project payback periods for foreign investors. Currency controls limit dividend flows from this supergiant carbonate reservoir. Amine unit import dependency for 6% sulfur content gas creates processing bottlenecks.
Caspian Coastal Corridor
Planned liquefaction routes along the Caspian coastal corridor offer price arbitrage against pipeline-dependent contracts. TAPI negotiations with Afghanistan and Pakistan remain unresolved, blocking firm offtake agreements. Turkmenbashi port clusters storage buffer capacity construction.
Turkmenistan Oil and Gas Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Turkmenistan's production-sharing contract tiers. State-backed operators dominate supergiant field development through joint venture mandates, while international contractors anchor technology transfer obligations. Two strategic archetypes define positioning: integrated national champions controlling reserve access, and specialized service providers recertifying equipment to GB-aligned standards. Competitive moves concentrate on seismic imaging partnerships and domestic assembly joint ventures.
Among state-affiliated operators, JSC Türkmengaz exemplifies the national champion archetype through Galkynysh field control, while CNPC (Turkmenistan) occupies a position as the primary foreign upstream partner in the Bagtyyarlyk contract area. Dragon Oil PLC represents the specialized heavy oil operator model at Cheleken Peninsula, where extended-reach drilling competency shapes competitive differentiation.
| Leading Market Players |
|---|
| Dragon Oil PLC |
| Eni Turkmenistan |
| JSC Türkmengaz |
| ADNOC XRG |
| Hyundai Engineering Co. |
| JSC Türkmennebit |
| Petronas Carigali |
| Çalik Enerji |
| CNPC (Turkmenistan) |
| Others |
Value Network & Pricing Analysis
The western Balkan province clusters Turkmenistan's gas-fired power generation expansion and Galkynysh field infrastructure, concentrating upstream capacity that feeds interruptible utility contracts and compresses pricing power toward processing facilities rather than extraction points. This geographic concentration forces operators to absorb nomination volatility through storage buffer investments, reshaping margin allocation across the value chain.
Pricing Analysis
Legacy Soviet-era processing technology commands steep discounts against GB-aligned certified equipment, while next-generation digital reservoir management systems extract premiums through compressed exploration-to-development cycles. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and sulfur handling capability. Pricing pressure stems from currency controls limiting capital repatriation, extending foreign investor payback periods. Power generation utilities exhibit highest price sensitivity due to interruptible contract structures, while industrial petrochemical buyers accept premium tiers for guaranteed offtake.
Supply Chain Analysis
Chinese and Russian manufacturers hold dominant contract-manufacturing capacity for drilling equipment and pipeline steel, with Turkmenbashi port clustering domestic assembly joint ventures. Component sourcing draws from China for blowout preventers, Russia for specialized amine units, and Kazakhstan for logistical support. Single-source vulnerability runs through sulfur processing equipment unavailable from domestic suppliers. Distribution feeds from Caspian coastal storage buffers through pipeline corridors toward Central Asia-China export routes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Turkmenistan's oil and gas market fragments across technology generations and regulatory compliance tiers, creating niches as power utilities shift procurement toward interruptible supply contracts.
For Market Incumbents: Build regulatory compliance moats through accelerated GB-aligned certification investments. Türkmengaz and CNPC should deepen backward integration into domestic drilling equipment assembly to satisfy local content mandates. Capture channel control over sulfur processing technology transfer before emerging Chinese manufacturers establish Turkmen joint ventures. For New Entrants and Emerging Players: Build out specialized service capabilities in distributed acoustic sensing and digital twin integration for Soviet-era plant upgrades. The most penetrable segment lies in enhanced recovery deployment for mature Turkmennebit assets facing natural decline. Go-to-market positioning should anchor on directional drilling competency for Cheleken Peninsula extended-reach programs. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-captive play because pipeline route resolution and liquefaction completion determine reserve monetization timelines. Acquisition targets should screen for production-sharing contract holders with established Turkmen joint venture structures. Watch TAPI negotiation milestones as the critical inflection signal for field development commitment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| GB-Aligned Equipment Localization | Chinese manufacturers recertifying blowout preventers capture Galkynysh tender access before rivals adapt. |
| Digital Reservoir Management Deployment | Real-time subsurface monitoring at Bagtyyarlyk compresses exploration-to-development cycles from months to weeks. |
| Sulfur Processing Capacity Expansion | Amine unit imports address 6% sulfur content bottlenecks at Dauletabad field zone processing trains. |
| Interruptible Supply Contract Structuring | Power utilities in western Balkan province drive storage buffer construction at processing facilities. |
| Caspian LNG Export Infrastructure | Turkmenbashi port liquefaction routes offer price arbitrage against pipeline-dependent European contracts. |
Research Methodology
A standing panel of upstream project developers, national energy regulator compliance officers, EPC contractors, and power utility procurement managers provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with secondary validation against customs records, State Standards Committee technical specifications, production-sharing contract registries, and Central Asia-China pipeline flow disclosures. Bottom-up reserve estimates and top-down export volume analysis triangulated market sizing across the analysis window.
Scenario-bracketing anchored the forecast framework around TAPI route resolution timing and liquefaction infrastructure completion. Segmentation modeling tracked product type, end user category, technology maturity tier, and service type obligations. CAGRs derived from production decline curves, capacity addition pipelines, and export contract renegotiation patterns. Forecast inputs incorporated sulfur content processing costs, local content threshold compliance trajectories, and seismic imaging adoption rates.
The forecast holds incumbent behavior within observed patterns; aggressive technology transfer acceleration by Chinese state-backed manufacturers or sudden pipeline route resolution would shift outcomes materially. Quarterly review of production-sharing contract award flows, GB-aligned equipment import volumes, and power utility nomination volatility is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Asia- Pacific Drilling Market
Oil & Gas
CO2 EOR Market
Oil & Gas
Sucker Rod Market
Oil & Gas
Modular Refinery Market
Oil & Gas
Oilwell Completion Tools Market
Oil & Gas
Marine Oil Water Separators Market
Oil & Gas
Rig and Oilfield Mats Market
Oil & Gas
GCC and North Africa Coiled Tubing Market
Oil & Gas
Azerbaijan Oil and Gas Downstream Market
Oil & Gas
Perforating Gun Market
Oil & Gas
Oil and Gas Midstream Market
Oil & Gas
Upstream Services Market
Oil & Gas
Kazakhstan Oil and Gas Midstream Market
Oil & Gas
Indonesia Oil and Gas Midstream Market
Oil & Gas
Integrated Gas System Market
Oil & Gas
Fracking Fluid Market