
 Spacer Fluid Market | 2026-2036
Spacer Fluid Market Size, Share, and Industry Trends Forecast 2026-2036
Spacer Fluid Market Intelligence
Specialty chemical production capacity in the United States is expanding to meet operator requirements for advanced wellbore cleaning solutions. Halliburton Company leverages its integrated service model to supply fluids alongside its cementing and completion services. SLB differentiates its offering through advanced digital modeling that simulates fluid displacement and optimizes job design. Baker Hughes Company competes on the performance of its proprietary fluid formulations engineered for challenging downhole conditions, while Weatherford International offers a broad portfolio for diverse well types.
A spacer fluid is a specifically engineered liquid used in well construction to physically separate incompatible fluids, primarily drilling mud and cement slurry, while also cleaning the wellbore. Its formulation is critical for achieving specific rheological properties, density, and solids suspension capabilities to prevent contamination and ensure a strong cement bond. Water-Based formulations represent the largest segment due to their cost-effectiveness and lower environmental footprint. The Cementing application remains the primary use case, though demand is also seen in Completion Fluids for wellbore preparation.
Environmental regulations from the US EPA and Europe's ECHA under the REACH framework directly influence product composition. These rules mandate stricter controls on the chemical constituents and disposal of fluids, particularly in offshore operations, driving innovation in biodegradable chemistries. Conformance with ISO standards for well cementing also sets performance benchmarks for these fluids. Therefore, operators and service companies must balance the technical performance of spacer systems with the increasing costs associated with environmental compliance and reporting.
Market Dynamics
The spacer fluid market's development is shaped by the fundamental tension between the demand for high-performance formulations for complex wellbores and the tightening grip of environmental regulations. This dynamic forces continuous innovation in chemical composition to balance technical efficacy with compliance costs.
Growth Catalysts
- Unconventional Resources:The expansion of hydraulic fracturing in North American shale basins and Argentina's Vaca Muerta formation drives volume demand for fluids essential for multistage well completion and cementing operations.
- Deepwater Exploration:Projects in the Gulf of Mexico and offshore West Africa require advanced, temperature- and pressure-resistant spacer systems, creating demand for premium, high-performance formulations to ensure well integrity.
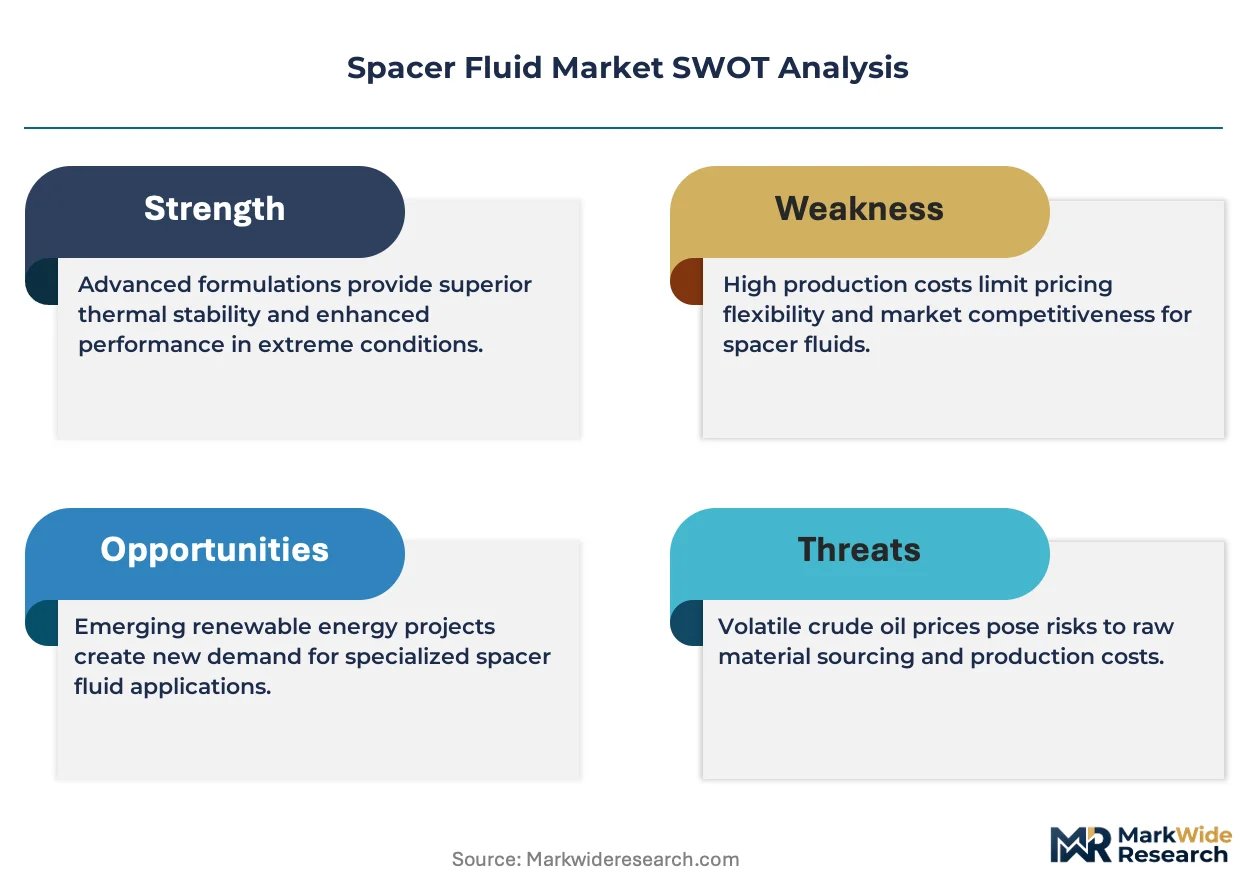
- Environmental Standards:Regulations like Europe's REACH framework incentivize the development and adoption of biodegradable, low-toxicity spacer fluids, opening a higher-margin market segment for compliant chemistries.
Market Restraints
- Input Cost Volatility:Key formulation components, such as surfactants, polymers, and weighting agents, are derived from petrochemical feedstocks, exposing fluid manufacturing costs to oil and gas price fluctuations.
- Substitution Risk:In less demanding, conventional onshore wells, some operators opt for lower-cost commodity washes or basic water flushes, bypassing the need for engineered spacer fluid systems to reduce upfront costs.
- Logistical Burden:The need to transport, store, and manage multiple distinct fluid systems (mud, spacer, cement) at remote or offshore drilling locations adds significant complexity and cost to well construction projects.
Strategic Opportunities
- Geothermal Well Applications:The global build-out of geothermal energy, particularly in regions like the US West Coast and Indonesia, creates an adjacent market for spacer fluids adapted to high-temperature steam and brine environments.
- Digital Twin Integration:Developing simulation software that models spacer fluid displacement allows service companies to sell an optimized, outcome-guaranteed cementing job rather than just a volume of fluid.
- Carbon Capture and Storage:The emerging CCUS industry requires long-term well integrity for CO2 injection wells, presenting an opportunity for specialized fluids designed to ensure a permanent cement bond.
Industry Challenges
- Extensive Compatibility Testing:Each spacer fluid must be lab-tested for compatibility with specific drilling muds and cement slurries on a per-job basis, creating significant logistical delays and increasing non-productive time.
- Field Quality Control:Maintaining the precise density, rheology, and chemical properties of a spacer fluid in harsh, variable field conditions is a constant operational challenge for rig crews.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spacer Fluid Market |
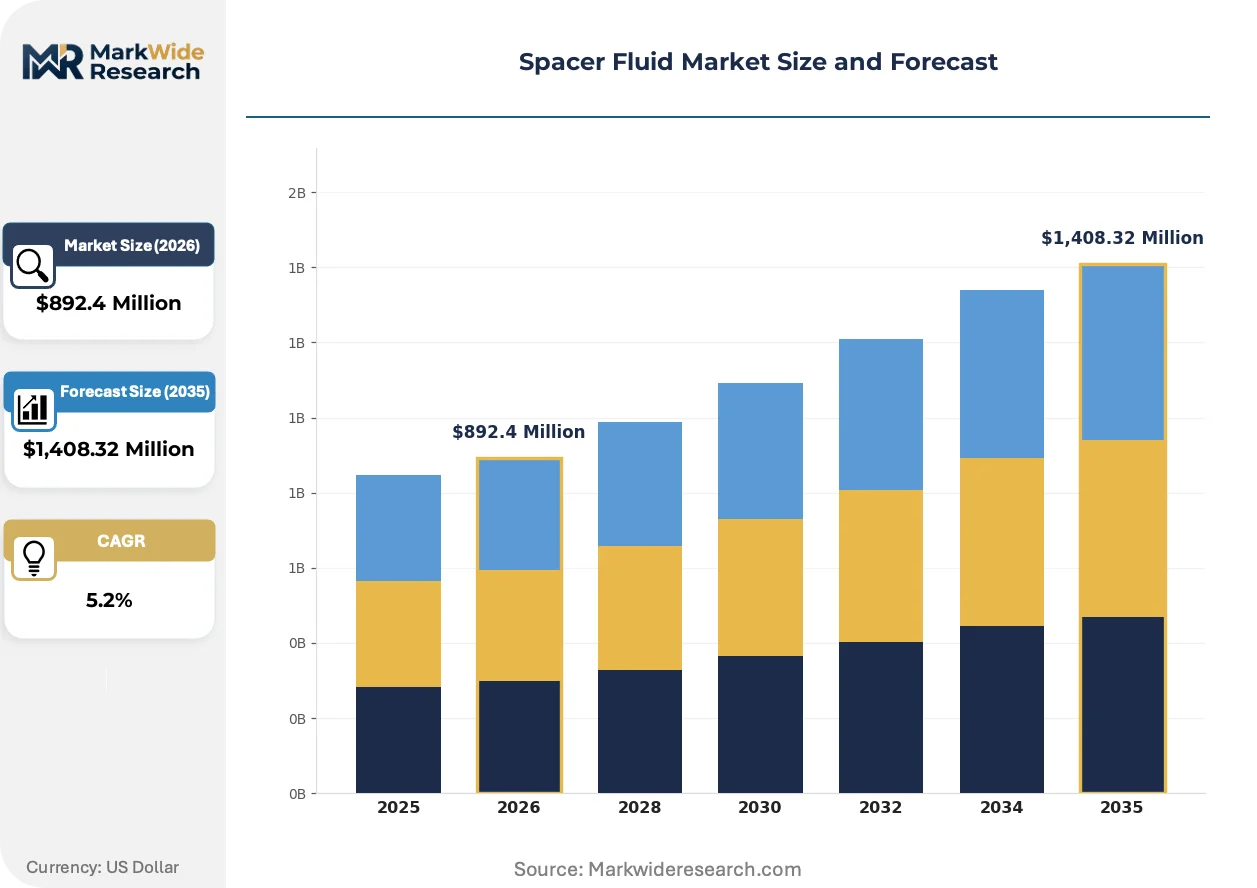
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,408.32 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Alcohol-Based, Silicone-Based, Hybrid, Oil-Based Application: Enhanced Oil Recovery, Cementing, Drilling Mud, Hydraulic Fracturing, Completion Fluids End User Industry: Upstream Oilfield Operators, Midstream Pipeline Services, Downstream Refining Plants, Drilling Contractors Packaging Type: Drums, IBC Totes, Bulk Tanks, Bag-in-Box, Cylinders |
| Companies Covered | Halliburton Company, SLB, Baker Hughes Company, Weatherford International, TETRA Technologies Inc., M&D Industries of Louisiana, Inc., Impact Fluid Solutions, Croda International plc, Trican Well Service Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spacer Fluid Market Strategic Shifts & Innovations
The evolution of spacer fluids is governed by a dual mandate: achieving perfect mechanical isolation in ever-more-complex wells while simultaneously meeting a new generation of chemical compliance and digital integration standards. This pushes development toward smarter, cleaner, and more predictable systems.
Smart fluids incorporating nanoparticles or chemical tracers provide real-time data on displacement efficiency. Major operators in high-cost deepwater and unconventional projects are the primary adopters of these advanced systems. This technology is unifying the physical displacement process with digital wellbore monitoring, transforming a mechanical step into a data-rich, verifiable operation that improves cement bond quality assurance.
Regulations from the US EPA governing offshore fluid discharge and Europe's ECHA under the REACH framework are directly impacting product design. These rules mandate strict controls on chemical constituents, forcing a move away from certain traditional, high-performance but environmentally persistent surfactants. Offshore operators are most affected, accelerating R&D investment in biodegradable and water-based chemistries to ensure operational permits.
Operators are increasingly shifting from procuring fluids as a standalone product to purchasing a holistic "wellbore integrity" service package. This model disrupts the traditional transactional sales channel from chemical manufacturers to oilfield service companies. The trend is most visible in fast-paced North American shale developments, where integrated service providers bundle fluids, cementing services, and digital optimization tools into a single contract.
Spacer Fluid Market Segmentation
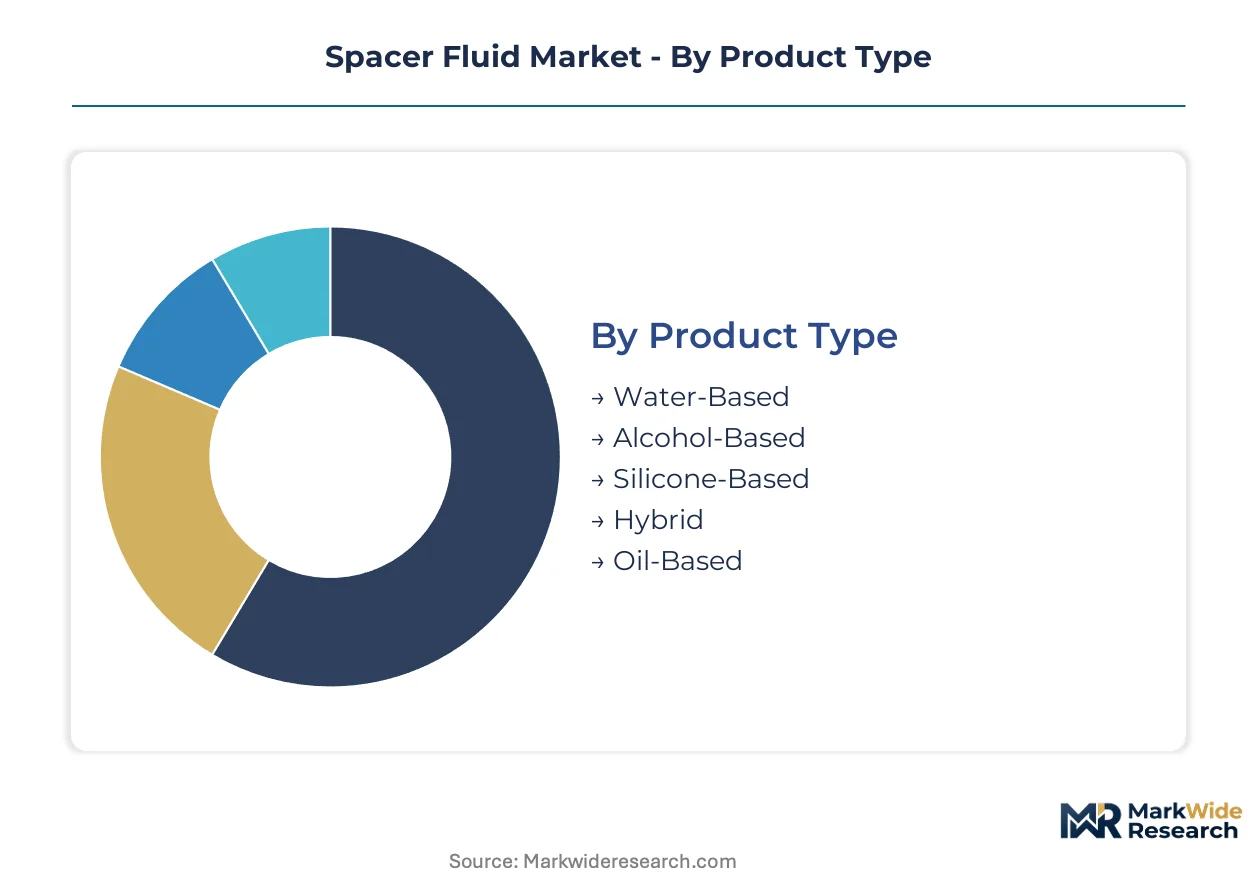
The spacer fluid market's segmentation provides a structured view of its diverse product offerings, applications, and end-user requirements. Understanding these distinct segments helps stakeholders identify specific growth pockets and tailor product development to evolving industry demands and regulatory landscapes.
Product Type:
The selection of spacer fluid product types is often dictated by the necessary environmental compliance and performance certifications required for specific operational environments.
- Water-Based:These formulations are highly cost-effective and exhibit a lower environmental footprint, making them a primary choice for many operations. Demand concentrates in North American shale basins, driven by their suitability for extensive well completion programs and environmental regulations from the US EPA.
- Oil-Based:Engineered for performance in challenging high-temperature and high-pressure downhole conditions, these fluids offer superior lubricity and shale inhibition. Demand is pronounced in deepwater exploration projects, where their robust properties ensure well integrity against stringent operational parameters.
- Alcohol-Based:These specialized fluids are employed in gas wells or low-temperature environments where water-based systems might freeze or cause formation damage.
- Silicone-Based:Offering unique lubricity and thermal stability, silicone-based fluids find niche applications in wells requiring specific material compatibility or extreme temperature resistance.
- Hybrid:Combining characteristics of different base fluids, hybrid formulations are tailored to optimize performance for complex wellbore conditions and specific fluid compatibility requirements.
Leading the category by volume: Water-Based. Growing fastest: Hybrid.
Application:
This segment highlights the varied operational contexts where spacer fluids are essential, with demand patterns reflecting the technical complexity and strategic importance of each use case.
- Cementing:This remains the primary application, critical for ensuring wellbore integrity by effectively separating drilling mud from cement slurry and preventing contamination. Demand is significant across all well types, particularly in unconventional shale plays in the United States and Argentina.
- Enhanced Oil Recovery:Spacer fluids in EOR operations improve oil displacement efficiency and well injectivity in mature fields, requiring specialized fluid properties for optimal performance. Demand is expanding in mature basins like the Permian Basin and in deepwater projects in the Gulf of Mexico.
- Drilling Mud:Spacer fluids are utilized to prepare the wellbore effectively before cementing, ensuring the removal of drilling mud and preventing its interaction with cement.
- Hydraulic Fracturing:These fluids support the creation of fractures in unconventional reservoirs, ensuring optimal communication with the formation.
- Completion Fluids:Employed during the final stages of well preparation, these fluids ensure a clean and stable wellbore before hydrocarbon production commences.
Cementing remains the dominant application, while Enhanced Oil Recovery shows significant expansion.
End User Industry:
The end-user segment reflects the diverse stakeholders involved in well construction and maintenance, each with distinct procurement patterns and technical requirements for spacer fluids.
- Upstream Oilfield Operators:These entities are primarily responsible for well design, drilling, and production, driving the specifications and demand for high-performance spacer fluids. Their demand is concentrated across global exploration and production activities, including projects in Norway and Brazil.
- Drilling Contractors:These companies execute the physical drilling and well completion operations, managing the logistics and application of spacer fluids at the rig site. Their demand is high in active drilling regions like the North Sea and the Middle East, where operational efficiency is paramount.
- Midstream Pipeline Services:These services may utilize spacer fluids for pipeline cleaning, pigging operations, or maintenance activities to ensure flow assurance.
- Downstream Refining Plants:Niche use cases for specialized cleaning or separation processes occasionally require specific spacer fluid formulations within refining operations.
Upstream Oilfield Operators and Drilling Contractors collectively represent the core demand base for spacer fluids.
Packaging Type:
Packaging choices for spacer fluids are primarily driven by the scale of operations, logistical constraints, and the specific chemical properties of the fluid, influencing transport and handling efficiency.
- Bulk Tanks:These provide high-volume delivery for large-scale drilling and completion programs, significantly reducing handling and transportation costs per unit volume. Demand is concentrated in deepwater drilling projects off the coast of Angola and remote onshore developments in Kazakhstan.
- IBC Totes:Intermediate bulk containers offer flexibility for medium-volume requirements and specialized fluid chemistries, providing efficient storage and deployment. Their use is widespread across unconventional shale plays in the United States and Canada, accommodating varied well site needs.
- Drums:Standard 55-gallon drums are used for smaller volumes of specialized additives or for locations with limited storage and handling infrastructure.
- Bag-in-Box:This packaging offers efficient storage and disposal for certain chemical formulations, particularly those with environmental handling considerations.
- Cylinders:Primarily used for gaseous components or highly specialized, small-volume additives that require precise dispensing and controlled environments.
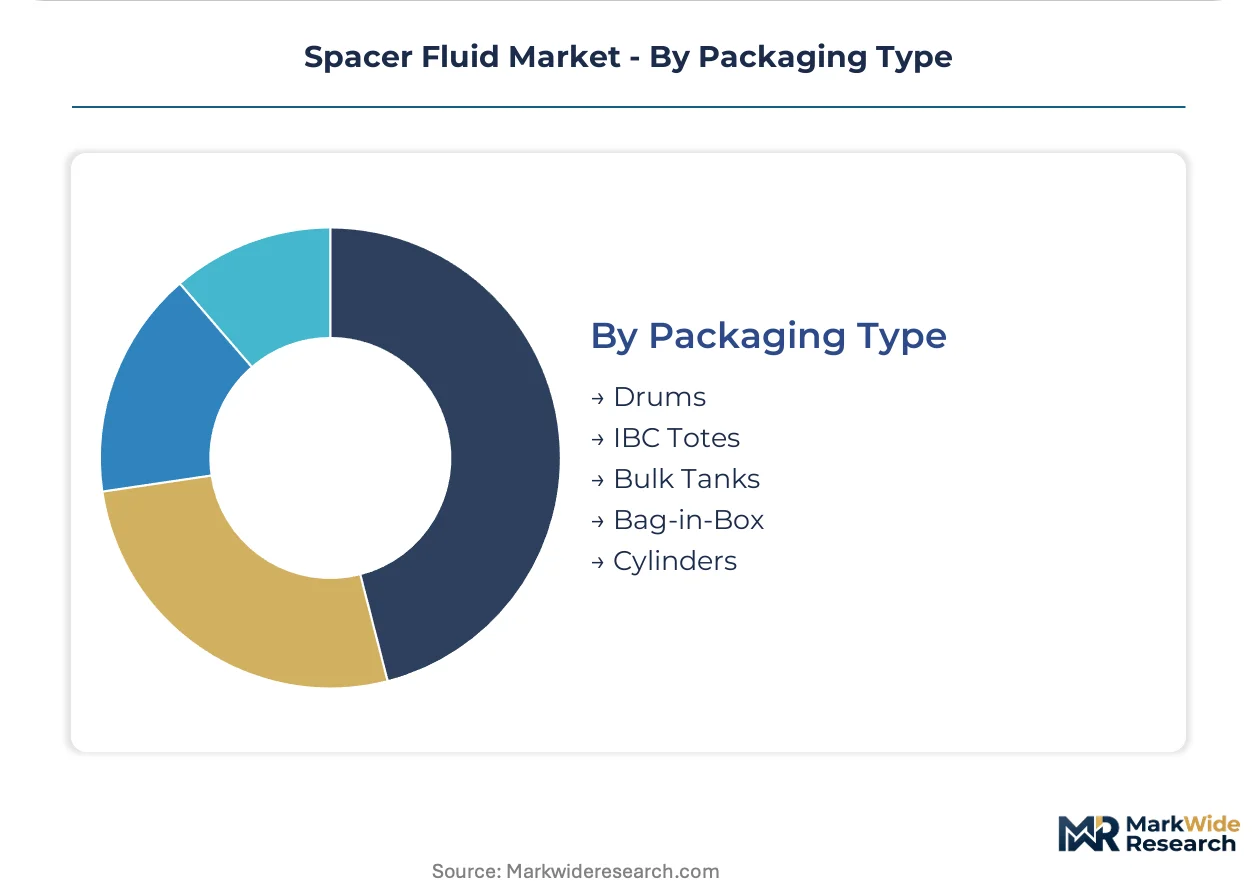
Packaging choices optimize logistics and cost efficiency for various operational scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global oil and gas basins, particularly those rich in unconventional and deepwater reserves, anchor the demand for spacer fluids. These specialized chemicals are essential for well integrity across diverse operational environments. Environmental regulations and technological advancements significantly influence regional market dynamics.
United States
Demand for spacer fluids in the United States stems from extensive unconventional shale plays, particularly in the Permian Basin. The US EPA regulations for hydraulic fracturing and wastewater disposal mandate the use of environmentally compliant fluid formulations. Houston, Texas, serves as a central hub for oilfield service companies developing and deploying advanced wellbore cleaning solutions.
Brazil
Offshore deepwater exploration in Brazil's pre-salt region drives significant demand for high-performance spacer fluids. ANP regulations govern the environmental impact of drilling and completion activities, requiring robust fluid design for challenging conditions. Rio de Janeiro is a key operational base, supporting advanced fluid logistics for complex offshore projects.
Norway
The Norwegian Continental Shelf's mature offshore fields and strict environmental standards create a market for specialized spacer fluids. NORSOK standards and the EU ECHA REACH framework influence product composition, favoring biodegradable and low-toxicity options. Stavanger acts as a critical center for offshore technology development, including advanced well integrity solutions.
Saudi Arabia
Extensive conventional oil and gas production in Saudi Arabia sustains consistent demand for spacer fluids in cementing applications. The Ministry of Energy's directives emphasize efficient and safe well construction practices, impacting fluid specifications. Dhahran, within the Eastern Province, concentrates research and development for oilfield chemicals tailored to regional needs.
China
China's expanding unconventional gas developments and offshore projects, particularly in the South China Sea, generate demand for spacer fluid technologies. GB standards and the Ministry of Ecology and Environment's policies push for greener chemical solutions in oilfield operations. Beijing and Shanghai host significant R&D centers focused on developing localized high-performance fluid formulations.
Spacer Fluid Market Key Industry Players
Global majors compete with regional champions across the spectrum of fluid formulation, service integration, and geographic reach. The market structure exhibits consolidation among top-tier oilfield service providers who offer integrated solutions. Several strategic archetypes include specialized chemical suppliers, full-service cementing providers, and technology-driven fluid innovators. Companies primarily pursue strategic partnerships for technology co-development and geographic expansion into emerging resource plays.
Within the full-service oilfield solutions segment, Halliburton Company and SLB exemplify integrated service models, leveraging their extensive global infrastructure and digital optimization tools. Baker Hughes Company occupies a position as a technology-focused provider, anchoring its offerings on proprietary fluid formulations engineered for demanding downhole conditions. These entities represent the trend towards bundled services, combining chemical supply with cementing and completion expertise to deliver optimized wellbore integrity solutions across diverse operational theaters.
| Leading Market Players |
|---|
| Halliburton Company |
| SLB |
| Baker Hughes Company |
| Weatherford International |
| TETRA Technologies Inc. |
| M&D Industries of Louisiana, Inc. |
| Impact Fluid Solutions |
| Croda International plc |
| Trican Well Service Ltd. |
| Others |
Cost & Logistics Intelligence
The development of advanced biodegradable formulations simultaneously reshapes cost economics and supply concentration in the spacer fluid market. This transition elevates research and development expenditures while focusing production capacity in regions with stringent environmental regulations.
Pricing Analysis
Service-inclusive pricing models dominate the spacer fluid market, where operators often purchase outcome-guaranteed cementing jobs rather than standalone fluid volumes. Price differentiation stems from fluid performance in challenging downhole conditions and compliance with environmental certifications such as REACH. Pricing pressure stems from the high R&D investment required for compliant, high-performance chemistries. Upstream oilfield operators in deepwater projects exhibit lower price sensitivity, prioritizing well integrity, while those in conventional onshore wells are highly sensitive to cost.
Supply Chain Analysis
Regional distribution centers and on-site storage facilities manage the logistical burden of spacer fluid delivery to remote drilling locations. Geographic supply concentration for specialty chemical components draws from the United States, Europe, and China. Raw material dependencies include petrochemical-derived surfactants, polymers, and weighting agents. Input cost volatility, driven by oil and gas price fluctuations, represents a significant structural supply chain risk. Distribution runs through integrated oilfield service providers directly to rig sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The spacer fluid market functions as a cost-of-compliance sector, where regulations like Europe's REACH framework create a barrier-to-entry moat for compliant players. This necessitates continuous investment in R&D for advanced, environmentally sound chemistries.
For Market Incumbents: Cement integrated service models by bundling advanced fluid formulations with digital optimization tools and cementing services. This defends market share against specialized chemical suppliers and reinforces customer relationships in high-value deepwater and unconventional projects. Invest in R&D for biodegradable chemistries to meet evolving environmental standards, especially for offshore operations. Leverage existing global infrastructure for efficient fluid logistics.
For New Entrants and Emerging Players: Specialized chemical distributors can target niche segments like geothermal well applications or carbon capture and storage (CCUS) projects. These emerging areas require specialized fluid properties and offer white space for innovative, performance-driven solutions. Focus on rapid compatibility testing services as a go-to-market angle, addressing a significant industry challenge. Smaller onshore conventional wells represent a penetrable segment for cost-effective, engineered alternatives to commodity washes.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by oilfield service majors seeking to enhance their integrated service offerings. The long-term viability of this market rests on sustained demand for well integrity solutions in complex and environmentally sensitive drilling environments. Acquisition targets should include specialized fluid formulators with proprietary biodegradable chemistries or advanced digital modeling capabilities. The signal to watch is increased M&A activity focused on sustainable chemistries or digital wellbore optimization platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand biodegradable fluid portfolio | Addresses stricter environmental regulations and opens higher-margin market segments. |
| Integrate digital twin simulation tools | Optimizes fluid displacement and enhances cementing job design for operators. |
| Develop fluids for geothermal applications | Captures demand from the global build-out of renewable energy infrastructure. |
| Invest in advanced compatibility testing labs | Reduces non-productive time and logistical delays for complex well projects. |
| Secure long-term supply agreements for key inputs | Mitigates input cost volatility stemming from petrochemical price fluctuations. |
Research Approach
Multi-period observation of market size, growth rates, and regulatory shifts anchored the trend analysis, supplemented by interviews with upstream oilfield operators, drilling contractors, chemical engineers, and environmental compliance officers. Secondary validation included government regulatory filings, company annual reports, and academic journals on drilling and cementing. This approach ensured robust bottom-up and top-down triangulation.
An input-output matrix framework informed quantitative projections across the analysis window. Segmentation dimensions modeled included product type, application, end-user industry, packaging type, and regional regulatory frameworks. Compound annual growth rates were derived through regression analysis on historical data and projections based on future demand drivers and restraints. Oil and gas drilling activity forecasts served as a primary industry-specific forecast input.
Caveats apply where sudden shifts in oil prices or major regulatory changes could materially shift the outlook. Forecasts reflect assumptions regarding drilling activity levels, technological advancements, and environmental policy evolution. Volatility in energy prices and unforeseen regulatory burdens represent specific risk factors. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Open Hole Logging Services Market
Oil & Gas
Modular Gas Processing Plants Market
Oil & Gas
Africa Natural Gas Market
Oil & Gas
Rigless Intervention Systems Sales Market
Oil & Gas
Swellable Packers Market
Oil & Gas
Liquefied Natural Gas Market
Oil & Gas
Pipeline Pigging Services Market
Oil & Gas
Oilfield Chemicals Market
Oil & Gas
United States Natural Gas Market
Oil & Gas
Well Casing Market
Oil & Gas
Thermal Spray Coating for Oil and Gas Market
Oil & Gas
Nigeria Oil and Gas Market
Oil & Gas
United States Onshore Drilling Fluid Market
Oil & Gas
Asia-Pacific Natural Gas Market
Oil & Gas
GCC and North Africa Coiled Tubing Market
Oil & Gas
Algeria Oil and Gas Market