
 Oil and Gas Storage Market | 2026-2036
Oil and Gas Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Storage Market Analytics
Project finance for independent storage terminals is fragmenting competitive dynamics across the midstream sector. Kinder Morgan leverages its vast pipeline-connected tank network to sustain fee-based revenue stability. Energy Transfer Partners anchors its position through integrated crude and NGL storage along the Gulf Coast. Enterprise Products Partners differentiates via automated tank gauging and vapor recovery investments at its Mont Belvieu complex.
Oil and gas storage encompasses above-ground atmospheric tanks, underground salt caverns, and pressurized vessels designed to hold crude oil, natural gas, LNG, and condensates at specified temperature and pressure thresholds for inventory management, supply balancing, and strategic reserve functions. Floating roof tanks dominate crude storage due to reduced evaporative losses, while underground caverns command premium economics for natural gas and LNG peak-shaving applications. Smart monitoring technology is displacing manual inspection regimes as operators seek real-time leak detection and emissions compliance.
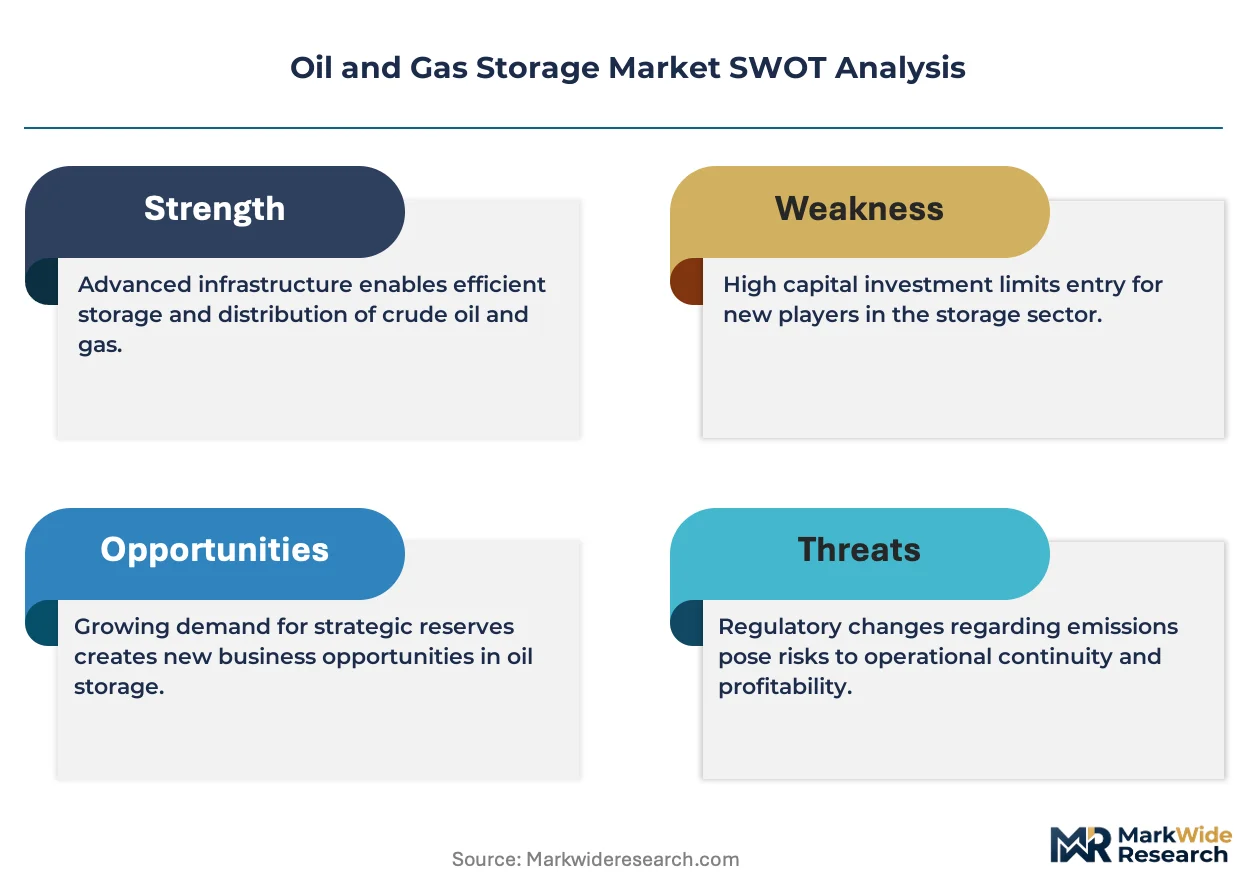
EPA New Source Performance Standards and OSHA Process Safety Management rules govern tank construction, emissions controls, and worker safety protocols across U.S. storage facilities. EMA and national regulators in Europe enforce REACH-aligned material standards and F-Gas Regulation compliance for refrigerated LNG storage systems. Stakeholders must weigh capital allocation between brownfield automation retrofits and greenfield cavern development as regulatory thresholds tighten and offtake contracts shift toward shorter durations.
Market Dynamics
EPA vapor recovery mandates and OSHA Process Safety Management rules are forcing storage operators to choose between expensive brownfield retrofits and greenfield automation investments, compressing project timelines and fragmenting capital allocation across the midstream sector.
Growth Catalysts
- Strategic Petroleum Reserve Buildouts:India and China are constructing massive underground cavern networks to buffer against supply disruptions, creating sustained demand for salt dome engineering and long-duration storage contracts.
- Floating Roof Tank Standards:EMA-aligned emissions frameworks across Europe are mandating evaporative loss controls, accelerating replacement cycles for older atmospheric tanks at Rotterdam and Antwerp terminals.
- Smart Monitoring Adoption:Automated tank gauging systems with real-time leak detection are displacing manual inspection regimes as operators seek continuous emissions compliance and reduced insurance premiums.
Market Restraints
- Steel Input Volatility:Carbon steel plate prices fluctuate with iron ore and energy costs, squeezing margins on new tank construction and forcing developers to delay greenfield projects.
- Cavern Development Lead Times:Salt dome leaching for underground gas storage requires 5-7 years from permitting to operation, locking capital in geologically suitable regions like the US Gulf Coast and Germany.
- Pipeline-Connected Concentration:Terminal economics depend on pipeline access controlled by integrated midstream operators, limiting independent storage developers to secondary locations with weaker offtake terms.
Strategic Opportunities
- India Terminal Expansion:The country's petroleum regulator is licensing coastal storage at Visakhapatnam and Mangalore for strategic reserves, opening capacity for international trading houses and national oil companies.
- Hydrogen Blending Infrastructure:Existing salt caverns and pressurized vessels can be retrofitted for hydrogen storage, positioning operators for industrial decarbonization contracts from steel and chemical producers.
- ISO 19840 Coatings Compliance:International standards for protective coatings on tank internals are creating premium service tiers for inspection and maintenance providers with certified applicator networks.
Industry Challenges
- Automation Integration Complexity:Legacy SCADA systems at decades-old terminals require expensive middleware to connect with cloud-based analytics platforms, delaying real-time monitoring deployments.
- Certified Welder Shortages:API 650 and API 653 qualified technicians are concentrated at specialized contractors, creating bottlenecks for tank construction and turnaround maintenance schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Storage Market |
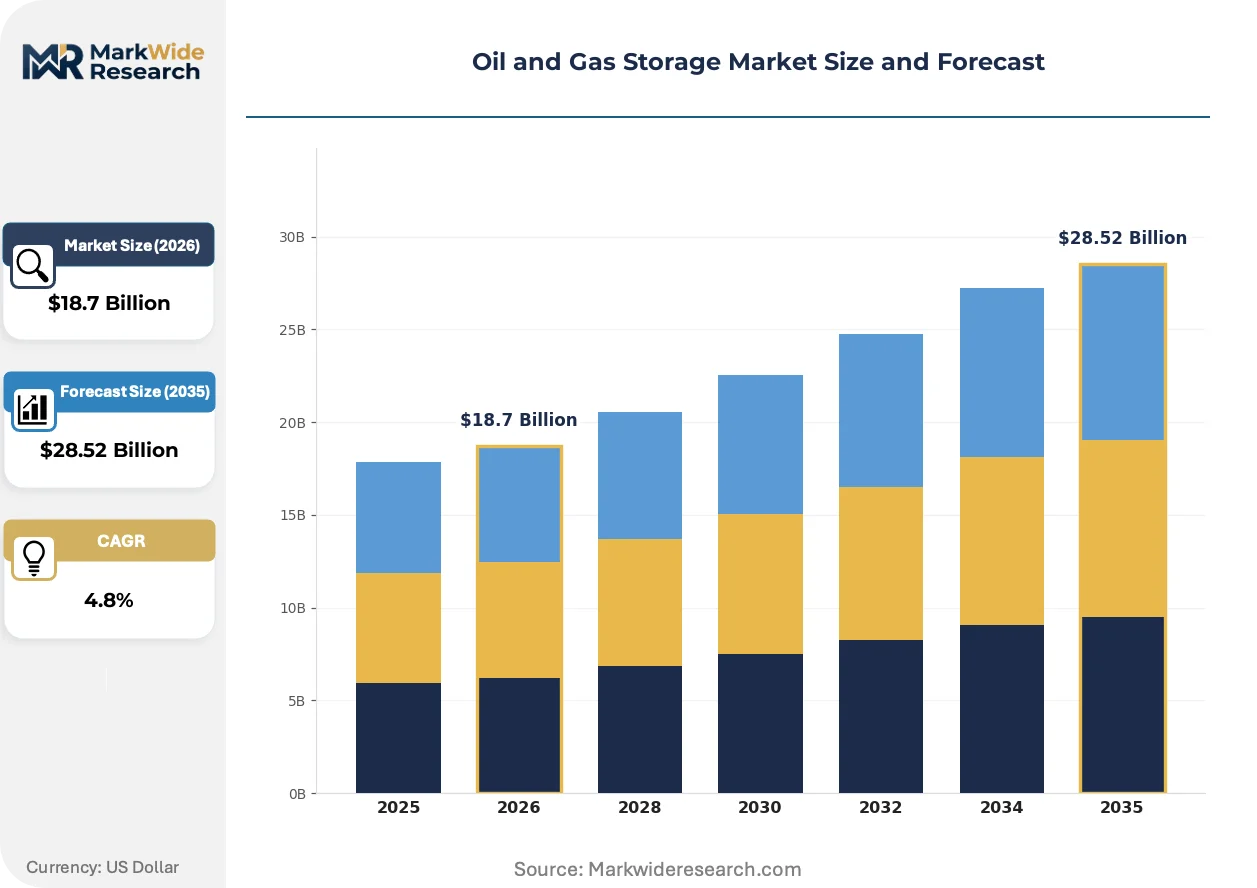
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Storage Type: Above Ground Tanks, Underground Caverns, Fixed Roof Tanks, Floating Roof Tanks Product Type: Crude Oil, Natural Gas, Liquefied Natural Gas, Condensates End User: Refineries, Pipeline Operators, Retail Gas Stations, Industrial Users Technology: Manual Storage, Automated Storage, Smart Monitoring, Vapor Recovery Systems |
| Companies Covered | Energy Transfer Partners, Targa Resources, Enterprise Products Partners, Cheniere Energy, MPLX, Kinder Morgan, ONEOK, Golar LNG, Williams Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Storage Market Evolving Landscape
Digital instrumentation and emissions sensing hardware are converging with predictive analytics software, transforming storage terminals from passive inventory facilities into actively optimized nodes within integrated supply chains.
Hybrid floating-fixed roof tank designs is hybridizing evaporative loss control with structural simplicity, allowing mid-size terminals to achieve emission rates approaching full floating roof systems at 30% lower capital cost. Independent operators in the US Midcontinent are piloting these configurations for condensate storage. The technology is compressing the premium gap between basic cone roof tanks and full floating roof installations.
REACH-aligned material standards and the EU F-Gas Regulation are tightening specifications for seals, gaskets, and refrigeration systems in LNG storage, forcing European terminals to source certified components through approved supplier lists. Tank farm operators at Zeebrugge and Barcelona are consolidating procurement to vendors with ECHA-registered substance portfolios. The regulatory friction is raising compliance costs but creating defensible positions for certified equipment providers.
Short-duration offtake contracts are displacing traditional 10-15 year storage leases as trading houses and refiners seek operational flexibility over rate certainty. This compression is visible at Gulf Coast NGL hubs where spot and monthly agreements now dominate term structures. Terminal operators are responding with tiered rate cards that penalize early exit while preserving headline capacity commitments.
Oil and Gas Storage Market Segmentation
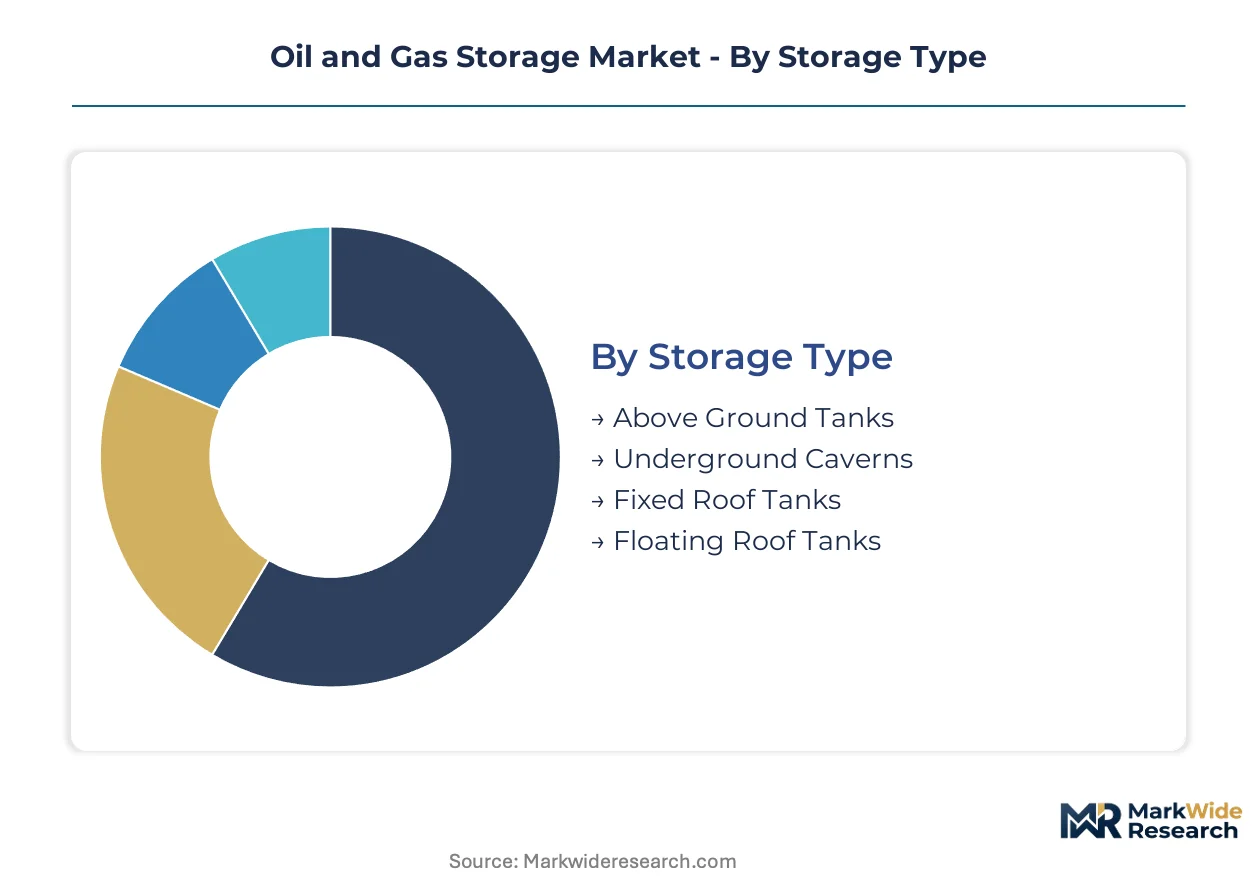
Storage infrastructure segmentation reveals how capital allocation shifts between mature tank technologies and emerging automation systems. Each dimension—physical containment, stored commodity, customer type, and operational technology—carries distinct regulatory burdens and margin profiles that reshape competitive positioning.
Storage Type:
Use cases span from high-turnover refinery feedstock tanks to multi-decade strategic reserves in salt formations.
- Above Ground Tanks:Atmospheric steel vessels dominate refinery tank farms and coastal terminals. India and China are expanding above-ground capacity at Visakhapatnam and Dalian for strategic petroleum reserves, though EPA vapor recovery mandates are forcing costly retrofits at US facilities.
- Underground Caverns:Leached salt domes deliver the lowest unit storage cost for natural gas and crude. Germany and the US Gulf Coast concentrate development, but 5-7 year lead times from permitting to operation lock capital in geologically suitable regions.
- Floating Roof Tanks:Pontoon-based designs cut evaporative losses by 80% versus fixed roofs. EMA-aligned emissions frameworks across Europe are mandating these configurations at Rotterdam and Antwerp terminals.
- Fixed Roof Tanks:Cone-roof structures persist for low-volatility products and water injection fluids. Operators favor them where vapor recovery systems can be retrofit affordably.
The dominant share belongs to above-ground tanks, while underground caverns are closing the gap fastest as strategic reserve buildouts accelerate.
Product Type:
Stored commodities differ sharply in pressure requirements, boil-off characteristics, and contract duration economics.
- Crude Oil:Sulfur content and API gravity dictate tank metallurgy and heating requirements. Floating roof tanks dominate crude storage due to reduced evaporative losses, with demand concentrating at pipeline injection points.
- Liquefied Natural Gas:Cryogenic storage at minus 162 degrees Celsius requires specialized nickel-steel alloys and full-containment concrete structures. REACH-aligned material standards and the EU F-Gas Regulation are tightening specifications for seals and refrigeration systems at Zeebrugge and Barcelona.
- Natural Gas:Underground salt caverns command premium economics for peak-shaving applications. Developers target the US Gulf Coast and Germany where geological formations support rapid injection and withdrawal cycles.
- Condensates:Light hydrocarbon mixtures bridge crude and NGL classifications. Midcontinent terminals are piloting hybrid floating-fixed roof designs to achieve emission controls at lower capital cost.
Crude oil holds the largest installed base, though LNG is expanding most quickly as import terminal networks proliferate.
End User:
Customer economics vary from fee-based pipeline connectivity to merchant trading exposure.
- Refineries:Integrated operators require continuous feedstock availability, favoring pipeline-connected tankage with automated inventory management. Asia-Pacific refineries are expanding tank farm capacity to secure supply chains.
- Pipeline Operators:Storage serves as line pack and batch segregation infrastructure. Kinder Morgan leverages its vast pipeline-connected tank network to sustain fee-based revenue stability.
- Retail Gas Stations:Underground pressurized vessels for gasoline and diesel face EPA leak detection mandates. Automated tank gauging systems are displacing manual inspection regimes.
- Industrial Users:Petrochemical and steel producers seek long-term storage for feedstock security. Hydrogen blending infrastructure retrofits are positioning salt cavern operators for industrial decarbonization contracts.
Refineries command the greatest storage volume, while industrial users are gaining share fastest as hydrogen storage applications emerge.
Technology:
Operational sophistication separates compliance-driven retrofits from greenfield automation investments.
- Smart Monitoring:IoT sensors and cloud-based analytics enable real-time leak detection and predictive maintenance. Energy Transfer Partners anchors its position through integrated storage with automated systems along the Gulf Coast.
- Vapor Recovery Systems:VRU units capture tank emissions for reprocessing or fuel use. EPA New Source Performance Standards are forcing storage operators to retrofit existing infrastructure.
- Automated Storage:Robotic tank cleaning and unmanned aerial inspection reduce worker exposure. Legacy SCADA systems at decades-old terminals require expensive middleware to connect with cloud platforms.
- Manual Storage:Visual inspection and dipstick measurement persist at smaller terminals. Certified API 650 and API 653 technician shortages are creating maintenance bottlenecks.
Smart monitoring leads technology investment, while vapor recovery systems are climbing the fastest as regulatory thresholds tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances are reshaping storage demand patterns across major economies. Countries with structural deficits are expanding strategic reserves, while surplus producers invest in export terminal capacity. Regulatory divergence is fragmenting investment timelines and technology choices.
United States
Gulf Coast export terminals and Permian Basin production growth are driving above-ground tank construction. EPA vapor recovery mandates and OSHA Process Safety Management rules are forcing brownfield retrofits at legacy facilities. Mont Belvieu and Houston host the densest concentration of NGL and crude storage infrastructure.
China
Strategic petroleum reserve buildouts at Dalian and Huangdao are accelerating salt cavern and tank farm development. MEE emissions standards and dual carbon goals are tightening construction specifications for new terminals. The Yangtze River Delta cluster is expanding coastal storage to secure Middle Eastern crude supply chains.
India
Visakhapatnam and Mangalore strategic reserve sites are licensing capacity to national oil companies and trading houses. CEA technical standards and DGFT import policies are shaping terminal design requirements. The country's west coast is emerging as the primary concentration for crude import storage.
Germany
Natural gas salt cavern development in Lower Saxony is expanding to buffer pipeline supply disruptions. EMA-aligned frameworks and EU F-Gas Regulation compliance are raising costs for LNG terminal operators. The Rehden and Etzel cavern complexes anchor northwest European gas storage capacity.
Netherlands
Rotterdam and Antwerp terminals are retrofitting floating roof tanks under EMA evaporative loss mandates. REACH-aligned material standards are restricting seal and gasket procurement to certified suppliers. The ARA cluster remains the primary hub for Northwest European crude and product storage.
Oil and Gas Storage Market Competitive Landscape
On the supply side, the industry is consolidating around pipeline-integrated midstream operators and independent terminal specialists. Capital intensity and regulatory compliance costs are squeezing smaller players toward niche positions or acquisition exits. Three archetypes dominate: integrated pipeline operators with captive storage, independent terminal developers with merchant exposure, and LNG specialists with cryogenic expertise. Competitive moves center on brownfield automation retrofits and strategic reserve contract capture.
Among pipeline-integrated operators, Kinder Morgan, Energy Transfer Partners, and Enterprise Products Partners exemplify the fee-based revenue stability model. These entities anchor positions through pipeline-connected tank networks and Gulf Coast corridor concentration. Independent developers occupy a more exposed tier, competing for shorter-duration offtake contracts at secondary locations. The competitive terrain rewards scale in automation deployment and regulatory compliance certification rather than pure capacity expansion.
| Leading Market Players |
|---|
| Energy Transfer Partners |
| Targa Resources |
| Enterprise Products Partners |
| Cheniere Energy |
| MPLX |
| Kinder Morgan |
| ONEOK |
| Golar LNG |
| Williams Companies |
| Others |
Value Network & Pricing Analysis
Gulf Coast pipeline corridors linking Permian Basin production to Houston export terminals concentrate cost dynamics for storage operators, with freight differentials between origin and destination creating three-tier pricing stratification across premium automation-equipped facilities, standard vapor-recovery-compliant terminals, and economy manual-storage sites.
Pricing Analysis
Industrial OEM buyers anchor contract structures around long-duration offtake agreements with automated inventory management provisions. Price differentiation rests on certification tier—API 653-qualified terminals command 15-20% premiums over uncertified competitors—and pipeline connectivity density. Cost compression in standard-tier storage is intensifying because steel input volatility squeezes construction margins, forcing developers to delay greenfield projects. Merchant trading houses exhibit highest price sensitivity due to shorter contract horizons, while strategic petroleum reserve operators prioritize supply security over rate optimization.
Supply Chain Analysis
Tariff exposure between US and Chinese steel suppliers dominates input cost volatility for tank construction. Manufacturing concentrates in China, South Korea, and Germany for specialized nickel-steel alloys used in cryogenic LNG containment. Raw material dependencies span carbon steel plate, API-certified welding consumables, and ECHA-registered seal compounds. Single-source vulnerability persists for qualified API 650/653 welders concentrated at specialized contractors. Distribution runs through EPC contractors with certified fabrication yards serving terminal developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Strategic petroleum reserve buildouts across India and China signal early-cycle expansion, with salt cavern engineering capacity becoming the binding constraint on project delivery timelines.
For Market Incumbents: Build regulatory compliance moats through automated tank gauging and vapor recovery retrofits at legacy facilities. Kinder Morgan's pipeline-connected network model offers defensive positioning against merchant storage margin compression. Enterprise Products Partners demonstrates how ISO 19840 coating certification investments create service-tier differentiation. Prioritize brownfield automation over greenfield capacity as short-duration contracts reduce rate certainty. For New Entrants and Emerging Players: Establish a beachhead in India's Visakhapatnam and Mangalore strategic reserve licensing rounds where national oil companies seek international partners. Hydrogen blending infrastructure retrofits for existing salt caverns represent the most penetrable white-space application, targeting steel and chemical producer decarbonization contracts. Pursue certified applicator partnerships for protective coatings compliance rather than competing on pure storage capacity. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated oil majors spinning non-core terminal assets to focus on upstream operations. Long-term viability favors operators with Gulf Coast corridor concentration and pipeline interconnectivity. Watch for inflection signals in EPA enforcement intensity around methane emissions monitoring requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Tank Gauging Deployment | Real-time leak detection at Mont Belvieu reduces insurance premiums and EPA violation exposure. |
| Salt Cavern Hydrogen Retrofit | Existing Lower Saxony formations position operators for industrial decarbonization contracts from German steel producers. |
| API 653 Certification Investment | Qualified technician networks create maintenance bottlenecks that certified operators can monetize through premium service tiers. |
| Strategic Reserve Contract Capture | Indian CEA licensing at coastal sites locks in decade-plus revenue visibility against merchant storage volatility. |
| Hybrid Floating-Fixed Roof Piloting | Midcontinent condensate terminals achieve emission compliance at 30% capital savings versus full floating roof systems. |
Research Methodology
A spread of perspectives from terminal operations managers, EPC contractors, petroleum regulatory officials, and trading house logistics directors converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against FERC storage capacity reports, EIA inventory data, EPA enforcement disclosures, and API standards documentation. Bottom-up capacity counts triangulated with top-down demand modeling across refinery feedstock requirements and strategic reserve buildout timelines.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include storage type, stored commodity, end-user category, and operational technology sophistication. CAGRs derived from capacity expansion pipelines and contract duration trends. Industry-specific forecast inputs incorporated salt cavern leaching lead times and EPA regulatory enforcement trajectories.
Stress conditions across steel price volatility, permitting timeline extensions, and emissions compliance cost escalation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about strategic reserve buildout pacing and automation adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
North America Drilling Completion Fluids Market
Oil & Gas
Smart Pipeline Pigging Market
Oil & Gas
Iran Oil and Gas Exploration and Production Market
Oil & Gas
Oil Storage Terminal Market
Oil & Gas
Global Floating LNG Terminal Market
Oil & Gas
North America Completion Equipment and Services Market
Oil & Gas
Venezuela Oil and Gas Market
Oil & Gas
Oil and Gas Security Services Market
Oil & Gas
Oil and Gas Hose Assemblies Market
Oil & Gas
Liquefied Natural Gas Market
Oil & Gas
India Natural Gas Market
Oil & Gas
Bunker Liners Market
Oil & Gas
Vacuum Gas Oil Market
Oil & Gas
Latin America Coiled Tubing Market
Oil & Gas
Asia-Pacific Oilfield Chemicals Market
Oil & Gas
Europe Well Intervention Market