
 Brazil Oil and Gas Midstream Market | 2026-2036
Brazil Oil and Gas Midstream Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Oil and Gas Midstream Market Outlook
Refinery offtake patterns is restructuring logistics contracting across Brazil's midstream sector. Petroleo Brasileiro SA leverages its integrated Santos Basin-to-coast pipeline network to dominate crude evacuation routes. Transportadora Brasileira Gasoduto Bolívia-Brasil S A anchors the Bolivia-Brazil natural gas corridor, sustaining cross-border flow reliability. Vopak competes through specialized liquid storage terminals at strategic port locations.
Brazil oil and gas midstream encompasses the transportation, storage, and processing infrastructure bridging upstream production with downstream refining and distribution, operating through pipelines typically rated at 100-144 bar pressure, cryogenic storage at minus 162 degrees Celsius for LNG, and gas processing units removing carbon dioxide and hydrogen sulfide to meet pipeline specifications. Pipelines and storage facilities command the largest capital allocation, with terminals capturing premium margins from import-export arbitrage. Gas processing technology is expanding fastest as pre-salt associated gas volumes rise, while monitoring systems and automation segments attract investment from ANP-mandated leak detection requirements.
ANP, the Brazilian Institute of Environment and Renewable Natural Resources (IBAMA), and the National Petroleum Agency's pipeline integrity standards shape project permitting, environmental licensing timelines, and operational safety baselines for all new midstream investments. ANP Resolution 52/2015 and subsequent amendments enforce mandatory inline inspection programs and pressure testing protocols that directly determine maintenance spending levels and equipment replacement cycles. Stakeholders must weigh pre-salt production ramp schedules against regulatory compliance deadlines when sizing infrastructure commitments.
Market Dynamics
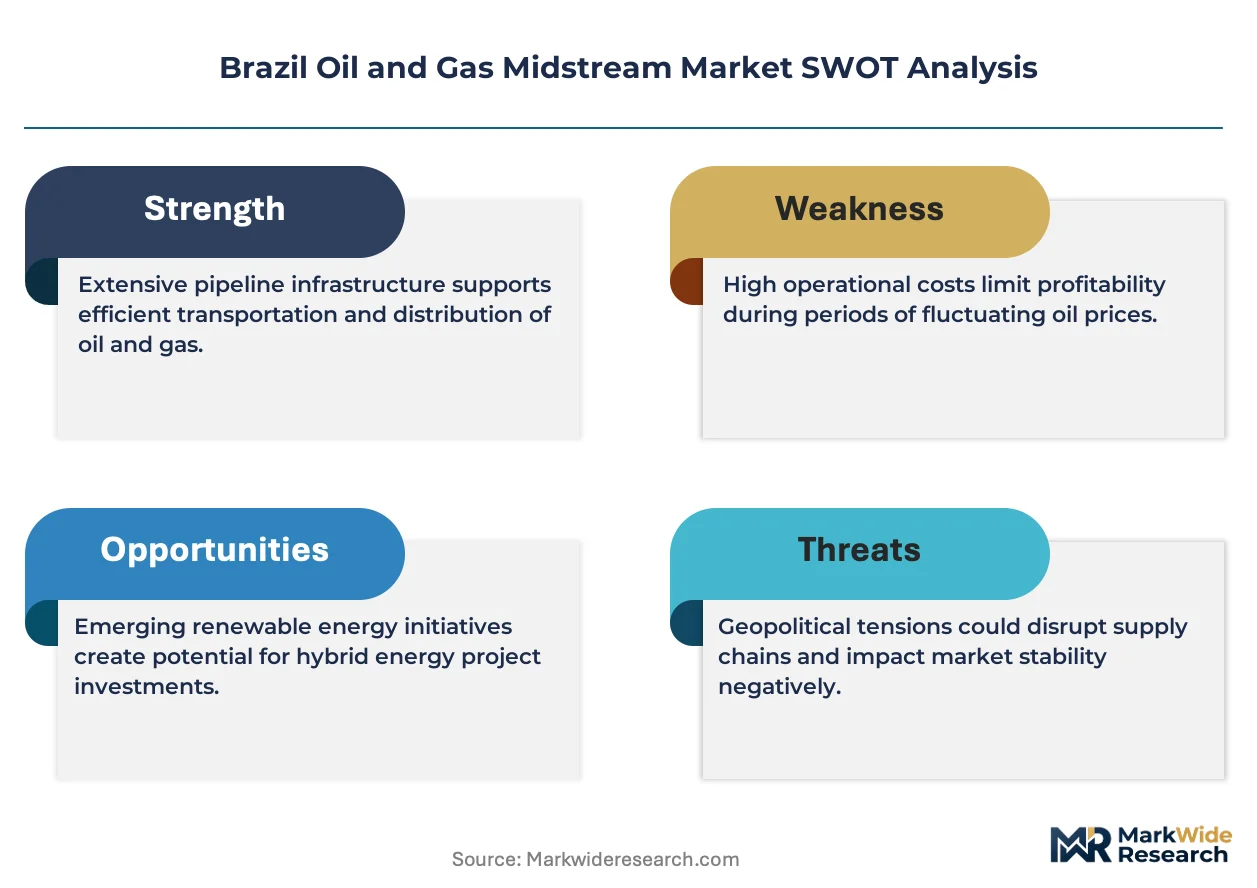
ANP's pipeline integrity mandates are forcing wholesale infrastructure replacement across Brazil's midstream network, compressing maintenance cycles and redirecting capital toward monitoring systems.
Growth Catalysts
- Pre-salt associated gas volumes:Rising production from the Santos Basin is pulling investment into gas processing capacity and cryogenic storage infrastructure.
- ANP Resolution 52/2015:Mandatory inline inspection programs are creating sustained demand for smart pigging services and pressure testing equipment.
- Southeast refinery restructuring:Petrobras's throughput reconfiguration is reshaping crude logistics contracting and terminal utilization patterns.
Market Restraints
- Steel input volatility:Pipeline grade steel price swings compress project margins and delay final investment decisions on greenfield routes.
- IBAMA licensing timelines:Environmental approval delays for coastal terminals extend project gestation periods by 18-36 months.
- Import dependency for specialized compressors:Cryogenic and high-pressure equipment sourcing concentrates on US and European suppliers, exposing operators to currency and lead-time risk.
Strategic Opportunities
- Northeast LNG regasification gap:Underdeveloped import infrastructure in Pernambuco and Ceará offers first-mover terminal development positions.
- Biomethane injection standards:ANP's draft regulations for renewable natural gas blending create offtake pathways for agricultural waste-to-gas projects.
- Digital twin convergence:Integration of SCADA systems with predictive analytics platforms is expanding into integrity management and leak detection workflows.
Industry Challenges
- Specialized welding certification scarcity:Qualified technicians for high-pressure pipeline construction remain concentrated in Rio de Janeiro and São Paulo, constraining nationwide buildout speed.
- Legacy pipeline integration:Retrofitting 1970s-era Santos Basin trunk lines with modern monitoring hardware requires custom engineering and extended shutdown windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Oil and Gas Midstream Market |
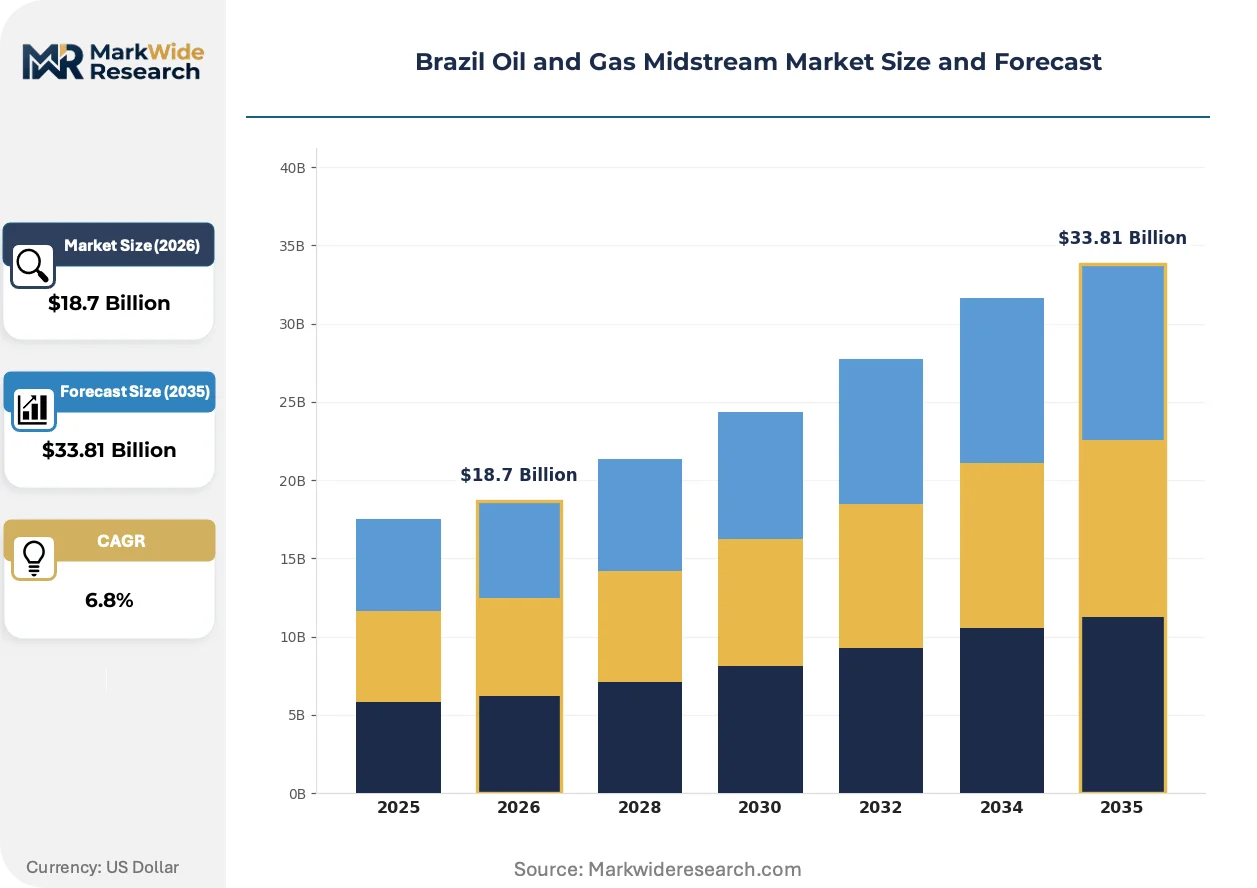
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pipelines, Storage Facilities, Terminals, Compressors Technology: Gas Processing, Liquid Transportation, Monitoring Systems, Automation End User: Refineries, Power Plants, Industrial Users, Distributors Service Type: Transportation, Storage, Maintenance, Construction |
| Companies Covered | Transportadora Brasileira Gasoduto Bolívia-Brasil S A, Kanfer Shipping AS, Petroleo Brasileiro SA, Vopak, Nimofast Brasil S A, Total SA, Gas TransBoliviano SA, Rumo Logística, Engie SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Oil and Gas Midstream Market Strategic Shifts
Automation and predictive maintenance systems are displacing scheduled inspection regimes across Brazil's pipeline network, while regulatory pressure accelerates the retirement of manual monitoring protocols.
Advanced pipeline monitoring systems combining fiber-optic sensing with satellite leak detection are expanding into the pre-salt evacuation corridors where subsea tiebacks complicate physical inspection access. Offshore operators are adopting these platforms fastest, driven by ANP-mandated response-time requirements for subsea releases. The technology is expanding into onshore gathering systems as marginal field developers seek to avoid manned station costs.
ANP's 2023 amendments to pipeline integrity standards are compressing reinspection intervals for high-consequence areas, forcing operators to reallocate maintenance budgets toward inline inspection tool deployment. The regulation is reshaping service contractor priorities, with diagnostic providers expanding Brazilian fleet capacity to capture recurring revenue streams. Coastal processing corridors face the tightest compliance deadlines, concentrating near-term investment in Rio de Janeiro state infrastructure.
Refinery procurement patterns are consolidating logistics contracts around integrated terminal-to-pipeline bundles, displacing spot-based trucking arrangements for coastal crude movements. Downstream buyers are negotiating throughput guarantees with midstream operators, transferring volume risk upstream in exchange for price certainty. This restructuring is most visible in the Southeast, where Petrobras's divestment program is opening contracted capacity to independent traders.
Brazil Oil and Gas Midstream Market Segmentation
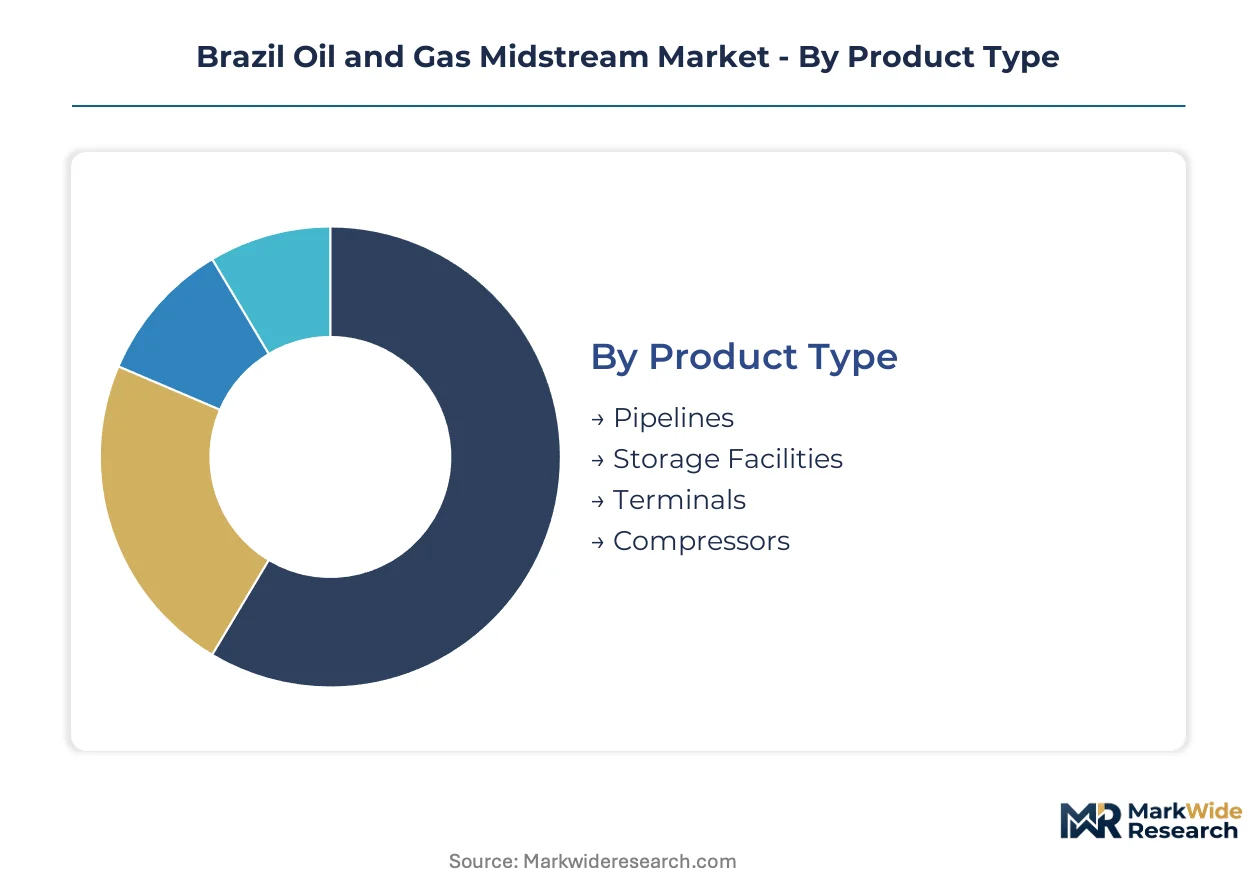
Brazil's midstream infrastructure spans four critical dimensions that determine capital allocation and regulatory exposure. Each segmentation axis reveals distinct growth trajectories tied to pre-salt production economics and ANP compliance mandates. Understanding these layers clarifies where infrastructure investment concentrates versus where service margins compress.
Product Type:
Pressure ratings and throughput capacity differentiate hardware deployment across Brazil's coastal and interior corridors.
- Pipelines:Trunk lines rated 100-144 bar dominate crude evacuation from Santos Basin pre-salt fields to coastal refineries. ANP Resolution 52/2015 mandates are accelerating smart pigging retrofit cycles on aging Santos Basin routes.
- Storage Facilities:Cryogenic tanks operating at minus 162 degrees Celsius anchor LNG import terminals in Rio de Janeiro and Bahia states. Floating storage regasification units are expanding fastest as Pernambuco and Ceará seek import diversification.
- Terminals:Liquid bulk terminals at strategic port locations capture arbitrage margins from import-export flows. Coastal processing corridors in Rio de Janeiro state concentrate utilization.
- Compressors:High-pressure gas compression units sustain flow rates across Bolivia-Brazil corridor and pre-salt gathering systems. Specialized cryogenic and high-pressure equipment sourcing concentrates on US and European suppliers.
Mature deployment sits with pipelines. Newer deployment is concentrated in storage facilities.
Technology:
Functional sophistication separates maintenance-intensive legacy systems from digitally integrated platforms.
- Gas Processing:Carbon dioxide and hydrogen sulfide removal units condition pre-salt associated gas for pipeline specifications. Santos Basin production ramp schedules are pulling investment into new capacity.
- Liquid Transportation:Multiphase pumping and slug handling systems manage subsea tieback complexity. Deepwater pre-salt clusters drive specification requirements.
- Monitoring Systems:Fiber-optic sensing combined with satellite leak detection expands where subsea tiebacks complicate physical inspection. ANP-mandated response-time requirements for subsea releases accelerate offshore adoption fastest.
- Automation:SCADA integration with predictive analytics platforms displaces scheduled inspection regimes. Digital twin convergence into integrity management workflows represents expanding investment.
Established infrastructure relies on liquid transportation. Automation platforms are gaining share fastest.
End User:
Volume certainty and contract duration shape midstream operator risk allocation.
- Refineries:Petrobras throughput reconfiguration in the Southeast is restructuring crude logistics contracting and terminal utilization patterns. Integrated terminal-to-pipeline bundles displace spot trucking.
- Power Plants:Natural gas-fired generation units depend on Bolivia-Brazil corridor reliability and coastal LNG regasification capacity. Thermoelectric dispatch patterns influence seasonal storage draws.
- Industrial Users:Petrochemical complexes and fertilizer plants anchor steady offtake from gas processing networks. São Paulo state industrial clusters concentrate demand.
- Distributors:Local gas distribution companies source from processing terminals and pipeline interconnections. ANP biomethane injection standards are creating renewable natural gas offtake pathways.
Refineries anchor contracted capacity. Distributor segment is expanding most quickly on biomethane regulation.
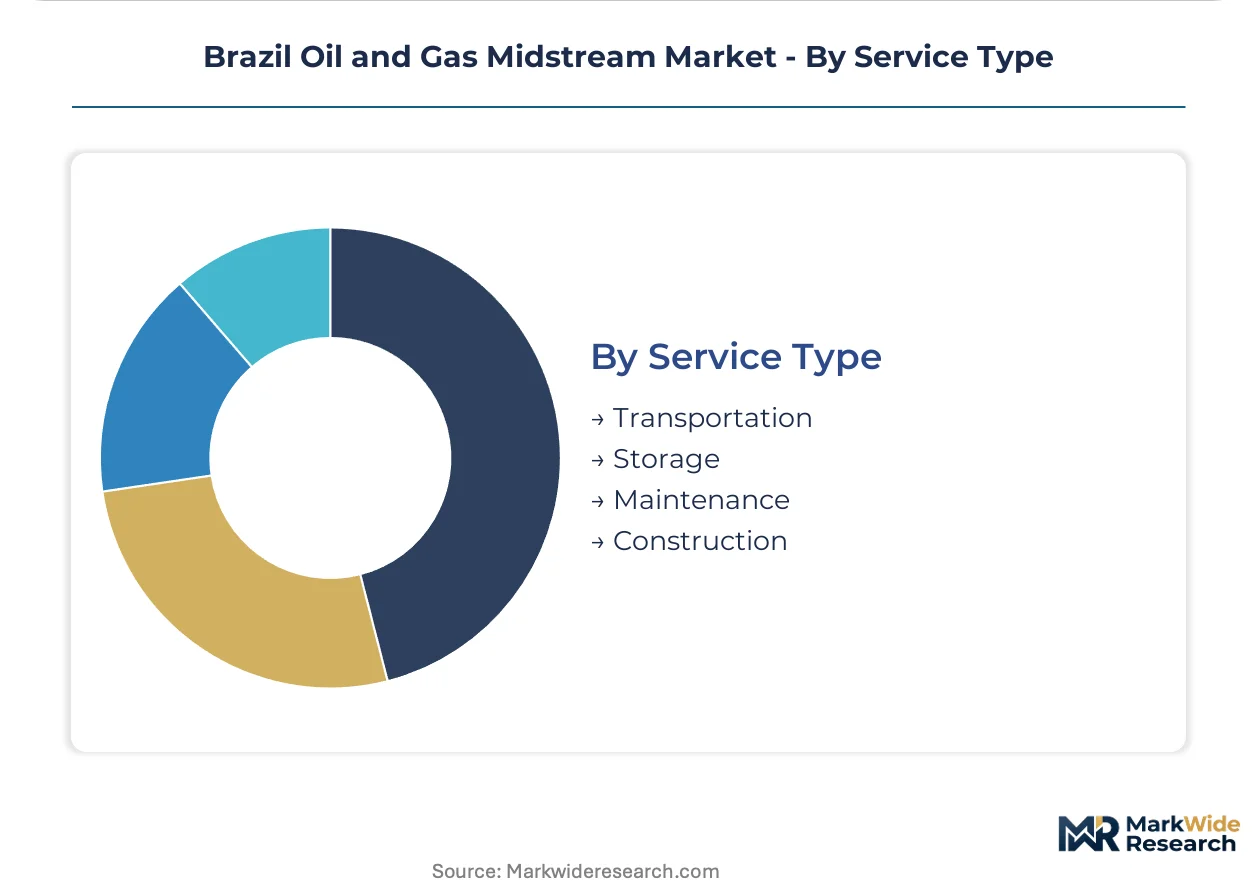
Service Type:
Revenue predictability divides transactional maintenance from long-term infrastructure commitments.
- Transportation:Tariff-regulated pipeline throughput contracts transfer volume risk to shippers. Petrobras divestment program is opening contracted capacity to independent traders.
- Storage:Terminal throughput guarantees negotiated with downstream buyers exchange price certainty for volume commitments. Coastal import-export arbitrage captures premium margins.
- Maintenance:Inline inspection tool deployment and pressure testing protocols dominate spending under ANP integrity mandates. Service contractors are expanding Brazilian fleet capacity.
- Construction:Greenfield pipeline and terminal development faces IBAMA licensing timelines extending 18-36 months. Steel input volatility compresses project margins.
Transportation services represent mature revenue streams. Maintenance services are climbing the fastest on regulatory compliance cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's midstream infrastructure concentrates in states bridging pre-salt production basins with coastal processing and export terminals. ANP regulations and Petrobras investment patterns determine regional capital flows across five critical states.
São Paulo
Industrial gas demand from petrochemical complexes and fertilizer plants drives pipeline interconnection investments. ANP biomethane injection standards are creating renewable natural gas offtake pathways for agricultural waste-to-gas projects. The São Paulo state industrial corridor anchors steady processing demand from distributors.
Rio de Janeiro
Pre-salt crude evacuation and coastal LNG regasification dominate infrastructure deployment. ANP Resolution 52/2015 mandates are compressing reinspection intervals for high-consequence areas, forcing maintenance budget reallocation. The coastal processing corridor faces the tightest compliance deadlines, concentrating near-term investment in terminal and pipeline integrity systems.
Minas Gerais
Interior pipeline routes connect southeastern production basins with midwestern refining capacity. IBAMA licensing timelines for greenfield development extend project gestation periods. The Belo Horizonte industrial cluster sustains demand for gas processing and distribution infrastructure.
Bahia
LNG import terminal operations and onshore storage capacity expansion attract capital allocation. The National Petroleum Agency's pipeline integrity standards shape operational safety baselines for new investments. The Salvador metropolitan area anchors cryogenic storage deployment for coastal import diversification.
Rio Grande do Sul
Southern border logistics and Uruguay River corridor development present strategic positioning opportunities. Steel input volatility for pipeline grade materials compresses project margins in this expansion zone. The Porto Alegre industrial basin sustains regional distribution network demand.
Brazil Oil and Gas Midstream Market Competitive Environment
Top-tier vendors anchor integrated infrastructure positions, while mid-tier operators compete on specialized service segments. State-affiliated energy groups dominate trunk line ownership through historical concession structures. Three archetypes define competitive positioning: integrated national oil companies controlling basin-to-coast corridors, international terminal operators capturing import-export arbitrage, and regional logistics specialists serving niche geographic segments. Dominant competitive moves include portfolio diversification into adjacent storage and processing assets, and strategic partnerships to secure long-term throughput contracts.
Among Brazil-based integrated operators, Petroleo Brasileiro SA and Transportadora Brasileira Gasoduto Bolívia-Brasil S A occupy positions spanning pipeline ownership and cross-border corridor management. Vopak represents the international terminal operator archetype, anchoring specialized liquid storage positions at strategic port locations. These three entities exemplify the tiered structure where scale advantages in infrastructure ownership create durable competitive positioning.
| Leading Market Players |
|---|
| Transportadora Brasileira Gasoduto Bolívia-Brasil S A |
| Kanfer Shipping AS |
| Petroleo Brasileiro SA |
| Vopak |
| Nimofast Brasil S A |
| Total SA |
| Gas TransBoliviano SA |
| Rumo Logística |
| Engie SA |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed pipeline operators anchor Brazil's midstream financing structure, concentrating supply procurement around Petrobras-directed capex cycles and compressing third-party contractor pricing power during budget recalibrations. ANP-mandated integrity spending creates inelastic demand pockets where specialized service providers command premium positioning.
Pricing Analysis
Margin tightening in maintenance services reflects ANP Resolution 52/2015 inspection frequency compression and qualified technician scarcity concentrated in Rio de Janeiro. Contract-based long-term offtake agreements dominate crude transportation, with tariff-regulated pipeline contracts transferring volume risk to shippers. Price differentiation rests on certification grade for high-pressure welding and geographic delivery cost to coastal terminals. Petrobras procurement consolidation intensifies pricing pressure on independent logistics contractors.
Supply Chain Analysis
Direct-to-refinery channels handle hyperscale crude movements, while specialized equipment flows through distributor networks serving marginal field developers. Pipeline-grade steel sourcing concentrates in China, South Korea, and Germany, with cryogenic compressors and smart pigging tools drawing from US and European suppliers. Supply chain risk centers on single-source vulnerability for subsea tieback components. Distribution runs through integrated terminal-to-pipeline bundles displacing spot trucking arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANP regulatory compliance deadlines are forcing capital-constrained operators toward asset sales, consolidating viable infrastructure positions around scaled players with balance sheet capacity for integrity investment cycles.
For Market Incumbents: Acquire stranded gas processing capacity in the Santos Basin corridor to capture pre-salt associated gas volume growth. Lock in long-term throughput guarantees with Petrobras divestment program participants before independent traders consolidate contracted positions. ANP biomethane injection standards threaten legacy gas processing margins without renewable natural gas blending retrofit investment. For New Entrants and Emerging Players: Specialized diagnostic contractors represent the most penetrable service segment, with ANP-mandated smart pigging deployment outpacing Brazilian fleet capacity expansion. Target first-mover LNG regasification terminal positions in Pernambuco and Ceará where import infrastructure remains underdeveloped. Partner with agricultural waste-to-gas project developers to secure biomethane offtake contracts ahead of ANP final regulations. For Investors and Strategic Acquirers: Distressed-cycle entries favor midstream maintenance specialists with ANP-certified inspection capabilities in Rio de Janeiro state. Five-to-ten year viability hinges on pre-salt production ramp schedules aligning with infrastructure replacement timelines. Watch Petrobras divestment program acceleration as the inflection signal for contracted capacity reallocation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Pipeline Integrity Retrofit Program | ANP Resolution 52/2015 mandates accelerate smart pigging deployment across aging Santos Basin trunk lines. |
| Biomethane Injection Infrastructure | ANP draft regulations create renewable natural gas blending pathways for agricultural waste-to-gas projects. |
| Northeast LNG Terminal Development | Pernambuco and Ceará import diversification gaps offer first-mover regasification capacity positions. |
| Digital Twin Integration | SCADA-predictive analytics convergence expands into leak detection workflows for subsea tieback monitoring. |
| Cross-Border Corridor Expansion | Bolivia-Brazil gas pipeline reliability investments sustain thermoelectric dispatch patterns for power plant offtake. |
Study Parameters
Document review covered ANP regulatory filings, Petrobras annual sustainability reports, and IBAMA environmental licensing databases, complemented by interviews with pipeline integrity managers, EPC contractors, and gas processing unit operators. Secondary validation drew from ANP production statistics, Brazilian customs trade records, and energy infrastructure project tracking services. Bottom-up segment sizing triangulated against top-down macroeconomic energy demand projections.
Segment-level outputs across product type, technology, end user, and service type dimensions were modeled using infrastructure replacement cycle schedules and pre-salt production ramp assumptions. CAGRs were derived from capital expenditure pipeline analysis and regulatory compliance spending trajectories. Forecast inputs incorporated ANP inspection interval amendments and Petrobras divestment program timelines without binding to specific calendar years.
Several conditions sit outside the modeled scope, including unannounced ANP regulatory amendments, IBAMA licensing timeline extensions beyond historical ranges, and Petrobras strategic redirection on midstream asset retention. Forecasts reflect assumptions about sovereign energy policy continuity and steel input price stabilization. Periodic stress-testing of base assumptions against pre-salt production variance and currency fluctuation scenarios is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
North America Fracking Chemicals Market
Oil & Gas
Offshore Oil and Gas Paints and Coatings Market
Oil & Gas
Coal Seam Gas Market
Oil & Gas
Oil Tank Rotating Stacker Market
Oil & Gas
Africa Drilling and Completion Fluids Market
Oil & Gas
United Kingdom Oil and Gas Midstream Market
Oil & Gas
Hydraulic Workover Units Market
Oil & Gas
Egypt Oil and Gas Market
Oil & Gas
Hydraulic Fracturing Market
Oil & Gas
United States Oil and Gas Separation Market
Oil & Gas
Downhole Tractor Market
Oil & Gas
Shale Gas Hydraulic Fracturing Market
Oil & Gas
Unconventional Gas Market
Oil & Gas
Flare Gas Recovery System Market
Oil & Gas
North America Oil Storage Market
Oil & Gas
North America Completion Equipment and Services Market