
 Crude Oil Desalter and Electrostatic Dehydrator Market | 2026-2036
Crude Oil Desalter and Electrostatic Dehydrator Market Size, Share, and Industry Trends Forecast 2026-2036
Crude Oil Desalter and Electrostatic Dehydrator Market Outlook
The gap between API-certified premium desalters and commodity electrostatic units is repositioning procurement criteria across upstream and downstream buyers. Forum Energy Technologies leverages its North American manufacturing footprint to anchor supply for shale operators requiring rapid deployment. Alfa Laval differentiates through plate-pack technology integration that reduces vessel footprint for offshore platforms. Schlumberger dominates digital monitoring add-ons that extend service revenue beyond hardware sales.
Crude oil desalters and electrostatic dehydrators are pressure vessels that use electrostatic grids, chemical demulsifiers, and temperature control to reduce water and salt content below refinery feedstock specifications, typically achieving less than 0.5% basic sediment and water. Electrostatic technology leads installed capacity globally due to superior efficiency on heavy and medium crude grades, while mechanical separation retains share in remote locations with unreliable power supply. Refineries represent the most mature end-user segment with predictable replacement cycles, whereas oil and gas producers in unconventional basins drive faster growth through greenfield pad installations requiring compact, modular units.
EPA wastewater regulations under the Clean Water Act and API RP 45 separation standards shape equipment specifications and compliance timelines for US operators. Saudi Arabia's national oil company procurement standards and the EU's Industrial Emissions Directive create divergent certification requirements that fragment supplier qualification pathways. Stakeholders must monitor how carbon border adjustments and methane intensity benchmarks reshape total cost-of-ownership calculations for dehydration infrastructure investments.
Market Dynamics
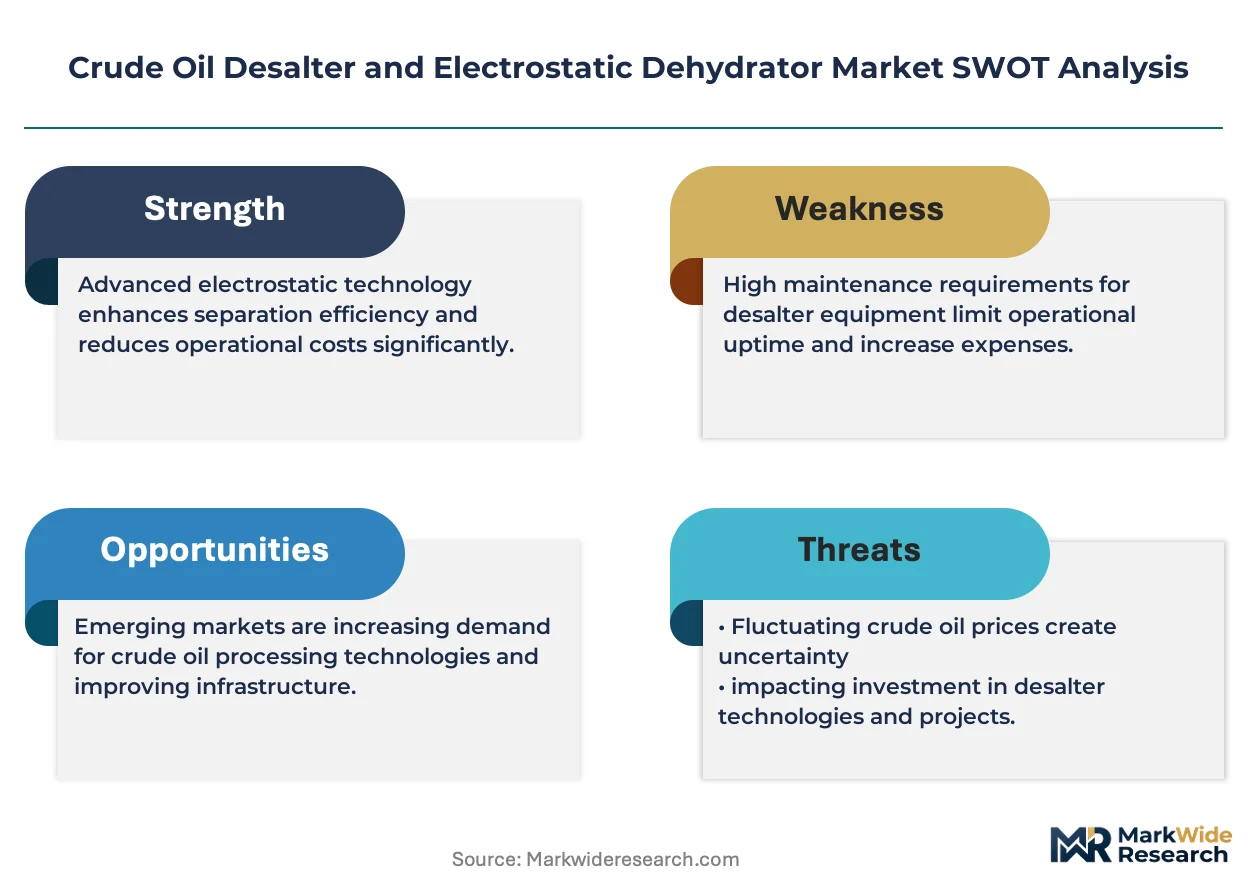
Refinery feedstock specifications are tightening globally as heavy crude processing expands, forcing electrostatic dehydration system upgrades to handle higher water cuts and salt loads in Middle Eastern and North American operations.
Growth Catalysts
- EPA Wastewater Discharge Rules:The Clean Water Act mandates force US refineries to install advanced desalting capacity, creating replacement demand across Gulf Coast processing clusters.
- Heavy Crude Processing Expansion:Saudi Aramco's megaprojects in the Middle East require large-scale electrostatic systems capable of handling deteriorating API gravity in domestic crude slates.
- API RP 45 Separation Standards:Updated emulsion treatment specifications compel upstream operators to modernize dehydration infrastructure to meet discharge compliance timelines.
Market Restraints
- High-Grade Steel Input Volatility:Pressure vessel fabrication depends on specialized corrosion-resistant alloys subject to supply chain disruptions from specialty metal producers.
- Electrostatic Grid Supplier Concentration:Premium electrode component manufacturing concentrates among a limited set of European and Japanese suppliers, creating procurement bottlenecks.
- Mechanical Separation Substitution:Centrifugal dehydrators retain cost advantage in remote locations with unreliable grid power, limiting electrostatic unit penetration in certain basins.
Strategic Opportunities
- Offshore Platform Miniaturization:Compact plate-pack electrostatic designs address space constraints on floating production vessels in Brazilian and West African deepwater developments.
- EU Industrial Emissions Directive:Carbon border adjustment mechanisms create competitive advantage for low-methane-intensity dehydration systems in European refinery procurement.
- Digital Monitoring Convergence:Integration of real-time salinity sensors with predictive maintenance platforms enables service revenue expansion beyond hardware-only sales models.
Industry Challenges
- Electrostatic Field Specialist Shortage:Commissioning and optimization of high-voltage grid systems requires expertise that outpaces vocational training program output in key producing regions.
- Legacy Vessel Retrofit Complexity:Existing mechanical separator infrastructure demands extensive piping modifications to accommodate electrostatic upgrade packages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crude Oil Desalter and Electrostatic Dehydrator Market |
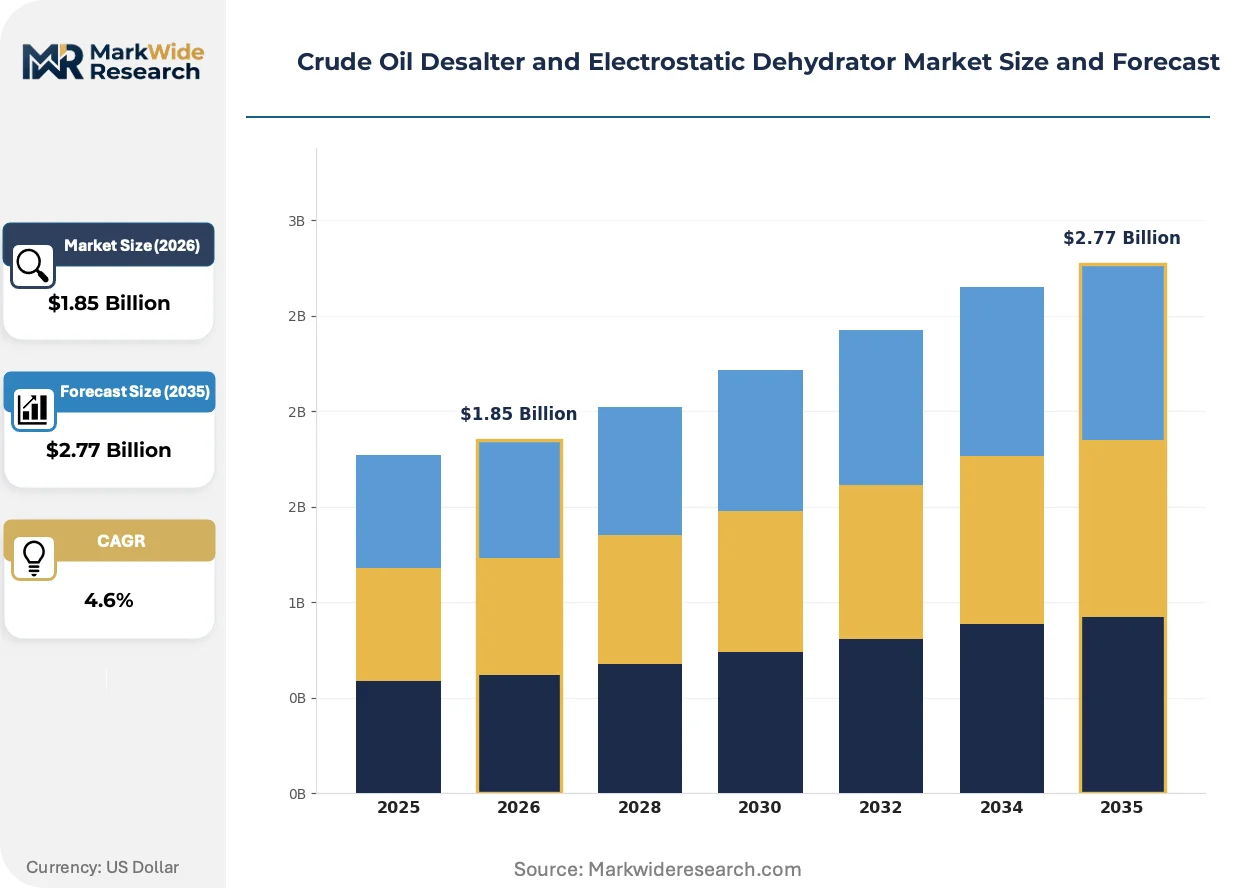
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.77 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desalters, Dehydrators, Separators, Treaters Technology: Electrostatic, Mechanical, Thermal, Chemical End User: Refineries, Petrochemical Plants, Oil & Gas Producers, Others Capacity: Small Scale, Medium Scale, Large Scale, Custom |
| Companies Covered | Forum Energy Technologies, Frames Group, Agar Corporation Ltd, Desalters LLC, AMR Process Limited, Alfa Laval, Canadian Petroleum Processing Equipment, Baker Hughes, Schlumberger, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crude Oil Desalter and Electrostatic Dehydrator Market Strategic Shifts
Electrostatic dehydration technology is advancing through materials science breakthroughs and digital integration, while regulatory pressure on water discharge quality accelerates equipment replacement cycles across mature refining bases.
AC electrostatic coalescence is overtaking traditional DC grid systems in heavy crude applications. The alternating current configuration prevents electrode fouling when processing high-asphaltene feedstocks. Canadian oil sands operators and Venezuelan heavy crude upgraders are adopting AC systems at accelerated rates. This technology is overtaking DC architectures in markets where reliability under extreme crude variability determines procurement decisions.
REACH chemical restrictions in Europe are reshaping demulsifier formulation requirements for electrostatic dehydration units. The regulation limits certain surfactant chemistries historically used in emulsion breaking. Refinery operators in Germany and the Netherlands are reformulating chemical injection protocols and demanding equipment compatibility with bio-based alternatives. This regulatory pressure most affects brownfield facilities with legacy chemical supply contracts.
Integrated service contracting is displacing traditional equipment-only procurement in offshore developments. Operators in the North Sea and Gulf of Mexico now bundle electrostatic unit supply with chemical management and performance guarantees. This model transfers operational risk to vendors while compressing capital expenditure recognition periods. The shift is most visible among independent producers lacking in-house dehydration optimization expertise.
Crude Oil Desalter and Electrostatic Dehydrator Market Segmentation
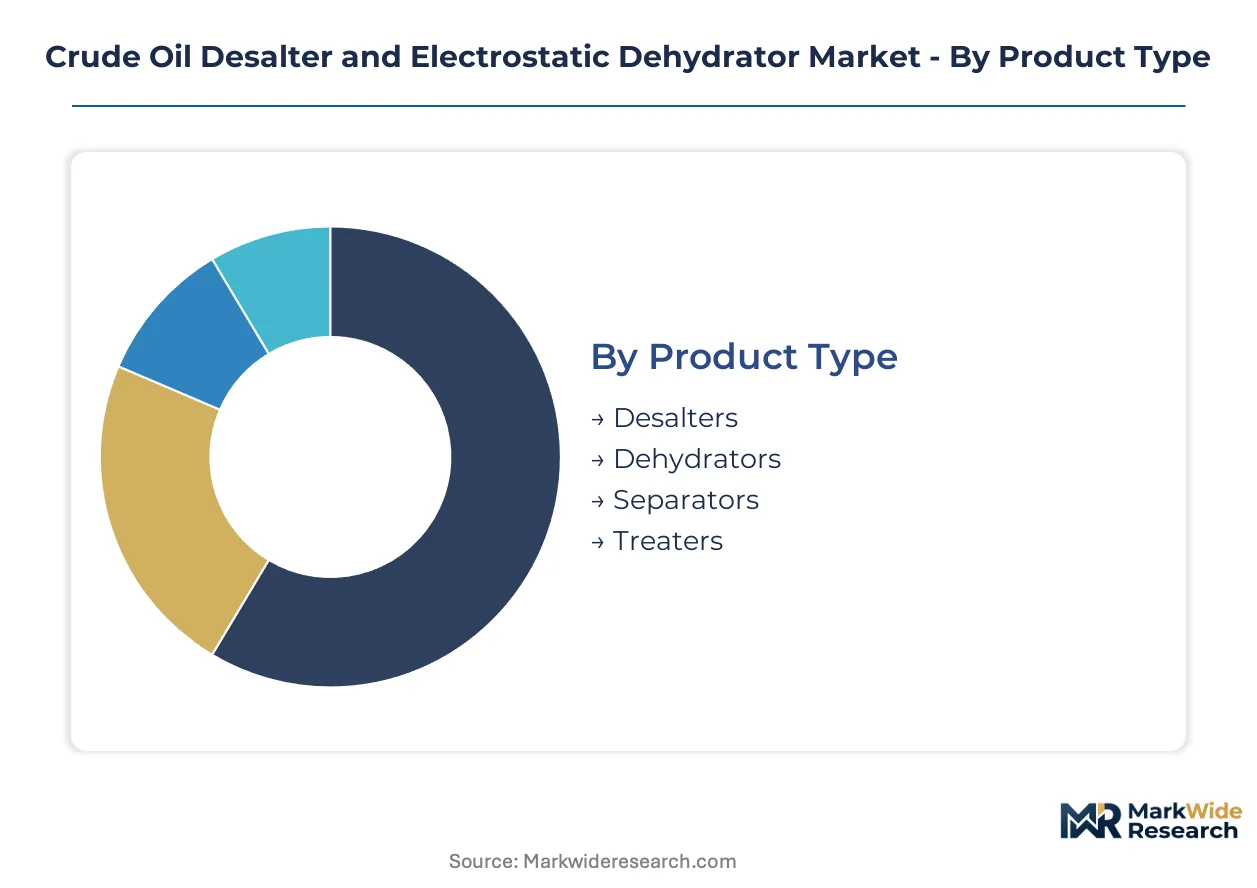
Segmentation in the crude oil desalter and electrostatic dehydrator market reveals how certification requirements, crude slate characteristics, and facility scale reshape procurement patterns across upstream and downstream operators. Equipment specifications diverge sharply between API RP 45-compliant refinery installations and modular field units serving unconventional production.
Product Type:
API RP 45 certification governs refinery-bound desalters, while offshore dehydration skids fall under ASME VIII pressure vessel standards with ABS or DNV marine approvals.
- Desalters:Two-stage electrostatic vessels reduce salt content below 10 PTB for refinery feedstock. Saudi Aramco's megaprojects in the Middle East specify API-certified units handling 500,000+ BPD throughput with automated wash water injection.
- Dehydrators:Single-stage electrostatic systems target basic sediment and water below 0.5% for pipeline specifications. Permian Basin shale operators drive demand for compact, trailer-mounted units with rapid deployment cycles.
- Separators:Gravity-based vessels without electrostatic grids serve remote locations with unreliable power supply.
- Treaters:Combined heat-electrostatic units process heavy crude with elevated pour points in Canadian oil sands operations.
Leading the category by volume: Desalters. Growing fastest: Dehydrators.
Technology:
Cost tiers separate premium electrostatic systems with real-time monitoring from commodity mechanical alternatives with minimal instrumentation.
- Electrostatic:AC coalescence grids prevent electrode fouling in high-asphaltene feedstocks. Brazilian deepwater pre-salt developments specify these units for space-constrained FPSO installations where reliability under crude variability determines procurement.
- Mechanical:Centrifugal and hydrocyclone systems operate without electrical infrastructure. West African marginal field operators favor these units where grid power remains intermittent.
- Thermal:Indirect heating reduces viscosity for heavy crude dehydration.
- Chemical:Demulsifier injection systems complement primary separation equipment.
Electrostatic systems command premium pricing. Mechanical units retain cost advantage in infrastructure-constrained basins.
End User:
Application maturity separates refineries with predictable replacement cycles from oil and gas producers with volatile greenfield demand patterns.
- Refineries:Complex desalting trains with multiple electrostatic stages handle deteriorating API gravity in domestic crude slates. US Gulf Coast facilities face EPA-mandated upgrades under Clean Water Act discharge rules.
- Oil & Gas Producers:Pad-mounted modular units serve unconventional wells with high initial water cuts. North Dakota Bakken operators cycle equipment between drilling sites based on production decline curves.
- Petrochemical Plants:Naphtha feedstock pretreatment requires specialized desalting.
- Others:Pipeline terminals and storage facilities maintain minimal dehydration capacity.
Refineries anchor replacement demand. Oil and gas producers generate fastest expansion in unit installations.
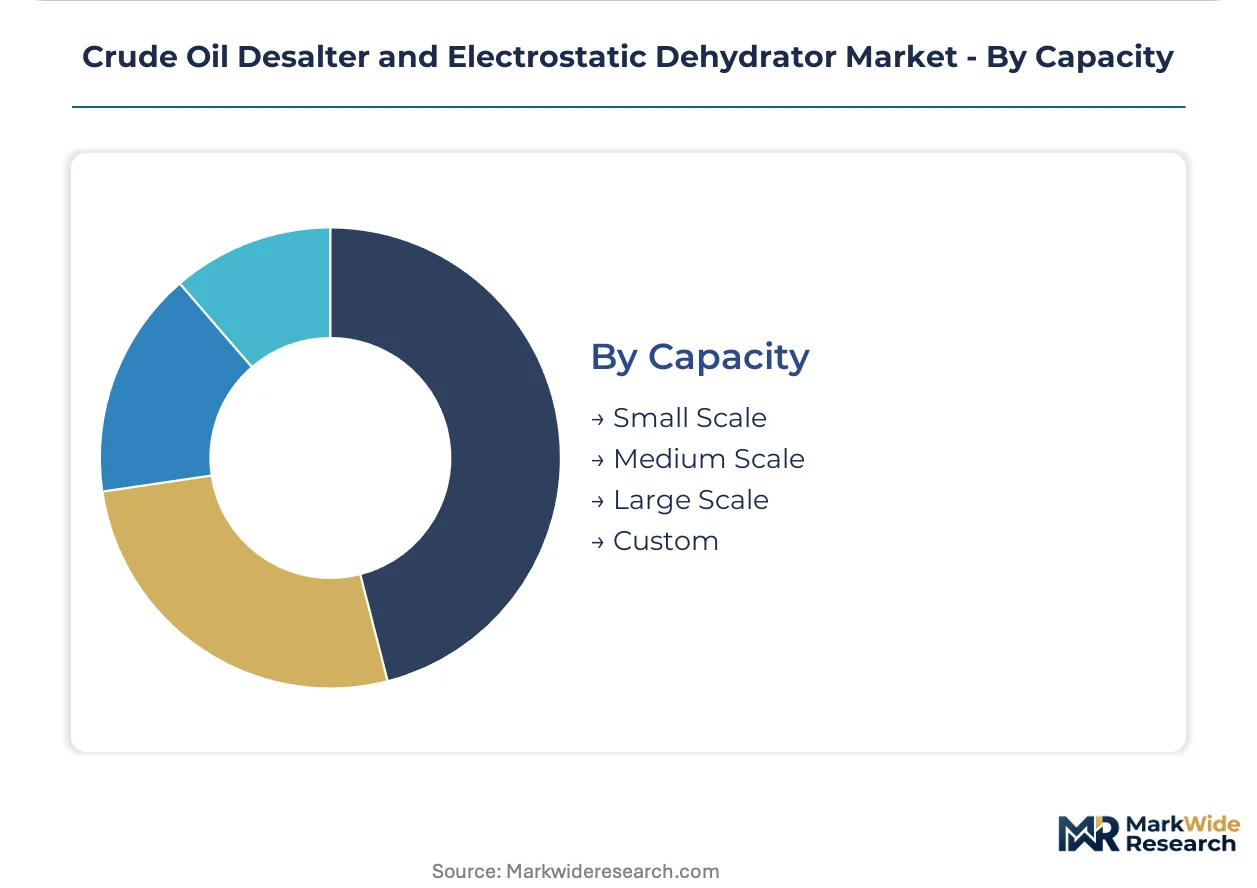
Capacity:
Customer type determines scale economics, with integrated majors specifying custom vessels while independents procure standardized skid packages.
- Large Scale:Field-erected vessels exceeding 20 feet diameter serve Saudi Arabia's Jafurah gas development and similar megaprojects. These units require extended lead times from specialized pressure vessel fabricators.
- Custom:Engineered-to-order systems address unique crude characteristics or space constraints. North Sea platform retrofits demand these configurations to accommodate legacy infrastructure footprints.
- Medium Scale:Shop-fabricated vessels balance throughput with transportability.
- Small Scale:Containerized units serve pilot testing and marginal well applications.
Large scale units dominate capital expenditure. Custom configurations expand most quickly in offshore redevelopment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jubail Industrial City anchors the world's most concentrated desalter procurement activity, with Saudi Aramco's megaprojects driving demand for vessels exceeding 500,000 BPD throughput capacity. Refinery clusters across the United States, Germany, China, Brazil, and the United Arab Emirates follow distinct regulatory and crude slate pressures that reshape equipment specifications.
United States
Gulf Coast refineries face replacement cycles triggered by EPA Clean Water Act discharge mandates. The Texas-Louisiana corridor hosts the densest cluster of electrostatic upgrade projects, with Houston-area fabricators supplying modular units for Permian Basin shale operators. Bakken producers in North Dakota cycle trailer-mounted dehydrators between drilling sites based on production decline curves.
Germany
REACH chemical restrictions force reformulation of demulsifier injection protocols at refineries in the Rhine-Ruhr industrial belt. The country's national chemical regulator limits surfactant chemistries historically used in emulsion breaking. Rotterdam-connected facilities in the Hamburg-Leuna corridor demand equipment compatibility with bio-based chemical alternatives.
China
State-backed refinery expansions in the Yangtze River Delta and Pearl River Delta prioritize electrostatic systems for deteriorating domestic crude quality. The Ministry of Ecology and Environment tightens wastewater discharge standards for coastal processing plants. Shandong Province's independent refineries drive demand for cost-optimized desalting trains with automated wash water injection.
Brazil
Pre-salt deepwater developments specify AC electrostatic coalescence grids for space-constrained FPSO installations. The national petroleum regulator mandates separation performance guarantees for floating production vessels in the Santos Basin. Rio de Janeiro-based engineering firms bundle equipment supply with chemical management contracts.
United Arab Emirates
ADNOC's downstream expansion in Ruwais and Fujairah requires large-scale desalting capacity for heavy crude processing. The federal environmental authority aligns discharge standards with tightening regional benchmarks. Dubai-based procurement hubs coordinate supply for offshore redevelopment projects across the Arabian Gulf.
Crude Oil Desalter and Electrostatic Dehydrator Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification grade and digital service bundling. The vendor base separates into three distinct tiers: integrated oilfield service conglomerates with full-service contracting capabilities, specialized pressure vessel fabricators focused on rapid-deployment modular units, and component suppliers dominating electrode grid manufacturing. Consolidation pressure concentrates among mid-scale fabricators lacking backward integration into specialty alloy supply. Technology licensing agreements and integrated service contracting represent the dominant competitive moves reshaping procurement relationships.
Among North American oilfield service providers, Forum Energy Technologies and Baker Hughes exemplify the integrated-service archetype combining hardware supply with chemical management. Schlumberger anchors the digital-monitoring tier through predictive maintenance platforms that extend revenue beyond equipment sales. European specialists including Alfa Laval and Frames Group occupy positions emphasizing compact vessel footprints for offshore constraints. Agar Corporation Ltd and Desalters LLC represent the independent fabricator segment serving regional operators with standardized skid packages.
| Leading Market Players |
|---|
| Forum Energy Technologies |
| Frames Group |
| Agar Corporation Ltd |
| Desalters LLC |
| AMR Process Limited |
| Alfa Laval |
| Canadian Petroleum Processing Equipment |
| Baker Hughes |
| Schlumberger |
| Others |
Value Chain & Pricing Dynamics
Integrated majors in Saudi Arabia and the US Gulf Coast anchor procurement volume and enforce performance-based contracting that ties vendor payments to salt removal efficiency and uptime guarantees. This buyer concentration shifts pricing power toward operators capable of documenting API RP 45 compliance and field-proven reliability across heavy crude slates.
Pricing Analysis
Value-based pricing anchored to dehydration efficiency metrics dominates large-scale refinery contracts, with Saudi Aramco megaprojects specifying payment structures tied to PTB reduction performance. Three-tier pricing structure across premium, standard, and economy levels separates API-certified desalters from commodity electrostatic units and basic mechanical separators. Pricing pressure stems from commodity-grade electrostatic grid oversupply among Asian fabricators. Independent shale operators in the Permian Basin exhibit highest price sensitivity, while Middle Eastern NOCs prioritize performance guarantees over unit cost.
Supply Chain Analysis
Refurbishment flows for high-voltage electrode grids create secondary supply channels that extend component lifecycles and moderate new-manufacturing demand peaks. Fabrication concentrates in the United States, Germany, and Japan, with specialized pressure vessel shops in Houston, Dortmund, and Yokohama serving regional clusters. Production draws from corrosion-resistant alloy feedstock sourced from European and Japanese specialty metal producers. Single-source vulnerability concentrates in premium electrostatic grid manufacturing among limited European and Japanese suppliers. Distribution runs through EPC contractors and direct OEM relationships with national oil companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where EPA Clean Water Act discharge mandates and API RP 45 certification requirements erect barrier-to-entry moats favoring incumbents with documented regulatory track records and established qualification pathways.
For Market Incumbents: Deploy integrated service contracting bundling equipment supply with chemical management and performance guarantees to lock out modular competitors. Deepen backward integration into specialty alloy supply to insulate margin pressure from nickel and chromium price volatility. Counter centrifugal dehydrator substitution in remote basins by offering solar-compatible electrostatic skids with battery backup systems. For New Entrants and Emerging Players: EPA wastewater discharge rules in the United States open a window for rapid-deployment modular desalters serving Gulf Coast refineries facing compressed compliance timelines. Target trailer-mounted electrostatic units for Permian Basin shale operators cycling equipment between drilling sites. Pursue qualification partnerships with established pressure vessel fabricators to bypass API certification delays. For Investors and Strategic Acquirers: The window for entry favors electrostatic grid technology specialists with proprietary AC coalescence architectures and digital monitoring platforms. Mid-cap fabricators lacking backward integration into electrode manufacturing represent consolidation targets as margin compression intensifies. Monitor Saudi Aramco procurement award announcements and EPA enforcement action timelines as inflection indicators for capacity expansion decisions.| Strategic Initiative | Industry Significance |
|---|---|
| AC Electrostatic Coalescence Licensing | Canadian oil sands operators and Brazilian FPSO developers seek electrode fouling resistance for heavy crude variability. |
| Integrated Service Contracting | North Sea and Gulf of Mexico independents transfer operational risk to vendors through bundled chemical management agreements. |
| Specialty Alloy Backward Integration | Pressure vessel fabricators secure captive supply of corrosion-resistant materials against nickel price volatility. |
| Digital Monitoring Platform Convergence | Real-time salinity sensors with predictive maintenance extend Schlumberger and Baker Hughes revenue beyond hardware sales. |
| Offshore Platform Miniaturization | Compact plate-pack designs from Alfa Laval address space constraints on Brazilian pre-salt and West African deepwater FPSOs. |
Study Parameters
Trade publications, regulatory filings with EPA and API, and pressure vessel certification databases formed the secondary backbone of this analysis. Primary interviews with refinery process engineers, electrostatic grid commissioning specialists, EPC procurement managers, and aftermarket service directors validated equipment specification trends and replacement cycle timing. Bottom-up and top-down triangulation cross-checked unit installation counts against capital expenditure disclosures from Saudi Aramco, ADNOC, and US Gulf Coast operators.
Bottom-up modeling aggregated individual project announcements and procurement awards across the analysis window, while top-down verification tracked refinery capacity expansion and regulatory compliance deadlines. Segmentation dimensions included product type, technology architecture, end-user vertical, and capacity tier. CAGRs derived from installed base growth rates and replacement demand curves. Forecast inputs incorporated crude slate gravity deterioration trajectories and EPA enforcement probability assessments.
The model assumes a particular technology adoption path; alternative pathways for mechanical centrifugal separation in power-constrained basins would alter the outlook. Forecasts reflect assumptions about Saudi Aramco megaproject timelines and REACH chemical restriction implementation pace. Practitioners should monitor EPA consent decree announcements and electrode grid supplier capacity utilization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Well Completion Market
Oil & Gas
Casing Centralizer Market
Oil & Gas
Qatar Oil and Gas Market
Oil & Gas
Operational Digital Oilfield Solution Market
Oil & Gas
North America Artificial Lift Systems Market
Oil & Gas
Oman Oil and Gas Upstream Market
Oil & Gas
Malaysia Oil and Gas Pipeline Market
Oil & Gas
Denmark Oil and Gas Midstream Market
Oil & Gas
Oil and Gas Nuclear Magnetic Resonance Market
Oil & Gas
Leak Detection for Oil & Gas Market
Oil & Gas
Casing and Cementation Hardware Market
Oil & Gas
Deepwater and Ultra-Deepwater Exploration and Production Market
Oil & Gas
Gulf of Mexico Oil and Gas Midstream Market
Oil & Gas
Unconventional Gas Market
Oil & Gas
LNG Bunkering Market
Oil & Gas
Oil and Gas Automation and Instrumentation Market