
 Oil Hose Market | 2026-2036
Oil Hose Market Size, Share, and Industry Trends Forecast 2026-2036
Oil Hose Market Analysis
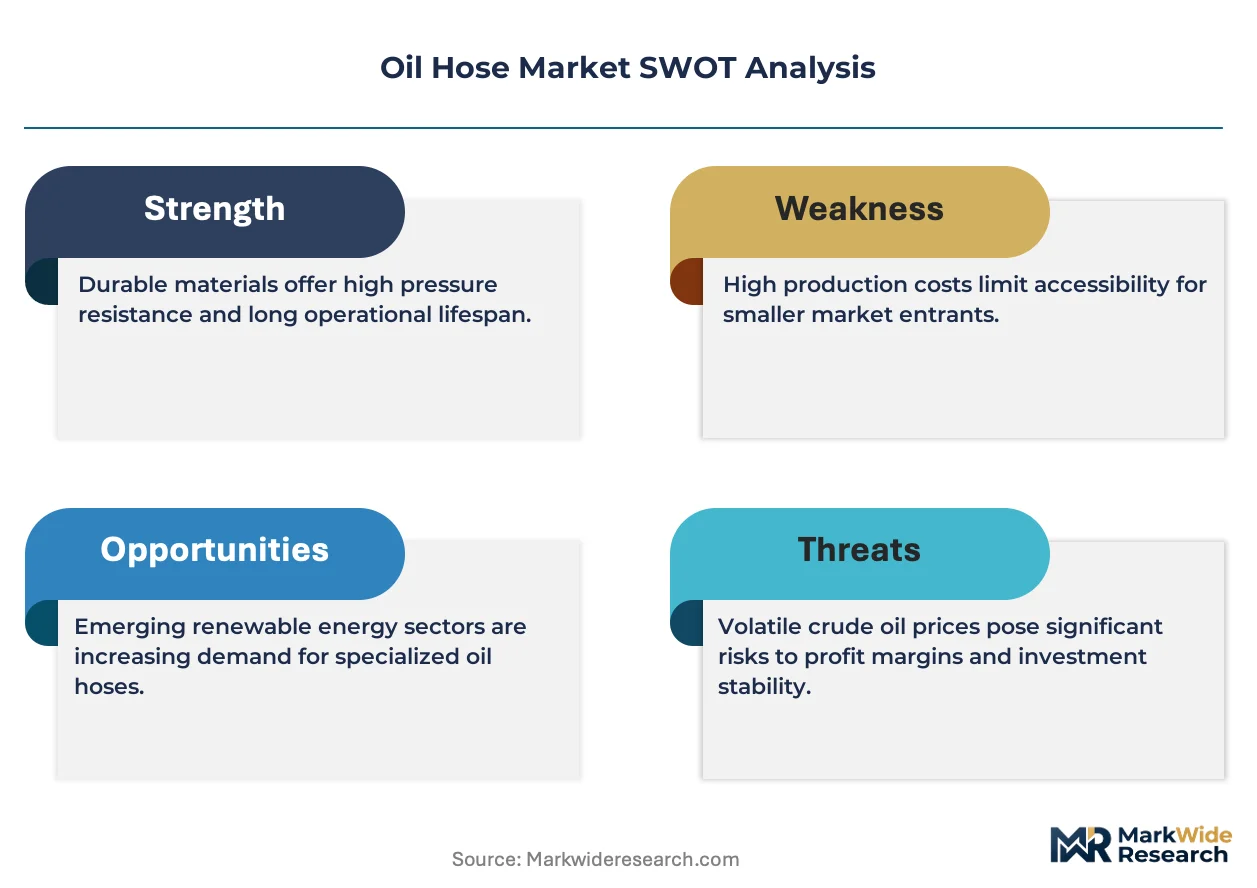
Offshore energy contractors are bifurcating procurement budgets between legacy fleet upkeep and next-generation deepwater rigs. Gates Corporation leverages backward integration into synthetic rubber compounding to control raw material quality for subsea assemblies. Parker Hannifin anchors North American distribution through dedicated oilfield service centers. Trelleborg specializes in polymer-laminated barrier technologies that extend hose fatigue life under cyclic pressure loading.
An oil hose is a flexible reinforced conduit engineered to transmit petroleum fluids, lubricants, or hydraulic media under rated pressure and temperature conditions, typically constructed from nitrile rubber inner tubes with textile or wire braid reinforcement and oil-resistant outer covers. Its primary purpose is to contain hydrocarbon flow while accommodating vibration, thermal expansion, and routing constraints in mobile and stationary equipment. Hydraulic hoses command the largest volume share within hose type segmentation due to universal deployment across construction and mining machinery. Stainless steel braided PTFE assemblies capture premium margin pools in chemical transfer and high-temperature fuel supply applications where elastomer degradation risks exclude conventional rubber constructions.
The US EPA enforces permeation thresholds under Clean Air Act mobile source provisions that disqualify non-compliant fuel dispensing hoses from retail petroleum infrastructure. MARPOL Annex VI administration through port state control regimes in Rotterdam, Singapore, and Houston mandates low-permeation bunker fuel transfer hoses for oceangoing vessels. ISO 18752 and SAE J517 standards define impulse test protocols and pressure ratings that govern product qualification for OEM hydraulic system integration. Stakeholders must monitor evolving IMO greenhouse gas strategy implementation timelines and assess capital allocation between conventional elastomer capacity and fluoropolymer barrier technology platforms.
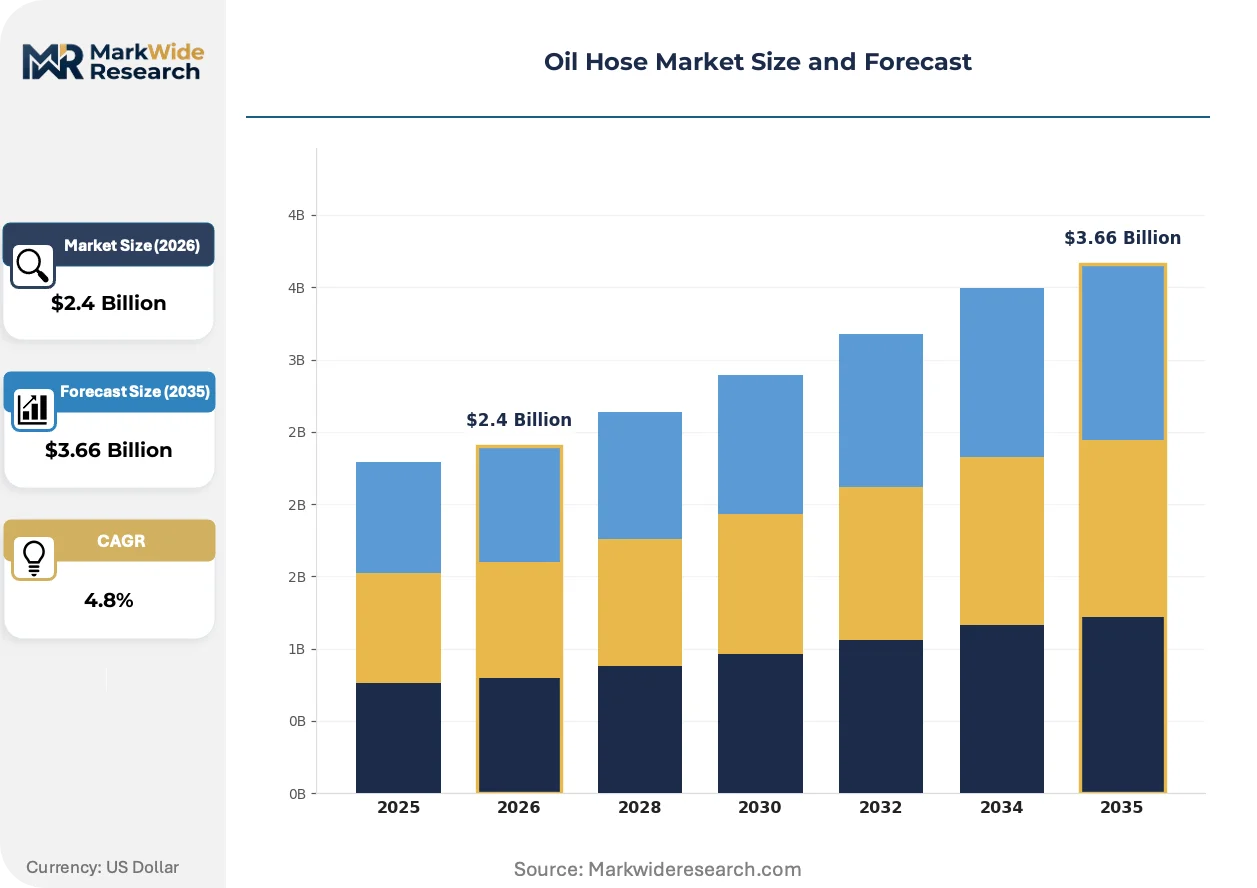
Market Dynamics
Fleet modernization among offshore drilling contractors is bifurcating procurement budgets between legacy vessel upkeep and next-generation deepwater rig construction, compressing lead times for subsea hose assemblies while elevating qualification thresholds.
Growth Catalysts
- MARPOL Annex VI port state control:Rotterdam, Singapore, and Houston authorities now mandate low-permeation bunker fuel transfer hoses, forcing fleet-wide replacement cycles that accelerate demand for barrier-layer technologies.
- Synthetic rubber compounding advances:Nitrile rubber formulations with enhanced aromatic resistance extend service intervals in hydraulic fracturing operations, reducing total cost of ownership for pressure pumping contractors.
- Gulf Coast petrochemical cluster expansion:Capacity additions in Texas and Louisiana require thousands of miles of process hose for feedstock handling and product transfer infrastructure.
Market Restraints
- Fluoropolymer resin supply concentration:PTFE and FKM feedstock production concentrates among a handful of chemical suppliers, exposing hose manufacturers to input cost volatility and allocation constraints.
- ISO 18752 impulse testing duration:Extended qualification protocols for high-pressure hydraulic hoses delay product commercialization by 18-24 months, freezing working capital in pre-revenue inventory.
- Metallic hose substitution in cryogenic service:Stainless steel corrugated assemblies capture share in LNG bunkering and Arctic exploration where elastomer flexibility limits fall below operational temperature floors.
Strategic Opportunities
- North Sea maintenance corridor digitization:Norwegian and UK offshore operators are piloting RFID-embedded hose assemblies for predictive replacement scheduling, opening premium service revenue streams.
- EU Green Deal synthetic fuel compatibility:Ammonia and methanol bunker fuel mandates will require entirely new hose barrier specifications, rewarding first-movers with validated material portfolios.
- Direct-to-rig distribution platforms:Digital procurement portals are disintermediating traditional oilfield supply houses, allowing manufacturers to capture margin previously allocated to distributor networks.
Industry Challenges
- Polymer science talent scarcity:Compound formulation expertise for high-pressure subsea environments concentrates among retiring specialists, constraining R&D velocity at mid-tier manufacturers.
- Legacy fleet integration complexity:New low-permeation hose designs often require incompatible coupling systems, forcing contractors to choose between full system replacement or compliance gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil Hose Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.66 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Hose Type: Fuel Oil Hoses, LPG Hoses, Hydraulic Hoses, High-Pressure Hoses Material: Rubber, PVC, PTFE, Stainless Steel End User: Marine, Construction, Automotive, Industrial Application: Transport, Transfer, Dispensing, Fuel Supply |
| Companies Covered | Gates Corporation, Manuli Hydraulics, SAMOA Industrial, Trelleborg, Alfagomma, Prevost UK, Eaton Hydraulics, Continental AG, Parker Hannifin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil Hose Market Emerging Trajectories
Material science breakthroughs and regulatory stringency are compressing product lifecycles while opening premium tiers for validated barrier technologies. Hose architecture is evolving from commodity commodity specification toward engineered systems integration.
Multi-layer polymer-laminated barrier construction is miniaturizing wall thickness while maintaining permeation resistance. Offshore drilling contractors are adopting these assemblies for subsea blowout preventer control lines where space constraints limit conduit routing flexibility. The technology is miniaturizing installation footprints on crowded rig decks, enabling deeper water deployments without umbilical diameter penalties.
EPA Clean Air Act mobile source provisions are tightening permeation thresholds for retail fuel dispensing infrastructure. Station operators face capital replacement mandates that disqualify legacy nitrile rubber constructions from new installations. California Air Resources Board enforcement patterns indicate similar state-level rulemaking will propagate to Arizona, Texas, and Florida markets within the compliance window.
Digital twin integration is altering aftermarket service expectations. Major offshore contractors now require continuous pressure-cycle data logging as a contract precondition, displacing traditional time-based replacement schedules. Norwegian continental shelf operators lead this transition, with UK and Brazilian deepwater projects following the procurement template.
Oil Hose Market Segmentation
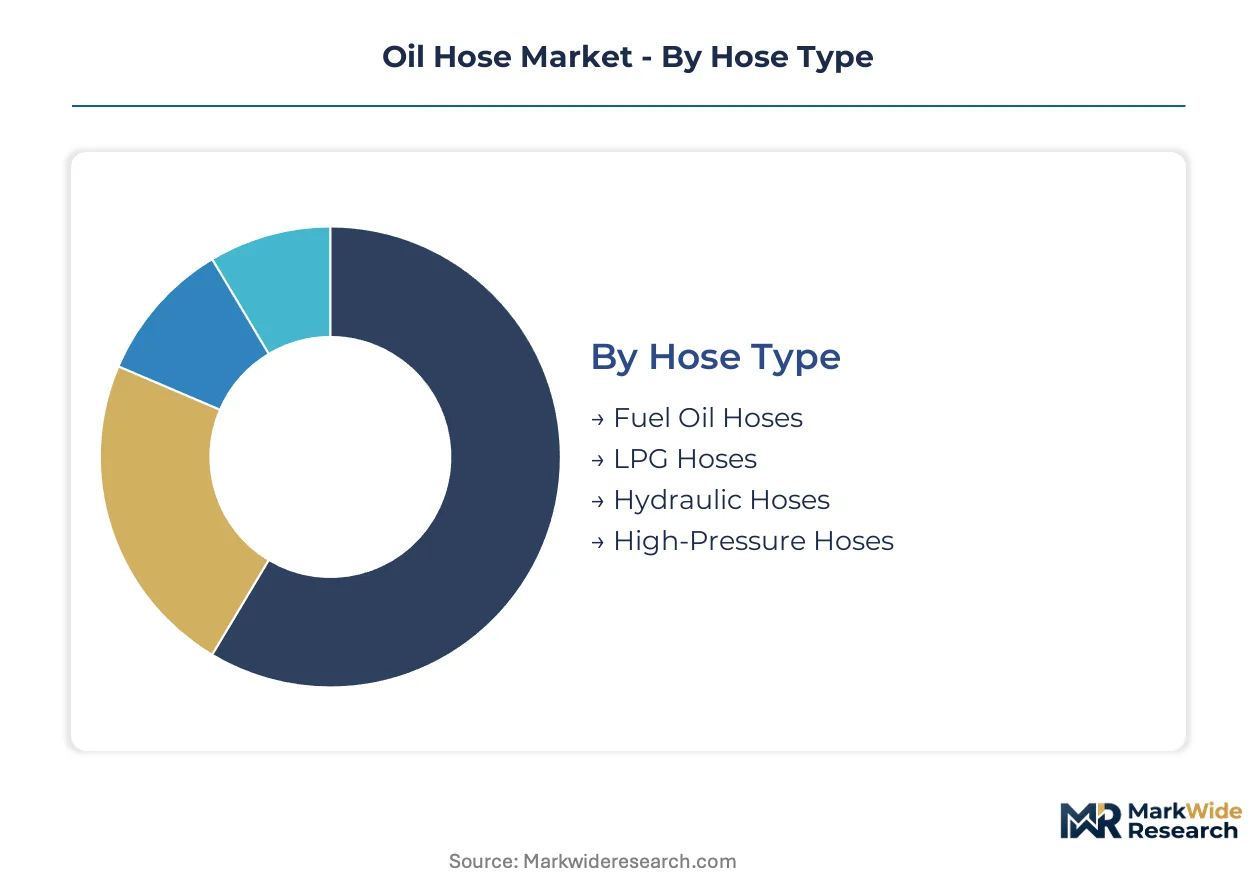
Segmentation in the oil hose market reveals distinct procurement channels and specification requirements that separate commodity volume plays from engineered premium positions. Understanding these divides enables targeted positioning across divergent customer technical literacy and compliance sensitivity.
Hose Type:
Channel mix varies sharply by pressure rating and certification burden, with hydraulic and high-pressure assemblies flowing through specialized fluid power distributors while fuel oil variants reach end-users via petroleum equipment retailers.
- Hydraulic Hoses:Nitrile rubber inner tubes with wire braid reinforcement handle cyclic pressure loading in construction and mining machinery. Demand concentrates in Gulf Coast pressure pumping operations where extended service intervals reduce contractor downtime costs during hydraulic fracturing campaigns.
- High-Pressure Hoses:Multi-layer steel wire spirals contain extreme pressure spikes in subsea blowout preventer control systems. Norwegian and UK North Sea operators drive specification upgrades as digital twin integration mandates continuous pressure-cycle data logging for predictive replacement scheduling.
- Fuel Oil Hoses:Nitrile rubber constructions with textile reinforcement serve stationary heating systems and marine bunkering where moderate pressure ratings suffice.
- LPG Hoses:Specialty nitrile-PVC compounds accommodate liquefied petroleum gas vapor pressure characteristics in residential and commercial distribution networks.
Hydraulic hoses dominate installed base. High-pressure variants are where expansion concentrates.
Material:
Cost tier stratification separates elastomer commodity supply from fluoropolymer premium positioning, with stainless steel capturing cryogenic niches where flexibility limits exclude polymers.
- Rubber:Nitrile, neoprene, and chloroprene formulations provide the baseline cost-performance ratio for general hydrocarbon transfer. Texas and Louisiana petrochemical cluster expansions require thousands of miles of rubber process hose for feedstock handling infrastructure.
- PTFE:Polytetrafluoroethylene inner tubes with stainless steel braid reinforcement withstand aggressive aromatic exposure and temperature extremes. Chemical transfer and high-temperature fuel supply applications in California and Texas refineries reward the premium positioning as EPA permeation thresholds tighten.
- PVC:Lower-cost thermoplastic constructions serve light-duty dispensing and ventilation applications where pressure and chemical resistance requirements remain modest.
- Stainless Steel:Corrugated or braided metal assemblies eliminate permeation entirely while surviving cryogenic temperatures in LNG bunkering and Arctic exploration where elastomer glass transition limits fail.
Rubber dominates installed base. PTFE is where expansion concentrates.
End User:
Customer type determines specification complexity, with marine and industrial buyers demanding certified traceability while construction and automotive segments prioritize availability and interchangeability.
- Marine:IMO MARPOL Annex VI compliance mandates low-permeation bunker fuel transfer hose for oceangoing vessels. Rotterdam, Singapore, and Houston port state control regimes enforce fleet-wide replacement cycles that accelerate barrier-layer technology adoption.
- Industrial:Process plants and refineries require chemical compatibility documentation and fire-resistant ratings for hydrocarbon handling. Gulf Coast capacity additions drive process hose demand for product transfer infrastructure.
- Construction:Mobile equipment fleets prioritize hydraulic hose availability and rapid field replacement over extended service life specifications.
- Automotive:OEM assembly lines and aftermarket service channels demand SAE J517 compliant assemblies with standardized end fittings for manufacturing efficiency.
Industrial dominates installed base. Marine is where expansion concentrates.
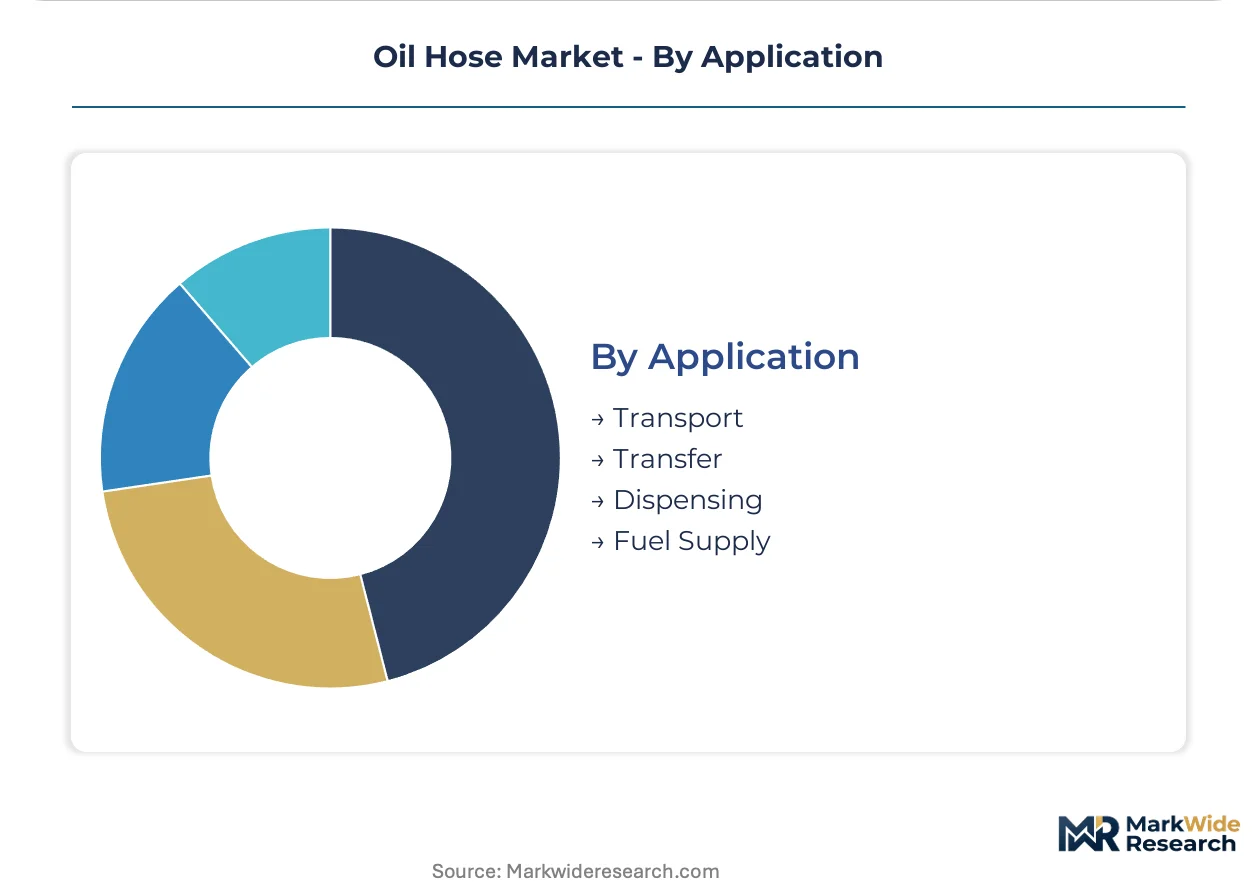
Application:
Volume-maturity tradeoffs separate established transport infrastructure from emerging dispensing compliance mandates, with transfer operations occupying the middle ground on specification intensity.
- Transfer:Intermediate bulk handling between storage, processing, and distribution nodes requires flexibility and pressure rating versatility. Petrochemical cluster logistics in Texas and Louisiana depend on transfer hose fleets that accommodate varying feedstock viscosities and temperatures.
- Dispensing:Retail fuel infrastructure faces EPA Clean Air Act mobile source permeation thresholds that disqualify legacy nitrile rubber constructions. California Air Resources Board enforcement patterns indicate similar state-level rulemaking will propagate to Arizona and Florida markets.
- Transport:Long-haul pipeline alternatives and mobile tanker connections emphasize durability and abrasion resistance over precision permeation control.
- Fuel Supply:Engine feed lines and burner connections prioritize temperature resistance and fire safety ratings in stationary and mobile equipment.
Transfer dominates installed base. Dispensing is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision-engineered hose assemblies to North Sea offshore contractors, while Chinese fabricators supply Gulf Coast petrochemical expansions through direct procurement channels.
United States
Gulf Coast petrochemical clusters in Texas and Louisiana drive process hose demand for ethylene crackers and derivative units. EPA Clean Air Act mobile source provisions enforce permeation thresholds that disqualify legacy constructions from retail fuel infrastructure. Houston anchors the largest concentration of oilfield service distribution centers.
Norway
North Sea maintenance corridors generate specification upgrades for subsea blowout preventer control systems. Norwegian continental shelf operators mandate continuous pressure-cycle data logging as a contract precondition for hose assemblies. Stavanger and Bergen host the primary technical service hubs for deepwater rig fleets.
Germany
Industrial machinery OEMs specify SAE J517 compliant hydraulic assemblies for construction and mining equipment exports. EU Green Deal synthetic fuel compatibility requirements are accelerating validation programs for ammonia and methanol barrier specifications. Stuttgart and Frankfurt concentrate fluid power engineering competence.
Singapore
Port state control regimes enforce MARPOL Annex VI compliance for oceangoing vessel bunker fuel transfer operations. The city-state serves as the primary logistics node for Southeast Asian offshore contractor procurement. Jurong Shipyard clusters drive demand for certified marine hose assemblies.
Brazil
Pre-salt deepwater development programs require high-pressure subsea hose specifications for blowout preventer control lines. ANVISA and environmental licensing processes govern offshore equipment qualification timelines. Rio de Janeiro anchors Petrobras procurement decision-making and technical specification authority.
Oil Hose Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and technical qualification dimensions. The vendor base stratifies into three tiers: integrated polymer compounders with captive raw material supply, specialized fluid power distributors with regional service networks, and commodity fabricators competing on interchangeability and availability. Dominant competitive moves include backward integration into synthetic rubber compounding and direct-to-rig digital procurement platform deployment.
Among diversified industrial conglomerates, Gates Corporation and Parker Hannifin exemplify the integrated archetype through in-house control over material quality and distribution infrastructure. Trelleborg occupies a position within the polymer-laminated barrier specialization tier. These three anchors represent distinct strategic postures: compounder-led quality assurance, distribution density capture, and engineered systems integration for cyclic pressure environments.
| Leading Market Players |
|---|
| Gates Corporation |
| Manuli Hydraulics |
| SAMOA Industrial |
| Trelleborg |
| Alfagomma |
| Prevost UK |
| Eaton Hydraulics |
| Continental AG |
| Parker Hannifin |
| Others |
Supply Flow & Price Mechanics
Eighteen-to-twenty-four month qualification protocols for high-pressure hydraulic hoses freeze working capital in pre-revenue inventory, compressing margin recovery windows and amplifying pricing power for compounders with captive synthetic rubber supply. This lead-time burden concentrates procurement leverage among integrated manufacturers while forcing distributors to absorb carrying cost penalties.
Pricing Analysis
Legacy nitrile rubber constructions face widening price discounts against next-generation fluoropolymer barrier technologies and stainless steel braided PTFE assemblies. Three-tier pricing structure across premium barrier-layer, standard reinforced rubber, and economy thermoplastic levels separates specification tiers. Price differentiation hinges on ISO 18752 certification grade and aromatic resistance ratings. Cost compression in standard rubber tiers intensifies because Gulf Coast petrochemical expansions prioritize volume procurement. Construction equipment fleets exhibit highest price sensitivity; subsea blowout preventer contractors show lowest sensitivity due to failure-cost exposure.
Supply Chain Analysis
China and Germany anchor global hose fabrication capacity, with Chinese producers supplying Gulf Coast petrochemical infrastructure and German specialists serving North Sea offshore contractors. Synthetic rubber compounding draws from nitrile and neoprene feedstock streams, while fluoropolymer barrier layers rest on PTFE and FKM resin allocations. Single-source vulnerability concentrates in fluoropolymer resin supply among a handful of chemical suppliers. Distribution runs through dedicated oilfield service centers and petroleum equipment retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as MARPOL Annex VI port state control regimes force fleet-wide replacement cycles across Rotterdam, Singapore, and Houston, accelerating barrier-layer technology penetration before synthetic fuel compatibility mandates reshape specifications again.
For Market Incumbents: Compound backward integration into synthetic rubber compounding to secure nitrile and neoprene feedstock allocations against fluoropolymer resin supply concentration. Expand captive barrier-layer R&D capacity to preempt EU Green Deal ammonia and methanol hose validation requirements. Defend against metallic hose substitution in cryogenic LNG bunkering by accelerating polymer-laminated fatigue-life improvements. For New Entrants and Emerging Players: Predictive maintenance service gaps in North Sea offshore corridors expose white-space opportunity. Target Norwegian and UK continental shelf operators with RFID-embedded hose assemblies and digital twin integration capabilities. Penetrate through direct-to-rig procurement platforms that disintermediate traditional oilfield supply houses. Prioritize polymer science talent acquisition from retiring specialist pools. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core fluid power divisions. Five-to-ten year viability frames this as a consolidation play around barrier-technology competence rather than commodity fabrication scale. Target mid-tier manufacturers with validated fluoropolymer portfolios but underdeveloped distribution infrastructure. Watch IMO greenhouse gas strategy implementation timelines as inflection signal for capital reallocation toward synthetic fuel compatibility R&D.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Rubber Compounding | Gates Corporation and Parker Hannifin secure nitrile quality control for subsea assemblies against feedstock volatility. |
| Barrier-Layer Technology Validation | Trelleborg polymer-laminated constructions extend fatigue life under cyclic pressure loading for deepwater BOP control lines. |
| Direct-to-Rig Digital Procurement Platform | Manufacturers capture distributor margin by connecting with offshore contractors through disintermediated portals. |
| RFID-Embedded Predictive Maintenance Service | Norwegian operators mandate continuous pressure-cycle data logging as contract precondition for hose assemblies. |
| EU Green Deal Synthetic Fuel Compatibility Program | First-movers with validated ammonia and methanol barrier specifications capture premium positioning ahead of mandate propagation. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with offshore drilling contractors, petrochemical procurement leads, fluid power distributors, and polymer compounding engineers. Secondary validation drew from EPA Clean Air Act regulatory filings, MARPOL Annex VI port state control enforcement records, ISO 18752 and SAE J517 standards documentation, and SEC 10-K disclosures from listed industrial conglomerates. Bottom-up segment sizing triangulated against top-down market aggregation across hose type, material, end user, and application dimensions.
Across the analysis window, volume and value outputs reflect modeled segmentation across hydraulic, high-pressure, fuel oil, and LPG hose types; rubber, PTFE, PVC, and stainless steel materials; marine, industrial, construction, and automotive end users; and transfer, dispensing, transport, and fuel supply applications. CAGRs were derived from regression analysis against offshore rig fleet modernization schedules, Gulf Coast petrochemical capacity expansion timelines, and regulatory compliance mandate propagation patterns. Forecast inputs incorporated permeation threshold tightening trajectories under EPA and MARPOL regimes.
Forecasts assume regulatory continuity in US EPA mobile source provisions and IMO MARPOL Annex VI administration; material policy shifts in sulfur content limits or greenhouse gas strategy implementation would require re-modeling. Specific risks include fluoropolymer resin supply disruption, ISO qualification protocol duration extensions, and metallic hose substitution acceleration in cryogenic service. Recalibration cycles align with material shifts in port state control enforcement patterns and synthetic fuel mandate adoption timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil Breather Tank Market
Oil & Gas
United States Oil and Gas Upstream Market
Oil & Gas
South and Central America Oil Field Services Market
Oil & Gas
Global Completion Equipment and Services Market
Oil & Gas
Coal Mining Market
Oil & Gas
Russian Federation Oil and Gas Downstream Market
Oil & Gas
Oil and Gas Pipe Market
Oil & Gas
Oil and Gas Fabrication Market
Oil & Gas
Connected Oil and Gas Market
Oil & Gas
Shale Gas Hydraulic Fracturing Market
Oil & Gas
Asia-Pacific Digital Oilfield Market
Oil & Gas
Coal Bed Methane Market
Oil & Gas
Oil and Gas Corrosion Protection Market
Oil & Gas
Oilfield Drill Bits Sales Market
Oil & Gas
Modular Gas Processing Plants Market
Oil & Gas
Wireline Logging Services Market