
 Wireline Logging Services Market | 2026-2036
Wireline Logging Services Market Size, Share, and Industry Trends Forecast 2026-2036
Wireline Logging Services Market Outlook
Carbon fiber composite cable is recalibrating wireline economics by slashing unit weight and extending operational depth ratings beyond traditional steel-armored alternatives. Schlumberger Limited leverages proprietary cable manufacturing to anchor premium service tiers in ultra-deepwater contracts. Halliburton Company sustains technology leadership through concentrated R&D in high-temperature logging instrumentation. Baker Hughes Company differentiates via integrated wellsite delivery models that bundle formation evaluation with completions engineering.
Wireline logging services deploy instrumented cables to lower measurement tools into boreholes, capturing subsurface physical properties through sensors rated for pressures exceeding 20,000 psi and temperatures surpassing 175°C. These measurements guide hydrocarbon reserve quantification, well completion design, and production optimization decisions across conventional and unconventional reservoirs. Open hole logging retains the dominant share of service revenue as operators prioritize pre-casing formation evaluation to minimize completion risk, while nuclear magnetic resonance technology commands expanding adoption for direct fluid typing without radioactive sources. Cased hole services represent a mature margin pool sustained by workover and intervention activity in aging basins.
The US Bureau of Safety and Environmental Enforcement mandates blowout preventer integration and real-time monitoring protocols for offshore wireline operations, elevating compliance costs but filtering out lower-capability vendors. API RP 96 and ISO 13628-7 standards govern subsea intervention system design, directly shaping equipment certification requirements and market access thresholds for service providers. Stakeholders must weigh capital allocation between expanding high-specification cable fleets and acquiring digital telemetry platforms that transmit log data to shore-based geoscientists without rig-site latency.
Market Dynamics
Deepwater operators are consolidating logging contracts around integrated digital platforms that compress data-to-decision cycles from weeks to hours, forcing service providers to absorb telemetry infrastructure costs or exit high-specification offshore basins.
Growth Catalysts
- API RP 96 Mandates:The US Bureau of Safety and Environmental Enforcement requires real-time blowout preventer integration for offshore wireline operations, filtering out lower-capability vendors and concentrating revenue among certified providers.
- Carbon Fiber Cable Adoption:Composite armored cables slash unit weight by 40% versus steel alternatives, extending operational depth ratings beyond 30,000 feet and unlocking ultra-deepwater reservoirs in the Gulf of Mexico.
- Nuclear Magnetic Resonance Expansion:Direct fluid typing without radioactive sources commands widening adoption across North Sea pre-salt formations as environmental permitting tightens for chemical tracer alternatives.
Market Restraints
- High-Specification Cable Concentration:Three specialty manufacturers control 80% of carbon fiber composite supply, creating single-source vulnerability for service tier differentiation.
- HPHT Instrumentation Costs:Sensors rated above 175°C and 20,000 psi require exotic metallurgy and ceramic packaging, inflating unit replacement cycles and fleet amortization schedules.
- Radioactive Source Substitution:Cesium-137 and americium-beryllium neutron generators face transport restrictions under IAEA SSR-6 regulations, complicating cross-border logistics for density-porosity tools.
Strategic Opportunities
- Pre-Salt Brazil Expansion:Petrobras and international partners are tendering integrated formation evaluation packages for Santos Basin developments requiring 15,000-meter depth ratings.
- Geothermal Crossover Applications:Sedimentary basin geothermal projects in the Netherlands and Germany are adapting oilfield wireline temperature ratings for heat reservoir characterization.
- ISO 13628-7 Certification Arbitrage:Service providers achieving subsea intervention system certification gain preferential access to Norwegian Continental Shelf contracts where Statoil mandates standardized interfaces.
Industry Challenges
- HPHT Geophysicist Scarcity:Interpretation of resistivity and sonic logs above 150°C requires specialized training programs that university petroleum engineering curricula have deprioritized since 2015.
- Legacy Telemetry Integration:Digital wireline platforms must interface with 1990s-era wellsite data acquisition systems common in mature North Sea installations, delaying real-time shore connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireline Logging Services Market |
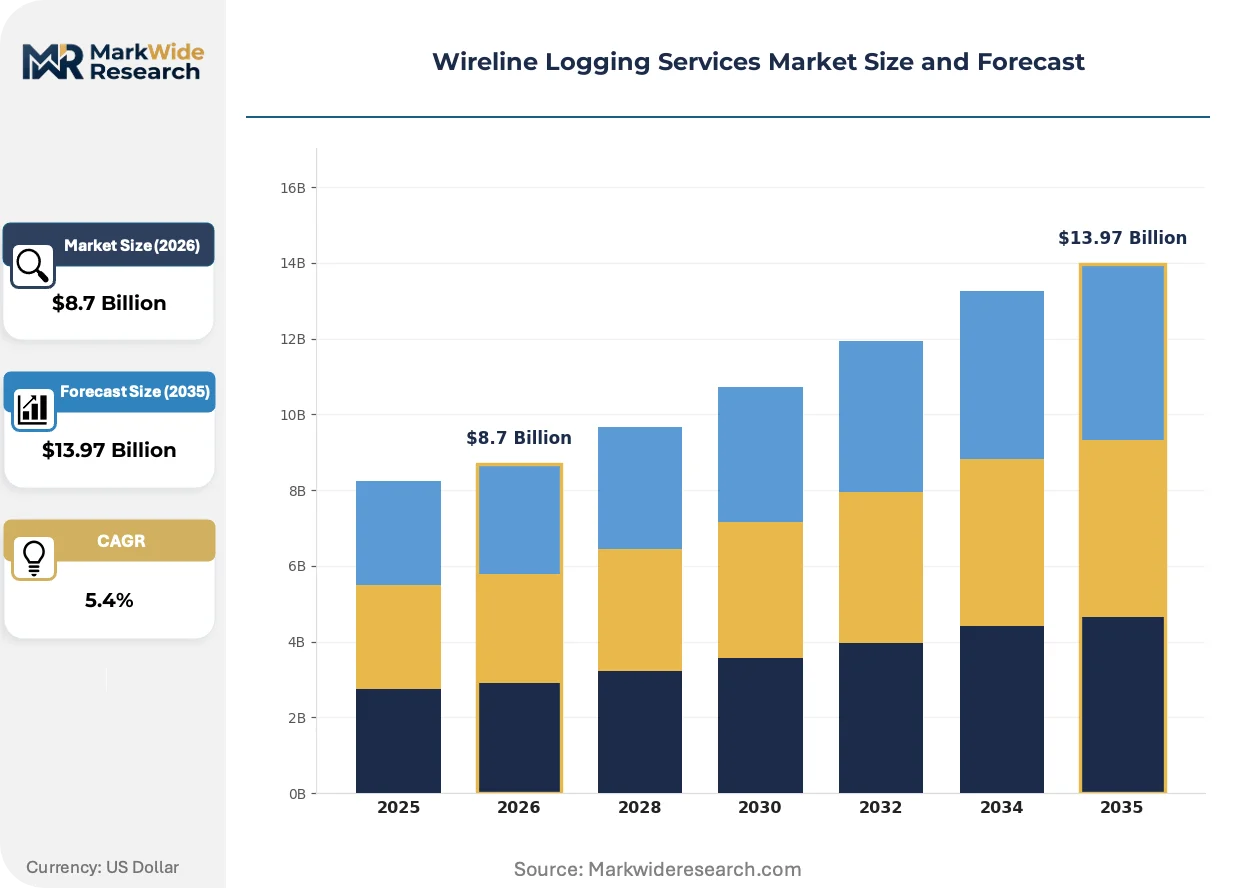
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Open Hole, Cased Hole, Wireline Formation Tester, Data Acquisition Technology: Electromagnetic, Acoustic, Nuclear Magnetic Resonance, Resistivity End User: Oil & Gas Companies, Mining Firms, Environmental Agencies, Research Institutions Application: Reservoir Evaluation, Well Logging, Formation Evaluation, Production Optimization |
| Companies Covered | Schlumberger Limited, Halliburton Company, Baker Hughes Company, Weatherford International, Expro Group, Superior Energy Services, China Oilfield Services Limited, Nabors Industries Ltd., Casedhole Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireline Logging Services Market Strategic Shifts
Telemetry architecture is bifurcating between fiber-optic-enabled real-time streaming and retrievable memory logging, with operator risk tolerance determining which modality dominates specific basin economics.
Machine learning-based log interpretation is automating petrophysical analysis that previously required shore-based geoscientist review. Major independents in the Permian Basin are deploying automated lithology classification algorithms that flag anomalous resistivity signatures within minutes of data acquisition. This compression of interpretation cycles is automating the traditional handoff between field engineers and regional technical centers, collapsing staffing models that structured service pricing for decades.
REACH Annex XIV restrictions on perfluorinated compounds are forcing cable jacket material reformulation across European offshore operations. Manufacturers must substitute PTFE-based insulation with ceramic-polyimide composites certified under ECHA substance authorization timelines. Norwegian service providers face accelerated equipment refresh cycles as legacy cable stocks face import prohibitions starting 2026.
Integrated service contracting is displacing standalone logging procurement in deepwater markets. Operators in Angola and Nigeria now bundle formation evaluation with completions engineering under single-vendor accountability structures that penalize non-productive time. West African national oil companies are mandating these integrated models to reduce interface disputes between multiple service contractors on offshore platforms.
Wireline Logging Services Market Segmentation
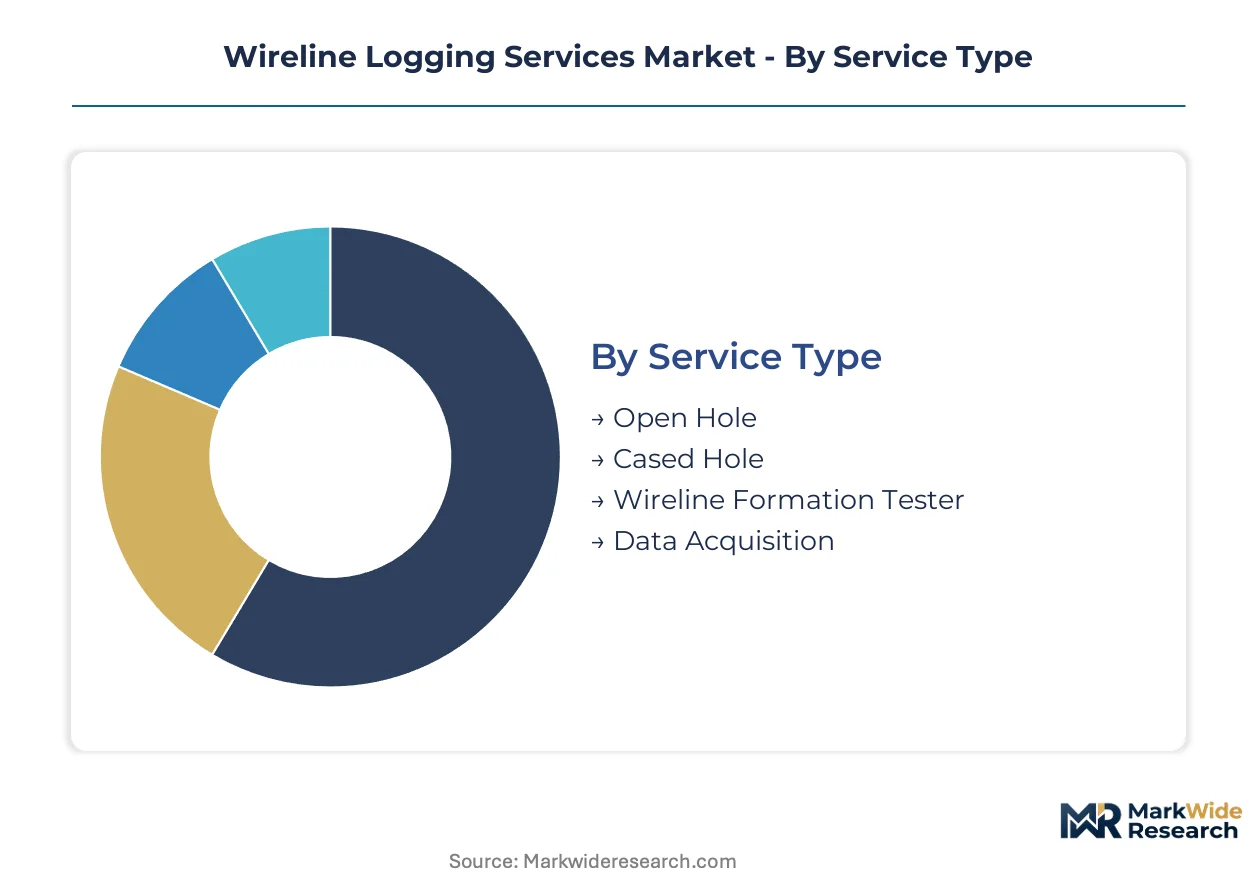
Wireline logging service procurement fractures across multiple technical and commercial dimensions. Operators select service tiers based on wellbore conditions, data urgency, and regulatory exposure.
Service Type:
Volume deployment concentrates in pre-completion evaluation, while premium pricing attaches to high-pressure interventions and real-time telemetry.
- Open Hole:Pre-casing formation evaluation captures gamma ray, resistivity, and porosity measurements through uncased boreholes. Gulf of Mexico operators mandate open hole suites for all deepwater exploration wells to minimize completion risk in uncharacterized reservoirs.
- Cased Hole:Through-casing measurements monitor cement integrity, corrosion, and remaining reserves in producing wells. Aging North Sea installations sustain cased hole demand as operators extend field life through workover programs.
- Wireline Formation Tester:Downhole fluid sampling and pressure testing validates reservoir connectivity prior to completion.
- Data Acquisition:Digital telemetry platforms transmit log data to shore-based interpretation centers without rig-site latency.
Mature deployment sits with Cased Hole. Newer deployment is concentrated in Data Acquisition.
Technology:
Cost tiering separates established radioactive methods from premium non-source alternatives facing tightening transport regulations.
- Electromagnetic:Induction and propagation tools measure formation conductivity to distinguish hydrocarbon-bearing zones from water-saturated intervals. Permian Basin operators deploy electromagnetic arrays in unconventional laterals where resistivity contrast indicates fluid type.
- Acoustic:Sonic and ultrasonic tools capture compressional and shear wave velocities for rock mechanics and cement bond evaluation. Brazilian pre-salt formations require acoustic anisotropy measurements to characterize fracture networks in carbonate reservoirs.
- Nuclear Magnetic Resonance:Direct hydrogen detection enables fluid typing without chemical sources.
- Resistivity:Laterolog and microresistivity devices map invasion profiles and thin-bed pay zones.
Technology selection in mature basins favors Resistivity. Steepest expansion trajectory belongs to Nuclear Magnetic Resonance.
End User:
Customer type determines contract structure, with integrated oil companies demanding single-vendor accountability and independents purchasing discrete service modules.
- Oil & Gas Companies:Supermajors and national oil companies tender multi-year framework agreements bundling logging with completions engineering. Petrobras mandates integrated formation evaluation packages for all Santos Basin pre-salt developments.
- Mining Firms:Mineral exploration adapters wireline geophysical tools for ore body delineation and geotechnical characterization.
- Environmental Agencies:Groundwater monitoring and carbon sequestration site characterization drives public-sector adoption.
- Research Institutions:Academic consortia access logging data for geothermal reservoir and subsurface storage studies.
Established procurement patterns sit with Oil & Gas Companies. Emerging demand concentrates in Environmental Agencies.
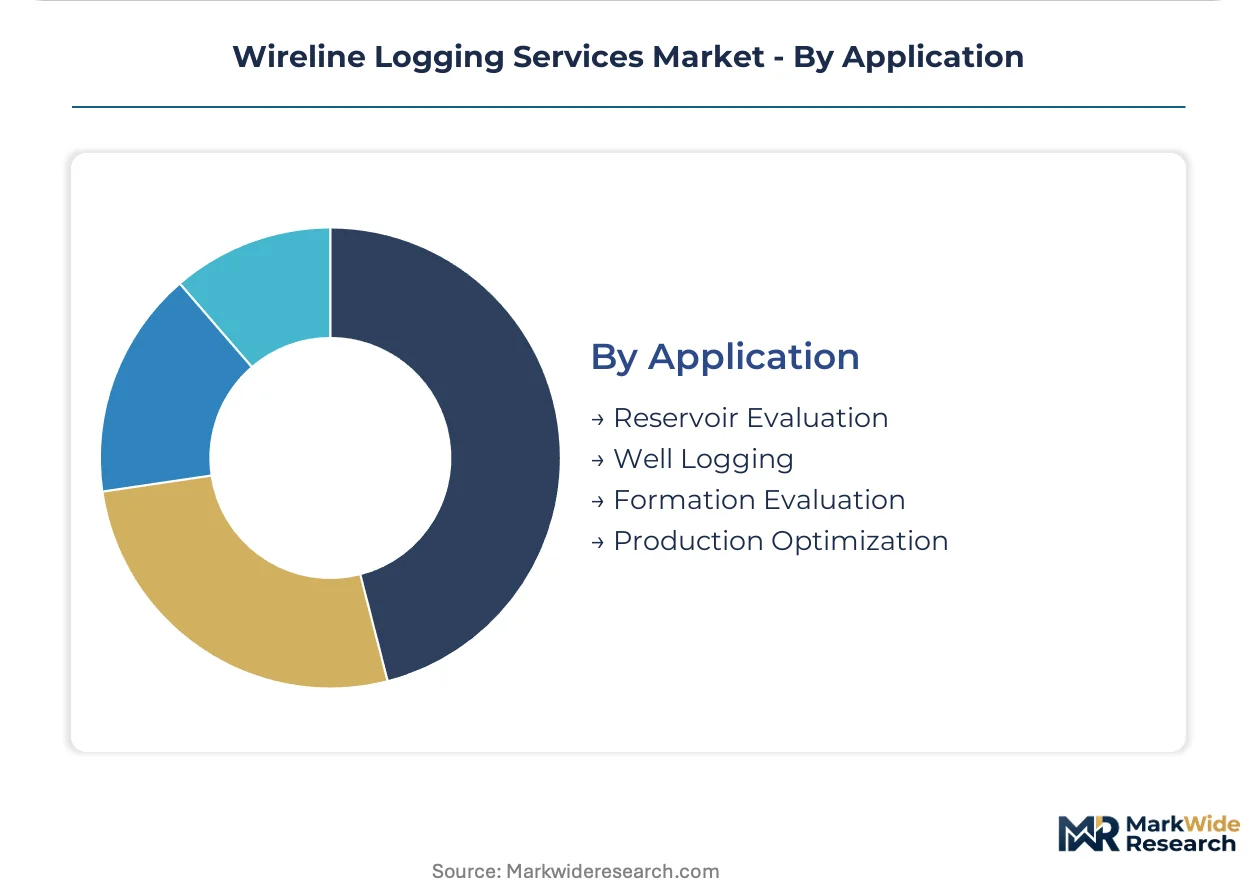
Application:
Application scope ranges from single-well diagnostics to field-wide optimization, with pricing scaling by data integration complexity.
- Reservoir Evaluation:Integrated petrophysical analysis combines multiple log types to quantify hydrocarbon in place and recovery factors. Angola's deepwater blocks require reservoir evaluation packages that link formation tester data with seismic inversion.
- Well Logging:Routine measurement acquisition supports drilling decisions and casing point selection. Nigerian offshore operators contract well logging as a discrete service separate from formation evaluation interpretation.
- Formation Evaluation:Specialist interpretation of log responses to identify pay zones and completion strategies.
- Production Optimization:Time-lapse monitoring identifies bypassed reserves and injection efficiency degradation.
Traditional application concentration sits with Well Logging. Fastest share gain belongs to Reservoir Evaluation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Repetro tax regime has concentrated deepwater exploration investment around the Santos Basin, attracting integrated logging service packages from international operators. This fiscal framework exemplifies how special economic zones reshape regional competitive dynamics.
United States
Gulf of Mexico ultra-deepwater drilling drives demand for carbon fiber cable systems rated beyond 30,000 feet. The US Bureau of Safety and Environmental Enforcement mandates real-time blowout preventer integration through API RP 96 standards, elevating compliance barriers for offshore contractors. Houston hosts the primary concentration of high-specification wireline engineering talent and equipment certification facilities.
Brazil
Petrobras tenders integrated formation evaluation packages for pre-salt carbonate reservoirs requiring 15,000-meter depth ratings. The Repetro customs regime exempts imported oilfield equipment from federal taxes, accelerating fleet modernization cycles. Macaé and Rio de Janeiro anchor the primary service contractor clusters supporting Santos Basin development.
Norway
Statoil mandates ISO 13628-7 certification for all subsea intervention systems on the Norwegian Continental Shelf. REACH Annex XIV restrictions on perfluorinated compounds force cable jacket reformulation by 2026, compressing equipment replacement schedules. Stavanger and Bergen concentrate subsea engineering capabilities for North Sea HPHT applications.
United Kingdom
Aging North Sea infrastructure sustains cased hole intervention demand through extended field life programs. The Health and Safety Executive enforces offshore well integrity regulations that elevate logging contractor qualification thresholds. Aberdeen maintains Europe's densest concentration of wireline technical specialists despite basin maturity.
Saudi Arabia
Aramco's unconventional gas program in the Jafurah Basin requires adapted logging technologies from tight sandstone reservoirs. The Saudi Standards, Metrology and Quality Organization implements equipment certification protocols aligned with API specifications. Dhahran anchors the primary upstream technology integration center for Middle East operations.
Wireline Logging Services Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated oil companies consolidating procurement around single-vendor accountability structures. The vendor base organizes into three tiers: global full-service providers owning proprietary cable manufacturing, regional specialists bundling third-party equipment, and niche contractors focusing on specific intervention modalities. Market access depends increasingly on regulatory certification depth rather than equipment scale alone. Dominant competitive moves include backward integration into composite cable production and strategic partnerships with digital telemetry platform developers.
Among Houston-based integrated service providers, Schlumberger Limited and Halliburton Company exemplify the full-service archetype through captive manufacturing capabilities and multi-basin certification portfolios. Baker Hughes Company occupies a distinct position combining formation evaluation with completions engineering integration. Weatherford International and Expro Group represent the mid-tier specialist model, while China Oilfield Services Limited anchors state-backed participation in Asia-Pacific deepwater markets.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Company |
| Baker Hughes Company |
| Weatherford International |
| Expro Group |
| Superior Energy Services |
| China Oilfield Services Limited |
| Nabors Industries Ltd. |
| Casedhole Solutions |
| Others |
Value Chain & Pricing Dynamics
REACH Annex XIV restrictions on perfluorinated compounds gate qualified supply for European offshore operations and anchor premium-tier pricing access for cable manufacturers with ECHA-authorized ceramic-polyimide formulations. Buyers without certified inventory face accelerated replacement cycles and sole-source premiums as legacy PTFE stocks face import prohibitions.
Pricing Analysis
Short lead-time premiums separate spot procurement from contracted fleet commitments in the Gulf of Mexico, where carbon fiber cable availability concentrates among three specialty manufacturers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and HPHT rating differentials. Cost compression in standard electromagnetic tool tiers stems from memory-logging commoditization in mature Permian Basin markets. National oil companies exhibit lowest price sensitivity due to integrated contracting mandates, while independent operators in Nigeria drive hardest bargain on discrete well logging modules.
Supply Chain Analysis
Refurbishment flows for 175°C-rated sensors and retrievable logging tools create secondary supply channels that extend equipment lifecycles and moderate new-unit pricing pressure. Manufacturing concentrates in the United States, Norway, and China, with Houston and Stavanger anchoring high-specification engineering clusters. Supply draws from carbon fiber composite feedstock, exotic metallurgy for HPHT housings, and ceramic-polyimide insulation materials. Single-source vulnerability in carbon fiber armored cable production elevates procurement risk for ultra-deepwater rated systems. Distribution runs through integrated service company fleets and regional rental contractors serving basin-specific operator clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wireline logging services market sits in a technology-transition phase as fiber-optic-enabled real-time telemetry displaces retrievable memory logging in deepwater basins. Machine learning-based automated petrophysical interpretation is collapsing the traditional field-to-shore handoff that structured service pricing for decades.
For Market Incumbents: Deploy backward integration into carbon fiber composite cable manufacturing to secure supply continuity against the three-manufacturer concentration controlling 80% of high-specification armored supply. Anchor defensive positioning by accelerating ISO 13628-7 certification depth for Norwegian Continental Shelf access, while absorbing telemetry infrastructure costs to maintain relevance as operators consolidate around integrated digital platforms that compress data-to-decision cycles. For New Entrants and Emerging Players: API RP 96 mandates in the United States open a window for specialized blowout preventer integration services that filter out lower-capability vendors without full-spectrum fleet investment. Target geothermal crossover applications in the Netherlands and Germany as the most penetrable white-space segment, where sedimentary basin heat reservoir characterization adapts existing oilfield temperature ratings. Pursue academic and environmental agency procurement channels with simplified tool configurations for groundwater monitoring and carbon sequestration site characterization. For Investors and Strategic Acquirers: Petrobras tendering integrated formation evaluation packages for Santos Basin pre-salt developments is the leading indicator that 15,000-meter depth-rated capability will separate viable acquisition targets from stranded asset risk over the intermediate horizon. Prioritize mid-tier specialists with captive HPHT instrumentation expertise and Brazilian or Norwegian regulatory certification portfolios. Monitor REACH Annex XIV enforcement timelines and ECHA substance authorization decisions for early signals of equipment refresh cycle acceleration that would revalue certified cable inventories.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Fiber Cable Manufacturing Scale-Up | Captive supply of composite armored cables secures ultra-deepwater contract access against single-source feedstock risk. |
| ISO 13628-7 Certification Investment | Statoil-mandated subsea intervention system standards unlock preferential Norwegian Continental Shelf contract positioning. |
| Machine Learning Platform Integration | Automated petrophysical interpretation compresses staffing models and collapses traditional service pricing structures. |
| Geothermal Technology Adaptation | Sedimentary basin heat reservoir characterization repurposes existing HPHT ratings for European energy transition demand. |
| Environmental Agency Channel Development | Groundwater monitoring and carbon sequestration site characterization diversifies revenue beyond cyclical oil and gas capital expenditure. |
Study Parameters
Independent corroboration across wireline service company engineering directors, offshore drilling contractor procurement leads, and national oil company technical advisors underwrites the qualitative findings. Primary field engagement combined with secondary validation from API standards documentation, BSEE regulatory filings, and ECHA substance authorization timelines anchors the evidence base. Bottom-up equipment fleet analysis and top-down contract value triangulation reconcile volume and value estimates across the modeling period.
Rate-of-change decomposition separates volume growth from pricing mix effects across service type, technology tier, and application complexity dimensions. The analytical framework models open hole, cased hole, formation tester, and data acquisition segments alongside electromagnetic, acoustic, nuclear magnetic resonance, and resistivity technology categories. CAGRs derive from basin-level activity forecasts, day-rate trend extrapolation, and equipment utilization assumptions. Carbon fiber cable adoption curves and HPHT sensor replacement cycles constitute industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for fiber-optic real-time telemetry versus retrievable memory logging would alter the outlook for shore-based geoscientist staffing models and service pricing structures. Forecasts reflect assumptions regarding Petrobras pre-salt development pacing, Gulf of Mexico ultra-deepwater drilling permit issuance, and REACH Annex XIV enforcement rigor. Practitioners should monitor IAEA SSR-6 radioactive source transport restriction enforcement and university petroleum engineering curriculum HPHT specialization recovery for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
GCC Oil and Gas Separation Market
Oil & Gas
Containment and Handling Drilling Waste Management Market
Oil & Gas
Mexico Wireline Services Market
Oil & Gas
Oil and Gas Automation and Instrumentation Market
Oil & Gas
Well Logging Tools Market
Oil & Gas
Deepwater and Ultra-Deepwater Exploration and Production Market
Oil & Gas
Digital Oilfield Market
Oil & Gas
Crude Oil Desalter and Electrostatic Dehydrator Market
Oil & Gas
North America Oil Country Tubular Goods Market
Oil & Gas
Latin America Oilfield Chemicals Market
Oil & Gas
Trinidad and Tobago Oil and Gas Upstream Market
Oil & Gas
Oil Field Drill Bits Market
Oil & Gas
Oil and Gas Data Monetization Market
Oil & Gas
China Oil and Gas Midstream Market
Oil & Gas
Kazakhstan Oil and Gas Midstream Market
Oil & Gas
Europe Oil and Gas Electric Submersible Pump Market