
 Cased Hole Logging Services Market | 2026-2036
Cased Hole Logging Services Market Size, Share, and Industry Trends Forecast 2026-2036
Cased Hole Logging Services Market Outlook
API Q2 specification is collapsing the supplier base for cased hole logging services, forcing smaller wireline contractors to either upgrade quality management systems or exit high-specification contracts. Schlumberger Limited leverages its integrated logging-while-drilling portfolio to sustain premium pricing on production logging deployments. Halliburton Company anchors its position through captive perforating tool manufacturing and proprietary acoustic cement evaluation platforms. Baker Hughes Company differentiates via fiber optic distributed temperature sensing bundled with conventional nuclear logging packages.
Cased hole logging services encompass diagnostic measurements performed inside completed wells to evaluate cement bond quality, reservoir fluid movement, and tubular integrity using gamma ray, neutron, and acoustic pulse-echo tools. These services enable operators to optimize artificial lift, identify channeling behind casing, and comply with abandonment regulations without drilling new wells. Production logging generates the largest revenue pool among service types due to recurring demand from artificial lift optimization in stripper wells. Fiber optic technology represents the fastest-expanding technology segment as operators install permanent downhole monitoring systems for real-time well performance tracking. Well integrity assessment commands the highest margins among applications because regulatory non-compliance carries field shutdown penalties.
API standards, NORSOK D-010 well integrity requirements, and Saudi Aramco drilling and workover specifications collectively dictate tool calibration protocols, operator certification, and data deliverable formats across major producing regions. Environmental Monitoring application demand tightens as regulators in the North Sea and Gulf of Mexico impose methane leak detection mandates on aging wellbores. Stakeholders must monitor whether national oil companies accelerate localization requirements that could restrict service company mobility between basins.
Market Dynamics
API Q2 certification mandates are compressing the supplier base for cased hole logging services, forcing wireline contractors to upgrade quality management systems or exit high-specification contracts entirely. This regulatory pressure is redistributing market share toward integrated service providers with captive calibration facilities and certified operator training programs.
Growth Catalysts
- Mature Field Redevelopment:Stripper well optimization across the Permian Basin and North Sea sustains recurring demand for production logging and artificial lift diagnostics.
- NORSOK D-010:Norway's well integrity standard mandates periodic cement bond evaluation, creating scheduled procurement cycles for pulsed-neutron and acoustic logging services.
- Fiber Optic Sensing:Distributed temperature and acoustic monitoring installations are expanding service attach rates for permanent downhole surveillance systems.
Market Restraints
- Specialized Tooling Concentration:Gamma ray and neutron source manufacturing concentrates among a handful of licensed suppliers, creating single-source vulnerability for logging contractors.
- Radioactive Materials Licensing:EPA and state-level NORM handling permits impose multi-year compliance timelines that block rapid market entry.
- Wireline Unit Utilization:Capital intensity of pressure-rated logging trucks limits fleet expansion during demand cyclicality.
Strategic Opportunities
- Abandonment Regulation Expansion:Gulf of Mexico methane leak detection mandates are extending serviceable well populations beyond productive life.
- Saudi Aramco Localization:In-kingdom manufacturing requirements for logging tools create partnership openings for technology licensors.
- Digital Twin Convergence:Integration of real-time fiber optic data with reservoir simulation platforms enables subscription-based performance monitoring contracts.
Industry Challenges
- Certified Operator Shortage:API Q2-qualified logging engineers command premium wages, constraining crew scaling for spot market opportunities.
- Legacy Tool Interoperability:Proprietary data formats from 1990s-era logging systems complicate integration with modern cloud-based analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cased Hole Logging Services Market |
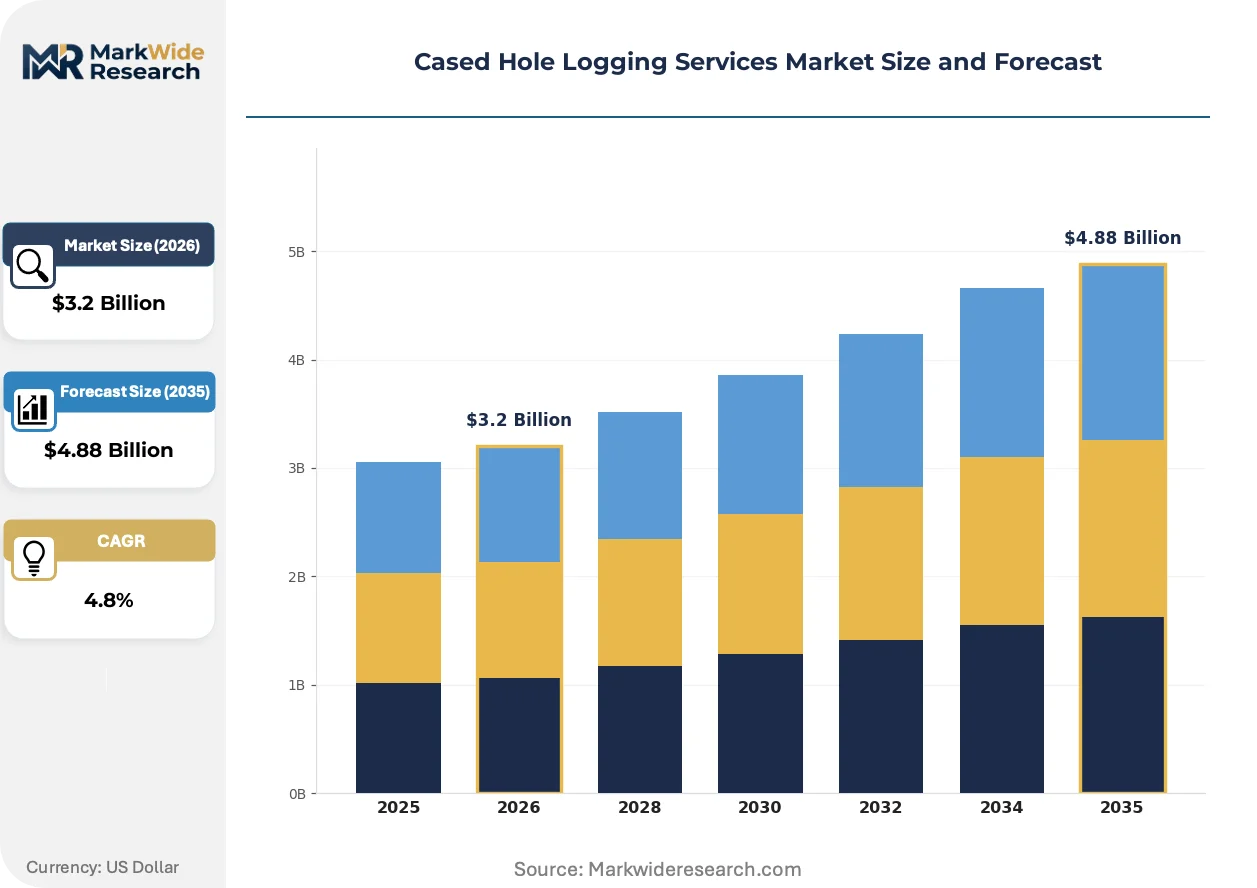
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $4.88 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Production Logging, Cement Evaluation, Perforation Logging, Multi-Finger Imaging Technology: Electrical Resistivity, Acoustic Logging, Nuclear Logging, Fiber Optic Application: Oil Recovery, Gas Recovery, Environmental Monitoring, Well Integrity Assessment End User: Oil & Gas Operators, Service Companies, Government Agencies, Research Institutions |
| Companies Covered | Weatherford International Plc, Superior Energy Services, Schlumberger Limited, RECON Petrotechnologies Ltd, OilServ, Halliburton Company, China Oilfield Services Limited, Nabors Industries Ltd, Baker Hughes Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cased Hole Logging Services Market Strategic Shifts
Permanent monitoring infrastructure is displacing conventional wireline intervention models across offshore and unconventional assets. Operators now prioritize real-time data continuity over episodic logging campaigns, reshaping capital allocation and service contracting structures.
Fiber optic distributed acoustic sensing is supplanting conventional production logging tools in horizontal shale wells. Permian Basin operators deploy permanent fiber installations during completions to eliminate future wireline interventions. This technology compression is eroding the revenue base for traditional spinner and gradiomanometer services while expanding recurring data subscription margins.
EPA methane emission regulations and BLM waste prevention rules are tightening measurement requirements for idle wellbores. Operators must now demonstrate mechanical integrity through certified logging diagnostics before regulatory deadlines. Gulf of Mexico shelf assets face the most acute compliance pressure, driving accelerated procurement of cement evaluation and casing inspection services.
Integrated service contracting is consolidating discrete logging, perforating, and remediation work scopes under single-provider agreements. National oil companies in the Middle East now bundle multi-year well surveillance programs with guaranteed response-time clauses. This preference compression disadvantages pure-play logging contractors lacking complementary pumping or coiled tubing capabilities.
Cased Hole Logging Services Market Segmentation
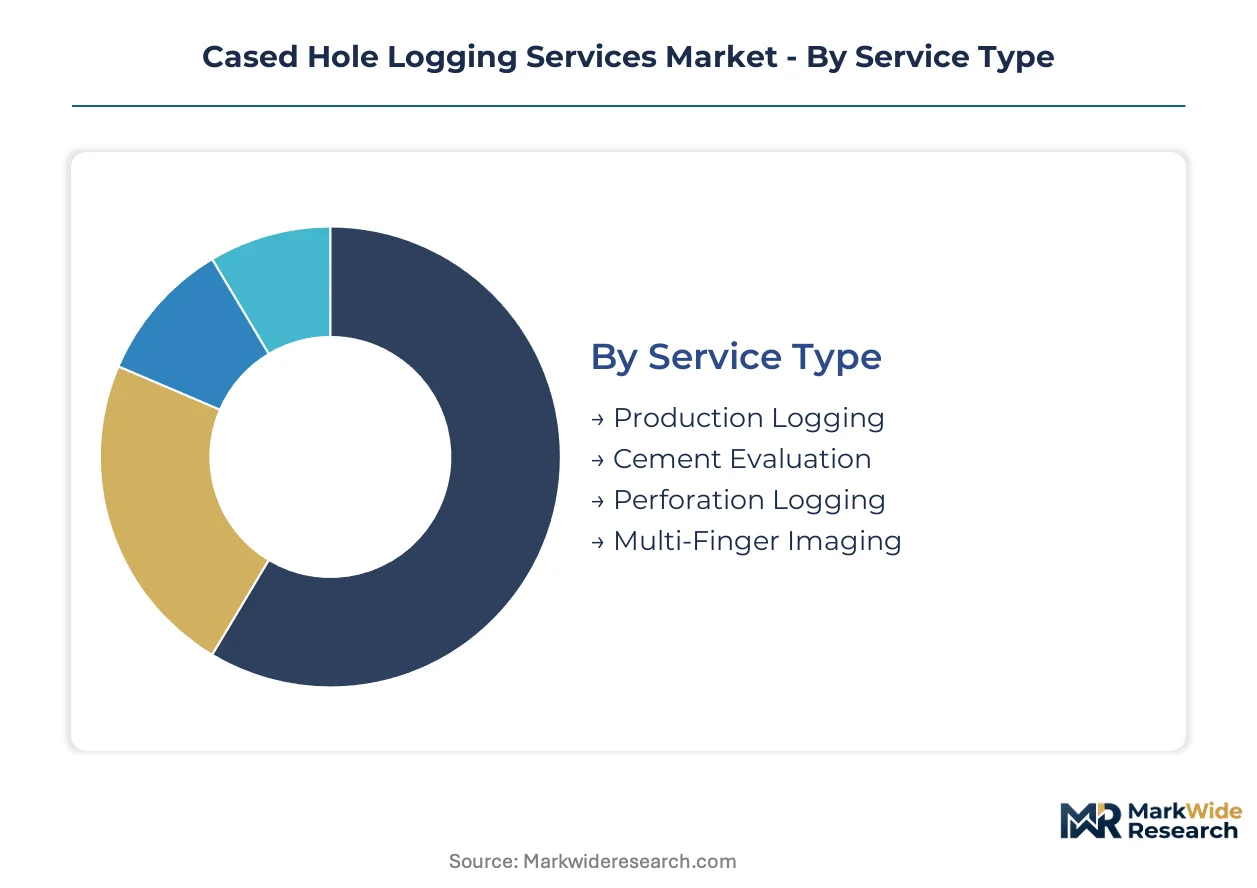
Cased hole logging services fragment across four dimensions that determine contracting structures, technology deployment patterns, and margin capture. Service type and technology choices dominate capital allocation decisions, while application scope and end-user category dictate regulatory compliance intensity and procurement cycle frequency.
Service Type:
Fiber optic distributed sensing is displacing conventional wireline interventions across multiple service categories, forcing traditional logging contractors to defend their revenue base through bundled offerings or specialized high-pressure deployments.
- Production Logging:Spinner flowmeters, gradiomanometers, and radioactive tracers measure fluid entry profiles and artificial lift efficiency in completed wells. Permian Basin stripper well operators sustain recurring demand for artificial lift diagnostics and flow allocation studies.
- Cement Evaluation:Acoustic pulse-echo and ultrasonic bond tools assess zonal isolation integrity behind casing. Norway's NORSOK D-010 mandates periodic cement bond verification, creating scheduled procurement cycles for pulsed-neutron and acoustic logging services in the North Sea.
- Perforation Logging:Gamma ray correlation and casing collar locators guide perforating gun positioning for stimulation or recompletion.
- Multi-Finger Imaging:Electromechanical caliper arrays map casing deformation, corrosion, and mechanical damage.
Production Logging retains volume leadership; Cement Evaluation holds the steepest expansion curve.
Technology:
Cost tier stratification separates capital-intensive permanent installations from episodic wireline campaigns, with technology selection driven by well economics and regulatory monitoring requirements.
- Electrical Resistivity:Laterolog and induction tools measure formation resistivity through casing for saturation monitoring. Mature field operators in Saudi Arabia deploy these tools for waterflood surveillance in carbonate reservoirs.
- Acoustic Logging:Compressional and shear wave velocity measurements evaluate cement bond quality and casing integrity. Gulf of Mexico shelf assets face acute EPA methane compliance pressure, accelerating procurement of acoustic cement evaluation services.
- Nuclear Logging:Gamma ray and neutron porosity tools require licensed radioactive source handling and specialized transportation protocols.
- Fiber Optic:Distributed temperature and acoustic sensing enables real-time well performance monitoring without wireline intervention. Permian Basin horizontal shale completions increasingly incorporate permanent fiber installations to eliminate future interventions.
Fiber Optic is climbing the fastest; Nuclear Logging maintains the highest barrier to competitive entry.
Application:
Customer type concentration varies sharply across applications, with environmental and regulatory mandates driving government agency procurement distinct from operator-driven reservoir optimization.
- Oil Recovery:Production logging and saturation monitoring optimize primary and enhanced oil recovery operations. United States unconventional operators prioritize real-time data for artificial lift optimization in stripper wells.
- Gas Recovery:Casing integrity verification and flow profiling support coalbed methane and tight gas production. Saudi Aramco drilling and workover specifications mandate specific logging protocols for gas well integrity assurance.
- Environmental Monitoring:Methane leak detection and abandoned well integrity assessment respond to regulatory mandates. North Sea regulators impose methane detection requirements on aging wellbores, extending serviceable populations beyond productive life.
- Well Integrity Assessment:Comprehensive casing, cement, and tubular evaluation for regulatory compliance and abandonment certification. Norway's Petroleum Safety Authority enforces periodic integrity verification through certified logging diagnostics.
Well Integrity Assessment commands premium pricing; Environmental Monitoring is expanding most quickly.
End User:
Supply concentration characterizes this dimension, with integrated service providers capturing share from pure-play contractors through multi-scope bundling and guaranteed response commitments.
- Oil & Gas Operators:Supermajors and independents contract logging services for reservoir surveillance and regulatory compliance. United States independent operators dominate spot market procurement for Permian Basin artificial lift optimization.
- Service Companies:Integrated oilfield service providers subcontract specialized logging capabilities or deploy proprietary toolstrings. Schlumberger Limited and Halliburton Company maintain captive perforating and cement evaluation platforms.
- Government Agencies:Regulatory bodies mandate logging diagnostics for orphan well programs and methane emission verification.
- Research Institutions:Universities and national laboratories develop next-generation sensing technologies and calibration standards.
Oil & Gas Operators dominate procurement volume; Government Agencies are gaining share fastest through regulatory enforcement expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer concentration clusters around national oil companies with mature field portfolios and regulatory mandates for well integrity verification. Procurement authority concentrates in state-directed operators with multi-year surveillance programs and integrated service contracting preferences.
United States
Permian Basin stripper well operators sustain recurring demand for artificial lift diagnostics and production logging services. EPA methane emission regulations and BLM waste prevention rules mandate certified cement evaluation for idle wellbores before abandonment deadlines. Houston anchors the largest concentration of wireline service contractors and calibration facilities serving Gulf of Mexico shelf assets.
Norway
North Sea mature field redevelopment drives scheduled procurement cycles for pulsed-neutron and acoustic logging services. The Petroleum Safety Authority enforces NORSOK D-010 well integrity standards requiring periodic cement bond verification across all producing assets. Stavanger hosts the primary cluster of specialized logging engineers and subsea intervention technology providers.
Saudi Arabia
Saudi Aramco drilling and workover specifications mandate specific logging protocols for gas well integrity assurance and waterflood surveillance in carbonate reservoirs. In-kingdom manufacturing requirements for logging tools create partnership openings for technology licensors seeking localization compliance. Dhahran concentrates the operator's procurement decision-making and technical specification authority.
China
Sinopec and PetroChina deploy cased hole logging for enhanced oil recovery optimization in aging Daqing and Shengli field assets. The Ministry of Ecology and Environment tightens methane leak detection requirements on aging wellbores in key production basins. Tianjin and Beijing host the primary concentration of domestic oilfield service companies developing indigenous logging tool manufacturing.
Brazil
Petrobras pre-salt development programs incorporate permanent fiber optic monitoring systems for real-time well performance tracking in deepwater assets. ANP regulatory mandates strengthen well integrity verification requirements for offshore abandonment certification. Rio de Janeiro anchors the national oil company's procurement authority and deepwater technology qualification programs.
Cased Hole Logging Services Market Competitive Environment
Player mix skews toward integrated oilfield service providers with captive tool manufacturing and multi-scope bundling capabilities. The supplier base compresses under API Q2 certification mandates that force smaller wireline contractors to upgrade quality management systems or exit high-specification contracts entirely. Three archetypes dominate: integrated majors with proprietary platforms, regional specialists with regulatory compliance expertise, and technology licensors pursuing localization partnerships. Competitive moves concentrate on strategic partnerships for in-kingdom manufacturing and portfolio diversification into permanent monitoring infrastructure.
Within the integrated service tier, Schlumberger Limited, Halliburton Company, and Baker Hughes Company exemplify the archetype of providers with captive calibration facilities and certified operator training programs. These companies occupy positions where multi-year well surveillance bundling and guaranteed response-time clauses consolidate procurement authority. Regional specialists such as Weatherford International Plc and China Oilfield Services Limited sit within tiers where geographic proximity and regulatory familiarity anchor competitive positioning against integrated majors.
| Leading Market Players |
|---|
| Weatherford International Plc |
| Superior Energy Services |
| Schlumberger Limited |
| RECON Petrotechnologies Ltd |
| OilServ |
| Halliburton Company |
| China Oilfield Services Limited |
| Nabors Industries Ltd |
| Baker Hughes Company |
| Others |
Value Chain & Pricing Dynamics
Capital intensity of pressure-rated logging trucks and captive calibration facilities creates scale advantages that compress price floors for smaller wireline contractors. API Q2 certification investments and radioactive materials licensing timelines concentrate supply among integrated providers with certified operator training programs, enabling premium pricing on high-specification cement evaluation and production logging contracts.
Pricing Analysis
Cost-plus contracts with day-rate indexation dominate cased hole logging procurement, with pricing stratifying across API Q2-certified premium tiers, standard wireline service tiers, and economy spot-market tiers. Price differentiation rests on certification grade and guaranteed response-time clauses, with integrated providers commanding premiums for bundled perforating and remediation capabilities. Pricing pressure stems from fiber optic distributed sensing displacing conventional spinner-based production logging in Permian Basin horizontal wells. Independent operators exhibit highest price sensitivity on spot-market artificial lift diagnostics, while national oil companies prioritize compliance assurance over rate negotiation.
Supply Chain Analysis
United States and Norway anchor gamma ray detector manufacturing and acoustic tool fabrication for cased hole logging systems. The supply chain draws from licensed cesium-137 and americium-241 suppliers for nuclear logging sources, specialized piezoelectric transducer manufacturers for ultrasonic cement evaluation, and pressure-rated electronics housings from aerospace-qualified machine shops. Single-source vulnerability concentrates in NORM-handling permits and EPA radioactive materials transportation licensing. Distribution runs through integrated service company fleets, regional wireline contractors, and technology licensors pursuing in-kingdom manufacturing partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API Q2-qualified logging engineers and certified calibration technicians represent the critical capability gap constraining crew scaling and market entry. Scarce technical talent concentrates among integrated majors with captive training programs, creating defensive moats against price-based competition.
For Market Incumbents: Compound market position through backward integration into fiber optic cable manufacturing and permanent downhole monitoring system deployment. Acquire regional specialists with NORSOK D-010 compliance expertise to defend against integrated bundling pressure from Halliburton and Schlumberger. Expand captive calibration facility capacity in Stavanger and Dhahran to capture scheduled procurement cycles from Saudi Aramco and Equinor.
For New Entrants and Emerging Players: API Q2 certification fast-track partnerships with established training providers offer the lowest-friction entry path into high-specification contracts. Target environmental monitoring and abandoned well integrity assessment as the most penetrable application segment, where regulatory enforcement expansion outpaces integrated provider capacity. Pursue technology licensing arrangements with Chinese domestic manufacturers to satisfy Sinopec and PetroChina localization requirements without captive tool development.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fiber optic distributed sensing providers with subscription-based data delivery contracts. Long-term viability favors asset-light technology licensors over capital-intensive wireline fleet operators facing utilization cyclicality. Monitor EPA methane emission rule enforcement intensity as the primary inflection signal for cement evaluation and well integrity assessment demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| API Q2 Certification Investment | Quality management system upgrades unlock Saudi Aramco and Equinor high-specification contract eligibility. |
| Fiber Optic Manufacturing Partnership | In-kingdom cable production satisfies Saudi Aramco localization mandates for permanent monitoring deployment. |
| Calibration Facility Expansion | Captive tool verification capabilities reduce third-party dependency and accelerate response-time guarantees. |
| Environmental Monitoring Service Launch | EPA methane compliance deadlines extend addressable well populations beyond productive economic life. |
| Digital Twin Platform Integration | Real-time fiber optic data feeds enable subscription-based reservoir performance monitoring contracts. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with wireline service company executives, petroleum engineers at Permian Basin independents, regulatory compliance officers at national oil companies, and procurement managers at integrated majors. Secondary validation incorporated API specification documents, NORSOK D-010 well integrity standards, Saudi Aramco drilling and workover specifications, EPA methane emission regulations, and SEC filings from publicly traded oilfield service providers. Bottom-up segmentation analysis triangulated against top-down macroeconomic indicators across the energy services sector.
Across the analysis window, the forecasting framework modeled service type, technology platform, application scope, and end-user category dimensions alongside regional regulatory cluster variations. CAGRs were derived from historical demand pattern analysis and forward-looking procurement cycle assessment. Forecast inputs incorporated mature field redevelopment capital allocation schedules, fiber optic installation growth trajectories, and well integrity mandate enforcement timelines from the Petroleum Safety Authority and BLM.
Underlying assumptions cover regulatory enforcement continuity, radioactive materials licensing stability, and oil price band maintenance, with deviation risk concentrated in NOC localization policy acceleration and fiber optic technology substitution rates. Recalibration cycles align with material shifts in EPA rulemaking, NORSOK standard revisions, and Saudi Aramco in-kingdom manufacturing requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Drilling Services Market
Oil & Gas
Nigeria Oil and Gas Midstream Market
Oil & Gas
Hydraulic Fracturing Market
Oil & Gas
Global Artificial Lift Market
Oil & Gas
Oil and Gas EPC Market
Oil & Gas
Containment and Handling Drilling Waste Management Market
Oil & Gas
Whipstocks Market
Oil & Gas
Oil and Gas Infrastructure Market
Oil & Gas
Exploration and Drilling Security Market
Oil & Gas
Digital Oilfield Services Market
Oil & Gas
Oilfield Drill Bits Sales Market
Oil & Gas
Russian Federation Oil and Gas Midstream Market
Oil & Gas
FTIR Oil Condition Monitoring Market
Oil & Gas
Hydrocracking Market
Oil & Gas
Modular Gas Processing Plants Market
Oil & Gas
Europe Well Intervention Market