
 Seismic Survey Equipment Market | 2026-2036
Seismic Survey Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Seismic Survey Equipment Market Intelligence
The integration of wireless and autonomous nodal acquisition systems is reshaping how seismic data is collected in challenging terrains and deepwater environments. Sercel SAS specializes in high-density land and marine acquisition systems, pushing the boundaries of survey resolution. Geospace Technologies Corporation leverages its expertise in seismic sensor and wireless data recording technology for oil and gas exploration. Meanwhile, Fugro N.V. dominates the geotechnical investigation and asset integrity segments with its integrated survey services.
Seismic survey equipment comprises devices used to generate and record seismic waves for subsurface imaging. These systems, including geophones and hydrophones, measure acoustic energy reflections with sensitivities often below 10 Hz to map geological structures. The primary purpose is to create detailed models of the Earth's subsurface for resource exploration and hazard assessment. Hydrocarbon exploration remains the largest application, though mineral exploration and geotechnical investigation represent the fastest-growing segments. Digital and wireless technologies are rapidly displacing older analog equipment.
Environmental regulations, such as those enforced by the U.S. EPA and through EU directives on offshore exploration, mandate low-impact survey methodologies. Concurrently, adherence to ISO standards for equipment calibration and data quality is critical for securing contracts with major geophysical contractors and research institutes. Navigating the balance between high-resolution data acquisition for complex reservoirs and minimizing environmental footprints will define future equipment design and operational strategies for all market participants.
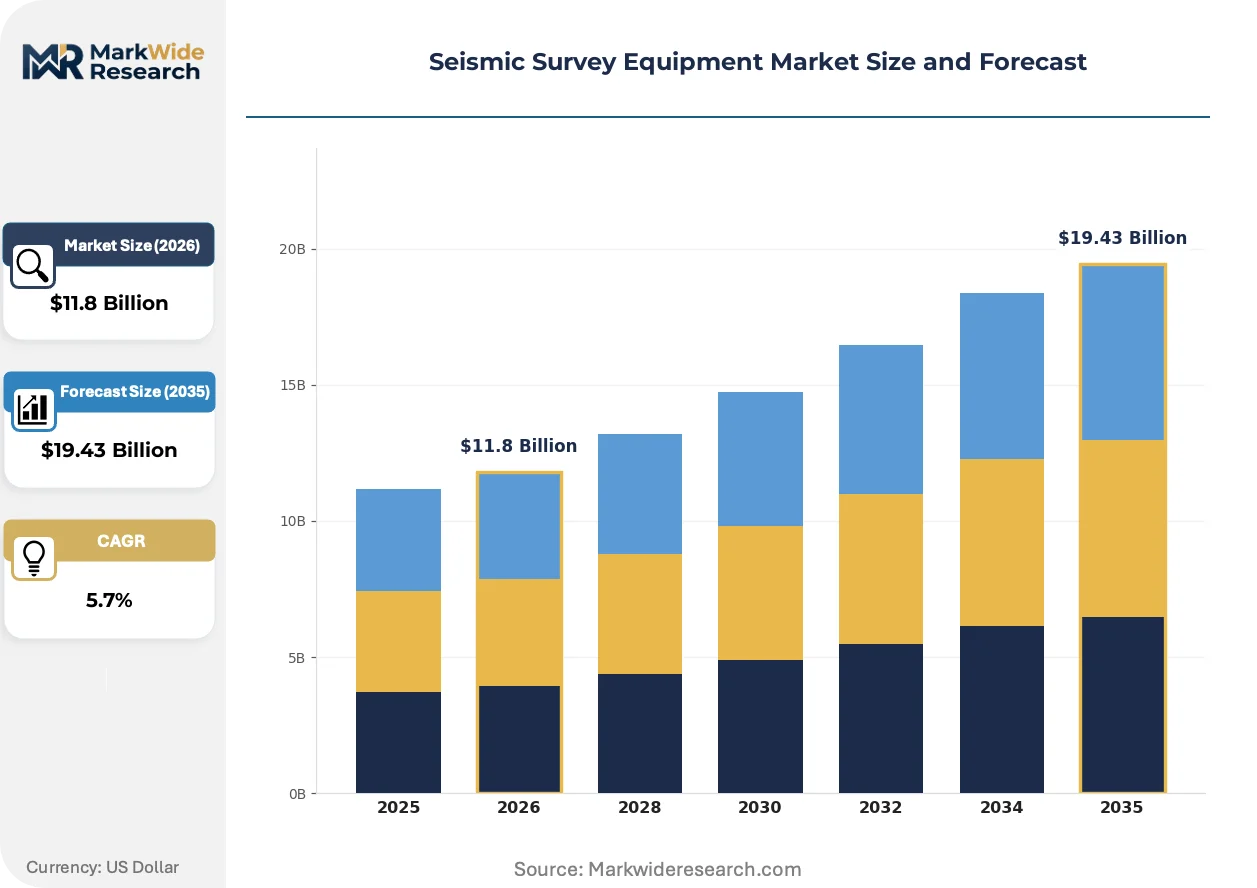
Market Dynamics
The expansion into complex geological environments and non-traditional applications like carbon capture and storage is the central force in the seismic survey equipment market. This demands higher-resolution data, pushing equipment design toward greater sensitivity and lower environmental impact simultaneously.
Growth Catalysts
- Infrastructure Investment:Government-backed infrastructure programs, such as those in India and the United States, mandate extensive geotechnical investigations for tunnels and bridges, directly fueling demand for shallow seismic survey equipment.
- Renewable Energy Siting:The global expansion of offshore wind energy requires detailed seabed characterization to ensure turbine foundation stability, creating a significant new application segment for high-resolution marine seismic systems.
- Deepwater Exploration:Continued exploration in complex deepwater basins, particularly Brazil's pre-salt fields, necessitates advanced technologies like ocean-bottom nodes to overcome challenges posed by salt canopies and achieve accurate reservoir imaging.
Market Restraints
- High Capital Expenditure:The significant upfront investment required for next-generation nodal and fiber-optic seismic systems creates a high barrier to entry for smaller geophysical contractors and limits fleet modernization.
- Environmental Regulations:Stringent environmental mandates, including the EU's Marine Strategy Framework Directive, restrict acoustic source usage and survey timing, increasing project complexity and operational costs for marine seismic operators.
- Alternative Technologies:Increasing use of satellite-based interferometric synthetic-aperture radar (InSAR) for surface deformation monitoring presents a substitution risk for some time-lapse and geotechnical survey applications.
Strategic Opportunities
- Carbon Sequestration Monitoring:The global push for CCUS projects creates a new, long-term market for time-lapse seismic surveys to monitor CO2 plume migration and ensure storage integrity in subsurface reservoirs.
- Critical Mineral Exploration:Demand for minerals essential for the energy transition is opening opportunities for seismic methods in hard-rock environments, particularly in resource-rich but under-explored regions of Australia and Canada.
- AI-Powered Processing:Integrating artificial intelligence algorithms into data processing workflows offers the potential to automate quality control and accelerate the interpretation of vast, high-density seismic datasets.
Industry Challenges
- Data Management Bottlenecks:The terabyte-scale datasets generated by high-density land and marine surveys create significant challenges for data telemetry, storage, and processing, demanding substantial investment in IT infrastructure.
- Specialized Talent Scarcity:A shortage of geophysicists and data scientists with expertise in both advanced seismic acquisition techniques and machine learning hinders the full exploitation of next-generation equipment capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seismic Survey Equipment Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $19.43 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seismographs, Hydrophones, Geophones, Accelerometers, Vibroseis, Cable Systems Technology: Analog, Digital, Wireless, Fiber Optic, Multicomponent, MEMS Application: Subsurface Mapping, Hydrocarbon Exploration, Mineral Exploration, Earthquake Monitoring, Environmental Assessment, Geotechnical Investigation End User Industry: Oilfield Services, Mining Operators, Research Institutes, Construction Firms, Geophysical Contractors, Environmental Agencies |
| Companies Covered | Geospace Technologies Corporation, ION Geophysical Corporation, Schlumberger Limited, DAWSON Geophysical Company, Petroleum Geo-Services ASA, CGG S.A., Fugro N.V., Magseis Fairfield AS, Sercel SAS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seismic Survey Equipment Market Strategic Shifts & Innovations
The pursuit of a high-fidelity digital subsurface model is driving equipment evolution. This involves a convergence of advanced sensor physics with powerful data analytics, transforming how seismic surveys are planned, executed, and interpreted across multiple industries.
Distributed Acoustic Sensing (DAS) repurposes fiber-optic cables into dense arrays of seismic sensors capable of recording strain changes. Adoption is accelerating in oil and gas for downhole monitoring and in civil engineering for tracking infrastructure integrity. The technology is digitizing linear infrastructure like pipelines and wells, transforming them into continuous, high-resolution seismic receivers.
Environmental regulations, such as those from the U.S. EPA governing offshore operations, mandate methodologies that minimize acoustic impact on marine ecosystems. This pressure spurs development of marine vibroseis and other low-impact sound sources as alternatives to traditional air guns. The marine exploration segment is most affected, shifting equipment investment toward technologies compliant with stricter environmental standards.
A shift from direct equipment procurement to integrated, data-centric service models is gaining traction among end-users. This model replaces capital expenditure on hardware in favor of contracts where geophysical service companies manage the entire workflow from acquisition to interpretation. The trend is most visible in the geotechnical investigation sector, where clients often lack specialized geophysical expertise.
Seismic Survey Equipment Market Segmentation
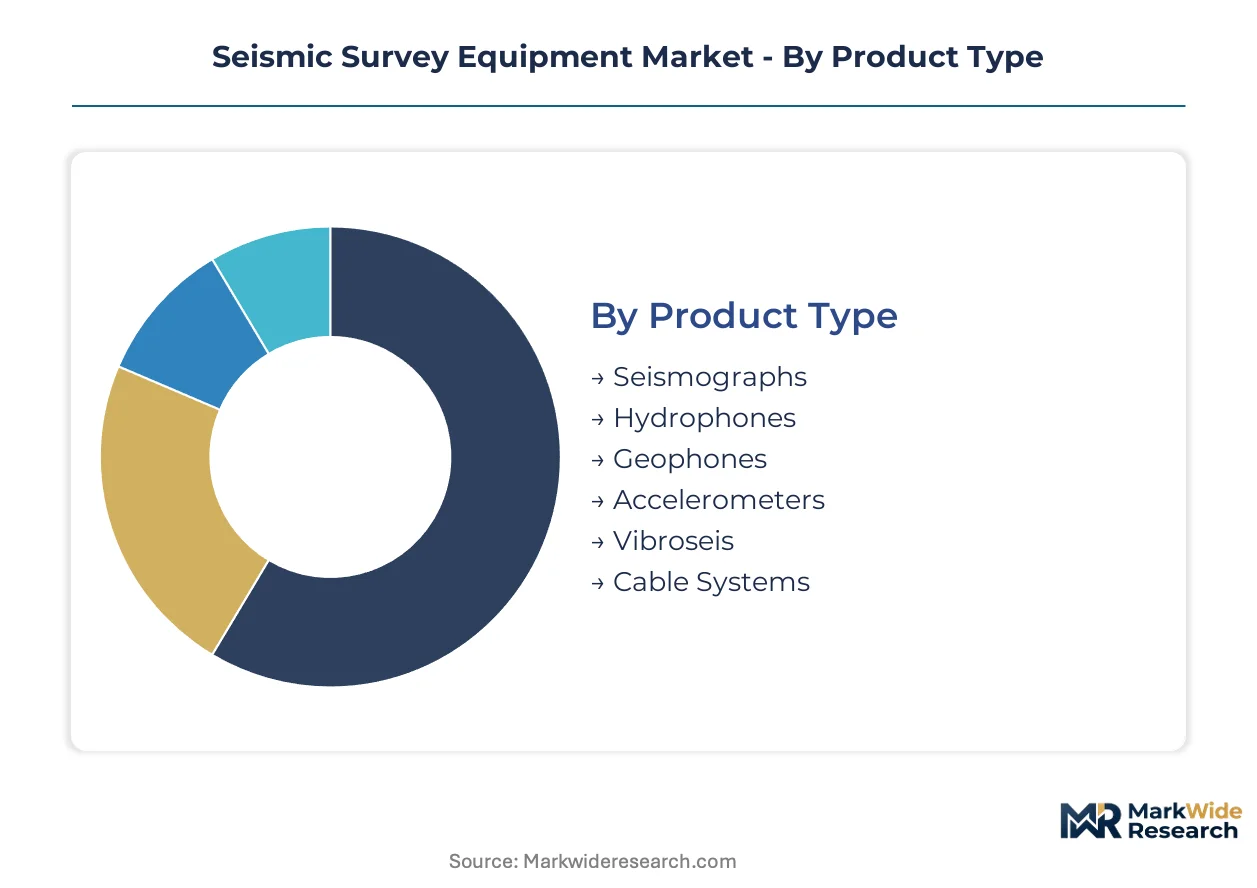
The seismic survey equipment market is highly diversified, reflecting the varied geological challenges and application requirements across different industries. Understanding these distinct segments allows stakeholders to identify specific technological needs, investment priorities, and evolving demand patterns. Each segment presents unique operational considerations, influencing equipment design and service delivery.
Product Type:
Some seismic survey equipment types exhibit rapid innovation cycles, while others maintain longer lifespans due to their fundamental operational roles.
- Geophones:These ground motion sensors convert seismic waves into electrical signals for land-based surveys. Demand concentrates in geotechnical investigations in the United States, driven by extensive road and bridge construction projects.
- Hydrophones:These underwater acoustic sensors detect pressure changes from seismic waves in marine environments. Offshore energy development in Brazil drives demand, particularly for pre-salt field imaging.
- Seismographs:Instruments record and display seismic waves, providing foundational data for geological analysis.
- Accelerometers:These sensors measure ground acceleration, offering complementary data in high-frequency seismic studies.
- Vibroseis:Mobile vibrator trucks generate controlled seismic energy, minimizing environmental impact in sensitive areas.
- Cable Systems:These connect arrays of sensors to recording units, facilitating data transmission in large-scale surveys.
Geophones anchor the volume base while Vibroseis gains share at the steepest rate.
Technology:
Technology segments reflect varying stages of maturity, from established methods to disruptive innovations fundamentally altering data acquisition.
- Wireless:These systems transmit seismic data without physical cables, streamlining deployment in complex terrains. Infrastructure projects in India drive demand for flexible, high-density land surveys.
- Fiber Optic:Distributed Acoustic Sensing (DAS) repurposes fiber optic cables into dense sensor arrays, offering continuous, high-resolution monitoring. Oil and gas companies use this for downhole well integrity monitoring.
- Analog:Older technology involves physical signal transmission, still present in some legacy systems for basic surveys.
- Digital:Converts seismic signals to digital format, improving data quality and compatibility with modern processing.
- Multicomponent:Records seismic waves in multiple directions (P and S waves), enhancing subsurface characterization for complex reservoirs.
- MEMS:Micro-Electro-Mechanical Systems sensors offer compact, low-power alternatives to traditional geophones, improving array density.
Digital technologies offer enhanced data quality and processing efficiency, while MEMS-based sensors provide superior precision for high-resolution imaging.
Application:
Demand for seismic survey applications is increasingly driven by both traditional resource extraction and emerging environmental and infrastructure needs.
- Hydrocarbon Exploration:This application uses seismic data to locate and characterize oil and gas reservoirs. Deepwater basins off Brazil require advanced seismic imaging to navigate complex salt structures.
- Geotechnical Investigation:This involves mapping shallow subsurface conditions for civil engineering projects. Large-scale infrastructure programs in the United States mandate detailed subsurface analysis for tunnels and bridges.
- Subsurface Mapping:Provides general geological models for various planning and resource assessment purposes.
- Mineral Exploration:Identifies potential mineral deposits in hard-rock environments, particularly for critical minerals in Australia.
- Earthquake Monitoring:Detects and analyzes seismic events for hazard assessment and structural engineering considerations.
- Environmental Assessment:Evaluates geological stability and potential hazards for environmental impact studies, often for renewable energy projects.
Hydrocarbon Exploration constitutes the largest application segment, while Geotechnical Investigation and Mineral Exploration exhibit the strongest growth trajectory.
End User Industry:
End-user industries vary significantly in their specialized requirements, from highly technical exploration to broad infrastructure development.
- Oilfield Services:These companies specialize in providing equipment and services for oil and gas drilling and production. Demand for advanced deepwater seismic systems is high for complex reservoir characterization.
- Geophysical Contractors:These firms acquire and process seismic data for diverse clients across multiple sectors. They increasingly require high-density acquisition systems for improved data resolution.
- Mining Operators:Utilize seismic surveys to identify and delineate mineral deposits, supporting efficient resource extraction.
- Research Institutes:Conduct fundamental and applied seismic research, often developing new sensor technologies and processing methods.
- Construction Firms:Employ shallow seismic techniques for site characterization, ensuring structural integrity for major projects.
- Environmental Agencies:Use seismic data for hazard assessment and monitoring, particularly for carbon capture and storage initiatives.
Oilfield Services represent an established end-user base, whereas Environmental Agencies are an emerging segment with increasing demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for seismic survey equipment concentrates in regions with extensive natural resource exploration and critical infrastructure development programs. Brazil's deepwater energy sector, the United States' infrastructure initiatives, India's large-scale construction projects, and Australia's mineral exploration drive significant market activity. These diverse applications highlight the varied technological requirements across different geographical contexts.
Brazil
Deepwater exploration in Brazil's pre-salt fields necessitates advanced seismic imaging technologies like ocean-bottom nodes. The country's national oil company, Petrobras, drives substantial investment in sophisticated marine survey capabilities. Rio de Janeiro serves as a hub for offshore energy companies, focusing on complex reservoir characterization for hydrocarbon production.
United States
The United States' infrastructure programs mandate extensive geotechnical investigations for tunnels and bridges. The U.S. EPA regulations also influence environmental assessment requirements for renewable energy projects. Major engineering firms in Texas and California frequently deploy shallow seismic survey equipment for site characterization and hazard assessment.
India
Extensive government-backed infrastructure programs in India, such as highway and railway expansions, fuel demand for flexible, high-density land survey equipment. The country's Bureau of Indian Standards (BIS) guides quality and safety for construction materials and methodologies. Delhi and Mumbai see significant activity from construction firms requiring detailed subsurface analysis for urban development.
Australia
Critical mineral exploration in Australia creates new opportunities for seismic methods in hard-rock environments. The Australian government's focus on resource security supports advanced geological mapping initiatives. Mining operators in Western Australia actively use seismic surveys to identify and delineate new mineral deposits.
Seismic Survey Equipment Market Key Industry Players
Channel-controlling players compete with product-specialist players across the seismic survey equipment market. The market structure involves a mix of large integrated service providers and specialized equipment manufacturers. Strategic archetypes include global geophysical contractors, niche sensor technology developers, and regional service companies. Competitive moves often involve portfolio diversification into non-hydrocarbon applications and strategic partnerships for technology co-development.
Specialists in advanced acquisition systems include Sercel SAS, known for high-density land and marine solutions. Geospace Technologies Corporation occupies a position in seismic sensor and wireless data recording technology. Fugro N.V. anchors the integrated survey services segment, particularly for geotechnical investigation and asset integrity, across various end-user industries.
| Leading Market Players |
|---|
| Geospace Technologies Corporation |
| ION Geophysical Corporation |
| Schlumberger Limited |
| DAWSON Geophysical Company |
| Petroleum Geo-Services ASA |
| CGG S.A. |
| Fugro N.V. |
| Magseis Fairfield AS |
| Sercel SAS |
| Others |
Cost & Logistics Intelligence
The global shipping lanes, particularly those connecting Asian manufacturing hubs to Western markets, dictate component costs for seismic equipment, influencing supply concentration and downstream project-based pricing differentiation.
Pricing Analysis
Cost-plus contracts, often indexed to raw material prices like rare earth elements and specialized electronics, dominate the seismic survey equipment market. Price differentiation stems from sensor precision and after-sales service bundles, particularly for high-resolution deepwater systems. Pricing pressure intensifies in the analog equipment segment due to rapid digital technology displacement. Geophysical contractors seeking basic survey tools exhibit the highest price sensitivity, while oilfield services prioritize advanced capabilities over cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are increasingly crucial for manufacturers sourcing complex components. Geographic supply concentrates in China for electronics and Germany for precision engineering, with specialized sensor manufacturing in the United States. Raw material dependencies include specialized alloys for geophone casings and fiber optic cables for DAS systems. Single-source vulnerability for advanced sensor components presents a structural risk, with distribution running primarily through direct sales channels to major geophysical contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The seismic survey equipment market is experiencing a shift in buyer power, driven by the consolidation of major geophysical contractors.
For Market Incumbents: Build intellectual property moats through continuous R&D in fiber optic and MEMS sensor technologies. This counters commoditization from generic digital systems, maintaining a competitive edge in high-resolution data acquisition. Strategic partnerships for software integration and data analytics serve as a critical lever for expanding service offerings.
For New Entrants and Emerging Players: Geotechnical investigation for renewable energy projects, particularly offshore wind farm siting, represents the most penetrable entry point. Focus on developing low-impact marine vibroseis solutions to meet stringent environmental regulations. A go-to-market angle emphasizing integrated data processing services differentiates offerings for construction firms.
For Investors and Strategic Acquirers: Niche technology developers specializing in AI-powered data processing and autonomous nodal systems offer long-term viability over a 5-10 year window. These firms provide critical capabilities for managing terabyte-scale datasets and accelerating interpretation. Increasing adoption of distributed acoustic sensing (DAS) technology serves as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Data Analytics Integration | Integrating AI algorithms enhances quality control and accelerates the interpretation of vast seismic datasets. |
| Low-Impact Source Development | Developing marine vibroseis alternatives addresses environmental concerns and expands access to regulated offshore areas. |
| Autonomous System R&D | Investing in autonomous nodal systems streamlines deployment in challenging terrains and reduces operational costs. |
| Fiber Optic Sensor Expansion | Expanding fiber optic sensor applications into infrastructure monitoring creates new revenue streams beyond traditional exploration. |
| Geotechnical Service Bundling | Bundling equipment with interpretation services captures value from end-users lacking specialized geophysical expertise. |
Research Approach
Initial hypotheses were tested against primary input from geophysicists, oilfield service executives, and civil engineering project managers, then refined through iterative secondary validation. This involved extensive review of geological surveys, energy exploration reports, and infrastructure development plans. Bottom-up data collection from equipment manufacturers and top-down market sizing from industry associations ensured robust triangulation.
Demand-supply balance modeling formed the core analytical framework across the projection horizon. Segmentation dimensions included product type, technology, application, end-user industry, and regional regulatory compliance. Compound annual growth rates were derived from historical data analysis and projected technological adoption curves, with key inputs like exploration spending and infrastructure investment forecasts.
Macroeconomic conditions sit as an overlay; deviation in global energy prices or infrastructure spending would shift the trajectory. Forecasts reflect assumptions regarding technological advancements and environmental policy. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Wired Drill Pipe Sales Market
Oil & Gas
Europe Seismic Survey Market
Oil & Gas
Frac Tree Market
Oil & Gas
Gulf of Mexico Oil and Gas Midstream Market
Oil & Gas
South America Intelligent Pigging Market
Oil & Gas
Asia-Pacific Small-Scale LNG Market
Oil & Gas
Oilfield Roller Chain Market
Oil & Gas
Electric Fracking Market
Oil & Gas
Intelligent Completion Sales Market
Oil & Gas
Well Abandonment Services Market
Oil & Gas
North America Hydraulic Fracturing Fluids Market
Oil & Gas
Coal Mining Market
Oil & Gas
Oil and Gas Separator Market
Oil & Gas
Oil Well Cement Market
Oil & Gas
Indonesia Oil and Gas Midstream Market
Oil & Gas
Europe Oilfield Chemicals Market