
 Crude Oil Market | 2026-2036
Crude Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Crude Oil Market Intelligence
Profitability from conventional upstream extraction is tilting towards specialized enhanced oil recovery technologies and integrated downstream chemical production. This shift favors companies with deep technical expertise and capital discipline. Saudi Aramco leverages its unparalleled low-cost production and extensive reserve base to influence market supply. ExxonMobil specializes in executing large-scale, technologically complex projects globally, while Shell positions its portfolio to capture value in deepwater exploration and integrated gas.
Crude oil is a naturally occurring fossil fuel, a complex mixture of hydrocarbons that forms in underground reservoirs. Its quality is defined by properties like API gravity and sulfur content, which directly influence its processing requirements and market price. Light sweet crudes are preferred for refining into high-value transportation fuels like gasoline. The market for petrochemical feedstock applications is expanding, driven by non-fuel chemical manufacturing, and represents the fastest-growing demand segment.
A complex web of regulations governs exploration, production, and transport. The US EPA mandates strict environmental standards for drilling, while the EU Green Deal pressures refiners to reduce their carbon footprint. In China, the MEE's enforcement of dual carbon goals directs investment toward cleaner production methods and energy efficiency. Future capital allocation decisions now hinge on accurately forecasting the pace of divergent regional energy transitions and their impact on long-term asset viability.
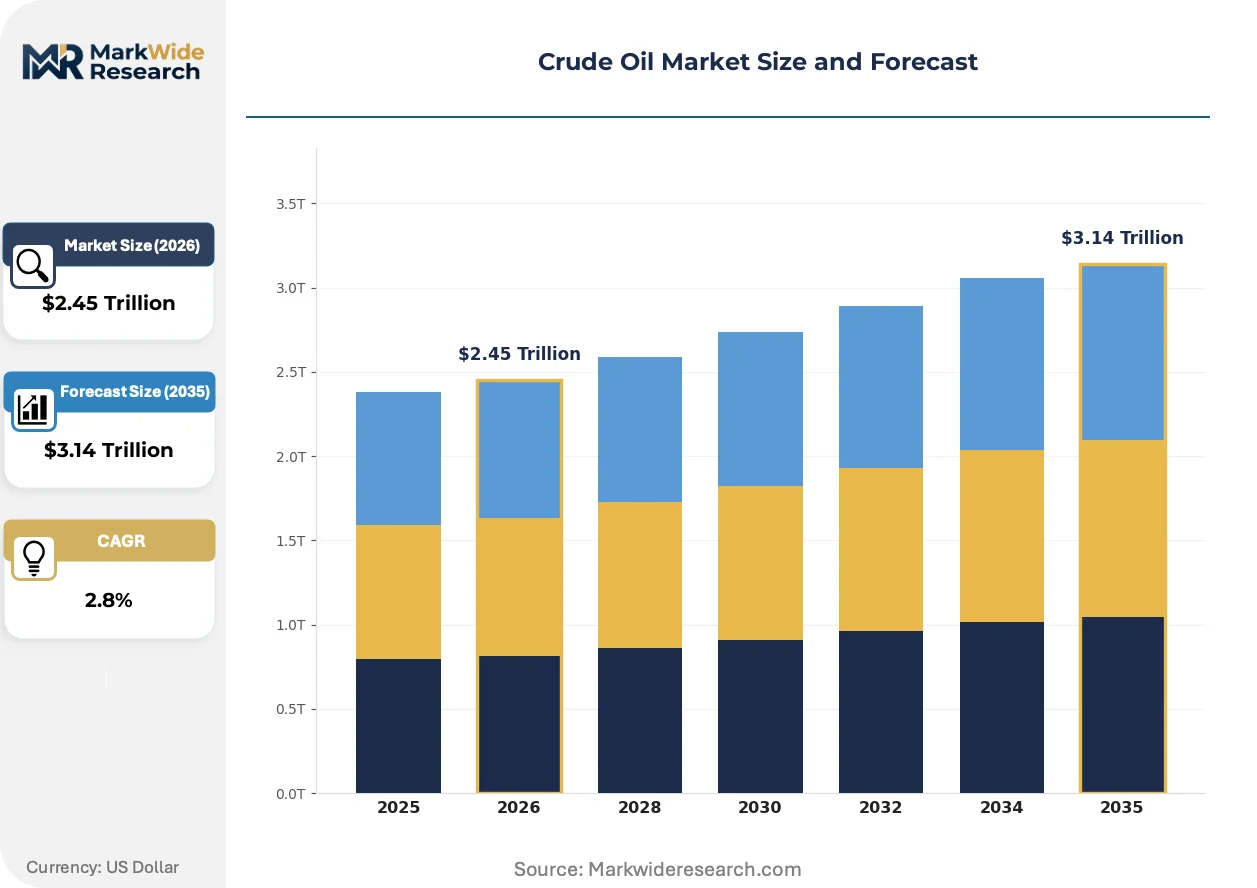
Market Dynamics
The crude oil market's core dynamic is the tension between long-cycle upstream capital investments and the uncertain velocity of divergent regional energy transitions. This creates a complex risk environment where accurately forecasting long-term asset viability is paramount for capital allocation.
Growth Catalysts
- Petrochemical Feedstock Demand:Sustained expansion in the manufacturing of plastics, fertilizers, and advanced composites, particularly in China and India, provides a foundational volume floor for crude oil consumption, independent of transportation fuel trends.
- Enhanced Oil Recovery (EOR):Advanced EOR technologies, including chemical and CO2 injection, unlock additional production from mature and previously non-viable fields, improving asset returns and extending the productive life of existing reserves.
- Infrastructure Development:Large-scale transportation and industrial infrastructure projects in developing economies across Southeast Asia and Africa underpin baseline demand for diesel, bitumen, and other industrial fuels, supporting crude oil volumes.
Market Restraints
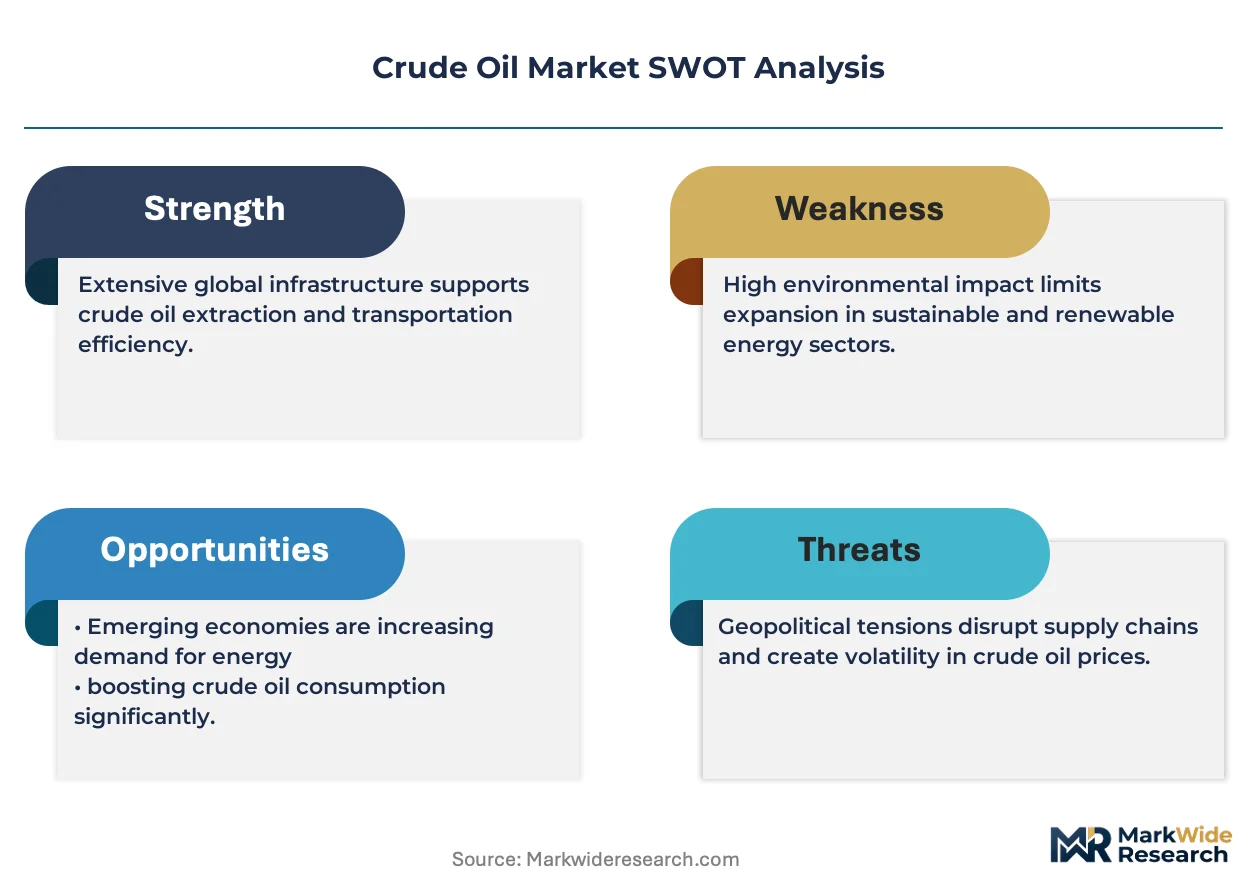
- Regulatory Pressure on Carbon:Mandates like the EU Green Deal and emissions reduction targets in other OECD nations impose significant compliance costs on refiners and producers, forcing investment in lower-carbon processes and potentially stranding carbon-intensive assets.
- Transportation Fuel Substitution:The accelerating adoption of electric vehicles and the increasing use of biofuels directly displace gasoline and diesel demand, eroding a core market segment, especially in developed economies.
- High Upstream Capital Costs:Exploration and development in frontier areas like ultra-deepwater and the Arctic require massive, long-term capital commitments with significant geological and political risk, deterring investment without high price certainty.
Strategic Opportunities
- Carbon Capture and Storage Integration:Leveraging depleted oil and gas reservoirs for large-scale Carbon Capture, Utilization, and Storage (CCUS) projects creates a new service-based revenue stream and helps decarbonize existing operations.
- Digitalization of Operations:The convergence of AI-powered analytics, IoT sensors, and robotics in upstream and downstream operations offers significant opportunities to improve drilling efficiency, predictive maintenance, and supply chain logistics.
- Specialty Chemical Production:Shifting refinery outputs toward high-value petrochemical intermediates for specialty applications, such as advanced polymers and performance materials, captures higher margins than traditional fuels.
Industry Challenges
- Workforce Skill Gaps:A persistent challenge is attracting and retaining talent with expertise in both petroleum engineering and data science, which is critical for implementing digital oilfield strategies and optimizing complex operations.
- Refinery Modernization Capex:The capital intensity of reconfiguring refineries to process lighter, sweeter crudes or to meet stricter fuel specifications, such as low-sulfur marine fuels, presents a major financial hurdle for operators with older assets.
- Managing Social License:Navigating intense public scrutiny and investor demands related to environmental, social, and governance (ESG) performance requires sophisticated stakeholder engagement and transparent reporting on emissions and environmental impact.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crude Oil Market |
| Market Size in 2026 | $2.45 Trillion |
| Market Size in 2035 | $3.14 Trillion |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Light Sweet, Heavy Sour, Medium, Extra Heavy, Synthetic Application: Refining, Petrochemical Feedstock, Lubricant Production, Asphalt Manufacturing, Power Generation Production Method: Conventional Drilling, Hydraulic Fracturing, Steam Injection, Cyclic Steam Stimulation, Enhanced Oil Recovery End User: Refineries, Petrochemical Plants, Power Utilities, Construction Firms, Industrial Manufacturers |
| Companies Covered | Saudi Aramco, ExxonMobil, Chevron, PetroChina, Shell, TotalEnergies, CNOOC, ConocoPhillips, BP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crude Oil Market Strategic Shifts & Innovations
The market is defined by a strategic bifurcation, where producers are simultaneously optimizing legacy hydrocarbon assets for cash flow while selectively investing in low-carbon technologies and chemical value chains. This dual-track approach reflects deep uncertainty about the pace of regional energy policy implementation.
Digital twin technology creates a real-time, data-fed virtual replica of a physical asset, such as a reservoir or a refinery processing unit. Major integrated and national oil companies are rapidly adopting this approach to simulate operational scenarios and predict performance. This predictive capability is rendering obsolete traditional static reservoir modeling and reactive, schedule-based maintenance programs by enabling proactive optimization.
China's MEE-enforced dual carbon goals are compelling a systemic shift in the country's refining and petrochemical industry. This policy forces state-owned and private enterprises to accelerate investments in energy efficiency, green hydrogen production, and carbon capture projects. The domestic refining sector is the most affected, responding by altering its output to favor a higher yield of petrochemicals over transportation fuels.
A notable shift in purchasing behavior involves buyers, especially independent refiners in Asia, moving away from rigid, long-term contracts. This preference for spot-market purchases and more flexible, shorter-term supply agreements is disrupting the historical pricing power of national oil producers. This trend is most visible in the competitive Atlantic Basin market, where refiners constantly optimize their crude slate for maximum margin capture.
Crude Oil Market Segmentation
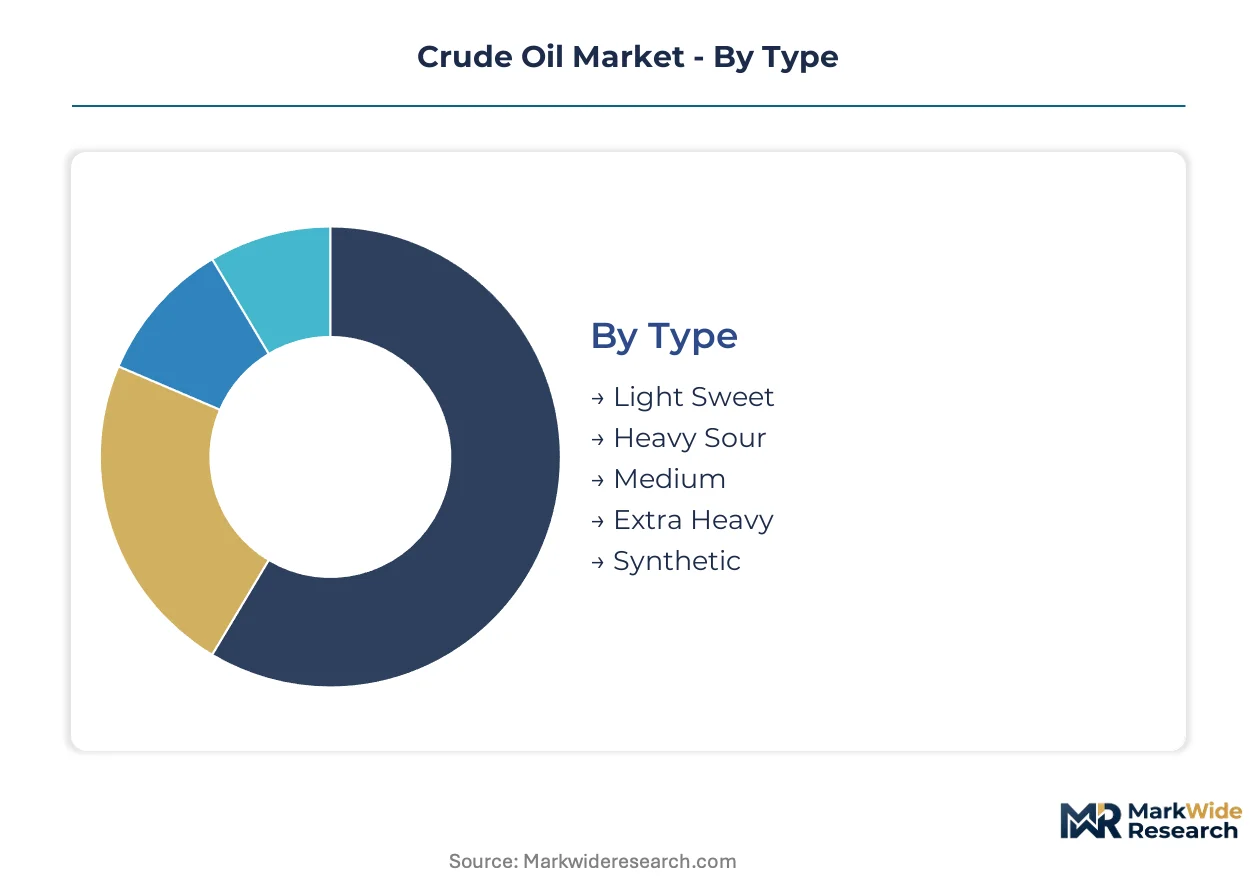
The crude oil market's intricate structure necessitates detailed segmentation to understand demand drivers and supply dynamics. This analysis breaks down the market by key characteristics, revealing distinct value pools and operational considerations. Identifying these segments helps stakeholders align capital allocation with evolving industry trends.
Type:
The crude oil market features a spectrum of crude types, ranging from mature, high-demand light sweet varieties to emerging, technically challenging extra heavy grades.
- Light Sweet:These crudes possess low density and sulfur content, making them highly desirable for producing high-value transportation fuels like gasoline and diesel in established refining centers. Demand concentrates in developed economies with sophisticated refining capacities.
- Heavy Sour:Characterized by high density and sulfur content, these crudes require more complex and capital-intensive refining processes to remove impurities. Demand is robust in regions like the US Gulf Coast and Asia, where refiners have invested in specialized coking and hydrocracking units.
- Medium:These crudes fall between light and heavy, offering a balanced yield of various refined products.
- Extra Heavy:This crude type is extremely viscous and dense, requiring significant upgrading before conventional refining.
- Synthetic:Derived from oil sands or coal, synthetic crude is a processed product rather than a naturally occurring crude oil.
Light Sweet retains volume leadership; Synthetic crude holds the steepest expansion curve due to unconventional resource development.
Application:
Crude oil finds diverse applications, from traditional fuel production to specialized chemical manufacturing, each with unique processing requirements and market values.
- Refining:This primary application converts crude oil into a wide range of petroleum products, including gasoline, diesel, and jet fuel, meeting global energy demand. Demand for refined products remains concentrated in developing economies like China and India, underpinning baseline crude consumption.
- Petrochemical Feedstock:Crude oil derivatives serve as essential building blocks for plastics, fertilizers, and advanced composites. This segment represents the fastest-growing demand for crude oil, driven by non-fuel chemical manufacturing.
- Lubricant Production:Specific crude fractions are refined to create base oils for various industrial and automotive lubricants.
- Asphalt Manufacturing:Heavy crude residues are processed into bitumen for road construction and roofing materials.
- Power Generation:Residual fuel oil from crude refining can be burned directly for electricity production in some industrial and utility settings.
Refining applications command the largest market share, while petrochemical feedstock applications offer superior margin capture.
Production Method:
Production methods for crude oil span a broad spectrum, from low-cost conventional extraction to more capital-intensive enhanced recovery techniques.
- Conventional Drilling:This traditional method involves drilling vertical or directional wells into permeable reservoirs to extract crude oil using natural pressure or pumps. It remains the backbone of global oil supply, characterized by established infrastructure and predictable output.
- Enhanced Oil Recovery:EOR technologies, such as chemical injection or CO2 flooding, increase crude oil recovery from mature fields beyond primary and secondary methods. These methods extend asset life and improve overall resource utilization in regions like the Permian Basin.
- Hydraulic Fracturing:This technique involves injecting high-pressure fluid to fracture rock formations, releasing trapped oil and gas.
- Steam Injection:Used primarily for heavy oil, steam injection reduces crude viscosity, allowing it to flow more easily to the surface.
- Cyclic Steam Stimulation:This method involves injecting steam into a well, allowing it to soak, and then producing the heated oil.
Conventional drilling methods provide foundational supply, but long-term investment increasingly targets enhanced oil recovery for asset life extension.
End User:
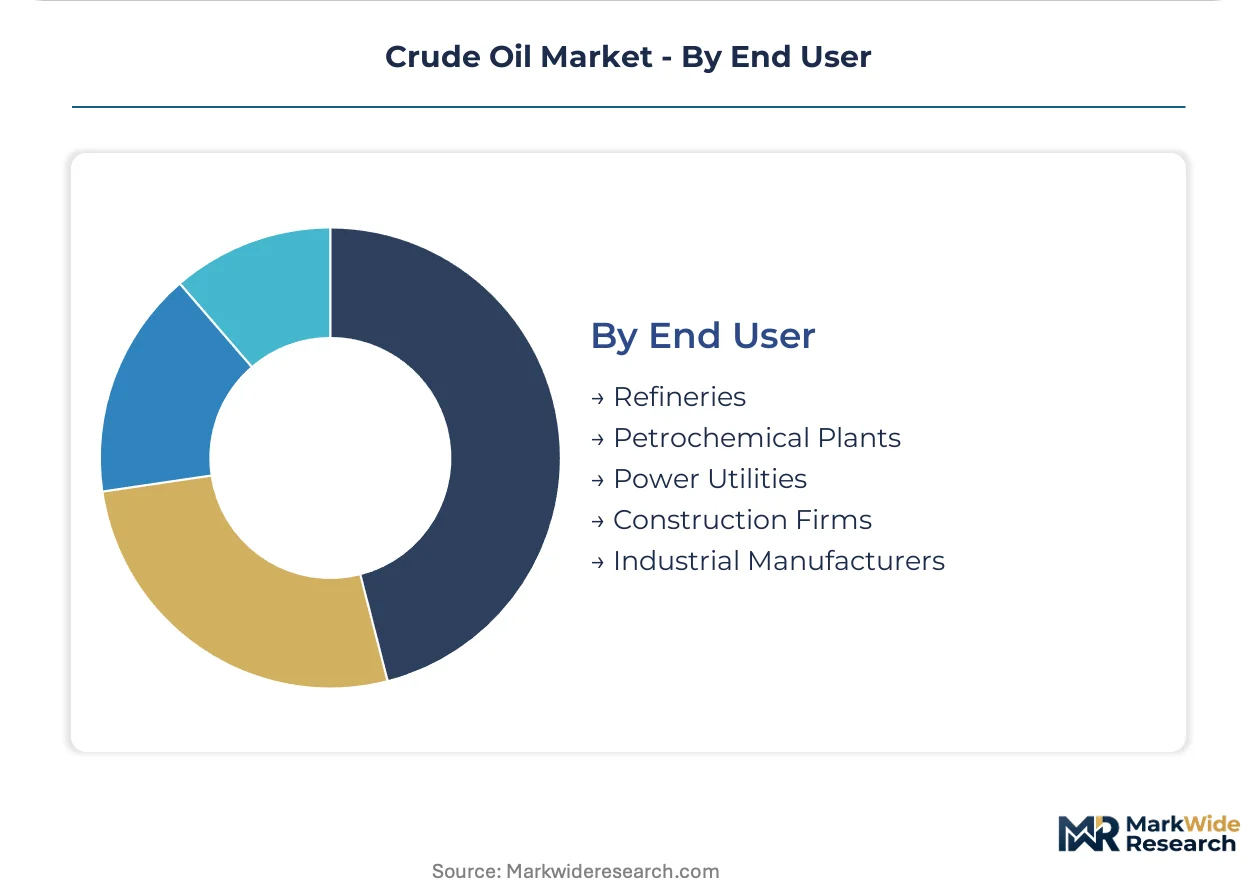
The crude oil market serves a diverse array of end users, each integrating crude derivatives into their specific industrial processes and product lines.
- Refineries:These facilities are the primary processors of crude oil, converting it into a wide range of fuels and intermediate products. Large integrated refineries in Asia and the US Gulf Coast drive significant crude demand.
- Petrochemical Plants:These industrial complexes utilize naphtha and other crude-derived feedstocks to produce chemicals, polymers, and plastics. Investment in new petrochemical capacity, especially in China, is a major demand driver.
- Power Utilities:Some power plants use heavy fuel oil, a crude derivative, for electricity generation.
- Construction Firms:These companies utilize asphalt and other petroleum-based products for infrastructure development.
- Industrial Manufacturers:Various industries consume fuel oils, lubricants, and chemical derivatives from crude oil in their operations.
Refineries represent the largest volume consumers, with petrochemical plants holding increasing strategic importance for future demand growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The crude oil market exhibits a differential in consumption patterns, with developing economies heavily relying on transportation fuels while developed nations pivot towards petrochemical feedstocks. This divergence influences regional investment priorities and regulatory landscapes. Future growth in specific regions depends on their energy transition pace.
China
Demand for petrochemical feedstock and industrial fuels underpins crude oil consumption in China. The MEE's dual carbon goals accelerate investments in energy efficiency and green hydrogen production within the refining sector. Refining hubs like those in Shandong province are reconfiguring operations to favor higher petrochemical yields over traditional fuels.
United States
Transportation fuel demand and expanding petrochemical manufacturing drive crude oil consumption across the United States. The US EPA mandates strict environmental standards for drilling operations, impacting production costs and methods. The Permian Basin in Texas and New Mexico increasingly relies on enhanced oil recovery technologies to extend asset life.
India
Industrial infrastructure projects and a growing transportation sector fuel India's crude oil requirements. The country's energy policies emphasize securing stable supplies to meet its expanding energy needs. Refineries along the west coast, such as those in Gujarat, are expanding capacity to process diverse crude grades for both fuel and chemical production.
Saudi Arabia
Crude oil production and export capabilities define Saudi Arabia's market position, leveraging low-cost extraction. The nation's energy strategy focuses on maintaining market supply influence and expanding downstream petrochemical integration. Industrial cities like Jubail are developing new petrochemical complexes to add value to crude derivatives.
Germany
Petrochemical feedstock applications and specialized fuel production sustain Germany's crude oil demand. The EU Green Deal pressures German refiners to reduce carbon footprints and invest in lower-carbon processes. Refineries in the Rhine-Ruhr region are adapting their configurations to meet stricter fuel specifications and increase bio-component blending.
Crude Oil Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another in the crude oil market. The industry structure reflects a blend of state-owned entities with vast reserves and integrated multinational corporations. Strategic archetypes include national oil companies focused on volume and international majors prioritizing complex project execution and downstream integration. Companies employ portfolio diversification and technology licensing as dominant competitive moves.
At the scale-driven end, Saudi Aramco leverages unparalleled low-cost production and extensive reserve bases to influence global supply dynamics. This national oil company anchors a significant portion of the world's crude oil output. Integrated multinational corporations like ExxonMobil specialize in executing large-scale, technologically complex projects globally, often in challenging environments requiring deep technical expertise. Shell positions its portfolio to capture value in deepwater exploration and integrated gas, alongside its refining and petrochemical operations, demonstrating a diversified approach. These entities collectively shape the market's supply-side characteristics and investment trends.
| Leading Market Players |
|---|
| Saudi Aramco |
| ExxonMobil |
| Chevron |
| PetroChina |
| Shell |
| TotalEnergies |
| CNOOC |
| ConocoPhillips |
| BP |
| Others |
Cost & Logistics Intelligence
Refinery overcapacity in the Atlantic Basin influences pricing behavior, compelling refiners to optimize crude slates for margin capture. This dynamic affects supplier strategies and contract negotiations.
Pricing Analysis
Spot-market purchases dominate independent refiner procurement, especially in Asia, shifting away from rigid long-term contracts. Price differentiation stems from crude quality, specifically API gravity and sulfur content, alongside regional transportation costs. Pricing pressure intensifies for producers as buyers prioritize flexible supply agreements. Independent refiners demonstrate high price sensitivity, while integrated majors often secure long-term volumes.
Supply Chain Analysis
Global crude production concentrates heavily with national oil companies like Saudi Aramco and major integrated firms in the US Permian Basin. Supply chain operations rely on specialized drilling equipment and advanced EOR chemicals for efficient extraction. Geopolitical instability and logistics chokepoints, such as major shipping lanes, pose significant structural risks. Distribution runs through extensive global tanker fleets and interconnected pipeline networks to regional refining hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The crude oil market faces a critical shortage of talent blending petroleum engineering with data science expertise. This capability gap hinders digital transformation and operational optimization across the value chain.
For Market Incumbents: Entrench core hydrocarbon assets by integrating Carbon Capture, Utilization, and Storage (CCUS) to mitigate regulatory pressure on carbon emissions. Modernize refining configurations to prioritize high-value petrochemical intermediates, countering transportation fuel substitution. Leverage deep technical expertise in complex project execution and capital discipline for sustained profitability. For New Entrants and Emerging Players: Pursue niche opportunities in specialty chemical production, leveraging advanced materials for higher margins. Target the digitalization of operations, offering AI-powered analytics and IoT solutions to optimize drilling efficiency in mature fields. A go-to-market strategy could involve technology licensing for enhanced oil recovery in regions like the Permian Basin. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across refinery modernization projects due to stricter environmental mandates. Long-term viability over the next decade hinges on companies balancing cash flow from legacy assets with selective investments in low-carbon technologies. Target acquisition archetypes include firms specializing in enhanced oil recovery technologies or advanced petrochemical intermediates. Watch for the pace of regional energy transitions and the enforcement of dual carbon goals as a key inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Integrate CCUS Technologies | Decarbonizes existing operations and creates new service-based revenue streams. |
| Modernize Refinery Configurations | Shifts output towards high-value petrochemicals, capturing superior margins. |
| Invest in Digital Oilfield Solutions | Improves drilling efficiency, predictive maintenance, and supply chain logistics. |
| Expand Enhanced Oil Recovery (EOR) | Extends productive life of mature fields and improves asset returns. |
| Diversify into Specialty Chemicals | Captures higher margins from advanced polymers and performance materials. |
Research Approach
Cross-validation between primary interviews and extensive secondary research anchors the qualitative findings of this study. Researchers engaged upstream engineers, refinery operations managers, petrochemical procurement leads, and energy policy analysts. Secondary data sources included IEA reports, EIA statistics, and government environmental regulations from the US EPA, EU Green Deal, and China MEE. This approach ensured bottom-up and top-down triangulation for robust market insights.
The analytical framework calibrated historical data against projected demand and supply-side capacity additions across the analysis window. Segmentation dimensions modeled included crude type, application, production method, end user, and key regional markets. Compound annual growth rates were derived through quantitative modeling and scenario analysis. Crude quality differentials and regional refining capacity utilization served as critical industry-specific forecast inputs.
Sensitivities concentrate around geopolitical events, the pace of energy transition, and unforeseen technological disruptions impacting demand or supply. Forecasts reflect assumptions documented at the time of publication. Quarterly review of crude price benchmarks, policy announcements, and new project Final Investment Decisions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Australia Refined Petroleum Products Market
Petroleum Products
Automotive Oil Strainer Market
Petroleum Products
Performance Oil Sales Market
Petroleum Products
Crude Oil Pour Point Depressant Market
Petroleum Products
Crude Tall Oil Market
Petroleum Products
Pygas (Pyrolysis Gasoline) Market
Petroleum Products
Natural Gas Liquid Market
Petroleum Products
India White Oil Market
Petroleum Products
LPG [Liquefied Petroleum Gas] Market
Petroleum Products
Tar Oil Market
Petroleum Products
Pale Oil Market
Petroleum Products
Oil Refinery Market
Petroleum Products
Alkylate Gasoline Market
Petroleum Products
Germany Refined Petroleum Products Market
Petroleum Products
Spiral Submerged Arc Welded (SSAW) Steel Pipe Market
Petroleum Products
Spindle Oil Market