
 United States Liner Hanger System Market | 2026-2036
United States Liner Hanger System Market Size, Share, and Industry Trends Forecast 2026-2036
United States Liner Hanger System Market Analytics
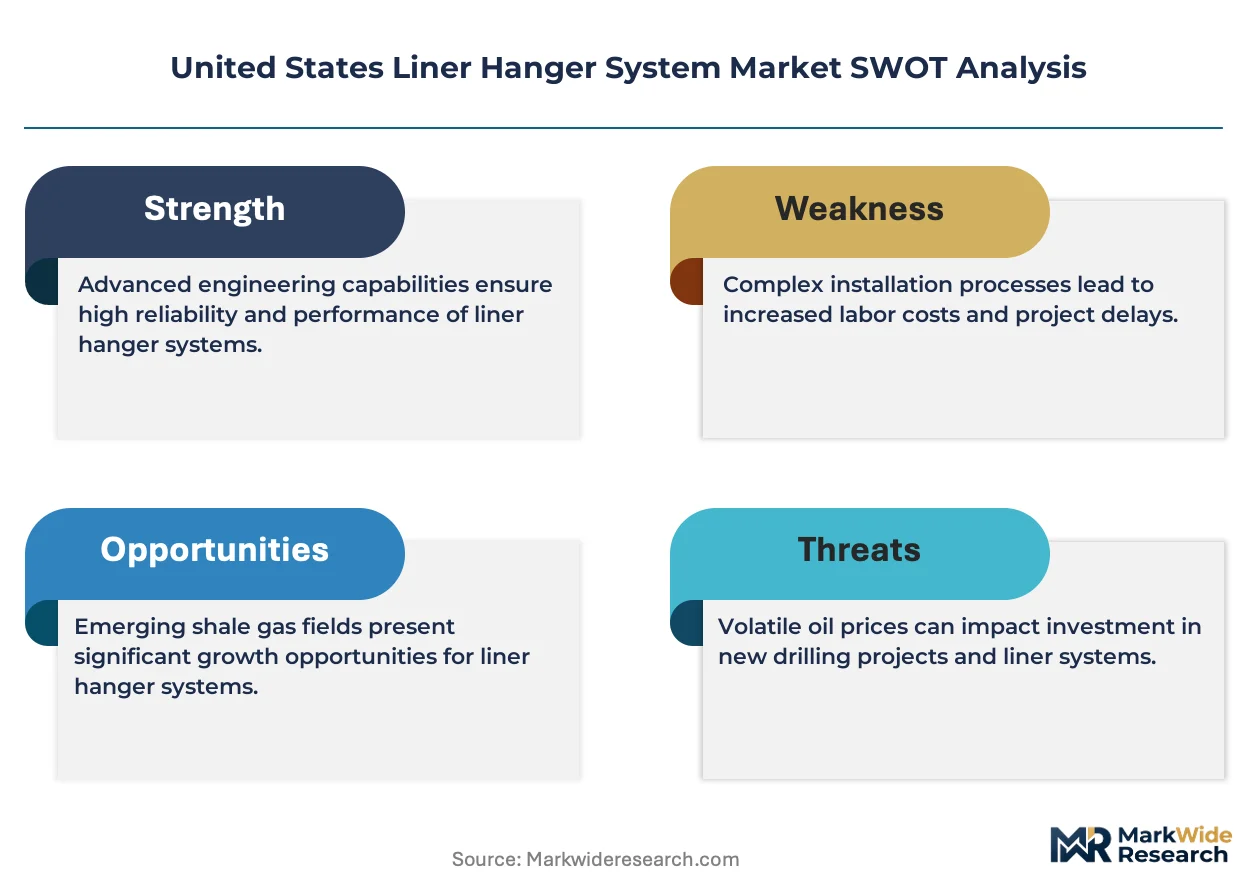
Asset-light leasing and pay-per-use equipment financing is fragmenting the competitive landscape for liner hanger systems across the Lower 48. Baker Hughes Company leverages its integrated drilling and completions portfolio to bundle hanger systems with directional services. Halliburton Company anchors its position through manufacturing scale and deep inventory positions in the Gulf Coast supply corridor. Dril-Quip, Inc. specializes in offshore-ready hydraulic hangers that withstand high-pressure deepwater conditions.
A liner hanger system is a mechanical or hydraulic downhole tool that suspends and seals casing liners within oil and gas wellbores, typically rated for pressure differentials exceeding 10,000 psi and temperatures above 350°F, enabling zonal isolation and pressure management during completion and production operations. Mechanical hangers retain dominant share in onshore Permian and Bakken applications where cost efficiency and simplicity drive procurement decisions. Hydraulic hangers capture premium positioning in ultra-deepwater Gulf of Mexico projects where remote setting capability and seal reliability justify higher unit economics. Among end users, oil and gas operators increasingly bypass service providers to procure hangers directly, compressing distributor margins while shifting specification authority upstream.
The EPA enforces methane monitoring and leak detection mandates under the Inflation Reduction Act that elevate seal integrity standards for all downhole equipment including liner hangers. The Bureau of Safety and Environmental Management enforces offshore well integrity rules that require third-party verification of hanger pressure ratings and material traceability. OSHA maintains workplace safety protocols for high-pressure testing operations that influence manufacturing facility locations and field deployment procedures. Stakeholders must weigh domestic content requirements against offshore component sourcing strategies as federal procurement rules tighten.
Market Dynamics
Extended lateral drilling in the Permian Basin is forcing liner hanger systems to withstand higher torque loads and pressure differentials, compressing equipment lifecycles and accelerating replacement schedules for unconventional operators.
Growth Catalysts
- EPA Methane Rules:The Inflation Reduction Act mandates gas-tight seals across all downhole equipment, creating mandatory upgrade cycles for legacy hanger installations in active shale basins.
- Permian Basin Drilling Intensity:Texas operators deploying laterals beyond 15,000 feet require reinforced hanger systems rated for sustained cyclic loading, expanding addressable equipment volume.
- Hydraulic Setting Technology:Remote-actuated hangers eliminate wireline trips in ultra-deepwater Gulf of Mexico completions, reducing rig time and enabling subsea tieback economics.
Market Restraints
- Alloy Steel Price Volatility:High-grade chromium-molybdenum bar stock for hanger bodies faces supply concentration from domestic electric arc furnace producers, squeezing fabrication margins.
- Offshore Certification Bottlenecks:Bureau of Safety and Environmental Enforcement third-party verification requirements extend lead times for deepwater hanger deliveries by four to six months.
- Mechanical Hanger Substitution:Simplified slip-and-cone designs retain cost advantage in shallow onshore wells, limiting hydraulic hanger penetration in price-sensitive basins.
Strategic Opportunities
- Appalachian Basin Gas Development:Marcellus and Utica operators underutilize premium liner hanger systems, presenting white-space expansion for seal-integrity-focused suppliers.
- Carbon Capture Well Construction:Class VI injection well standards require zonal isolation systems compatible with corrosive CO2 streams, opening specialty metallurgy demand.
- Direct Operator Procurement:Oil and gas producers bypassing distributors to specify hangers directly compresses channel margins while shifting technical authority upstream to completion engineers.
Industry Challenges
- Deepwater Metallurgy Expertise Gap:Gulf of Mexico projects require sour-service-qualified engineers capable of specifying nickel-alloy hangers for high-H2S reservoirs, constraining deployment velocity.
- Legacy System Integration:Operators retrofitting gas-tight seals onto existing well architectures face compatibility failures between new hanger elastomers and aged casing surfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Liner Hanger System Market |
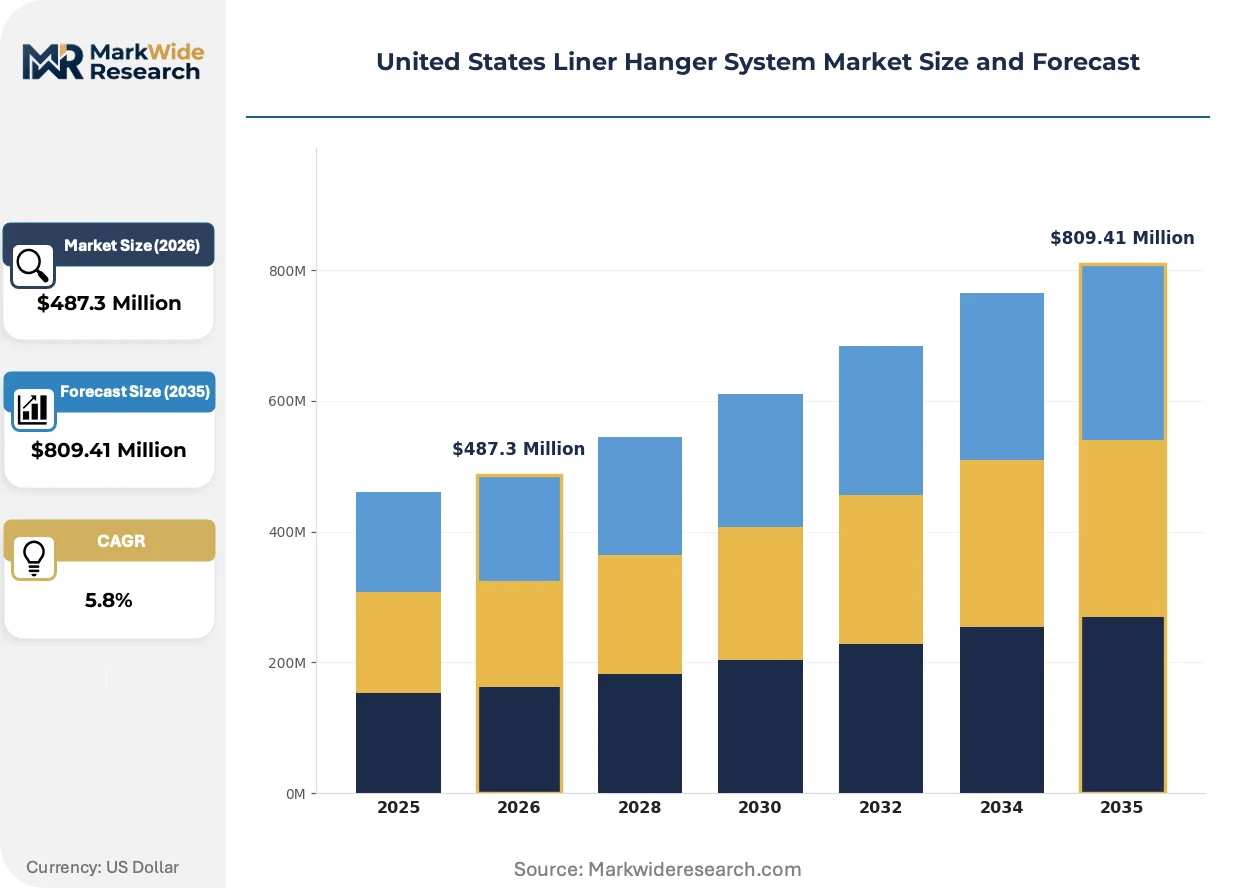
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Hangers, Hydraulic Hangers, Permanent Hangers, Wireline Hangers End User: Oil & Gas Operators, Service Providers, Drilling Contractors, Engineering Firms Installation Type: Offshore, Onshore, Ultra-Deepwater, Shallow Water Application: Well Completion, Cementing, Production, Intervention |
| Companies Covered | Baker Hughes Company, Dril-Quip, Inc., Halliburton Company, TechnipFMC plc, NCS Multistage Holdings, Inc., Schlumberger Limited, National Oilwell Varco, Inc., Expro Group Holdings N.V., Weatherford International plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Liner Hanger System Market Evolving Landscape
Downhole equipment specifications are hardening under regulatory pressure while automation and materials science converge to extend operational envelopes in extreme well conditions.
Metallurgical formulations for hanger slip segments are migrating from traditional carbon steel to precipitation-hardened nickel alloys rated for 450°F service. Permian operators with high-pressure, high-temperature laterals are adopting these grades to prevent stress-corrosion cracking in cyclic loading environments. The shift is compressing demand for commodity-grade mechanical hangers while elevating qualification requirements for domestic foundries.
The EPA's methane emissions monitoring mandates under the Inflation Reduction Act now extend to downhole seal integrity verification. Operators must document leak-tight performance across hanger connections during initial completion and periodic recompletion activities. Gulf of Mexico deepwater projects face the strictest enforcement timelines, driving pre-emptive seal upgrades ahead of formal inspection deadlines.
Completion engineers at major shale producers now specify liner hangers directly through technical procurement portals, disintermediating traditional oilfield distributors. This channel compression transfers pricing leverage upstream while forcing hanger manufacturers to maintain dedicated application engineering support for operator technical teams. The pattern is most pronounced in Texas, where consolidated independents centralize supply chain decision-making at corporate headquarters.
United States Liner Hanger System Market Segmentation
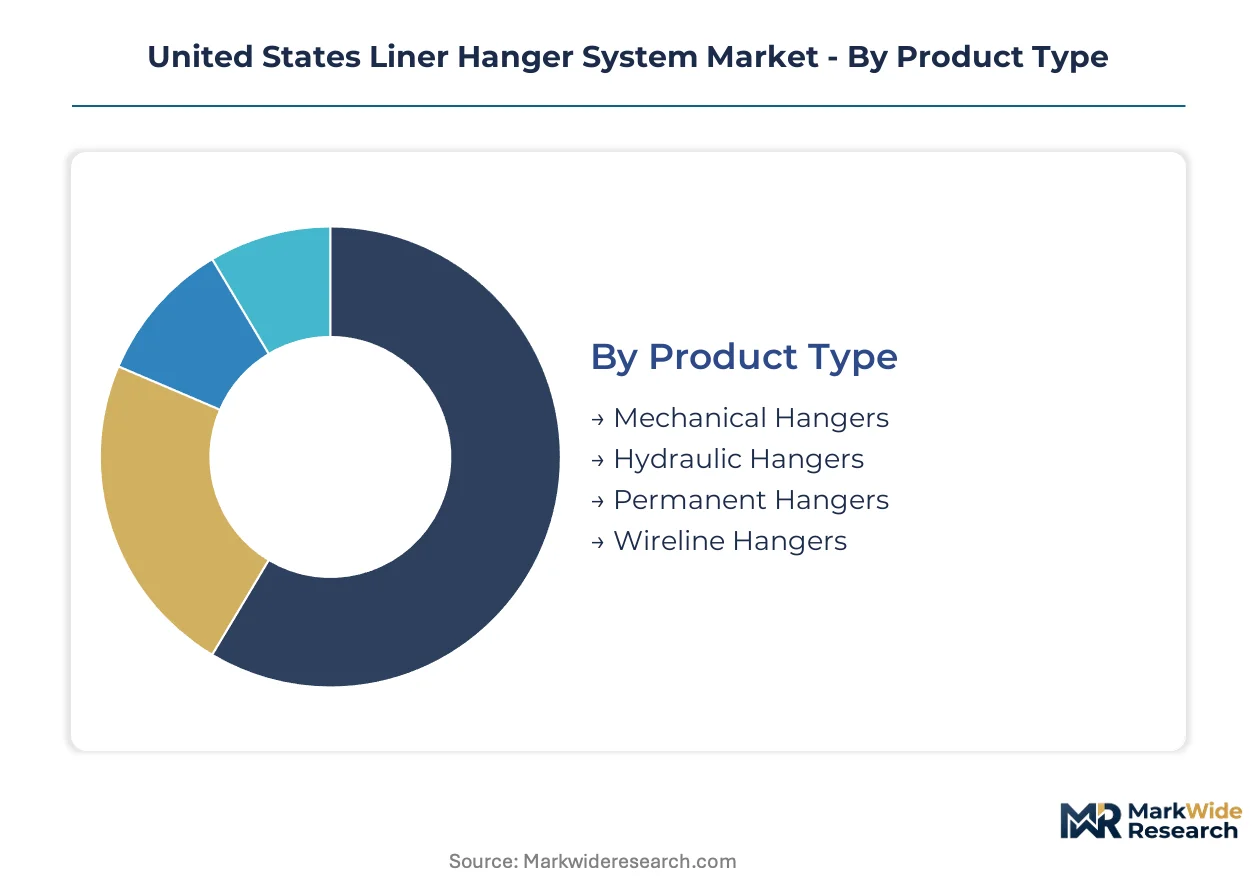
Liner hanger procurement patterns diverge sharply across well architectures and operator capabilities, with product specifications hardening under EPA methane rules while installation environments dictate metallurgy and setting mechanism selection.
Product Type:
Use-case spectrum spans cost-driven shallow onshore wells through remotely-actuated deepwater completions where seal reliability justifies premium unit economics.
- Mechanical Hangers:Slip-and-cone designs utilizing expandable metal slips to anchor casing against wellbore walls without external power sources. Demand concentrates in Texas Permian Basin applications where operators prioritize capital efficiency and field-proven reliability for laterals under 12,000 feet.
- Hydraulic Hangers:Pressure-actuated setting mechanisms enabling remote deployment in subsea environments without wireline intervention. Gulf of Mexico ultra-deepwater projects drive specification authority, with Bureau of Safety and Environmental Enforcement certification requirements extending lead times four to six months.
- Permanent Hangers:Non-retrievable systems welded or cemented in place for final well abandonment or long-term zonal isolation.
- Wireline Hangers:Conveyance-dependent tools set through electric line operations, retaining niche positioning in recompletion campaigns where rig mobilization is uneconomical.
Established volume favors Mechanical Hangers; emerging adoption favors Hydraulic Hangers.
End User:
Procurement authority is migrating upstream as technical specification shifts from distributor networks to operator engineering teams.
- Oil & Gas Operators:Exploration and production companies now bypass service intermediaries to specify hanger metallurgy, seal ratings, and torque capacity directly through centralized procurement portals. Texas independents with consolidated supply chain functions drive this disintermediation most aggressively.
- Service Providers:Integrated drilling and completions firms bundle hanger systems with directional services and cementing packages. Margin compression from direct operator procurement forces these entities toward application engineering support rather than inventory carrying.
- Drilling Contractors:Rig owners with retained completion crews procure hangers as part of well construction packages, particularly in Appalachia where pad drilling standardizes equipment specifications.
- Engineering Firms:Specialist consultants specify hangers for complex well architectures including high-pressure, high-temperature laterals and carbon capture injection wells.
Direct procurement is climbing the fastest among Oil & Gas Operators; bundled service models retain largest installed base through Service Providers.
Installation Type:
Environmental severity dictates metallurgical grade and certification burden, with subsea settings imposing the strictest material traceability requirements.
- Offshore:Platform-based installations in federal waters subject to Bureau of Safety and Environmental Enforcement well integrity rules requiring third-party verification of pressure ratings and sour-service qualification.
- Onshore:Land-based drilling across Texas, New Mexico, and North Dakota dominates unit volume, with EPA methane monitoring mandates now extending to downhole seal integrity documentation.
- Ultra-Deepwater:Subsea completions below 5,000 feet water depth require nickel-alloy hangers rated for 450°F service and high-H2S reservoir conditions, constraining supplier base to foundries with precipitation-hardening capabilities.
- Shallow Water:Continental shelf projects between 200-1,000 feet depth utilize simplified hydraulic systems with lower certification overhead than ultra-deepwater equivalents.
Onshore installations command widest deployment; ultra-deepwater specifications are gaining share fastest on per-unit value basis.
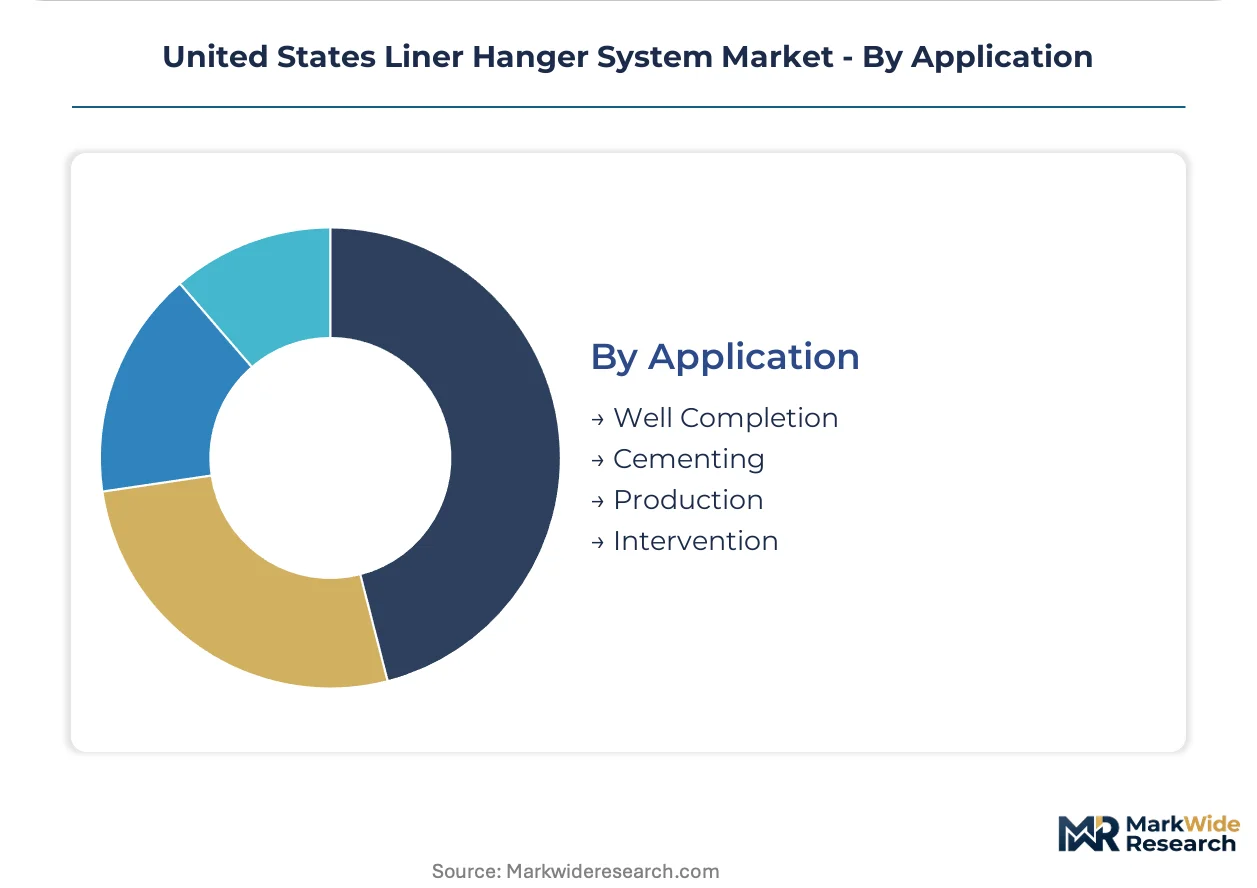
Application:
Operational phase determines seal performance requirements and replacement frequency, with production-phase hangers facing sustained cyclic loading versus single-use completion tools.
- Well Completion:Initial liner deployment during drilling phase, where hanger integrity establishes zonal isolation foundation for subsequent hydraulic fracturing or production tubing installation.
- Cementing:Hangers engineered to withstand cement slurry displacement pressures while maintaining annular seal integrity during hydration and curing cycles.
- Production:Sustained-pressure applications where thermal cycling and reservoir pressure depletion stress hanger seals over multi-year well lifespans, driving replacement demand in mature shale basins.
- Intervention:Workover and recompletion operations requiring hanger retrieval or supplementary seal installation, with gas-tight retrofit compatibility emerging as critical specification under Inflation Reduction Act methane rules.
Well Completion generates highest annual unit demand; Intervention applications are expanding most quickly as legacy shale wells enter recompletion cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal methane monitoring mandates under the Inflation Reduction Act are redistributing liner hanger demand across U.S. shale basins. Texas retains dominant deployment volume while Appalachian operators accelerate seal-integrity upgrades. Gulf of Mexico deepwater activity concentrates procurement authority among ultra-deepwater-certified fabricators.
Texas
Permian Basin operators deploying laterals beyond 15,000 feet require reinforced hanger systems rated for sustained cyclic loading. EPA methane rules mandate gas-tight seal documentation across all active completions. Midland-Odessa anchors the highest equipment turnover rates as lateral extension accelerates replacement schedules.
Louisiana
Ultra-deepwater projects in the Gulf of Mexico drive specification authority for hydraulic hangers with remote-actuated setting mechanisms. Bureau of Safety and Environmental Enforcement certification requirements extend lead times four to six months. Houma-New Orleans corridor hosts the primary subsea equipment fabrication and testing infrastructure.
Pennsylvania
Marcellus shale operators underutilize premium liner hanger systems relative to Permian intensity, presenting white-space expansion for seal-integrity-focused suppliers. Pennsylvania Department of Environmental Protection enforces well casing standards that intersect with federal methane monitoring timelines. Pittsburgh-based completion engineering teams increasingly specify hangers directly through centralized procurement portals.
New Mexico
Delaware Basin drilling activity mirrors Permian intensity with equivalent lateral length extension and pressure differential requirements. State Oil Conservation Division rules align with federal EPA methane monitoring mandates for downhole seal integrity. Lea and Eddy counties concentrate the highest density of unconventional completions requiring reinforced hanger metallurgy.
North Dakota
Bakken operators prioritize mechanical hanger cost efficiency for shallower laterals under 12,000 feet where capital discipline dominates procurement decisions. North Dakota Industrial Commission well integrity rules enforce pressure rating documentation without equivalent seal-strictness to Gulf of Mexico standards. Williston Basin drilling pads standardize equipment specifications across multi-well programs.
United States Liner Hanger System Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a consolidated vendor base where integrated service portfolios dominate procurement decisions. Three archetypes anchor competitive positioning: integrated oilfield service conglomerates bundling hangers with directional drilling and cementing packages; specialized downhole equipment fabricators focusing on metallurgy and pressure rating certification; and offshore-focused hydraulic system engineers targeting ultra-deepwater qualification requirements. Dominant competitive moves include backward integration into high-grade alloy supply chains and strategic partnerships with operators for direct procurement portal access.
Among integrated service providers, Baker Hughes Company and Halliburton Company exemplify the bundling archetype that anchors market presence through manufacturing scale and Gulf Coast supply corridor positioning. Dril-Quip, Inc. occupies a specialist position within the offshore-certified fabricator tier, representing the hydraulic hanger engineering focus required for Bureau of Safety and Environmental Enforcement verification timelines.
| Leading Market Players |
|---|
| Baker Hughes Company |
| Dril-Quip, Inc. |
| Halliburton Company |
| TechnipFMC plc |
| NCS Multistage Holdings, Inc. |
| Schlumberger Limited |
| National Oilwell Varco, Inc. |
| Expro Group Holdings N.V. |
| Weatherford International plc |
| Others |
Value Network & Pricing Analysis
Alloy steel price volatility from domestic electric arc furnace producers compresses fabrication margins while simultaneously widening spreads between commodity-grade mechanical hangers and certified hydraulic systems for Gulf of Mexico deployment. This input cost instability forces procurement managers to balance inventory carrying costs against spot market exposure, reshaping contract structures across the Lower 48.
Pricing Analysis
Certification level creates the primary spread between Bureau of Safety and Environmental Enforcement-verified hydraulic hangers and standard mechanical alternatives. Project-based contract pricing dominates, with premium tiers commanding spreads justified by nickel-alloy metallurgy and sour-service qualification. Price differentiation rests on material grade and after-sales engineering support bundled with direct operator procurement portals. Cost compression in commodity mechanical hangers is intensifying because Permian operators prioritize capital efficiency for laterals under 12,000 feet. Independent shale producers exhibit highest price sensitivity; ultra-deepwater majors demonstrate lowest sensitivity due to seal failure risk exposure.
Supply Chain Analysis
Tariff exposure between domestic foundries and offshore component sourcing strategies dominates supply chain risk calculus for hanger manufacturers navigating federal procurement rule tightening. Manufacturing gravity centers on Texas and Louisiana, with specialty metallurgy sourcing drawing from Pennsylvania and Ohio specialty steel producers. High-grade chromium-molybdenum bar stock, precipitation-hardened nickel alloys, and elastomer seal compounds constitute critical input dependencies. Single-source vulnerability concentrates in domestic electric arc furnace capacity for sour-service-qualified material. Distribution runs through integrated service company bundling networks and direct operator technical procurement portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Liner Hanger System Market functions as a defensive-moat arena where Bureau of Safety and Environmental Enforcement certification requirements create substantial switching costs that entrench incumbent positions. Regulatory entrenchment extends lead times four to six months for new entrants attempting ultra-deepwater qualification.
For Market Incumbents: Harden certification moats through accelerated Bureau of Safety and Environmental Enforcement verification pipeline investments and captive supply chain control over high-grade chromium-molybdenum bar stock. Deepen metallurgy expertise in precipitation-hardened nickel alloys to exploit the sour-service engineering gap constraining Gulf of Mexico deployment velocity. Threat substitution from asset-light leasing models demands counter-positioning through application engineering staffing that distributor-dependent competitors cannot replicate. For New Entrants and Emerging Players: Establish a beachhead in the Appalachian Basin where Marcellus and Utica operators underutilize premium seal-integrity systems relative to Permian intensity. Carbon capture injection well construction presents parallel white-space opportunity given Class VI zonal isolation requirements and limited incumbent focus. Go-to-market execution should target direct procurement portal access with Pittsburgh-based completion engineering teams rather than competing for bundled service provider slots. For Investors and Strategic Acquirers: Offshore-certified hydraulic system fabricators with Bureau of Safety and Environmental Enforcement track records represent the highest-value acquisition target archetype given certification scarcity and ultra-deepwater project economics. Long-term viability over the projection horizon rests on regulatory entrenchment deepening rather than commodity cycle exposure. Monitor EPA methane enforcement timelines as the critical inflection signal; accelerated inspection schedules will force legacy well retrofit demand that favors seal-integrity-focused suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Supply | Captive chromium-molybdenum sourcing insulates margins from electric arc furnace price volatility. |
| Bureau Certification Acceleration | Compressed lead times for hydraulic hanger verification unlock ultra-deepwater project participation. |
| Direct Procurement Portal Development | Operator-facing technical interfaces disintermediate distributor networks and capture specification authority. |
| Carbon Capture Metallurgy Investment | CO2-corrosion-resistant hanger systems address Class VI injection well construction requirements. |
| Appalachian Engineering Presence | Pittsburgh-based application support targets underpenetrated Marcellus seal-integrity upgrade cycles. |
Research Methodology
Initial hypotheses were tested against primary input from drilling engineers, completion superintendents, procurement directors at shale operators, metallurgical quality managers at domestic foundries, and regulatory compliance officers, then refined through secondary validation. Primary intelligence combined structured interviews with field deployment observations across Texas Permian Basin and Gulf of Mexico ultra-deepwater installations. Secondary sources encompassed Bureau of Safety and Environmental Enforcement certification databases, EPA methane monitoring enforcement timelines, SEC 10-K filings from integrated service providers, and American Petroleum Institute technical standards documentation. Bottom-up equipment unit demand modeling triangulated against top-down operator capital expenditure patterns.
Demand-supply balance framing anchored the analytical framework across the analysis window, with segmentation modeling spanning product type, installation environment, application phase, and end-user procurement authority. CAGRs were derived through equipment replacement cycle analysis, lateral extension trajectories in unconventional basins, and regulatory upgrade mandate timing. Industry-specific forecast inputs incorporated Permian drilling intensity projections and Gulf of Mexico project sanctioning velocity for subsea tieback developments.
Sensitivities concentrate around EPA methane enforcement acceleration, alloy steel spot price volatility, and Bureau of Safety and Environmental Enforcement certification backlog fluctuations. Forecasts reflect documented assumptions regarding lateral length extension rates and regulatory compliance cost pass-through elasticity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Gulf of Mexico Oil and Gas Midstream Market
Oil & Gas
Downhole Drilling Tools Market
Oil & Gas
Drones for Oil & Gas Market
Oil & Gas
India AI in Oil and Gas Market
Oil & Gas
Asia- Pacific Drilling Market
Oil & Gas
South-East Asia Oil and Gas Pipeline Market
Oil & Gas
Vacuum Gas Oil Market
Oil & Gas
Libya Oil and Gas Upstream Market
Oil & Gas
Malaysia Oilfield Services Market
Oil & Gas
Europe Completion Equipment and Services Market
Oil & Gas
Qatar Oil and Gas Market
Oil & Gas
India LNG Bunkering Market
Oil & Gas
Indonesia Coal Market
Oil & Gas
North America Oil Country Tubular Goods Market
Oil & Gas
APAC Oil and Gas Automation Market
Oil & Gas
3D Printing in Oil and Gas Market