
 North America Oil Storage Market | 2026-2036
North America Oil Storage Market Size, Share, and Industry Trends Forecast 2026-2036
North America Oil Storage Market Analytics
Buyer concentration is shifting as midstream operators consolidate terminal access contracts while independent traders fragment spot storage demand across smaller Gulf Coast facilities. Kinder Morgan anchors its position through pipeline-integrated tankage along the Houston Ship Channel. Magellan Midstream Partners dominates refined product storage with a network spanning Oklahoma and Texas. TF Warren Group specializes in corrosion-resistant coatings that extend tank life cycles for legacy infrastructure owners.
North America oil storage encompasses fixed and mobile containment systems engineered to hold crude oil, refined products, and intermediate feedstocks at atmospheric or pressurized conditions, typically constructed from carbon steel with cathodic protection and leak detection systems. Above ground tanks lead installed capacity due to lower capital costs and easier inspection access, while floating roof tanks capture the fastest growth segment as volatile organic compound regulations tighten. Underground tanks retain niche importance in environmentally sensitive coastal zones where surface footprint restrictions apply.
The US EPA enforces SPCC and Facility Response Plan standards that mandate secondary containment for above-ground tanks exceeding threshold capacity, while Canada's Energy Regulator imposes integrity management requirements on federally regulated pipelines and associated tankage. OSHA confined-space entry rules shape maintenance service demand across the US Gulf Coast tank farm cluster. Stakeholders must monitor how emerging state-level carbon intensity benchmarks for stored products could reshape terminal economics and retrofit priorities.
Market Dynamics
Canadian oil sands operators are driving heavier crude slate acceptance across Gulf Coast refineries, forcing terminal operators to retrofit tankage for high-viscosity feedstocks and sulfur-handling infrastructure. This feedstock transition is compressing storage economics for light sweet crude facilities while expanding demand for heated and insulated containment systems.
Growth Catalysts
- EPA SPCC Rule Expansion:Secondary containment mandates for above-ground tanks exceeding threshold capacity are accelerating tank farm modernization across the US Gulf Coast and Great Lakes regions.
- Petrochemical Export Terminal Buildouts:Gulf Coast ethane and propane export capacity additions require millions of barrels of additional working storage for fractionation feedstocks.
- Floating Roof Tank Adoption:Volatile organic compound capture requirements under state-level air quality regulations are displacing fixed roof designs in California and Texas terminals.
Market Restraints
- Carbon Steel Price Volatility:Input cost swings for tank plate and weld materials compress fabrication margins and delay greenfield construction timelines.
- Specialized Coating Supplier Concentration:Corrosion-resistant lining systems for sour crude service depend on a narrow base of qualified applicators concentrated along the Houston Ship Channel.
- Underground Tank Technical Limits:Hydrostatic pressure constraints and leak detection complexity restrict pressurized product storage in coastal zones with high water tables.
Strategic Opportunities
- Mexico Energy Reform Storage Liberalization:Pemex terminal access openings create white space for US midstream operators to develop cross-border tankage at Tuxpan and Veracruz.
- Carbon Intensity Benchmarking:California's LCFS and emerging state standards create premium storage tiers for low-carbon intensity crude and renewable feedstocks.
- Drone-Based Tank Inspection Convergence:UAV-mounted ultrasonic thickness measurement combined with AI defect classification is compressing outage durations and maintenance costs.
Industry Challenges
- API 653 Inspector Shortage:Certified above-ground storage tank inspectors are concentrated among retiring specialists, extending recertification backlogs for legacy infrastructure.
- Legacy SCADA Integration Complexity:Leak detection system upgrades require protocol translation between 1980s-era tank gauging hardware and modern distributed control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Oil Storage Market |
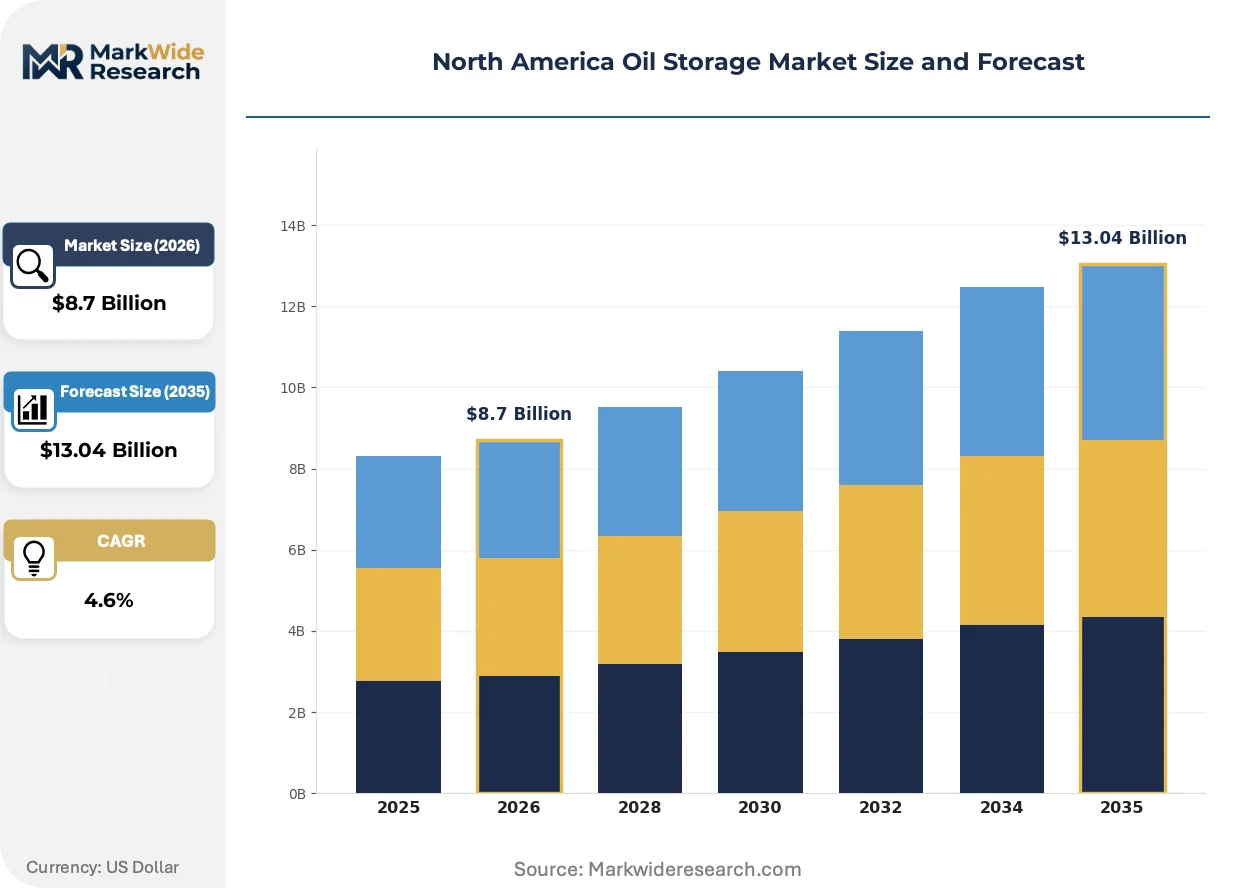
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Above Ground Tanks, Underground Tanks, Mobile Storage Units, Floating Roof Tanks End User: Refineries, Distributors, Traders, Petrochemical Plants Installation Type: Onshore, Offshore, Retrofit, New Construction Service Type: Storage Services, Maintenance, Inspection, Equipment Rental |
| Companies Covered | Manchester Tank, TF Warren Group, Mcdermott International Ltd., Magellan Midstream Partners, Kinder Morgan, Shawcor, Hassco Industries, Buckeye Partners, Matrix NAC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Oil Storage Market Evolving Landscape
Digital twin deployment is compressing inspection cycles across North American tank farms while corrosion-resistant alloys and modular fabrication methods reshape capital deployment patterns. These shifts are reducing outage durations and enabling faster capacity additions.
Advanced composite tank linings with fiberglass-reinforced polymer construction are consolidating market share in sour crude and high-acid feedstock service. Canadian oil sands producers and US heavy crude refiners are specifying these systems for newbuild tankage to extend maintenance intervals. The technology is consolidating demand previously fragmented between carbon steel with internal coatings and stainless steel alternatives.
EPA's updated Spill Prevention, Control, and Countermeasure rules are tightening secondary containment calculations for tank farms in flood-prone zones. Facility operators must now model worst-case discharge scenarios using updated precipitation data, driving berm expansion and impoundment capacity additions. Gulf Coast terminals in hurricane corridors face the steepest compliance capital requirements.
Spot storage contracting is fragmenting as independent traders bypass traditional terminal access agreements in favor of shorter-duration, smaller-volume arrangements. Midstream incumbents are responding with unbundled service tiers separating throughput, heating, and blending functions. This behavioral shift is most visible along the Houston Ship Channel and Corpus Christi export corridor where trader participation has expanded fastest.
North America Oil Storage Market Segmentation
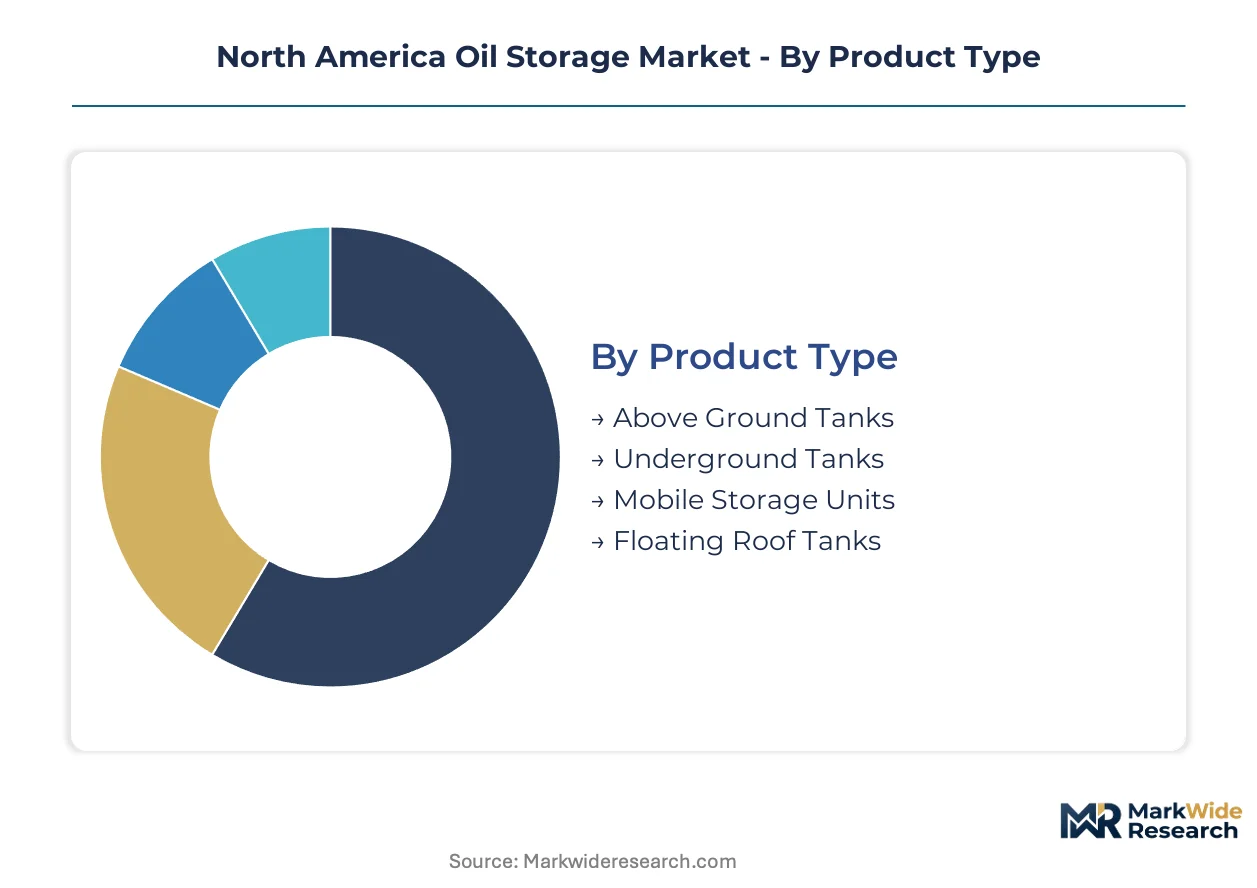
Oil storage segmentation in North America reflects divergent capital intensity profiles and regulatory exposure across containment technologies. Terminal operators select tank configurations based on crude slate viscosity, vapor pressure characteristics, and site-specific environmental constraints rather than generic capacity metrics.
Product Type:
Standalone tankage dominates capital deployment, while embedded heating and vapor recovery systems increasingly integrate at the fabrication stage.
- Above Ground Tanks:Carbon steel atmospheric vessels with fixed or floating roof configurations account for the majority of installed base across US Gulf Coast and Canadian terminal clusters. Lower capital costs and simplified API 653 inspection access drive preference for greenfield refinery tank farms in Texas and Louisiana.
- Floating Roof Tanks:Pontoon-supported deck designs with primary and secondary seals capture evaporative losses from volatile crude and gasoline stocks. California Air Resources Board and Texas Commission on Environmental Quality mandates for VOC containment accelerate displacement of fixed-roof alternatives in coastal terminals.
- Underground Tanks:Double-wall fiberglass or steel construction with continuous leak detection serves environmentally sensitive coastal zones in Florida and Pacific Northwest where surface footprint restrictions apply.
- Mobile Storage Units:Modular frac tanks and ISO containerized systems enable rapid deployment for pipeline maintenance outages and emergency response staging.
Above Ground Tanks leads volumes today; Floating Roof Tanks is gaining share fastest.
End User:
Volume concentration scales with throughput commitment duration, separating long-term capacity holders from spot market participants.
- Refineries:Integrated operators along the Houston Ship Channel and Port Arthur complex maintain captive tankage for crude charge flexibility and intermediate feedstock buffering. Heated storage for Canadian heavy sour crude expands fastest among Gulf Coast cokers.
- Petrochemical Plants:Ethane and propane fractionation facilities in Mont Belvieu and Corpus Christi require cryogenic and pressurized containment for NGL feedstocks and export staging.
- Distributors:Refined product marketers in the Midwest and Northeast lease terminal capacity for gasoline, diesel, and heating oil inventory positioning.
- Traders:Independent merchants fragment demand across smaller Gulf Coast facilities with shorter-duration, unbundled service contracts separating storage from heating and blending.
Refineries anchor capacity commitments; Traders are expanding contract velocity fastest.
Installation Type:
Greenfield construction commands premium margins while retrofit activity concentrates in hurricane-exposed legacy corridors.
- New Construction:Greenfield tank farms with integrated vapor recovery and secondary containment systems serve export terminal buildouts along Corpus Christi and Brownsville ship channels.
- Retrofit:Existing tankage upgrades for heated service, floating roof conversion, and berm expansion absorb compliance capital across EPA SPCC-regulated facilities.
- Onshore:Terrestrial tank farms with pipeline and rail connectivity dominate working storage economics across Permian and Bakken supply basins.
- Offshore:Platform-integrated and subsea storage systems serve limited deepwater production applications in US Gulf of Mexico.
New Construction captures capital flow; Retrofit activity is climbing fastest.
Service Type:
Recurring maintenance and inspection services fragment across specialized contractors while storage services consolidate under midstream operators.
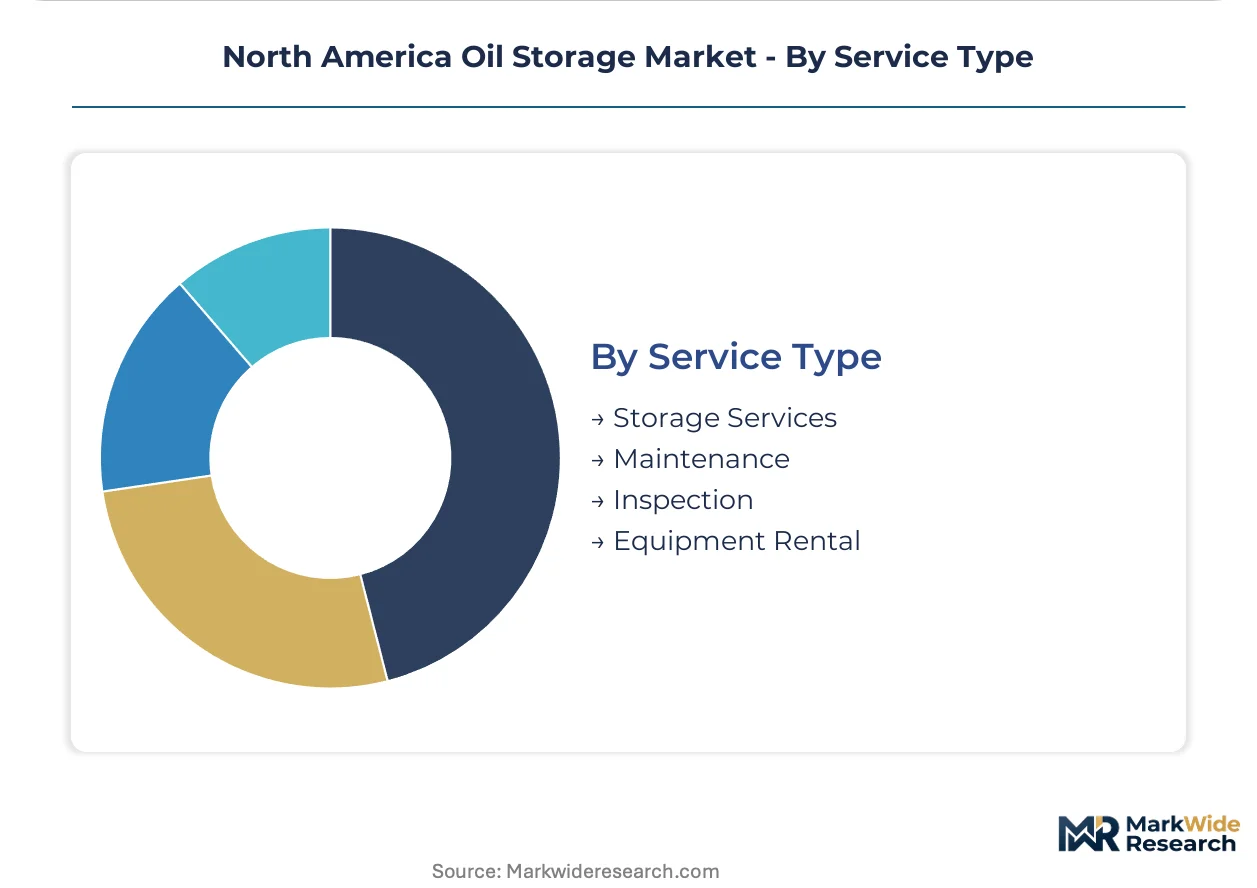
- Storage Services:Throughput fees, heating, blending, and throughput guarantees generate recurring revenue for terminal operators with pipeline-integrated positions.
- Inspection:API 653 external and internal assessments with ultrasonic thickness measurement face certified inspector shortages extending outage schedules.
- Maintenance:Coating rehabilitation, floating roof seal replacement, and foundation repair demand concentrates among legacy infrastructure owners.
- Equipment Rental:Temporary tankage and pumping systems serve emergency response and planned turnaround periods.
Storage Services generates revenue concentration; Inspection is expanding fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified API 653 inspectors and specialized coating applicators cluster along the Gulf Coast, anchoring North America's oil storage workforce concentration. This talent density shapes terminal economics and compliance timelines across the region's tank farm corridors.
United States
Gulf Coast refineries in Texas and Louisiana drive heated tankage demand for Canadian heavy sour crude acceptance. EPA SPCC rules mandate secondary containment expansion across hurricane-exposed terminals in Corpus Christi and Houston. The Houston Ship Channel anchors the continent's densest tank farm cluster, where Kinder Morgan and Magellan Midstream Partners maintain pipeline-integrated storage positions.
Canada
Alberta oil sands producers require insulated containment systems for bitumen and diluted bitumen export staging. The Canada Energy Regulator imposes integrity management standards on federally regulated pipelines and associated tankage. Edmonton and Hardisty terminal clusters concentrate working storage capacity for Trans Mountain Pipeline and Keystone system feedstocks.
Mexico
Energy reform liberalization opens Pemex terminal access at Tuxpan and Veracruz for cross-border midstream development. Mexico's national hydrocarbons regulator establishes storage licensing frameworks for private terminal operators. The Tuxpan marine terminal corridor attracts US midstream investment for refined product and crude export staging.
North America Oil Storage Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across North American oil storage, creating a tiered vendor structure. Midstream operators with pipeline-integrated positions capture recurring throughput revenue, while independent tank fabricators and coating specialists fragment across project-based maintenance cycles. Three archetypes dominate: pipeline-integrated terminal operators, specialized corrosion protection contractors, and modular fabrication houses. Capacity expansion and strategic terminal access partnerships constitute the dominant competitive moves as export terminal buildouts accelerate.
Among pipeline-integrated operators, Kinder Morgan and Magellan Midstream Partners exemplify the captive throughput model. TF Warren Group occupies a specialist position in corrosion-resistant coating systems for sour crude service. These three companies represent the archetype spectrum from infrastructure-scale storage services to niche technical applications.
| Leading Market Players |
|---|
| Manchester Tank |
| TF Warren Group |
| Mcdermott International Ltd. |
| Magellan Midstream Partners |
| Kinder Morgan |
| Shawcor |
| Hassco Industries |
| Buckeye Partners |
| Matrix NAC |
| Others |
Value Network & Pricing Analysis
Pipeline-integrated terminal operators anchor pricing power through captive throughput positions along the Houston Ship Channel and Corpus Christi corridors. This vertical integration into storage services insulates incumbents from spot market volatility while forcing independent tankage providers toward unbundled service tiers.
Pricing Analysis
Capacity additions in Texas and Louisiana are reshaping price floors for heated tankage serving Canadian heavy crude acceptance. Contract-based long-term offtake dominates refinery captive storage, while spot storage fragments into shorter-duration arrangements with unbundled heating and blending fees. Price differentiation hinges on vapor recovery certification tier and pipeline connectivity depth. Margins are tightening for legacy fixed-roof facilities facing floating roof conversion mandates. Independent traders exhibit highest price sensitivity; integrated refiners prioritize throughput reliability over per-barrel storage rates.
Supply Chain Analysis
Dual-sourcing requirements for API 653-certified inspectors and specialized coating applicators concentrate vendor qualification along the Gulf Coast corridor. Carbon steel plate fabrication draws from domestic US mills and Canadian rolled steel producers, with cathodic protection systems sourcing from specialized electrochemical suppliers. Supply chain risk centers on single-source vulnerability for sour-service lining applicators qualified under NACE standards. Distribution runs through pipeline-integrated terminal networks with rail and marine backup connectivity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America oil storage market functions as a regulatory compounder where EPA SPCC rule expansion and state-level VOC mandates continuously refresh compliance-driven demand.
For Market Incumbents: Anchor market position through pipeline-integrated capacity additions at export terminal nodes. Defend against trader-driven spot fragmentation by unbundling service tiers while maintaining throughput guarantees. Prioritize backward integration into specialized coating application capabilities to capture retrofit cycles. Invest in drone-based inspection certification to compress outage durations and differentiate maintenance service offerings. For New Entrants and Emerging Players: Launch via cross-border terminal development at Mexico's Tuxpan and Veracruz corridors under energy reform liberalization. Target independent trader demand with modular, rapid-deploy tankage for shorter-duration contracts. Exploit API 653 inspector scarcity by building certified inspection capabilities as a service wedge. Focus initial penetration on heated storage for high-viscosity Canadian crude acceptance where incumbent capacity constraints create white space. For Investors and Strategic Acquirers: Consolidation pressure builds where pipeline-integrated operators seek captive throughput positions and specialized coating applicators face generational ownership transition. Long-term viability favors assets with dual connectivity to pipeline and marine export infrastructure. Acquisition targets include regional inspection contractors with certified inspector rosters and modular fabrication houses with sour-service lining qualifications. Monitor California LCFS carbon intensity benchmarking adoption as inflection signal for premium storage tier emergence.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Export terminal expansions along Corpus Christi and Brownsville channels anchor Gulf Coast storage growth. |
| Backward Integration | Terminal operators acquiring coating applicators capture recurring maintenance revenue from legacy tankage. |
| Technology Licensing | Floating roof seal designs licensed under CARB and TCEQ mandates displace fixed-roof alternatives. |
| Vertical Integration into Storage | |
| Green Certification Program | Low-carbon intensity storage tiers under California LCFS attract premium contract structures. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged terminal operations managers, API 653 certified inspectors, midstream procurement leads, and petrochemical feedstock planners across the US Gulf Coast, Alberta, and Mexico's Tuxpan corridor. Secondary validation drew from EPA SPCC enforcement data, EIA storage capacity surveys, FERC pipeline filings, and Canada Energy Regulator integrity management disclosures. Bottom-up tankage capacity counts triangulated against top-down midstream revenue segmentation.
Historical reference periods anchored volume and value trajectories across the projection horizon. The analytical framework modeled containment technology type, end-user segment, installation category, and service tier alongside crude slate viscosity classification and regulatory compliance status. CAGRs derived from segmented growth rate reconciliation against macro energy demand indicators. Industry-specific forecast inputs included Canadian oil sands production outlooks and Gulf Coast ethane export capacity buildouts.
Forecast precision tightens around the base case; tail outcomes carry wider variance under carbon intensity benchmark adoption timing and inspector certification pipeline constraints. Forecasts reflect documented assumptions regarding EPA rule implementation schedules and Mexico energy reform continuity. Deviation in Canadian heavy crude export pipeline utilization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
India Oil and Gas Midstream Market
Oil & Gas
India AI in Oil and Gas Market
Oil & Gas
North America Frac Sand Market
Oil & Gas
Subsea Well Intervention Market
Oil & Gas
Rig and Oilfield Mats Market
Oil & Gas
North America Fracking Chemicals Market
Oil & Gas
Gold Mining Market
Oil & Gas
Southeast Asia LNG Market
Oil & Gas
Malaysia Oil and Gas Midstream Market
Oil & Gas
Europe Completion Equipment and Services Market
Oil & Gas
Injection Well Market
Oil & Gas
Seismic Survey Equipment Market
Oil & Gas
Middle East and Africa Early Production Facility Market
Oil & Gas
Central Asia Oil and Gas Midstream Market
Oil & Gas
Subsea Flowlines Market
Oil & Gas
Oil and Gas Logistics Market