
 Fuel Oil Market | 2026-2036
Fuel Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Oil Market Intelligence
The International Maritime Organization's (IMO) global sulfur cap is repositioning the competitive landscape for marine fuel suppliers. Shell leverages its global refinery network to supply compliant low-sulfur fuel oils. ExxonMobil competes on the development of advanced lubricant formulations compatible with new fuel types. Saudi Aramco anchors its market position through large-scale crude-to-chemicals projects that influence feedstock availability.
Fuel oil refers to a range of liquid petroleum products, fractions from crude oil distillation, that are heavier than gasoline and naphtha. These products, including residual fuel oil, are characterized by high viscosity and density, serving primarily as energy sources for engines and furnaces. Demand within the marine fuel segment is shifting towards lower sulfur content, while the power generation application remains a mature but substantial volume driver. Heating oil for residential heating constitutes a seasonal and geographically concentrated market segment.
Regulatory frameworks from bodies like the U.S. Environmental Protection Agency (EPA) and standards under the EU's Green Deal dictate emissions limits for industrial furnaces. The International Organization for Standardization (ISO) provides specifications, such as ISO 8217 for marine fuels, ensuring quality and interoperability. Producers must now navigate a dual challenge: meeting stricter environmental mandates while ensuring fuel compatibility for a diverse and aging global equipment fleet.
Market Dynamics
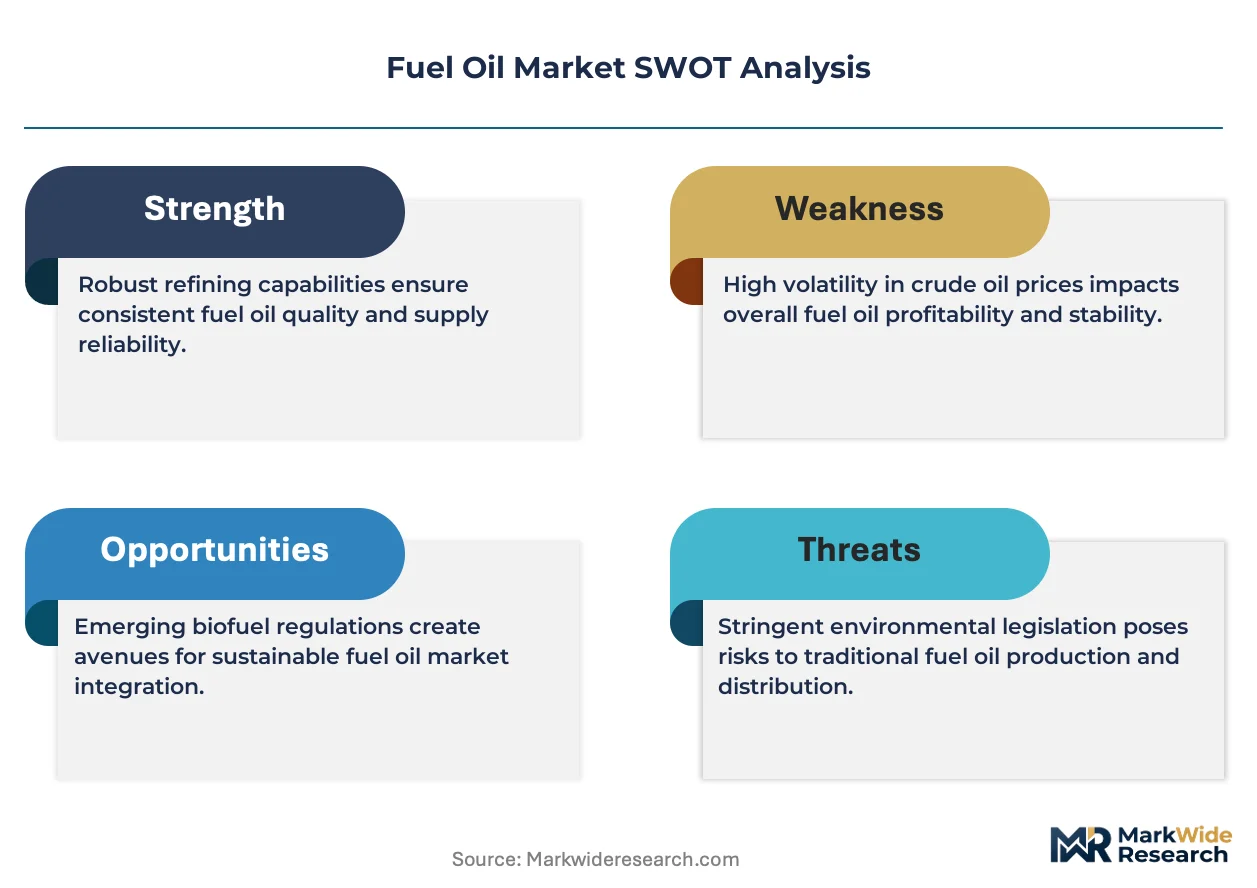
The International Maritime Organization's global sulfur cap is the central structural force shaping the fuel oil market. This regulation compels a fundamental shift in refinery output and marine fuel product specifications, altering competitive dynamics for suppliers and operational realities for end-users in shipping.
Growth Catalysts
- IMO 2020 Compliance:The ongoing enforcement of the International Maritime Organization's sulfur cap mandates the use of very low sulfur fuel oil, creating sustained demand from the global shipping fleet for compliant products.
- Asian Industrialization:Power generation and industrial furnace applications in rapidly industrializing economies, particularly in Southeast Asia, provide a substantial volume floor for residual fuel oil grades.
- Scrubber Adoption Lag:Slower-than-expected retrofitting of exhaust gas cleaning systems on older vessels forces a larger portion of the marine fleet to purchase more expensive compliant fuels directly, boosting demand.
Market Restraints
- Alternative Fuel Penetration:The increasing viability of liquefied natural gas and second-generation biofuels as alternative marine fuels presents a long-term substitution threat, capping growth potential for conventional fuel oil.
- Refinery Economics:High capital expenditure required for refinery upgrades, such as delayed coker units, limits the supply elasticity of compliant low-sulfur fuels and pressures margins for less complex refineries.
- Regional Emission Standards:A patchwork of stricter regional emissions regulations beyond the IMO framework, such as those in EU and Californian ports, creates operational complexity and compliance costs for ship operators.
Strategic Opportunities
- Crude-to-Chemicals Integration:Leveraging fuel oil streams as feedstock for advanced crude-to-chemicals projects offers a pathway to higher-margin products, diversifying revenue away from combustion-only applications.
- Bunkering Hub Modernization:Investing in digitalized and efficient bunkering infrastructure in emerging hubs outside of Singapore, such as in the Middle East or Latin America, can capture regional demand growth.
- Advanced Lubricant Development:Formulating specialized marine lubricants optimized for new VLSFO and ULSFO blends creates a valuable, tied-in product offering that addresses engine performance and compatibility concerns.
Industry Challenges
- Fuel Blend Incompatibility:Ensuring the stability and compatibility of various VLSFO blends from different suppliers remains a significant operational challenge for vessel engineers, risking engine damage and downtime.
- Supply Chain Quality Assurance:The complexity of new fuel blends requires more rigorous onboard and shoreside testing to meet ISO 8217 standards, increasing the burden on supply chain logistics and verification processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Oil Market |
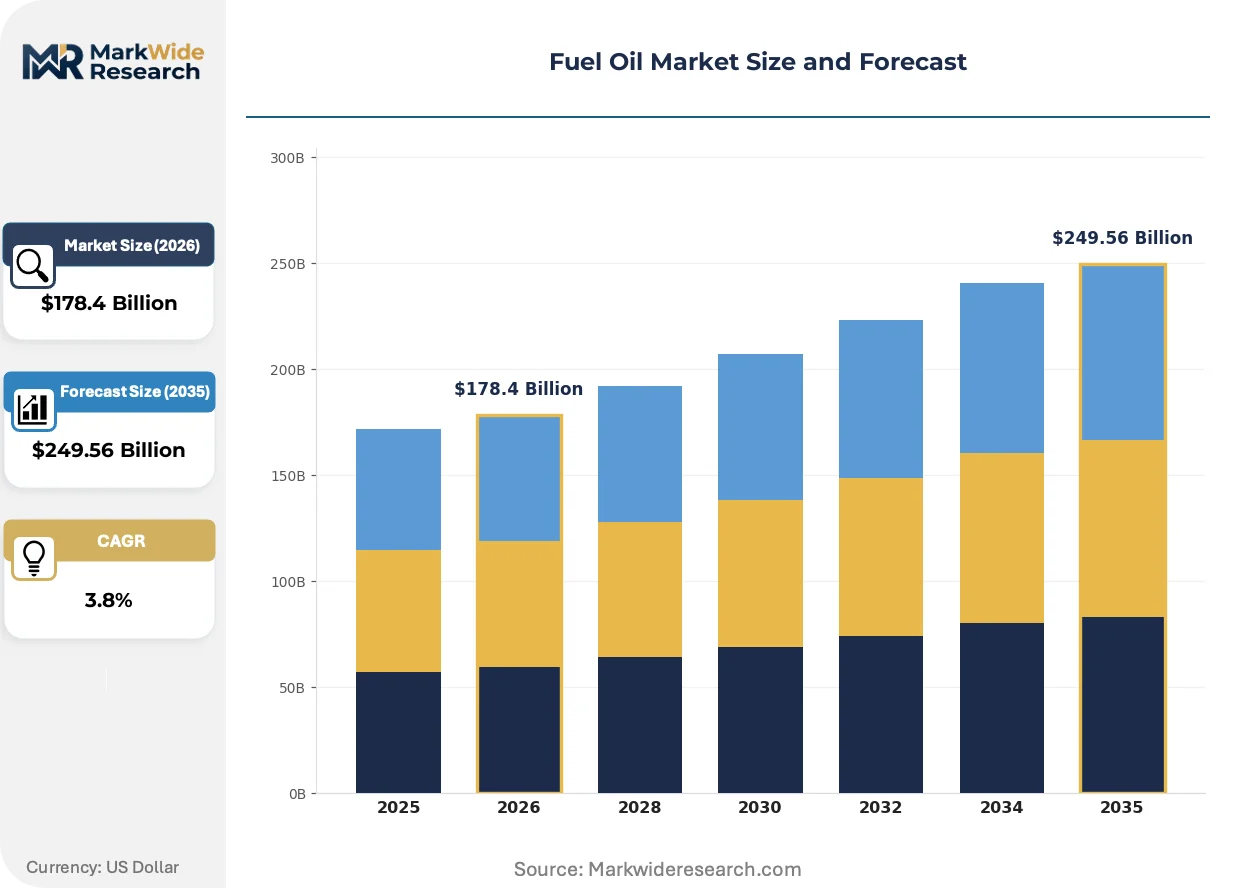
| Market Size in 2026 | $178.4 Billion |
| Market Size in 2035 | $249.56 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diesel Fuel, Residual Fuel Oil, Marine Fuel, Heating Oil, Lubricants Application: Power Generation, Industrial Furnaces, Marine Propulsion, Residential Heating, Agricultural Equipment Distribution Channel: Direct Sales, Wholesale Distributors, Retail Fuel Stations, Online Procurement, Bulk Supply End User: Power Plants, Manufacturing Facilities, Shipping Companies, Commercial Buildings, Farming Cooperatives |
| Companies Covered | Saudi Aramco, ExxonMobil, Chevron, Shell, PetroChina, TotalEnergies, BP, ENEOS Holdings, SK Innovation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Oil Market Strategic Shifts & Innovations
The fuel oil market is defined by a dual adaptation to stringent environmental rules and the technological realities of a diverse global equipment fleet. This forces innovation in product formulation, regulatory navigation, and commercial models.
Advanced sensor-based onboard fuel monitoring systems provide real-time data on fuel quality, consumption, and emissions. Ship operators and fleet managers are adopting these systems to ensure compliance and optimize engine performance. This data-driven approach is consolidating the market around suppliers who can guarantee consistent fuel quality and offer digital integration, marginalizing smaller blenders.
The European Union's "Fit for 55" package and its FuelEU Maritime initiative introduce greenhouse gas intensity reduction targets for marine fuels. This regulation forces a lifecycle assessment approach, moving beyond just sulfur content to consider the carbon footprint of production and transport. The power generation segment using fuel oil is also affected by tightening emissions limits under the EU's Industrial Emissions Directive.
A shift toward shorter-term, index-linked supply contracts is replacing traditional fixed-price annual agreements for large shipping lines. This change reflects volatility in both crude prices and the VLSFO-HSFO price spread, disrupting long-term planning for both suppliers and buyers. This trend is most pronounced in major bunkering hubs like Singapore and Rotterdam, where pricing transparency is highest.
Fuel Oil Market Segmentation
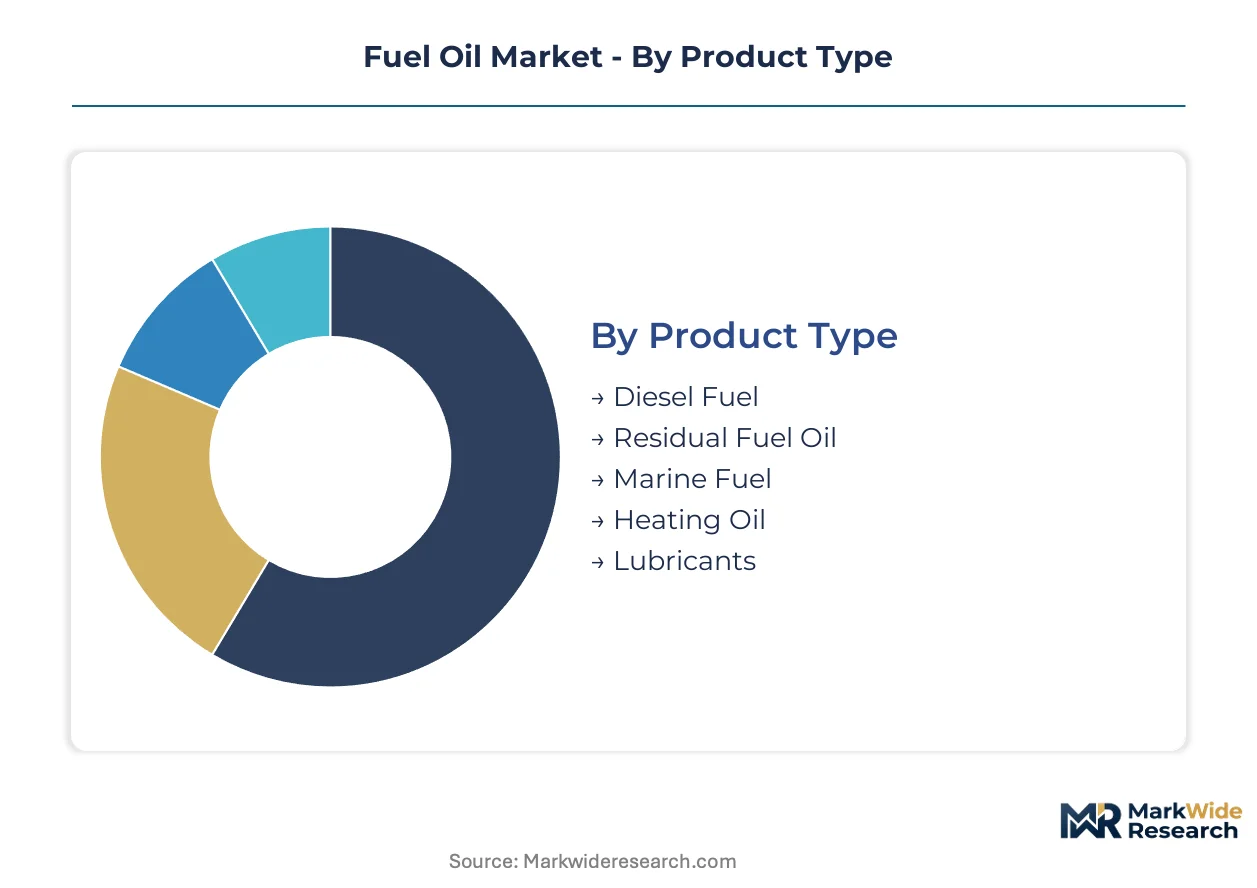
The Fuel Oil market's segmentation provides a granular understanding of demand drivers and supply chain complexities. Distinct product formulations and diverse end-use applications require tailored strategies from suppliers. Analyzing these segments reveals varying regulatory pressures and technological adaptation needs across the industry.
Product Type:
The upgrade and replacement cycles within industrial and marine equipment significantly influence the demand for specific fuel oil product types.
- Diesel Fuel:This refined petroleum product is primarily used in compression-ignition engines, serving transportation, industrial, and agricultural sectors globally. Diesel fuel quality standards, such as those set by the U.S. Environmental Protection Agency (EPA), dictate sulfur content and cetane number.
- Residual Fuel Oil:Characterized by high viscosity and density, this heavy fraction from crude oil distillation serves as a primary energy source for industrial furnaces and power generation plants. Demand for this product is concentrating in rapidly industrializing economies like Vietnam and Indonesia, driven by sustained energy requirements.
- Marine Fuel:Specifically formulated for ship engines, this category includes Very Low Sulfur Fuel Oil (VLSFO) and Ultra Low Sulfur Fuel Oil (ULSFO), mandated by the International Maritime Organization (IMO) sulfur cap. Demand is particularly high in major bunkering hubs such as Singapore and Rotterdam, where shipping companies prioritize compliant fuels.
- Heating Oil:A light fuel oil grade, heating oil provides warmth for residential and commercial buildings, primarily in regions with cold climates.
- Lubricants:These specialized oils reduce friction and wear in engines and machinery, with formulations increasingly adapting to new, lower-sulfur fuel types.
Residual Fuel Oil sits at the top of the volume ranking, with Marine Fuel climbing the fastest.
Application:
Specific applications dictate the volume and quality requirements for fuel oil, influencing procurement patterns across diverse industrial sectors.
- Power Generation:Heavy fuel oil serves as a substantial energy source for thermal power plants, especially in regions with limited natural gas infrastructure or as a backup fuel. Utility companies in countries like India and Pakistan maintain consistent demand for reliable grid stability.
- Industrial Furnaces:This application segment encompasses various manufacturing processes requiring high-temperature heat, such as cement production, steelmaking, and glass manufacturing. Manufacturing facilities in China and Brazil utilize fuel oil for its consistent energy output.
- Marine Propulsion:The global shipping fleet relies on fuel oil to power vast cargo vessels, tankers, and passenger ships across international waters. The International Maritime Organization's regulations are forcing a shift towards lower sulfur content fuels for this critical transport sector.
- Residential Heating:Smaller volumes of heating oil provide warmth for homes, particularly in older housing stock or rural areas lacking natural gas connections.
- Agricultural Equipment:Diesel fuel powers tractors, harvesters, and other heavy machinery essential for modern farming operations.
Marine Propulsion demonstrates significant growth, while Power Generation maintains a substantial volume base.
Distribution Channel:
The efficiency and scale of distribution channels determine the accessibility and pricing of fuel oil products for various end-user segments.
- Direct Sales:Large industrial consumers and shipping lines often negotiate direct contracts with refiners or major fuel suppliers for bulk volumes. This channel facilitates customized supply agreements and technical support for complex fuel requirements.
- Wholesale Distributors:These intermediaries purchase fuel oil in large quantities from producers and then resell it to smaller businesses, commercial fleets, or retail outlets. Wholesale networks are crucial for reaching dispersed industrial and commercial clients.
- Retail Fuel Stations:Primarily serving smaller consumers of diesel fuel for vehicles and light equipment, these stations offer convenient access for on-road and off-road users.
- Online Procurement:Digital platforms are emerging for transparent pricing and efficient ordering of fuel oil, particularly for commercial fleets and smaller industrial users.
- Bulk Supply:This channel involves the delivery of large quantities of fuel oil directly to industrial sites, power plants, or marine bunkering operations via pipelines, barges, or rail.
Direct Sales accounts for the largest transaction volumes, with Online Procurement showing notable expansion.
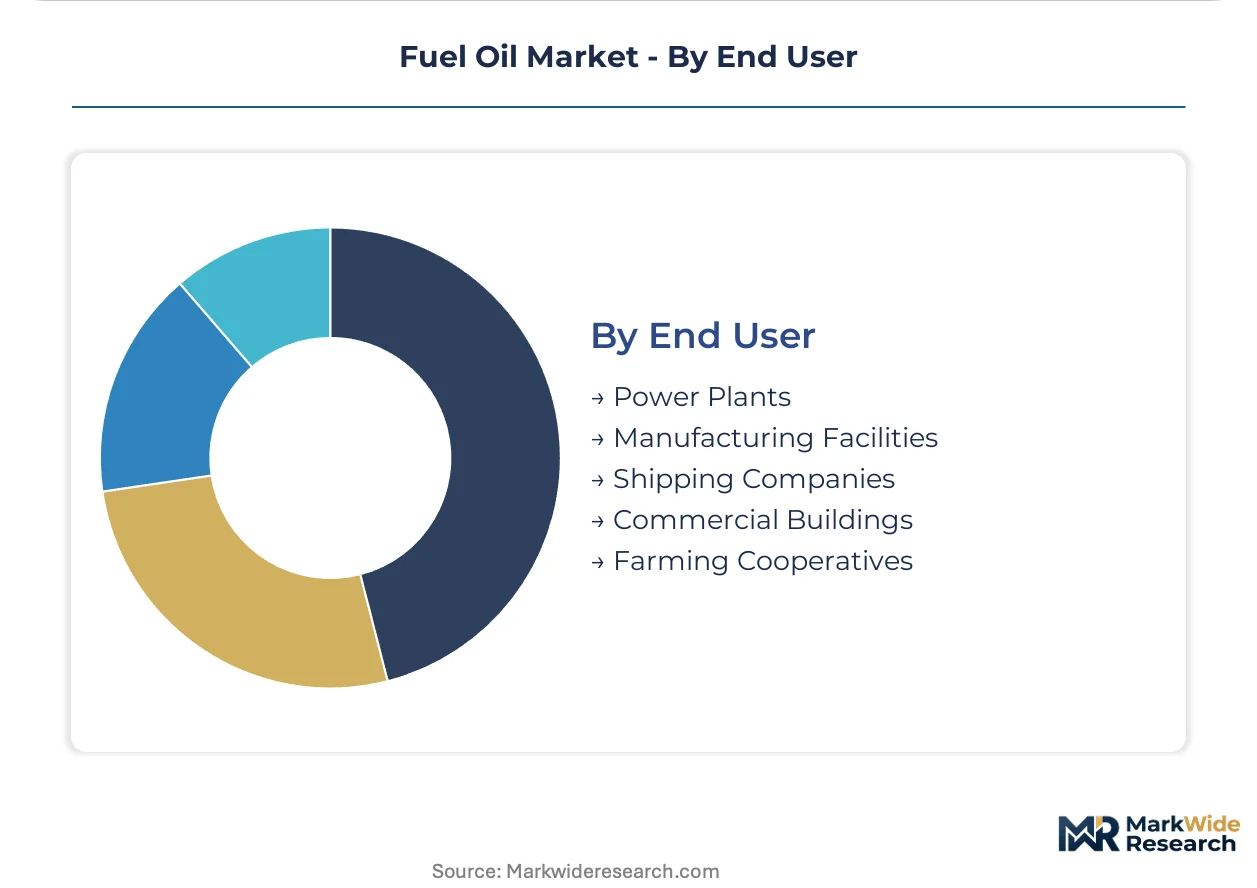
End User:
The operational scale and regulatory environment impacting specific end-user categories significantly shape their fuel oil consumption patterns.
- Power Plants:Large-scale electricity generation facilities, particularly those operating in emerging markets or as peak-load plants, consume substantial volumes of residual fuel oil. These utilities often manage complex supply logistics to ensure continuous operation.
- Manufacturing Facilities:Industrial plants across various sectors, including chemicals, textiles, and food processing, utilize fuel oil for process heat and steam generation. Companies in Germany and Japan comply with strict emissions limits under the EU's Industrial Emissions Directive.
- Shipping Companies:Global maritime operators represent a critical end-user segment, with demand heavily influenced by international trade volumes and environmental regulations like the IMO 2020 sulfur cap. Major container lines and bulk carriers are adapting their fleets to compliant fuels.
- Commercial Buildings:Businesses and institutions use heating oil for space heating and hot water systems, especially in regions with colder climates.
- Farming Cooperatives:Agricultural organizations procure diesel fuel for their members' machinery, supporting crop production and livestock management.
Shipping Companies are undergoing the most significant transformation in their fuel usage, while Power Plants remain a consistent volume consumer.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global fuel oil market's foundational growth emerged from the industrial revolution, particularly with the widespread adoption of crude oil refining. Early applications concentrated in industrial furnaces and marine propulsion. Today, regional dynamics reflect diverse energy needs and stringent environmental mandates.
Singapore
Singapore's demand for marine fuel remains robust due to its status as a premier bunkering hub. The International Maritime Organization's sulfur cap mandates strict adherence to compliant fuel specifications. The Port of Singapore continues to see high concentration of very low sulfur fuel oil procurement by shipping companies.
China
China's industrial furnace and power generation sectors sustain substantial demand for residual fuel oil. The Ministry of Ecology and Environment (MEE) enforces increasingly stringent emissions limits on industrial operations. Manufacturing facilities in the Yangtze River Delta actively consume fuel oil for consistent energy output.
United States
Demand for diesel fuel in transportation and heating oil for residential use drives consumption across the United States. The U.S. Environmental Protection Agency (EPA) dictates sulfur content and quality standards for various fuel types. Residential heating oil requirements are particularly concentrated in the Northeast region during colder seasons.
Netherlands
The Netherlands experiences significant marine fuel demand, particularly for international shipping lanes. The EU's FuelEU Maritime initiative introduces greenhouse gas intensity reduction targets for marine fuels. Major bunkering operations at the Port of Rotterdam prioritize the supply of compliant low-sulfur products.
India
India's power generation sector and industrial furnaces provide a consistent volume base for fuel oil consumption. The Central Electricity Authority (CEA) monitors fuel supply and usage for grid stability across the nation. Thermal power plants in Gujarat utilize residual fuel oil to maintain reliable electricity supply.
Fuel Oil Market Key Industry Players
Capital-heavy producers compete with asset-light designers for market share within the global fuel oil sector. The market structure is tiered, reflecting diverse operational scales and strategic focuses. Integrated oil majors, specialized refiners, and independent traders constitute key strategic archetypes. Companies engage in significant capacity expansion initiatives to meet evolving fuel specifications, particularly for low-sulfur products. Strategic partnerships also foster compliance solutions and market reach for complex supply chains, addressing compatibility challenges.
Integrated oil majors like Saudi Aramco and ExxonMobil anchor significant market positions through extensive refining capabilities and global supply networks. These entities represent the large-scale, upstream-to-downstream archetype within the industry, influencing feedstock availability for various products. Shell also exemplifies a global footprint, leveraging its vast network for compliant fuel supply across major bunkering hubs like Singapore and Rotterdam. These companies often drive portfolio diversification into adjacent chemical products, seeking higher-margin opportunities beyond traditional combustion applications. Their operational scale allows for substantial investment in refinery upgrades to meet new sulfur regulations and ensure product quality.
| Leading Market Players |
|---|
| Saudi Aramco |
| ExxonMobil |
| Chevron |
| Shell |
| PetroChina |
| TotalEnergies |
| BP |
| ENEOS Holdings |
| SK Innovation |
| Others |
Cost & Logistics Intelligence
Shipping companies' procurement patterns are shifting towards shorter-term, index-linked supply contracts, reflecting the inherent volatility in crude prices and the VLSFO-HSFO price spread. This dynamic pricing environment influences supplier margins and operational planning across the entire fuel oil supply chain.
Pricing Analysis
Index-linked supply contracts dominate pricing for marine fuels, particularly in major bunkering hubs like Singapore and Rotterdam. Price differentiation stems from fuel quality specifications such as Very Low Sulfur Fuel Oil (VLSFO) versus High Sulfur Fuel Oil (HSFO), and the specific geographic delivery costs. Pricing softness stems from the ongoing volatility in crude oil benchmarks and the fluctuating spread between compliant and non-compliant fuel grades. Shipping companies demonstrate high price sensitivity, constantly seeking competitive rates, while industrial furnace operators prioritize consistent supply over marginal price differences for continuous operations.
Supply Chain Analysis
Reverse logistics for fuel oil, primarily concerning managing off-spec batches or tank residues, constitutes a minor but critical flow within the broader supply chain. Geographic supply concentration centers on major refining hubs in Saudi Arabia, the United States, and the Netherlands. The supply chain relies on crude oil as its primary raw material and adequate refinery capacity, particularly delayed coker units, for producing compliant low-sulfur products. Commodity price volatility, driven by global crude markets, represents a significant structural risk. Bulk supply via pipelines, barges, and rail directly to industrial sites and bunkering operations forms the dominant distribution model.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fuel oil market operates as a regulatory compounder, with the International Maritime Organization's (IMO) 2020 sulfur cap continuing to drive demand for compliant products. Strategic adaptation is essential for all market participants.
For Market Incumbents:Lock in long-term supply agreements with major shipping lines to secure consistent demand for Very Low Sulfur Fuel Oil (VLSFO). Invest in refinery upgrades, specifically delayed coker units, to increase compliant fuel production and diversify into crude-to-chemicals streams. This strategy mitigates the long-term threat from alternative marine fuels like LNG and biofuels, while addressing stricter regional emission standards. Shell and ExxonMobil leverage their global networks to offer integrated solutions to shipping companies.
For New Entrants and Emerging Players:Enter via niche product formulations, such as specialized marine lubricants optimized for new VLSFO blends, addressing engine compatibility concerns for vessel operators. Target emerging bunkering hubs in regions like the Middle East or Latin America by investing in digitalized and efficient infrastructure. A technology-driven go-to-market angle, focusing on consistent fuel quality assurance and digital integration, can attract smaller shipping operators and industrial users in rapidly industrializing economies.
For Investors and Strategic Acquirers:Integrated oil majors are the most active acquirers in this space, seeking to consolidate refining assets and expand distribution networks. The market retains long-term viability for essential marine propulsion and industrial power generation over the next 5-10 years, despite transition pressures. Acquisition targets should include specialized refiners with advanced coking capacity or developers of advanced fuel monitoring technologies. Investors should monitor the pace of alternative fuel infrastructure buildout and the tightening of EU FuelEU Maritime targets as key inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Refinery Modernization | Ensures compliance with IMO 2020 by producing compliant low-sulfur fuels for global shipping. |
| Crude-to-Chemicals Integration | Diversifies revenue streams by converting fuel oil into higher-margin chemical feedstocks. |
| Digital Bunkering Platform Investment | Enhances transparency and efficiency for shipping companies in major marine hubs. |
| Advanced Lubricant R&D | Addresses engine compatibility issues for diverse VLSFO blends, ensuring fleet operational integrity. |
| Supply Chain Optimization in Asia | Captures sustained demand from industrialization and marine traffic in Southeast Asian economies. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with robust secondary validation. Stakeholders included marine fuel procurement managers, refinery operations directors, environmental compliance officers, and shipping fleet engineers. Secondary data sources encompassed IMO regulations, EPA reports, EU Green Deal documents, ISO 8217 standards, and various trade association publications. This comprehensive approach allowed for both bottom-up and top-down triangulation of market data.
The forecast framework anchored historical data analysis to project market trends across the analysis window. Segmentation dimensions modeled included product type (VLSFO, ULSFO, residual fuel oil), application (marine propulsion, power generation), distribution channel, end-user, and regional regulatory environments. Compound annual growth rates were derived from detailed demand forecasts and supply capacity projections. Global shipping traffic volumes, refinery coking capacity, and alternative fuel adoption rates served as critical industry-specific forecast inputs.
Inputs from regulatory bodies and industry associations were available through the study window; gaps in real-time global shipping fleet compliance data introduce uncertainty bands. Forecasts reflect assumptions regarding geopolitical stability and economic growth. Practitioners should monitor regulatory updates from the IMO and EU, alongside refinery investment cycles, for early signals of market shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
LPG Gas Cylinder Market
Fuels
Middle-East and Africa Bunker Fuel Market
Fuels
Mobile Fuel Delivery Market
Fuels
Industrial Fuel Filter Market
Fuels
Collapsible Fuel Tank Market
Fuels
Fuel Quality Testing Market
Fuels
Saudi Arabia Fuel Station Market
Fuels
Bituminous Coal Market
Fuels
Europe Aviation Fuel Market
Fuels
Marine Fuel Optimization Market
Fuels
Global Charcoal Market
Fuels
India LNG Market
Fuels
Oil Dispensing Stations Market
Fuels
Wood Charcoal Market
Fuels
Caribbean Islands Bunker Fuel Market
Fuels
Global Fuel Ethanol Market