
 Swellable Packers Market | 2026-2036
Swellable Packers Market Size, Share, and Industry Trends Forecast 2026-2036
Swellable Packers Market Analysis
API 19OH is decoupling low-cost packer suppliers from premium contract tiers by mandating extended thermal cycling validation and elastomer compatibility testing. Weatherford leverages its integrated manufacturing footprint to sustain qualification pipelines across multiple basin types. Halliburton Energy Services, Inc. dominates high-temperature applications through proprietary nitrile and hydrogenated nitrile compound formulations. Baker Hughes Company differentiates via coiled-tubing-deployable swellable systems that reduce rig time in extended-reach laterals.
Swellable packers are downhole sealing devices comprising elastomeric sleeves bonded to mandrels that expand upon contact with wellbore fluids to create zonal isolation barriers, typically rated for differential pressures exceeding 5,000 psi and temperatures to 150°C. Their primary purpose is to replace mechanical set-and-release packers in open-hole completions, eliminating moving parts and reducing failure modes in horizontal and multilateral wells. Hydraulic swellable packers anchor margin pools in deepwater Gulf of Mexico and West Africa deployments where rig-day economics prioritize single-trip reliability. Formation testing applications within the oil and gas industry represent the fastest-growing end-use channel as operators shift from drillstem tests to wireline-conveyed, packer-isolated reservoir evaluation. Elastomer material formulations face margin compression from thermoplastic hybrid sleeves that extend chemical resistance in CO2-rich reservoirs.
OSHA process safety management requirements and EPA offshore discharge standards shape material selection and testing protocols for US-deployed swellable packers, while BIS certification pressures constrain import-dependent supply chains serving India's Cambay and Krishna-Godavari basins. The EU F-Gas Regulation indirectly affects packer manufacturing through restrictions on fluorinated elastomer precursors used in high-seal-performance compounds. Stakeholders must monitor evolving API qualification timelines and regional content mandates that determine supplier eligibility in Brazil, Nigeria, and Saudi Arabia's procurement frameworks.
Market Dynamics
API 19OH qualification timelines are compressing supplier eligibility windows while deepwater operators in Brazil and the Gulf of Mexico prioritize single-trip reliability over unit cost, reshaping competitive positioning toward integrated manufacturing capabilities.
Growth Catalysts
- Hydraulic swellable systems:Elastomeric sleeves activated by wellbore fluids eliminate mechanical setting mechanisms, reducing failure modes in extended-reach laterals where rig-day economics dominate operator decisions.
- EPA offshore discharge standards:Tightening environmental protocols for Gulf of Mexico completions are accelerating replacement of conventional packers with fluid-activated seals that minimize intervention waste streams.
- Brazil's pre-salt basins:High-pressure carbonate formations favor advanced nitrile and hydrogenated nitrile formulations capable of maintaining seal integrity above 150°C and 5,000 psi differential pressure.
Market Restraints
- Fluorinated elastomer precursor constraints:EU F-Gas Regulation restrictions on perfluorinated compound feedstocks are limiting domestic European production of high-seal-performance packer sleeves.
- Thermoplastic hybrid substitution:CO2-rich reservoir conditions in West Africa and the North Sea are displacing conventional elastomers with chemically resistant thermoplastic barrier layers.
- Extended thermal cycling validation:API 19OH mandates for multi-cycle qualification are extending certification timelines to 18-24 months, freezing out capital-constrained suppliers.
Strategic Opportunities
- Wireline-conveyed formation testing:Packer-isolated reservoir evaluation is displacing drillstem tests in tight-gas and shale formations, creating demand for slim-profile swellable seals.
- India's Cambay and Krishna-Godavari basins:BIS certification pressures on import-dependent supply chains create openings for locally qualified manufacturers with captive elastomer compounding.
- Coiled-tubing-deployable architectures:Integration with lightweight deployment systems enables zonal isolation in extended-reach laterals without conventional workover rigs.
Industry Challenges
- Compound formulation expertise scarcity:Hydrogenated nitrile development requires polymer scientists with deepwater elastomer experience, a talent pool concentrated among legacy suppliers.
- Multi-basin qualification pipeline management:Divergent thermal and chemical requirements across Brazil's pre-salt, Gulf of Mexico deepwater, and West Africa fields force parallel certification tracks.
- Legacy mechanical packer installed base:Existing well architectures in mature North Sea and Permian Basin fields complicate retrofit specifications for swellable alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Swellable Packers Market |
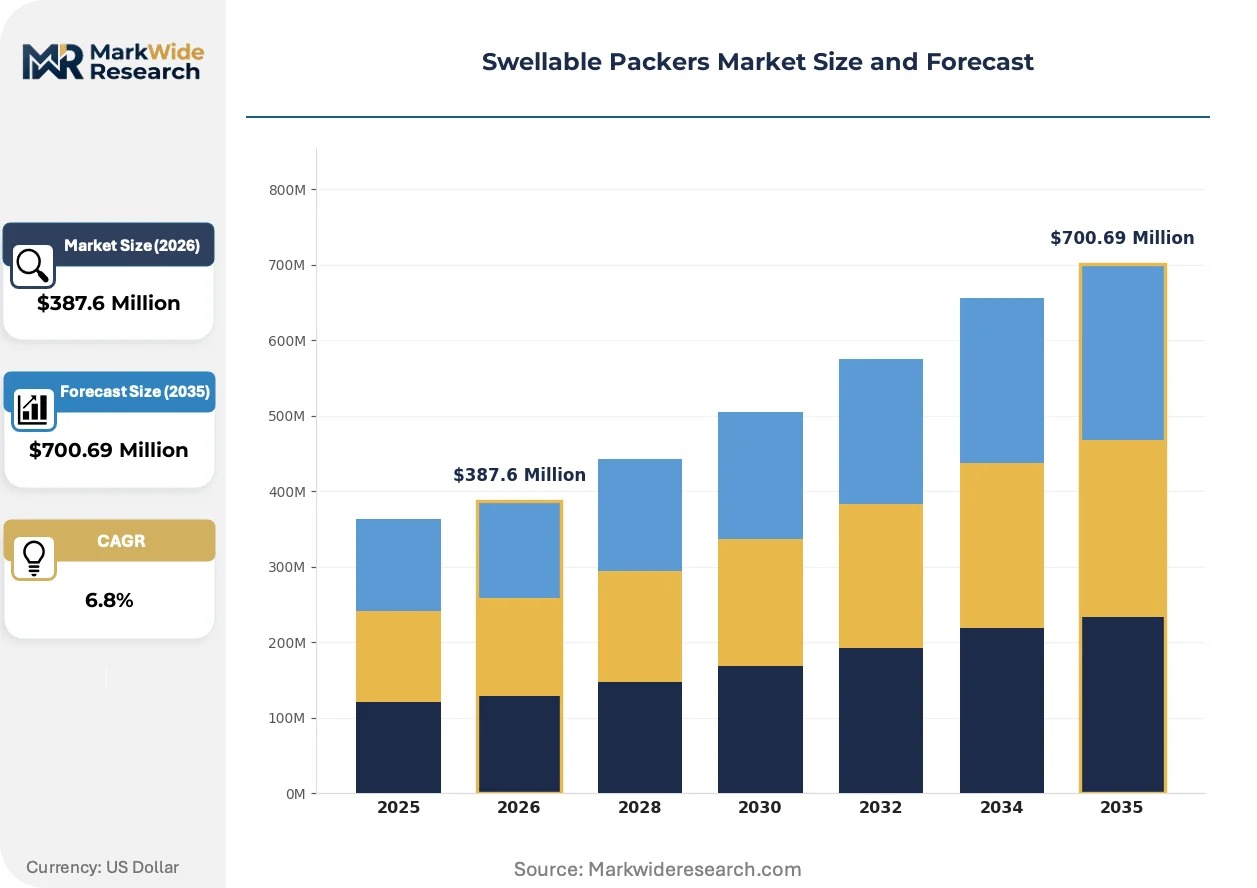
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Swellable Packers, Mechanical Swellable Packers, Coiled Tubing Packers, Others End User: Oil & Gas Industry, Water Well Industry, Mining Industry, Geothermal Sector Application: Well Isolation, Formation Testing, Pressure Maintenance, Production Enhancement Material: Elastomers, Thermoplastics, Metal Alloys, Composite Materials |
| Companies Covered | Weatherford, Nine Energy Service, Schlumberger Limited, Peak Completion Technologies Inc., Reactive Downhole Tools Limited, Halliburton Energy Services, Inc., TAM International, Inc., Tendeka, Baker Hughes Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Swellable Packers Market Emerging Trajectories
Elastomer science and deployment mechanics are converging to eliminate moving parts from downhole isolation, with material formulation and conveyance method innovations dominating supplier R&D allocation.
Thermoplastic hybrid barrier sleeves are expanding into high-CO2 reservoir applications where conventional nitrile compounds suffer rapid chemical degradation. Norwegian North Sea operators and West African deepwater projects are specifying these materials for expected 20-year service lives. The technology is expanding into premium contract tiers previously reserved for fluorinated elastomer systems, compressing margins on legacy compound categories.
REACH authorization requirements for persistent organic pollutants are forcing reformulation of high-temperature elastomer precursors used in European-manufactured packers. Compound suppliers must substitute bio-based plasticizers and curatives to maintain seal performance above 150°C. North Sea completion programs are experiencing 6-12 month material qualification delays as laboratories validate alternative chemistries against API 19OH protocols.
Operators are consolidating supplier relationships around integrated service providers capable of manufacturing, deploying, and retrieving swellable systems under single-contract accountability. This procurement compression is displacing standalone packer vendors in Brazil's pre-salt and Gulf of Mexico deepwater markets. Halliburton Energy Services and Weatherford are capturing expanded scope through bundled offerings that combine elastomer manufacturing with wireline deployment services.
Swellable Packers Market Segmentation
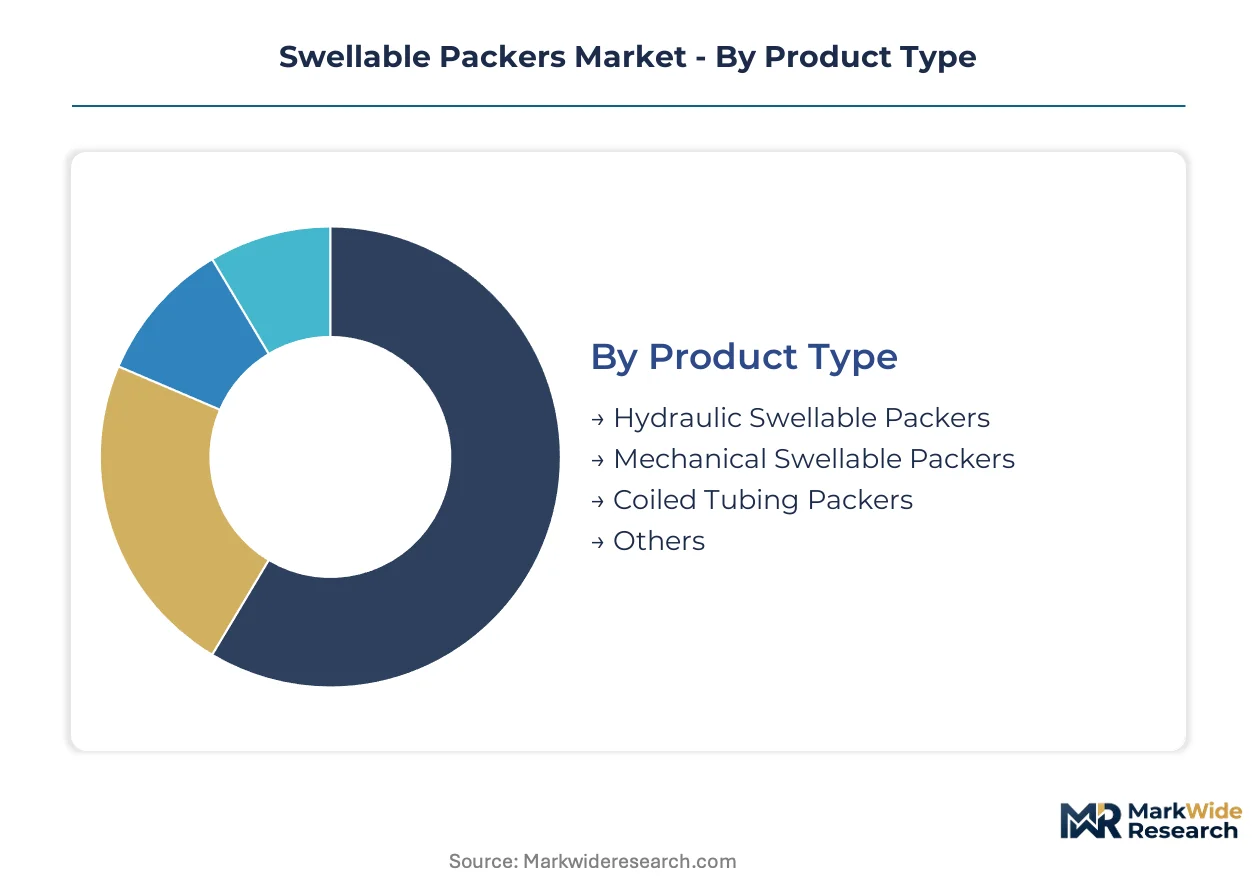
Swellable packer procurement decisions hinge on deployment mechanics and reservoir chemistry, with capital allocation varying dramatically across hydraulic activation systems versus mechanical alternatives. Material selection and application specificity determine qualification timelines and contract eligibility in deepwater basins.
Product Type:
Capital intensity peaks with coiled tubing-integrated architectures requiring precision manufacturing and real-time deployment telemetry, while hydraulic systems demand extensive elastomer R&D investment.
- Hydraulic Swellable Packers:Elastomeric sleeves expand upon contact with wellbore fluids, eliminating mechanical setting tools and reducing failure modes in extended-reach laterals. Demand concentrates in Brazil's pre-salt basins where single-trip reliability offsets premium unit costs against rig-day economics.
- Coiled Tubing Packers:Lightweight deployment systems enable zonal isolation without conventional workover rigs, integrating swellable seals with continuous conduit architecture. Gulf of Mexico operators prioritize these for marginal pool developments where platform crane capacity constraints limit conventional string weights.
- Mechanical Swellable Packers:Hybrid designs retain limited mechanical backup setting mechanisms for contingency activation in high-risk completions.
- Others:Specialty configurations include slim-profile wireline-conveyed variants for through-tubing interventions.
Most installed capacity flows through hydraulic swellable systems. Expansion is steepest in coiled tubing-integrated architectures.
End User:
Customer procurement scale varies from supermajor drilling programs spanning multiple basins to single-well geothermal developers with limited batch volume leverage.
- Oil & Gas Industry:Dominates absolute consumption with deepwater exploration budgets driving specification of API 19OH-qualified systems rated above 150°C and 5,000 psi differential pressure.
- Geothermal Sector:Emerging demand from high-temperature brine production favors thermoplastic hybrid barriers resistant to corrosive mineral content and thermal cycling fatigue.
- Water Well Industry:Municipal and agricultural groundwater extraction employs simplified elastomer formulations with reduced pressure ratings.
- Mining Industry:In-situ leaching and solution mining operations specify chemically resistant isolation barriers for controlled injection-recovery cycles.
Oil and gas operators command the largest procurement volumes. Geothermal applications are climbing the fastest as renewable baseload capacity expands.
Application:
Functional requirements span permanent zonal barriers versus retrievable evaluation tools, with qualification protocols diverging accordingly.
- Formation Testing:Packer-isolated reservoir evaluation displaces conventional drillstem tests, demanding slim-profile seals compatible with wireline conveyance and rapid deployment cycles. Tight-gas and shale operators in North American unconventional plays drive specification of retrievable elastomer systems.
- Well Isolation:Permanent zonal segregation in multilateral and horizontal completions requires 20-year seal integrity predictions validated through accelerated aging protocols.
- Pressure Maintenance:Injection well applications specify chemical compatibility with produced water and enhanced oil recovery fluids.
- Production Enhancement:Stimulation isolation barriers must survive aggressive acid and proppant slurry exposure during fracturing operations.
Well isolation retains the largest installed base. Formation testing is gaining share fastest as operators shift toward lower-cost reservoir evaluation.
Material:
Raw material sourcing and compounding expertise create tiered supplier capabilities, with fluorinated elastomer precursors facing regulatory constraints.
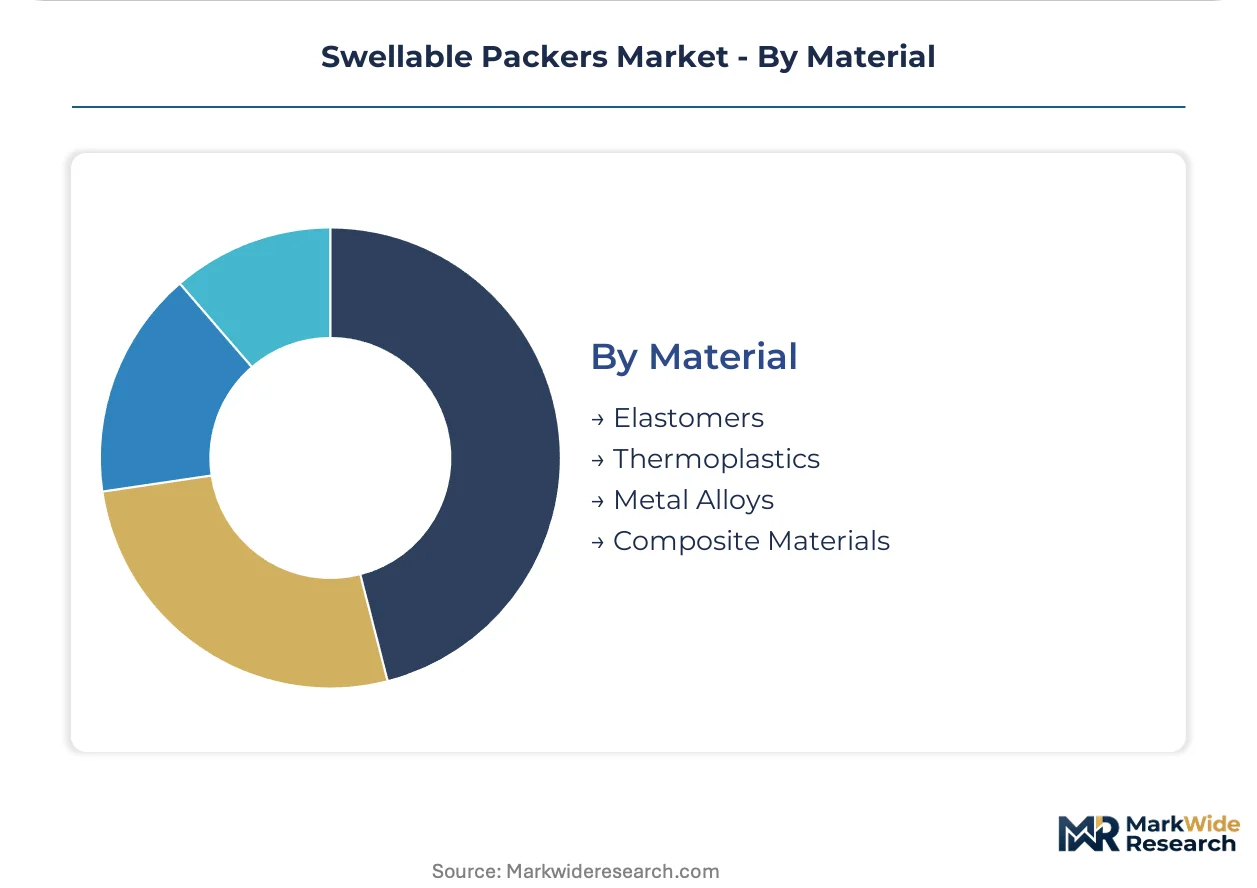
- Elastomers:Nitrile and hydrogenated nitrile compounds dominate conventional applications, with formulation expertise concentrated among legacy suppliers possessing deepwater qualification histories. Brazil's pre-salt carbonate formations favor advanced hydrogenated variants for thermal stability above 150°C.
- Thermoplastics:Hybrid barrier layers expand into high-CO2 reservoir applications where conventional elastomers suffer chemical degradation, with Norwegian North Sea and West African deepwater projects specifying 20-year service life predictions.
- Metal Alloys:Corrosion-resistant mandrel substrates anchor elastomeric sleeves in sour gas environments.
- Composite Materials:Lightweight fiber-reinforced architectures reduce deployment string weight for extended-reach laterals.
Elastomer systems carry the dominant installed capacity. Thermoplastic hybrids are expanding most quickly as CO2-rich reservoir developments proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petroleum engineers and elastomer compound specialists cluster around deepwater basins and pre-salt formations, concentrating technical expertise in Brazil, the United States, Norway, and West African coastal zones.
Brazil
Pre-salt carbonate formations drive specification of hydrogenated nitrile systems rated above 150°C. ANP regulatory frameworks mandate local content thresholds that favor domestic manufacturing partnerships. Rio de Janeiro anchors engineering centers where Halliburton and Baker Hughes maintain compound qualification laboratories serving Campos and Santos basin operators.
United States
Gulf of Mexico deepwater completions prioritize single-trip reliability over unit cost in marginal pool developments. EPA offshore discharge standards accelerate fluid-activated seal adoption to minimize intervention waste streams. Houston hosts the largest concentration of API 19OH qualification facilities, with Weatherford operating integrated manufacturing and testing campuses.
Norway
North Sea high-CO2 reservoirs specify thermoplastic hybrid barriers for 20-year service life predictions. REACH authorization requirements for persistent organic pollutants force reformulation of high-temperature elastomer precursors. Stavanger and Bergen clusters experience 6-12 month material qualification delays as laboratories validate alternative chemistries.
Nigeria
Deepwater field developments in the Niger Delta favor swellable systems for zonal isolation in extended-reach laterals. Local content mandates under Nigerian Oil and Gas Industry Content Development regulations constrain import-dependent supply chains. Lagos and Port Harcourt serve as procurement hubs where operators consolidate supplier relationships around integrated service providers.
Saudi Arabia
High-pressure carbonate formations in the Arabian Basin favor advanced elastomer formulations for thermal stability. Saudi Aramco procurement frameworks emphasize supplier eligibility through qualification pipelines across multiple basin types. Dhahran anchors research centers where compound development aligns with domestic manufacturing expansion under Vision 2030 industrial localization targets.
Swellable Packers Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered contract categories. The vendor base organizes around three strategic archetypes: integrated oilfield service providers with captive elastomer manufacturing, standalone packer specialists with deep qualification histories, and emerging regional fabricators serving local content mandates. Dominant competitive moves include backward integration into compound formulation and strategic partnerships with deployment service providers.
Within the integrated service tier, Weatherford, Halliburton Energy Services, and Baker Hughes occupy positions that combine elastomer manufacturing with wireline deployment capabilities. These conglomerates exemplify the bundled offering model capturing expanded scope in Brazil's pre-salt and Gulf of Mexico deepwater markets. Schlumberger Limited and Tendeka represent alternative archetypes—Schlumberger as a technology-licensing aggregator, Tendeka as a deployment-focused specialist. Peak Completion Technologies Inc. and Reactive Downhole Tools Limited anchor the standalone packer segment where qualification depth substitutes for manufacturing scale.
| Leading Market Players |
|---|
| Weatherford |
| Nine Energy Service |
| Schlumberger Limited |
| Peak Completion Technologies Inc. |
| Reactive Downhole Tools Limited |
| Halliburton Energy Services, Inc. |
| TAM International, Inc. |
| Tendeka |
| Baker Hughes Company |
| Others |
Supply Flow & Price Mechanics
Deepwater operator procurement consolidation around single-contract accountability is forcing standalone packer vendors to absorb deployment service costs or cede share to integrated providers, compressing margins and accelerating backward integration into elastomer compounding. API 19OH qualification timelines extending to 18-24 months are freezing out capital-constrained suppliers, concentrating pricing power among legacy manufacturers with captive testing infrastructure.
Pricing Analysis
The bundled-versus-unbundled service split dominates pricing architecture, with integrated providers commanding premium-mid-economy pricing differentiation based on deployment scope while standalone vendors compete on unit economics. Price differentiation rests on API 19OH certification tier and after-sales service bundling, with fully qualified systems carrying substantial premiums over provisional alternatives. Pricing pressure stems from thermoplastic hybrid substitution in CO2-rich reservoirs, eroding margins on conventional elastomer tiers. National oil companies in Brazil and Saudi Arabia exhibit lowest price sensitivity, prioritizing single-trip reliability over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with hydrogenated nitrile precursor suppliers concentrated in the United States, Germany, and Japan, where polymer science expertise anchors specialty elastomer production. Raw material dependencies include fluorinated compound feedstocks, nitrile rubber base stocks, and thermoplastic barrier resins. Supply chain risk centers on EU F-Gas Regulation restrictions limiting domestic European production of high-seal-performance compounds. Distribution runs through oilfield service company procurement frameworks, with national oil company tender processes determining supplier eligibility in basin-specific markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The swellable packers market functions as a stable compounder, with deepwater drilling program continuity and replacement cycle predictability generating resilient demand foundations across volatile commodity cycles.
For Market Incumbents: Hedge against thermoplastic hybrid substitution by accelerating R&D allocation to chemically resistant barrier technologies compatible with CO2-rich reservoir conditions. Secure compound formulation talent pools through targeted acquisition of polymer science teams with deepwater elastomer experience. Defensive positioning requires parallel qualification pipeline management across Brazil's pre-salt, Gulf of Mexico, and West African thermal regimes to maintain multi-basin contract eligibility.
For New Entrants and Emerging Players: Thermoplastic hybrid sleeve technology offers a technology-first wedge for specialized entrants lacking legacy elastomer qualification histories. Target India's Cambay and Krishna-Godavari basins where BIS certification pressures on import-dependent supply chains create white-space openings for locally qualified manufacturers. Formation testing applications represent the most penetrable segment, with wireline-conveyed packer-isolated reservoir evaluation displacing conventional drillstem tests and favoring slim-profile, rapid-deployment architectures.
For Investors and Strategic Acquirers: Asymmetric upside sits with compound formulation specialists possessing API 19OH qualification depth but limited deployment service scale, positioned for acquisition by integrated service providers seeking backward integration. Long-term viability frames around 5-10 year replacement cycles in installed deepwater completions and expansion into geothermal sector applications. Monitor API qualification timeline compression and local content mandate evolution in Brazil, Nigeria, and Saudi Arabia as inflection indicators for supplier consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Elastomer Compounding | Captures margin from specialty hydrogenated nitrile formulations required for Brazil's pre-salt thermal regimes. |
| Multi-Basin Qualification Pipeline Expansion | Secures contract eligibility across divergent API 19OH thermal cycling requirements in Gulf of Mexico and West Africa. |
| Thermoplastic Hybrid Barrier Development | Addresses CO2-rich reservoir degradation risks displacing conventional nitrile in Norwegian North Sea deployments. |
| Local Content Manufacturing Partnerships | Satisfies ANP, NOGICD, and Saudi Aramco domestic procurement thresholds for basin access. |
| Wireline Deployment Service Bundling | Captures formation testing segment growth as operators shift from drillstem tests to packer-isolated evaluation. |
Methodological Framework
Multiple input streams — primary interviews with completion engineers and elastomer compound specialists, regulatory filing analysis, and procurement database review — were reconciled to construct market estimates. Stakeholder engagement spanned drilling program managers at supermajors, polymer scientists at specialty chemical suppliers, and contracts officers at national oil companies. Secondary validation drew from API qualification records, EPA offshore discharge compliance filings, and ANP local content certification databases. Bottom-up segment sizing triangulated against top-down energy sector capital expenditure allocations.
Data-stream reconciliation anchored the forecast framework across the analysis window, with segmentation modeling spanning product type, end-use sector, application function, and material composition dimensions. CAGRs were derived from elasticity-adjusted demand projections incorporating deepwater rig count trajectories and pre-salt development timelines. Industry-specific inputs included thermal cycling degradation curves for hydrogenated nitrile compounds and thermoplastic hybrid barrier adoption rates in high-CO2 reservoirs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to deepwater drilling cost inflation, regional content mandate enforcement, and fluorinated elastomer precursor regulatory restrictions. Forecasts reflect documented assumptions regarding API 19OH timeline stability and operator procurement consolidation patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Chemical Enhanced Oil Recovery (EOR) Market
Oil & Gas
Oil and Gas Cloud Applications Market
Oil & Gas
Flow Computer Oil Gas Market
Oil & Gas
Multi-Point Ground Flares (MPGF) Market
Oil & Gas
North America Digital Oilfield Market
Oil & Gas
Venezuela Oil and Gas Market
Oil & Gas
Open Hole Logging Services Market
Oil & Gas
Turkmenistan Oil and Gas Market
Oil & Gas
GCC Natural Gas Market
Oil & Gas
Fracking Fluid Market
Oil & Gas
Malaysia Oil and Gas Midstream Market
Oil & Gas
Latin America Coiled Tubing Market
Oil & Gas
Oil and Gas Engineering Services Market
Oil & Gas
Smart Oilfield Market
Oil & Gas
Well Stimulation Vessels Market
Oil & Gas
India AI in Oil and Gas Market