
 Oil Filled Transformer Market | 2026-2036
Oil Filled Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Oil Filled Transformer Market Analysis
Project finance and long-term leasing for grid infrastructure is rewriting competitive dynamics in the Oil Filled Transformer space. ABB Group leverages its turnkey project capabilities to secure utility-scale contracts across emerging markets. Siemens AG anchors European demand through high-voltage power transformer specialization. Bharat Heavy Electricals Limited dominates domestic procurement cycles for Indian utilities with in-house manufacturing scale.
An oil filled transformer is an electromagnetic static device that uses mineral oil or ester-based dielectric fluid for insulation and cooling, typically operating at voltages from 11 kV to 765 kV to step up or step down alternating current in power distribution networks. Power transformers command the largest value share due to their critical role in long-distance transmission and higher material intensity. Distribution transformers see volume concentration from rural electrification programs and urban grid densification. Smart technology integration represents the fastest-evolving segment as utilities deploy sensors and remote monitoring for predictive maintenance and load optimization.
The US Department of Energy enforces efficiency standards under 10 CFR 431 that mandate minimum performance levels for liquid-immersed distribution transformers. The EU Ecodesign Directive and F-Gas Regulation restrict fluid types and loss thresholds, compelling redesigns toward natural esters and lower core losses. India's Central Electricity Authority mandates BIS certification and stringent efficiency norms for grid-connected equipment. Stakeholders must weigh fluid transition timelines against retrofit economics and regional certification lead times.
Market Dynamics
The EU F-Gas Regulation's phase-down schedule for synthetic esters is forcing utilities across multiple continents to accelerate fluid transition roadmaps and redesign procurement specifications around natural and synthetic ester alternatives.
Growth Catalysts
- India's transmission expansion:State-owned utilities under the Central Electricity Authority mandate are procuring bulk power transformers for 765 kV and 400 kV corridors linking renewable zones to load centers.
- Ecodesign loss thresholds:The EU Directive's tiered efficiency requirements compel manufacturers to adopt amorphous metal cores and optimized winding geometries in distribution units.
- Smart sensor integration:Dissolved gas analysis and thermal monitoring systems are embedding predictive maintenance capabilities into substation assets.
Market Restraints
- Grain-oriented electrical steel concentration:Supply of high-permeability core material concentrates among Japanese and South Korean metallurgical producers, exposing transformer OEMs to input volatility.
- Ester fluid cost premium:Natural ester dielectrics command 40-60% price elevation over mineral oil, compressing margins on efficiency-compliant units.
- SF6-alternative vacuum interrupters:Medium-voltage switchgear substitution threatens oil-filled distribution transformer attach rates in secondary substations.
Strategic Opportunities
- Rural electrification in sub-Saharan Africa:Development finance institutions are funding distribution transformer deployments for last-mile grid extension where pad-mounted units replace pole-mounted alternatives.
- Repurposed ester fluids:Envirotemp FR3 and MIDEL 7131 formulations enable fire-safety upgrades in dense urban substations and underground vaults.
- Turnkey EPC bundling:Engineering-procurement-construction contractors are consolidating transformer supply with switchgear and civil works for utility-scale substation projects.
Industry Challenges
- Winding technician scarcity:Precision copper coil fabrication requires skilled labor pools that are aging out in Germany, Japan, and the United States without adequate apprenticeship pipeline replacement.
- Multi-standard certification lag:Simultaneous pursuit of IEEE C57, IEC 60076, and BIS IS 2026 approvals extends product launch timelines by 18-24 months for multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil Filled Transformer Market |
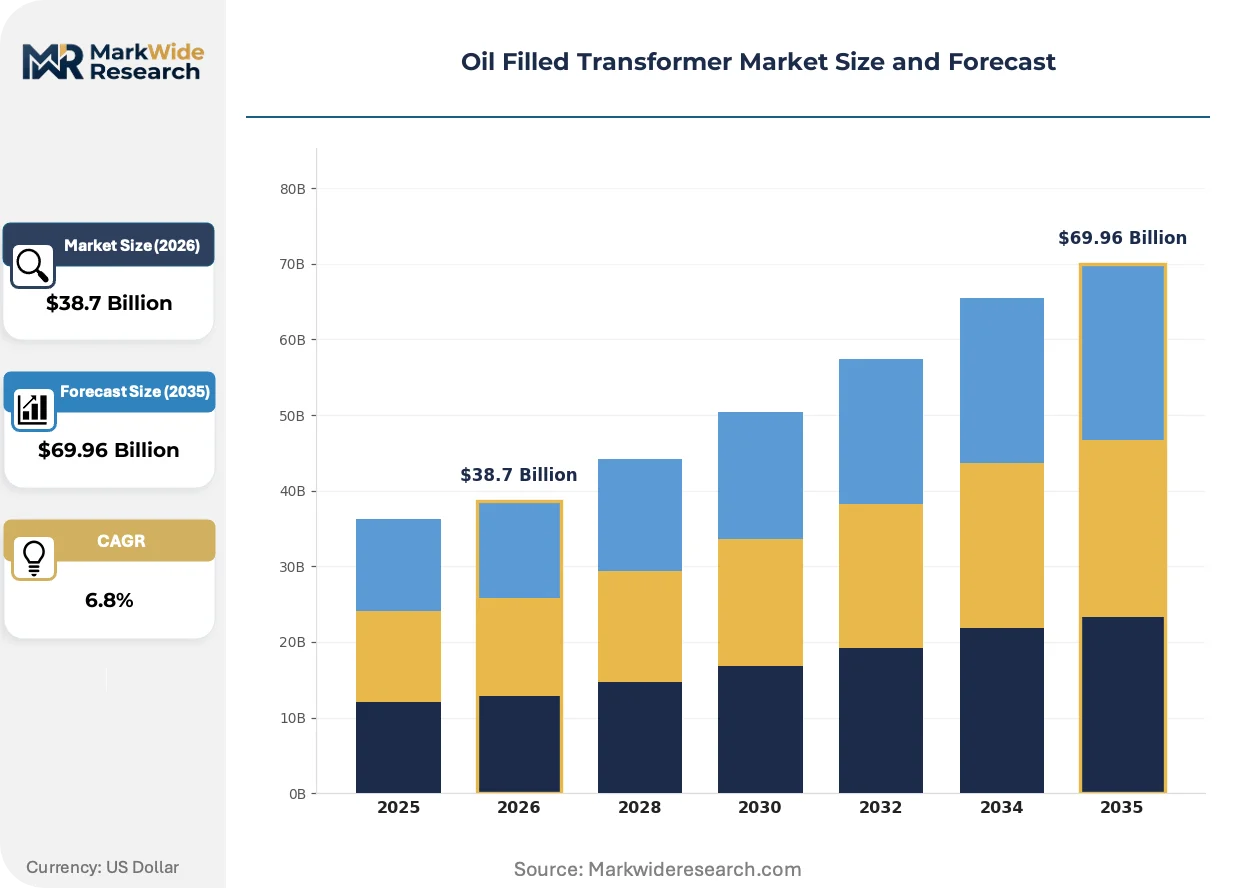
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Distribution Transformers, Power Transformers, Instrument Transformers, Special Transformers End User: Utilities, Industrial, Commercial, Renewable Energy Installation: Indoor, Outdoor, Substation-based, Mobile Technology: Conventional, Smart, Hybrid, Nano-Technology |
| Companies Covered | General Electric Company, Mitsubishi Electric Corporation, ABB Group, Bharat Heavy Electricals Limited, Hitachi, Ltd., Siemens AG, Toshiba Corporation, Zhejiang Lvma Electric Co., Ltd., Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil Filled Transformer Market Emerging Trajectories
Fluid chemistry, core metallurgy, and digital instrumentation are converging to redefine transformer lifecycle economics and operational visibility for grid operators managing aging infrastructure replacement cycles.
Amorphous metal ribbon is migrating from niche applications to mainstream distribution transformer cores. The material's non-crystalline atomic structure enables 70-80% core loss reduction versus conventional grain-oriented silicon steel. European utilities under Ecodesign Tier 2 mandates are specifying amorphous cores for pole-mounted units below 500 kVA. The technology is migrating from premium urban deployments to standard rural electrification tenders as Chinese ribbon production scales.
The EU F-Gas Regulation's synthetic ester phase-down is compelling fluid reformulation across the 2026-2030 window. Manufacturers must certify natural ester compatibility with existing gasket materials and cellulose insulation systems. High-voltage power transformers above 220 kV face the steepest redesign burden, as these units historically relied on synthetic esters for thermal performance. European OEMs are accelerating in-house ester blending capabilities to secure supply chain control.
Performance-based service contracts are displacing traditional break-fix maintenance arrangements for utility fleets. Asset owners in the United States and Germany are purchasing guaranteed availability and loss-limit guarantees rather than discrete spare parts. This shifts capital expenditure toward integrated monitoring platforms and remote diagnostics infrastructure. The model concentrates most rapidly among municipal utilities with limited in-house transformer engineering staff.
Oil Filled Transformer Market Segmentation
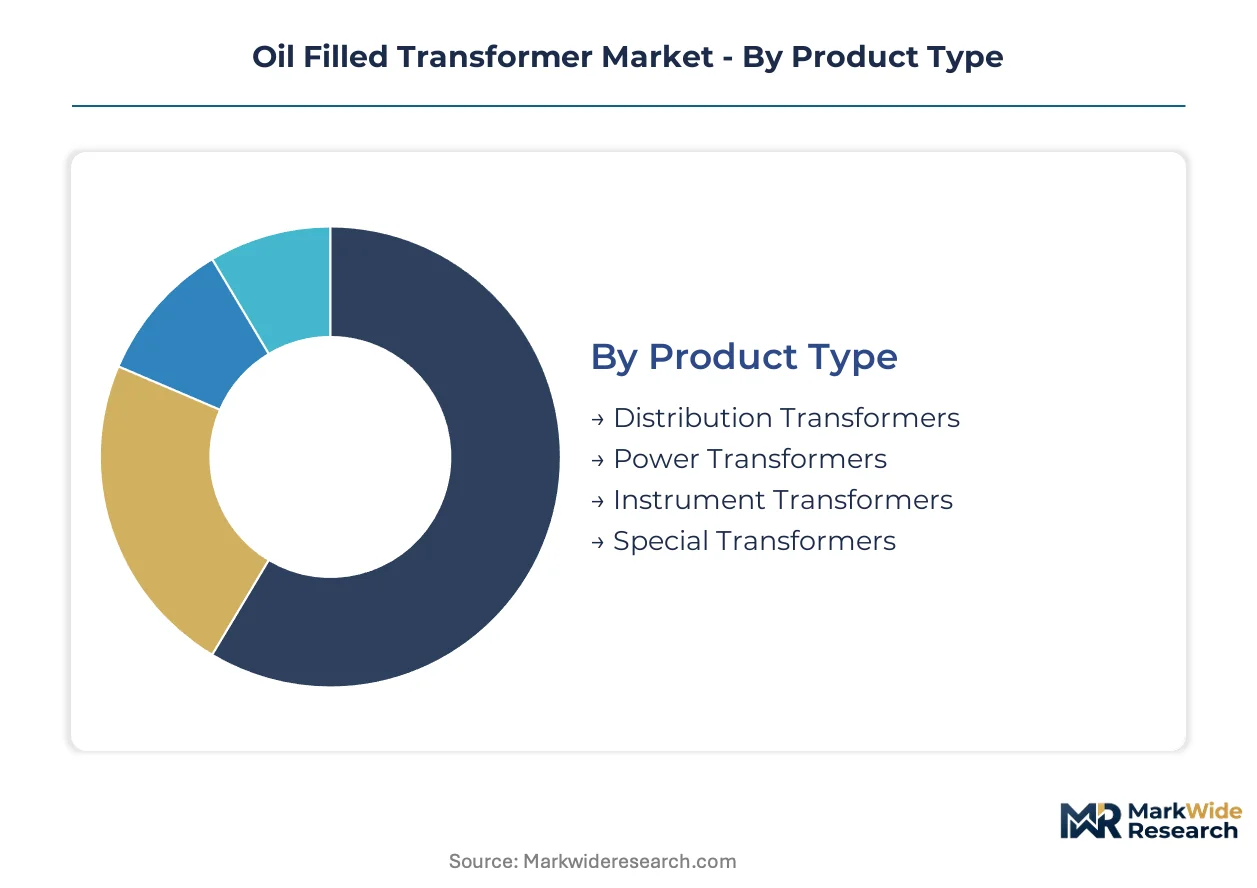
Transformer architecture varies sharply by duty cycle, voltage class, and operational environment. Each segment carries distinct procurement specifications, fluid compatibility requirements, and lifecycle cost profiles that shape vendor positioning and utility capital planning.
Product Type:
Application intensity and material specifications separate the four product categories, with voltage rating and thermal loading determining core metallurgy and insulation system choices.
- Power Transformers:These units operate from 220 kV to 765 kV with MVA ratings exceeding 100, utilizing grain-oriented silicon steel cores and synthetic or natural ester dielectric fluids for bulk transmission interconnection. India's Central Electricity Authority mandates these for 765 kV renewable evacuation corridors linking Rajasthan solar zones to Maharashtra load centers, with procurement cycles running 18-24 months due to winding complexity.
- Distribution Transformers:Pole-mounted and pad-mounted units below 500 kVA dominate unit volume, stepping voltage down to 11 kV or 415 V for last-mile delivery. Rural electrification programs across sub-Saharan Africa and India's Saubhagya scheme concentrate demand for compact, fire-resistant ester-filled designs in dense urban vaults and remote village clusters.
- Instrument Transformers:These precision devices isolate metering and protection circuits from high-voltage busbars, utilizing oil-impregnated paper insulation for current and voltage sensing accuracy.
- Special Transformers:Furnace duty, rectifier, and traction transformers serve steel melting, electrochemical processing, and railway electrification with customized impedance characteristics and enhanced short-circuit withstand.
Power transformers command the established base. The steepest expansion runs through distribution units.
End User:
Customer type determines specification stringency, with regulated utilities imposing certification requirements that industrial buyers often waive for faster delivery.
- Utilities:State-owned transmission companies and distribution network operators specify IEC 60076 or IEEE C57 compliance with dissolved gas analysis monitoring, driving standardization across procurement tenders in Germany, India, and the United States.
- Industrial:Steel mills, petrochemical complexes, and mining operations prioritize fault tolerance and overload capacity over efficiency metrics, accepting mineral oil fluids despite urban fire codes.
- Commercial:Data centers, hospitals, and high-rise developments specify natural ester fills for indoor vault installations where fire safety and biodegradability outweigh 40-60% fluid cost premiums.
- Renewable Energy:Wind farm collection platforms and solar inverter step-up stations demand compact, modular designs with wide operating temperature ranges for desert and offshore environments.
Utilities anchor procurement volume. Commercial installations are gaining share fastest.
Installation:
Physical deployment context dictates enclosure ratings, cooling system architecture, and accessibility for maintenance intervention.
- Outdoor:Pole-mounted and ground-mounted units exposed to weather utilize hermetically sealed tanks with conservator or nitrogen blanket systems to prevent moisture ingress in tropical climates.
- Indoor:Vault and basement installations in urban substations mandate fire-resistant ester fluids and secondary containment with oil-segregation systems per local electrical codes.
- Substation-based:Large power transformers in dedicated switchyards employ forced oil and forced air cooling with radiator banks and on-load tap changers for voltage regulation.
- Mobile:Skid-mounted and trailer-mounted units provide emergency restoration capacity for grid resilience programs in storm-prone regions of the United States and Japan.
Outdoor deployments hold the volume base. Indoor specifications are climbing the fastest.
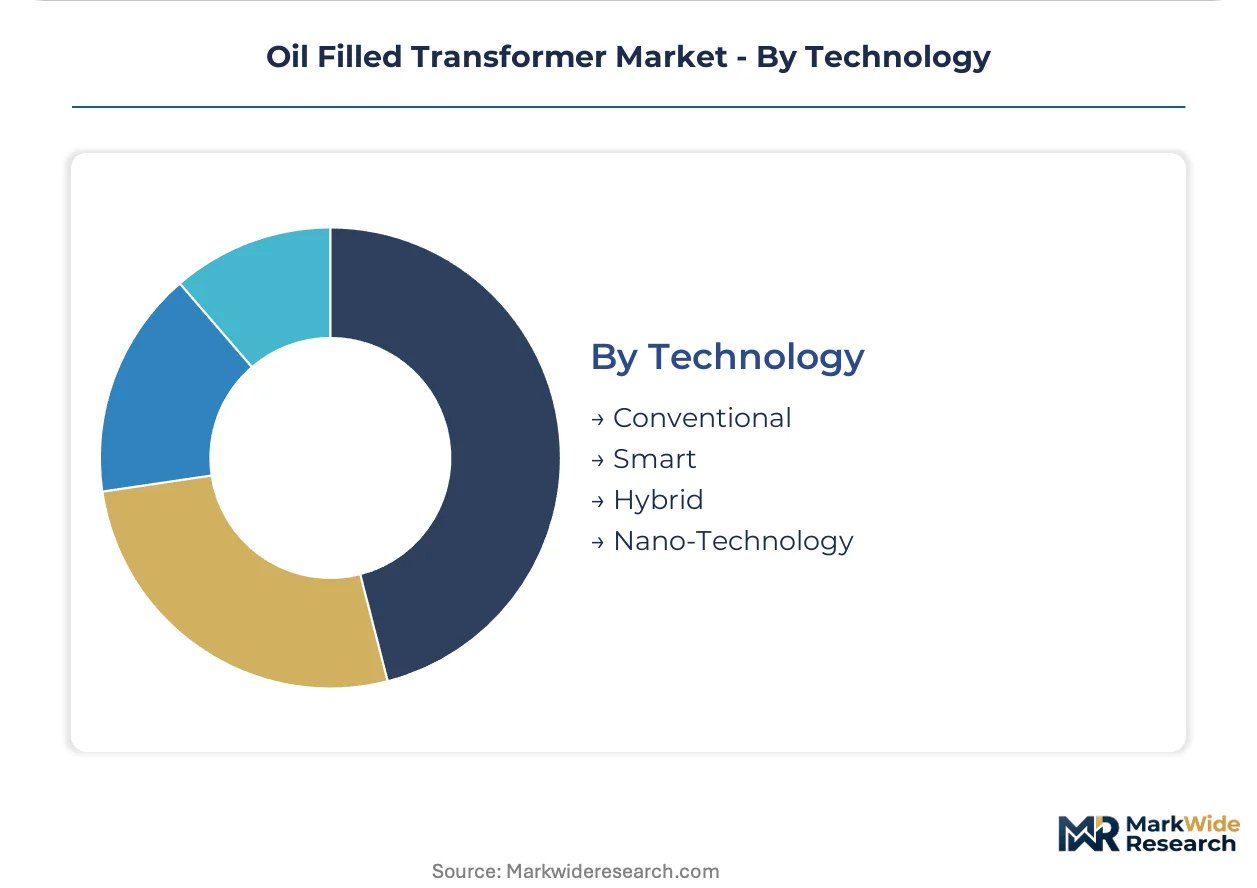
Technology:
Digital instrumentation and material science advances are stratifying the technology landscape between legacy electromechanical designs and sensor-integrated platforms.
- Smart:Embedded thermal sensors, partial discharge monitors, and dissolved gas analysis units transmit real-time condition data to utility asset management platforms, enabling predictive maintenance and load optimization. German municipal utilities under performance-based service contracts are specifying these for critical substation assets.
- Conventional:Electromechanical designs without digital instrumentation continue serving price-sensitive rural electrification markets and backup redundancy applications where monitoring infrastructure is absent.
- Hybrid:Retrofit sensor packages upgrade existing transformer fleets with remote monitoring capabilities without tank replacement, bridging capital constraints in aging infrastructure markets.
- Nano-Technology:Nanofluid dielectrics with suspended nanoparticles promise enhanced thermal conductivity and dielectric strength, though commercial deployment remains limited to pilot installations.
Conventional technology retains the installed base. Smart platforms show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-owned utilities and municipal grid operators concentrate transformer procurement across five distinct national markets, each shaped by unique electrification priorities and regulatory enforcement timelines.
China
State Grid Corporation and China Southern Power Grid are deploying 765 kV power transformers for renewable evacuation corridors linking western solar zones to eastern load centers. The National Energy Administration enforces GB standards for efficiency and fluid compatibility. Manufacturing clusters in Shandong and Jiangsu provinces supply domestic demand while exporting amorphous-core distribution units to Southeast Asian markets.
India
Power Grid Corporation and state transmission utilities under the Central Electricity Authority mandate are procuring bulk power transformers for 400 kV and 765 kV corridors. BIS certification and stringent efficiency norms govern grid-connected equipment. Manufacturing concentration in Bhopal and Jhansi supports domestic procurement cycles while meeting rural electrification targets under the Saubhagya scheme.
United States
Municipal utilities and investor-owned transmission operators are replacing aging infrastructure with smart sensor-integrated units for predictive maintenance. The Department of Energy enforces 10 CFR 431 efficiency standards for liquid-immersed distribution transformers. Storm-prone regions in Florida and the Gulf Coast are deploying mobile transformer units for grid resilience programs.
Germany
TenneT and 50Hertz are specifying amorphous-core distribution transformers to meet Ecodesign Tier 2 loss thresholds. The EU F-Gas Regulation and Ecodesign Directive restrict fluid types and mandate core loss reductions. Industrial clusters in Bavaria and North Rhine-Westphalia are accelerating natural ester blending capabilities to secure supply chain control.
Brazil
Eletrobras subsidiaries and regional utilities are expanding transmission networks to connect Amazon hydropower to southeastern industrial zones. ANEEL regulations govern grid equipment certification and efficiency standards. Manufacturing presence in São Paulo state serves domestic demand while exporting to Argentine and Chilean markets.
Oil Filled Transformer Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered market structure where scale-driven OEMs, regional fabricators, and technology integrators occupy distinct competitive positions. The vendor base stratifies between multinational conglomerates with turnkey EPC capabilities and mid-tier specialists focused on distribution transformer volume. Strategic archetypes include full-service grid infrastructure providers, component-focused manufacturers, and digital monitoring technology suppliers. Dominant competitive moves center on backward integration into core material supply and geographic expansion through local manufacturing partnerships.
Among conglomerate-scale providers, General Electric Company and Siemens AG exemplify the full-service archetype with integrated project capabilities spanning high-voltage power transformers through substation automation. Mitsubishi Electric Corporation occupies a position within the technology-integrated tier, representing Japanese industrial diversification into grid infrastructure. These three anchors illustrate how competitive positioning diverges between North American-German engineering heritage and East Asian manufacturing scale.
| Leading Market Players |
|---|
| General Electric Company |
| Mitsubishi Electric Corporation |
| ABB Group |
| Bharat Heavy Electricals Limited |
| Hitachi, Ltd. |
| Siemens AG |
| Toshiba Corporation |
| Zhejiang Lvma Electric Co., Ltd. |
| Schneider Electric |
| Others |
Supply Flow & Price Mechanics
Shandong and Jiangsu manufacturing clusters in China dictate transformer pricing power through captive amorphous metal ribbon production and integrated core lamination capabilities that compress procurement cycles for downstream OEMs. The EU F-Gas Regulation's synthetic ester phase-down is forcing fluid reformulation costs through supply chains, while Indian BIS certification requirements extend lead times for multi-market suppliers.
Pricing Analysis
Cost-plus contracts indexed to grain-oriented electrical steel and copper LME pricing dominate utility-scale procurement, with Japanese and South Korean metallurgical suppliers capturing premium tier positioning through high-permeability core material. Three-tier pricing structure across premium, standard, and economy levels separates amorphous-core Ecodesign-compliant units from conventional silicon steel designs and refurbished legacy assets. Cost compression in distribution transformers is intensifying because Chinese ribbon production scales and erodes Japanese material premiums. Rural electrification programs in sub-Saharan Africa exhibit highest price sensitivity, while German municipal utilities under performance-based service contracts accept 40-60% fluid cost premiums for natural ester fire-safety specifications.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for transformer OEMs sourcing core laminations and tap changer subassemblies. Manufacturing gravity centers on China, India, and Germany, with Shandong province feeding Southeast Asian export markets and Bhopal-Jhansi clusters serving Indian domestic procurement. The supply chain draws from grain-oriented electrical steel, copper winding wire, and cellulose insulation paper as critical inputs. Single-source vulnerability concentrates in Japanese amorphous metal ribbon production. Distribution runs through turnkey EPC contractors consolidating transformer supply with switchgear and civil works for utility-scale substation projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Oil Filled Transformer Market functions as a defensive-moat sector where regulatory entrenchment through multi-standard certification requirements creates structural barriers that protect incumbent positions against rapid competitive displacement.
For Market Incumbents: Insulate core margin positions through backward integration into amorphous metal ribbon production and captive natural ester blending capabilities that secure supply chain control against fluid transition volatility. Accelerate certification investment across IEEE C57, IEC 60076, and BIS IS 2026 standards to extend product launch timeline advantages over emerging Asian competitors. Prioritize smart sensor platform development to capture performance-based service contract migration among municipal utilities with limited in-house engineering staff. For New Entrants and Emerging Players: Sub-Saharan Africa's rural electrification financing gaps offer white-space entry through development institution-funded distribution transformer deployments where pad-mounted units replace aging pole-mounted infrastructure. Target commercial indoor vault installations in dense Asian megacities where fire-resistant ester specifications and secondary containment requirements favor specialized product configurations over commodity utility tenders. Pursue joint venture structures with established EPC contractors to bypass multi-standard certification lag and accelerate market access. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates divesting non-core transformer divisions amid portfolio rationalization pressures and stranded synthetic ester inventory burdens. Long-term viability rests on exposure to renewable evacuation corridor buildouts and grid resilience replacement cycles rather than cyclical industrial demand. Monitor dissolved gas analysis sensor attach rates as the inflection indicator for smart technology adoption velocity and recurring revenue model penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Amorphous Core Manufacturing Scale-Up | Chinese ribbon production expansion enables 70-80% core loss reduction for Ecodesign Tier 2 compliance. |
| Natural Ester Blending Capability | In-house fluid formulation secures supply chain control against EU F-Gas Regulation synthetic ester phase-down. |
| Multi-Standard Certification Investment | Simultaneous IEEE C57, IEC 60076, and BIS IS 2026 approvals extend competitive moats through 18-24 month launch barriers. |
| Smart Sensor Platform Integration | Embedded thermal monitoring and dissolved gas analysis enable predictive maintenance contracts with German municipal utilities. |
| Turnkey EPC Bundling Partnership | Consolidating transformer supply with switchgear and civil works captures utility-scale substation procurement concentration. |
Methodological Framework
Cross-validation between utility procurement database analysis and transformer OEM technical documentation anchors the qualitative findings in documented specification trends and contract award patterns. Primary interviews with utility planning officers, EPC contractor procurement leads, transformer manufacturing engineers, and grid operator asset managers combined with secondary validation through IEC standards documentation, Central Electricity Authority tender records, and Department of Energy efficiency filings. Bottom-up unit deployment tracking across voltage classes and top-down transmission investment flow analysis provided triangulation discipline.
Calibration against historical capacity installation data and disclosed utility capital expenditure plans shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user category, installation environment, and technology tier alongside regional regulatory framework clustering. CAGRs were derived from installed base replacement cycle analysis and renewable evacuation corridor buildout trajectories. Industry-specific forecast inputs incorporated amorphous core penetration assumptions and smart sensor attach rate migration patterns.
Macroeconomic conditions sit as an overlay; deviation in transmission grid investment flows, copper price volatility, or development finance institution lending appetite would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and fluid transition roadmaps. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
EHV & UHV (above 330KV) Power Transformers Market
Transformers
Canada Transformer Market
Transformers
Transformer Core Market
Transformers
North America Dry Type Transformer Market
Transformers
Latin America Transformer Market
Transformers
Green Power Transformers Market
Transformers
High Voltage (35-550 KV) Power Transformer Market
Transformers
India Power Transformer Market
Transformers
Neon Transformer Market
Transformers
Power Transformer Market
Transformers
North America Transformer Market
Transformers
Transformer Bobbin Market
Transformers
South America Transformer Market
Transformers
Europe Distribution Transformer Market
Transformers
Transformer Monitoring Systems (TMS) Market
Transformers
Gas Insulated Transformer Market