
 Underground Storage Tanks Market | 2026-2036
Underground Storage Tanks Market Size, Share, and Industry Trends Forecast 2026-2036
Underground Storage Tanks Market Analytics
Double-wall fiberglass specifications is collapsing the price premium once separating premium from standard tank tiers. Xerxes Corporation leverages its filament-winding expertise to sustain dominance in corrosion-resistant petroleum applications. CST Industries anchors North American market presence through integrated steel-fabrication capabilities. ZCL Composites differentiates via specialized chemical-storage geometries that navigate stringent secondary-containment codes.
Underground storage tanks are pressure-rated vessels installed below grade, typically fabricated from carbon steel with dielectric coatings or glass-reinforced polymer composites, designed to contain hazardous liquids while preventing soil and groundwater contamination. Double-wall fiberglass configurations lead petroleum applications due to inherent corrosion immunity and built-in leak-detection interstices, while steel variants retain cost advantages in high-capacity municipal fire-suppression systems. Polyethylene segments capture niche chemical-storage demand where pH extremes exclude metallic options, and horizontal tank geometries dominate constrained urban footprints. Concrete applications persist in wastewater containment where structural load-bearing and decades-long service life offset higher installed costs.
EPA underground storage tank regulations mandate double-wall construction, automatic leak detection, and financial responsibility mechanisms that shape procurement specifications across commercial and municipal buyers. State-level fire codes and NFPA standards further constrain material selection and installation protocols for flammable-liquid containment. Stakeholders must monitor evolving per- and polyfluoroalkyl substance remediation liabilities, as legacy tank sites face accelerating cleanup obligations that redirect capital toward replacement rather than rehabilitation.
Market Dynamics
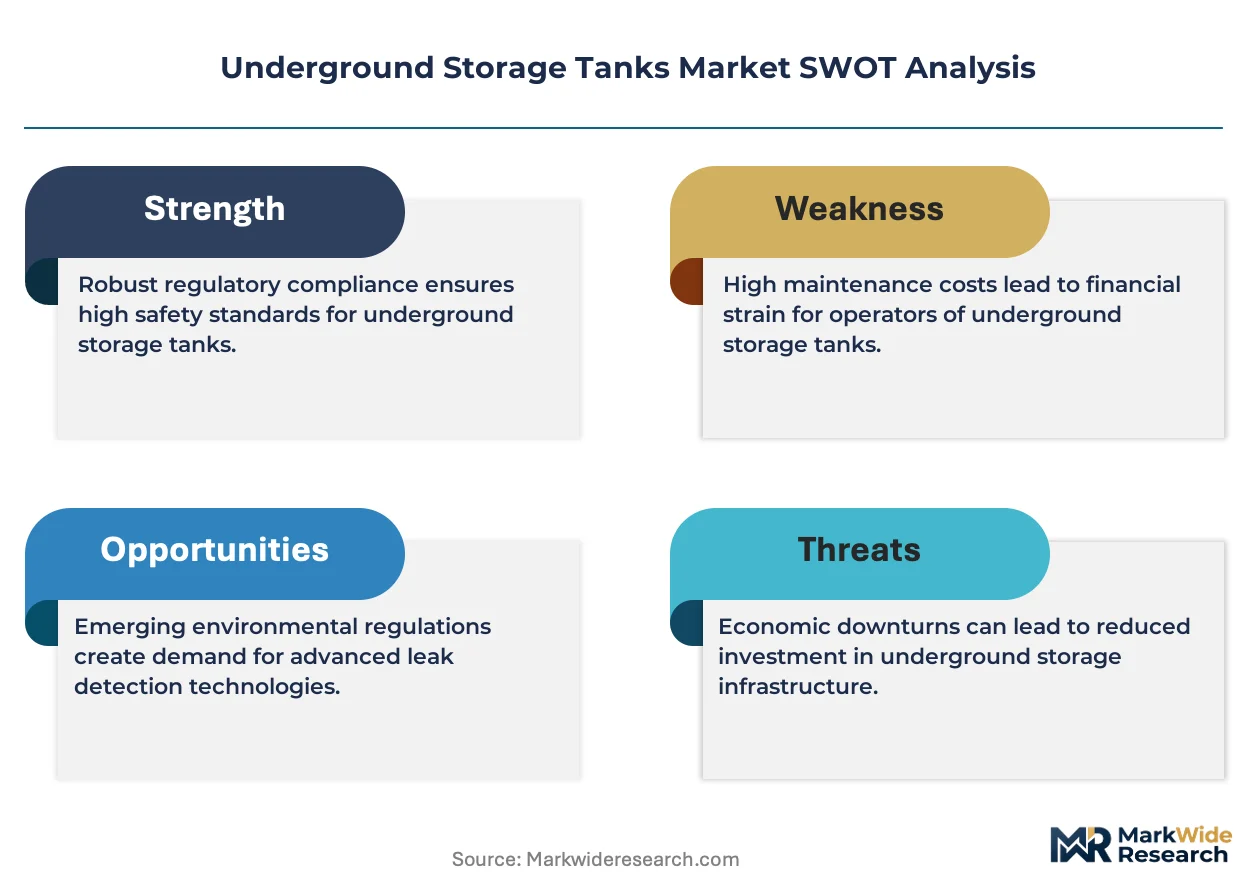
EPA leak detection mandates are forcing wholesale infrastructure replacement across the United States, collapsing the installed base of single-wall steel tanks and redirecting capital toward double-wall fiberglass systems with integrated monitoring interstices.
Growth Catalysts
- EPA UST Regulations:Federal mandates for secondary containment and automatic leak detection are accelerating municipal procurement cycles for compliant double-wall systems.
- Petrochemical Corridor Expansion:Gulf Coast refinery capacity additions and strategic petroleum reserve maintenance are sustaining bulk storage demand for corrosion-resistant composite vessels.
- Cathodic Protection Advances:Impressed-current and sacrificial anode innovations are extending steel tank service life in high-conductivity soil environments, preserving metallic options for cost-sensitive buyers.
Market Restraints
- Epoxy Resin Cost Volatility:Glass-reinforced polymer tank fabrication depends on petrochemical-derived resins exposed to feedstock price swings and supply chain disruptions.
- Fabrication Concentration:Filament-winding expertise and large-diameter composite manufacturing capacity concentrate among a limited supplier base in North American industrial corridors.
- Concrete Tank Substitution:Wastewater containment applications increasingly specify precast concrete for structural load-bearing requirements that composites cannot economically match.
Strategic Opportunities
- PFAS Remediation Liabilities:Accelerating cleanup obligations at legacy tank sites are redirecting municipal capital from rehabilitation toward full replacement with compliant systems.
- Hydrogen Storage Adaptation:Emerging demand for underground hydrogen containment is creating specification opportunities for high-pressure-rated composite vessel geometries.
- Smart Monitoring Integration:Convergence of leak detection sensors with IoT telemetry platforms enables predictive maintenance contracts and recurring revenue streams for tank system providers.
Industry Challenges
- Composite Technician Scarcity:Filament-winding and resin-transfer molding expertise remains concentrated among aging workforces with limited apprenticeship pipeline replenishment.
- Multi-Agency Certification Timelines:Simultaneous EPA, state environmental, and NFPA fire code approvals extend project lead times and compress installation windows for seasonal construction schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underground Storage Tanks Market |
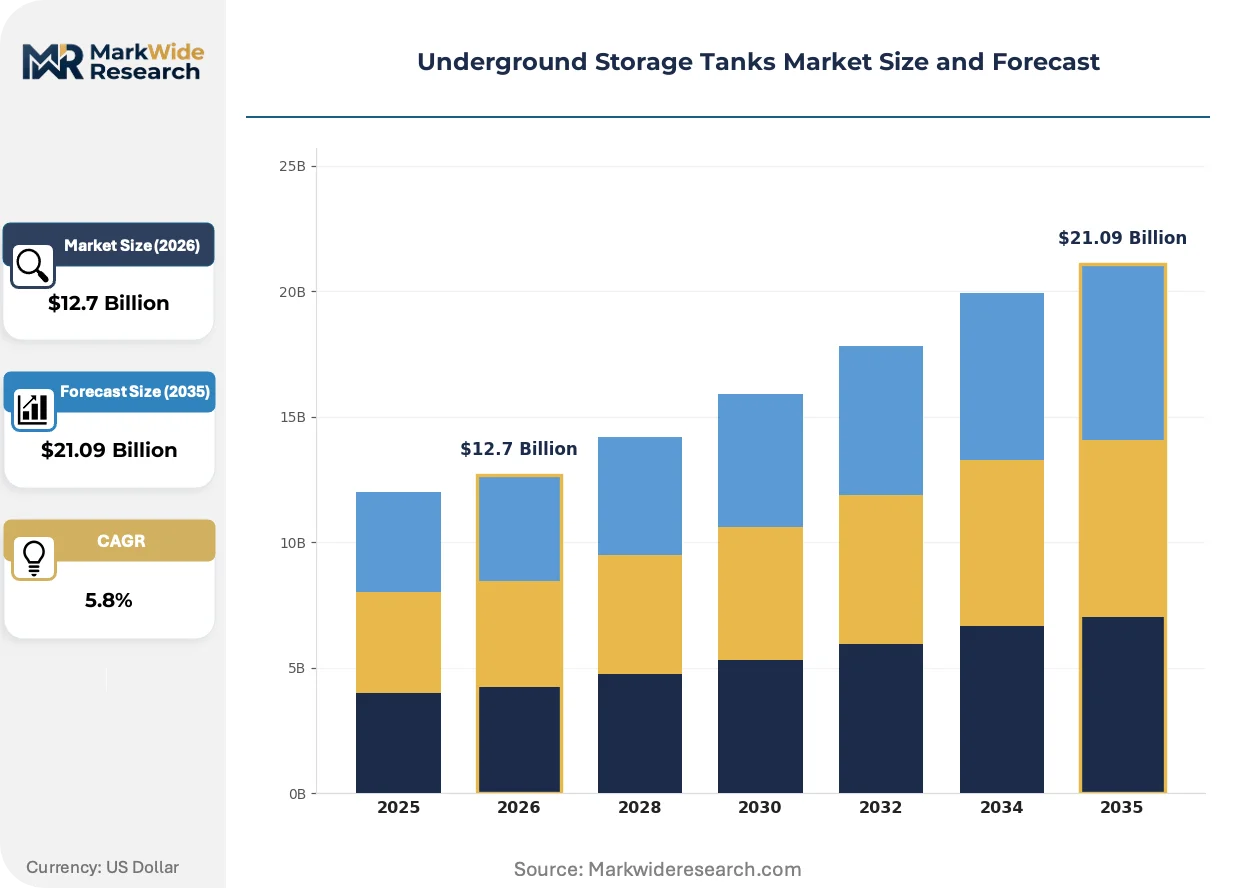
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $21.09 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Double-Wall Tanks, Single-Wall Tanks, Vertical Tanks, Horizontal Tanks Material: Fiberglass, Steel, Polyethylene, Concrete Application: Petroleum Storage, Chemical Storage, Wastewater Storage, Fire Suppression End User: Commercial Facilities, Industrial Plants, Municipalities, Oil & Gas |
| Companies Covered | CST Industries, McDermott International, Xerxes Corporation, ZCL Composites, Tank Connection, Containment Solutions, Highland Tank & Manufacturing, TATSUNO Corporation, Snyder Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underground Storage Tanks Market Evolving Landscape
Material science advances and regulatory stringency are fragmenting tank procurement into performance-tiered categories, with monitoring-integrated systems commanding specification priority over basic containment.
Sensor-embedded double-wall fiberglass is bifurcating the petroleum storage segment into monitored and unmonitored tiers. Municipal buyers and retail fuel operators are specifying interstitial leak detection as standard equipment rather than optional upgrade. This technology compression is eliminating price-competitive single-wall alternatives from compliant procurement pools.
REACH chemical authorization protocols in Europe are restricting legacy coating chemistries used in steel tank corrosion protection. Manufacturers are reformulating dielectric barrier systems to eliminate restricted substances while maintaining sulfate-reducing bacteria resistance. Chemical storage applications in industrial zones face the most acute compliance-driven material substitution pressures.
Lifecycle service contracting is displacing discrete tank sales in municipal procurement. Texas and Louisiana water authorities now specify twenty-year performance guarantees encompassing installation, monitoring, and remediation liability transfer. This financial structuring shift compresses capital expenditure recognition and elevates vendor balance sheet requirements.
Underground Storage Tanks Market Segmentation
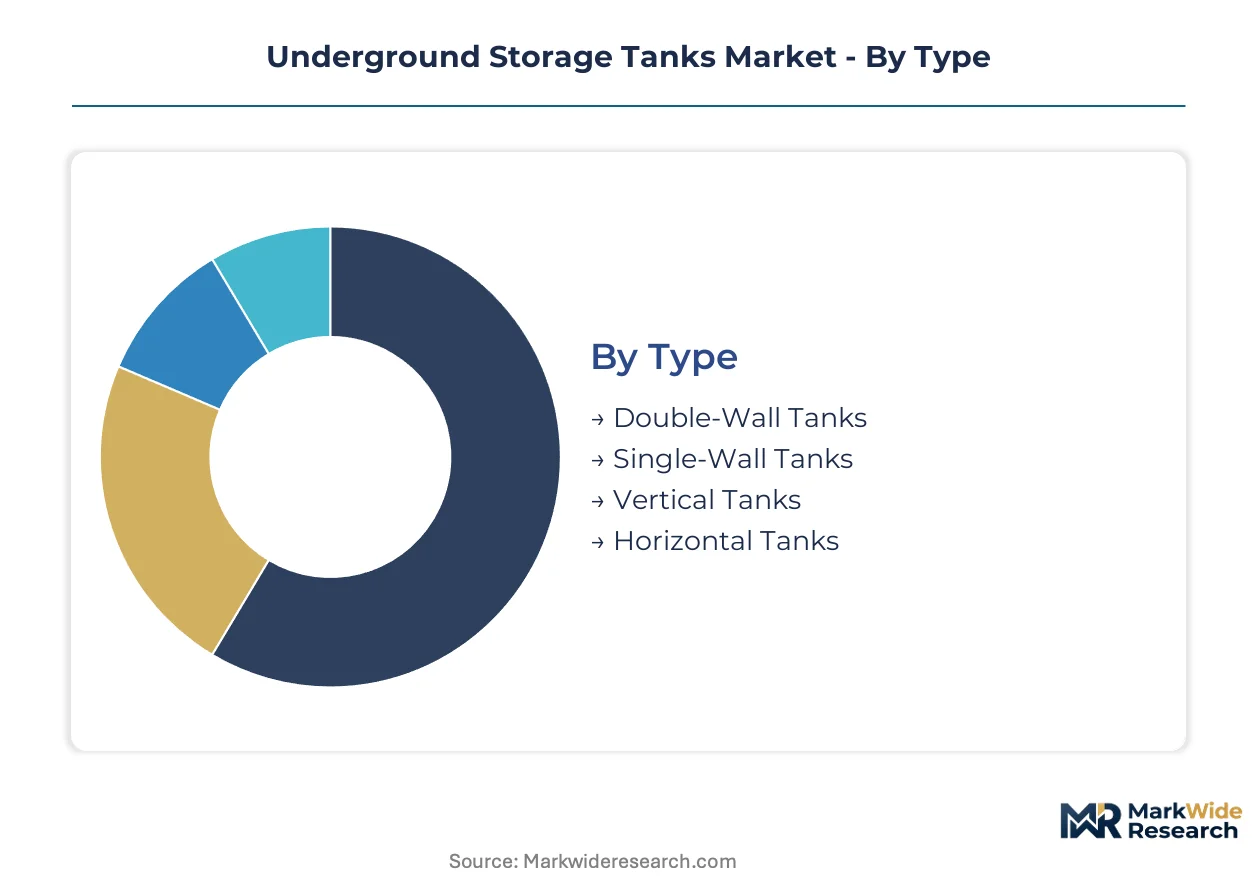
EPA leak detection mandates have fragmented procurement into compliance tiers, with double-wall systems commanding specification priority and single-wall alternatives relegated to non-regulated niches. Material selection now hinges on corrosion resistance versus structural load-bearing trade-offs across petroleum, chemical, and wastewater applications.
Type:
Regulatory stringency separates monitored from unmonitored configurations, with interstitial leak detection becoming standard rather than optional equipment.
- Double-Wall Tanks:Built-in interstitial spaces enable continuous leak monitoring through sensor-embedded fiberglass or steel constructions. Municipalities across Texas and Louisiana specify these for petroleum storage to satisfy EPA secondary containment mandates and transfer long-term remediation liability.
- Single-Wall Tanks:Legacy installations predominate in grandfathered agricultural fuel storage and remote mining operations where regulatory enforcement remains sparse. Accelerating replacement programs in California and Florida are collapsing this installed base toward obsolescence.
- Vertical Tanks:Footprint-constrained urban installations favor these for high-capacity chemical storage where horizontal excavation proves cost-prohibitive.
- Horizontal Tanks:Standard configuration for retail fuel stations and vehicle fleet depots requiring below-grade petroleum containment with minimal surface disruption.
Established volume favors horizontal geometries; emerging adoption favors vertical configurations in dense urban corridors.
Material:
Cost tiers stratify around corrosion immunity, with premium composites commanding petroleum applications and economy concrete dominating wastewater containment.
- Fiberglass:Glass-reinforced polymer filament-winding delivers inherent corrosion resistance and dielectric isolation for sulfate-reducing bacteria environments. Gulf Coast petrochemical facilities specify these for strategic petroleum reserve maintenance where soil conductivity accelerates steel degradation.
- Steel:Carbon steel fabrication retains cost advantages in high-capacity municipal fire suppression systems where cathodic protection extends service life economically. Kansas and Nebraska water authorities specify dielectric-coated steel for budget-constrained infrastructure renewal.
- Polyethylene:Rotational-molded high-density polyethylene captures niche chemical storage where pH extremes exclude metallic options.
- Concrete:Precast reinforced concrete dominates wastewater containment in Chicago and Detroit where structural load-bearing and decades-long service life offset higher installed costs.
Procurement volume concentrates in fiberglass for regulated petroleum; substitution pressure mounts from concrete in municipal wastewater.
Application:
End-use differentiation tracks fluid hazard classification, with flammable liquid containment facing the most stringent material and monitoring specifications.
- Petroleum Storage:Retail fuel stations, fleet depots, and bulk distribution terminals drive specification demand for double-wall fiberglass with integrated leak detection. Refinery expansion along the Texas Gulf Coast sustains procurement cycles for corrosion-resistant composite vessels.
- Chemical Storage:Industrial manufacturers require specialized geometries and barrier coatings for aggressive pH environments and solvent containment. REACH authorization protocols in Europe are restricting legacy coating chemistries and forcing material substitution.
- Wastewater Storage:Municipal treatment facilities specify concrete or polyethylene for below-grade containment of process effluent and stormwater overflow.
- Fire Suppression:Building codes in high-rise districts mandate dedicated water storage with rapid discharge capabilities and seismic-rated anchoring.
Revenue concentration sits with petroleum containment; steepest expansion trajectory emerges in chemical storage driven by industrial zone compliance pressures.
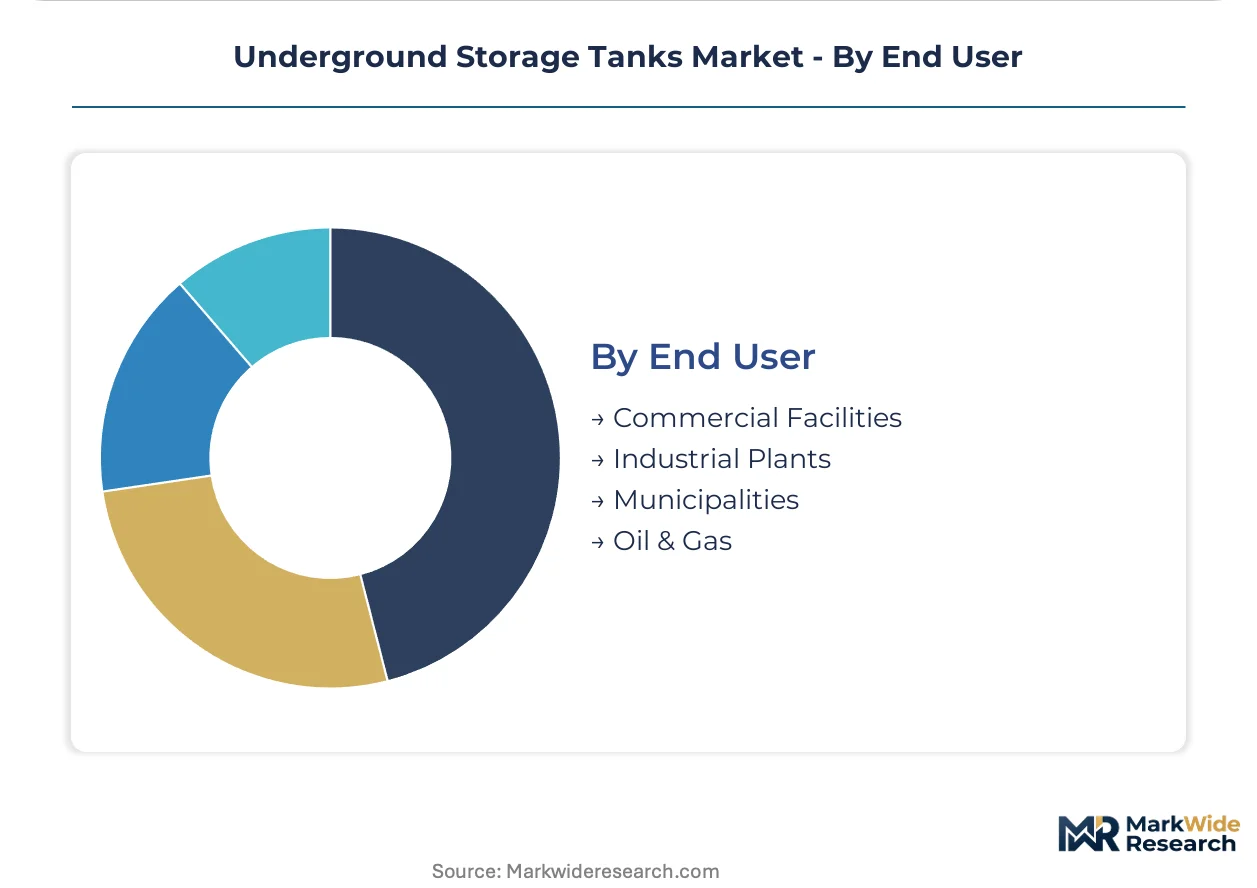
End User:
Customer type determines contracting structure, with municipalities shifting toward lifecycle service agreements and industrial buyers favoring capital purchase.
- Commercial Facilities:Retail fuel operators and property management groups prioritize rapid installation and minimal maintenance downtime. Convenience store chains in Ohio and Pennsylvania specify standardized tank packages with twenty-year performance guarantees.
- Industrial Plants:Petrochemical processors and manufacturing facilities demand custom geometries and chemical compatibility certification. Louisiana refinery operators procure through engineering-procurement-construction contractors with integrated installation liability.
- Municipalities:Water authorities and public works departments specify compliant replacement of aging single-wall infrastructure with federal funding support.
- Oil & Gas:Upstream producers and midstream terminals require high-capacity bulk storage with strategic petroleum reserve compatibility.
Contracting sophistication advances fastest among municipalities; procurement velocity remains highest in oil and gas corridor expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive municipal buyers in the United States Midwest drive volume procurement of coated steel tanks, while Gulf Coast petrochemical operators absorb premium pricing for corrosion-resistant composite systems without demand elasticity.
United States
EPA underground storage tank regulations mandate double-wall construction with automatic leak detection for all new petroleum installations. Texas and Louisiana water authorities specify twenty-year performance guarantees encompassing installation, monitoring, and liability transfer. Gulf Coast refinery expansion sustains procurement cycles for fiberglass vessels in Houston and Beaumont corridors.
Canada
Provincial environmental ministries enforce secondary containment standards that mirror EPA stringency for cross-border supply chain compatibility. Ontario and Quebec municipalities leverage federal infrastructure funding to replace aging single-wall infrastructure. Calgary and Edmonton petrochemical terminals specify cathodic-protected steel for strategic petroleum reserve maintenance.
Germany
REACH chemical authorization protocols restrict legacy coating chemistries used in steel tank corrosion protection. Bavaria and North Rhine-Westphalia industrial zones face acute compliance-driven material substitution pressures. Frankfurt-Rhine-Main chemical manufacturers demand specialized barrier coatings for aggressive solvent containment.
China
Ministry of Ecology and Environment standards tighten leak prevention requirements for petroleum storage in high-density urban districts. Yangtze River Delta municipalities specify double-wall fiberglass for retail fuel station modernization. Shandong Province refinery operators procure high-capacity composite vessels for bulk distribution terminals.
Saudi Arabia
Saudi Aramco procurement specifications prioritize corrosion-resistant materials for strategic petroleum reserve infrastructure in high-salinity soil environments. Eastern Province industrial cities specify fiberglass tanks for petrochemical feedstock storage. Riyadh municipal authorities deploy concrete containment for wastewater treatment facility expansion.
Underground Storage Tanks Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with composite filament-winding specialists commanding premium petroleum applications and integrated steel fabricators capturing municipal fire-suppression contracts. The vendor base stratifies across three tiers: multinational tank system integrators with lifecycle service capabilities, regional composite specialists with corrosion-resistant expertise, and commodity steel fabricators competing on installed cost. Dominant competitive moves include capacity expansion in Gulf Coast industrial corridors and strategic partnerships between tank manufacturers and IoT monitoring platform providers.
Among North American fabricators, CST Industries exemplifies integrated steel-fabrication capabilities, Xerxes Corporation anchors corrosion-resistant petroleum applications through filament-winding expertise, and ZCL Composites occupies a position in specialized chemical-storage geometries. These three represent distinct competitive archetypes: scale-driven metal fabrication, premium composite technology, and regulatory-specialized niche positioning. Each anchors a different procurement channel—municipal bulk tender, petrochemical engineering-procurement-construction contracts, and industrial chemical compliance projects.
| Leading Market Players |
|---|
| CST Industries |
| McDermott International |
| Xerxes Corporation |
| ZCL Composites |
| Tank Connection |
| Containment Solutions |
| Highland Tank & Manufacturing |
| TATSUNO Corporation |
| Snyder Industries |
| Others |
Value Network & Pricing Analysis
Epoxy resin substitution for polyester formulations in fiberglass tank fabrication is redrawing supply geography toward Gulf Coast petrochemical corridors while compressing margins for inland composite fabricators lacking feedstock proximity. This input shift simultaneously elevates pricing power for integrated resin producers and erodes cost advantages for regional tank assemblers dependent on spot resin markets.
Pricing Analysis
Lifecycle service contracts now drive lifetime value more than discrete tank sales, with twenty-year performance guarantees bundling installation, monitoring, and liability transfer commanding premium positioning. Three-tier pricing structure across premium sensor-embedded double-wall systems, standard monitored fiberglass, and economy cathodic-protected steel reflects certification grade and after-sales bundling intensity. Cost compression in economy steel tiers is intensifying because municipal budget constraints favor lowest compliant bids. Water authorities in Kansas and Nebraska exhibit highest price sensitivity; Gulf Coast refinery operators show least elasticity for corrosion-resistant composite specifications.
Supply Chain Analysis
Port congestion on Houston-Galveston container lanes elevates inbound logistics costs for epoxy resin and glass fiber shipments from Asian manufacturing hubs. Filament-winding capacity concentrates in the United States, Canada, and Germany, with raw material feeds drawing from Saudi Arabian petrochemical complexes and Chinese glass fiber foundries. Single-source vulnerability persists in specialized resin formulations qualified for EPA-compliant interstitial barrier applications. Distribution runs through engineering-procurement-construction contractors for industrial projects and municipal procurement offices for public infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA leak detection mandates constitute a regulatory inflection disrupting legacy single-wall infrastructure, creating sustained replacement demand that outpaces organic growth in new installation capacity.
For Market Incumbents: Shield installed base relationships through captive monitoring service contracts that transfer remediation liability and create switching costs. Backward integration into resin formulation secures supply continuity against epoxy feedstock volatility threatening production schedules. Prioritize certification maintenance for evolving state-level fire codes and NFPA standards that extend project lead times. For New Entrants and Emerging Players: Anchor in PFAS remediation liability redirection as municipalities abandon rehabilitation for full replacement with compliant systems. Target secondary containment retrofit opportunities in California and Florida where accelerated replacement programs collapse grandfathered single-wall positions. Pursue direct contracting with convenience store chains seeking standardized tank packages with performance guarantees. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed composite specialists possessing filament-winding expertise but lacking integrated monitoring platforms. Five-to-ten year viability hinges on service revenue attachment rates exceeding equipment margins. Watch EPA enforcement variance across state environmental agencies as signal for procurement velocity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| IoT Monitoring Platform Integration | Sensor-telemetry convergence enables predictive maintenance contracts with recurring revenue streams. |
| Filament-Winding Capacity Expansion | Gulf Coast proximity to resin supply reduces logistics costs and compresses delivery timelines. |
| Lifecycle Service Contract Structuring | Texas and Louisiana water authorities now mandate twenty-year performance guarantees with liability transfer. |
| REACH-Compliant Coating Reformulation | German chemical manufacturers demand barrier systems eliminating restricted substances for solvent containment. |
| Hydrogen Storage Vessel Development | High-pressure-rated composite geometries address emerging underground hydrogen containment specifications. |
Research Methodology
Operator-level perspectives from municipal water authority procurement officers, petrochemical facility engineering directors, tank installation contractors, and composite manufacturing plant managers anchored the qualitative base. Primary interview insights triangulated against EPA enforcement databases, state environmental agency permitting records, SEC filings from publicly traded tank fabricators, and American Petroleum Institute standards documentation. Bottom-up tank shipment data from regional manufacturing clusters reconciled with top-down infrastructure spending forecasts from federal and state budget disclosures.
Sensitivity analysis tested volume and value outputs across material substitution scenarios, regulatory enforcement variance, and resin price volatility throughout the forecast period. The analytical framework modeled segmentation across tank type, material composition, application hazard classification, and end-user contracting structure. CAGRs derived from fitted trend extrapolation validated against historical replacement cycle patterns and announced refinery capacity additions. Hydrogen storage adaptation timelines and smart monitoring penetration rates served as scenario-dependent inputs.
Decision-makers should treat outputs as directional under sustained EPA enforcement stringency and stable epoxy resin supply; material deviation would warrant model refresh. Specific risk factors include multi-agency certification timeline extensions, composite technician workforce scarcity, and concrete tank substitution in wastewater applications. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Asia-Pacific Lubricants Market
Petroleum Products
Petcoke Market
Petroleum Products
LPG [Liquefied Petroleum Gas] Market
Petroleum Products
France Refined Petroleum Product Market
Petroleum Products
Crude Oil Market
Petroleum Products
Pyrolysis Oil Market
Petroleum Products
South Africa Refined Petroleum Products Market
Petroleum Products
Southeast Asia Refined Petroleum Products Market
Petroleum Products
Tar Oil Market
Petroleum Products
Oil Storage Sales Market
Petroleum Products
Pyrolysis Gasoline Market
Petroleum Products
North Africa Refined Petroleum Products Market
Petroleum Products
Ultra Low Sulphur Fuel Oil (ULSFO) Market
Petroleum Products
Very Low Sulphur Fuel Oil (VLSFO) Market
Petroleum Products
Green Petcoke Market
Petroleum Products
Naphtha Market