
 North America Transformer Market | 2026-2036
North America Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
North America Transformer Market Outlook
Modular substation packaging is consolidating buyer preference across the North America Transformer Market as utilities seek faster deployment with smaller footprints. General Electric leverages its Waukesha manufacturing base to anchor large power transformer production for utility-scale projects. Siemens Energy competes through high-voltage direct current expertise and regional service networks. Hammond Power Solutions specializes in dry-type distribution units for commercial and industrial segments where indoor installation constraints dominate.
A transformer is a static electromagnetic device that transfers electrical energy between circuits through magnetic induction, typically operating at frequencies of 50 or 60 hertz with efficiency ratings exceeding 98 percent in modern designs. Its primary purpose is to step voltage up for efficient long-distance transmission or down for safe end-use distribution across power systems. Distribution transformers occupy the largest volume pool across the region due to pervasive grid-edge replacement cycles and residential electrification loads. Power transformers command concentrated margin pools where extra high voltage ratings and custom engineering create supplier stickiness with integrated utilities.
The US Department of Energy enforces minimum efficiency standards under 10 CFR 431 that dictate core steel grades and no-load loss thresholds for distribution units sold domestically. NERC reliability standards and provincial regulators in Canada shape procurement specifications for grid-connected assets, while OSHA and CSA Group certifications govern worker safety and equipment interoperability across the region. Stakeholders must monitor how state-level interconnection queue reforms and transformer lead-time volatility reshape capital planning timelines and inventory strategies.
Market Dynamics
ERCOT grid expansion and data center load growth in Texas are straining substation capacity across the region, forcing utilities to compress procurement timelines and accept modular packaging solutions that bypass traditional site-built construction cycles.
Growth Catalysts
- EPA Efficiency Mandates:Updated standards under the Energy Policy Act are accelerating replacement of aging transformer fleets across integrated utilities. The regulations dictate core steel grades and no-load loss thresholds that obsolete pre-2016 installed units.
- Renewable Interconnection:Remote wind and solar generation in the Great Plains requires new transmission infrastructure with step-up transformers rated for extra-high-voltage corridors. ERCOT interconnection queues are driving concentrated demand for power-class units.
- Data Center Electrification:Hyperscale facilities in Northern Virginia and Dallas-Fort Worth are creating step-load increments that exceed existing distribution capacity. Utilities are procuring larger dry-type units for indoor substation installations.
Market Restraints
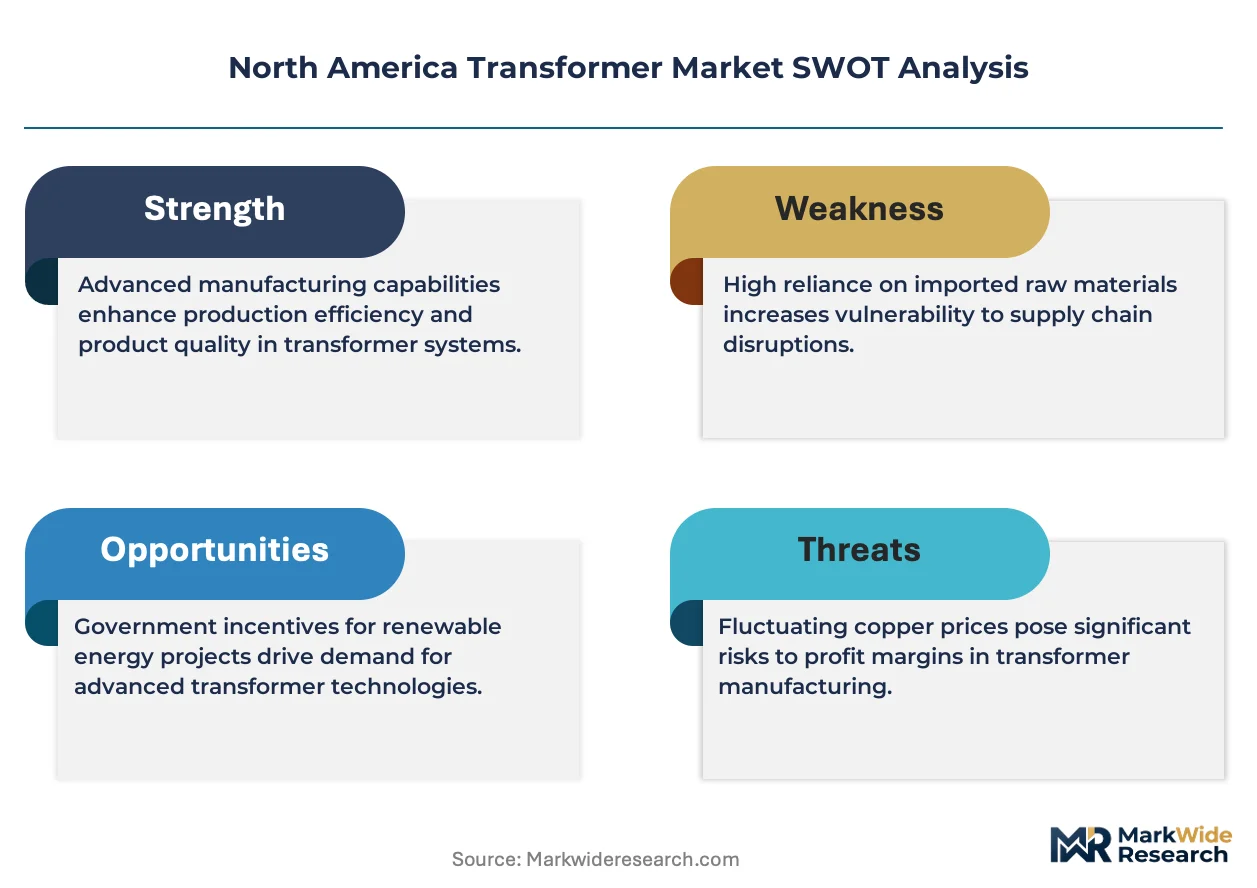
- Grain-Oriented Electrical Steel Concentration:Domestic GOES supply concentrates among a limited producer base, exposing transformer manufacturers to input cost volatility and allocation rationing during demand surges.
- Extended Lead Times:Large power transformer fabrication cycles now stretch 12-18 months due to core material scarcity and skilled winding labor shortages, freezing utility capital planning timelines.
- Copper Price Volatility:Winding conductor costs fluctuate with commodity markets, compressing margin visibility for distribution transformer producers on fixed-price utility contracts.
Strategic Opportunities
- Canadian Grid Modernization:Provincial utilities in Ontario and Alberta are replacing aging transmission assets with high-efficiency units, creating procurement windows for suppliers with CSA Group certification.
- Digital Twin Integration:Sensor-embedded transformers with predictive maintenance analytics are penetrating utility fleets, enabling performance-based service contracts that extend supplier revenue streams beyond hardware sales.
- Infrastructure Investment and Jobs Act:Federal transmission and grid resilience funding is unlocking utility capex for substation hardening projects that specify domestic content requirements.
Industry Challenges
- Specialized Winding Technician Shortage:The craft knowledge required for large power transformer core assembly and coil winding is retiring faster than apprenticeship programs can replenish, constraining production throughput.
- NERC CIP Compliance Burden:Critical infrastructure protection standards impose cybersecurity documentation and testing requirements that extend factory acceptance testing timelines and inflate engineering overhead.
- Legacy Asset Integration:New efficient units must interface with 40-60 year-old switchgear and protection systems, requiring custom engineering that fragments production scale economies.
Report Scope
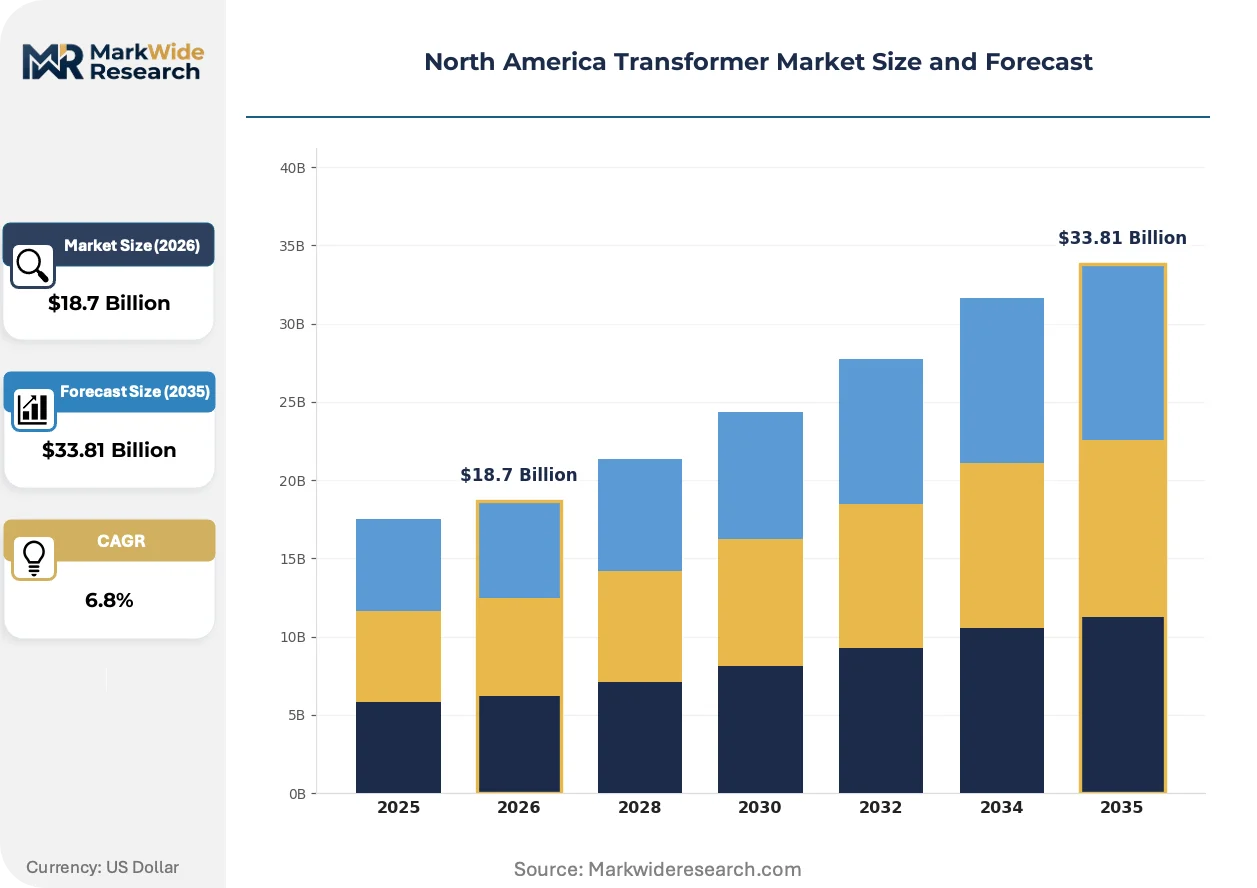
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Transformer Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Transformer, Distribution Transformer, Instrument Transformer, Specialty Transformer End User: Utilities, Industrial, Commercial, Residential Installation Type: Onshore, Offshore, Substation, Transmission Network Voltage Rating: Low Voltage, Medium Voltage, High Voltage, Extra High Voltage |
| Companies Covered | General Electric, Siemens Energy, Eaton, ABB, Schneider Electric, Hammond Power Solutions, Virginia Transformer Corp, Prolec-GE Waukesha, Northern Transformer Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Transformer Market Strategic Shifts
Transformer design is pivoting toward factory-integrated solutions that compress site construction schedules, while digital monitoring layers and efficiency regulations reshape supplier value propositions across voltage classes.
Modular substation packaging is consolidating buyer preference across voltage classes. Utilities facing interconnection queue pressures are specifying skid-mounted transformer-switchgear assemblies that ship as single units. This architecture is modularizing project delivery, enabling parallel civil and electrical workstreams that compress energization schedules by 30-40 percent compared to site-built alternatives.
The US Department of Energy enforces minimum efficiency standards under 10 CFR 431 that dictate core steel grades and no-load loss thresholds for distribution units. Manufacturers are responding with amorphous metal core designs that cut no-load losses by 70 percent versus conventional grain-oriented silicon steel. Distribution transformer procurement specifications in California and New York now mandate compliance with the most stringent loss bands, segmenting supplier capabilities.
Data center operators are unbundling transformer procurement from traditional EPC contracts to secure dedicated capacity. Hyperscale buyers in Northern Virginia and Phoenix are issuing direct purchase orders for dry-type units with K-factor ratings, bypassing utility intermediaries. This disintermediation concentrates volume with manufacturers holding UL listing and IEEE C57.12.01 certification, compressing margins for distributor-dependent competitors.
North America Transformer Market Segmentation
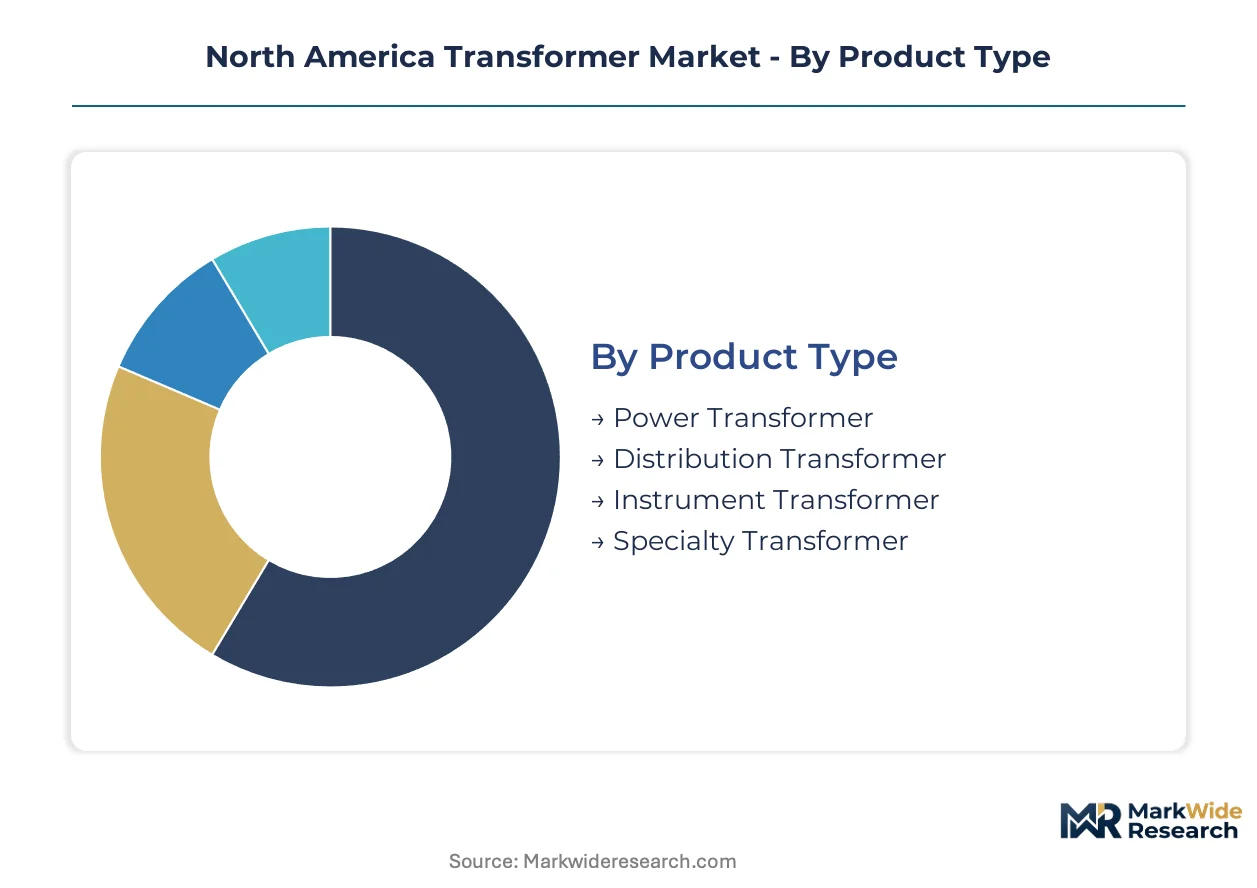
Transformer procurement patterns diverge sharply across voltage classes and installation contexts. Each segment carries distinct technical specifications, regulatory overlays, and margin structures that reshape supplier positioning.
Product Type:
Core design specifications and insulation systems define the competitive landscape across transformer categories.
- Power Transformer:Extra-high-voltage units rated above 60 MVA employ mineral oil insulation and forced-air cooling for utility-scale transmission corridors. ERCOT interconnection queues in Texas are absorbing record volumes as remote wind generation seeks grid access.
- Distribution Transformer:Pole-mounted and pad-mounted units dominate unit volume across residential electrification cycles. EPA efficiency mandates under 10 CFR 431 are obsoleting pre-2016 core designs and triggering fleet-wide replacement programs.
- Instrument Transformer:Current and voltage sensing units provide metering and protection inputs for grid monitoring systems. ANSI accuracy classes govern revenue metering applications.
- Specialty Transformer:Rectifier and furnace transformers serve industrial process loads with non-standard impedance profiles. Custom engineering cycles extend lead times beyond standard offerings.
Distribution Transformer leads on scale; Power Transformer leads on momentum.
End User:
Procurement authority and technical sophistication vary dramatically across customer categories.
- Utilities:Integrated transmission owners and distribution cooperatives specify NERC-compliant assets with 30-40 year service life. Capital planning cycles now stretch 24-36 months due to transformer lead-time volatility.
- Industrial:Heavy manufacturing and petrochemical facilities procure dry-type units for indoor substations. Arc flash mitigation and K-factor ratings drive specification complexity.
- Commercial:Data center operators in Northern Virginia and Dallas-Fort Worth are issuing direct purchase orders for dedicated transformer capacity. Hyperscale buyers bypass traditional utility intermediaries.
- Residential:Single-family electrification and multi-family construction drive pad-mounted distribution unit demand. California Title 24 efficiency standards exceed federal minimums.
Utilities command procurement volume; Commercial segments are climbing the fastest.
Installation Type:
Site constraints and civil work requirements reshape delivery architecture preferences.
- Onshore:Land-based installations encompass generation step-up, transmission substations, and distribution feeders. Modular skid-mounted packaging is compressing energization schedules by 30-40 percent.
- Offshore:Platform-mounted units serve Gulf of Mexico oil production and emerging Atlantic Coast wind developments. Salt spray corrosion protection adds engineering overhead.
- Substation:Dedicated transformer bays integrate switchgear, protection, and control systems. Brownfield expansions must interface with 40-60 year-old legacy assets.
- Transmission Network:Series and shunt compensation units stabilize long-distance AC corridors. Series capacitor banks and static VAR compensators accompany transformer installations.
Onshore dominates absolute deployment; Offshore shows steepest expansion trajectory.
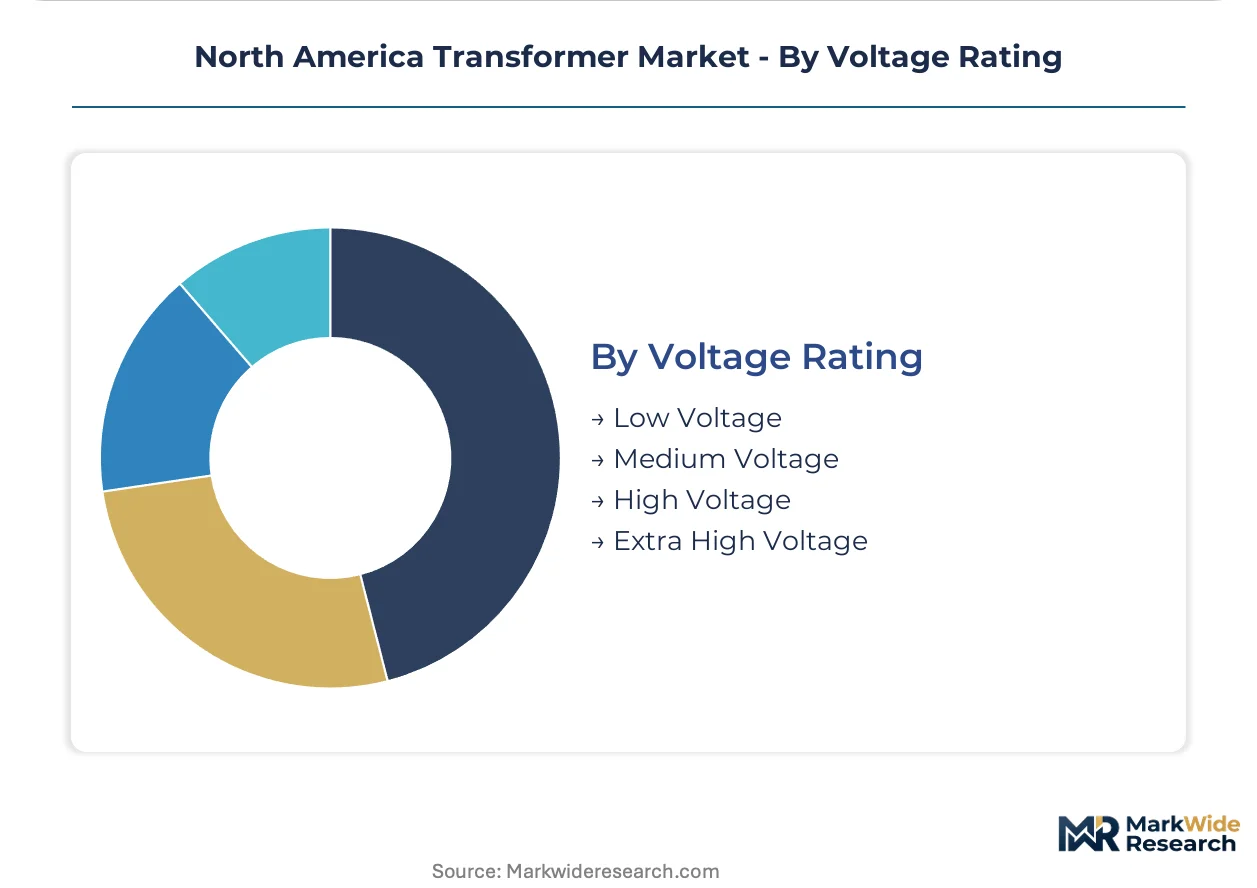
Voltage Rating:
Insulation coordination and thermal design intensify with voltage class escalation.
- Low Voltage:Units rated below 1 kV serve commercial building services and light industrial loads. Dry-type epoxy resin insulation dominates indoor applications.
- Medium Voltage:1-69 kV ratings cover distribution substations and industrial interconnections. Pad-mounted and vault-type enclosures address urban space constraints.
- High Voltage:69-230 kV step-up and step-down units interconnect transmission grids. BIL (basic insulation level) specifications govern lightning protection design.
- Extra High Voltage:Ratings above 230 kV enable long-distance bulk power transfer with minimal losses. Grain-oriented electrical steel core designs and forced oil cooling are mandatory.
Medium Voltage leads on unit volume; Extra High Voltage leads on margin concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American transformer industry traces its commercial roots to early twentieth-century electrification programs that established manufacturing corridors around the Great Lakes and Northeast industrial belt. Regional demand patterns now reflect divergent grid modernization timelines, renewable interconnection backlogs, and data center concentration clusters.
United States
ERCOT grid expansion and hyperscale data center load growth in Texas are absorbing record volumes of extra-high-voltage power transformers. EPA efficiency standards under 10 CFR 431 are obsoleting pre-2016 distribution fleets and triggering utility-wide replacement programs. Northern Virginia's Ashburn-Loudoun corridor hosts the densest concentration of data center transformer demand, with direct procurement bypassing traditional utility channels.
Canada
Provincial utilities in Ontario and Alberta are replacing aging transmission infrastructure with high-efficiency units rated for cold-climate operation. CSA Group certification requirements shape procurement specifications for grid-connected assets across provincial regulatory jurisdictions. Toronto and Calgary anchor industrial demand for dry-type distribution units in commercial and manufacturing applications.
Mexico
Nearshoring manufacturing expansion in Nuevo León and the Bajío Region is driving medium-voltage distribution transformer demand for new industrial parks. CFE transmission modernization programs specify domestic content requirements for substation equipment. Monterrey and Querétaro manufacturing clusters are procuring pad-mounted units for electrification of expanded production facilities.
North America Transformer Market Competitive Environment
Premium-margin players sit above commodity-margin players across voltage-class specialization and utility-scale project complexity. The vendor base organizes into three tiers: integrated electrical conglomerates with full voltage-range portfolios, mid-scale specialists focused on distribution-class units, and regional fabricators serving niche industrial applications. Strategic moves concentrate on modular packaging capabilities and factory-integrated substation solutions that compress customer energization schedules.
Among North American-based manufacturers, General Electric, Siemens Energy, and Hammond Power Solutions exemplify distinct competitive archetypes. General Electric anchors large power transformer production through its Waukesha manufacturing footprint, serving utility-scale transmission projects. Siemens Energy competes through high-voltage direct current expertise and regional service network density. Hammond Power Solutions occupies the distribution-class specialist tier, concentrating on dry-type units for commercial and industrial segments where indoor installation constraints dominate specification requirements.
| Leading Market Players |
|---|
| General Electric |
| Siemens Energy |
| Eaton |
| ABB |
| Schneider Electric |
| Hammond Power Solutions |
| Virginia Transformer Corp |
| Prolec-GE Waukesha |
| Northern Transformer Corporation |
| Others |
Value Chain & Pricing Dynamics
Captive grain-oriented electrical steel production anchors supply positioning and pricing power for integrated transformer manufacturers serving North American utilities. Backward integration into core material fabrication buffers margin volatility when commodity markets spike, while non-integrated distributors absorb price swings through inventory risk.
Pricing Analysis
Project-based long-term contracting dominates large power transformer procurement, with utility offtake agreements spanning multi-year fabrication cycles. Price differentiation hinges on NERC certification tier and domestic content compliance under Buy American provisions. Cost compression in distribution-class units is intensifying because amorphous metal core designs command premium positioning against conventional silicon steel. Data center operators exhibit lowest price sensitivity due to load-critical energization timelines, while residential contractors face acute budget constraints on pad-mounted unit specifications.
Supply Chain Analysis
UL listing and IEEE C57 certification gating restricts qualified supplier pools to established manufacturers with proven testing infrastructure. Core steel supply concentrates in the United States, Japan, and Germany, with grain-oriented electrical steel drawing from specialized rolling mills. Winding copper and transformer oil feed from commodity markets exposes producers to input cost volatility. Single-source vulnerability in electrical steel allocation during demand surges threatens production throughput. Distribution runs through utility procurement departments and EPC contractor intermediaries for project-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Transformer Market compounds steadily as grid modernization mandates and renewable interconnection backlogs sustain replacement demand across voltage classes. EPA efficiency standards and data center electrification provide durable demand tailwinds.
For Market Incumbents: Deepen captive core steel supply through tolling arrangements with domestic rolling mills to defend against grain-oriented electrical steel allocation rationing. Expand modular substation packaging capacity in Texas and Virginia to capture ERCOT and Northern Virginia data center procurement windows before emerging fabricators secure UL listing.
For New Entrants and Emerging Players: Direct-to-utility digital procurement platforms offer white-space entry for CSA-certified manufacturers targeting Canadian provincial utilities in Ontario and Alberta. Specialty dry-type units for indoor data center substations present the most penetrable segment, with K-factor rating expertise as the critical go-to-market differentiator against established distributors.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale distribution transformer specialists because utility procurement consolidation favors vendors with multi-site service networks and NERC compliance documentation. The long-term viability window favors manufacturers with amorphous metal core capabilities and factory-integrated digital monitoring layers. Watch transformer lead-time volatility as the inflection signal—sustained extension beyond historical norms indicates structural supply shortage and pricing power accumulation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Core Steel Supply | Tolling agreements with domestic rolling mills buffer margin volatility during GOES allocation crunches. |
| Modular Substation Packaging Scale-Up | Factory-integrated skid-mounted assemblies compress Texas and Virginia energization schedules by 30-40 percent. |
| Amorphous Metal Core Manufacturing Investment | EPA 10 CFR 431 compliance positions suppliers for California and New York efficiency mandate capture. |
| Digital Twin Platform Development | Sensor-embedded transformers enable predictive maintenance contracts extending revenue beyond hardware sales. |
| CSA Group Certification Expansion | Canadian provincial utility procurement specifications require CSA validation for grid-connected asset eligibility. |
Study Parameters
Bottom-up utility procurement modeling reconciled against top-down transformer manufacturing output tracking forms the analytical core of this study. Primary interviews with utility planning officers, EPC contractor procurement leads, transformer plant managers, and grid operator interconnection queue administrators combined with secondary validation from EIA generation data, FERC transmission filings, NERC reliability reports, and EPA regulatory dockets. Triangulation between demand-side capital expenditure disclosure and supply-side production capacity verification anchors volume estimates.
Historical trendline analysis across transformer installation databases and utility asset replacement schedules informed projection construction. Segmentation modeling spans voltage rating, core design specification, installation architecture, end-user category, and regional regulatory framework. CAGRs derive from regression analysis of replacement cycle timing, renewable interconnection queue depth, and efficiency mandate compliance deadlines. Forecast inputs incorporate grain-oriented electrical steel capacity utilization rates and data center power demand disclosure from hyperscale operators.
The model assumes a particular technology adoption path for amorphous metal core distribution transformers; alternative pathways for conventional silicon steel retention would alter the outlook if raw material cost differentials narrow. Forecasts reflect documented assumptions regarding EPA enforcement continuity and ERCOT interconnection queue processing rates. A model refresh is warranted upon material change in federal domestic content requirements or grain-oriented electrical steel trade policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
North America Dry Type Transformer Market
Transformers
Current Transformer Market
Transformers
United Arab Emirates Transformer Market
Transformers
Middle East Distribution Transformer Market
Transformers
North America Oil Filled Transformer Market
Transformers
Europe Oil Filled Distribution Transformer Market
Transformers
Phase-Shifting Transformer Market
Transformers
Asia-Pacific Power Transformer (Below 100 MVA) Market
Transformers
Green Transformer Market
Transformers
Global Transformer Market
Transformers
Asia Pacific Smart Transformers Market
Transformers
Box Transformer Substation Market
Transformers
Smart Transformer Market
Transformers
Europe Smart Transformers Market
Transformers
Green Power Transformers Market
Transformers
Latin America Transformer Market