
 Canada Transformer Market | 2026-2036
Canada Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Transformer Market Outlook
Data center operators and heavy industrial facilities are redrawing procurement patterns across the Canadian transformer landscape. Northern Transformer Corporation anchors domestic manufacturing capacity through its Toronto-area production base. Siemens AG leverages European engineering standards to compete on high-voltage intertie projects. Hammond Power Solutions specializes in dry-type units for commercial and indoor installations where fire safety codes are tightening.
A transformer is a static electromagnetic device that transfers electrical energy between circuits through mutual induction, typically operating at frequencies of 50 or 60 Hz with voltage ratings spanning from distribution-level kilovolts to transmission-class 765 kV. Its core function is to step voltage up for efficient long-distance power transfer or step it down for safe end-use consumption. Power transformers capture the bulk of capital deployment as provincial utilities replace aging transmission assets, while dry-type technology is gaining share in urban commercial settings where oil containment costs and indoor fire codes drive specification shifts. Distribution transformers remain the highest-volume category, though margin pools concentrate in specialized instrument transformers serving metering and protection systems.
Health Canada and the Canadian Standards Association set insulation and fire-safety benchmarks that shape product certification timelines and material selection. The Canadian Electrical Code, administered by provincial authorities, mandates efficiency tiers that filter which designs qualify for utility procurement. Natural Resources Canada enforces energy performance standards under its EnerGuide framework, pushing manufacturers toward lower-loss core materials. Stakeholders must track how provincial renewable integration targets and interprovincial transmission commitments reshape transformer sizing requirements and delivery schedules.
Market Dynamics
Provincial utilities across Ontario and Quebec are accelerating grid-connected asset procurement as Natural Resources Canada tightens efficiency standards under its EnerGuide framework, forcing manufacturers toward lower-loss core materials and compressed certification timelines.
Growth Catalysts
- Interprovincial Transmission Upgrades:Natural Resources Canada is channeling federal funding into cross-border grid infrastructure, expanding procurement pools for high-voltage intertie transformers.
- Data Center Electrification:Hyperscale facilities in the Toronto-Montreal corridor are driving demand for dry-type units with enhanced fire-safety ratings.
- Manufacturing Reshoring:Heavy industrial electrification across southwestern Ontario is lifting orders for medium-voltage distribution transformers.
Market Restraints
- Grain-Oriented Electrical Steel Concentration:Domestic manufacturers rely on concentrated North American and Asian suppliers for transformer-grade core steel, exposing margins to input volatility.
- Extended CSA Certification Cycles:Canadian Standards Association testing protocols for fire-resistant insulation systems add 4-8 months to product launch timelines.
- Technical Limitation in Amorphous Metal Adoption:Core loss advantages remain offset by brittleness and winding complexity in high-voltage designs.
Strategic Opportunities
- Underpenetrated Northern Territories:Remote mining and indigenous community electrification in Nunavut and Northwest Territories remain underserved by conventional distribution networks.
- Battery Storage Integration:Hybrid inverter-transformer skids for Ontario's grid-scale storage procurements represent emerging specification demand.
- Channel Innovation via Utility Partnerships:Direct OEM-utility framework agreements are displacing traditional distributor intermediaries in large capital projects.
Industry Challenges
- Specialized Winding Technician Scarcity:Aging workforce demographics in precision coil winding and vacuum pressure impregnation create recruitment bottlenecks.
- Legacy SCADA Integration Complexity:Digital monitoring retrofits for installed oil-filled units face protocol fragmentation across provincial utility fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Transformer Market |
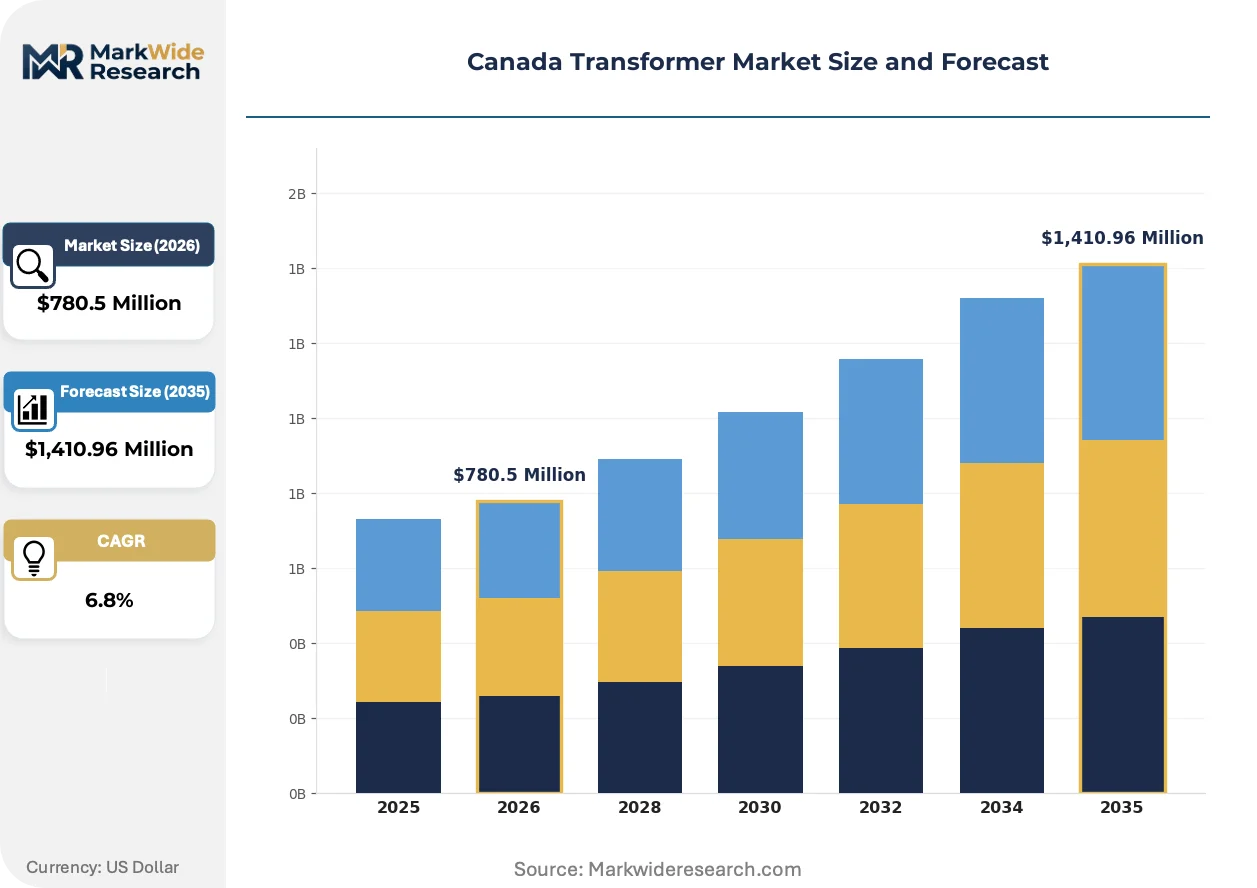
| Market Size in 2026 | $780.5 Million |
| Market Size in 2035 | $1,410.96 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Transformers, Distribution Transformers, Autotransformers, Instrument Transformers End User: Utilities, Industrial, Commercial, Residential Installation Type: Onshore, Offshore, Indoor, Outdoor Technology: Oil-Immersed, Dry-Type, Gas-Insulated, Vacuum |
| Companies Covered | Northern Transformer Corporation, PTI Transformers, Siemens AG, CES Transformers, Hitachi Energy, Schneider Electric SE, Hammond Power Solutions, Electric Power Inc, Eaton Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Transformer Market Strategic Shifts
Transformer technology in Canada is pivoting toward fire-safe indoor deployment and digital monitoring integration, driven by urban density constraints and utility asset management modernization.
Amorphous metal core technology is fragmenting traditional silicon steel dominance in distribution-class units. Data center operators and commercial building developers are specifying these cores for indoor installations where fire codes restrict oil-filled alternatives. The technology is fragmenting procurement patterns by enabling smaller-footprint, higher-efficiency designs that command premium positioning against conventional offerings.
Natural Resources Canada's EnerGuide efficiency tiers are tightening loss allowances for distribution transformers. Manufacturers must redesign core geometries and adopt higher-grade electrical steels to maintain procurement eligibility. Ontario's local distribution companies are most affected, with efficiency-compliant units now mandatory for new connections and replacement cycles.
Asset performance monitoring contracts are unbundling from hardware sales as utilities seek predictive maintenance capabilities. Traditional lump-sum procurement is yielding to service-layer subscriptions with embedded sensor diagnostics. This shift is most visible in Hydro-Québec's transmission fleet, where digital twin integration is becoming a standard evaluation criterion.
Canada Transformer Market Segmentation
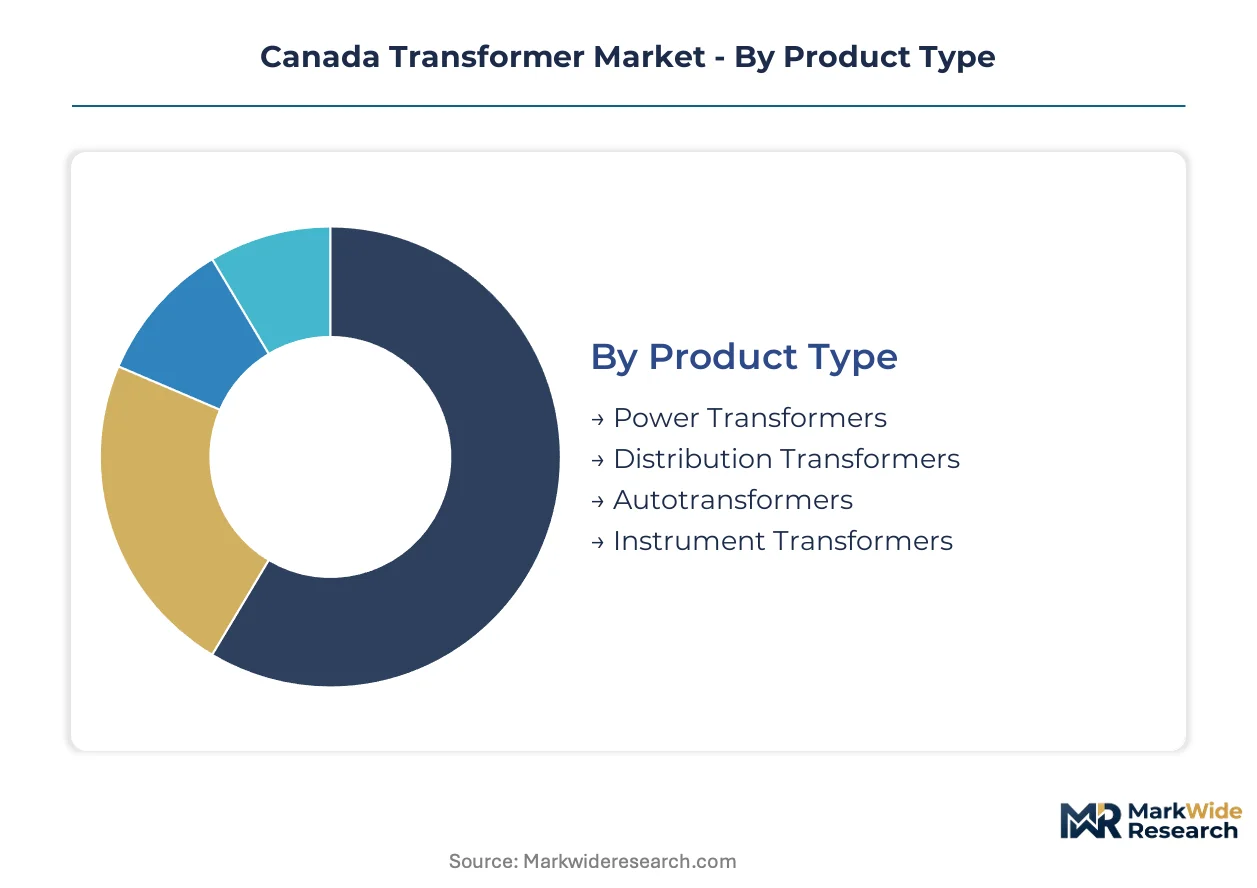
Transformer procurement in Canada fragments across voltage class, application environment, and thermal management approach. Each segmentation axis carries distinct certification requirements under CSA and provincial electrical codes, shaping supplier qualification barriers and margin structures.
Product Type:
Oil-immersed designs face substitution pressure from dry-type alternatives as Ontario and Quebec tighten indoor fire safety codes for commercial and data center installations.
- Power Transformers:These units handle bulk power transfer at transmission voltages above 60 kV, utilizing oil-immersed cooling and laminated grain-oriented steel cores. Procurement concentrates with Hydro-Québec and Ontario's IESO for interprovincial tie lines and aging 230 kV corridor replacements, where lead times now stretch 18-24 months due to specialized winding capacity constraints.
- Distribution Transformers:Step-down units operating between 4-36 kV serve local distribution networks and industrial interconnections. Demand clusters in southwestern Ontario's manufacturing reshoring zones and Toronto's data center buildouts, with Natural Resources Canada's EnerGuide efficiency tiers now mandating lower-loss core materials for all new utility procurements.
- Autotransformers:Single-winding designs provide voltage transformation with reduced copper mass for specific ratio applications.
- Instrument Transformers:Current and voltage sensing units isolate metering and protection circuits from high-voltage primaries.
Distribution transformers retain volume leadership; power transformers hold the steepest expansion curve.
End User:
Procurement authority splits between centralized utility capital programs and fragmented industrial site electrification, with divergent specification priorities.
- Utilities:Provincial crown corporations and local distribution companies dominate high-voltage procurement through multi-year framework agreements. Hydro-Québec's transmission fleet modernization and Ontario's grid-scale storage integration are reshaping transformer sizing requirements toward higher MVA ratings with embedded digital monitoring.
- Industrial:Heavy manufacturing, mining, and primary metals operations drive medium-voltage demand for motor drives and furnace feeds. Northern Ontario's ring of fire mining developments and Alberta oil sands electrification projects are lifting orders for ruggedized outdoor units with extended temperature ranges.
- Commercial:Office complexes, retail, and institutional buildings specify lower-kVA dry-type units for indoor electrical rooms.
- Residential:Single-phase pole-mounted and pad-mounted units serve last-mile distribution.
Utilities command the largest transaction values; industrial buyers are expanding most quickly.
Installation Type:
Site constraints and environmental exposure dictate enclosure ratings, cooling system selection, and maintenance access protocols.
- Outdoor:Pad-mounted and pole-mounted configurations withstand Canadian climatic extremes from Atlantic salt spray to Prairie temperature swings. These units dominate utility distribution networks and remote industrial sites where indoor space is unavailable or uneconomical.
- Indoor:Dry-type and less-flammable liquid-filled designs occupy electrical vaults and dedicated equipment rooms. Toronto's downtown density and Montreal's underground distribution corridors are accelerating indoor specifications, with CSA C9 fire-resistance testing now mandatory for high-rise applications.
- Onshore:Conventional ground-based installation across all voltage classes.
- Offshore:Specialized marine-grade units for coastal and island applications.
Outdoor installations retain volume leadership; indoor configurations are gaining share fastest.
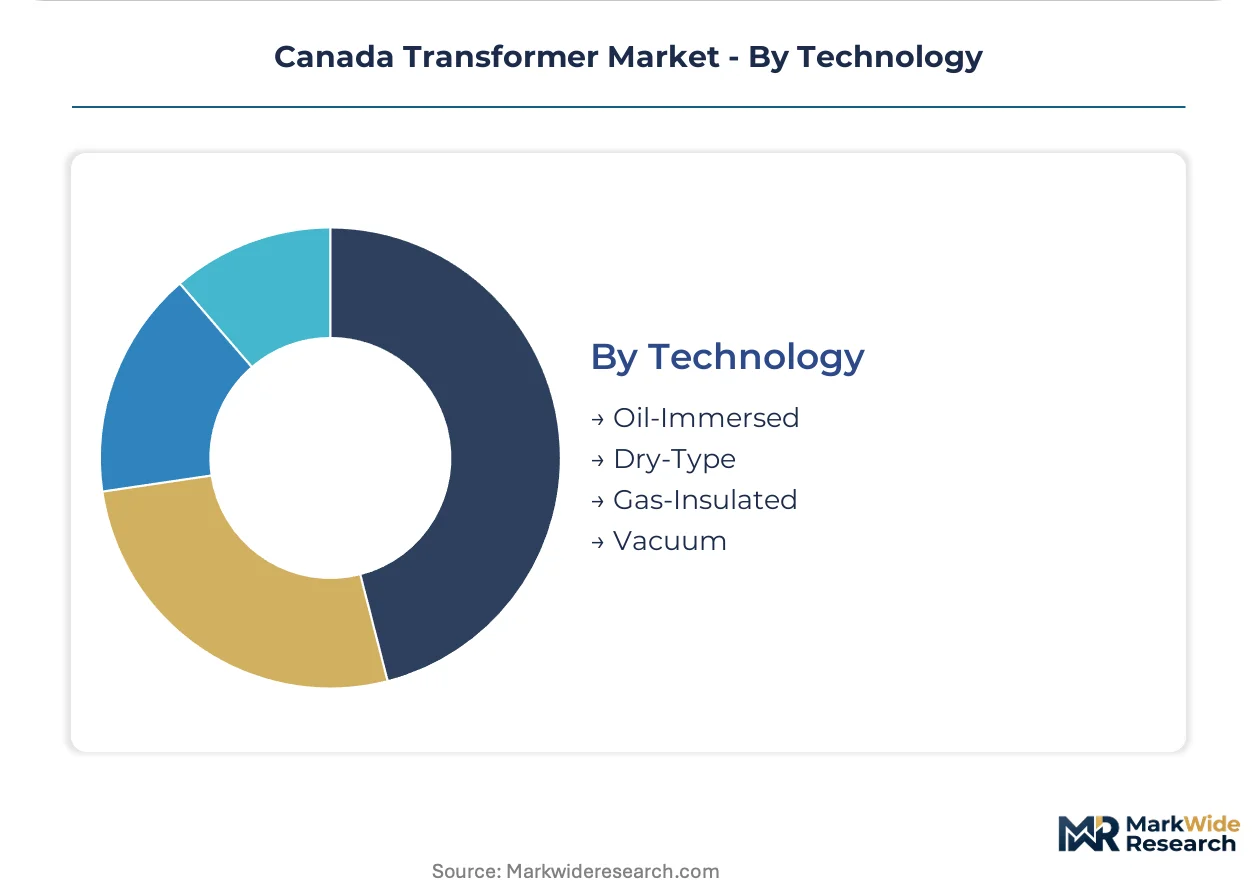
Technology:
Thermal management and insulation media selection determines efficiency profiles, fire safety classification, and lifecycle maintenance burdens.
- Oil-Immersed:Mineral oil or ester-based dielectric fluids provide superior heat dissipation for high-power density applications. These designs dominate transmission-class procurement and outdoor distribution, though containment requirements and spill remediation costs are driving specification shifts in environmentally sensitive watersheds.
- Dry-Type:Air-cooled designs with epoxy or cast resin insulation eliminate liquid fire risks and enable indoor deployment. Data center operators across the Toronto-Montreal corridor are specifying these units exclusively, with amorphous metal core variants capturing efficiency-sensitive segments despite 15-20% cost premiums.
- Gas-Insulated:SF6 or fluoronitrile-based designs for compact high-voltage installations.
- Vacuum:Specialized applications leveraging vacuum as dielectric medium.
Oil-immersed technology retains volume leadership; dry-type designs are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian transformer manufacturers export primarily to United States utilities along cross-border transmission corridors, with Ontario and Quebec serving as the dominant production and demand centers.
Ontario
Toronto's data center buildouts and southwestern Ontario manufacturing electrification drive procurement of medium-voltage distribution units. Natural Resources Canada's EnerGuide efficiency tiers mandate lower-loss core materials for all new utility connections. The Windsor-Toronto-Ottawa corridor concentrates transformer deployment for automotive reshoring and grid-scale battery storage integration.
Quebec
Hydro-Québec's transmission fleet modernization and interprovincial tie line expansions lift demand for high-voltage power transformers. The Canadian Standards Association enforces fire-resistance testing protocols that extend certification timelines for new product launches. Montreal's underground distribution network and northern mining electrification projects anchor procurement volume.
Alberta
Oil sands electrification and renewable integration targets reshape transformer specifications toward ruggedized outdoor designs. Alberta Utilities Commission interconnection standards filter which equipment qualifies for grid deployment. Edmonton-Calgary industrial corridors concentrate demand for motor drive and furnace feed applications.
British Columbia
BC Hydro's transmission infrastructure upgrades and coastal marine-grade requirements drive specialized procurement. The province's clean electricity objectives accelerate intertie transformer deployment for Pacific Northwest power trading. Vancouver's port electrification and interior mining operations anchor regional demand clusters.
Canada Transformer Market Competitive Environment
Player mix skews toward domestic manufacturers with regional fabrication capacity and multinational electrical equipment conglomerates with established utility relationships. The competitive structure concentrates around three strategic tiers: Toronto-area specialists with proximity advantages, European engineering-led multinationals bidding interprovincial projects, and North American power equipment broadliners with integrated distribution networks. Dominant competitive moves include direct OEM-utility framework agreements displacing traditional distributor channels, and efficiency-focused product redesigns to meet tightening EnerGuide loss allowances.
Within the domestic specialist tier, Northern Transformer Corporation and PTI Transformers exemplify Toronto-area production capacity serving Ontario-Quebec demand corridors. Siemens AG occupies a position among European engineering-led multinationals competing for high-voltage intertie projects, while Hammond Power Solutions anchors the dry-type specialization segment for indoor commercial and data center applications where CSA fire-safety codes drive specification shifts.
| Leading Market Players |
|---|
| Northern Transformer Corporation |
| PTI Transformers |
| Siemens AG |
| CES Transformers |
| Hitachi Energy |
| Schneider Electric SE |
| Hammond Power Solutions |
| Electric Power Inc |
| Eaton Corporation |
| Others |
Value Chain & Pricing Dynamics
Amorphous metal core adoption in distribution-class units simultaneously redraws supplier geography toward specialized Asian steel mills and compresses pricing premiums as Ontario utilities enforce Natural Resources Canada EnerGuide loss allowances. This substitution dynamic forces incumbent manufacturers to absorb higher input costs or cede share to efficiency-focused competitors.
Pricing Analysis
Technology-generation pricing gaps separate conventional grain-oriented silicon steel cores from amorphous metal alternatives and emerging nanocrystalline prototypes. Three-tier pricing structure across premium efficiency, standard compliance, and economy-grade tiers reflects certification level under CSA C802 efficiency standards and after-sales service bundling. Pricing pressure stems from raw material volatility in transformer-grade electrical steel, with margins tightening most acutely in standard-tier procurement. Data center operators exhibit lowest price sensitivity, prioritizing fire-safety ratings and footprint reduction over unit cost.
Supply Chain Analysis
Strategic stockpiling of grain-oriented electrical steel dominates procurement behavior among Canadian manufacturers confronting 18-24 month transformer lead times. Supply concentrates in Japan, South Korea, and select North American mills for core steel, with copper winding conductors drawing from Chilean and domestic smelters. Single-source vulnerability concentrates in specialized amorphous metal ribbon feedstock from Asian suppliers. Distribution runs through direct OEM-utility framework agreements displacing traditional electrical distributor networks for projects above 10 MVA.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against solid-state transformer architectures and power electronics integration threatening conventional electromagnetic designs. Incumbents must navigate efficiency-tier compression while protecting core material sourcing relationships.
For Market Incumbents: Fortify backward integration into transformer-grade steel sourcing through long-term offtake agreements with Japanese and South Korean mills. Anchor certification investment in CSA C9 fire-resistance testing to lock out commodity competitors from Toronto-Montreal data center procurement. Defend against solid-state transformer encroachment by embedding digital monitoring subscriptions that create switching costs. For New Entrants and Emerging Players: Anchor in Nunavut and Northwest Territories mining electrification where incumbent coverage remains thin and logistics complexity deters established competitors. Target hybrid inverter-transformer skids for Ontario grid-scale battery storage procurements as the most penetrable specification segment. Pursue direct utility framework agreements rather than distributor channel penetration to capture margin and specification influence. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision winding capability and established utility relationships over pure manufacturing scale. Long-term viability hinges on digital service-layer attachment rates and efficiency-tier positioning through the projection horizon. Target acquisition archetypes combine Toronto-area fabrication assets with embedded utility framework contracts. Watch Hydro-Québec transmission fleet digital twin integration requirements as the signal for predictive maintenance contract inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Core Steel Supply | Long-term offtake agreements with Japanese mills insulate margins from spot volatility in transformer-grade electrical steel. |
| CSA C9 Fire-Resistance Certification Investment | Mandatory testing protocols for Toronto high-rise applications create qualification barriers against uncertified competitors. |
| Digital Twin Service-Layer Subscription | Hydro-Québec's predictive maintenance requirements unbundle hardware from recurring revenue streams. |
| Hybrid Inverter-Transformer Skid Development | Ontario battery storage procurements generate emerging specification demand beyond conventional transformer boundaries. |
| Direct OEM-Utility Framework Agreement | Channel displacement of electrical distributors captures margin and secures multi-year procurement visibility. |
Study Parameters
Initial hypotheses were tested against primary input from utility planning officers, transformer procurement managers at provincial crown corporations, EPC contractors specializing in intertie projects, and precision winding technicians, then refined through secondary validation. Sources included Natural Resources Canada EnerGuide compliance databases, CSA certification registries, Hydro-Québec and IESO capital expenditure disclosures, customs import records for electrical steel, and provincial electrical code amendments. Bottom-up unit economics triangulated against top-down utility capital deployment trajectories.
Variance decomposition across voltage class, cooling technology, end-use sector, and regional regulatory cluster shaped the analytical framework. CAGRs derived from modeled replacement cycles, efficiency-tier adoption curves, and data center deployment pipelines throughout the forecast period. Industry-specific inputs incorporated grain-oriented steel price indices, CSA certification timeline distributions, and interprovincial transmission commitment schedules.
Material uncertainties — supply disruption in Asian amorphous metal feedstock, abrupt CSA efficiency tier revisions, or accelerated solid-state transformer commercialization — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding provincial renewable integration targets and utility capital allocation priorities. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Rail Traction Transformers Market
Transformers
Green Power Transformers Market
Transformers
Auto Transformer Rectifier Unit (ATRU) Market
Transformers
Neon Transformer Market
Transformers
Gas Insulated Transformer Market
Transformers
Cast Resin Transformers Market
Transformers
Asia Pacific Smart Transformers Market
Transformers
Transformer Core Market
Transformers
Step Up/Down Transformers Market
Transformers
Single Phase Power Transformer Market
Transformers
Transformer Oil Market
Transformers
Uninhibited Transformer Oil Market
Transformers
Air Cooled Transformer Market
Transformers
North America Oil Filled Transformer Market
Transformers
North America Power Transformer Market
Transformers
Three Phase Transformer Market