
 Transformer Monitoring Systems (TMS) Market | 2026-2036
Transformer Monitoring Systems (TMS) Market Size, Share, and Industry Trends Forecast 2026-2036
Transformer Monitoring Systems (TMS) Market Analytics
Modular hardware-software bundles is repositioning procurement patterns across the TMS value chain. Schneider Electric leverages its integrated IoT platform to anchor large utility deployments across multiple continents. Siemens Energy AG specializes in AI-based analytics modules that differentiate its offering from component-only suppliers. Eaton competes through extensive channel control in North American industrial markets.
Transformer Monitoring Systems comprise sensor arrays, communication gateways, and analytics platforms that measure dissolved gas analysis, load tap changer performance, and thermal profiles to predict insulation failure and optimize maintenance scheduling. The primary commercial purpose centers on extending transformer asset life while preventing catastrophic outages in critical power infrastructure. Condition monitoring currently dominates installed base revenue due to mature IEC 60599 standards, whereas predictive maintenance represents the fastest-expanding margin pool as utilities shift from time-based to condition-based asset strategies. Cloud computing infrastructure underpins this transition by enabling centralized fleet analytics across geographically dispersed transformer populations.
The Federal Energy Regulatory Commission enforces mandatory reliability standards through NERC CIP that directly mandate monitoring capabilities for bulk power system transformers. The EU Green Deal and F-Gas Regulation impose efficiency and leak-detection requirements that expand addressable demand for integrated monitoring solutions. Grid operators and asset managers must evaluate vendor platform interoperability before committing to multi-decade deployment architectures.
Market Dynamics
Cloud-connected monitoring platforms are compressing maintenance cycles across utility transformer fleets, forcing legacy equipment suppliers to re-architect around subscription analytics rather than hardware-only sales.
Growth Catalysts
- FERC NERC CIP mandates:The Federal Energy Regulatory Commission enforces mandatory reliability standards that directly require monitoring capabilities for bulk power system transformers across the United States.
- Dissolved gas analysis sensors:Advanced sensor arrays detecting hydrogen and methane levels enable predictive insulation failure detection, extending asset life in critical substation infrastructure.
- Germany's grid modernization:Utility operators in Germany are replacing aging substation infrastructure under EU Green Deal efficiency requirements, concentrating demand for integrated monitoring solutions.
Market Restraints
- Copper and rare earth volatility:Sensor manufacturing depends on copper windings and neodymium magnets, with price swings compressing hardware margins for component suppliers.
- Legacy protocol fragmentation:Substation automation systems run incompatible communication standards, forcing costly gateway development to bridge IEC 61850 with proprietary SCADA networks.
- Utility procurement inertia:Publicly regulated utilities face multi-year capital approval cycles that delay condition-based maintenance adoption despite proven ROI.
Strategic Opportunities
- India's smart grid rollout:The country's national power regulator is mandating distribution transformer monitoring under revised grid codes, opening greenfield deployment opportunities.
- Edge-AI convergence:On-device inference engines combined with 5G private networks enable real-time thermal profiling without cloud dependency, appealing to security-sensitive operators.
- Outcome-based service contracts:Asset managers are unbundling hardware from performance guarantees, creating recurring revenue pools for vendors willing to assume uptime risk.
Industry Challenges
- Field engineering scarcity:Installation and calibration of dissolved gas analysis systems requires specialized technicians familiar with both electrical safety and chromatography principles.
- IEC 60599 certification timelines:Third-party validation of gas ratio interpretation algorithms extends product launch schedules by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transformer Monitoring Systems (TMS) Market |
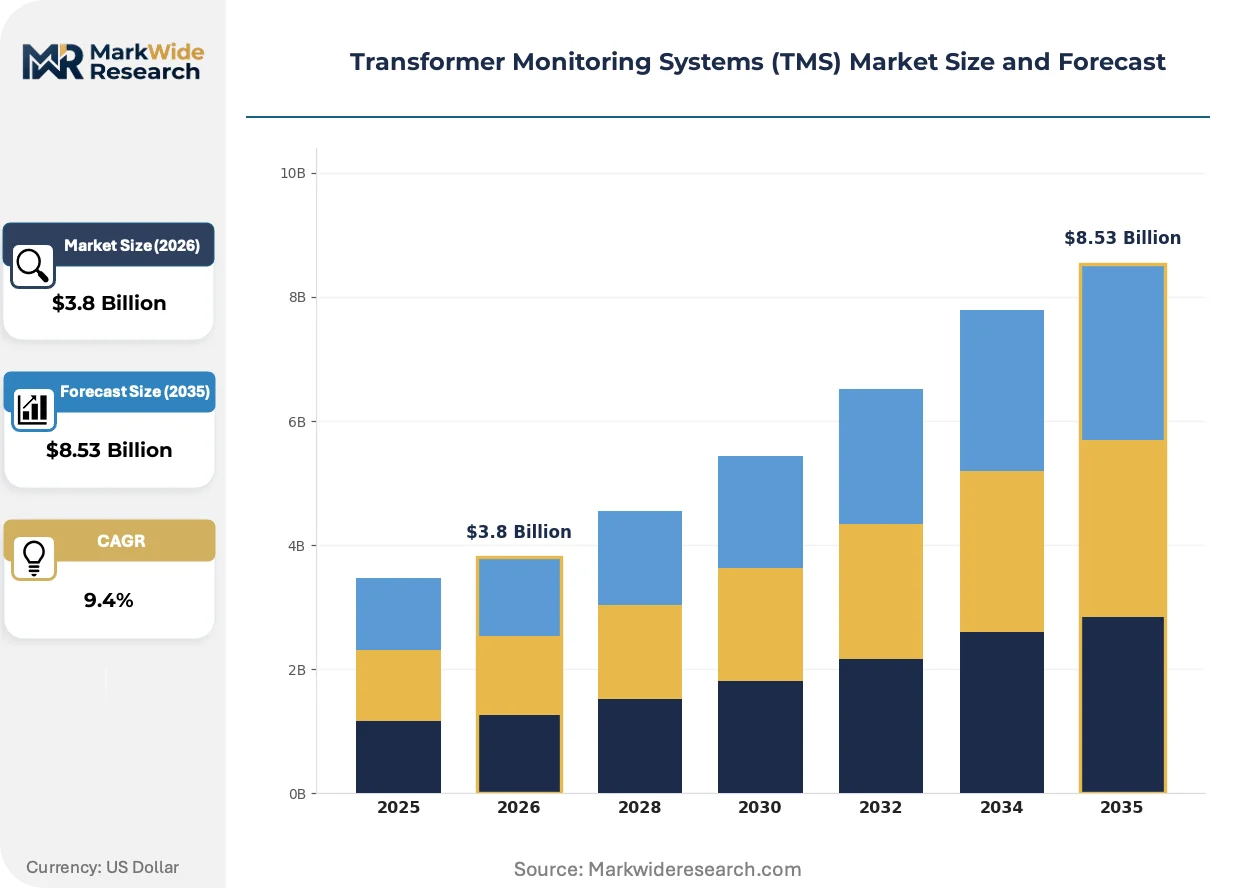
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Condition Monitoring, Advanced Monitoring, Predictive Maintenance, Real-time Monitoring Technology: IoT, AI-based Analytics, Wireless Sensor Networks, Cloud Computing End User: Utilities, Industrial Manufacturers, Oil & Gas Companies, Renewable Energy Providers Installation: On-site, Off-site, Hybrid, Remote |
| Companies Covered | Schneider Electric, Eaton, GE Vernova, Mistras Group, Qualitrol, Siemens Energy AG, ABB, Doble Engineering Company, Hitachi Energy Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transformer Monitoring Systems (TMS) Market Evolving Landscape
Digital twin architectures are redefining how utilities simulate transformer degradation, merging physics-based models with live sensor feeds to compress maintenance decision cycles from months to hours.
Optical fiber distributed temperature sensing is overtaking conventional thermocouple arrays for winding hotspot detection. European transmission operators are deploying fiber-optic cables embedded directly in transformer windings during factory refurbishment. This technology is overtaking point-sensor approaches by delivering continuous thermal profiles rather than discrete measurements, enabling dynamic loading strategies that extract 15-20% additional capacity from existing assets.
The EU F-Gas Regulation is tightening leak-detection requirements for transformer insulating fluids, mandating continuous monitoring for units above certain capacity thresholds. Industrial consequence includes mandatory sensor retrofits on existing installations, not merely new builds. Grid operators in France and Germany are responding by bundling F-Gas compliance modules into broader condition monitoring contracts, accelerating vendor consolidation around integrated platform providers.
Asset managers are consolidating procurement around fleet-wide analytics subscriptions rather than unit-by-unit hardware purchases. This pattern disrupts traditional electrical distributor channels that specialized in component sales. The shift is most visible among municipal utilities in the United States, where constrained engineering staff favor turnkey monitoring services over in-house system integration.
Transformer Monitoring Systems (TMS) Market Segmentation
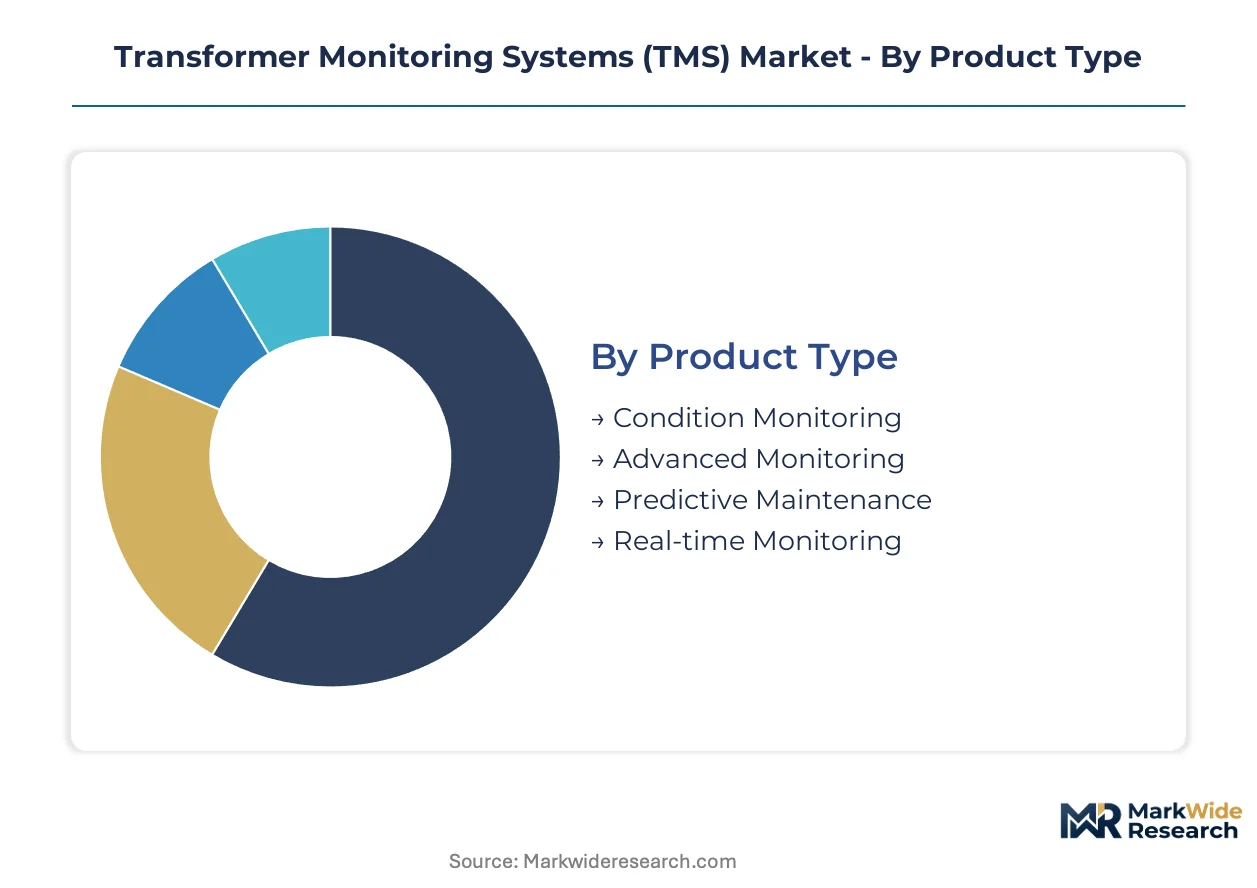
Transformer Monitoring Systems fragment across four dimensions that determine deployment economics and vendor selection criteria. Product type dictates hardware intensity, while technology choices shape recurring revenue potential for platform providers.
Product Type:
Capital requirements vary sharply across this category, with predictive maintenance platforms demanding the heaviest upfront software investment while condition monitoring relies on established sensor hardware.
- Condition Monitoring:Sensor arrays measuring dissolved gas, thermal profiles, and load tap changer performance against IEC 60599 standards. Utilities in Germany and the United States concentrate procurement here for aging substation fleets where proven reliability outweighs advanced analytics.
- Predictive Maintenance:Machine learning models forecasting insulation failure from multi-parameter sensor fusion, requiring substantial cloud infrastructure and data science staffing. This segment attracts municipal utilities with constrained engineering headcount who favor turnkey subscriptions over in-house integration.
- Advanced Monitoring:Integrated platforms combining real-time sensing with fleet-level analytics dashboards.
- Real-time Monitoring:Continuous data streams enabling immediate operational response to thermal excursions or gas anomalies.
Condition Monitoring absorbs the bulk of installed capacity; Predictive Maintenance is expanding most quickly as FERC NERC CIP compliance deadlines accelerate subscription analytics adoption.
Technology:
Deployment architecture determines whether utilities retain operational control or cede infrastructure management to vendors.
- IoT:Networked sensor gateways transmitting transformer health metrics to centralized platforms. European transmission operators under EU Green Deal mandates favor IoT architectures for retrofitting existing substations without full SCADA replacement.
- Cloud Computing:Scalable data lakes enabling cross-fleet pattern recognition and algorithmic maintenance scheduling. This technology commands premium pricing from asset managers seeking to consolidate monitoring across geographically dispersed transformer populations.
- AI-based Analytics:Pattern recognition engines interpreting gas ratios and thermal trends for failure prediction.
- Wireless Sensor Networks:Battery-powered nodes eliminating cabling costs in hard-to-access installations.
IoT platforms dominate current deployment volumes; Cloud Computing is climbing the fastest as utilities replace capital-intensive hardware purchases with recurring analytics subscriptions.
End User:
Procurement sophistication separates price-sensitive industrial buyers from regulated utilities with mandated reliability obligations.
- Utilities:Grid operators subject to FERC NERC CIP reliability standards and EU Green Deal efficiency requirements. These buyers concentrate demand for integrated platforms bundling hardware, software, and compliance reporting.
- Industrial Manufacturers:Captive power users monitoring in-plant transformers for production continuity. Oil refineries and chemical complexes in the United States prioritize real-time thermal monitoring to prevent catastrophic outages in continuous-process environments.
- Oil & Gas Companies:Midstream and downstream operators with isolated substations requiring remote monitoring capabilities.
- Renewable Energy Providers:Wind and solar farm operators managing transformer fleets with variable loading profiles.
Utilities command the largest addressable spend; Industrial Manufacturers are gaining share fastest as manufacturing reshoring expands captive substation investment.
Installation:
Site architecture determines whether monitoring systems require specialized field engineering or permit vendor-managed deployment.
- On-site:Hardware installed directly at transformer locations with local data processing. German transmission system operators favor on-site architectures for critical 380kV substations where latency constraints preclude cloud dependency.
- Remote:Sensor data transmitted to off-premises analytics platforms with minimal local infrastructure. This model appeals to rural electric cooperatives in the United States lacking specialized substation technicians for calibration and maintenance.
- Off-site:Complete monitoring function outsourced to vendor operations centers.
- Hybrid:Edge processing for immediate alarms combined with cloud analytics for fleet optimization.
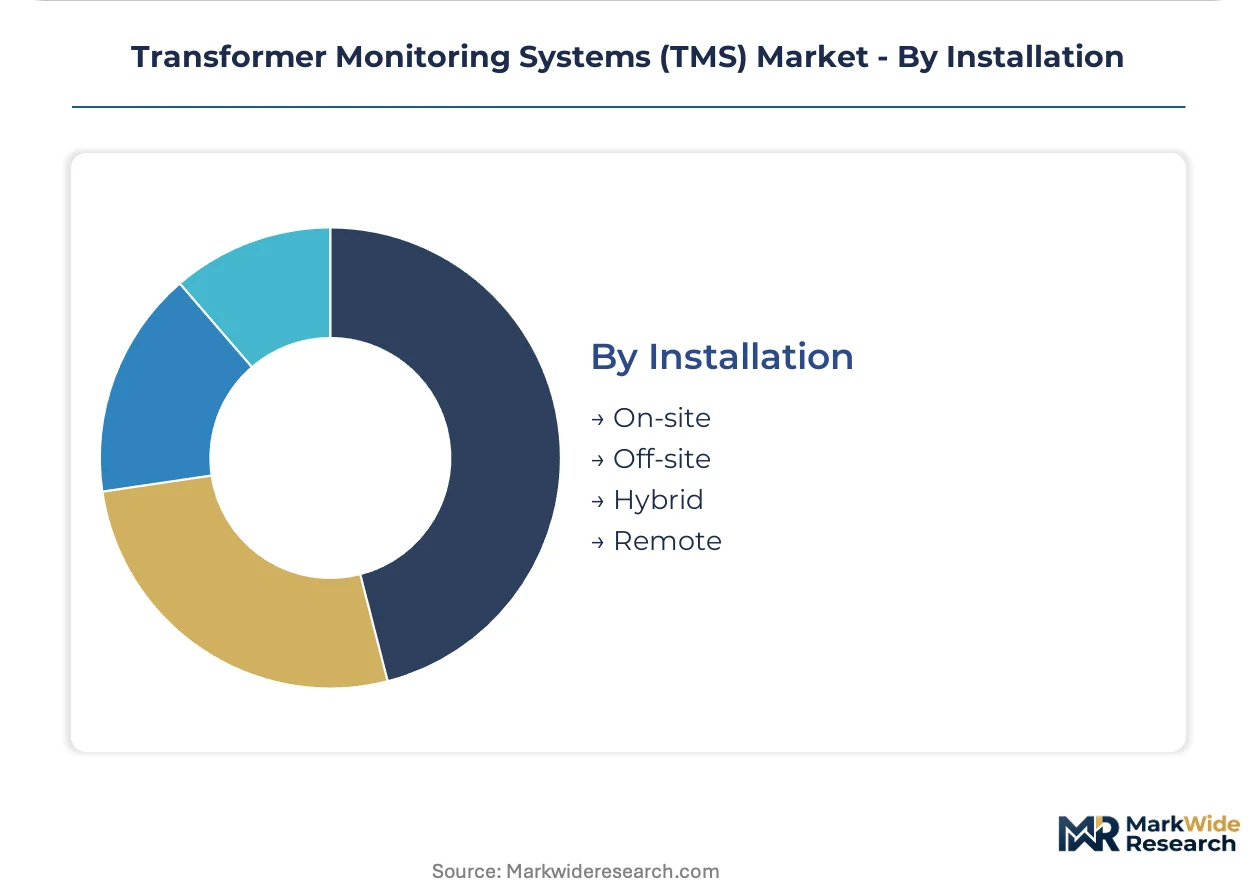
On-site configurations retain the majority of legacy deployments; Remote installations are expanding most rapidly as 5G private networks reduce connectivity barriers for distributed transformer fleets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for power infrastructure in Gujarat, Texas, and Bavaria concentrate transformer manufacturing and monitoring deployment. These zones attract vendor investment through accelerated permitting and tax incentives for grid modernization equipment.
United States
FERC NERC CIP reliability mandates drive bulk power system transformer monitoring requirements. The Federal Energy Regulatory Commission enforces mandatory standards that directly obligate utilities to deploy dissolved gas analysis and thermal monitoring capabilities. Houston hosts major utility procurement centers where grid operators consolidate fleet-wide analytics contracts.
Germany
EU Green Deal efficiency requirements and F-Gas Regulation leak-detection mandates accelerate substation retrofit programs. The country's national power regulator enforces grid codes that expand addressable demand for integrated monitoring platforms. Bavaria's industrial corridor concentrates transmission system operator investment in 380kV substation modernization.
China
Dual carbon goals and grid reliability targets under MIIT directives expand smart substation deployment. The Ministry of Industry and Information Technology mandates digital transformation of power infrastructure through GB standards compliance. Yangtze River Delta utilities pilot edge-AI thermal profiling in high-density urban transformer installations.
India
Central Electricity Authority revised grid codes mandate distribution transformer monitoring nationwide. The country's national power regulator requires real-time health metrics for critical substation assets under new reliability frameworks. Gujarat's special economic zones for power equipment attract Schneider Electric and Siemens Energy AG manufacturing partnerships.
Japan
METI strategic energy plans prioritize aging infrastructure replacement with predictive maintenance integration. The Ministry of Economy, Trade and Industry funds demonstration projects for optical fiber distributed temperature sensing in high-voltage transformers. Kansai region utilities deploy hybrid on-site/cloud architectures for earthquake-resilient substation monitoring.
Transformer Monitoring Systems (TMS) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware, software, and service layers. The vendor base organizes into three tiers: integrated platform providers bundling sensors with analytics subscriptions, component suppliers selling discrete sensor arrays, and engineering services firms specializing in installation and calibration. Two competitive moves dominate: backward integration into sensor manufacturing to capture hardware margins, and forward integration into outcome-based service contracts assuming uptime risk.
Among integrated platform providers, Schneider Electric, Siemens Energy AG, and Eaton occupy positions exemplifying distinct strategic archetypes. Schneider Electric anchors the multinational conglomerate model with IoT platform breadth. Siemens Energy AG represents the energy-focused spin-off structure concentrating predictive analytics capabilities. Eaton exemplifies channel-intensive positioning through industrial distribution control. These three entities collectively illustrate how vendor selection criteria vary by utility procurement sophistication and compliance burden.
| Leading Market Players |
|---|
| Schneider Electric |
| Eaton |
| GE Vernova |
| Mistras Group |
| Qualitrol |
| Siemens Energy AG |
| ABB |
| Doble Engineering Company |
| Hitachi Energy Ltd |
| Others |
Value Network & Pricing Analysis
Backward integration into sensor manufacturing anchors both supply security and pricing power for integrated platform providers serving FERC-regulated utilities. Captive production of dissolved gas analysis modules and thermal sensor arrays insulates vendors from copper and neodymium price volatility while supporting premium positioning against component-only competitors.
Pricing Analysis
Lead-time-driven pricing separates urgent deployment premiums from standard procurement cycles in utility transformer monitoring. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with IEC 60599-validated systems commanding substantial premiums over uncertified alternatives. Cost compression in hardware tiers is intensifying because rare earth magnet volatility squeezes component supplier margins. Municipal utilities exhibit highest price sensitivity due to constrained capital budgets, while transmission system operators prioritize reliability over unit cost.
Supply Chain Analysis
Direct-to-utility channels handle hyperscale procurement from transmission system operators, while electrical distributors serve fragmented industrial buyer demand. Manufacturing concentrates in Germany, China, and the United States, with sensor assembly drawing from Taiwanese semiconductor foundries and Japanese precision component suppliers. Supply chain risk centers on single-source vulnerability for neodymium magnet procurement from Chinese rare earth processors. Distribution runs through authorized service partners for installation and calibration of dissolved gas analysis systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Transformer Monitoring Systems market sits in a technology-transition phase as cloud-based predictive analytics displace time-based maintenance schedules. Edge-AI thermal profiling and fiber-optic distributed sensing are replacing conventional thermocouple arrays in high-value substation deployments.
For Market Incumbents: Deepen backward integration into optical fiber sensor manufacturing to capture margins from European F-Gas Regulation retrofit demand. Fortify platform interoperability certification against IEC 61850 gateway fragmentation that threatens multi-decade deployment architectures. Prioritize captive supply of chromatography-grade sensor membranes to offset field engineering scarcity in dissolved gas analysis installation.
For New Entrants and Emerging Players: Rural electric cooperatives in the United States represent an underserved buyer archetype lacking specialized substation technicians for traditional on-site systems. Target remote monitoring subscriptions with minimal local infrastructure requirements, leveraging 5G private network coverage expansion. Pursue outcome-based service contracts assuming uptime risk to differentiate from hardware-only incumbents.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform consolidation plays as utilities consolidate procurement around fleet-wide analytics subscriptions. Five-to-ten year viability favors vendors with demonstrated FERC NERC CIP compliance integration and recurring revenue concentration above hardware transactional exposure. Watch for inflection when India's Central Electricity Authority enforcement accelerates beyond pilot distribution transformer monitoring mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captive production of dissolved gas analysis modules insulates margins from rare earth volatility. |
| Fleet-Wide Analytics Platform Launch | Recurring subscription revenue displaces transactional hardware sales among municipal utilities. |
| IEC 61850 Interoperability Certification | Gateway standardization reduces integration costs for utilities with legacy SCADA networks. |
| Edge-AI Thermal Profiling Development | On-device inference enables real-time response without cloud dependency for security-sensitive operators. |
| Outcome-Based Service Contract Expansion | Uptime risk assumption creates recurring revenue pools and deepens utility vendor relationships. |
Research Methodology
Multi-period observation of utility capital expenditure patterns and substation modernization timelines anchored the trend analysis, supplemented by interviews with utility planning officers, grid operations directors, EPC contractors, and transformer asset managers. Secondary validation drew from FERC filings, EIA infrastructure databases, EU Green Deal implementation reports, and IEC standard development documentation. Bottom-up project pipeline analysis triangulated against top-down regulatory mandate impact assessment.
Segment-weighting across product type, technology architecture, end-user category, and installation model shaped volume and value projections throughout the forecast period. CAGRs derived from regression analysis of historical utility procurement cycles against regulatory compliance deadline clustering. Forecast inputs incorporated transformer fleet age demographics, FERC NERC CIP enforcement trajectory, and EU F-Gas Regulation retrofit obligation schedules.
Revisions become necessary when rare earth supply disruptions, accelerated grid code enforcement, or breakthrough sensor technology commercialization materialize outside modeled scenarios. Forecasts reflect documented assumptions regarding utility capital availability and regulatory implementation pacing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Air Cooled Transformer Market
Transformers
Europe Oil Filled Distribution Transformer Market
Transformers
India Transformer Market
Transformers
Transformer Steel Market
Transformers
Single Phase Power Transformer Market
Transformers
China Transformer Market
Transformers
United States Power Transformer Market
Transformers
Traction Transformer Market
Transformers
High Voltage (35-550 KV) Power Transformer Market
Transformers
Renewable Energy Transformer Market
Transformers
Oil Filled Transformer Market
Transformers
Neon Transformer Market
Transformers
Uninhibited Transformer Oil Market
Transformers
EHV & UHV (above 330KV) Power Transformers Market
Transformers
Asia Pacific Smart Transformers Market
Transformers
Europe Transformer Market