
 Transformer Bobbin Market | 2026-2036
Transformer Bobbin Market Size, Share, and Industry Trends Forecast 2026-2036
Transformer Bobbin Market Analytics
Asset-light contract manufacturing and third-party coil-winding outsourcing is reconfiguring competitive dynamics in transformer bobbin supply. TDK Corporation leverages captive ferrite and ceramic material streams to anchor high-reliability bobbin production for automotive-grade inductors. Würth Elektronik GmbH & Co. KG sustains European manufacturing scale through vertical integration into stamping and overmolding operations. Sumida Corporation specializes in ultra-fine wire-wound bobbins for compact switch-mode power supplies, occupying a defensible niche in consumer electronics.
A transformer bobbin is a precisely engineered spool or frame, typically injection-molded from thermoplastic resins such as polybutylene terephthalate or liquid crystal polymer, that provides structural support for copper windings and maintains critical creepage and clearance distances in electromagnetic assemblies. The component insulates adjacent coil layers, defines magnetic path geometry, and secures terminal pins for circuit board attachment in power conversion equipment. Plastic and nylon material categories dominate unit volume due to cost-efficient injection molding and adequate thermal performance up to 130°C, while polycarbonate grades capture premium positioning in applications requiring higher dielectric strength and dimensional stability under humidity cycling. Multi-layer and stackable design configurations represent the fastest-expanding segment as miniaturization trends in server power supplies and on-board chargers force higher winding density within constrained footprints.
RoHS and REACH frameworks in Europe restrict halogenated flame retardants and specific phthalates in bobbin substrates, compelling reformulation of legacy bakelite and standard nylon grades. IEC 61558 and UL 5085 safety standards govern insulation systems, creepage distances, and thermal endurance testing, directly shaping product qualification timelines and market access for regional suppliers. Stakeholders must monitor evolving efficiency tiers in DOE and EU Ecodesign transformer regulations, as these will dictate bobbin thermal class requirements and material substitution pathways.
Market Dynamics
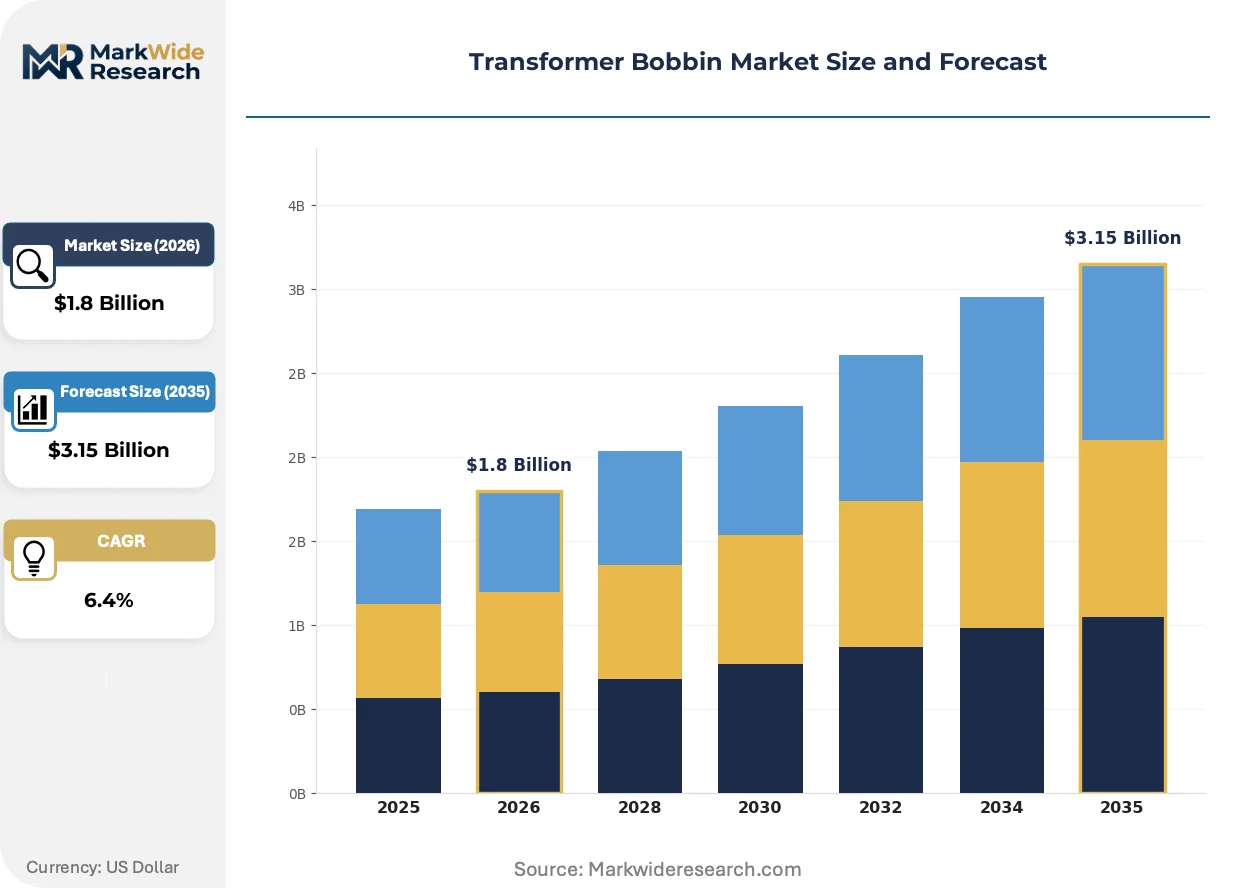
Power grid modernization across emerging economies is expanding procurement of medium and high-capacity transformer bobbins while IEC 61558 safety standards and RoHS material restrictions push manufacturers toward halogen-free thermoplastic compounds.
Growth Catalysts
- Grid Modernization Mandates:National power utilities in India and Brazil are replacing aging distribution transformers, creating sustained demand for IEC-rated bobbins in medium-voltage applications.
- REACH Compliance Deadlines:European ECHA restrictions on halogenated flame retardants are accelerating reformulation of legacy nylon grades toward phosphorous-based alternatives.
- Electric Vehicle Manufacturing:On-board charger production in China and Germany requires precision-wound magnetic components with enhanced thermal endurance.
Market Restraints
- Engineering Resin Volatility:Liquid crystal polymer and high-heat PBT pricing fluctuates with petrochemical feedstock cycles, compressing margin stability for molders.
- Concentrated Ferrite Supply:Sintered ferrite core manufacturing concentrates in East Asian facilities, exposing bobbin assemblers to single-source ceramic magnet risks.
- Copper Substitution Pressure:Aluminum winding wire adoption in cost-sensitive distribution transformers threatens premium bobbin specifications designed for copper conductivity.
Strategic Opportunities
- Renewable Inverter Integration:Solar and wind power conversion equipment in Australia and Saudi Arabia requires high-frequency bobbins for compact DC-AC stages.
- EU Ecodesign Tier Expansion:Upcoming efficiency regulations for distribution transformers will mandate Class F and H insulation systems, favoring advanced thermoplastic substrates.
- Additive Manufacturing Convergence:Selective laser sintering of high-temperature polymers enables rapid prototyping of complex multi-chamber bobbin geometries for custom magnetics.
Industry Challenges
- Precision Winding Technician Scarcity:Automated coil winding programming and micro-wire tension control require specialized training that outpaces vocational pipeline output.
- UL/IEC Dual Certification Burden:North American and European safety agency testing cycles add 14-18 weeks to new product introduction timelines.
- Legacy Tooling Amortization:Existing injection molds for standard nylon grades carry sunk costs that delay capital redeployment into halogen-free compound processing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transformer Bobbin Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Nylon, Polycarbonate, Bakelite Design Configuration: Single Layer, Multi-Layer, Stackable, Integrated Application Type: Power Transformers, Audio Transformers, Isolation Transformers, Instrument Transformers Capacity: Low Power, Medium Power, High Power, Others |
| Companies Covered | Coilcraft, Inc., Würth Elektronik GmbH & Co. KG, TDK Corporation, Schaffner Holding AG, Eaton Corporation, Sumida Corporation, Vishay Intertechnology, Inc., Laird PLC, Murata Manufacturing Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transformer Bobbin Market Evolving Landscape
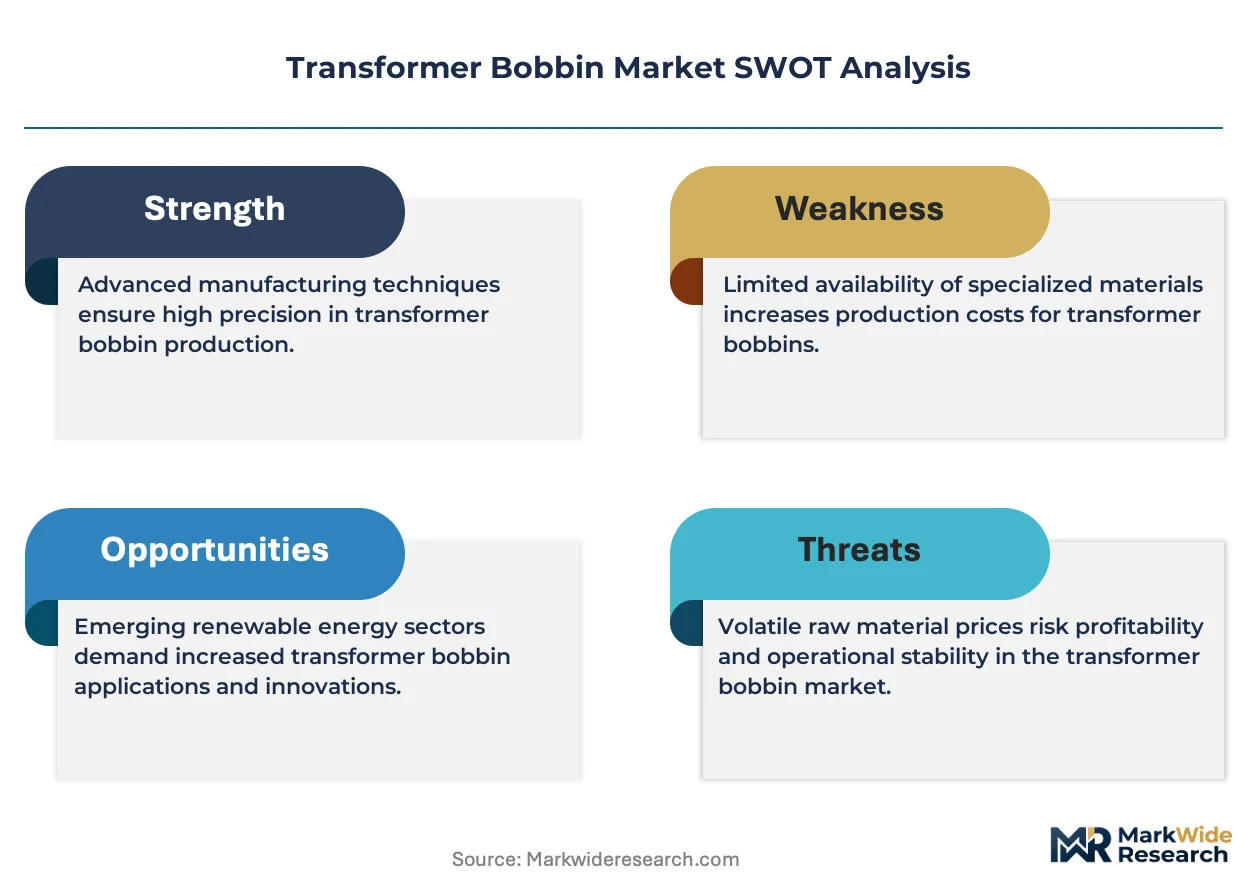
Material science advances and regulatory tightening are compressing product lifecycles while reshaping competitive advantage around thermal performance credentials rather than unit cost alone.
High-heat liquid crystal polymer compounds with glass fiber reinforcement are rendering obsolete standard PBT bobbins in server power supply applications. Data center operators in Virginia and Frankfurt now specify 155°C thermal index ratings for magnetic components. This material transition is compressing qualification timelines and favoring compounders with captive polymerization capabilities.
REACH Annex XVII restrictions on short-chain chlorinated paraffins are forcing reformulation of legacy flame-retardant nylon 6/6 grades across European supply chains. Compounders must validate alternative phosphinate systems through glow-wire and comparative tracking index testing. Automotive inductor manufacturers face the steepest compliance burden due to VW 60306 and OEM material approval requirements.
Contract coil-winding services are consolidating procurement decisions among fewer magnetics specialists with integrated ferrite sourcing and automated winding capacity. Appliance OEMs in Mexico and Turkey now outsource entire magnetic subassembly production rather than managing bobbin and core suppliers separately. This vertical consolidation favors mid-tier bobbin molders with statistical process control certification and regional logistics hubs.
Transformer Bobbin Market Segmentation
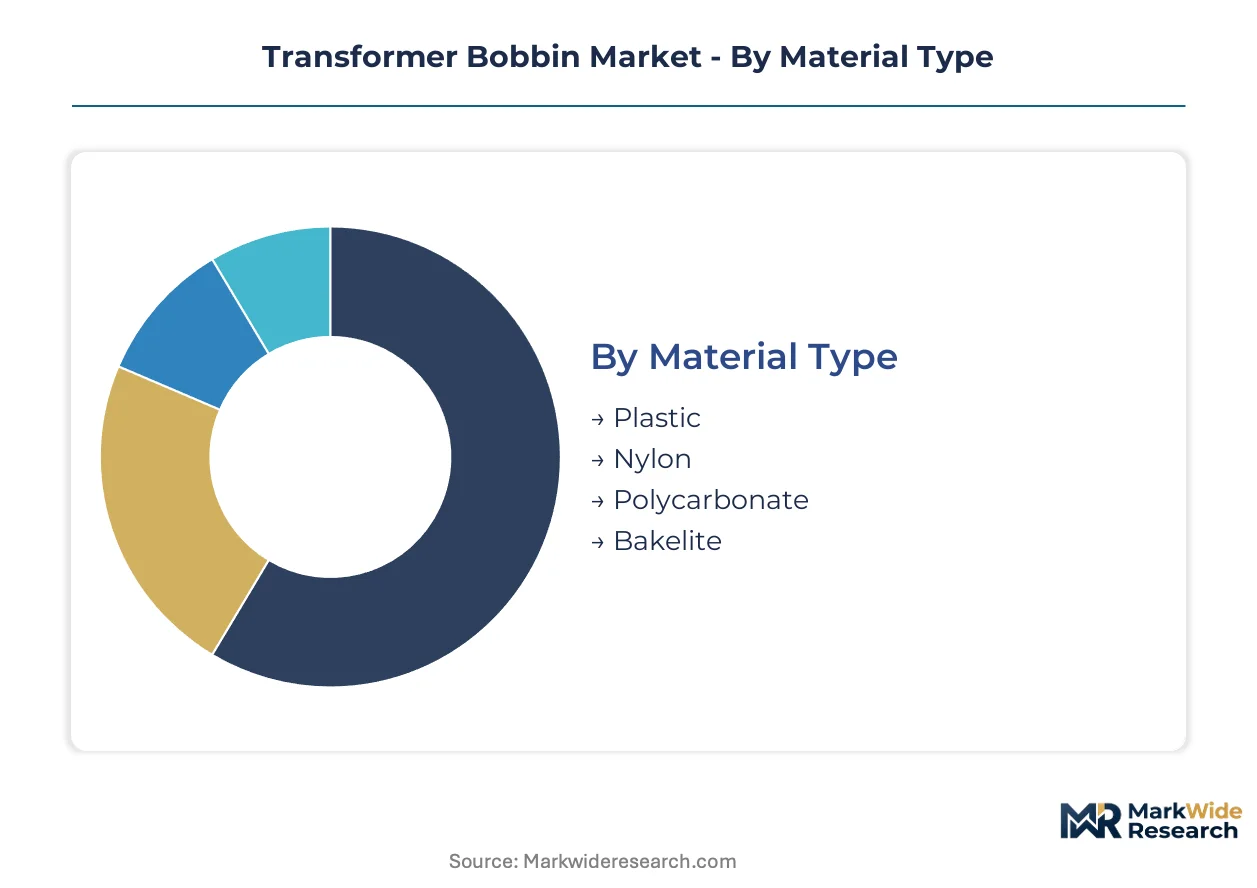
Transformer bobbin segmentation reveals how material chemistry, winding geometry, and thermal class requirements fragment procurement decisions across power electronics value chains. Manufacturers configure product portfolios around insulation system ratings and end-use duty cycles rather than commodity resin grades alone.
Material Type:
Cost tier positioning separates commodity thermoplastics from engineered compounds with certified thermal endurance and halogen-free flame retardancy.
- Plastic:Polybutylene terephthalate dominates unit economics through cost-efficient injection molding cycles and adequate 130°C thermal performance for standard distribution transformers. Appliance manufacturers in China specify plastic bobbins for volume-driven consumer power supplies where material cost outweighs thermal margin requirements.
- Nylon:Polyamide 6/6 grades offer superior mechanical toughness and abrasion resistance for automated high-speed winding operations. REACH Annex XVII restrictions on halogenated flame retardants are accelerating phosphinate-based reformulations across European supply chains.
- Polycarbonate:Captures premium positioning through higher dielectric strength and dimensional stability under humidity cycling in outdoor instrument transformers.
- Bakelite:Phenolic resin legacy formulations persist in cost-sensitive regions despite RoHS-driven phase-out pressure in EU and North American markets.
Plastic holds installed capacity. Nylon is rotating up the share rankings.
Design Configuration:
Winding density requirements and magnetic path geometry dictate structural complexity in bobbin architecture.
- Multi-Layer:Segmented winding chambers enable higher turns-per-cubic-centimeter in compact switch-mode power supplies for server farms and electric vehicle on-board chargers. Data center operators in Virginia and Frankfurt now specify multi-layer bobbins to achieve 155°C thermal index ratings in high-frequency magnetics.
- Stackable:Modular lamination-style assemblies allow flexible core window area scaling without custom tooling investments. Solar inverter manufacturers in Australia and Saudi Arabia deploy stackable configurations for rapid DC-AC stage prototyping.
- Single Layer:Simplest structural form for low-voltage isolation transformers with minimal creepage distance requirements.
- Integrated:Combines ferrite core seating, terminal block, and mounting flange in single molded assemblies for automated pick-and-place assembly.
Single Layer holds installed capacity. Multi-Layer is expanding most quickly.
Application Type:
End-use electrical stress profiles and agency certification requirements segment demand across transformer categories.
- Power Transformers:Medium and high-capacity bobbins for grid infrastructure face IEC 61558 creepage distance mandates and Class F insulation system requirements. National utilities in India and Brazil are replacing aging distribution transformers, creating sustained procurement for IEC-rated bobbins.
- Isolation Transformers:Medical-grade and industrial safety isolation applications require reinforced insulation systems with documented partial discharge performance.
- Audio Transformers:Specialized low-capacitance winding configurations for high-fidelity signal path magnetics in professional audio equipment.
- Instrument Transformers:Precision ratio and phase accuracy requirements for metering and protection relay applications in substation automation.
Power Transformers holds installed capacity. Isolation Transformers is climbing the fastest.
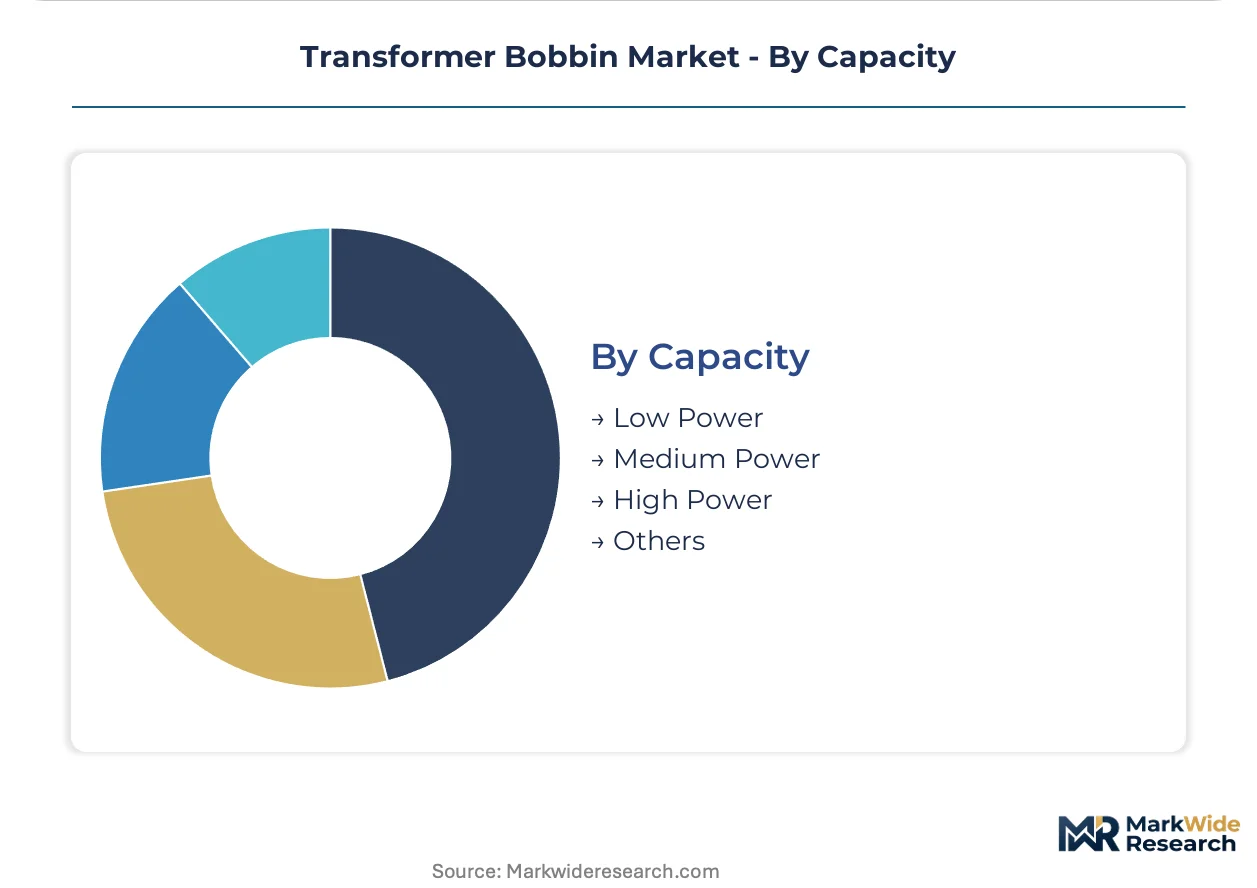
Capacity:
Thermal class and conductor cross-section scale separate low-wattage signal magnetics from utility-scale distribution hardware.
- Medium Power:100VA to 10kVA range captures the broadest addressable market across industrial control transformers and commercial HVAC magnetics. IEC-rated medium power bobbins with Class H insulation systems are gaining preference in EU Ecodesign efficiency tier compliance.
- High Power:Above 10kVA ratings for substation and renewable inverter applications require ceramic-filled thermoplastic compounds with 180°C continuous operating capability.
- Low Power:Sub-100VA signal and small-signal isolation transformers for consumer electronics and telecommunications.
- Others:Specialty pulsed power and resonant converter applications with non-standard duty cycle requirements.
Medium Power holds installed capacity. High Power is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial equipment manufacturers and power utility procurement offices concentrate demand across five manufacturing economies where grid infrastructure spending and electronics assembly intersect with evolving material compliance regimes.
China
Electric vehicle on-board charger production and domestic appliance manufacturing drive precision-wound magnetic component consumption. MIIT efficiency standards for power electronics tighten thermal class requirements for magnetic assemblies. Shenzhen and Dongguan clusters host integrated ferrite core and bobbin molding operations serving EV supply chains.
Germany
Automotive inductor manufacturers and industrial drive suppliers source high-reliability bobbins for traction inverters and servo motors. REACH Annex XVII restrictions on halogenated flame retardants accelerate phosphinate-based nylon reformulations. Baden-Württemberg's precision component corridor maintains captive stamping and overmolding capacity for Tier-1 automotive magnetics.
United States
Data center operators in Virginia and server manufacturers specify 155°C thermal index ratings for high-frequency power supply magnetics. DOE efficiency tiers for distribution transformers influence insulation system procurement specifications. Pacific Northwest utility districts deploy medium-voltage bobbins in grid modernization programs replacing aging distribution infrastructure.
India
National power utilities under CEA mandates replace aging distribution transformers, creating sustained demand for IEC-rated medium-capacity bobbins. BIS certification requirements for electrical insulation materials shape supplier qualification protocols. Gujarat and Maharashtra industrial corridors expand domestic molding capacity for appliance and transformer OEMs.
Japan
Compact switch-mode power supply manufacturers and telecommunications equipment makers demand ultra-fine wire-wound bobbins for miniaturized magnetics. METI energy efficiency standards for industrial equipment elevate thermal performance requirements. Nagoya and Osaka manufacturing basins concentrate precision coil-winding automation and ceramic-filled thermoplastic compound expertise.
Transformer Bobbin Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Integrated magnetics suppliers with captive ferrite sourcing and automated winding capacity dominate high-reliability segments, while regional molders with statistical process control certification capture appliance and industrial procurement. Strategic moves concentrate on backward integration into ceramic magnet supply and geographic expansion through contract manufacturing partnerships in Mexico and Southeast Asia.
Within the integrated materials tier, TDK Corporation exemplifies compounders with captive polymerization capabilities, while Würth Elektronik GmbH & Co. KG represents European fabricators maintaining in-house stamping operations. Sumida Corporation occupies a specialist position in ultra-fine wire-wound configurations for compact power electronics.
| Leading Market Players |
|---|
| Coilcraft, Inc. |
| Würth Elektronik GmbH & Co. KG |
| TDK Corporation |
| Schaffner Holding AG |
| Eaton Corporation |
| Sumida Corporation |
| Vishay Intertechnology, Inc. |
| Laird PLC |
| Murata Manufacturing Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Sintered ferrite core manufacturing concentrates in East Asian facilities, anchoring margin capture with compounders possessing captive ceramic magnet supply while pressuring independent bobbin molders into price-taker positions. This upstream consolidation cascades downstream, where procurement power aggregates among integrated magnetics suppliers with automated winding capacity.
Pricing Analysis
Certification level creates the primary spread across bobbin procurement tiers. Three-tier pricing structure separates UL/IEC dual-certified premium grades from single-agency standard products and uncertified economy alternatives. Price differentiation rests on thermal class rating and halogen-free compound validation, with Class H insulation systems commanding substantial premiums over Class B equivalents. Pricing pressure stems from aluminum winding wire substitution in cost-sensitive distribution transformers, compressing margins for copper-optimized bobbin specifications. Appliance OEMs in Mexico and Turkey exhibit highest price sensitivity, while automotive inductor manufacturers prioritize thermal endurance over unit cost.
Supply Chain Analysis
Tariff exposure between China and North American markets dominates supply chain risk calculations for transformer bobbin procurement. Manufacturing concentrates in China, Germany, and Japan, with Dongguan and Shenzhen clusters hosting integrated ferrite core and bobbin molding operations. Raw material dependencies center on liquid crystal polymer feedstocks, phosphinate-based flame retardants, and sintered ferrite ceramics. Single-source vulnerability persists in ceramic-filled thermoplastic compound supply, where Japanese and German compounders control specialized formulations. Distribution runs through contract coil-winding services consolidating procurement among integrated magnetics specialists with regional logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as aluminum winding wire adoption threatens copper-optimized bobbin specifications in cost-sensitive distribution transformer segments. The imperative is to anchor value in thermal performance credentials that aluminum alternatives cannot replicate.
For Market Incumbents: Build captive ferrite sourcing moats through backward integration into ceramic magnet supply or exclusive offtake agreements with East Asian sintering facilities. Invest in Class H and Class F insulation system certification ahead of EU Ecodesign tier expansion, creating regulatory compliance barriers that aluminum-wound competitors cannot easily surmount. Prioritize automated coil-winding capacity expansion in Mexico and Southeast Asia to match contract manufacturing consolidation trends among appliance OEMs.
For New Entrants and Emerging Players: Establish a beachhead in renewable inverter integration for solar and wind power conversion equipment in Australia and Saudi Arabia, where high-frequency bobbin demand outpaces established supply. Target stackable design configurations for rapid DC-AC stage prototyping, exploiting modular lamination-style assemblies that bypass custom tooling investments required by integrated competitors. Pursue phosphinate-based nylon reformulation partnerships with European compounders navigating REACH Annex XVII restrictions.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier molders possessing statistical process control certification but lacking captive ferrite supply. Long-term viability favors compounders with in-house polymerization capabilities and automated winding integration. Monitor EU Ecodesign efficiency tier implementation as inflection indicator for Class F and H insulation system demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferrite Supply | Captive ceramic magnet sourcing insulates against East Asian single-source concentration risks. |
| Halogen-Free Compound Reformulation | Phosphinate-based nylon validation secures REACH Annex XVII compliance for European market access. |
| Automated Coil-Winding Capacity Expansion | Statistical process control certification matches contract manufacturing consolidation among appliance OEMs. |
| Class H Insulation System Certification | EU Ecodesign tier expansion mandates elevated thermal class procurement specifications. |
| Selective Laser Sintering Prototyping | Additive manufacturing convergence enables rapid multi-chamber bobbin geometry validation for custom magnetics. |
Research Methodology
A spread of perspectives from plant managers at injection molding facilities, procurement leads at transformer OEMs, technical R&D directors at thermoplastic compounders, and channel partners in magnetics distribution converged on the working assumptions. Primary fieldwork combined with secondary validation against IEC 61558 safety standard documentation, RoHS and REACH regulatory filings, EIA electricity infrastructure spending data, and customs trade records for ferrite ceramic imports. Bottom-up segment sizing triangulated against top-down power electronics equipment production estimates.
Demand-supply balance modeling anchored volume projections, with segmentation across material type, design configuration, application category, and capacity tier. The analytical framework incorporated thermal class substitution dynamics, regional regulatory compliance timelines, and contract manufacturing consolidation patterns across the projection horizon. CAGRs derived from elasticity-adjusted equipment production forecasts and material intensity coefficients specific to switch-mode power supply and electric vehicle charger applications.
Sensitivities concentrate around engineering resin price volatility, REACH restriction expansion scope, and aluminum winding wire substitution rates in distribution transformers. Forecasts reflect documented assumptions regarding grid modernization spending trajectories and electric vehicle production scaling. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
India Power Transformer Market
Transformers
Transformer Monitoring Systems (TMS) Market
Transformers
Air Cooled Transformer Market
Transformers
Middle-East Smart Transformer Market
Transformers
Asia-Pacific Power Transformer (Below 100 MVA) Market
Transformers
High Voltage (35-550 KV) Power Transformer Market
Transformers
US Oil Filled Distribution Transformer Market
Transformers
Global Large Power Transformers Market
Transformers
North America Oil Filled Transformer Market
Transformers
Middle East and Africa Transformer Market
Transformers
Oil Filled Transformer Market
Transformers
India Transformer Market
Transformers
Distribution Transformer Market
Transformers
Locomotive Traction Transformer Market
Transformers
Europe Smart Transformers Market
Transformers
Europe Distribution Transformer Market