
 Power Transformer Market | 2026-2036
Power Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Power Transformer Market Analysis
Market Context
Software-defined transformer monitoring and predictive maintenance subscriptions is realigning how OEMs capture lifetime value from utility customers. Siemens Energy leverages its digital twin platform to extend service contracts across installed European and North American fleets. Hitachi Energy anchors its competitiveness in grid integration solutions for offshore wind interconnectors. General Electric differentiates through advanced winding insulation systems rated for higher thermal classes.
Technical Definition and Structural Segments
A power transformer is a static electromagnetic device that transfers electrical energy between circuits through mutual induction, typically operating at frequencies of 50 or 60 Hz with voltage ratings from 60 kV to 1,100 kV for grid-scale applications. Its primary industrial purpose is to step up generation voltage for efficient long-distance transmission and step down for safe distribution to end users. Step-up transformers dominate margin pools in ultra-high voltage projects linking remote renewable generation to load centers, while renewable energy application demand outpaces traditional transmission segments as offshore wind and solar parks require specialized converter-duty units. The utilities end-user segment sustains the largest volume base, though industrial captive power installations are gaining traction in energy-intensive manufacturing clusters.
Regulatory Frame and Outlook
The U.S. Department of Energy enforces minimum efficiency standards under 10 CFR 431, while the EU Ecodesign Directive and F-Gas Regulation constrain dielectric fluid choices and loss requirements for transformers placed on the European market. IEEE C57 and IEC 60076 standards govern insulation coordination, short-circuit withstand, and load noise specifications that determine product qualification for cross-border procurement tenders. Stakeholders must monitor how carbon-border adjustment mechanisms and domestic content incentives reshape sourcing strategies for core electrical steel and copper winding materials.
Market Dynamics
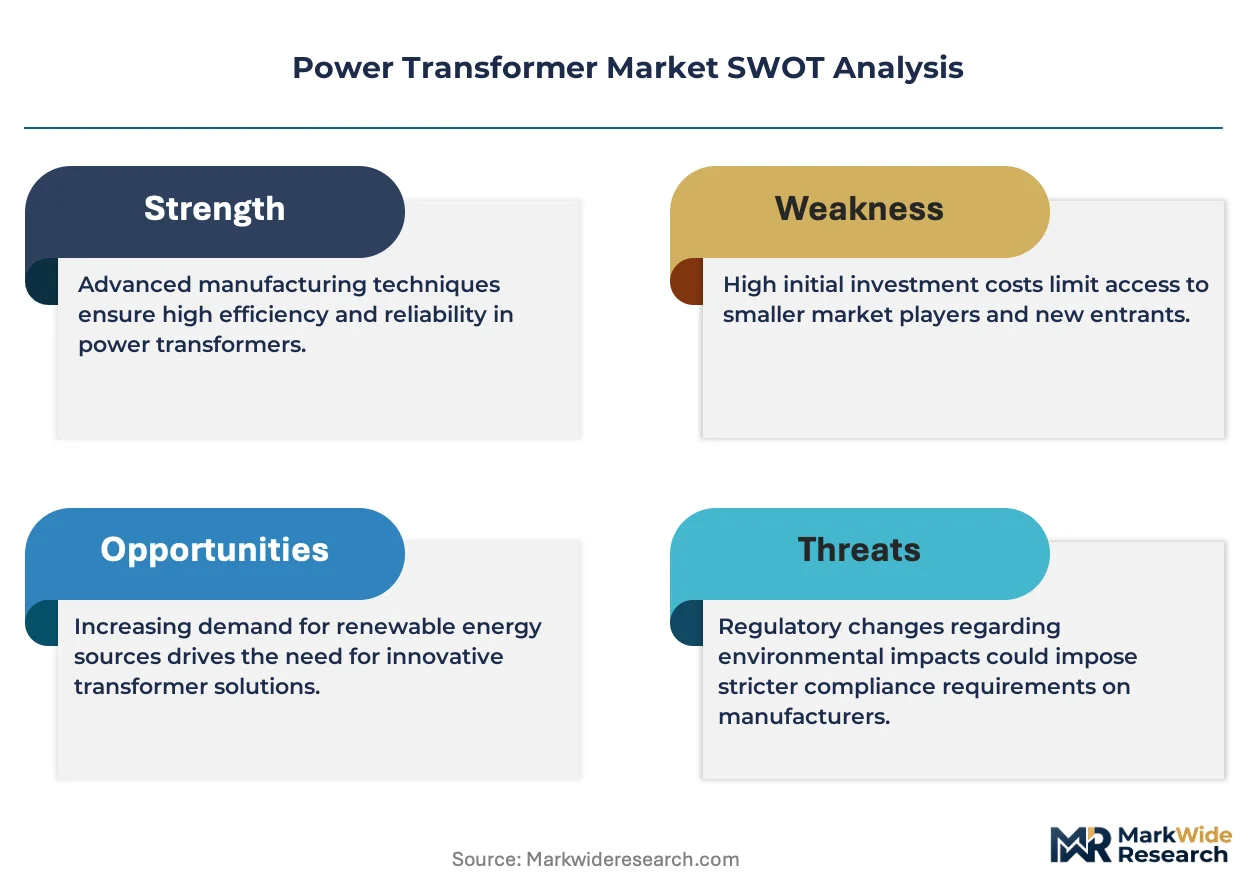
The power transformer market is being restructured by ultra-high voltage transmission buildouts in China and the electrification of industrial clusters across multiple continents, which together are compressing lead times for large-unit manufacturing and rewiring procurement priorities toward grid stability assets.
Growth Catalysts
- Grid Interconnection Mandates:FERC Order 2023 in the United States is forcing utilities to accelerate transmission capacity additions, directly expanding procurement volumes for step-up transformers linking renewable generation to bulk power networks.
- Offshore Wind Converter Stations:Specialized converter-duty transformer demand is concentrating around North Sea lease rounds and East Asian floating wind pilots, requiring liquid-immersed units with enhanced harmonic withstand capability.
- Electrical Steel Capacity Expansion:Government-backed domestic content incentives in India and the United States are accelerating localized grain-oriented steel production, reducing import dependency for core lamination materials.
Market Restraints
- Copper and CRGO Steel Volatility:Spot price swings for copper cathode and cold-rolled grain-oriented electrical steel directly compress transformer OEM margins and destabilize fixed-price tender submissions.
- Specialized Winding Labor Scarcity:The concentration of skilled coil winding technicians in Central Europe and Japan creates bottleneck risk for large power transformer delivery schedules.
- SF6 Phase-Down Constraints:The EU F-Gas Regulation is restricting gas-insulated transformer deployments, forcing design pivots toward liquid-immersed alternatives with longer manufacturing cycles.
Strategic Opportunities
- Digital Twin Integration:Predictive maintenance platforms combining dissolved gas analysis with thermal imaging are opening subscription revenue streams for transformer OEMs serving European utility fleets.
- Industrial Captive Power:Data center and semiconductor fabrication clusters in Arizona and Bavaria are procuring dedicated step-down units with redundant cooling systems, bypassing traditional utility procurement channels.
- Retrofit and Uprate Services:Aging transformer assets in the United Kingdom and Germany are creating demand for winding replacement and thermal class upgrades without full unit replacement.
Industry Challenges
- IEC 60076-7 Thermal Modeling Certification:Extended validation timelines for dynamic loading algorithms are delaying product qualification for utility tenders requiring 30-year asset life guarantees.
- Multi-Site Manufacturing Coordination:Disaggregated production of active parts, tanks, and bushings across Poland, Mexico, and Vietnam is complicating quality assurance and final test scheduling.
- Legacy SCADA Integration:New digital monitoring systems must interface with decades-old utility control architectures, requiring custom protocol gateways and extended commissioning periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Transformer Market |
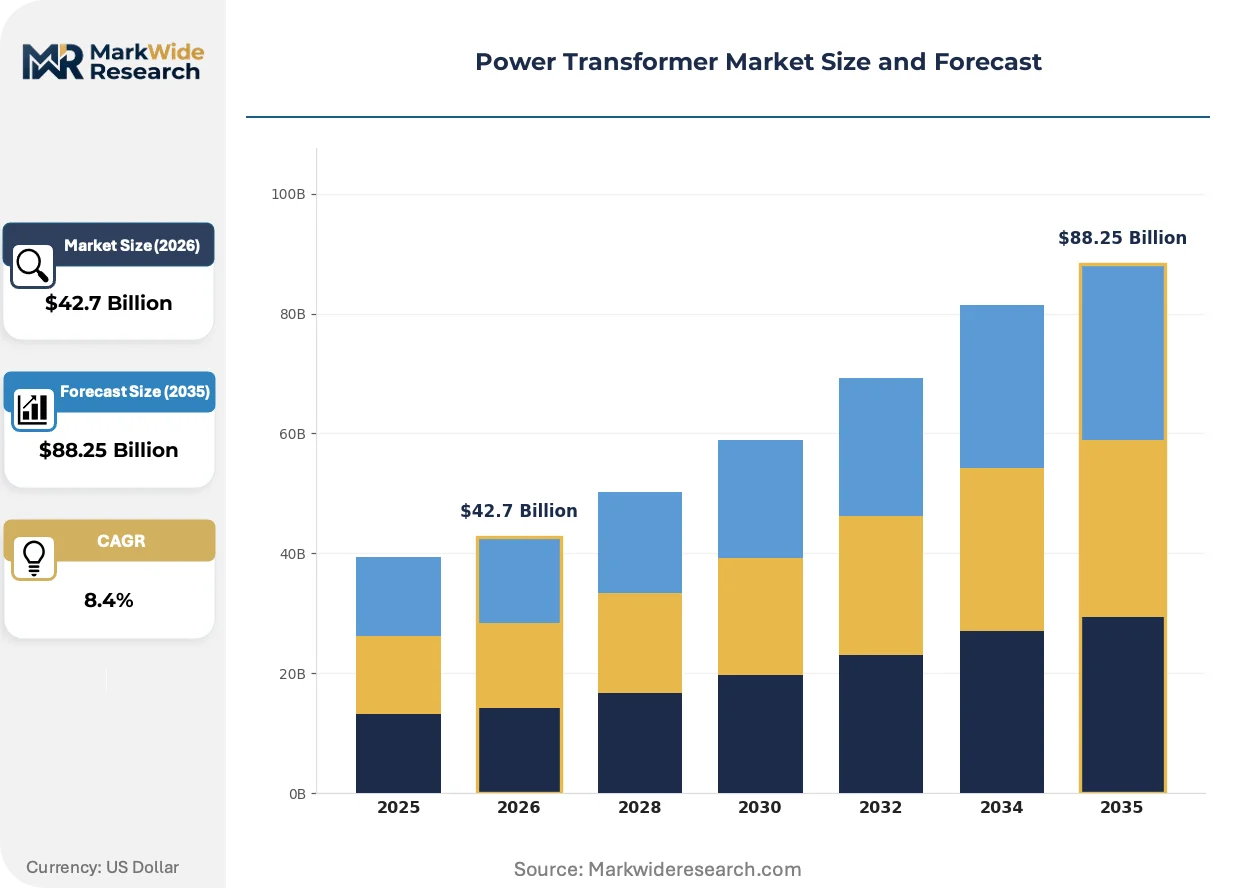
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $88.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
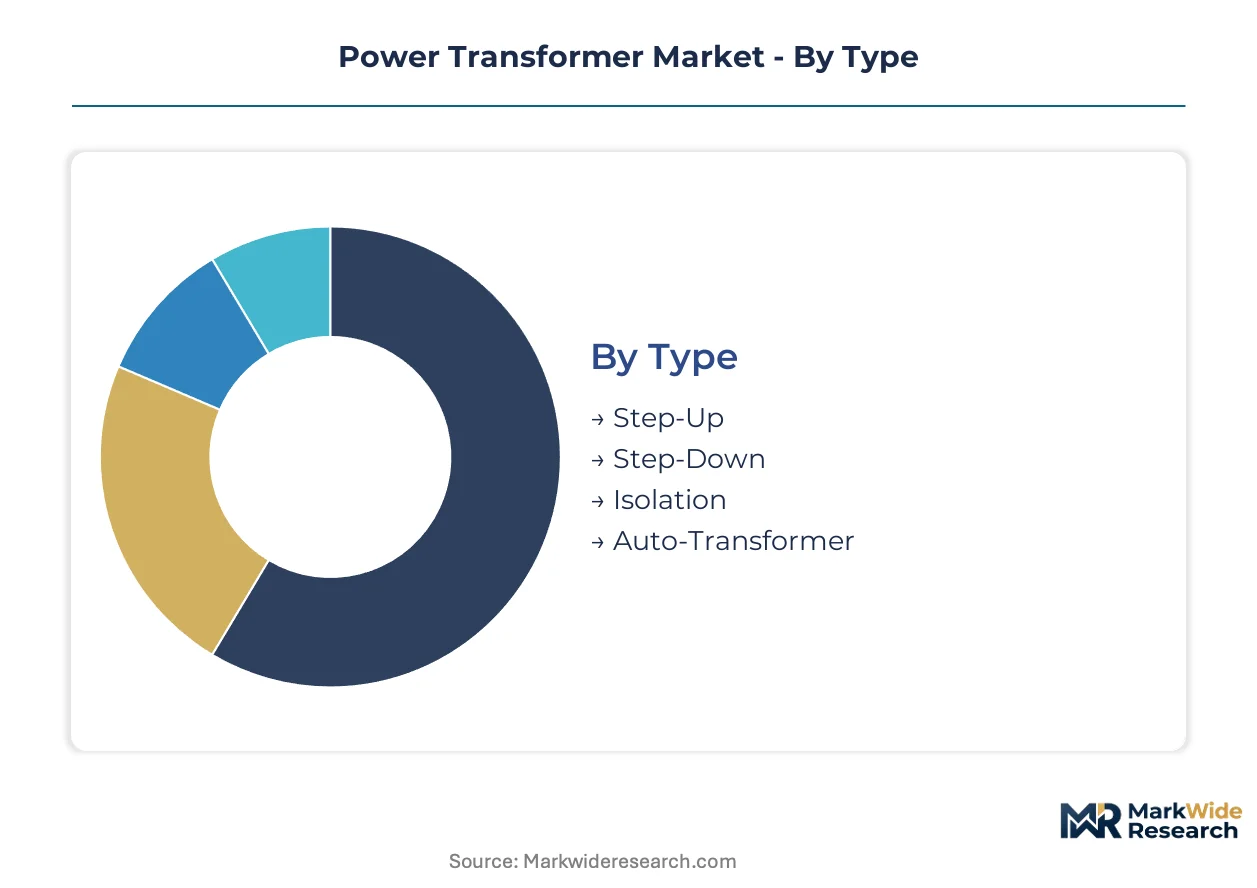
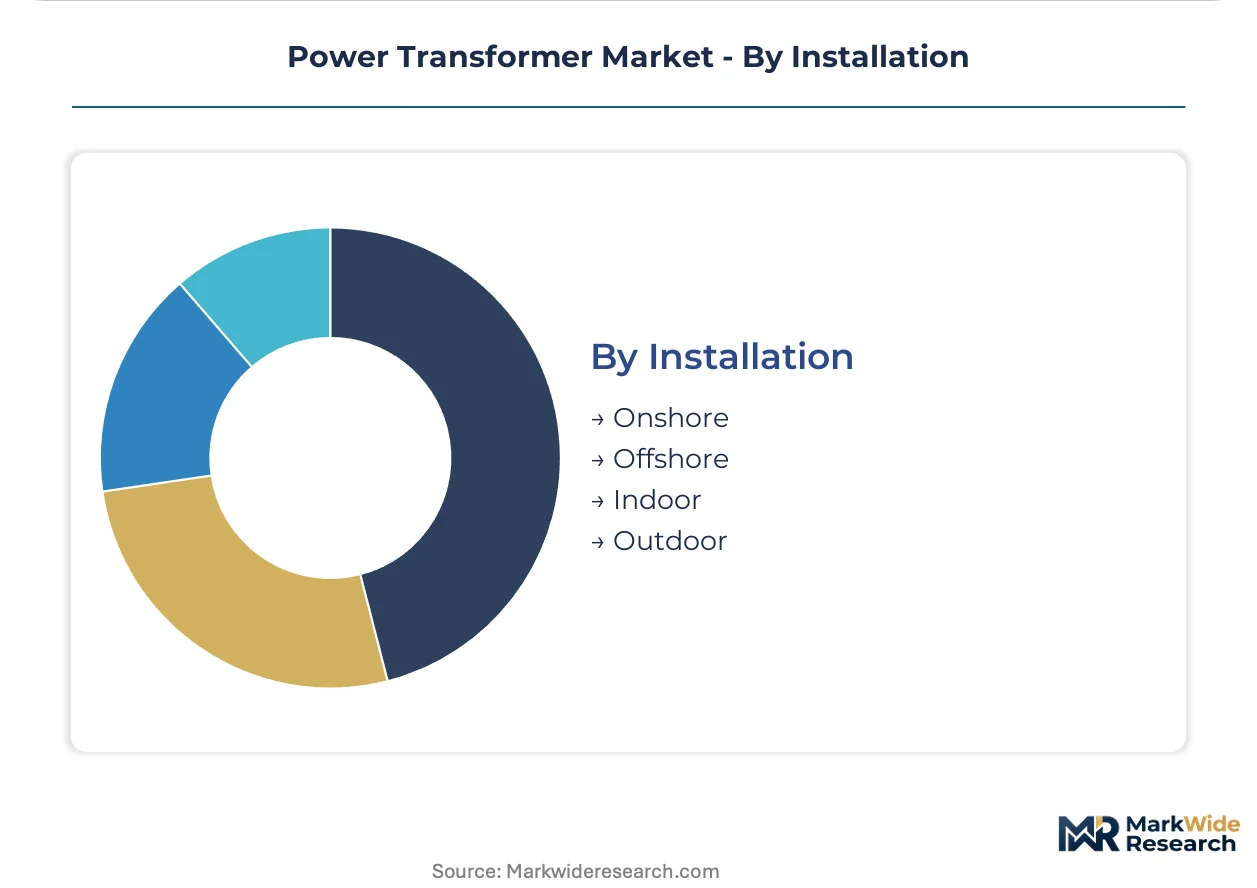
| Segmentation | Type: Step-Up, Step-Down, Isolation, Auto-Transformer Application: Power Generation, Transmission, Distribution, Renewable Energy End User: Utilities, Industrial, Commercial, Residential Installation: Onshore, Offshore, Indoor, Outdoor |
| Companies Covered | Siemens Energy, Hitachi Energy, General Electric, Schneider Electric, Mitsubishi Electric, Virginia Transformer Corporation, Eaton, Toshiba Energy Systems & Solutions, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Transformer Market Emerging Trajectories
Transformer technology is pivoting toward condition-based asset management and modular designs that compress installation timelines. The competitive frontier now sits in software-defined monitoring rather than incremental efficiency gains in core materials.
Natural ester dielectric fluids derived from seed oils are automating fire-safety compliance for indoor substations and urban underground networks. European distribution utilities are specifying these biodegradable alternatives for transformers inside commercial buildings and metro systems. The technology is automating the elimination of mineral oil containment infrastructure and reducing insurance premiums for densely sited assets.
The EU F-Gas Regulation is tightening permissible sulfur hexafluoride leakage rates for gas-insulated switchgear and transformer applications. Manufacturers are redesigning sealed-tank systems with welded bushings to eliminate gasketed joints. Dry-type and liquid-immersed units are capturing share in medium-voltage substations where SF6 previously dominated.
Utility procurement departments are consolidating transformer purchases into multi-year framework agreements with embedded digital service tiers. Nordic and German grid operators are unbundling hardware supply from lifetime monitoring subscriptions. This reconfiguration is most visible in offshore wind interconnector projects where OEMs retain operational responsibility for converter station transformers through the first decade of service.
Power Transformer Market Segmentation
Power transformer procurement patterns diverge sharply across voltage classes and deployment contexts, with grid-scale utilities prioritizing thermal performance guarantees while industrial buyers emphasize footprint constraints and harmonic withstand. Segment boundaries are blurring as renewable interconnection requirements force step-up units to absorb converter-duty stresses previously handled by separate equipment.
Type:
Integration depth varies substantially across transformer architectures, with standalone outdoor installations dominating transmission corridors while compact auto-transformer designs embed directly within substation switchgear assemblies.
- Step-Up:These units elevate generation voltage from 15-25 kV to 400-765 kV for efficient bulk power transmission, utilizing grain-oriented silicon steel cores and mineral oil or natural ester dielectric systems. Demand concentrates in China's ultra-high voltage corridors linking western solar and wind bases to eastern load centers, driven by State Grid Corporation's continuous transmission buildouts and the need to reduce line losses across 2,000+ kilometer spans. IEC 60076-14 thermal class ratings determine qualification for these projects.
- Step-Down:Voltage reduction from transmission to distribution levels (typically 132 kV to 11-33 kV) requires robust short-circuit withstand capability and on-load tap changer integration for voltage regulation. Industrial clusters in Germany's Bavaria region and Arizona's semiconductor corridor are procuring dedicated step-down units with redundant cooling, bypassing traditional utility channels to secure power quality for sensitive manufacturing loads. IEEE C57.12.00 standards govern insulation coordination.
- Isolation:Galvanic separation between primary and secondary circuits protects sensitive downstream equipment from grid transients and ground fault propagation.
- Auto-Transformer:Single-winding designs with tapped intermediate points achieve voltage transformation with reduced copper mass and core volume for specific ratio applications.
Volume placements concentrate in Step-Up configurations for transmission infrastructure; the faster expansion belongs to Step-Down units serving industrial captive power installations.
Application:
Cost tier stratification separates commodity distribution assets from premium converter-duty units, with the latter commanding multiple price multiples due to harmonic filtering requirements and extended thermal modeling validation.
- Power Generation:Generator step-up transformers at thermal, nuclear, and hydroelectric plants interface directly with turbine output at 15-27 kV, requiring exceptional mechanical withstand for through-fault conditions. Fleet renewal programs at aging coal and nuclear facilities in the United States and France are sustaining replacement demand, constrained by extended lead times for large-unit manufacturing and specialized winding labor availability in Central Europe and Japan.
- Transmission:Bulk power movement across synchronous grids depends on high-voltage autotransformers and phase-shifting units for power flow control. The North Sea offshore wind buildout is accelerating procurement of 220-400 kV transmission interconnections between Germany, Denmark, and the United Kingdom, with EU F-Gas Regulation constraints pushing designs toward liquid-immersed alternatives with welded bushing seals.
- Distribution:Final voltage reduction to end-use levels dominates unit volume but compresses margins through standardization and regional manufacturing competition.
- Renewable Energy:Converter-duty specifications for solar and wind integration require enhanced harmonic withstand and frequent load cycling tolerance.
Revenue concentration sits with Transmission deployments; Renewable Energy applications are climbing the fastest as offshore wind and solar park interconnection requirements intensify.
End User:
Customer type determines procurement channel structure, with utilities consolidating purchases through multi-year framework agreements while industrial buyers negotiate directly with OEMs for specialized specifications.
- Utilities:Grid operators and transmission system operators procure standardized designs through competitive tender processes with embedded 30-year asset life guarantees. FERC Order 2023 in the United States is accelerating transmission capacity additions, expanding procurement volumes for step-up transformers linking renewable generation to bulk power networks. Utilities are unbundling hardware supply from lifetime monitoring subscriptions, particularly in Nordic and German offshore wind interconnector projects.
- Industrial:Energy-intensive manufacturing, data centers, and semiconductor fabrication facilities require dedicated step-down units with redundant cooling systems and power quality assurance. Arizona's Phoenix-Tucson corridor and Bavaria's Ingolstadt-Munich cluster are bypassing traditional utility procurement to secure direct transformer supply, driven by 24/7 operational continuity requirements and voltage sag sensitivity of precision equipment.
- Commercial:Shopping centers, hospitals, and office complexes utilize compact substation designs with natural ester fluids for indoor fire-safety compliance.
- Residential:Distribution transformers serving neighborhood loads represent high-volume, low-margin commodity production with localized manufacturing.
Contract value aggregates in Utility frameworks; Industrial direct procurement is gaining share fastest as captive power installations multiply.
Installation:
Geography and physical environment dictate cooling system design, enclosure specifications, and maintenance accessibility, with offshore deployments requiring the most extensive customization.
- Onshore:Conventional outdoor substations with radiators, conservators, and bushings exposed to ambient conditions constitute the majority of installed base. India's transmission expansion and the United States' interconnection queue backlog are sustaining demand, with domestic content incentives in both countries accelerating localized grain-oriented electrical steel production for core lamination materials.
- Offshore:Platform-mounted and floating wind converter stations require hermetically sealed designs with welded bushings, pressurized nitrogen blankets, and enhanced seismic and marine environmental withstand. North Sea lease rounds and East Asian floating wind pilots are concentrating specialized converter-duty transformer demand, with OEMs retaining operational responsibility through the first decade of service.
- Indoor:Urban substations and building-integrated installations specify natural ester dielectric fluids to eliminate mineral oil containment infrastructure and reduce insurance premiums.
- Outdoor:Exposed installations in extreme climates require extended temperature range specifications and anti-corrosion coatings.
Unit volume dominates Onshore deployments; Offshore specifications are expanding most quickly as floating wind technology matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China produces the majority of ultra-high voltage transformer cores while the United States and Germany absorb premium units for grid interconnection and industrial captive power. This production-consumption divide shapes regional procurement strategies and domestic content incentives.
United States
FERC Order 2023 compels utilities to accelerate transmission capacity additions, expanding step-up transformer procurement for renewable interconnection. The Department of Energy enforces minimum efficiency standards under 10 CFR 431. Arizona's Phoenix-Tucson semiconductor corridor is procuring dedicated step-down units with redundant cooling systems, bypassing traditional utility channels.
China
State Grid Corporation's ultra-high voltage transmission buildouts concentrate demand for 1,100 kV step-up units linking western renewable bases to eastern load centers. The country's dual carbon goals mandate efficiency improvements in grid infrastructure. The Yangtze River Delta manufacturing clusters supply grain-oriented electrical steel for core lamination materials to domestic OEMs.
Germany
The EU F-Gas Regulation restricts sulfur hexafluoride leakage rates, forcing design pivots toward liquid-immersed transformer alternatives. Ecodesign Directive constraints tighten loss requirements for units placed on the European market. Bavaria's Ingolstadt-Munich industrial cluster is securing dedicated step-down transformers for semiconductor fabrication facilities.
India
Domestic content incentives under the PLI scheme accelerate localized grain-oriented electrical steel production, reducing import dependency for core materials. The Central Electricity Authority mandates efficiency standards for transmission infrastructure. Maharashtra and Gujarat transmission expansions sustain procurement volumes for 400 kV and 765 kV interconnection projects.
Japan
METI efficiency standards govern transformer loss requirements for grid-scale deployments. The concentration of skilled coil winding technicians in Japanese manufacturing creates specialized supply capacity for large-unit production. Tokyo and Osaka metropolitan utilities are unbundling hardware supply from lifetime monitoring subscriptions for offshore wind interconnector projects.
Power Transformer Market Vendor Landscape
Top-tier vendors anchor premium ultra-high voltage and offshore wind converter-duty segments, while mid-tier fabricators compete on lead-time compression for standardized distribution units. The market exhibits tiered consolidation around digital service integration and core material supply security. Three archetypes dominate: integrated energy technology conglomerates with digital twin platforms, specialized transformer OEMs with winding expertise concentration, and electrical equipment diversifiers with broad portfolio coverage. Capacity expansion into grain-oriented electrical steel and strategic partnerships for offshore wind service retention represent the dominant competitive moves.
Within the integrated energy technology tier, Siemens Energy and Hitachi Energy exemplify vendors combining hardware supply with predictive maintenance subscriptions. General Electric occupies a position among North American-based manufacturers emphasizing advanced insulation systems. These three companies represent the competitive frontier in software-defined transformer monitoring and grid integration solutions for renewable interconnection.
| Leading Market Players |
|---|
| Siemens Energy |
| Hitachi Energy |
| General Electric |
| Schneider Electric |
| Mitsubishi Electric |
| Virginia Transformer Corporation |
| Eaton |
| Toshiba Energy Systems & Solutions |
| ABB |
| Others |
Supply Flow & Price Mechanics
Cold-rolled grain-oriented electrical steel moves from Yangtze River Delta mills through three pricing tiers before reaching utility procurement desks, with each handoff embedding margin layers that compound at transformer OEMs facing fixed-price tender obligations. The path from raw lamination material to installed asset reveals how upstream concentration in Chinese metallurgy shapes downstream contract economics for European and North American grid operators.
Pricing Analysis
Margin tightening in standard distribution units reflects commodity-grade manufacturing competition from Indian and Southeast Asian fabricators. Three-tier pricing structure across premium converter-duty, standard transmission, and economy distribution levels separates projects by IEC 60076-7 thermal certification requirements and harmonic withstand specifications. Cost-down pressure on large power transformers accelerates because copper cathode spot volatility destabilizes fixed-price submissions for 30-year asset life guarantees. Industrial captive power buyers in Arizona and Bavaria exhibit lowest price sensitivity due to operational continuity premiums, while municipal utilities face procurement committee scrutiny on per-MVA capital expenditure.
Supply Chain Analysis
Direct-to-utility channels handle framework agreement volumes for State Grid Corporation and FERC-jurisdictional operators, while project-based procurement serves offshore wind EPC consortia. Active part manufacturing concentrates in China, Germany, and Japan, with tank fabrication and final assembly distributed across Poland, Mexico, and Vietnam. The supply chain draws from copper cathode, grain-oriented silicon steel, and natural ester dielectric fluid inputs. Single-source vulnerability around Japanese coil winding technicians creates delivery bottleneck risk for 500+ MVA units. Distribution runs through OEM direct sales teams for utility accounts and specialized agents for industrial captive power installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The power transformer market has become a vertical-integration race, with grain-oriented electrical steel capacity and predictive maintenance software subscriptions representing the decisive upstream and downstream levers for competitive positioning.
For Market Incumbents: Deploy digital twin platform subscriptions to extend service contract capture across installed European and North American utility fleets. Anchor hardware margins through backward integration into grain-oriented electrical steel production in India and the United States, responding to domestic content incentives. Defend against emerging Chinese OEMs by accelerating IEC 60076-7 thermal modeling certification timelines that delay competitor qualification.
For New Entrants and Emerging Players: Industrial EPC contractors represent the most accessible channel partners for bypassing entrenched utility procurement relationships. Target retrofit and uprate services in the United Kingdom and Germany where aging assets require winding replacement without full unit substitution. Penetrate through specialized converter-duty specifications for floating wind pilot projects in East Asia, where OEM operational responsibility contracts reduce upfront capital barriers.
For Investors and Strategic Acquirers: Framework agreement unbundling in Nordic and German offshore wind interconnectors is the leading indicator that hardware-software separation will redistribute value capture toward monitoring platform providers. Five-to-ten year viability favors vertically integrated specialists with captive electrical steel supply and certified winding labor pools. Monitor F-Gas Regulation enforcement intensity as the signal for liquid-immersed design pivot acceleration and associated manufacturing cycle extension.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain-Oriented Electrical Steel | Captive core lamination supply secures margin protection against copper and CRGO spot volatility. |
| Digital Twin Platform Deployment | Siemens Energy and Hitachi Energy monetize lifetime subscriptions across European utility fleets. |
| Converter-Duty Certification Investment | IEC 60076-7 thermal modeling qualification opens offshore wind interconnector procurement channels. |
| Regional Manufacturing Footprint Expansion | Localized assembly in India and the United States satisfies PLI scheme and Buy American domestic content requirements. |
| Natural Ester Dielectric Fluid Transition | Seed-oil-based insulation automates EU Ecodesign Directive fire-safety compliance for urban substations. |
Methodological Framework
Document review covered IEC 60076 and IEEE C57 standard evolution, FERC Order 2023 implementation filings, EU F-Gas Regulation impact assessments, and State Grid Corporation procurement disclosures, complemented by interviews with utility planning officers, transformer OEM procurement directors, EPC contractor project managers, and grain-oriented electrical steel metallurgy specialists. Secondary validation drew from EIA transmission project databases, IEA grid infrastructure reports, and customs trade data for copper and CRGO steel flows. Bottom-up unit placement tracking and top-down grid investment forecasts were triangulated against utility capital expenditure disclosures.
Historical capacity utilization and tender award patterns were cross-referenced against panel input from grid operators across the analysis window. Segmentation modeling incorporated voltage class, application context, end-user procurement channel, and installation environment dimensions. CAGRs were derived from regression against transmission interconnection queue backlogs and renewable energy capacity addition trajectories. Forecast inputs included skilled winding labor availability constraints and domestic content incentive phase-in schedules.
Caveats apply where copper and CRGO steel spot volatility, F-Gas Regulation enforcement calibration, or IEC 60076-7 certification timeline extensions could materially shift the outlook. Practitioners should monitor offshore wind lease round award pacing and utility framework agreement renegotiation cycles for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Liquid-Immersed Transformers Market
Transformers
Box Transformer Substation Market
Transformers
Asia-Pacific Transformer Market
Transformers
Europe Distribution Transformer Market
Transformers
North America Power Transformer Market
Transformers
North America Oil Filled Transformer Market
Transformers
Neon Transformer Market
Transformers
Traction Transformer Market
Transformers
United States Transformer Market
Transformers
Gas Insulated Transformer Market
Transformers
High Voltage (35-550 KV) Power Transformer Market
Transformers
Transformer Steel Market
Transformers
Step Up/Down Transformers Market
Transformers
EHV & UHV (above 330KV) Power Transformers Market
Transformers
Global Transformer Market
Transformers
Green Transformer Market