
 North America Dry Type Transformer Market | 2026-2036
North America Dry Type Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
North America Dry Type Transformer Market Analysis
Cast resin and vacuum pressure impregnation technology is reshaping dry type transformer manufacturing across North America, replacing older varnish-dip methods with more thermally stable insulation systems. Eaton leverages its integrated electrical portfolio to dominate commercial building specifications, while Schneider Electric sustains technology leadership through advanced resin formulation R&D. Siemens Energy anchors utility-scale renewable interconnection projects with high-voltage dry type designs.
North America dry type transformers are air-cooled electrical devices that use epoxy resin or vacuum pressure impregnated insulation to isolate conductive windings, eliminating flammable liquid dielectrics and enabling indoor installation without fire suppression infrastructure. Their primary purpose is voltage step-up or step-down in commercial buildings, industrial plants, and renewable energy facilities where safety codes restrict oil-filled alternatives. Indoor product types command the largest volume share due to dense urban construction and basement electrical room requirements across Canadian and US metropolitan zones. Medium voltage ratings represent the fastest expansion category, driven by distributed solar and energy storage interconnection standards that favor dry type solutions for direct grid connection.
The US Department of Energy enforces minimum efficiency standards under 10 CFR 431 that compel manufacturers to adopt amorphous metal and grain-oriented electrical steel cores, while CSA C802.2 in Canada mandates comparable loss reduction thresholds for commercial and industrial units. NEMA TP-1 and TP-2 testing protocols further shape procurement specifications by establishing standardized efficiency measurement methods that utilities and engineering firms embed in bid documents. Stakeholders must monitor proposed amendments to DOE efficiency tiers and state-level building electrification codes that could accelerate replacement cycles in existing commercial stock.
Market Dynamics
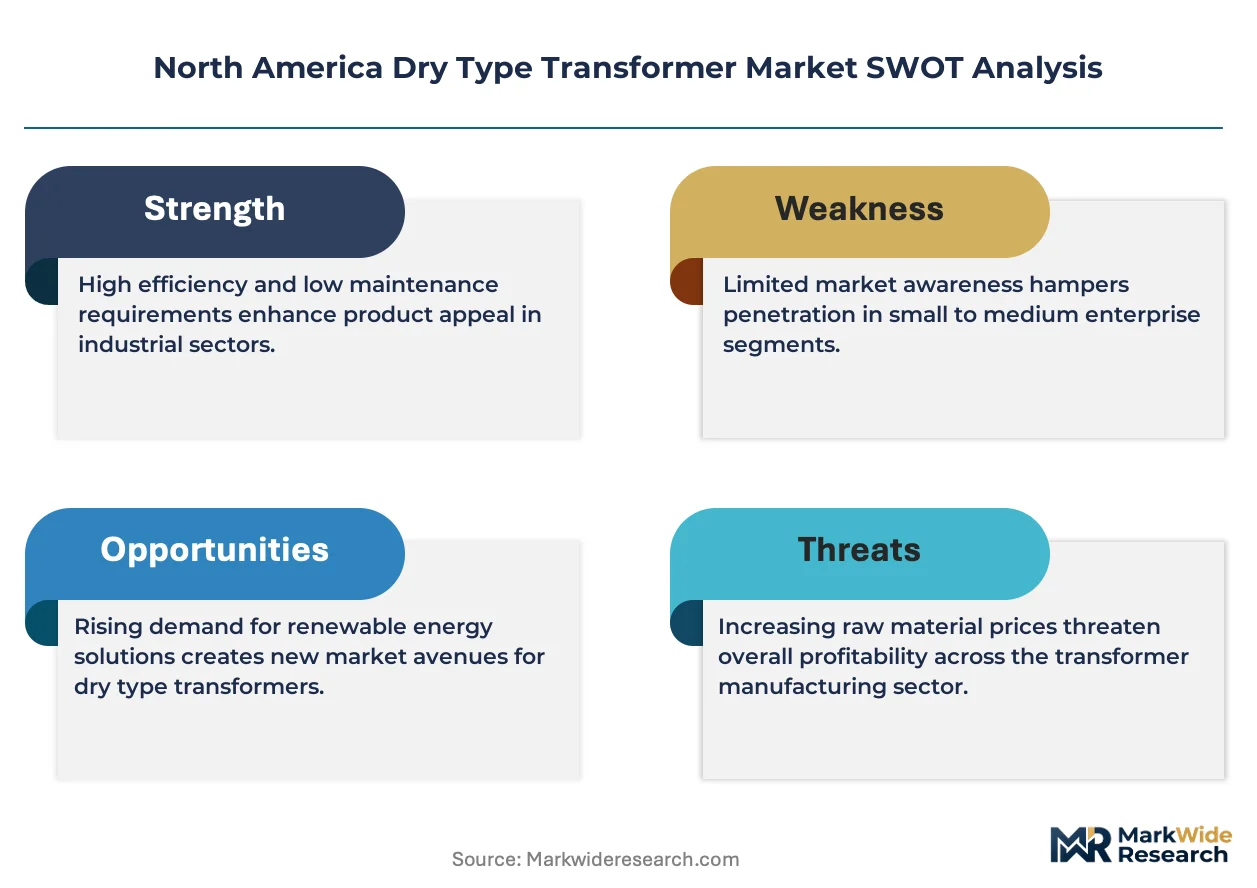
US Department of Energy efficiency mandates under 10 CFR 431 are compressing replacement cycles and forcing core material upgrades across the installed base, while data center power density requirements pull medium-voltage dry type units into hyperscale facilities.
Growth Catalysts
- 10 CFR 431 Efficiency Tiers:The US DOE's amended minimum efficiency standards compel commercial building operators to retire aging oil-filled units ahead of schedule, accelerating dry type adoption in retrofit applications.
- Hyperscale Data Center Buildouts:Microsoft, Amazon, and Google facility expansions across Virginia and Texas require fire-safe, indoor-rated transformers that eliminate liquid dielectric containment infrastructure.
- Amorphous Metal Core Adoption:Transformer manufacturers are integrating non-crystalline alloy cores to meet loss reduction thresholds while maintaining compact footprints for urban electrical rooms.
Market Restraints
- Grain-Oriented Electrical Steel Concentration:North American transformer producers depend on a concentrated supplier base for high-permeability core steel, exposing margins to commodity volatility and import tariff uncertainty.
- Cast Resin Curing Bottlenecks:Vacuum pressure impregnation and epoxy resin curing processes extend manufacturing lead times versus conventional varnish-dip methods, constraining volume response to demand spikes.
- Medium-Voltage Technical Ceiling:Dry type insulation systems face dielectric stress limitations above 35kV class, capping addressable market share in utility transmission applications where oil-filled designs dominate.
Strategic Opportunities
- Canadian Building Electrification Codes:Provincial mandates in British Columbia and Ontario are accelerating commercial HVAC electrification, creating incremental demand for CSA C802.2-compliant dry type distribution transformers.
- Solar-Plus-Storage Interconnection:Utility-scale photovoltaic and battery hybrid projects in California and Texas favor dry type solutions for direct medium-voltage grid connection without fire suppression systems.
- Digital Twin Integration:Sensor-embedded dry type transformers combined with cloud-based thermal monitoring platforms enable predictive maintenance contracts that unbundle hardware from recurring service revenue.
Industry Challenges
- Vacuum Pressure Impregnation Technician Shortage:The specialized skill set for resin formulation, vacuum chamber operation, and cure cycle optimization is concentrated among aging workforce cohorts in the US Midwest and Ontario manufacturing corridors.
- NEMA TP-2 Certification Timelines:Third-party efficiency validation and witness testing protocols add 8-14 weeks to product qualification, compressing responsiveness to utility bid windows.
- Legacy Oil-Filled Infrastructure Interoperability:Dry type retrofits into existing commercial buildings require coordination with aged switchgear, bus duct, and protection relay systems that lack standardized interface protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Dry Type Transformer Market |
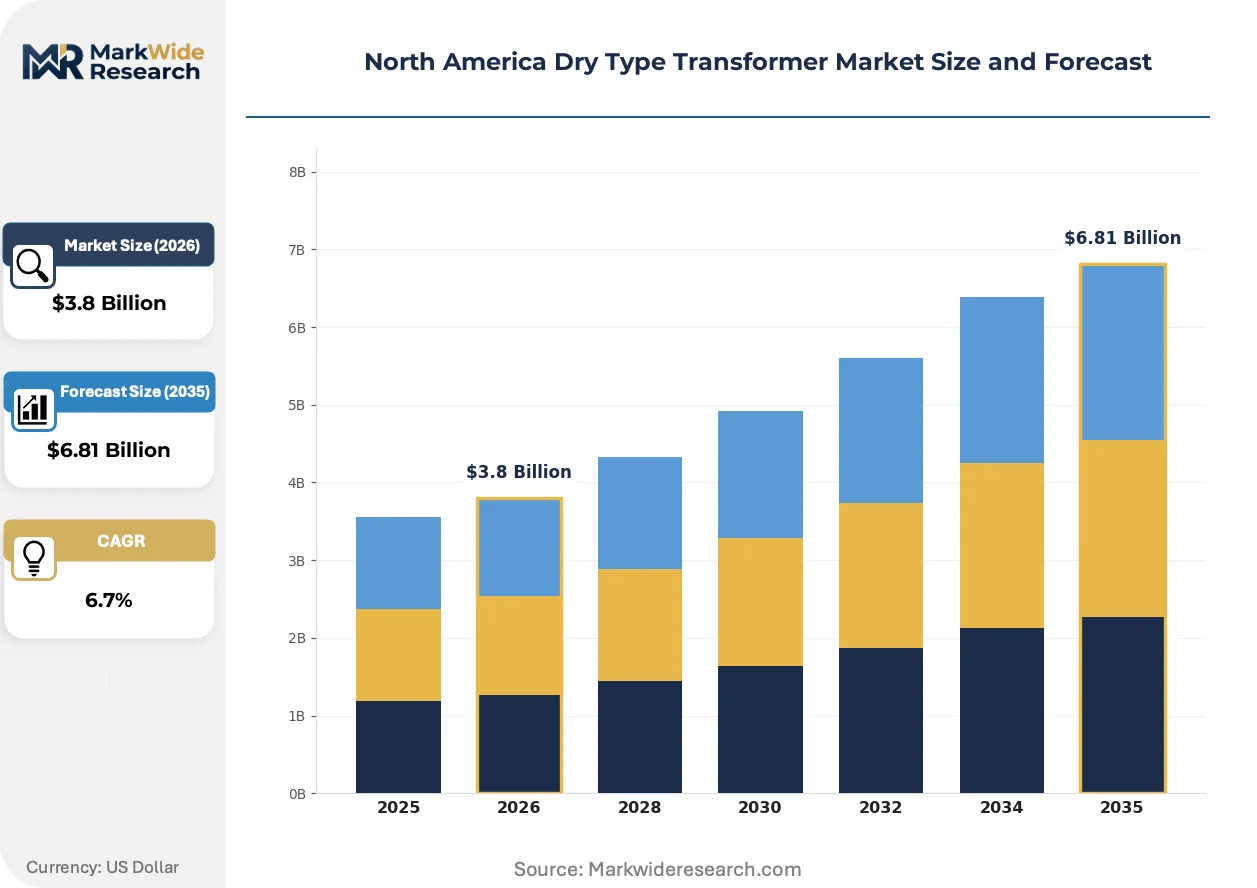
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor, Outdoor, Compact, Standard End User: Utilities, Industrial, Commercial, Renewable Energy Installation Type: Floor Mounted, Wall Mounted, Pole Mounted, Skid Mounted Voltage Rating: Low Voltage, Medium Voltage, High Voltage, Extra High Voltage |
| Companies Covered | Eaton, Schneider Electric, Siemens Energy, ABB, Hammond Power Solutions, MGM Transformer Company, General Electric, Virginia Transformer Corp, Hitachi Energy, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Dry Type Transformer Market Emerging Trajectories
Digital instrumentation and predictive analytics are embedding intelligence into dry type transformer architectures, shifting value capture from commodity hardware toward performance-guaranteed service models.
Smart thermal monitoring systems using distributed fiber-optic temperature sensors and dissolved gas analysis proxies are digitizing condition-based maintenance protocols. Data center operators and large commercial real estate portfolios are deploying these systems at scale to minimize unplanned outages. The technology is digitizing traditional time-based inspection schedules into continuous remote diagnostics, compressing service contractor margins while expanding OEM recurring revenue streams.
The US Environmental Protection Agency's updated energy efficiency standards for distribution transformers are mandating amorphous metal and advanced grain-oriented steel core materials that reduce no-load losses. Manufacturers must retool winding and core stacking processes to comply with the amended 10 CFR 431 framework. Medium-voltage commercial and industrial units face the steepest compliance burden, pushing regional producers toward vertical integration into core steel sourcing.
Engineering-procurement-construction firms and large facility operators are consolidating transformer purchasing through master service agreements that bundle specification, installation, and multi-year maintenance. Traditional electrical distributor channels face disintermediation as direct OEM relationships capture specification influence earlier in project development. The shift is most visible in US hyperscale data center and utility-scale renewable energy verticals, where procurement teams prioritize total cost of ownership over upfront capital expenditure.
North America Dry Type Transformer Market Segmentation
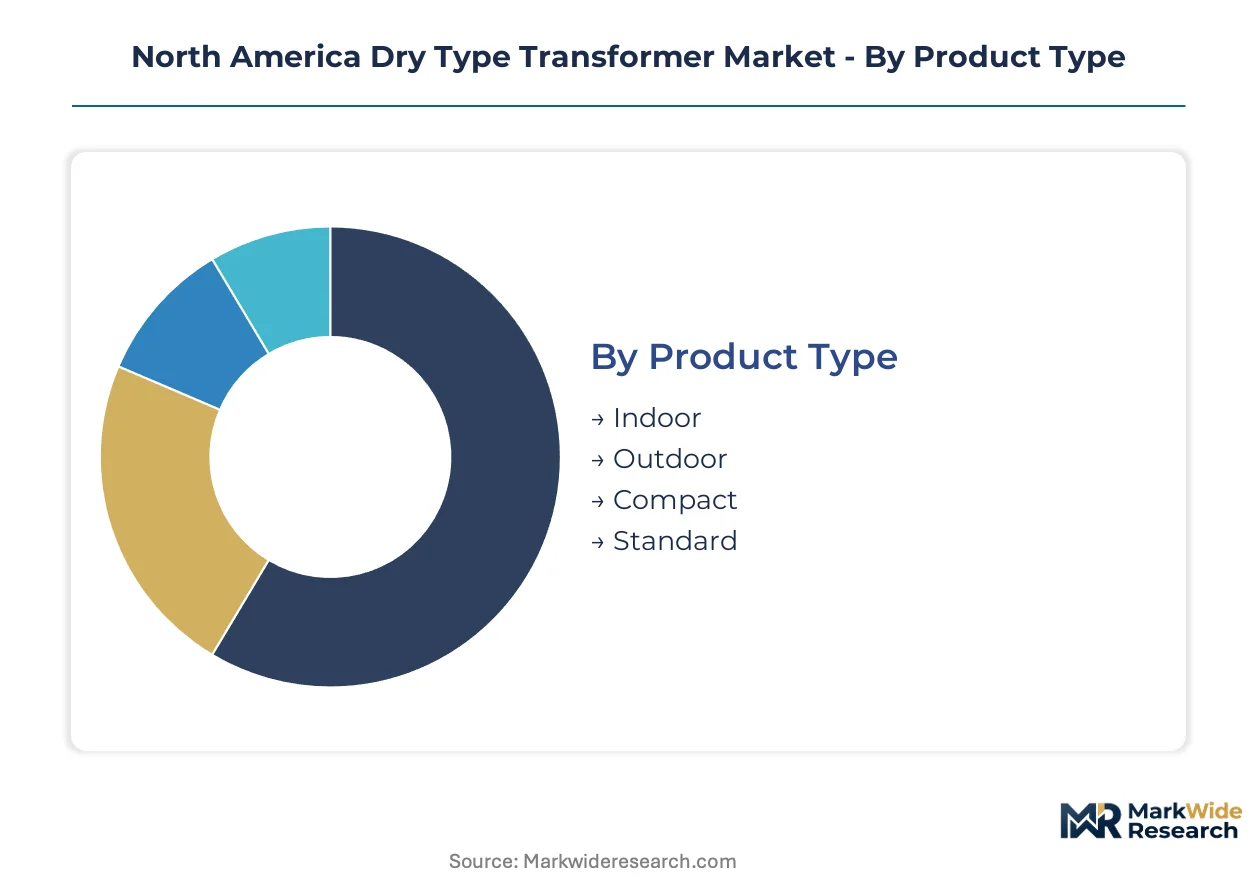
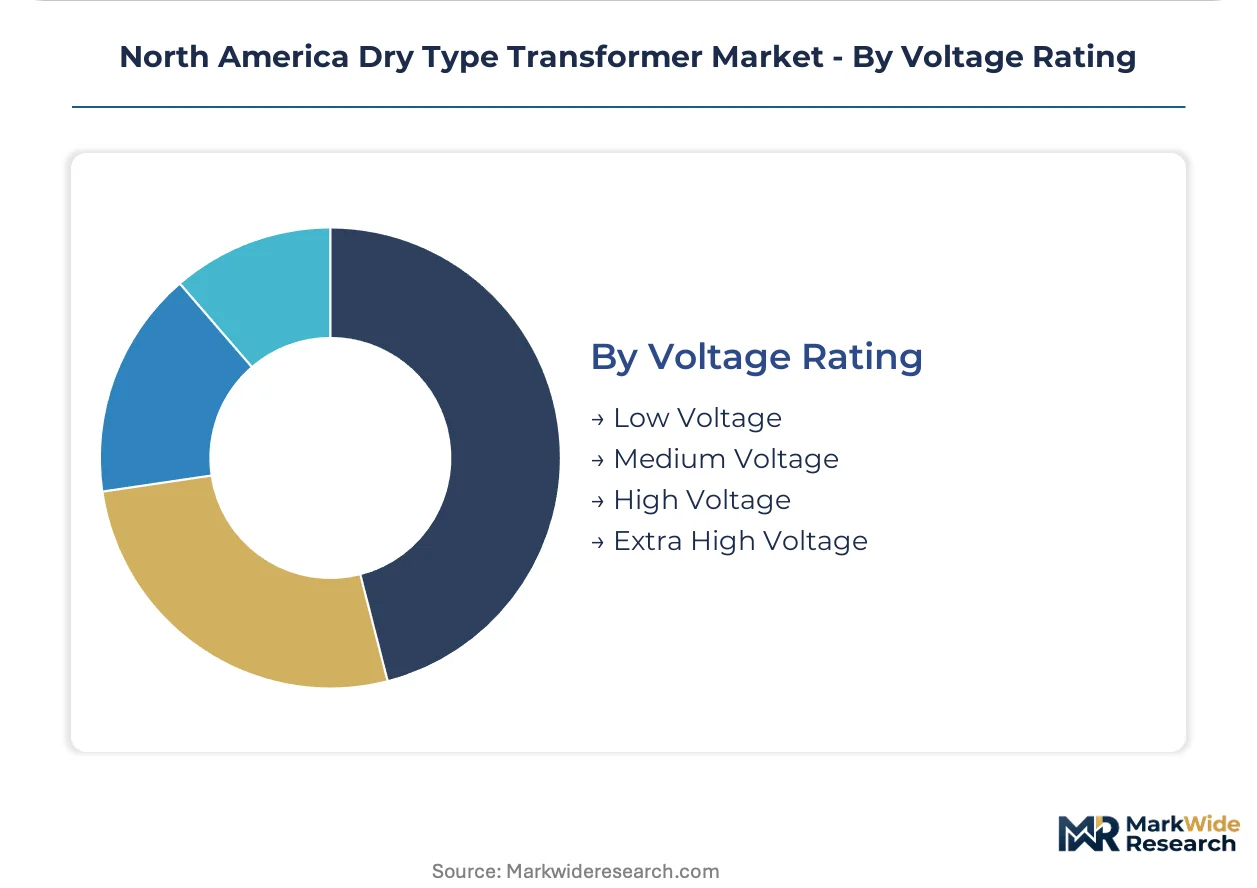
Dry type transformer segmentation reveals distinct procurement patterns across voltage classes and installation environments. Specification engineers match insulation systems to fire safety codes, spatial constraints, and grid interconnection standards.
Product Type:
Indoor specifications dominate procurement volumes across dense metropolitan construction zones.
- Indoor:Epoxy resin and vacuum pressure impregnated units eliminate flammable liquid containment requirements for basement electrical rooms and high-rise infrastructure. Demand concentrates in California and Texas data center corridors where fire codes restrict oil-filled alternatives.
- Outdoor:Weatherproof enclosures with UV-stabilized insulation withstand direct exposure for distributed solar and industrial substations. Texas utility-scale renewable projects favor these units for pad-mounted installations without secondary containment.
- Compact:Reduced footprint designs fit constrained urban electrical rooms and modular data center power modules.
- Standard:Conventional dimension units serve replacement cycles in existing commercial buildings with established spatial allowances.
Established volume favors Indoor; emerging adoption favors Outdoor.
End User:
Customer procurement patterns diverge between regulated utilities and private infrastructure operators.
- Utilities:Investor-owned and municipal utilities specify NEMA TP-2 certified units for distribution grid modernization. Procurement runs through multi-year master service agreements that bundle installation with predictive maintenance contracts.
- Industrial:Manufacturing facilities and process plants require medium-voltage step-down units for motor drive centers and heavy machinery loads. Demand clusters in Ontario automotive corridors and Texas petrochemical zones.
- Commercial:Office towers, retail complexes, and healthcare facilities prioritize fire-safe indoor ratings for basement electrical rooms.
- Renewable Energy:Solar-plus-storage developers in California and Texas specify dry type solutions for direct medium-voltage grid connection without fire suppression infrastructure.
Commercial maintains installed base dominance; Renewable Energy climbs the fastest on project pipeline expansion.
Installation Type:
Mounting configurations align with facility spatial economics and seismic zone requirements.
- Floor Mounted:Pad and foundation-based installations anchor utility-scale and heavy industrial applications. Texas solar farms and California data centers specify these for seismic stability and thermal clearance.
- Wall Mounted:Bracket-supported units maximize floor space in congested electrical rooms and high-rise mechanical floors. Toronto and Vancouver commercial towers drive specification for these space-constrained environments.
- Pole Mounted:Overhead distribution applications in rural Canadian provinces and US Mountain West regions.
- Skid Mounted:Pre-assembled transportable units serve temporary power and mobile substation applications.
Floor Mounted commands utility-scale volumes; Wall Mounted gains share fastest on urban densification.
Voltage Rating:
Insulation system capabilities define addressable market boundaries across the voltage spectrum.
- Low Voltage:600V-class units serve commercial building distribution and light industrial loads. California Title 24 building electrification codes accelerate replacement of aging oil-filled units in existing stock.
- Medium Voltage:5kV through 35kV-class designs interconnect distributed solar, energy storage, and data center power infrastructure. Texas ERCOT grid interconnection standards favor these for direct renewable integration.
- High Voltage:69kV through 138kV-class applications face dielectric stress limitations that constrain dry type penetration against oil-filled alternatives.
- Extra High Voltage:230kV-plus transmission class remains outside practical dry type insulation capabilities.
Low Voltage sustains replacement cycle volumes; Medium Voltage shows steepest expansion trajectory on renewable interconnection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center developers, solar-plus-storage integrators, and commercial building electrification contractors concentrate procurement across three national markets with distinct regulatory timelines and infrastructure buildout cycles.
United States
Virginia's Loudoun County data center corridor and Texas ERCOT grid zones drive hyperscale facility power infrastructure demand. The EPA's amended 10 CFR 431 efficiency tiers compel core material upgrades for commercial and industrial units. California Title 24 building electrification codes accelerate dry type retrofits in Los Angeles and San Francisco metropolitan electrical rooms.
Canada
Ontario automotive manufacturing corridors and British Columbia commercial tower construction anchor medium-voltage step-down requirements. CSA C802.2 loss reduction thresholds mandate comparable efficiency gains to US DOE standards. Toronto and Vancouver urban densification concentrates wall-mounted specification for constrained basement electrical infrastructure.
Mexico
Nearshoring manufacturing expansion across Nuevo León and Baja California generates industrial power distribution demand. The country's national energy regulator oversees grid interconnection standards for distributed generation assets. Monterrey automotive clusters and Tijuana electronics assembly plants specify fire-safe indoor-rated units for facility electrification.
North America Dry Type Transformer Market Vendor Landscape
Channel-controlling players compete with product-specialist players across specification-influenced procurement channels. The market structure consolidates around diversified electrical equipment conglomerates with integrated portfolios and regional specialists with focused manufacturing capabilities. Three archetypes dominate: full-spectrum electrical infrastructure providers, transformer-dedicated fabricators, and utility-scale renewable interconnection specialists. Capacity expansion into vacuum pressure impregnation curing facilities and strategic partnerships for amorphous metal core sourcing represent the dominant competitive moves.
Among North American-based diversified electrical manufacturers, Eaton, Schneider Electric, and Siemens Energy exemplify the integrated infrastructure archetype. Eaton occupies a position reflecting broad commercial building specification reach. Schneider Electric sits within the technology-forward tier emphasizing resin formulation capabilities. Siemens Energy anchors utility-scale renewable interconnection positioning. These three represent channel-control strategies against specialist competitors including Hammond Power Solutions and Virginia Transformer Corp.
| Leading Market Players |
|---|
| Eaton |
| Schneider Electric |
| Siemens Energy |
| ABB |
| Hammond Power Solutions |
| MGM Transformer Company |
| General Electric |
| Virginia Transformer Corp |
| Hitachi Energy |
| Others |
Supply Flow & Price Mechanics
Undercapacity in North American vacuum pressure impregnation curing facilities is compressing supplier margins and amplifying pricing power for resin-formulation specialists serving data center and renewable energy procurement channels.
Pricing Analysis
Cost-plus contracts indexed to grain-oriented electrical steel and copper LME pricing dominate utility and hyperscale data center procurement. Three-tier pricing structure across premium, standard, and economy levels separates NEMA TP-2 certified amorphous core units from conventional grain-oriented designs and basic commercial building specifications. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in standard-grade commercial units is intensifying because of tariff exposure on imported core steel. Industrial manufacturing facilities demonstrate highest price sensitivity, while hyperscale data center operators prioritize total cost of ownership over upfront capital.
Supply Chain Analysis
Upstream feedstock for amorphous metal cores draws from Japan, Germany, and the United States, while epoxy resin formulations source from South Korea, China, and domestic specialty chemical producers. Raw material dependencies center on grain-oriented electrical steel, copper winding wire, and vacuum-grade epoxy compounds. Supply chain risk rests on single-source vulnerability for high-permeability core steel from concentrated metallurgical suppliers. Distribution runs through direct OEM master service agreements with EPC firms and large facility operators, bypassing traditional electrical distributor channels in utility-scale renewable and data center verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as procurement consolidation through master service agreements disintermediates traditional distributor channels and splinters specification influence across regional specialist manufacturers.
For Market Incumbents: Harden resin formulation capabilities through captive supply of custom epoxy compounds to defend against Asian specialty chemical entrants. Expand vacuum pressure impregnation curing capacity in the US Midwest and Ontario manufacturing corridors to capture utility-scale renewable interconnection demand. Channel control through multi-year predictive maintenance contracts anchors specification influence against transformer-dedicated fabricators. For New Entrants and Emerging Players: Pursue Canadian provincial building electrification mandates in British Columbia and Ontario as the most penetrable geography, where CSA C802.2 compliance requirements lag US DOE efficiency tier adoption and create specification windows for CSA-certified entrants. Target wall-mounted compact designs for Toronto and Vancouver urban densification projects. Go-to-market angle: direct EPC contractor relationships bypassing incumbent distributor networks. For Investors and Strategic Acquirers: Capital is best deployed toward transformer-dedicated fabricators with vacuum pressure impregnation curing assets and established CSA C802.2 certification pathways. Long-term viability over the mid-term projection horizon rests on resin formulation R&D capabilities and amorphous core sourcing relationships rather than commodity winding operations. Signal to monitor: proposed amendments to DOE efficiency tiers that would accelerate replacement cycles in existing commercial stock.| Strategic Initiative | Industry Significance |
|---|---|
| Vacuum Pressure Impregnation Capacity Expansion | Resin-curing bottlenecks constrain volume response to Texas and California demand spikes. |
| Amorphous Metal Core Backward Integration | Captive supply of non-crystalline alloy cores insulates margins from grain-oriented steel tariff volatility. |
| Digital Twin Platform Development | Sensor-embedded units with cloud-based thermal monitoring enable predictive maintenance revenue streams. |
| CSA C802.2 Certification Investment | Canadian provincial electrification mandates create incremental demand for loss-reduction compliant units. |
| Direct EPC Master Service Agreements | Bundled specification, installation, and maintenance contracts capture procurement influence early in project development. |
Methodological Framework
The analysis maps indoor, outdoor, and compact product configurations alongside low, medium, and high voltage ratings, each validated through utility planning officers, IPP project developers, EPC contractors, and commercial facility engineering directors. Primary interviews with transformer procurement teams at hyperscale data center operators and renewable energy developers combined with secondary validation from EIA electricity distribution data, FERC interconnection filings, NEMA TP-2 certification registries, and CSA C802.2 compliance databases. Bottom-up unit shipment estimates and top-down infrastructure investment flows triangulate market sizing.
Assumptions held fixed include continuation of 10 CFR 431 efficiency tier frameworks and CSA C802.2 loss reduction thresholds, while variables included data center power density trajectories and provincial building electrification code adoption timelines across the projection horizon. Segmentation dimensions modeled span product type, voltage rating, installation configuration, and end-use vertical. CAGRs derive from regression against historical utility capital expenditure patterns and renewable interconnection queue data, with sensitivity analysis on amorphous metal core adoption rates and resin curing capacity expansion schedules.
Macroeconomic conditions sit as an overlay; deviation in copper and electrical steel commodity pricing, construction cost inflation, or interest rate environments would shift the trajectory of replacement cycle timing and new project development. Forecasts reflect documented assumptions regarding regulatory stability and technology cost curves. Quarterly review of DOE efficiency tier amendment proceedings, provincial code adoption announcements, and core steel import tariff adjustments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
High Voltage (35-550 KV) Power Transformer Market
Transformers
Three Phase Transformer Market
Transformers
Liquid Filled Transformer Market
Transformers
Europe Distribution Transformer Market
Transformers
Europe Telecom Transformers Market
Transformers
Gas Insulated Transformer Market
Transformers
Step Up/Down Transformers Market
Transformers
India Distribution Transformer Market
Transformers
Single Phase Power Transformer Market
Transformers
North America Smart Transformers Market
Transformers
Smart Transformer Market
Transformers
United States Transformer Market
Transformers
North America Power Transformer Market
Transformers
Cast Resin Transformers Market
Transformers
US Oil Filled Distribution Transformer Market
Transformers
Global Transformer Market