
 UK Smart Grid Network Market | 2026-2036
UK Smart Grid Network Market Size, Share, and Industry Trends Forecast 2026-2036
UK Smart Grid Network Market Insights
Utility procurement channels is fragmenting as Ofgem's regulatory reforms splinter traditional vendor relationships across regional distribution networks. Siemens AG leverages its automation portfolio to anchor large-scale grid modernization contracts in southern England. Schneider Electric SE competes through integrated energy management platforms that span metering and distribution control. ABB differentiates with high-voltage switchgear and digital substation expertise that sustains its position in transmission-linked smart grid projects.
A smart grid network constitutes an electricity distribution architecture incorporating two-way digital communication, automated control systems, and real-time sensing across generation, transmission, and consumption nodes, typically operating at frequencies of 50 Hz with latency requirements below 100 milliseconds for protection relaying. Its primary purpose enables dynamic load balancing, renewable intermittency management, and fault isolation without manual intervention. Advanced Metering Infrastructure dominates technology deployment volumes as utilities replace legacy meters with cellular-connected units capable of half-hourly data transmission. Grid Optimization commands premium pricing within application categories due to algorithmic complexity and integration with legacy SCADA systems. Demand Response is expanding fastest among technology segments as industrial plants and commercial buildings enroll in flexibility services markets.
Ofgem enforces RIIO-ED2 price controls that compel distribution network operators to publish innovation stimulus spending and demonstrate carbon reduction outcomes. BEIS and the Climate Change Committee set binding decarbonization trajectories that tighten grid emission intensity benchmarks across successive carbon budget periods. National Grid ESO operates the electricity system operator function under license conditions that mandate increasing volumes of inertia-free renewable integration. Stakeholders must monitor how the Future System Operator transition reconfigures procurement accountability between transmission and distribution tiers.
Market Dynamics
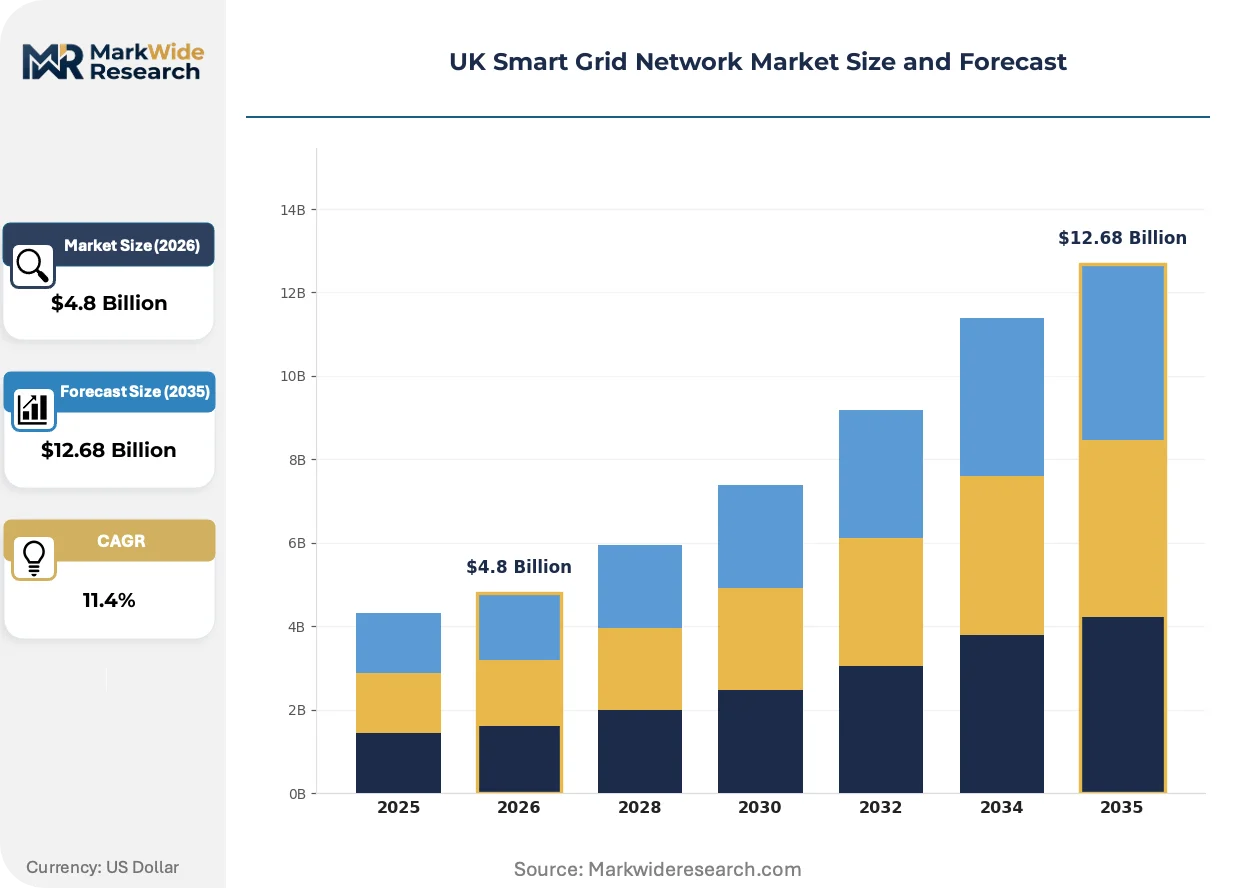
Ofgem's RIIO-ED2 price control framework is compressing distribution network operator margins while mandating measurable carbon reduction outcomes, forcing utilities to accelerate procurement of demand response platforms and intelligent automation systems across England, Scotland, and Wales.
Growth Catalysts
- RIIO-ED2 Efficiency Mandates:Ofgem's price control framework compels distribution network operators to publish innovation stimulus spending and demonstrate quantifiable efficiency gains, driving procurement of grid optimization platforms.
- Urban Infrastructure Renewal:Aging substations and distribution circuits in London, Birmingham, and Manchester require intelligent automation to manage rising electrification loads from transport and heating.
- Flexibility Services Markets:National Grid ESO's procurement mechanisms for frequency response and reserve services create revenue streams for industrial plants and commercial buildings enrolled in demand response programs.
Market Restraints
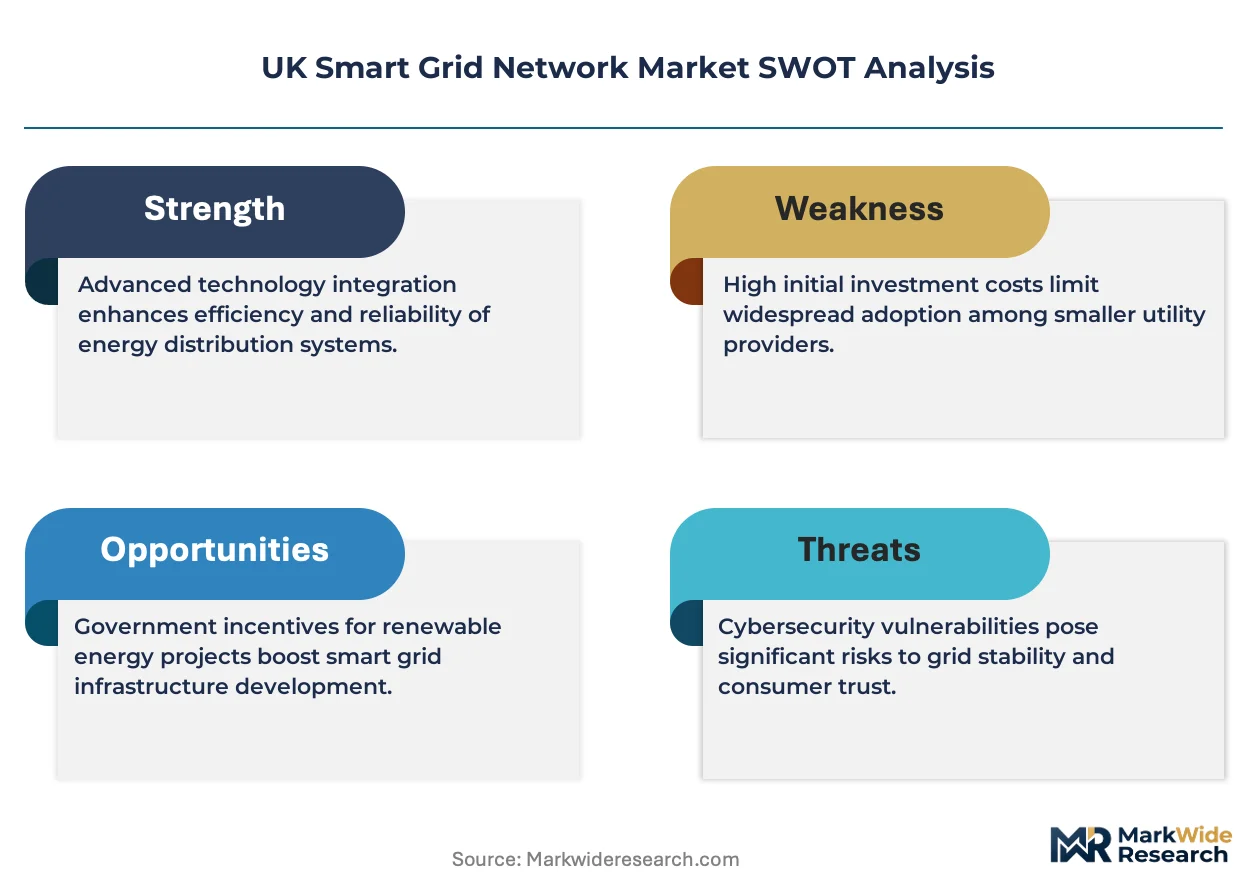
- Copper and Rare Earth Price Volatility:Supply concentration in processing facilities outside the UK creates input cost uncertainty for transformer manufacturing and power electronics deployment.
- Legacy SCADA Integration Complexity:Proprietary communication protocols in existing distribution control systems impose technical debt that slows digital substation rollout.
- Skills Shortage in Protection Engineering:The retirement trajectory of specialized relay technicians outpaces university pipeline output, constraining deployment velocity for protection system upgrades.
Strategic Opportunities
- Welsh and Scottish Rural Electrification:Remote distribution networks in the Scottish Highlands and Welsh valleys present underpenetrated terrain for microgrid and battery storage integration.
- Vehicle-to-Grid Convergence:Bidirectional charging infrastructure is hybridizing automotive and power electronics supply chains, opening new channel relationships between automakers and distribution operators.
- Future System Operator Transition:The reconfiguration of procurement accountability between transmission and distribution tiers creates whitespace for integrated energy service providers.
Industry Challenges
- Cybersecurity Certification Timelines:NCSC and Ofgem security standards for critical national infrastructure impose lengthy approval cycles for software-defined protection systems.
- Interoperability Testing Burden:Multi-vendor integration projects require extensive conformance validation against IEC 61850 and DNP3 protocols before operational deployment.
- Capex Intensity of Digital Substations:Full automation retrofits demand substantial upfront investment in merging units, process buses, and engineering workstations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Smart Grid Network Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Advanced Metering Infrastructure, Demand Response, Smart Sensors, Distributed Generation Application: Energy Management, Distribution Automation, Grid Optimization, Renewable Integration End User: Utilities, Commercial Buildings, Residential Users, Industrial Plants Deployment: Public Sector, Private Sector, Hybrid Systems, Others |
| Companies Covered | Schneider Electric SE, Landis+Gyr Group AG, E.ON SE, Efacec Energia, Hitachi Ltd, EdF Energy, Siemens AG, ABB, SSE PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Smart Grid Network Market Trends and Innovations
Digitalization of protection and control systems is compressing substation footprints while enabling centralized visibility across geographically dispersed distribution networks. The convergence of operational technology and information technology stacks is creating new attack surfaces and procurement criteria.
Distributed energy resource management systems are hybridizing traditional distribution management platforms with behind-the-meter asset orchestration. Scottish and Welsh network operators are deploying these systems fastest to manage high renewable penetration. The technology is compressing the distinction between transmission-linked balancing services and local network constraint management.
Ofgem's RIIO-ED2 innovation stimulus mechanism is redirecting capital toward demonstrable carbon reduction outcomes rather than traditional asset replacement. Distribution network operators must now justify expenditure through published innovation metrics. The framework most affects urban clusters where aging infrastructure coincides with electrification pressure from transport and heat.
Industrial energy buyers are consolidating procurement authority into centralized energy management functions that negotiate directly with flexibility market platforms. This disintermediates traditional supplier relationships and compresses switching cycles. The pattern is most visible in the manufacturing corridor between Manchester and Birmingham where large industrial loads cluster.
UK Smart Grid Network Market Segmentation
Smart grid procurement patterns diverge sharply across technology maturity, application criticality, and end-user sophistication. Understanding these fault lines enables vendors to calibrate pricing architectures and channel investments against actual deployment velocity rather than aggregate market momentum.
Technology:
Use cases span from passive data collection through active network control, with deployment complexity escalating across the functional spectrum.
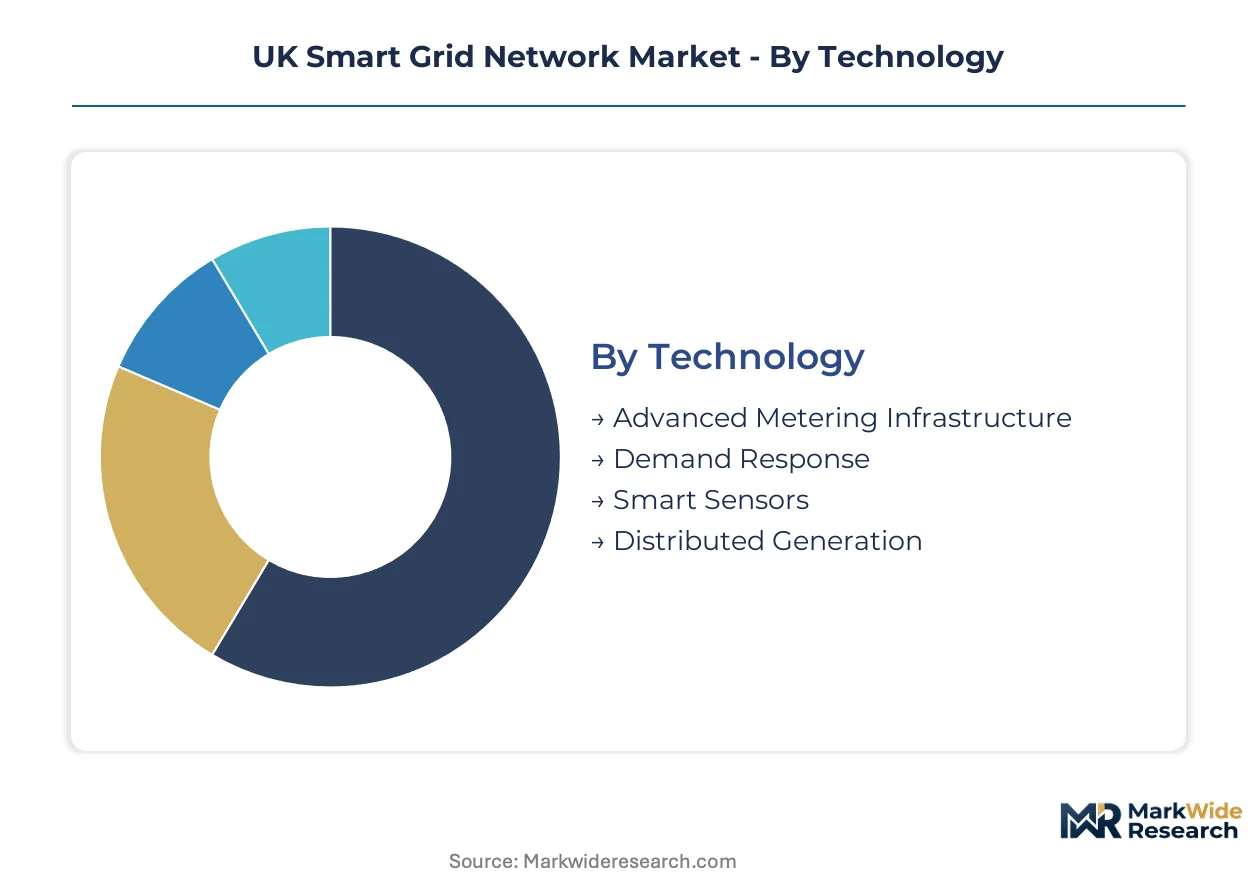
- Advanced Metering Infrastructure:Cellular-connected meters transmit half-hourly consumption data across England, Scotland, and Wales. Procurement concentrates in urban clusters where Ofgem's RIIO-ED2 mandates accelerate legacy replacement timelines.
- Demand Response:Industrial plants and commercial buildings modulate consumption in response to National Grid ESO frequency signals. Revenue streams from flexibility services markets are expanding most quickly in the Manchester-Birmingham manufacturing corridor.
- Smart Sensors:Real-time thermal and voltage monitoring devices deployed across distribution circuits.
- Distributed Generation:Behind-the-meter solar and storage assets integrated into network visibility platforms.
The dominant share belongs to Advanced Metering Infrastructure, while Demand Response is closing the gap fastest.
Application:
Cost tiers separate commodity automation from algorithmic optimization requiring legacy SCADA integration.
- Grid Optimization:Algorithmic load balancing and predictive maintenance platforms command premium pricing due to SCADA integration complexity and specialized engineering requirements. Scottish and Welsh network operators prioritize these systems to manage high renewable penetration in remote terrain.
- Energy Management:Enterprise-level consumption analytics and automated control systems for large commercial and industrial facilities. Procurement authority is consolidating into centralized energy management functions that negotiate directly with flexibility platforms.
- Distribution Automation:Feeder reconfiguration and fault isolation systems operating at sub-100 millisecond latency.
- Renewable Integration:Inverter control and curtailment management for distributed solar and wind assets.
Grid Optimization captures the highest margin pool, though Energy Management is gaining share fastest as industrial buyers consolidate procurement authority.
End User:
Customer type determines contract structure, with utilities favoring capital expenditure frameworks and commercial entities preferring service-based arrangements.
- Utilities:Distribution network operators across England, Scotland, and Wales procure under Ofgem's RIIO-ED2 price controls that mandate innovation stimulus spending and carbon reduction outcomes. These entities dominate procurement volume but face compressed margins.
- Industrial Plants:Manufacturing facilities in the Manchester-Birmingham corridor enroll in demand response programs to capture National Grid ESO flexibility payments. Revenue stacking across multiple grid services is accelerating adoption.
- Commercial Buildings:Office and retail portfolios implementing building energy management systems.
- Residential Users:Households receiving smart meters through utility-mandated rollout programs.
Utilities account for the dominant procurement volume, while Industrial Plants are expanding their share fastest through direct participation in flexibility markets.
Deployment:
Maturity gradients separate established public infrastructure from emerging hybrid ownership models.
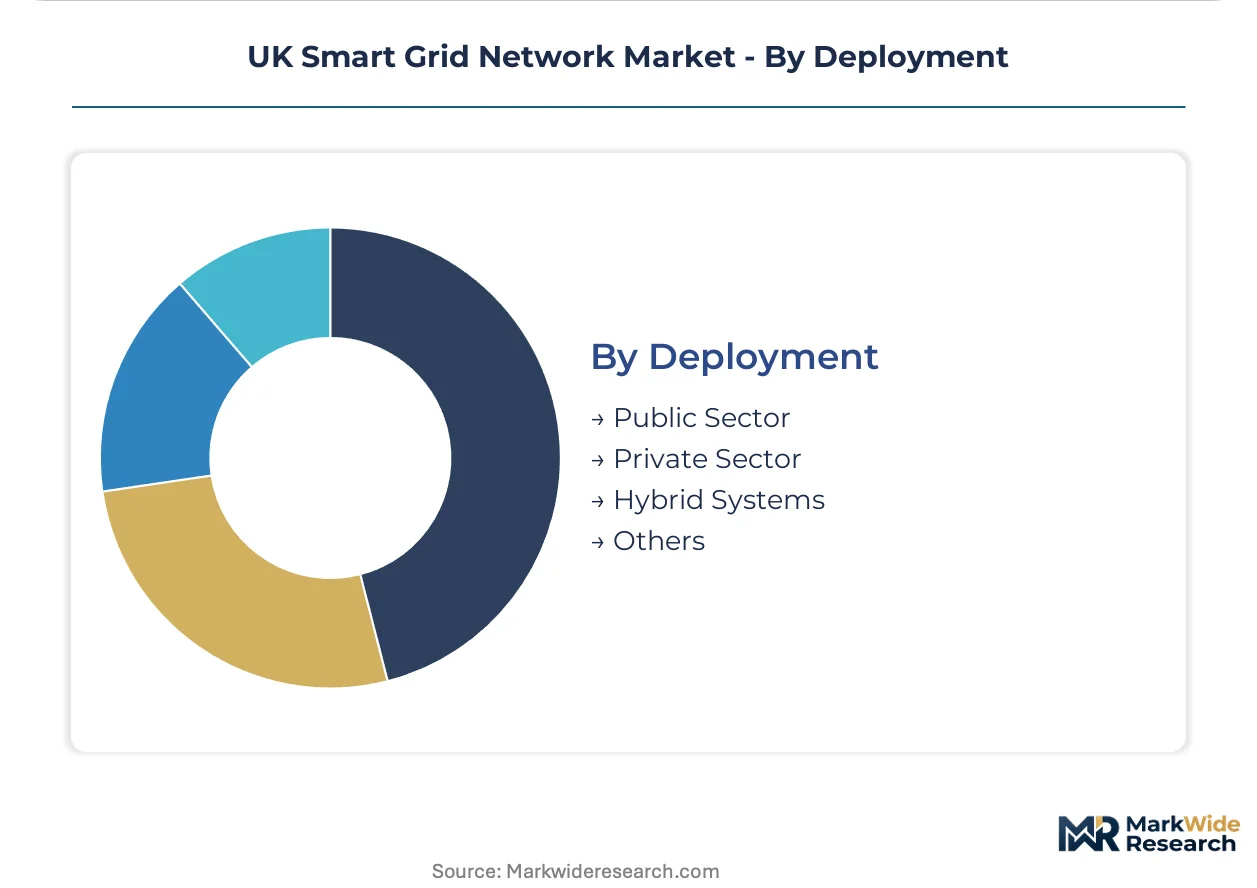
- Public Sector:Government-funded rural electrification projects in Scottish Highlands and Welsh valleys prioritize microgrid and battery storage integration. BEIS funding streams support demonstration projects that validate novel technical architectures.
- Private Sector:Investor-owned distribution networks and commercial facility operators deploying automation without regulatory procurement mandates. These deployments emphasize rapid payback and operational cost reduction.
- Hybrid Systems:Public-private partnerships combining utility infrastructure with behind-the-meter assets.
- Others:Community energy schemes and cooperative ownership structures.
Public Sector deployment holds the dominant share, though Hybrid Systems are climbing fastest as vehicle-to-grid convergence creates new ownership structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ofgem anchors the UK regulatory architecture through RIIO-ED2 price controls that mandate efficiency targets and carbon reduction outcomes across England, Scotland, and Wales. Distribution network operators respond by accelerating procurement of grid optimization platforms and demand response technologies in urban clusters where aging infrastructure faces electrification pressure.
England
London, Birmingham, and Manchester concentrate the heaviest smart grid investment as distribution network operators replace legacy substations with intelligent automation systems. Ofgem's innovation stimulus spending requirements under RIIO-ED2 compel utilities to publish measurable efficiency gains. The Manchester-Birmingham manufacturing corridor enrolls industrial plants in National Grid ESO flexibility services markets at accelerating rates.
Scotland
Scottish network operators deploy distributed energy resource management systems fastest to manage high renewable penetration in remote Highland terrain. BEIS funding streams support rural electrification demonstration projects that validate microgrid and battery storage architectures. Edinburgh and Glasgow anchor procurement clusters where grid optimization platforms command premium pricing due to integration complexity with legacy SCADA systems.
Wales
Welsh valleys present underpenetrated terrain for smart grid deployment as public sector rural electrification programs prioritize intelligent automation in isolated distribution networks. The country's national energy regulator enforces carbon reduction benchmarks that tighten across successive reporting periods. Cardiff and Swansea concentrate commercial building demand response enrollment as flexibility market participation expands.
Northern Ireland
The single electricity market operator coordinates cross-border procurement frameworks that align with Republic of Ireland grid modernization timelines. Network operators face compressed margins under efficiency mandates while managing aging infrastructure in Belfast and Derry urban clusters. The region's regulatory framework emphasizes demonstrable innovation outcomes over traditional asset replacement expenditure.
UK Smart Grid Network Market Competitive Landscape
Integrated energy conglomerates and specialized automation technology providers split the market between utility-scale infrastructure contracts and distributed asset management platforms. Siemens AG leverages its automation portfolio to anchor large-scale grid modernization contracts in southern England distribution networks. Schneider Electric SE competes through integrated energy management platforms spanning metering and distribution control functions. ABB differentiates with high-voltage switchgear and digital substation expertise that sustains its position in transmission-linked smart grid projects. Competitive moves concentrate on strategic partnerships with distribution network operators and portfolio diversification into behind-the-meter asset orchestration.
Within the integrated technology tier, Siemens AG and Schneider Electric SE occupy positions exemplifying the convergence of operational technology and information technology stacks. ABB represents the specialized engineering archetype focused on transmission-linked infrastructure. Landis+Gyr Group AG and Hitachi Ltd sit within the metering and sensing equipment segment where cellular-connected device deployment volumes dominate procurement patterns. These companies anchor competitive positioning across the functional spectrum from passive data collection through active network control.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Landis+Gyr Group AG |
| E.ON SE |
| Efacec Energia |
| Hitachi Ltd |
| EdF Energy |
| Siemens AG |
| ABB |
| SSE PLC |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in transformer manufacturing across South Korea and Japan is compressing supplier margins while amplifying pricing leverage for semiconductor-based protection relay vendors serving UK distribution networks. This utilization asymmetry is forcing procurement officers to accept longer lead times for conventional switchgear while accelerating migration toward digital substation architectures that reduce copper dependency.
Pricing Analysis
Price spreads between cellular-connected AMI endpoints and full-scale grid optimization platforms now exceed threefold across England's urban procurement clusters. Project-based contracting dominates utility-scale deployments, with Ofgem's RIIO-ED2 efficiency mandates intensifying cost compression in standard-tier automation hardware. Price differentiation hinges on IEC 61850 certification tier and after-sales engineering support bundling. Industrial buyers in the Manchester-Birmingham corridor exhibit highest price sensitivity, while transmission-linked digital substation projects show lowest elasticity due to SCADA integration complexity.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for power electronics and rare earth magnet procurement. Manufacturing concentrates in China, Germany, and South Korea for IGBT modules, merging units, and process bus equipment. Raw material dependencies center on copper cathodes, neodymium-dysprosium alloys, and silicon carbide wafers. Single-source vulnerability in semiconductor fabrication constrains deployment velocity for software-defined protection systems. Distribution runs through authorized system integrators holding NCSC cybersecurity certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RIIO-ED2's innovation stimulus mechanism is compressing traditional asset replacement cycles and forcing a technology-led disruption across UK distribution networks. This regulatory inflection creates asymmetric opportunity for vendors capable of demonstrating quantifiable carbon reduction outcomes.
For Market Incumbents: Insulate core revenue streams by deepening captive production of digital substation software stacks and securing exclusive channel partnerships with Scottish and Welsh network operators facing renewable integration pressure. Prioritize NCSC certification investment to extend approval timelines that block challenger entry.
For New Entrants and Emerging Players: Pursue whitespace in Welsh valley rural electrification and vehicle-to-grid convergence platforms where incumbent automation portfolios lack coverage. The Scottish Highlands microgrid segment offers lowest competitive density. Lead with flexibility-market aggregation software that bypasses hardware-heavy procurement cycles.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across behind-the-meter DERMS deployment as software-as-a-service models displace capital expenditure frameworks. Five-to-ten year viability favors platform plays with recurring revenue visibility over project-dependent engineering services. Monitor Ofgem's Future System Operator transition timeline as the critical inflection signal for procurement accountability reconfiguration.
| Strategic Initiative | Industry Significance |
|---|---|
| Grid Optimization Platform Integration | Consolidates SCADA visibility across England's aging urban substation infrastructure. |
| Demand Response Aggregation Partnership | Captures National Grid ESO flexibility payments from Manchester-Birmingham industrial loads. |
| NCSC Cybersecurity Certification Pathway | Accelerates software-defined protection system approval timelines under critical infrastructure standards. |
| Welsh Microgrid Demonstration Deployment | Validates battery storage architectures in BEIS-funded rural electrification programs. |
| Vehicle-to-Grid Infrastructure Convergence | Opens channel relationships between automakers and distribution network operators. |
Research Methodology
A spread of perspectives from distribution network planning officers, flexibility market platform engineers, SCADA integration specialists, and Ofgem regulatory affairs leads converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against RIIO-ED2 innovation stimulus disclosures, National Grid ESO procurement databases, and IEC standards documentation. Bottom-up deployment tracking across England, Scotland, and Wales triangulated against top-down utility capital expenditure forecasts.
Demand-supply balance modeling anchored projections across the analysis window, with segmentation by technology maturity, application criticality, and end-user procurement authority. CAGRs derived from deployment velocity curves weighted by Ofgem-mandated efficiency targets and renewable penetration trajectories. Forecast inputs incorporated copper price volatility scenarios and protection engineering labor supply constraints.
Sensitivities concentrate around RIIO-ED2 framework revisions, semiconductor lead time disruptions, and Future System Operator transition timing. Forecasts reflect documented assumptions regarding regulatory stability and technology substitution rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
Smart Grid Network Market
Smart Grid
Smart Demand Response Market
Smart Grid
United States Smart Grid Security Market
Smart Grid
Smart Grid Data Management Market
Smart Grid
Smart Grid Communications Market
Smart Grid
India Smart Grid Network Market
Smart Grid
Microgrid Market
Smart Grid
United Arab Emirates Smart Grid Market
Smart Grid
Saudi Arabia Smart Grid Market
Smart Grid
Smart Grid Market
Smart Grid
Smart Grid Sensors Market
Smart Grid
Smart Microgrid Controller Market
Smart Grid
Smart Grid Technology Market
Smart Grid
Asia-Pacific Smart Grid Network Market
Smart Grid
Smart Energy Switch Market
Smart Grid
South Africa Smart Grid Network Market