
 South America Transformer Market | 2026-2036
South America Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
South America Transformer Market Insights
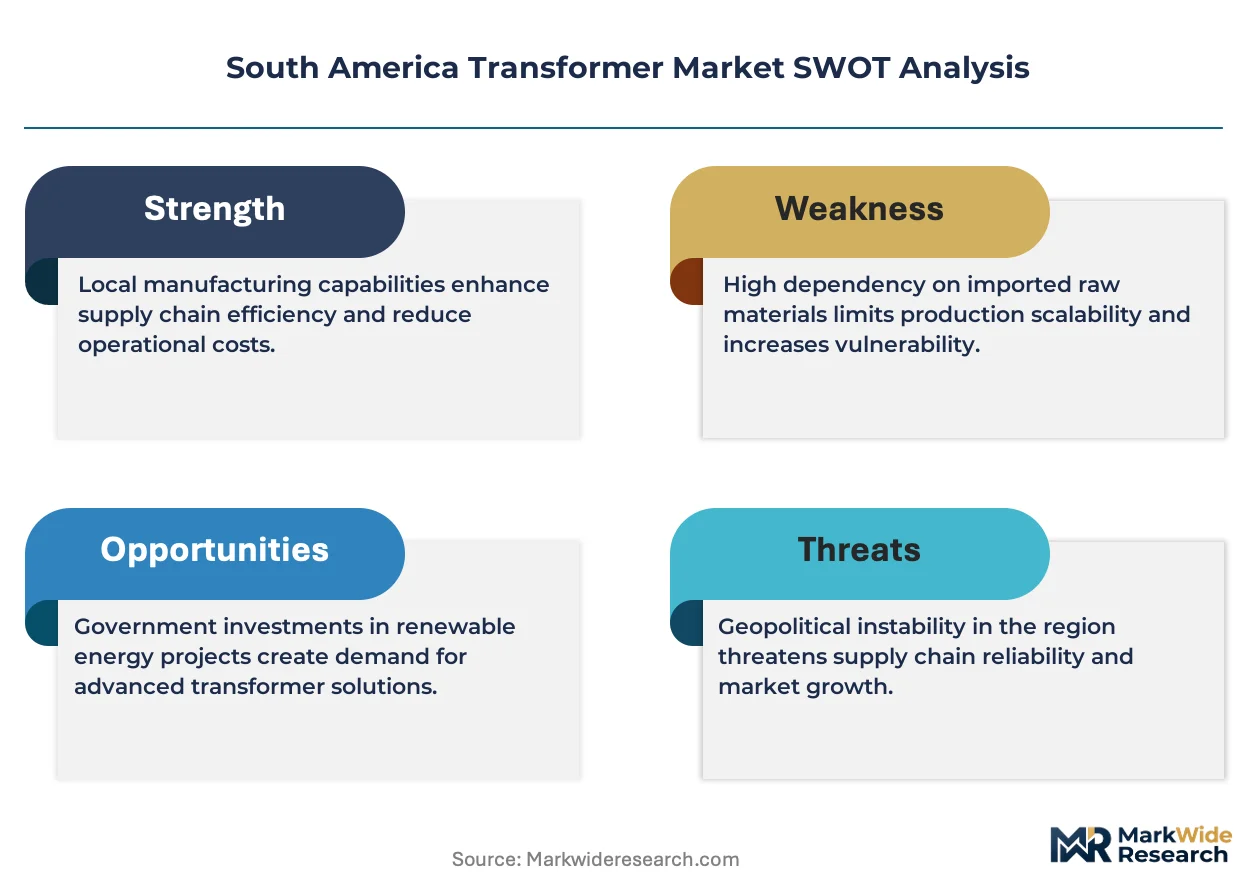
Maintenance and lifecycle service contracts is broadening what transformer vendors monetize beyond unit sales. WEG S.A. leverages its Brazilian manufacturing footprint to anchor service agreements across utilities in São Paulo and Rio de Janeiro. Siemens Energy competes through technology leadership in digital monitoring systems that reduce outage frequency for grid operators. Prolec GE sustains geographic dominance in Mexico-linked supply chains that extend into Central Andean markets.
A transformer is an electromagnetic static device that transfers electrical energy between circuits through mutual induction, typically operating at frequencies of 50-60 Hz with voltage ratings spanning 11 kV to 800 kV depending on application. Its core function is to step voltage up for efficient long-distance transmission or step it down for safe industrial and residential distribution. Distribution transformers occupy the largest installed base across South America due to sprawling rural electrification programs and urban grid densification, though power transformers command the deepest margin pools where utilities prioritize reliability over first cost. Renewable energy end users represent the fastest-expanding demand category as wind and solar projects in Chile's Atacama and Brazil's Northeast require specialized step-up units.
Brazil's ANEEL imposes efficiency standards that disqualify older oil-immersed designs from new utility procurement, while Argentina's ENRE mandates technical compliance certificates for imported equipment. IEC standards and local INMETRO certification requirements shape product specifications for manufacturers seeking cross-border sales within Mercosur. Stakeholders must monitor how regulatory divergence between national energy agencies affects standardization costs and supplier qualification timelines.
Market Dynamics
ANEEL's efficiency mandates are forcing accelerated replacement of oil-immersed transformer fleets across Brazilian utilities, while renewable interconnection requirements in Chile and Argentina reshape procurement specifications toward higher-capacity step-up units.
Growth Catalysts
- Grid Modernization Mandates:ANEEL's regulatory standards disqualify aging transformer designs from new procurement, compelling utilities across São Paulo and Minas Gerais to upgrade installed capacity.
- Renewable Energy Interconnection:Wind and solar developers in Chile's Atacama and Brazil's Northeast require specialized step-up transformers for utility-scale project integration.
- Rural Electrification Programs:Distribution transformer deployment accelerates across Argentina's northern provinces and Brazil's interior to close connectivity gaps.
Market Restraints
- Raw Material Volatility:Electrical steel and copper price swings compress transformer manufacturing margins and destabilize long-term contract pricing.
- Import Dependency for Core Components:South American manufacturers rely on Asian suppliers for grain-oriented electrical steel, exposing lead times to maritime logistics disruptions.
- Technical Limitation in Extreme Altitude:Standard transformer cooling designs face derating challenges in Bolivia's Altiplano and Peru's highland mining operations.
Strategic Opportunities
- Digital Monitoring Integration:IoT-enabled transformer health monitoring creates aftermarket service revenue streams for vendors serving grid operators.
- Argentina's Underserved Distribution Network:ENRE compliance pathways open qualified foreign suppliers to replace aging infrastructure in Buenos Aires and Córdoba provinces.
- Biodegradable Insulating Fluids:Natural ester dielectrics meet emerging environmental standards while extending transformer operational lifespan in tropical climates.
Industry Challenges
- Certification Timeline Compression:INMETRO and ENRE testing protocols extend product qualification cycles, delaying revenue recognition for new market entrants.
- Specialized Winding Technician Scarcity:Precision transformer manufacturing requires skilled labor pools that remain concentrated in São Paulo's industrial corridor.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Transformer Market |
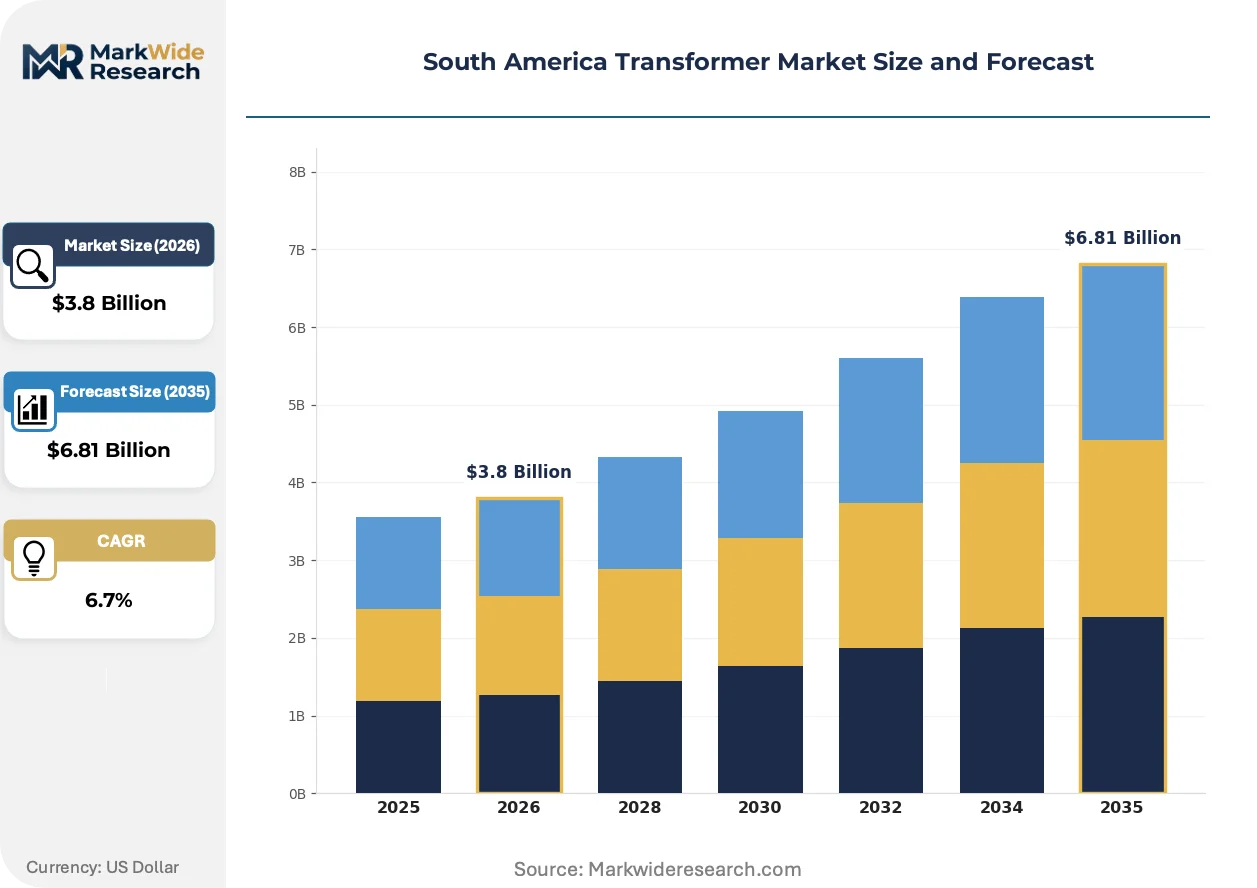
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Distribution Transformer, Power Transformer, Isolation Transformer, Instrument Transformer End User: Utilities, Manufacturing, Construction, Renewable Energy Installation: Indoor, Outdoor, Substation, Pole-Mounted Technology: Liquid-Immersed, Dry-Type, Gas-Insulated, High-Voltage |
| Companies Covered | WEG S.A., Prolec GE, Siemens Energy, Hitachi Energy, Schneider Electric, ABB Ltd., GE Vernova, Eaton Corporation, Toshiba Corporation, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Transformer Market Trends and Innovations
Dry-type transformer technology is gaining traction across South American utilities seeking reduced fire risk and simplified maintenance protocols in dense urban installations.
Cast resin insulation systems eliminate oil containment requirements while enabling indoor substation configurations in São Paulo and Rio de Janeiro metropolitan areas. Brazilian utilities are adopting these units for underground distribution networks at accelerating rates. This technology is decentralizing transformer placement from peripheral substations into building-integrated installations.
ANEEL's efficiency certification program mandates minimum performance thresholds that exclude conventional silicon-steel core designs from new procurement. Industrial buyers must now specify amorphous metal or high-permeability grain-oriented steel to qualify for grid connection permits. Distribution transformer procurement across Brazil's Southeast corridor faces the steepest compliance cost adjustments.
Integrated service contracts now bundle transformer supply with predictive maintenance and lifecycle asset management. Brazilian utilities in the Southeast industrial corridor are unbundling capital expenditure from operational budgets through multi-year performance agreements. Chilean renewable developers pioneered this structure for Atacama solar farms and now extend it to wind installations in Biobío region.
South America Transformer Market Segmentation
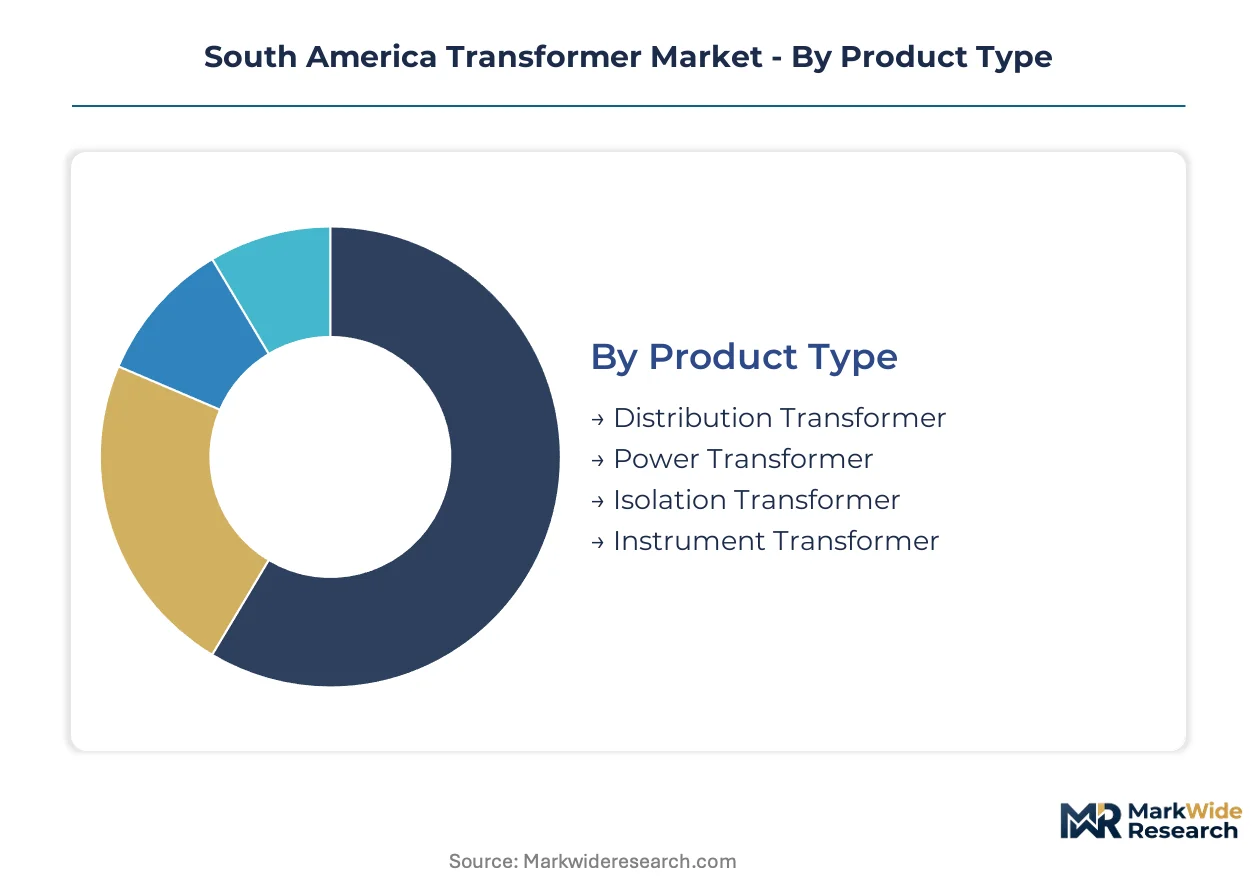
Transformer procurement patterns across South America diverge sharply by application environment and grid integration requirements. Product specifications must reconcile ANEEL efficiency mandates with altitude constraints in Andean mining corridors and tropical humidity in Amazon basin deployments.
Product Type:
Supply concentration for core materials shapes competitive positioning across transformer categories, with grain-oriented electrical steel procurement determining manufacturing feasibility for high-capacity units.
- Distribution Transformer:These units step down medium-voltage transmission to consumer-level voltages across 11-36 kV ratings. Brazil's rural electrification programs and Argentina's northern province connectivity initiatives concentrate demand for pole-mounted and pad-mounted configurations. ANEEL efficiency mandates disqualify conventional silicon-steel cores from new procurement, forcing amorphous metal adoption in São Paulo and Minas Gerais utility fleets.
- Power Transformer:High-capacity units rated 69 kV to 800 kV anchor transmission backbone infrastructure and renewable interconnection nodes. Chile's Atacama solar farms and Brazil's Northeast wind corridors require specialized step-up designs with enhanced thermal management for desert and coastal humidity exposure.
- Isolation Transformer:Galvanic separation units protect sensitive industrial equipment from voltage transients and ground loops. São Paulo's automotive and electronics manufacturing clusters specify these for production line power quality assurance.
- Instrument Transformer:Current and potential transformers enable metering and protection relay functions across substation automation systems. Grid modernization investments in Rio de Janeiro and Buenos Aires drive replacement cycles for electromechanical units with digital-grade accuracy classes.
Today's leader: Distribution Transformer. Tomorrow's challenger: Power Transformer.
End User:
Customer procurement sophistication determines contract structures, with utilities favoring lifecycle service bundles while industrial buyers prioritize capital expenditure minimization.
- Utilities:Grid operators across Brazil's Southeast corridor and Argentina's Buenos Aires province deploy capital-intensive replacement programs for aging oil-immersed fleets. ANEEL and ENRE compliance pathways favor vendors offering integrated asset management over standalone equipment sales.
- Manufacturing:São Paulo's automotive and food processing sectors specify dry-type units for indoor substations with reduced fire risk profiles. Voltage stability requirements in precision manufacturing drive demand for isolation and voltage regulation transformers.
- Construction:Temporary power infrastructure for commercial and residential developments in Santiago and Bogotá relies on mobile substation configurations. Project-based procurement cycles create demand volatility tied to building permit issuance rates.
- Renewable Energy:Utility-scale solar and wind developers in Chile's Atacama and Brazil's Pernambuco require step-up transformers with desert-rated cooling systems and salt spray corrosion resistance. This segment is climbing the fastest as auction mechanisms accelerate project commissioning timelines.
Current procurement dominance: Utilities. Emerging volume shift: Renewable Energy.
Installation:
Physical deployment constraints dictate cooling system selection and fire safety compliance, with urban density pushing technology choices toward reduced-risk configurations.
- Indoor:Dry-type and cast resin units eliminate oil containment requirements for building-integrated substations in São Paulo and Rio de Janeiro metropolitan cores. ANEEL fire safety regulations accelerate substitution of oil-immersed designs in underground distribution networks.
- Outdoor:Conventional oil-immersed and dry-type units populate utility substations across Brazil's interior and Argentina's pampas regions. Climate exposure ranges from tropical humidity in Amazon basin deployments to freeze-thaw cycling in Patagonian wind farms.
- Substation:Centralized transformation hubs at 138 kV and 230 kV levels aggregate distribution feeders for urban load centers. Chile's SIC and SING grid interconnection projects expand high-voltage substation deployment in Antofagasta and Coquimbo regions.
- Pole-Mounted:Single-phase and small three-phase units extend rural distribution reach across Brazil's Northeast and Colombia's coffee-growing departments. Lightweight core designs reduce structural loading on wooden and concrete support structures.
Deployment standard: Outdoor. Regulatory momentum: Indoor.
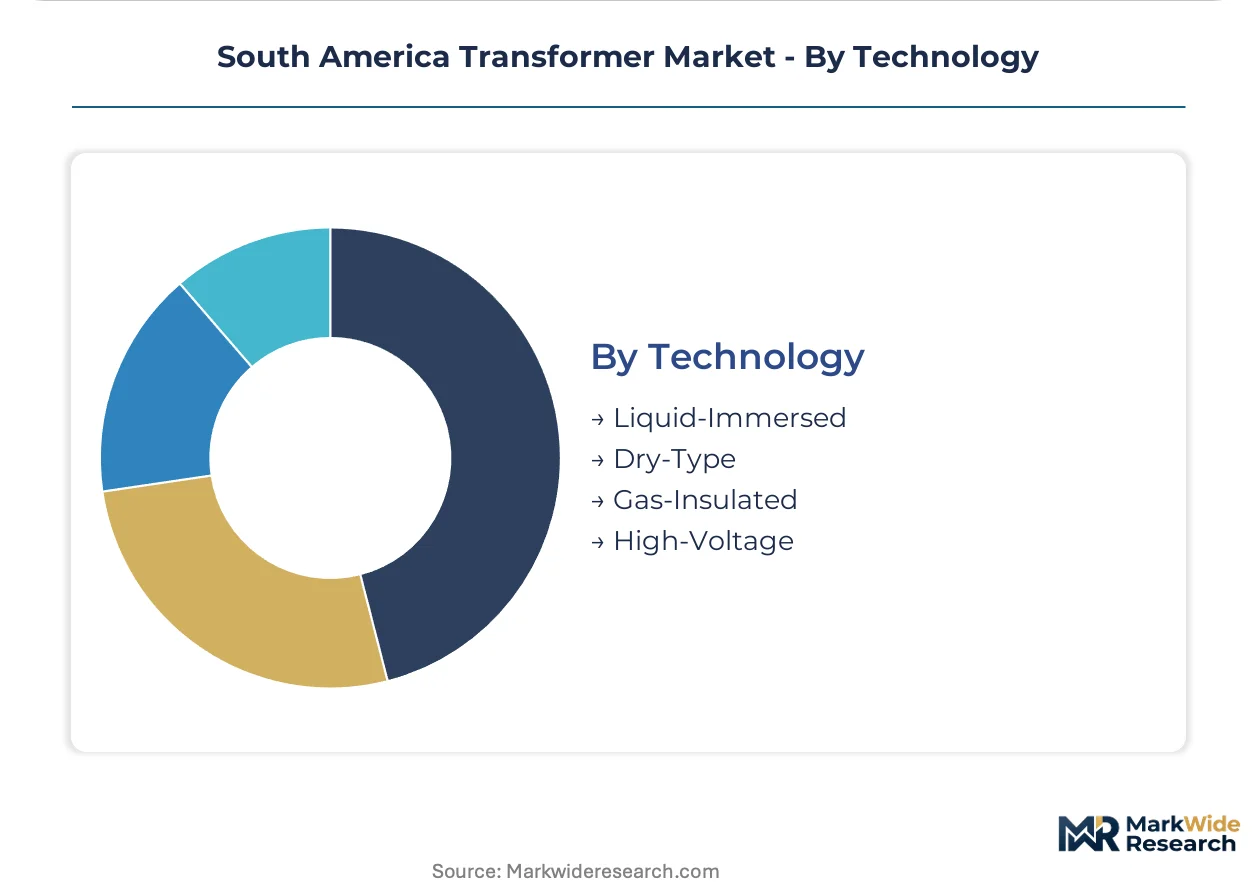
Technology:
Insulation medium selection determines environmental compliance pathways and operational lifespan in tropical and high-altitude conditions.
- Liquid-Immersed:Mineral oil and natural ester dielectrics dominate high-capacity power transformer designs for transmission and renewable interconnection. ANEEL efficiency standards and emerging biodegradable fluid requirements reshape procurement specifications for Brazilian utilities.
- Dry-Type:Cast resin and vacuum pressure impregnated windings enable indoor installations with eliminated fire risk and simplified maintenance protocols. São Paulo's underground distribution densification programs adopt these units at accelerating rates.
- Gas-Insulated:SF6 and emerging fluoronitrile mixtures enable compact high-voltage designs for space-constrained urban substations. Environmental regulations in Chile and Argentina constrain SF6 deployment despite superior dielectric performance.
- High-Voltage:Specialized designs rated 345 kV and above serve long-distance transmission corridors and cross-border interconnection projects. Brazil's Belo Monte transmission lines and Argentina-Chile interconnection nodes require altitude-compensated cooling systems.
Established base: Liquid-Immersed. Regulatory displacement target: Dry-Type.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands the deepest transformer procurement volumes across South America, while Chile's renewable interconnection surge is compressing project timelines for specialized step-up units. Argentina's distribution network rehabilitation lags both neighbors due to currency instability and import financing constraints.
Brazil
São Paulo and Minas Gerais states anchor utility-scale replacement programs for aging oil-immersed fleets. ANEEL's efficiency certification mandates disqualify conventional silicon-steel core designs from new grid connection permits. WEG S.A. leverages its domestic manufacturing footprint to secure integrated service agreements across the Southeast industrial corridor.
Chile
Atacama solar farms and Biobío wind installations require desert-rated cooling systems and salt spray corrosion resistance. The national energy commission's renewable auction mechanisms accelerate commissioning timelines for step-up transformer procurement. Antofagasta and Coquimbo regions concentrate high-voltage substation deployment for SIC and SING grid interconnection projects.
Argentina
Buenos Aires and Córdoba provinces present replacement demand for aging distribution infrastructure. ENRE mandates technical compliance certificates for imported equipment, extending qualification cycles for foreign suppliers. Currency volatility constrains utility capital expenditure planning despite ENRE's network modernization directives.
Colombia
Bogotá's commercial construction sector drives mobile substation demand tied to building permit issuance rates. The national mining regulator's safety standards push underground operations toward dry-type transformer adoption for fire risk mitigation. Coffee-growing departments in the Andean interior extend rural distribution reach through pole-mounted unit deployment.
Peru
Highland mining operations in the central Andes confront altitude derating challenges for standard cooling designs. The Ministry of Energy and Mines prioritizes electrification corridors linking remote extraction sites to transmission backbones. Lima's metropolitan grid densification programs adopt cast resin units for indoor substation configurations.
South America Transformer Market Competitive Landscape
Top-tier vendors anchor integrated service contracts, while mid-scale fabricators compete on regional certification speed. The vendor base clusters around three strategic archetypes: Brazilian domestic manufacturers with utility relationships, European-headquartered technology licensors with digital monitoring portfolios, and Asian industrial conglomerates with scale-driven cost positions. Competitive moves concentrate on backward integration into electrical steel sourcing and predictive maintenance platform development.
Among Brazil-based industrial groups, WEG S.A. exemplifies the domestic manufacturing archetype with anchored service agreements. Siemens Energy occupies a position representing European technology leadership in grid monitoring systems. Prolec GE sits within the Mexico-linked supply chain tier extending into Andean markets. These three company profiles illustrate how geographic manufacturing footprint, technology specialization, and regional logistics integration shape competitive positioning across procurement cycles.
| Leading Market Players |
|---|
| WEG S.A. |
| Prolec GE |
| Siemens Energy |
| Hitachi Energy |
| Schneider Electric |
| ABB Ltd. |
| GE Vernova |
| Eaton Corporation |
| Toshiba Corporation |
| Others |
Pricing and Supply Chain Analysis
Amorphous metal core adoption in Brazil's Southeast corridor simultaneously elevates unit production costs and concentrates transformer manufacturing among qualified suppliers. ANEEL efficiency mandates disqualify conventional silicon-steel designs, forcing utilities to absorb premium pricing for certified equipment while narrowing the vendor pool to domestic fabricators with INMETRO-approved winding capabilities.
Pricing Analysis
Capacity additions in Brazil's industrial corridor are reshaping price floors for distribution transformers. Three-tier pricing structure across premium certified, standard compliant, and economy replacement levels segments procurement by ANEEL certification grade and bundled service intensity. Cost compression in the economy tier is intensifying because raw material volatility in electrical steel and copper destabilizes long-term contract pricing. Renewable energy developers exhibit the least price sensitivity due to project finance structures that amortize equipment costs, while municipal utilities in Argentina's northern provinces face acute budget constraints.
Supply Chain Analysis
Dual-sourcing requirements from Brazilian utilities mandate multi-supplier qualification for grain-oriented electrical steel, yet procurement teams remain tethered to Asian mills in Japan, South Korea, and China for high-permeability core materials. Critical dependencies extend to copper winding wire from Chilean smelters and cast resin insulation compounds from specialized European chemical producers. Single-source vulnerability in maritime logistics for electrical steel exposes lead times to Panama Canal congestion and Pacific port bottlenecks. Distribution runs through manufacturer-direct contracts with integrated service agreements, bypassing traditional electrical distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service contract bundling represents a margin-expansion story for transformer vendors, as ANEEL-mandated lifecycle management shifts revenue from transactional equipment sales toward recurring maintenance streams.
For Market Incumbents: Cement dominance in Brazil's Southeast corridor by locking multi-year performance agreements with CEMIG and Eletropaulo before efficiency certification deadlines accelerate. Backward integration into electrical steel trading desks mitigates raw material volatility that threatens margin stability. Digital monitoring platform development defends against European technology licensors encroaching on predictive maintenance revenue pools. For New Entrants and Emerging Players: Regional EPC contractors serving Chilean renewable auctions offer the fastest channel to utility-scale step-up transformer deployment without established utility relationships. Argentina's ENRE compliance backlog creates qualification arbitrage for foreign suppliers willing to absorb extended testing timelines. White-space concentration sits in biodegradable insulating fluid retrofit programs for tropical-climate utilities seeking extended asset lifespan. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale Brazilian fabricators lacking integrated service platforms but holding ANEEL certification and São Paulo industrial corridor real estate. Long-term viability hinges on regulatory enforcement durability across successive political cycles in Brasília. The signal to watch is ENRE's pace of technical compliance certificate issuance, which would unlock Argentine distribution network replacement demand. Deviation in ANEEL's efficiency mandate implementation timeline would shift the outlook materially.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrical Steel | Captive supply of grain-oriented steel insulates Brazilian manufacturers from Asian maritime logistics disruptions. |
| Digital Monitoring Platform Launch | IoT-enabled health diagnostics create recurring revenue streams beyond unit sales for grid operators. |
| Natural Ester Fluid Certification | Biodegradable dielectrics meet emerging environmental standards while extending operational lifespan in tropical climates. |
| Renewable Auction Partnership | Early engagement with Chilean solar and wind developers secures step-up transformer allocation before commissioning deadlines. |
| Service Contract Unbundling | Multi-year performance agreements separate capital expenditure from operational budgets for Brazilian utilities. |
Research Methodology
Coverage spans Brazil, Chile, Argentina, Colombia, and Peru, with primary inputs from each national market. Utility planning officers, IPP project developers, EPC contractors, and aftermarket service heads provided structured interviews on procurement cycles and specification evolution. Secondary validation drew from ANEEL regulatory filings, ENRE technical bulletins, customs trade data for electrical steel imports, and utility capital expenditure disclosures. Bottom-up unit deployment estimates triangulated against top-down grid investment forecasts.
Rate-of-change decomposition anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user category, installation environment, and cooling technology. CAGRs derived from regression analysis of historical replacement cycles, renewable interconnection timelines, and regulatory compliance deadlines. Industry-specific inputs incorporated ANEEL efficiency certification adoption curves and Chilean renewable auction award trajectories.
Revisions become necessary when raw material price volatility exceeds historical bands or maritime logistics disruptions extend electrical steel lead times beyond contingency planning horizons. Deviation in ANEEL's enforcement posture toward silicon-steel core disqualification would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Step Up/Down Transformers Market
Transformers
North America Power Transformer Market
Transformers
Asia-Pacific Power Transformer (Below 100 MVA) Market
Transformers
Renewable Energy Transformer Market
Transformers
United States Distribution Transformer Market
Transformers
Green Transformer Market
Transformers
Box Transformer Substation Market
Transformers
Electric Vehicle Charging Station Transformer Market
Transformers
North America Smart Transformers Market
Transformers
Amorphous Core Transformers Market
Transformers
North America Oil Filled Transformer Market
Transformers
Industrial Control Transformers Market
Transformers
Oil Immersed Transformer and Dry Type Transformer Market
Transformers
Europe Telecom Transformers Market
Transformers
Middle East Distribution Transformer Market
Transformers
Saudi Arabia Transformer Market