
 Gas Insulated Transformer Market | 2026-2036
Gas Insulated Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Insulated Transformer Market Intelligence
Power purchase agreement-backed leasing and asset-light service contracts is rewriting capital deployment for gas insulated transformers, enabling utilities to defer ownership burdens while locking in long-term maintenance coverage. Siemens Energy leverages its broad service portfolio to anchor recurring revenue streams across European utility fleets. Hitachi Energy competes through integrated digital monitoring platforms that extend equipment lifecycle value. Toshiba Energy Systems specializes in compact designs for dense Asian metropolitan corridors.
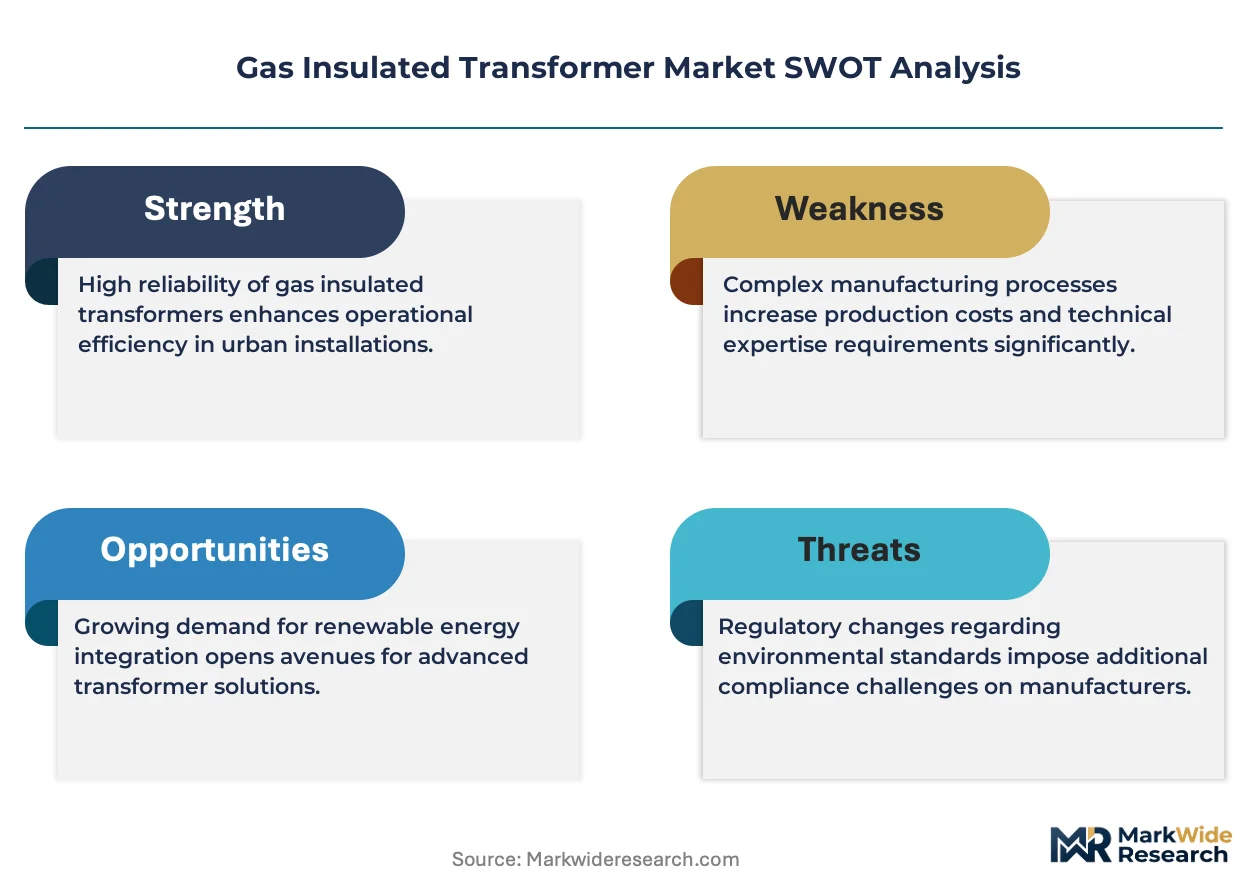
A gas insulated transformer encloses windings and core within a sealed tank pressurized with insulating gas—historically sulfur hexafluoride at 0.4-0.6 MPa—to achieve dielectric strength far exceeding oil or air alternatives in roughly one-third the footprint. Its primary purpose serves space-restricted indoor substations, underground vaults, and coastal installations where fire risk or environmental exposure prohibits conventional liquid-filled units. High voltage designs dominate margin pools given engineering complexity and utility-scale project values, while solid insulation technology gathers momentum as fluorinated gas restrictions tighten across multiple jurisdictions. Renewable energy end users represent the fastest-expanding installation base, driven by offshore wind collector platforms requiring salt-resistant, compact transformation.
Europe's ECHA enforces F-Gas Regulation phase-down schedules that directly constrain SF6 procurement volumes, while Japan's METI promotes voluntary leakage monitoring protocols through industrial guidance. The US EPA maintains greenhouse gas reporting thresholds for electrical equipment that shape importer compliance costs and domestic refurbishment economics. Stakeholders must weigh insulation technology bets against regulatory trajectory uncertainty, as tomorrow's stranded asset risk hinges on gas chemistry choices made in today's specifications.
Market Dynamics
The Gas Insulated Transformer Market pivots on Europe's F-Gas Regulation phase-down, which forces immediate insulation chemistry transitions while utilities simultaneously demand higher power density for urban substations. This regulatory-technical tension compresses product development cycles and reshapes supplier R&D allocation.
Growth Catalysts
- Urban densification:Underground substations in Tokyo, Berlin, and Shanghai require compact transformation equipment that eliminates fire risk and oil containment systems.
- Offshore wind collector platforms:Salt-resistant gas insulation replaces conventional units on North Sea and East Asian turbine arrays where maintenance access is severely constrained.
- Japan's METI leakage protocols:Voluntary monitoring standards accelerate fleet replacement cycles and create pull-through demand for sealed-system designs with lower permeation rates.
Market Restraints
- SF6 supply rationing:Europe's ECHA phase-down quotas constrain gas procurement volumes, forcing manufacturers to absorb inventory risk or pass through scarcity premiums.
- Specialized winding fabrication:Epoxy-impregnated conductor production concentrates among German and Japanese suppliers, creating single-source vulnerability for high-voltage designs.
- Solid insulation performance gaps:Dry-type and vacuum alternatives currently fail to match sulfur hexafluoride dielectric strength above 145 kV, limiting addressable market scope.
Strategic Opportunities
- India's underground metro electrification:Fire-code restrictions in Delhi, Mumbai, and Bangalore substations create first-mover advantage for gas-insulated compact designs.
- Digital twin integration:Convergence of dissolved gas analysis sensors with cloud-based thermal modeling enables predictive maintenance contracts that extend equipment monetization horizons.
- US IRA manufacturing credits:Domestic content incentives for electrical infrastructure reshore procurement toward North American transformer assembly facilities.
Industry Challenges
- High-voltage test bay scarcity:Few facilities worldwide can validate 420 kV+ designs, extending certification timelines and constraining new entrant market access.
- Legacy GIS interoperability:Retrofit projects demand mechanical and electrical interface matching with 30-year-old installations, fragmenting engineering resources across customization work.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Insulated Transformer Market |
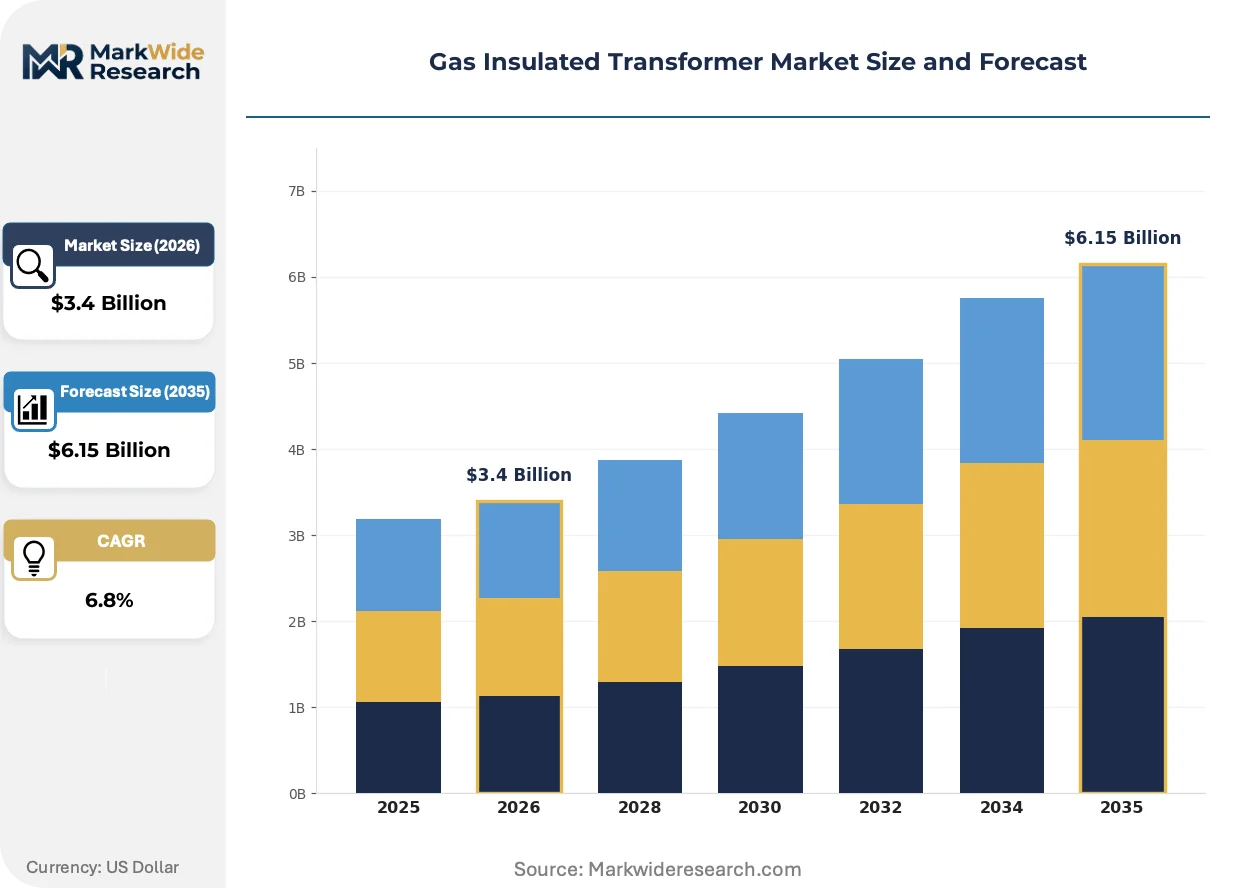
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Voltage, Medium Voltage, Low Voltage, Compact End User: Power Utilities, Commercial, Industrial, Renewable Energy Installation Type: Indoor, Outdoor, Hybrid, Modular Technology: Vacuum Insulation, SF6 Insulated, Solid Insulation, Others |
| Companies Covered | Hitachi Energy, Siemens Energy, GE Vernova, Mitsubishi Electric, Toshiba Energy Systems, MEIDENSHA CORPORATION, ARTECHE, Hyundai Electric, Fuji Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Insulated Transformer Market Strategic Shifts & Innovations
Insulation chemistry substitution and digital instrumentation integration are actively reconfiguring product architectures and service economics across the Gas Insulated Transformer Market. These shifts compress hardware margins while expanding recurring revenue attachment rates.
Solid dielectric systems using epoxy resin and vacuum interrupters are virtualizing the traditional gas-pressurized core design. Offshore wind developers in the North Sea and Baltic corridors adopt these units for nacelle and platform applications where SF6 containment carries regulatory liability. The technology is virtualizing maintenance scheduling by eliminating gas handling protocols and reducing inspection frequency.
Europe's F-Gas Regulation mandates 67% SF6 phase-down by 2030 from 2014 baseline levels, with quota allocation tied to verified leakage rates. Electrical equipment manufacturers face accelerated product redesign cycles to secure gas allocations for remaining high-voltage applications. German utilities now specify solid-insulation alternatives for all new 72.5 kV indoor installations regardless of technical preference.
Leasing structures with bundled lifecycle service are displacing conventional capital purchase models among European power utilities. Asset-light contracts transfer residual value risk to manufacturers while locking in 15-20 year maintenance revenue streams. This pattern concentrates in Germany and Scandinavia where municipal utility governance favors operational expenditure treatment over balance-sheet asset ownership.
Gas Insulated Transformer Market Segmentation
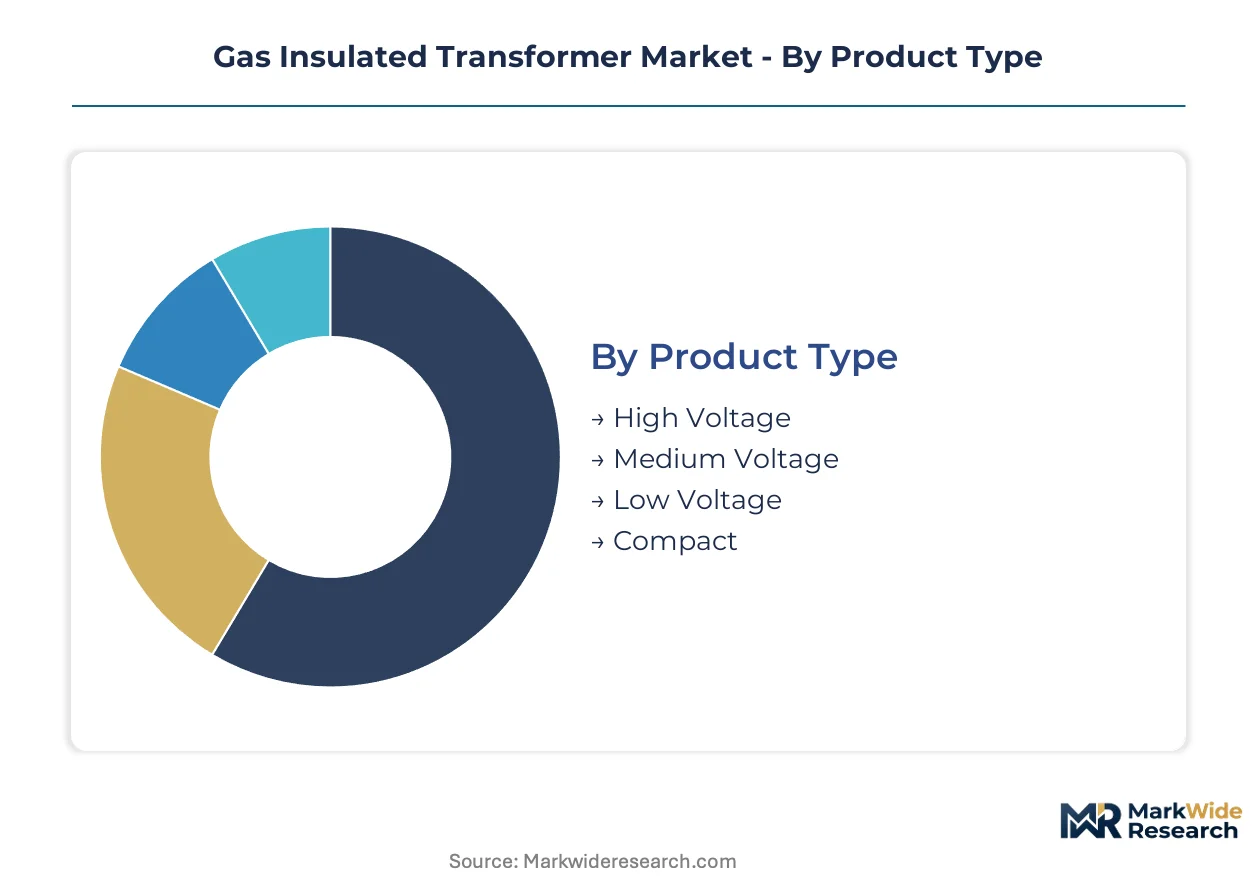
Segmentation in the Gas Insulated Transformer Market reveals how regulatory pressure and installation constraints fragment procurement patterns across voltage classes and insulation chemistries. Buyers select architectures based on spatial limitations, environmental exposure, and compliance timelines rather than cost optimization alone.
Product Type:
Mature high-voltage designs anchor utility-scale procurement while compact configurations emerge for dense urban corridors.
- High Voltage:Units rated above 145 kV enclose windings in pressurized sulfur hexafluoride tanks achieving dielectric strength exceeding oil alternatives. Offshore wind collector platforms in the North Sea and East Asian waters drive concentrated demand where salt exposure and maintenance access constraints eliminate conventional liquid-filled options.
- Medium Voltage:Designs spanning 36-145 kV balance footprint reduction with established supply chains. German utilities under ECHA phase-down quotas now specify solid-insulation alternatives for 72.5 kV indoor installations regardless of incumbent technical preference.
- Low Voltage:Compact below-grade vault installations in Tokyo and Shanghai metro systems favor sealed gas systems over dry-type alternatives.
- Compact:Ultra-dense configurations for underground substations in Berlin and Mumbai prioritize dimensional constraints over thermal margins.
High Voltage retains volume leadership; Compact holds the steepest expansion curve.
End User:
Customer concentration varies sharply across capital deployment models and regulatory exposure profiles.
- Power Utilities:Municipal and regional grid operators dominate procurement volumes through 15-20 year leasing structures with bundled lifecycle service. Scandinavian utilities favor operational expenditure treatment over balance-sheet ownership.
- Renewable Energy:Offshore wind developers adopt salt-resistant gas insulation for turbine nacelles and platform substations where SF6 containment carries regulatory liability.
- Industrial:Petrochemical and mining operations specify sealed systems for fire-code compliance in confined process areas.
- Commercial:Data center operators in Singapore and Frankfurt select compact indoor units for urban edge computing facilities.
Power Utilities command procurement volume; Renewable Energy climbs fastest on offshore wind buildouts.
Installation Type:
Physical deployment constraints dictate insulation chemistry and enclosure specifications.
- Indoor:Underground vaults and building-integrated substations in Tokyo, Berlin, and Shanghai require fire-risk elimination and oil containment waiver. Solid insulation technology gathers momentum as fluorinated gas restrictions tighten.
- Outdoor:Coastal installations in hurricane corridors specify pressurized gas systems for salt spray resistance and reduced maintenance intervals.
- Hybrid:Partially enclosed designs bridge indoor fire codes with outdoor thermal management for transitional urban sites.
- Modular:Factory-integrated skid packages accelerate deployment for rapid grid reinforcement projects.
Indoor commands the largest addressable scope; Modular gains share on speed-to-commissioning requirements.
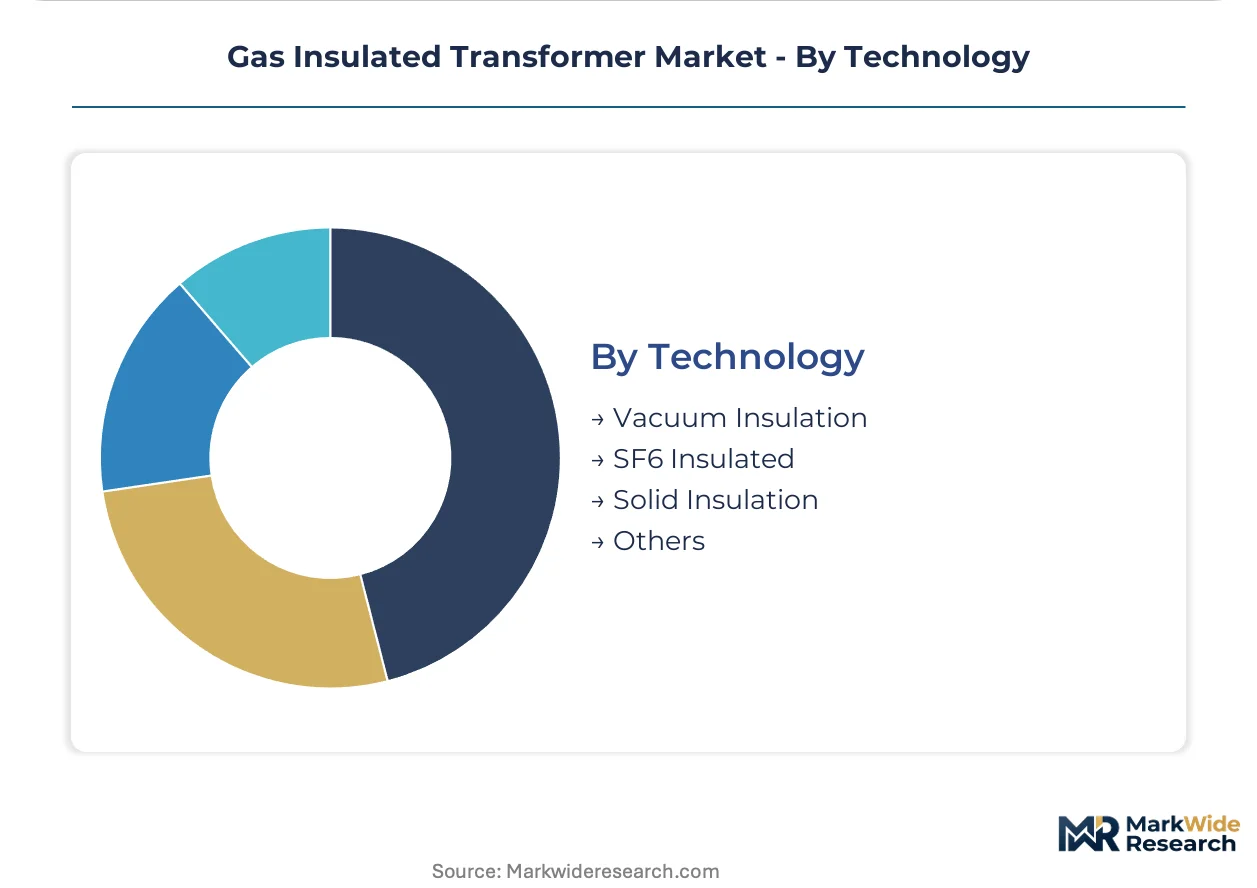
Technology:
Insulation chemistry selection now carries stranded asset risk as regulatory phase-downs accelerate.
- SF6 Insulated:Sulfur hexafluoride at 0.4-0.6 MPa delivers unmatched dielectric strength above 145 kV. ECHA quota allocation tied to verified leakage rates forces manufacturers into accelerated redesign cycles.
- Solid Insulation:Epoxy resin and vacuum interrupters eliminate gas handling protocols. North Sea offshore developers adopt these units to avoid regulatory liability exposure.
- Vacuum Insulation:Dry-type designs penetrate medium-voltage indoor applications where leakage monitoring is operationally prohibitive.
- Others:Alternative gas mixtures and fluoronitrile blends occupy niche pilot installations pending long-term performance validation.
SF6 Insulated maintains installed base dominance; Solid Insulation expands most quickly on regulatory displacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's F-Gas Regulation and Japan's METI leakage protocols are accelerating insulation chemistry transitions across major procurement markets. Utilities in dense metropolitan corridors drive concentrated demand for compact, fire-safe transformation equipment.
Germany
ECHA phase-down quotas constrain SF6 procurement volumes for high-voltage installations. Municipal utilities in Berlin and Hamburg now mandate solid-insulation specifications for all new 72.5 kV indoor substations regardless of technical preference. The Ruhr industrial corridor sustains replacement demand for aging underground infrastructure.
Japan
Tokyo Metro's fire-code restrictions eliminate oil-filled alternatives in below-grade vaults across the capital region. METI voluntary leakage monitoring protocols accelerate fleet replacement cycles among regional utilities. Osaka-Kansai corridor utilities prioritize sealed-system designs with lower permeation rates for coastal exposure.
China
State Grid Corporation drives procurement volumes for urban underground substations in Shanghai and Beijing where space constraints dominate. National dual carbon goals pressure SF6 containment standards for new coastal wind collector platforms. Yangtze River Delta manufacturing clusters supply epoxy-impregnated winding components for domestic and export markets.
United States
EPA greenhouse gas reporting thresholds shape importer compliance costs and domestic refurbishment economics. Offshore wind developers along the Atlantic coast specify salt-resistant gas insulation for turbine collector platforms. Texas and California grid operators evaluate modular factory-integrated packages for rapid urban reinforcement projects.
India
Underground metro electrification in Delhi, Mumbai, and Bangalore creates first-mover demand for fire-code-compliant compact designs. Central Electricity Authority guidelines on urban substation safety tighten oil containment requirements. Gujarat and Maharashtra industrial corridors specify sealed systems for petrochemical process areas with confined space exposure.
Gas Insulated Transformer Market Key Industry Players
On the supply side, the industry is consolidating around integrated energy conglomerates with captive high-voltage test capabilities and long-term utility service relationships. Tiered competitive positioning separates full-lifecycle service providers from component specialists and regional assembly houses. Two strategic archetypes dominate: diversified industrial electrification platforms and transformer-focused engineering specialists. Capacity expansion in solid-insulation fabrication and technology licensing for alternative gas mixtures represent the primary competitive moves reshaping supplier positioning.
Among diversified industrial electrification platforms, Hitachi Energy and Siemens Energy exemplify the integrated service-provider archetype. Siemens Energy leverages its broad service portfolio to anchor recurring revenue streams across European utility fleets through power purchase agreement-backed leasing structures. Hitachi Energy competes through integrated digital monitoring platforms that extend equipment lifecycle value for utility-scale deployments. Toshiba Energy Systems occupies a specialist position serving dense Asian metropolitan corridors with compact design expertise.
| Leading Market Players |
|---|
| Hitachi Energy |
| Siemens Energy |
| GE Vernova |
| Mitsubishi Electric |
| Toshiba Energy Systems |
| MEIDENSHA CORPORATION |
| ARTECHE |
| Hyundai Electric |
| Fuji Electric |
| Others |
Cost & Logistics Intelligence
Undercapacity in German epoxy-impregnated winding fabrication is compressing lead times for high-voltage designs and amplifying supplier pricing power across European utility procurement cycles. This utilization squeeze forces manufacturers to prioritize certified-tier buyers while passing scarcity premiums through contract structures.
Pricing Analysis
Certification level creates the primary spread between IEC 62271-203 compliant systems and non-certified alternatives, with CE-marked units commanding substantial premiums in ECHA-regulated markets. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling and leakage-rate guarantees rather than hardware differentiation alone. Cost compression in medium-voltage solid insulation tiers is intensifying because German utilities now mandate epoxy-resin specifications regardless of incumbent SF6 technical preference. Industrial end-users exhibit highest price sensitivity due to capital budget constraints, while offshore wind developers prioritize salt-resistance certification over unit economics.
Supply Chain Analysis
Single-source vulnerability in specialized conductor production concentrates among German and Japanese suppliers, exposing procurement timelines to geopolitical friction and capacity allocation decisions. Geographic supply concentration centers on Germany, Japan, and China for epoxy-impregnated windings, sulfur hexafluoride gas reclamation, and tank fabrication respectively. Raw material dependencies rest on high-purity aluminum conductor, sulfur hexafluoride gas stocks, and epoxy resin formulations subject to petrochemical feedstock volatility. Distribution runs through EPC contractor channels for utility-scale projects and direct OEM relationships for industrial retrofit applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Gas Insulated Transformer Market functions as a defensive-moat industry where regulatory entrenchment around ECHA quota allocation and high-voltage test bay scarcity protects incumbent positioning against price-based disruption.
For Market Incumbents: Pre-empt solid insulation technology transitions by acquiring German epoxy-impregnated winding specialists before capacity constraints harden into structural shortages. Anchor recurring revenue through 15-20 year leasing structures with bundled lifecycle service to lock out emerging competitors lacking balance-sheet depth for residual value absorption. Defensive consolidation around captive high-voltage test capabilities creates certification bottlenecks that fragment new entrant market access. For New Entrants and Emerging Players: India's underground metro electrification corridors offer the most penetrable white-space opportunity, where fire-code restrictions in Delhi, Mumbai, and Bangalore create first-mover demand without incumbent entrenched relationships. Target modular factory-integrated skid packages for rapid grid reinforcement projects where speed-to-commissioning outweighs brand preference. License solid insulation technology from European specialists to bypass SF6 quota allocation barriers and accelerate product qualification timelines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across solid insulation fabrication as ECHA phase-downs force capacity buildout in epoxy-impregnated winding production. Acquisition targets should emphasize German and Japanese engineering specialists with captive high-voltage test bay access and established utility service relationships rather than commodity assembly operations. Monitor ECHA quota allocation announcements as the critical inflection signal for stranded asset risk in remaining SF6-dependent portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Solid Insulation | Builds epoxy-impregnated winding fabrication to capture ECHA-driven substitution demand from German utilities. |
| Backward Integration into Conductor Production | Secures high-purity aluminum supply chains against German-Japanese single-source vulnerability. |
| Technology Licensing for Alternative Gas Mixtures | Transmits fluoronitrile blend expertise to offshore wind developers avoiding SF6 regulatory liability. |
| Long-term Service Contracting | Locks 15-20 year maintenance revenue streams through power purchase agreement-backed leasing structures. |
| Joint Venture for High-Voltage Test Access | Overcomes certification bottleneck scarcity through shared 420 kV+ validation facility investment. |
Research Approach
The analysis maps insulation chemistry transitions, voltage class procurement patterns, and end-user deployment models, each validated through utility planning officers, EPC contractor procurement leads, and aftermarket service directors. Primary fieldwork combined structured interviews with grid operators in Germany, Japan, and China alongside secondary validation through ECHA regulatory filings, IEC standard documentation, and customs trade data for transformer component flows. Bottom-up installation tracking triangulates against top-down utility capital expenditure disclosures.
Assumptions around ECHA phase-down quota enforcement, METI leakage protocol adoption, and offshore wind buildout trajectories were held fixed across baseline scenarios while sensitivity testing varied solid insulation performance improvement rates and alternative gas mixture commercialization timelines. Segmentation dimensions modeled span voltage class, insulation technology, installation type, and end-user vertical across the projection horizon. CAGRs derive from utility procurement pipeline analysis and renewable energy interconnection queue data.
Practitioners should monitor ECHA quota allocation revisions, solid insulation dielectric strength breakthroughs above 145 kV, and offshore wind project financing closures for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Neon Transformer Market
Transformers
South America Transformer Market
Transformers
India Transformer Market
Transformers
Step Up/Down Transformers Market
Transformers
Transformer Bobbin Market
Transformers
High Frequency Transformer Market
Transformers
United States Dry-Type Transformer Market
Transformers
HVDC Converter Transformers Market
Transformers
United States Distribution Transformer Market
Transformers
Rectifier Transformers Market
Transformers
North America Smart Transformers Market
Transformers
Oil Filled Transformer Market
Transformers
Europe Telecom Transformers Market
Transformers
Liquid-Immersed Transformers Market
Transformers
North America Transformer Market
Transformers
United States Transformer Market