
 US Oil Filled Distribution Transformer Market | 2026-2036
US Oil Filled Distribution Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
US Oil Filled Distribution Transformer Market Analysis
NEMA TP-1 and DOE efficiency qualification cycles is reorganizing competitive access across the supplier base. Hitachi Energy leverages its vertically integrated core steel and coil manufacturing to sustain cost discipline on large utility tenders. Schneider Electric anchors its position through digital monitoring integrations that extend transformer lifecycle value. Howard Industries competes aggressively in the Southeastern utility corridor where regional procurement preferences favor domestic assembly.
A US oil filled distribution transformer is a static electromagnetic device immersed in mineral oil or ester-based dielectric fluid, typically rated from 10 kVA to 50 MVA, designed to step down medium-voltage distribution levels to end-use voltages for commercial and industrial loads. The oil serves dual functions: electrical insulation and convective heat dissipation through wound copper or aluminum conductors sealed within a welded steel tank. Three-phase units dominate utility procurement due to economies of scale in substation and overhead line deployments, while single-phase models persist in rural residential extensions where load density does not justify three-phase infrastructure. Underground installation configurations command premium positioning as municipalities restrict overhead easements in dense urban zones, compressing available vendor pools for pad-mounted and vault-style designs.
The DOE Appliance and Equipment Standards Program, NEMA TP-1 efficiency protocols, and EPA spill prevention regulations under 40 CFR 112 collectively govern product design, loss thresholds, and fluid containment architectures. DOE's amended efficiency tiers have eliminated margin-viable production of older core designs, forcing capital retooling across domestic foundries and core-cutting operations. Stakeholders must monitor state-level integrated resource plans and interconnection queue backlogs to anticipate transformer procurement waves before manufacturing lead times extend beyond grid deployment schedules.
Market Dynamics
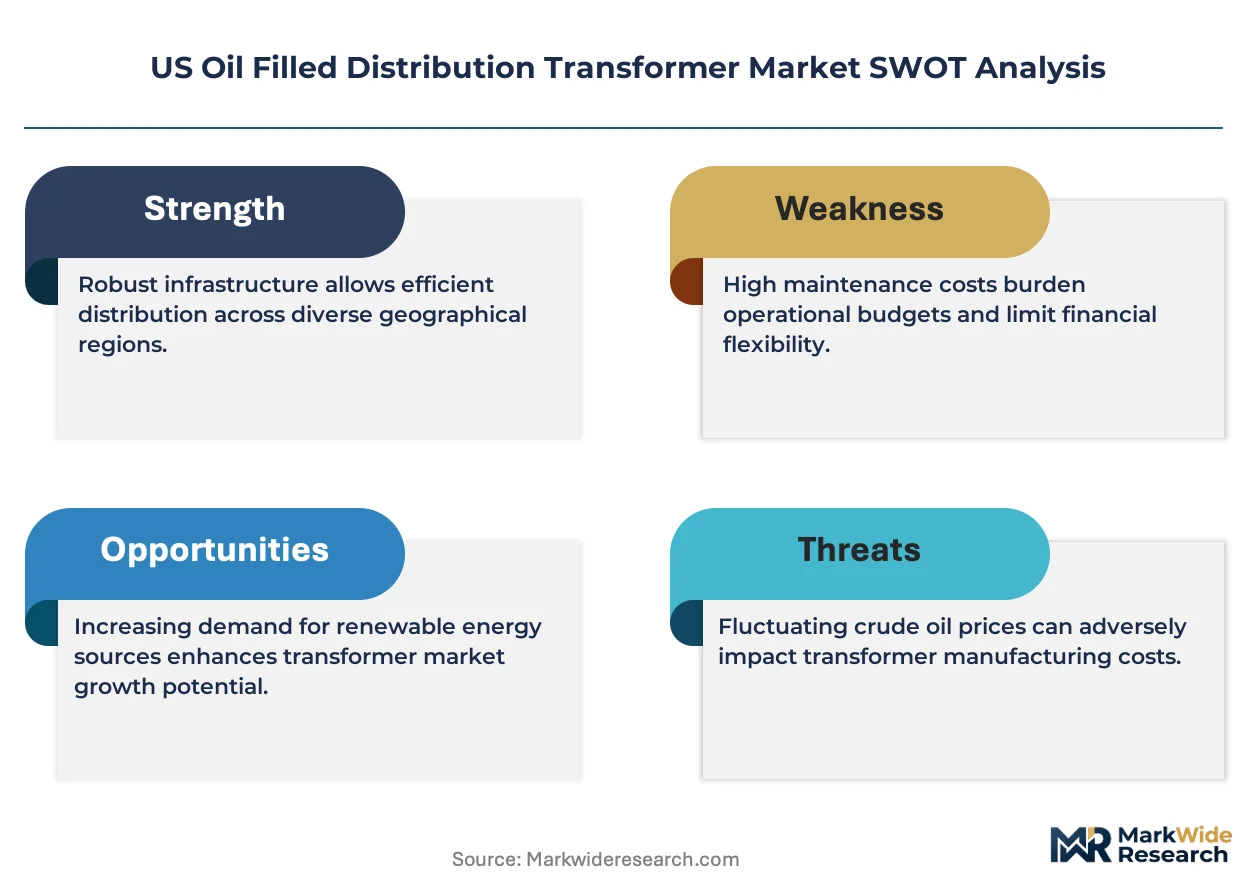
Grid modernization mandates from state public utility commissions are compressing replacement cycles for aging distribution infrastructure across the Midwest and Southeast, while EPA efficiency standards under DOE jurisdiction eliminate margin-viable production of legacy core designs.
Growth Catalysts
- Interconnection Queue Backlogs:Renewable energy projects in Texas, California, and Florida strain substation capacity, forcing utilities to procure higher-capacity transformers ahead of generation commissioning schedules.
- DOE Amended Efficiency Tiers:The Appliance and Equipment Standards Program mandates reduced no-load losses, compelling utilities to replace pre-2016 units and sustaining replacement demand independent of failure rates.
- Underground Installation Restrictions:Municipal easement limitations in dense urban zones compress vendor pools for pad-mounted and vault-style designs, creating premium positioning for certified manufacturers.
Market Restraints
- Grain-Oriented Electrical Steel Concentration:Domestic foundry capacity for core steel remains concentrated among limited suppliers, exposing procurement costs to raw material volatility and import tariff exposure.
- Mineral Oil Substitution Pressure:Natural and synthetic ester dielectric fluids gain regulatory preference under EPA spill prevention frameworks, requiring capital retooling for fluid containment architectures.
- Extended Manufacturing Lead Times:Core-cutting and coil-winding capacity constraints stretch delivery schedules beyond grid deployment timelines, forcing project delays or inventory pre-positioning.
Strategic Opportunities
- Digital Monitoring Integration:IoT-enabled dissolved gas analysis and thermal sensors extend transformer lifecycle value, creating recurring revenue streams through predictive maintenance subscriptions.
- Ester Fluid Retrofit Programs:Utilities in coastal flood zones and environmentally sensitive watersheds accelerate adoption of biodegradable dielectrics to mitigate spill liability exposure.
- Rural Single-Phase Extensions:Load density gaps in agricultural and remote residential zones sustain demand for pole-mounted units below 100 kVA where three-phase infrastructure remains uneconomical.
Industry Challenges
- Core Steel Winding Technician Shortage:Specialized craft skills for precision core assembly and coil winding face generational attrition, constraining domestic production scaling.
- NEMA TP-1 Certification Timelines:Third-party efficiency validation and DOE qualification cycles extend product launch windows, compressing competitive response times to tender releases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Oil Filled Distribution Transformer Market |
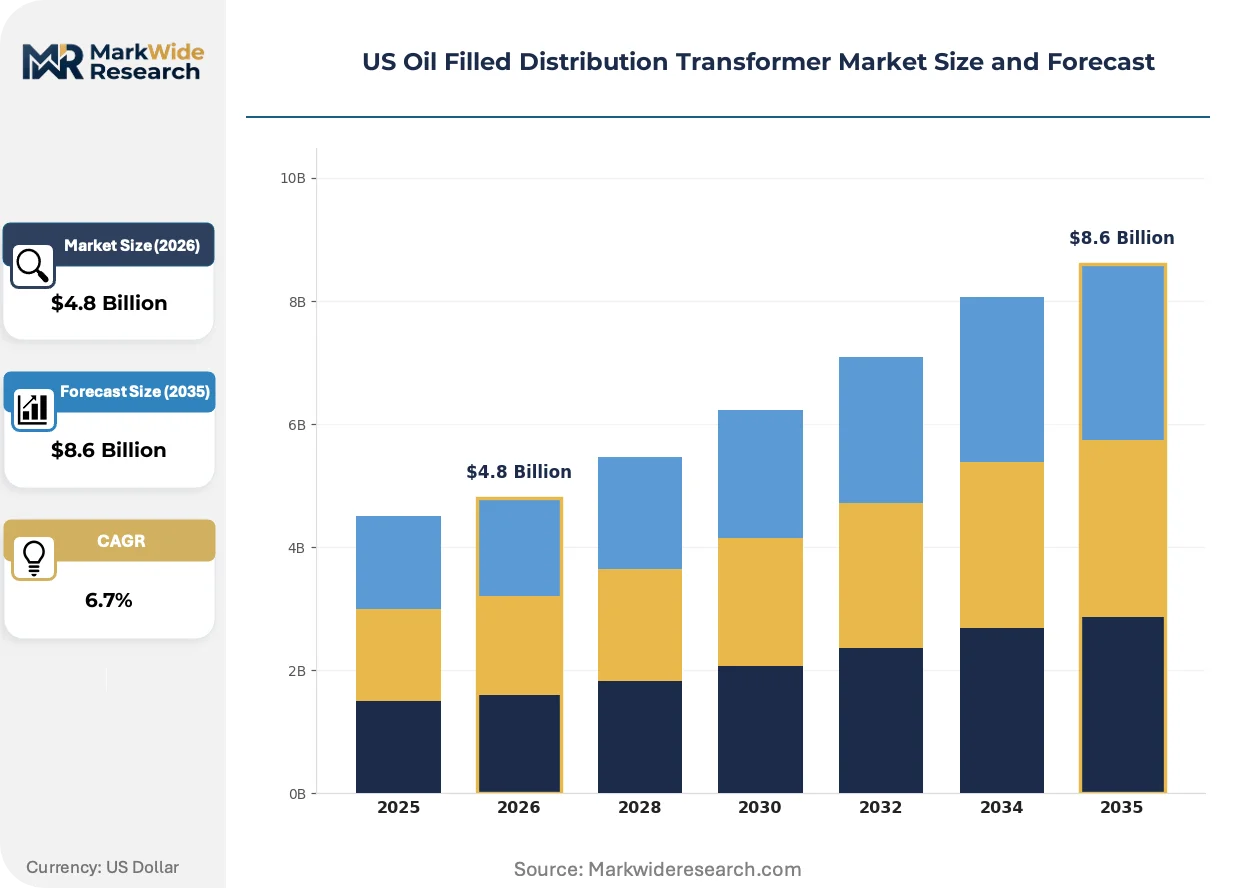
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Single-Phase, Three-Phase, Compact, Rugged End User: Utility Companies, Industrial Sector, Commercial Sector, Residential Users Installation: Overhead, Underground, Substation, Hybrid Power Rating: Low Voltage, Medium Voltage, High Voltage, Ultra High Voltage |
| Companies Covered | Hitachi Energy, Schneider Electric, Howard Industries, Central Moloney, Hammond Power Solutions, ERMCO, Eaton, Prolec-GE, General Electric, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Oil Filled Distribution Transformer Market Emerging Trajectories
Transformer architecture is converging with grid digitization and environmental compliance, reshaping how utilities evaluate total cost of ownership beyond unit procurement price.
Amorphous metal core technology is supplanting conventional grain-oriented silicon steel in distribution applications where no-load loss reduction justifies material cost premiums. Municipal utilities and cooperative purchasing groups in California and the Northeast are specifying amorphous cores for new substation installations. This material transition is compressing competitive differentiation around core loss performance rather than nameplate capacity alone.
EPA spill prevention regulations under 40 CFR 112 are mandating enhanced fluid containment systems and secondary barriers for underground installations. The rulemaking forces design modifications to tank seams, bushings, and cable termination enclosures. Pad-mounted transformer specifications in Florida and coastal Texas now routinely require double-wall tank construction or integral spill containment, favoring manufacturers with in-house welding and pressure-testing capabilities.
Integrated resource planning processes at state public utility commissions now embed transformer procurement into multi-year capital forecasts. Procurement teams bundle transformer orders with switchgear, reclosers, and voltage regulators to secure volume pricing and synchronized delivery. This consolidation is most pronounced in the Southeastern utility corridor where integrated utilities coordinate large-scale infrastructure replacement programs.
US Oil Filled Distribution Transformer Market Segmentation
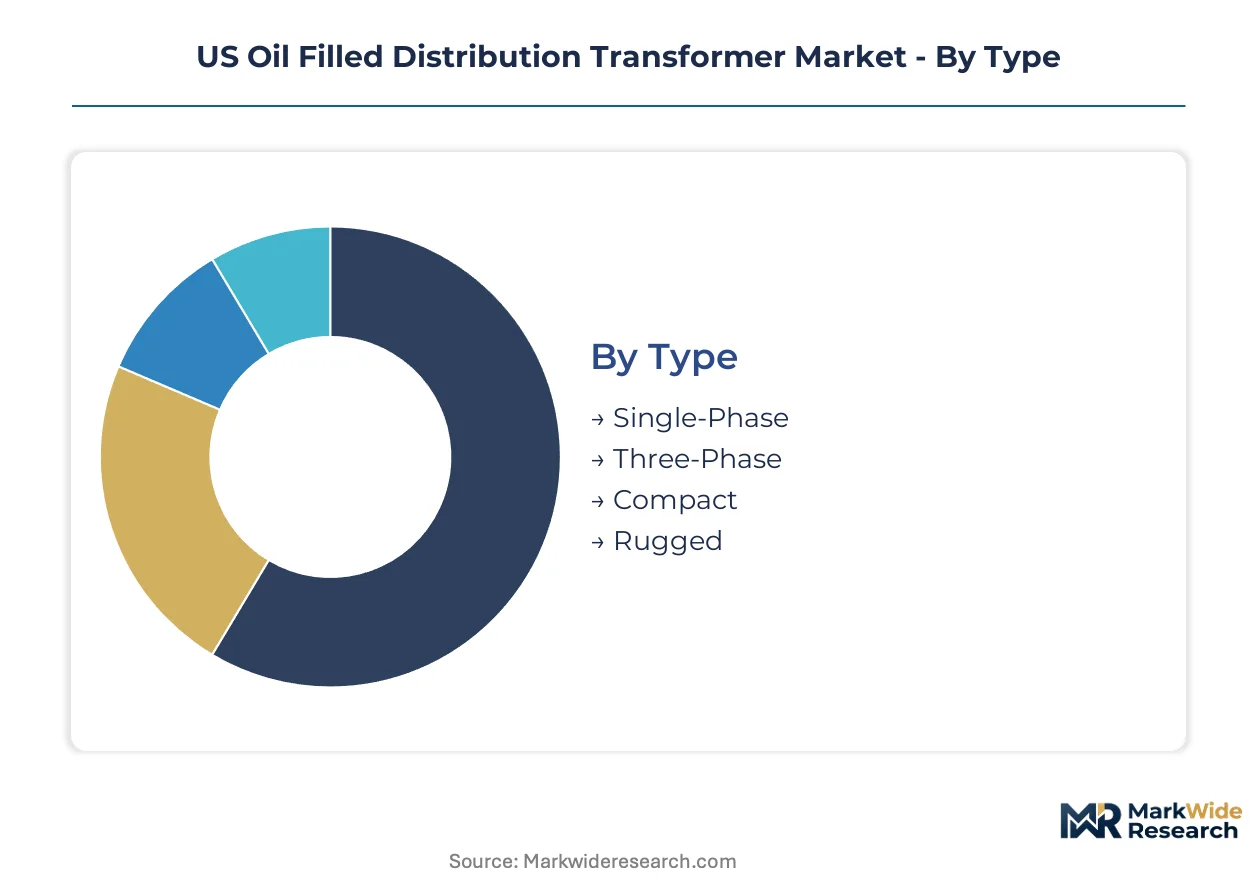
Segmentation in the US oil filled distribution transformer market reveals how regulatory frameworks, installation constraints, and load characteristics fragment procurement patterns. Utilities, industrials, and commercial operators source distinct specifications governed by DOE efficiency tiers, EPA spill prevention rules, and state-level integrated resource plans.
Type:
DOE amended efficiency tiers under the Appliance and Equipment Standards Program impose divergent compliance burdens across transformer architectures, reshaping competitive access by core material and winding configuration.
- Three-Phase:Units rated from 15 kVA to 50 MVA dominate utility substation and overhead line deployments. Procurement concentrates in Texas, California, and Florida where renewable interconnection queues strain distribution capacity and force higher-nameplate procurement ahead of generation commissioning.
- Single-Phase:Pole-mounted designs serve rural residential extensions and agricultural load pockets below 100 kVA. Demand persists in the Midwest and Southeast where cooperatives extend service to low-density zones without three-phase infrastructure economics.
- Compact:Space-constrained urban installations favor reduced-footprint designs with enhanced thermal management. Municipal easement restrictions in dense coastal metros compress available vendor pools.
- Rugged:Harsh-environment specifications withstand temperature extremes, seismic loading, and coastal corrosion. Gulf Coast utilities specify these for hurricane exposure zones under hardened grid mandates.
Established volume favors Three-Phase; emerging adoption favors Compact.
End User:
Capital deployment cycles and regulatory exposure split procurement behavior across customer categories, with utilities bearing efficiency mandate compliance costs that commercial and industrial operators partially avoid through behind-the-meter configurations.
- Utility Companies:Investor-owned utilities, municipal systems, and rural cooperatives account for bulk procurement under state public utility commission modernization mandates. Grid hardening programs in the Southeast and Midwest sustain replacement demand independent of failure rates.
- Industrial Sector:Heavy manufacturing, data centers, and petrochemical facilities procure dedicated substation transformers for load isolation and power quality. Texas and California industrial clusters drive specification for high-capacity units with digital monitoring integration.
- Commercial Sector:Retail, healthcare, and office complexes source pad-mounted and vault-style designs. Underground installation restrictions in urban California and Florida municipalities compress vendor pools for certified containment architectures.
- Residential Users:Single-family and multi-family developments rely on utility-owned distribution infrastructure with limited direct procurement. New construction in Florida and Texas suburban corridors indirectly drives pole-mounted and pad-mounted demand through developer impact fees.
Procurement scale concentrates with Utility Companies; margin expansion favors Industrial Sector.
Installation:
Site constraints and environmental liability exposure determine tank architecture, fluid containment systems, and secondary barrier requirements under EPA 40 CFR 112 frameworks.
- Underground:Pad-mounted and vault-style designs serve dense urban zones where municipalities restrict overhead easements. Double-wall tank construction and integral spill containment now dominate Florida and coastal Texas specifications.
- Overhead:Pole-mounted and crossarm configurations persist in suburban and rural extensions. Lower installed cost sustains preference in the Midwest and Southeast where right-of-way access remains unconstrained.
- Substation:Bulk power transformation at distribution voltage levels requires large-footprint three-phase units with advanced cooling. Renewable interconnection backlogs in California and Texas strain substation capacity and force procurement ahead of queue clearance.
- Hybrid:Mixed overhead-underground configurations accommodate urban fringe development and retrofit scenarios. Utilities in transitioning metros specify modular designs that bridge installation typologies.
Overhead retains volume leadership; Underground commands premium positioning.
Power Rating:
Loss threshold regulations and load growth trajectories segment procurement across voltage classes, with efficiency mandates tightening most aggressively at distribution-level ratings.
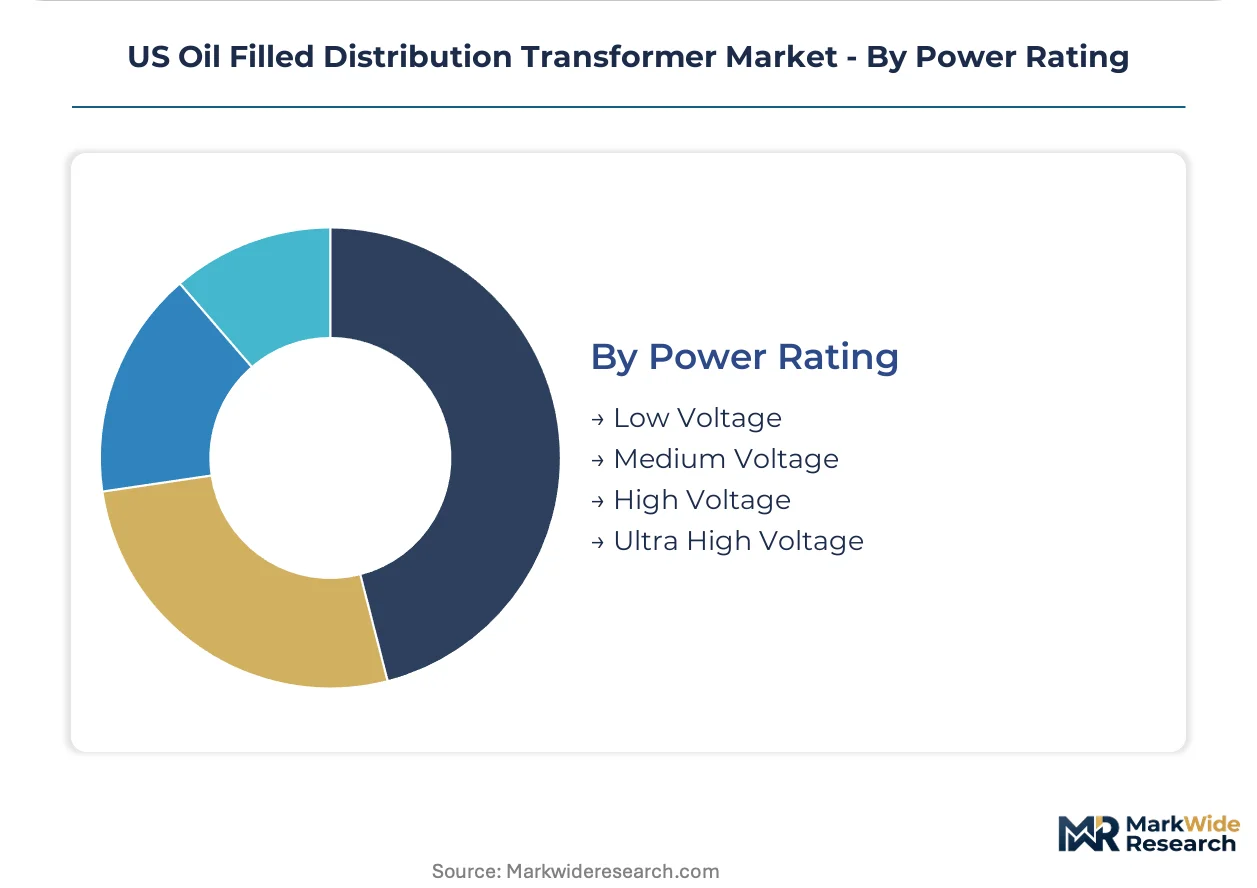
- Medium Voltage:Units stepping 4-35 kV distribution levels to end-use voltages constitute core utility procurement. DOE no-load loss reduction mandates eliminated margin-viable production of pre-2016 core designs.
- Low Voltage:Secondary-side distribution and service entrance applications serve commercial and light industrial loads. Specification concentrates in urban retrofit markets where aging infrastructure replacement coincides with efficiency upgrade cycles.
- High Voltage:Substation and transmission interconnection transformers handle 69-230 kV stepping requirements. Procurement ties to renewable generation integration in Texas and California interconnection queues.
- Ultra High Voltage:Specialized applications for grid interconnection and bulk power transfer remain limited in distribution contexts. Specification rarity restricts vendor participation to manufacturers with in-house high-voltage testing capabilities.
Medium Voltage anchors procurement volume; High Voltage climbs fastest on renewable integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility procurement teams concentrate transformer purchasing decisions within state regulatory jurisdictions rather than national programs. Regional demand clusters form around renewable interconnection backlogs, grid hardening mandates, and urban undergrounding restrictions.
Texas
ERCOT interconnection queues for solar and wind projects strain distribution substation capacity. The Public Utility Commission of Texas mandates grid reliability standards that accelerate transformer replacement cycles. Houston and Dallas-Fort Worth metro areas drive procurement of high-capacity three-phase units for data center load growth.
California
CPUC integrated resource planning embeds transformer procurement into multi-year capital forecasts. Title 24 building efficiency codes and SB 100 renewable mandates force underground installation in dense urban zones. Los Angeles and San Francisco Bay Area utilities specify pad-mounted designs with double-wall containment for coastal flood exposure.
Florida
Storm-hardening requirements from the Florida Public Service Commission sustain replacement demand independent of failure rates. EPA spill prevention rules under 40 CFR 112 mandate enhanced fluid containment for vault-style installations. Tampa and Miami-Dade procurement concentrates on hurricane-resistant specifications with seismic and corrosion resistance.
Southeast
State public utility commissions in Georgia, Alabama, and the Carolinas coordinate large-scale infrastructure replacement programs. Rural cooperatives extend single-phase service to agricultural load pockets below 100 kVA density thresholds. Atlanta and Charlotte industrial clusters drive specification for digital monitoring integration on dedicated substation transformers.
Midwest
Grid modernization mandates from Illinois and Ohio utility commissions compress replacement cycles for aging distribution infrastructure. Manufacturing reshoring initiatives in Michigan and Indiana strain existing substation capacity. Chicago and Detroit procurement teams bundle transformer orders with switchgear and voltage regulators for volume pricing.
US Oil Filled Distribution Transformer Market Vendor Landscape
Player mix skews toward vertically integrated electrical equipment conglomerates with captive core steel supply. Market structure concentrates among manufacturers with in-house winding operations and DOE certification capabilities. Two strategic archetypes dominate: integrated energy technology providers with global manufacturing footprints, and regional specialists with state-level procurement relationships. Competitive moves center on backward integration into grain-oriented electrical steel supply and strategic partnerships for digital monitoring platform integration.
Among the integrated technology providers, Hitachi Energy and Schneider Electric occupy positions exemplifying scale-driven and digitally-integrated archetypes respectively. Howard Industries anchors the domestic specialist tier with regional assembly advantages. These three manufacturers represent the competitive spectrum from global conglomerate to state-level procurement specialist, each sitting within distinct competitive vectors defined by supply chain control and customer proximity.
| Leading Market Players |
|---|
| Hitachi Energy |
| Schneider Electric |
| Howard Industries |
| Central Moloney |
| Hammond Power Solutions |
| ERMCO |
| Eaton |
| Prolec-GE |
| General Electric |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements with index-linked grain-oriented electrical steel pricing lock in both supply access and cost visibility for utility procurement teams navigating volatile raw material markets. These contracts anchor transformer pricing to commodity indices while insulating vendors from spot market spikes, creating bid-ask stability across multi-year infrastructure replacement cycles.
Pricing Analysis
Cost-plus contracts with CRU Group steel indexation dominate large utility tenders, linking transformer unit prices to monthly grain-oriented electrical steel assessments. Price differentiation rests on DOE efficiency tier certification and amorphous core material selection, with NEMA TP-1 qualified units commanding premiums over baseline designs. Cost compression in standard-efficiency tiers is intensifying because legacy core production lines face margin elimination under amended DOE loss thresholds. Municipal utilities exhibit highest price sensitivity due to ratepayer oversight constraints, while data center operators prioritize digital monitoring integration over unit cost.
Supply Chain Analysis
Inbound logistics costs from Asian steel mills through West Coast port gateways expose domestic transformer manufacturers to container availability swings and chassis shortages at Los Angeles-Long Beach. Core steel supply concentrates in Japan, South Korea, and domestic foundries in Ohio and Pennsylvania, creating geographic concentration risk around Pacific trade lane disruptions. Raw material dependencies span grain-oriented electrical steel, copper magnet wire, and mineral oil or natural ester dielectric fluids. Single-source vulnerability in specialized core-cutting equipment constrains domestic production scaling. Distribution runs through direct utility procurement channels and electrical distributor networks serving commercial and industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance subscriptions and dissolved gas analysis monitoring services are expanding faster than hardware unit sales, transforming transformer procurement from capital expenditure into lifecycle service relationships. This service-attach dynamic rewards vendors who bundle digital platforms with physical equipment.
For Market Incumbents: Compound defensive positioning through backward integration into captive core steel supply and accelerated DOE certification timelines for amorphous metal designs. Natural ester fluid substitution pressure from EPA spill prevention rules threatens mineral oil-based product lines, requiring capital retooling investments. Prioritize in-house winding capacity expansion in the Southeastern utility corridor where regional procurement preferences favor domestic assembly proximity. For New Entrants and Emerging Players: Lead with digital monitoring platform integration as a wedge against established hardware vendors, targeting rural cooperative utilities with limited in-house analytics capabilities. Single-phase pole-mounted units below 100 kVA in Midwest agricultural zones represent the most penetrable white space, as incumbent attention concentrates on high-capacity three-phase substation tenders. Pursue OEM partnerships with switchgear manufacturers to bundle transformer orders into integrated substation packages. For Investors and Strategic Acquirers: Regional specialists with state-level procurement relationships and NEMA TP-1 certification capabilities offer acquisition exposure to grid modernization tailwinds. Long-term viability hinges on exposure to renewable interconnection backlogs in Texas and California rather than cyclical replacement demand. Monitor FERC interconnection queue clearance rates as the critical inflection signal for transformer procurement velocity ahead of generation commissioning schedules.| Strategic Initiative | Industry Significance |
|---|---|
| Amorphous Core Manufacturing Scale-Up | Captures DOE efficiency tier premiums while displacing conventional grain-oriented silicon steel in loss-sensitive applications. |
| Natural Ester Fluid Containment Retrofit | Mitigates EPA 40 CFR 112 spill liability exposure for coastal utilities in Florida and California flood zones. |
| Digital Monitoring Platform Integration | Creates recurring revenue streams through predictive maintenance subscriptions extending transformer lifecycle value. |
| Utility Corridor Regional Assembly Expansion | Aligns production footprint with Southeastern and Midwest procurement preferences favoring domestic proximity. |
| Interconnection Queue Pre-Positioning | Anticipates ERCOT and CAISO transformer procurement waves before manufacturing lead times extend beyond grid deployment schedules. |
Methodological Framework
Desk research of DOE efficiency standard filings, EPA regulatory dockets, and state integrated resource plans preceded structured interviews with utility planning officers, transformer procurement managers, EPC contractors, and core steel supply specialists. Secondary validation drew from FERC interconnection queue databases, EIA grid infrastructure surveys, and NEMA technical committee proceedings. Primary fieldwork captured utility capital deployment timelines and vendor qualification practices. Bottom-up unit demand estimates triangulated against top-down infrastructure investment forecasts.
Variance decomposition across the projection horizon isolates volume sensitivity to renewable interconnection clearance rates, efficiency mandate compliance deadlines, and raw material cost pass-through mechanisms. Segmentation modeling spans transformer architecture, installation configuration, power rating tier, and end-user category. CAGRs derive from regression-adjusted procurement trajectories anchored to state public utility commission capital forecasts. Industry-specific inputs include grain-oriented electrical steel price indices and transformer manufacturing capacity utilization surveys.
The analysis sits within stated boundaries; outcomes outside sustained grid modernization funding levels or accelerated DOE efficiency tier enforcement would require recalibration. Forecasts reflect documented assumptions regarding interconnection queue processing speeds and core steel supply expansion timelines. Regulatory shifts in EPA spill prevention rules or state-level undergrounding mandates could materially revise demand patterns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Cast Resin Transformers Market
Transformers
South America Transformer Market
Transformers
United States Dry-Type Transformer Market
Transformers
Auto Transformer Rectifier Unit (ATRU) Market
Transformers
Liquid Filled Transformer Market
Transformers
Amorphous Core Transformers Market
Transformers
Transformer Monitoring Systems (TMS) Market
Transformers
China Transformer Market
Transformers
Europe Oil Filled Distribution Transformer Market
Transformers
Middle-East Smart Transformer Market
Transformers
Rail Traction Transformers Market
Transformers
Asia Pacific Smart Transformers Market
Transformers
United Arab Emirates Transformer Market
Transformers
Renewable Energy Transformer Market
Transformers
Industrial Control Transformers Market
Transformers
Asia-Pacific Transformer Market