
 Latin America Transformer Market | 2026-2036
Latin America Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Transformer Market Insights
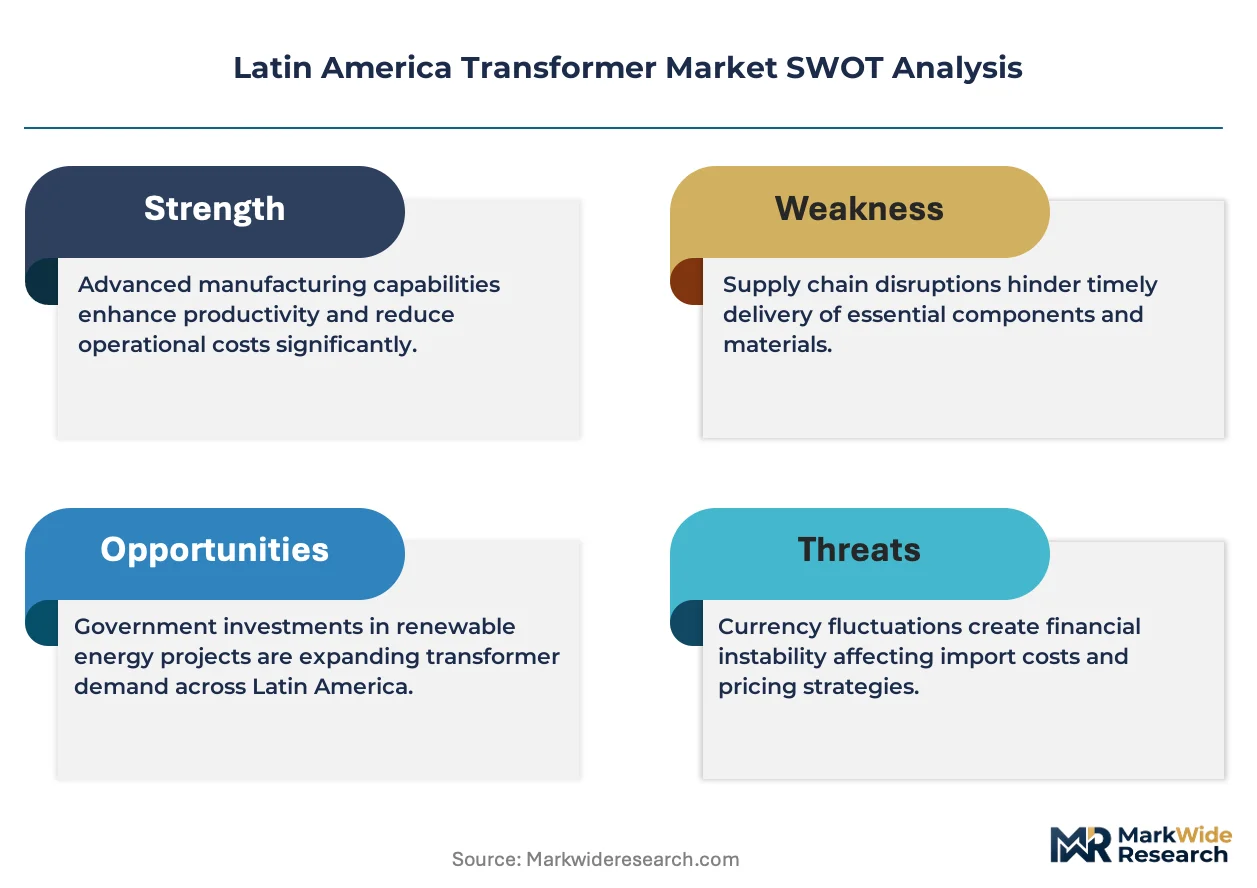
Amorphous core and copper-winding specification tiers are unwinding across Latin America as utilities prioritize loss-reduction mandates. WEG leverages its integrated steel-lamination foundry in Brazil to anchor regional supply of high-efficiency distribution units. Prolec GE sustains technology leadership through joint development programs with CFE in Mexico. Siemens Energy competes on turnkey substation packages that bundle transformers with digital monitoring systems.
A transformer is a static electromagnetic device that transfers electrical energy between circuits through mutual induction, typically operating at frequencies of 50 or 60 Hz with voltage ratings spanning from distribution-level 11 kV to transmission-class 765 kV. Its core function is to step voltage up for efficient long-distance power transport and step it down for safe end-use consumption in industrial, commercial, and residential settings. Distribution transformers occupy the largest volume pool across Latin America given pervasive rural electrification gaps and urban grid densification programs, while smart transformer technology is expanding fastest as utilities deploy sensors for real-time thermal monitoring and predictive maintenance. Power transformers command the deepest margin concentration due to custom engineering requirements and limited qualified fabrication capacity within the region.
Brazil's ANEEL enforces PROINFA-mandated grid standards that require transformer interoperability with variable renewable output, while Mexico's CRE regulates efficiency benchmarks under national energy transition frameworks. IEC 60076 and IEEE C57 standards govern insulation classes and short-circuit withstand protocols, shaping procurement specifications for cross-border projects. Stakeholders must monitor how national content requirements and local certification timelines affect project economics as governments link electrification spending to domestic manufacturing quotas.
Market Dynamics
Dry-type insulation technology is displacing mineral oil in urban substations across Brazil and Mexico, driven by stricter municipal fire safety codes and densification of load centers in metropolitan corridors.
Growth Catalysts
- PROINFA Grid Standards:Brazil's ANEEL mandates transformer interoperability with variable renewable output, forcing equipment upgrades to absorb wind power from the Northeast region.
- Data Center Clustering:Hyperscale facilities in São Paulo's industrial corridor demand upgraded distribution infrastructure with higher thermal margins and digital monitoring capabilities.
- Amorphous Core Adoption:Loss-reduction mandates from national energy transition frameworks accelerate specification tiers for high-efficiency distribution units across utility procurement.
Market Restraints
- Copper Price Volatility:Winding material cost swings compress margin predictability for regional fabricators dependent on imported cathode.
- Qualified Fabrication Scarcity:Power transformer engineering capacity concentrates in southern Brazil, creating bottleneck risk for transmission-class projects.
- IEC-IEEE Specification Friction:Divergent insulation class and short-circuit withstand protocols between European and North American standards complicate cross-border procurement.
Strategic Opportunities
- Smart Transformer Deployment:Real-time thermal monitoring and predictive maintenance sensors create upgrade cycles in Colombia's Andean utilities.
- CRE Efficiency Benchmarks:Mexico's national energy transition frameworks tighten loss limits, opening replacement demand in aging distribution networks.
- Digital-Turnkey Bundling:Substation packages integrating transformers with SCADA monitoring systems capture premium positioning in Chilean mining electrification.
Industry Challenges
- Certification Timeline Compression:ANEEL and CRE local approval protocols extend project lead times, straining working capital for equipment suppliers.
- Legacy Grid Integration:Aging 60 Hz infrastructure in portions of Argentina requires custom tap-changer configurations, fragmenting production runs.
- Specialized Winding Labor:Copper foil and sheet winding expertise concentrates among retiring technician cohorts in southeastern Brazil.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Transformer Market |
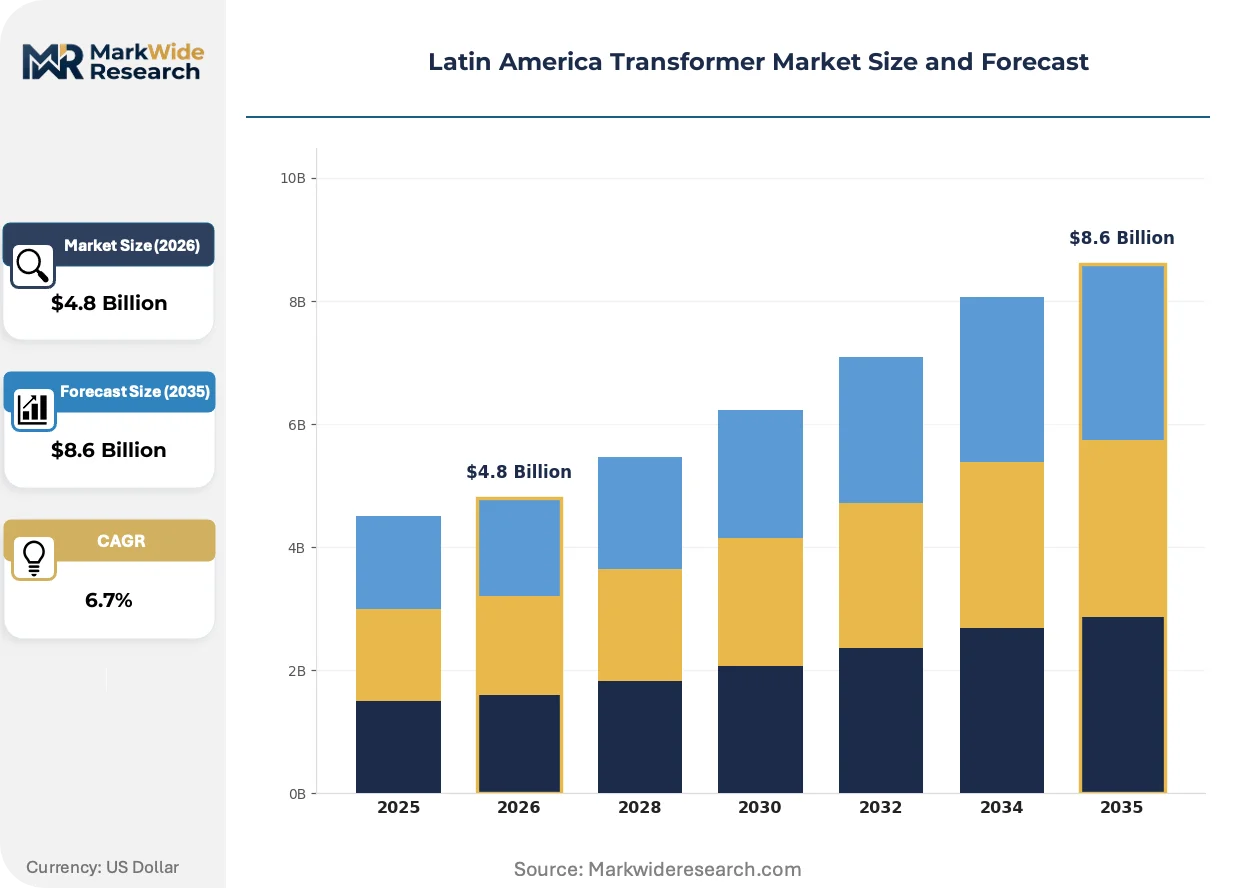
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Transformers, Distribution Transformers, Instrument Transformers, Isolation Transformers End User: Utilities, Industrial, Commercial, Renewable Energy Installation Type: Indoor, Outdoor, Pole-mounted, Substation Technology: Conventional, Smart, Liquid-filled, Dry-type |
| Companies Covered | WEG, Prolec GE, Siemens Energy, Hitachi Energy, ABB, Schneider Electric, GE Vernova, Eaton, Trafo Tec, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Transformer Market Trends and Innovations
Transformer technology across Latin America is splitting between premium efficiency tiers for regulated utilities and cost-optimized specifications for private industrial offtake, with digital monitoring layers becoming the primary differentiation vector.
Amorphous metal core technology is bifurcating the efficiency landscape for distribution transformers. The material's near-zero hysteresis loss enables compliance with stringent no-load loss limits. Brazilian utilities in the Southeast corridor are specifying amorphous cores for urban substation rebuilds, while rural electrification programs prioritize conventional silicon steel to contain capital outlay.
Brazil's ANEEL has tightened PROINFA-mandated grid standards to require dynamic voltage regulation capabilities in new transformer installations. The regulation forces manufacturers to embed on-load tap changers with faster response algorithms. Wind-rich states in the Northeast face the steepest compliance curves as interconnection queues accelerate.
Industrial buyers in Mexico's Bajío manufacturing cluster are unbundling transformer procurement from EPC contracts, establishing direct relationships with regional fabricators. The disintermediation compresses margin capture by turnkey integrators and accelerates specification customization for automotive and aerospace load profiles.
Latin America Transformer Market Segmentation
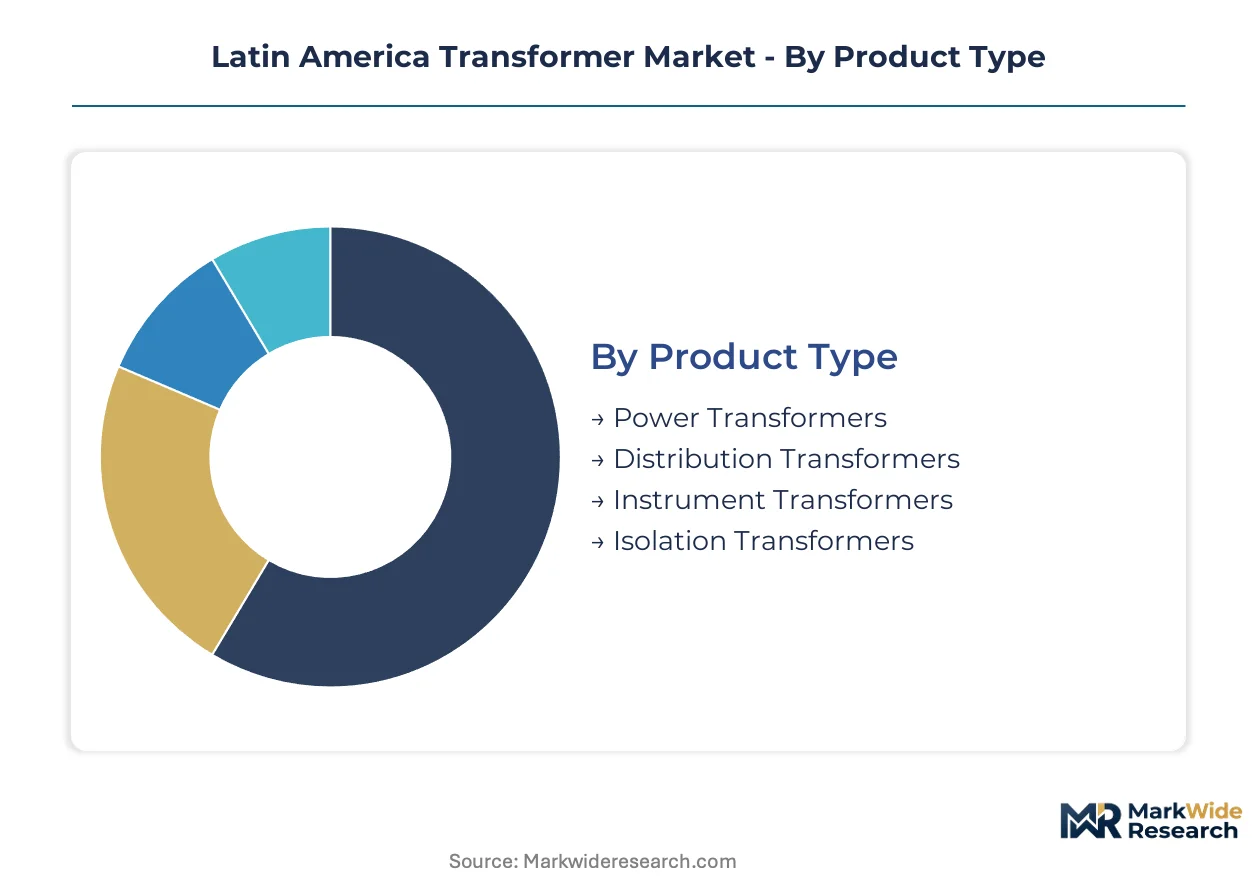
Transformer procurement across Latin America fragments across voltage classes, installation constraints, and digital readiness tiers. Each segment carries distinct margin profiles and regulatory exposure that reshape supplier positioning.
Product Type:
Substitution pressure from solid-state power electronics and modular substations weighs most heavily on lower-kVA distribution units, while transmission-class equipment remains insulated by engineering complexity barriers.
- Power Transformers:Custom-engineered units rated above 50 MVA handle inter-regional transmission and bulk renewable integration. Brazilian wind corridors in Rio Grande do Norte and Piauí drive demand for dynamic tap-changer configurations that stabilize voltage fluctuation.
- Distribution Transformers:Pole-mounted and pad-mounted units below 50 MVA dominate unit volumes across rural electrification programs. ANEEL-mandated loss-reduction tiers are accelerating amorphous core specifications in São Paulo's dense urban substations.
- Instrument Transformers:Current and voltage sensing devices enable metering and protection relay coordination. Mexican CFE procurement emphasizes accuracy class upgrades for smart grid pilot zones.
- Isolation Transformers:Galvanic separation units protect sensitive industrial loads from harmonic distortion. Data center clusters in Querétaro and Campinas specify K-factor rated designs for IT equipment protection.
Distribution Transformers retains volume leadership; Smart transformer functionality holds the steepest expansion curve.
End User:
Customer-type concentration varies sharply by voltage tier, with utility procurement governed by regulatory efficiency mandates while industrial buyers prioritize thermal margin and customization speed.
- Utilities:State-owned and regulated distributors across Brazil, Mexico, and Colombia account for the deepest project pipelines. ANEEL and CRE efficiency benchmarks force replacement cycles in aging distribution networks.
- Industrial:Mining, steel, and automotive clusters demand ruggedized designs with elevated short-circuit withstand. Chilean copper mines in the Atacama specify sealed-tank units for altitude and contamination resistance.
- Commercial:Shopping centers, hospitals, and office complexes drive dry-type indoor specifications. São Paulo municipal fire codes now prohibit mineral-oil units in high-rise basement installations.
- Renewable Energy:Wind and solar developers require step-up transformers with wide tap-range flexibility. Northeast Brazil's PROINFA-compliant wind farms mandate interoperability with weak-grid conditions.
Utilities command the largest revenue pool; Renewable Energy is climbing the fastest as interconnection queues accelerate.
Installation Type:
Physical deployment constraints in dense Latin American metropolitan corridors are forcing technology trade-offs between fire safety, footprint, and maintenance access.
- Indoor:Dry-type and cast-resin units occupy climate-controlled electrical rooms. Mexico City building codes now require encapsulated designs for all underground substations.
- Outdoor:Conventional oil-filled units on concrete pads remain standard for suburban and rural distribution. Brazilian utilities specify hermetically sealed tanks to reduce maintenance in remote Amazonian localities.
- Pole-mounted:Single-phase and small three-phase units extend grid reach into dispersed rural settlements. Colombia's universal service programs deploy compact designs for Andean terrain accessibility.
- Substation:Large power transformers anchor bulk supply points and renewable collection stations. Argentina's 500 kV backbone expansion concentrates demand in high-voltage outdoor yards.
Outdoor installations retain volume leadership; Indoor specifications are gaining share fastest on urban densification.
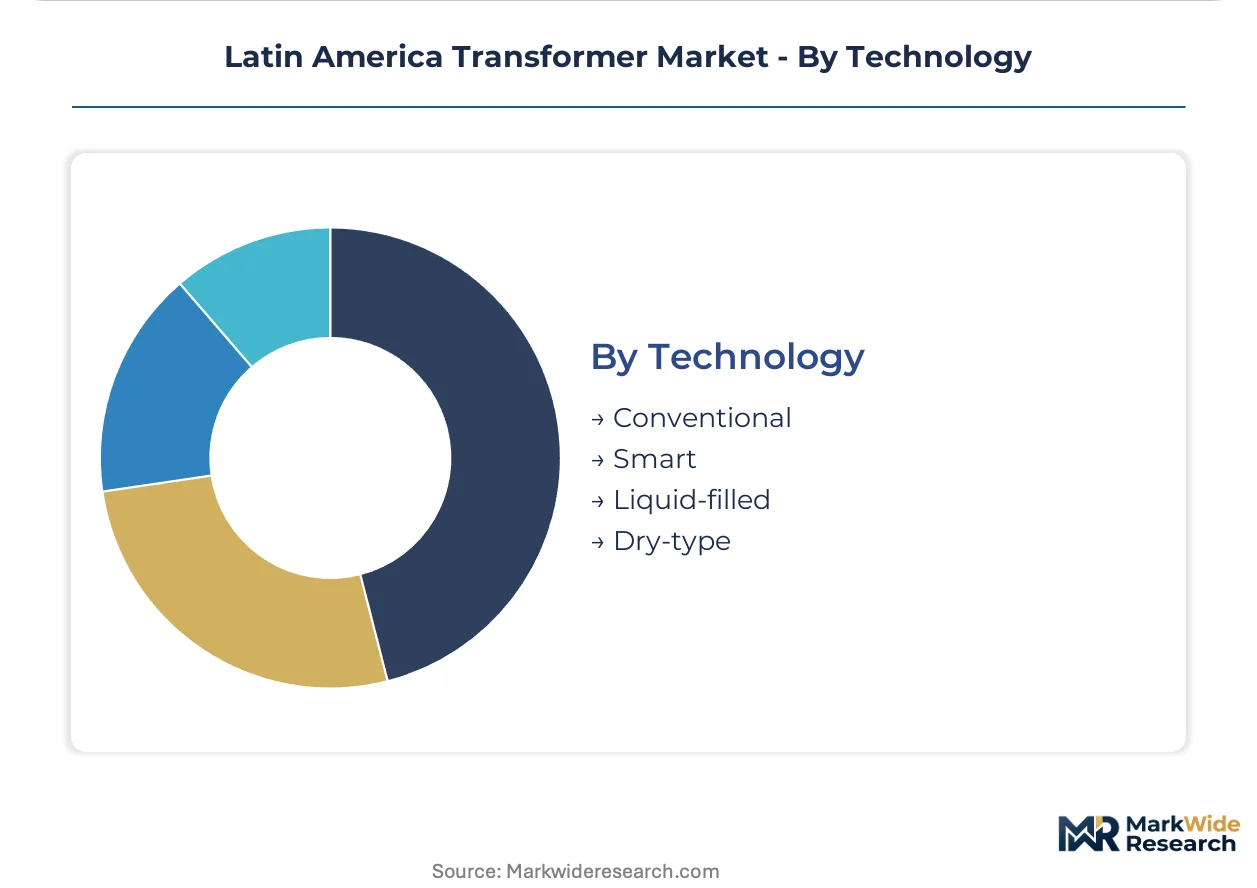
Technology:
Digital layer penetration splits the market between legacy electromechanical reliability and sensor-enabled predictive capabilities.
- Conventional:Standard silicon-steel core designs with electromechanical protection satisfy cost-sensitive rural programs. Paraguay and Bolivia electrification initiatives prioritize capital containment over efficiency premiums.
- Smart:Embedded thermal, dissolved-gas, and partial-discharge sensors enable condition-based maintenance. Colombian utilities in the Andean region pilot remote monitoring for avalanche-prone transmission corridors.
- Liquid-filled:Mineral oil and ester-based insulation dominate outdoor transmission and large distribution ratings. Fire-resistant natural ester fluids are penetrating urban substations in Curitiba and Porto Alegre.
- Dry-type:Cast-resin and vacuum-pressure-impregnated designs eliminate fire and spill risks. Rio de Janeiro's tunnel and metro electrification mandates dry-type for all underground vaults.
Conventional technology retains volume leadership; Smart transformer platforms are expanding most quickly on utility digitalization budgets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-voltage fabrication capacity clusters in southeastern Brazil, while distribution assembly spreads across Mexico and Argentina. National regulators in each major economy impose distinct efficiency mandates and local content rules that reshape procurement patterns.
Brazil
Wind-rich states in the Northeast drive demand for dynamic tap-changer configurations that stabilize voltage fluctuation. ANEEL enforces PROINFA-mandated grid standards requiring transformer interoperability with variable renewable output. São Paulo's industrial corridor concentrates data center clustering that demands upgraded distribution infrastructure with digital monitoring capabilities.
Mexico
Hyperscale facilities in Querétaro and the Bajío manufacturing cluster require K-factor rated isolation transformers for IT equipment protection. CRE regulates efficiency benchmarks under national energy transition frameworks that tighten loss limits in aging distribution networks. Mexico City building codes now mandate encapsulated dry-type designs for all underground substations.
Argentina
The 500 kV backbone expansion concentrates demand for transmission-class outdoor yards in high-voltage corridors. The country's national energy regulator imposes local certification timelines that extend project lead times for equipment suppliers. Aging 60 Hz infrastructure in portions of Buenos Aires province requires custom tap-changer configurations that fragment production runs.
Chile
Copper mines in the Atacama specify sealed-tank units for altitude and contamination resistance in harsh desert conditions. The national mining regulator enforces electrical safety standards that mandate ruggedized designs with elevated short-circuit withstand. Santiago's metro electrification mandates dry-type transformers for all underground vaults and tunnel installations.
Colombia
Andean utilities pilot smart transformer deployment with remote monitoring for avalanche-prone transmission corridors. The national utility regulator emphasizes accuracy class upgrades for smart grid pilot zones in mountainous terrain. Universal service programs deploy compact pole-mounted designs for rural electrification in difficult Andean terrain accessibility zones.
Latin America Transformer Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Latin America transformer market. The vendor base splits between integrated electromechanical conglomerates with captive steel-lamination foundries and specialized transformer fabricators focused on custom engineering. Three archetypes dominate: regional champions with backward integration into core materials, multinational energy technology groups bundling digital layers, and niche specialists in dry-type or amorphous core segments. Competitive moves center on turnkey substation packaging and strategic partnerships with national utilities for technology co-development.
Among Brazil-based integrated manufacturers, WEG leverages its foundry position to anchor regional supply of high-efficiency distribution units. Prolec GE occupies a position within the technology co-development tier through joint programs with CFE in Mexico. Siemens Energy sits within the digital-turnkey bundling archetype, competing on substation packages that integrate transformers with SCADA monitoring systems for mining electrification in Chile.
| Leading Market Players |
|---|
| WEG |
| Prolec GE |
| Siemens Energy |
| Hitachi Energy |
| ABB |
| Schneider Electric |
| GE Vernova |
| Eaton |
| Trafo Tec |
| Others |
Pricing and Supply Chain Analysis
High-voltage fabrication scale in southeastern Brazil anchors regional price floors for transmission-class units, while distribution assembly fragmentation across Mexico and Argentina compresses margins on standardized designs. ANEEL-mandated efficiency tiers and CRE loss-reduction benchmarks force specification premiums that widen spreads between compliant and non-compliant suppliers.
Pricing Analysis
ANEEL's PROINFA grid standards dictate the pricing tier structure across Brazilian utility procurement, separating amorphous core premium specifications from conventional silicon steel economy tiers. Price differentiation hinges on IEC 60076 certification grade and volume scale in multi-year framework agreements. Cost compression in standard distribution units is intensifying because copper cathode import dependency exposes fabricators to exchange-rate volatility. Rural electrification programs exhibit highest price sensitivity, while data center operators in São Paulo's industrial corridor prioritize thermal margin over unit cost.
Supply Chain Analysis
Extended lead times for on-load tap changers and specialized winding labor concentrate inventory risk in power transformer fabrication. Supply concentrates in Brazil, Mexico, and Argentina, with high-voltage core lamination drawing from WEG's captive foundry in Jaraguá do Sul and copper winding feedstock resting on Chilean cathode imports. Single-source vulnerability in amorphous metal ribbon from limited qualified suppliers threatens loss-reduction tier expansion. Distribution runs through utility procurement frameworks, direct industrial relationships, and EPC contractor bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital monitoring service layers expand faster than hardware replacement cycles across Latin American utilities, creating recurring-revenue attach opportunities that reshape supplier economics. Predictive maintenance subscriptions and SCADA integration contracts now command margin premiums exceeding base equipment sales in Colombian and Chilean deployments.
For Market Incumbents: Fortify position through backward integration into core lamination capacity and certification pre-positioning for ANEEL's evolving interoperability mandates. Solid-state power electronics substitution in low-kVA distribution threatens volume pools in rural electrification programs. Prioritize captive supply of amorphous metal ribbon to defend margin structure in efficiency-tier procurement. For New Entrants and Emerging Players: Differentiate on smart transformer platform architecture for Andean utility digitalization budgets in Colombia and Peru. White-space concentrates in dry-type indoor specifications for São Paulo and Mexico City underground substations, where municipal fire codes now prohibit mineral-oil alternatives. Pursue direct relationships with hyperscale data center developers unbundling from EPC contracts. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors transformer fabricators with installed base scale and service attach capabilities over pure equipment plays. Long-term viability hinges on recurring-revenue mix and regional regulatory relationship depth. Acquisition targets should demonstrate ANEEL or CRE pre-certification pipelines and established utility framework presence. Monitor CRE efficiency benchmark tightening as inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Transformer Platform Development | Embedded thermal monitoring captures ANEEL-mandated digitalization budgets in Brazilian utilities. |
| Amorphous Core Foundry Investment | Captive lamination supply secures loss-reduction tier positioning against copper price volatility. |
| Dry-Type Manufacturing Scale-Up | Mexico City and São Paulo fire code compliance drives substitution demand for cast-resin designs. |
| Utility Co-Development Partnership | Joint programs with CFE and Eletrobras anchor technology roadmap alignment and procurement preference. |
| Digital Service Layer Expansion | Predictive maintenance subscriptions extract recurring value from installed base in Chilean mining electrification. |
Research Methodology
A spread of perspectives from utility planning officers, EPC procurement leads, transformer plant engineers, and aftermarket service heads converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against ANEEL regulatory filings, CRE efficiency benchmark documentation, customs trade data for copper and electrical steel imports, and SEC disclosures from listed electromechanical conglomerates. Bottom-up unit shipment estimates triangulated against top-down addressable market sizing across voltage class and installation type segments.
Segmentation dimensions modeled include product type, end user category, installation environment, and technology tier across the projection horizon. CAGRs were derived from regression analysis of historical procurement patterns and regulatory-mandated replacement schedules. Forecast inputs incorporated PROINFA interconnection queue data, data center power demand projections for São Paulo and Querétaro clusters, and mining electrification capex disclosures from Chilean copper operations.
Forecasts assume regulatory continuity in ANEEL and CRE regimes; material policy shifts in national content requirements or efficiency benchmark stringency would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
United States Power Transformer Market
Transformers
United States Distribution Transformer Market
Transformers
Electric Vehicle Charging Station Transformer Market
Transformers
Global Transformer Market
Transformers
Europe Telecom Transformers Market
Transformers
South America Transformer Market
Transformers
Transformer Oil Market
Transformers
Middle-East Smart Transformer Market
Transformers
Transformer Steel Market
Transformers
Oil Immersed Transformer and Dry Type Transformer Market
Transformers
Locomotive Traction Transformer Market
Transformers
Distribution Transformer Market
Transformers
US Oil Filled Distribution Transformer Market
Transformers
Uninhibited Transformer Oil Market
Transformers
United States Large Power Transformer Market
Transformers
Asia Pacific Smart Transformers Market