
 Packaged Substation Market | 2026-2036
Packaged Substation Market Size, Share, and Industry Trends Forecast 2026-2036
Packaged Substation Market Analysis
The gap between premium intelligent substations and commodity compact units is recalibrating competitive investment across the industry. Siemens Energy AG leverages digital twin integration and predictive maintenance software to command premium positioning in European utility tenders. ABB Ltd. anchors its volume base through standardized compact designs engineered for emerging market cost structures. Schneider Electric SE differentiates via EcoStruxure platform compatibility, embedding IoT-enabled monitoring as a default feature across mid-tier and premium configurations.
A packaged substation integrates transformers, switchgear, protection systems, and control equipment within a single factory-assembled enclosure, typically rated between 1 kV and 36 kV for primary distribution networks. The assembly arrives pre-tested and wired, slashing on-site installation from weeks to days while reducing civil works and commissioning labor. Compact substations dominate current shipment volumes across dense urban deployments where footprint constraints override customization needs. Renewable energy integration represents the fastest-expanding application segment, driven by solar and wind projects requiring rapid grid-connection turnaround. Containerized solutions command elevated margins in remote mining and data center applications where modular transportability justifies premium pricing over permanent installations.
IEC 62271 standards govern switchgear performance and safety testing across international markets, while local regulators including India's CEA mandate specific efficiency and fault-withstand certifications for grid-connected assets. The EU F-Gas Regulation and REACH frameworks are accelerating manufacturer migration toward vacuum interrupters and dry-type transformers, reshaping material sourcing and design roadmaps. Stakeholders must weigh SF6-phaseout timelines against the capital intensity of retooling production lines for alternative insulation systems.
Market Dynamics
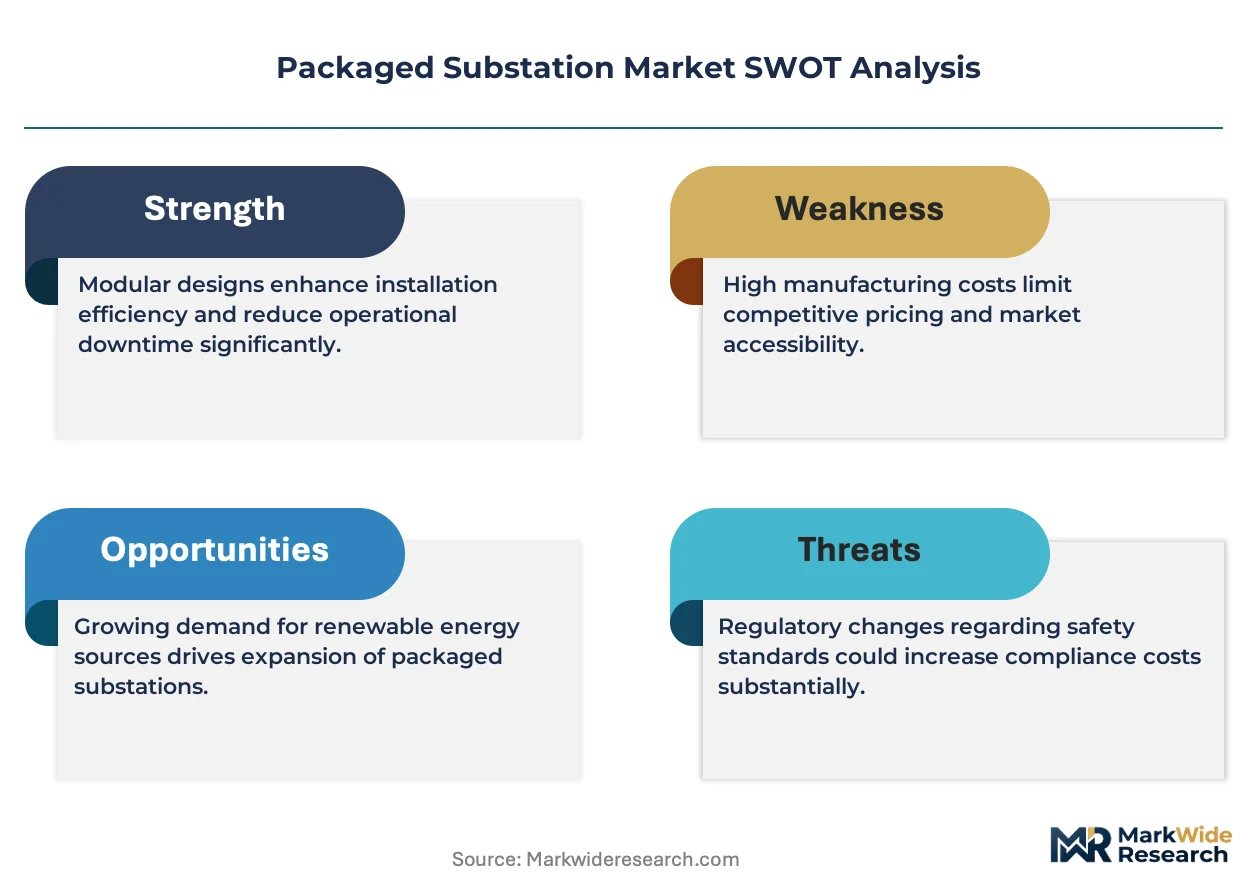
The EU F-Gas Regulation is forcing manufacturers to abandon sulfur hexafluoride insulation, triggering a wholesale retooling of production lines toward vacuum interrupters and dry-type transformers. This single mandate is compressing supplier margins while creating first-mover advantages for firms with alternative insulation ready for certification.
Growth Catalysts
- Rural electrification mandates:India's CEA certification requirements for rapid-deployment distribution infrastructure are pulling containerized substations into village grid extensions and metro rail expansions.
- Data center buildouts:Hyperscale operators are specifying factory-assembled units to compress energization timelines from months to weeks.
- SF6 phaseout deadlines:The EU Green Deal's binding emission reduction targets are accelerating replacement cycles across European utility fleets.
Market Restraints
- Copper and grain-oriented electrical steel volatility:Transformer core material costs swing with commodity markets, compressing quoted margins on fixed-price contracts.
- Specialized fabrication concentration:Vacuum interrupter manufacturing clusters in Germany and Japan create chokepoints for SF6-free switchgear supply.
- IEC 62271 certification timelines:Type-testing protocols for new insulation systems extend product launch windows by 12-18 months.
Strategic Opportunities
- Offshore wind grid connection:North Sea lease rounds require marine-grade containerized substations with salt corrosion resistance.
- EcoStruxure-compatible retrofits:Mid-tier utilities are seeking IoT monitoring upgrades for existing compact installations without full replacement.
- Remote mining electrification:Modular transportable units command premium pricing in Australian and Chilean extraction corridors lacking permanent infrastructure.
Industry Challenges
- Vacuum interrupter engineering talent scarcity:The shift from gas to vacuum insulation requires rare expertise in arc quenching physics and contact material science.
- Legacy SCADA integration friction:Digital twin platforms must interface with decades-old utility communication protocols, extending commissioning complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaged Substation Market |
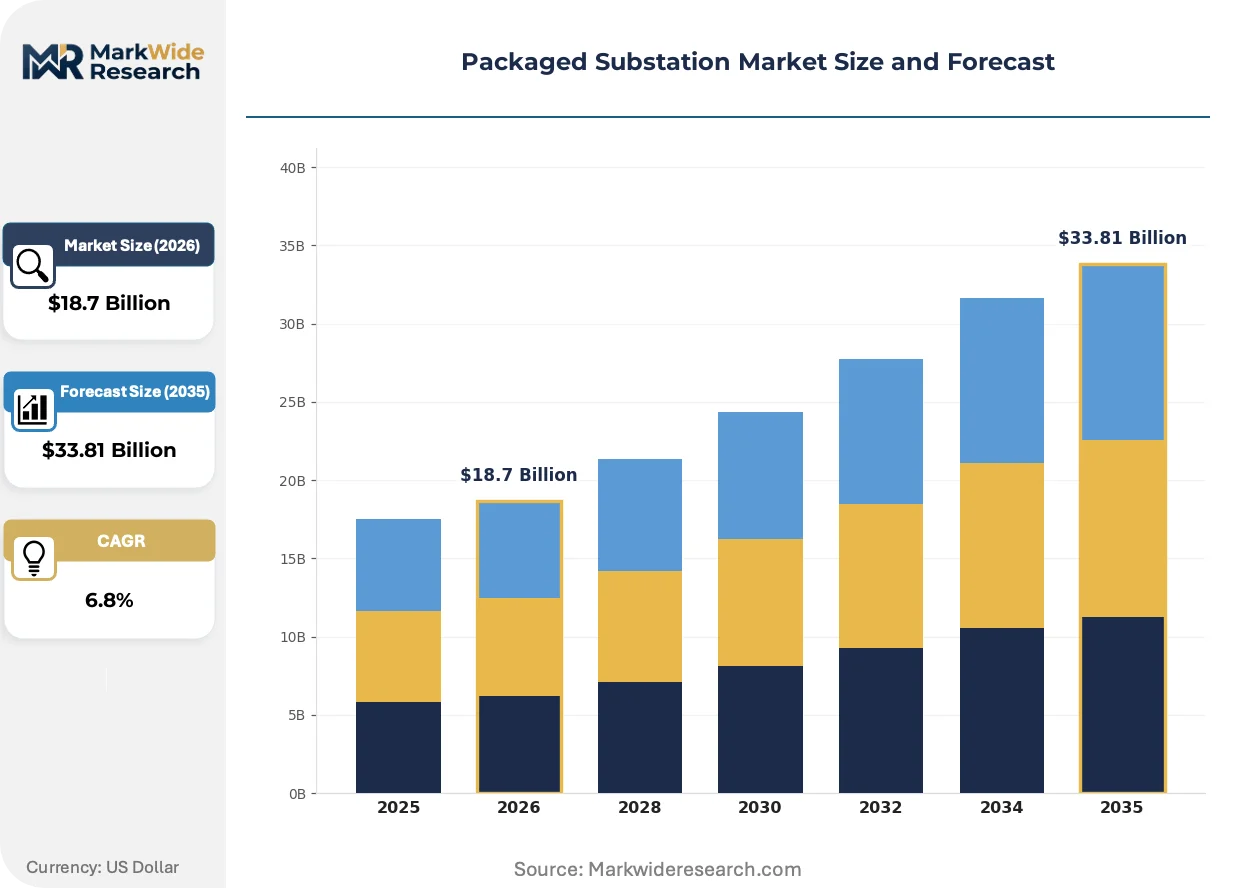
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Substations, Mini-Substations, Containerized Solutions, Mobile Substations Application: Power Distribution, Renewable Energy Integration, Industrial Use, Commercial Use End User: Utilities, Contractors, Manufacturers, Large Enterprises Installation Type: Indoor Installations, Outdoor Installations, Temporary Installations, Permanent Installations |
| Companies Covered | ABB Ltd., Siemens Energy AG, Schneider Electric SE, General Electric Company, Eaton Corporation, Hitachi Energy Ltd., Larsen & Toubro Ltd., C&S Electric Ltd., Kirloskar Electric Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaged Substation Market Emerging Trajectories
Digital twin integration is absorbing capital allocation across the supplier base, with predictive maintenance software becoming a standard tender requirement rather than a premium add-on. This convergence of physical asset and virtual monitoring is redefining value capture in aftermarket services.
Vacuum interrupter technology is absorbing the functional role once filled by SF6-insulated switchgear across medium-voltage ratings. European utilities are specifying vacuum-based designs in 80% of new tenders. The technology is absorbing the capital expenditure that manufacturers previously directed toward gas handling equipment and emission monitoring systems.
The EU F-Gas Regulation's staged phaseout mandates are compressing the viable commercial lifespan of SF6-dependent product lines. Manufacturers must now balance inventory liquidation against accelerated R&D amortization. Distribution utilities in Germany and France are responding by front-loading replacement orders to secure last-available gas-insulated units before supply constraints tighten.
Utility procurement departments are unbundling installation and commissioning from equipment supply, driving margin compression on turnkey contracts. EPC contractors are capturing the civil works and site integration value that manufacturers once retained. This pattern is most visible in Indian state electricity board tenders, where separate bidding for supply and installation has become standard practice.
Packaged Substation Market Segmentation
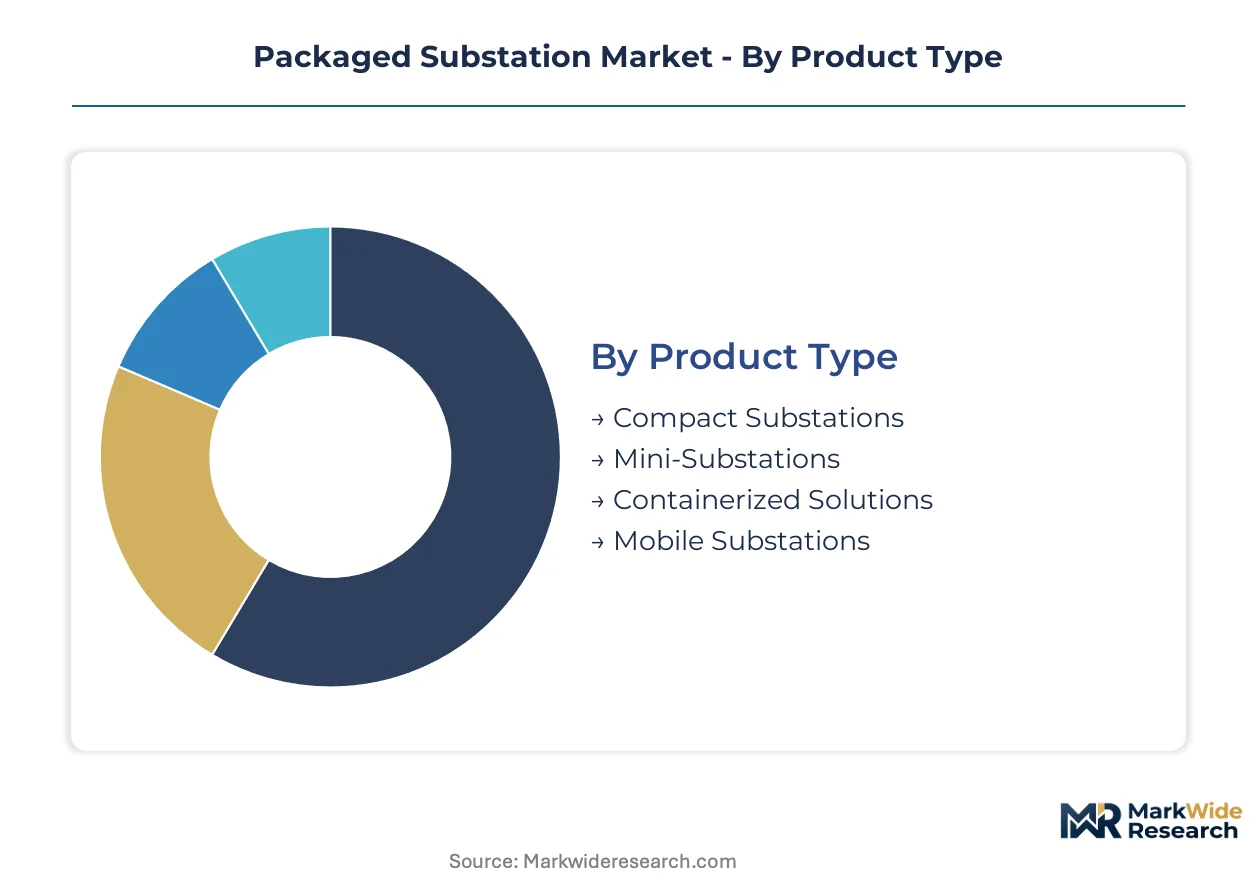
Segmentation in packaged substations reveals how deployment constraints and operational urgency reshape procurement priorities. Utilities balance footprint limitations against energization speed, while industrial buyers prioritize transportability over permanent infrastructure.
Product Type:
Upgrade cycles vary sharply across enclosure formats, with legacy compact designs facing displacement by containerized and mobile alternatives in time-sensitive deployments.
- Compact Substations:Factory-integrated transformer and switchgear assemblies occupy minimal footprints through optimized internal layouts and liquid-immersed or dry-type cooling configurations. Dense urban deployments in Indian metro corridors and European city centers specify these units where substation real estate commands premium valuations. IEC 62271 certification requirements extend lead times for compact designs with vacuum interrupters.
- Containerized Solutions:Standard shipping-container enclosures house complete substation functionality with marine-grade corrosion protection and plug-and-play cable terminations. Data center operators in Germany and hyperscale facilities in India specify these for rapid energization without permanent civil foundations. Salt-resistant variants serve North Sea offshore wind grid connections.
- Mini-Substations:Reduced-capacity units serve low-density distribution networks with single-transformer configurations.
- Mobile Substations:Trailer-mounted or skid-based designs enable emergency restoration and planned maintenance bypasses.
Volume placements concentrate in compact substations; the faster expansion belongs to containerized solutions.
Application:
End-use economics determine specification intensity, with grid-connected assets facing stricter certification burdens than captive industrial installations.
- Power Distribution:Utility-owned assets interconnect medium-voltage feeders with low-voltage distribution networks through ring-main units and circuit breaker configurations. Indian state electricity boards and French distribution operators dominate procurement volumes under rural electrification mandates and SF6 replacement programs. CEA certification and EU F-Gas Regulation compliance reshape material specifications.
- Renewable Energy Integration:Solar and wind projects require rapid grid-connection turnaround with pre-tested assemblies minimizing commissioning risk. Developers in Spain and solar parks in Rajasthan specify containerized units to compress project timelines. Vacuum interrupter technology displaces gas-insulated alternatives across medium-voltage ratings.
- Industrial Use:Mining and extraction corridors in Australia and Chile deploy modular transportable units lacking permanent infrastructure.
- Commercial Use:Retail and office complexes specify compact indoor installations with noise-attenuated enclosures.
Power distribution commands current shipment volumes; renewable energy integration is climbing the fastest.
End User:
Procurement sophistication separates institutional buyers from commercial purchasers, with utilities unbundling supply from installation while contractors seek turnkey margins.
- Utilities:Grid operators specify standardized designs with digital twin compatibility and predictive maintenance integration. German and French utilities front-load replacement orders ahead of SF6 supply constraints. Unbundled tendering for supply and commissioning compresses manufacturer margins on turnkey contracts.
- Contractors:EPC firms capture civil works and site integration value through separate bidding in Indian state electricity board tenders.
- Manufacturers:Industrial facilities with captive generation specify packaged interconnection equipment.
- Large Enterprises:Data center operators and mining companies drive premium pricing for rapid-deployment configurations.
Utilities anchor procurement volumes; large enterprises generate the steepest margin expansion.
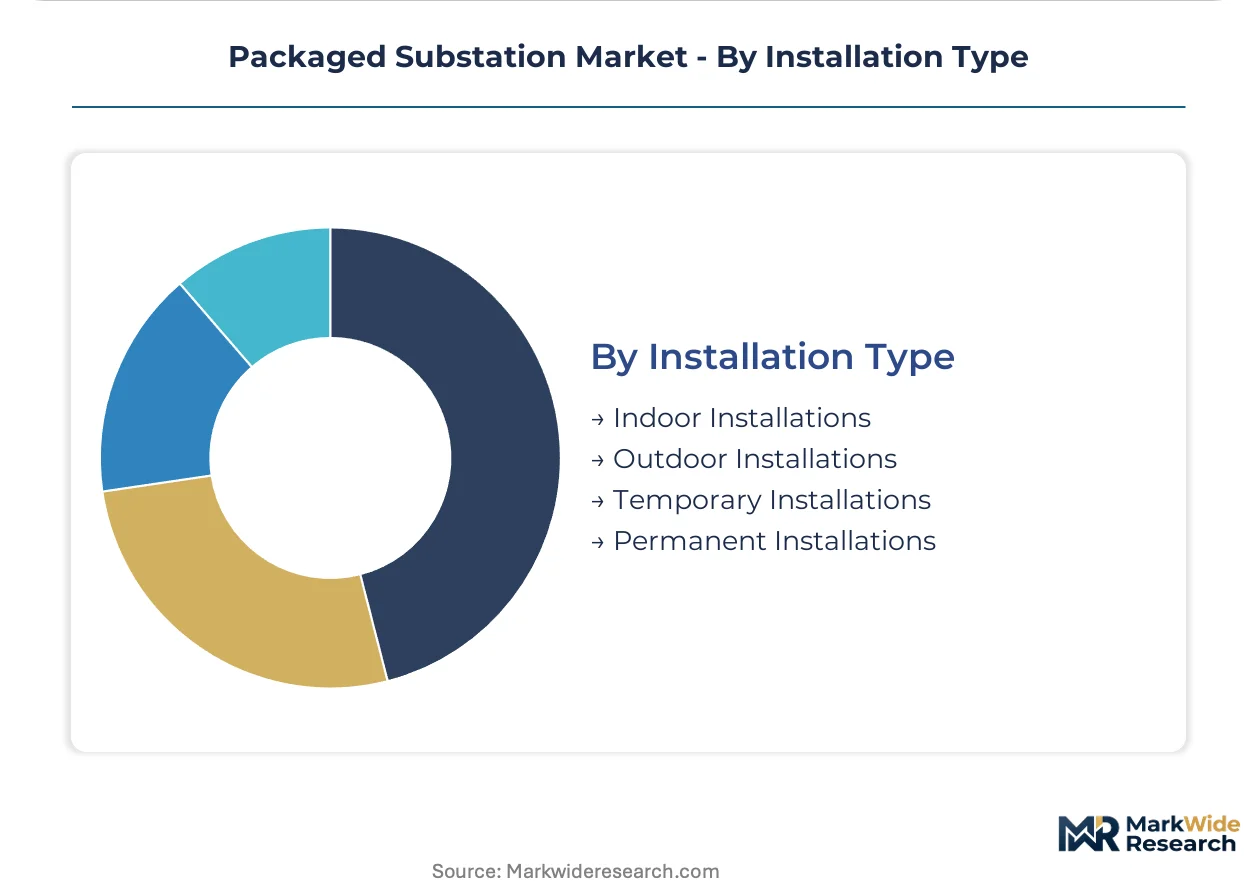
Installation Type:
Permanence expectations determine enclosure durability and foundation requirements, with temporary deployments prioritizing transportability over weatherproofing.
- Outdoor Installations:Weather-resistant enclosures with IP-rated sealing and thermal management serve exposed locations. Urban utilities in India and rural extensions across sub-Saharan markets specify these for minimal site preparation. Salt-fog testing protocols apply to coastal and offshore deployments.
- Indoor Installations:Reduced weatherproofing requirements enable cost-optimized designs for controlled environments.
- Temporary Installations:Skid-mounted or trailer-based units serve construction sites and emergency restoration.
- Permanent Installations:Concrete-pad foundations with buried cable trenches support decades-long asset lifecycles.
Outdoor installations dominate current deployment; temporary installations are gaining share fastest in mining and emergency response segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gurgaon-Manesar industrial corridor anchors packaged substation fabrication for Indian metro rail and rural electrification programs. Containerized unit deployment concentrates in Noida and Chennai manufacturing zones.
India
Rural electrification mandates and urban metro expansions drive containerized substation procurement across Maharashtra and Karnataka. The Central Electricity Authority certification requirements compress supplier qualification timelines. Larsen & Toubro and C&S Electric fabrication facilities in Gurgaon and Chennai dominate domestic tender volumes.
Germany
Offshore wind grid connections and data center buildouts accelerate marine-grade containerized unit demand in Hamburg and Bremerhaven ports. The EU F-Gas Regulation forces vacuum interrupter migration across medium-voltage switchgear lines. Siemens Energy AG and ABB Ltd. engineering centers in Erlangen and Heidelberg lead SF6-free technology certification.
United States
Hyperscale data center operators in Northern Virginia and Dallas-Fort Worth specify factory-assembled units for rapid energization. FERC interconnection standards and state renewable portfolio mandates reshape procurement specifications. Eaton Corporation and General Electric manufacturing presence in Pittsburgh and Atlanta serves utility replacement cycles.
France
Distribution utility SF6 replacement programs front-load orders ahead of supply constraints in Île-de-France and Auvergne-Rhône-Alpes. The EU Green Deal binding targets accelerate vacuum interrupter adoption. Schneider Electric SE headquarters and engineering operations in Rueil-Malmaison anchor premium-tier digital twin integration.
Australia
Remote mining electrification corridors in Western Australia and Queensland deploy modular transportable units lacking permanent infrastructure. Salt-fog testing protocols apply to coastal deployments. Hitachi Energy Ltd. and regional fabricators serve extraction operations in Pilbara and Bowen Basin.
Packaged Substation Market Vendor Landscape
Premium-margin players sit above commodity-margin players across digital integration and certification speed dimensions. The supplier base concentrates around three strategic tiers: diversified electrical conglomerates with full-stack capabilities, regional specialists with cost-optimized compact designs, and technology licensors with proprietary insulation systems. Consolidation pressure intensifies as SF6-phaseout timelines compress viable product line lifecycles. Dominant competitive moves include backward integration into vacuum interrupter manufacturing and strategic partnerships for offshore wind marine certification.
Among diversified electrical conglomerates, ABB Ltd., Siemens Energy AG, and Schneider Electric SE exemplify the three archetype positions. ABB Ltd. anchors the volume-optimized tier through standardized compact designs engineered for emerging market cost structures. Siemens Energy AG occupies the premium-integration position via digital twin platforms and predictive maintenance software bundling. Schneider Electric SE represents the ecosystem-centric model through IoT-enabled monitoring as a default feature across mid-tier and premium configurations.
| Leading Market Players |
|---|
| ABB Ltd. |
| Siemens Energy AG |
| Schneider Electric SE |
| General Electric Company |
| Eaton Corporation |
| Hitachi Energy Ltd. |
| Larsen & Toubro Ltd. |
| C&S Electric Ltd. |
| Kirloskar Electric Company |
| Others |
Supply Flow & Price Mechanics
Vacuum interrupter engineering talent scarcity in Germany and Japan widens labor-cost differentials that separate premium-tier digital-integrated substations from commodity compact units. These regional skill concentrations compress margins for SF6-free certification investments while amplifying price spreads between certified and uncertified supplier tiers.
Pricing Analysis
Value-based pricing anchored to energization uptime and grid-connection speed separates containerized solutions from permanent installations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and digital twin integration depth. Cost compression in compact substations intensifies as Indian state electricity boards unbundle supply from installation contracts. Data center operators exhibit lowest price sensitivity; rural electrification contractors face acute margin pressure.
Supply Chain Analysis
CEA certification and IEC 62271 type-testing requirements gate supplier qualification timelines, compressing viable vendor pools. Manufacturing concentrates in India, Germany, and Japan. Transformer production draws from copper and grain-oriented electrical steel feedstocks. Single-source vulnerability clusters around vacuum interrupter fabrication in Erlangen and Heidelberg engineering centers. Distribution runs through EPC contractors capturing civil works value in Indian tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The packaged substation market occupies a technology-transition phase where vacuum interrupter platforms displace SF6-dependent switchgear across medium-voltage ratings. This substitution dynamic reconfigures competitive moats around certification speed and arc-quenching physics expertise.
For Market Incumbents:Lock in backward integration into vacuum interrupter manufacturing to secure captive supply of SF6-free components before fabrication chokepoints tighten. Accelerate digital twin platform deployment to capture predictive maintenance recurring revenue streams against emerging software-native competitors. Prioritize marine-grade certification investment for North Sea offshore wind lease rounds.
For New Entrants and Emerging Players:The EU F-Gas Regulation in Europe opens a window for specialized vacuum interrupter suppliers to capture share from legacy gas-insulated incumbents during retooling transitions. Target containerized retrofit opportunities for mid-tier utilities seeking IoT monitoring upgrades without full asset replacement. Pursue direct EPC partnerships in Indian metro rail corridors where rapid-deployment specifications favor agile fabricators.
For Investors and Strategic Acquirers:Re-rating potential sits with vacuum interrupter technology licensors given binding SF6 phaseout mandates across European utility fleets. Long-term viability hinges on five-to-ten-year certification runway visibility. Monitor IEC 62271 type-test completion rates as inflection indicator for viable product line commercialization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum Interrupter Manufacturing | Captive supply of SF6-free components insulates margins from German and Japanese fabrication chokepoints. |
| Marine-Grade Certification Investment | Salt-corrosion resistance credentials unlock North Sea offshore wind grid connection contracts. |
| Digital Twin Platform Deployment | Predictive maintenance software bundling commands premium positioning in European utility tenders. |
| IoT Monitoring Retrofit Programs | EcoStruxure-compatible upgrades capture mid-tier utility budgets without full substation replacement. |
| CEA Certification Fast-Track Investment | Compressed qualification timelines secure access to Indian rural electrification and metro rail procurement. |
Methodological Framework
Document review covered IEC 62271 standards documentation, EU F-Gas Regulation implementation guidance, and CEA certification protocols, complemented by interviews with utility planning officers, EPC contractors, and transformer procurement leads at state electricity boards. Secondary validation drew from customs trade data, FERC interconnection filings, and IEA grid infrastructure reports. Bottom-up shipment analysis triangulated against top-down market sizing across product type and application segments.
Installed base forecasts and replacement cycle projections emerged from segment-level modeling across compact, containerized, and mobile enclosure formats. The analytical framework incorporated renewable energy interconnection velocity, data center buildout cadence, and SF6 phaseout compliance timelines throughout the forecast period. CAGRs derived from regression analysis of historical shipment patterns against regulatory mandate acceleration curves and commodity input cost trajectories.
The model assumes a particular technology adoption path; alternative pathways for solid-state insulation or air-insulated switchgear would alter the outlook for vacuum interrupter demand trajectories. Forecasts reflect assumptions regarding IEC certification timeline stability and copper price volatility bands. A model refresh is warranted upon material change in EU F-Gas Regulation enforcement intensity or Indian CEA mandate expansion scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
HVDC Converter Station Market
Electrical Power Equipment
US Electric Towers and Poles Market
Electrical Power Equipment
Copper Ground Rod Market
Electrical Power Equipment
North America Surge Arresters Market
Electrical Power Equipment
North America Air-Insulated Switchgear Market
Electrical Power Equipment
Electrodialysis System Market
Electrical Power Equipment
Utility Poles Market
Electrical Power Equipment
Frameless Brushless DC Motors Market
Electrical Power Equipment
Power Strip Market
Electrical Power Equipment
Middle East and Africa Hazardous Location Motor Starters Market
Electrical Power Equipment
Europe Brushless DC Motors Market
Electrical Power Equipment
North America Power Inverter Market
Electrical Power Equipment
AC-DC Controller Market
Electrical Power Equipment
Global Hazardous Location Motor Starters Market
Electrical Power Equipment
Skid Mounted Unit Substations Market
Electrical Power Equipment
Power Line Carrier System Market