
 High Voltage (35-550 KV) Power Transformer Market | 2026-2036
High Voltage (35-550 KV) Power Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
High Voltage (35-550 KV) Power Transformer Market Insights
Digital twin integration is rewriting transformer lifecycle management by enabling predictive diagnostics and condition-based maintenance across fleet operations. Siemens Energy leverages its software-hardware convergence to anchor long-term service contracts. Hitachi Energy competes through advanced insulation fluid technologies that extend asset durability in extreme climates. TBEA dominates ultra-high-voltage manufacturing scale for long-distance transmission corridors.
High voltage power transformers are electromagnetic devices rated between 35 kV and 550 kV that transfer electrical energy across primary and secondary windings through magnetic induction, typically employing mineral oil or ester-based dielectric fluids for insulation and thermal management. These assets form the backbone of bulk power transmission networks, stepping voltage up for efficient long-haul distribution and down for regional consumption. Oil-cooled designs retain the largest installed base due to superior thermal performance at elevated MVA ratings, while air-cooled variants capture niche indoor and environmentally sensitive installations where fire safety and spill containment constrain fluid selection. Renewable energy end users represent the fastest-expanding demand pool as offshore wind and solar parks require dedicated step-up transformers for grid injection.
IEC 60076 governs international transformer testing protocols and loss evaluation, while EPA regulations restrict sulfur hexafluoride emissions from switchgear commonly co-located with transformer substations. IEEE C57.12.00 shapes North American construction standards and short-circuit withstand requirements. Grid operators and asset owners must weigh copper versus aluminum winding economics against evolving efficiency mandates and extended lead times for core steel procurement.
Market Dynamics
Digital twin deployment is compressing transformer maintenance cycles and locking utilities into long-term platform contracts with equipment vendors.
Growth Catalysts
- Grid Interconnection Mandates:India's CEA and China's State Grid are accelerating ultra-high-voltage corridor buildouts to absorb renewable generation from western provinces.
- IEC 60076 Efficiency Tiers:Loss evaluation standards are forcing asset replacement across European transmission networks operating 1970s-era oil-cooled units.
- Offshore Wind Clustering:North Sea lease rounds in Germany, the Netherlands, and Denmark are generating dedicated step-up transformer demand for 66 kV collector systems.
Market Restraints
- Grain-Oriented Electrical Steel Concentration:Nippon Steel and POSCO control over 70% of high-permeability core steel supply, extending lead times to 18-24 months.
- SF6 Regulatory Friction:EPA emission restrictions and EU F-Gas Regulation phase-down schedules are complicating switchgear-transformer co-location designs.
- Copper-Aluminum Cost Volatility:LME price swings in winding conductors are destabilizing project economics for multi-unit utility tenders.
Strategic Opportunities
- Sub-Saharan Grid Extension:Kenya, Ethiopia, and Nigeria lack domestic 132 kV+ manufacturing capacity, creating import-dependent white space for established suppliers.
- Natural Ester Fluid Conversion:Fire-safety codes in urban substations are displacing mineral oil with FR3 and MIDEL 7131 biodegradable alternatives.
- Modular Mobile Substations:Rapid-deployment skids for data center campuses and disaster recovery are bypassing traditional 18-month installation timelines.
Industry Challenges
- Specialized Winding Technician Scarcity:Vacuum pressure impregnation and interleaved disc coil expertise is concentrated among retiring European and Japanese craft workers.
- Short-Circuit Withstand Certification Bottlenecks:IEEE C57.12.00 and IEC 60076-5 testing queue lengths at KEMA and CESI laboratories now exceed 14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Voltage (35-550 KV) Power Transformer Market |
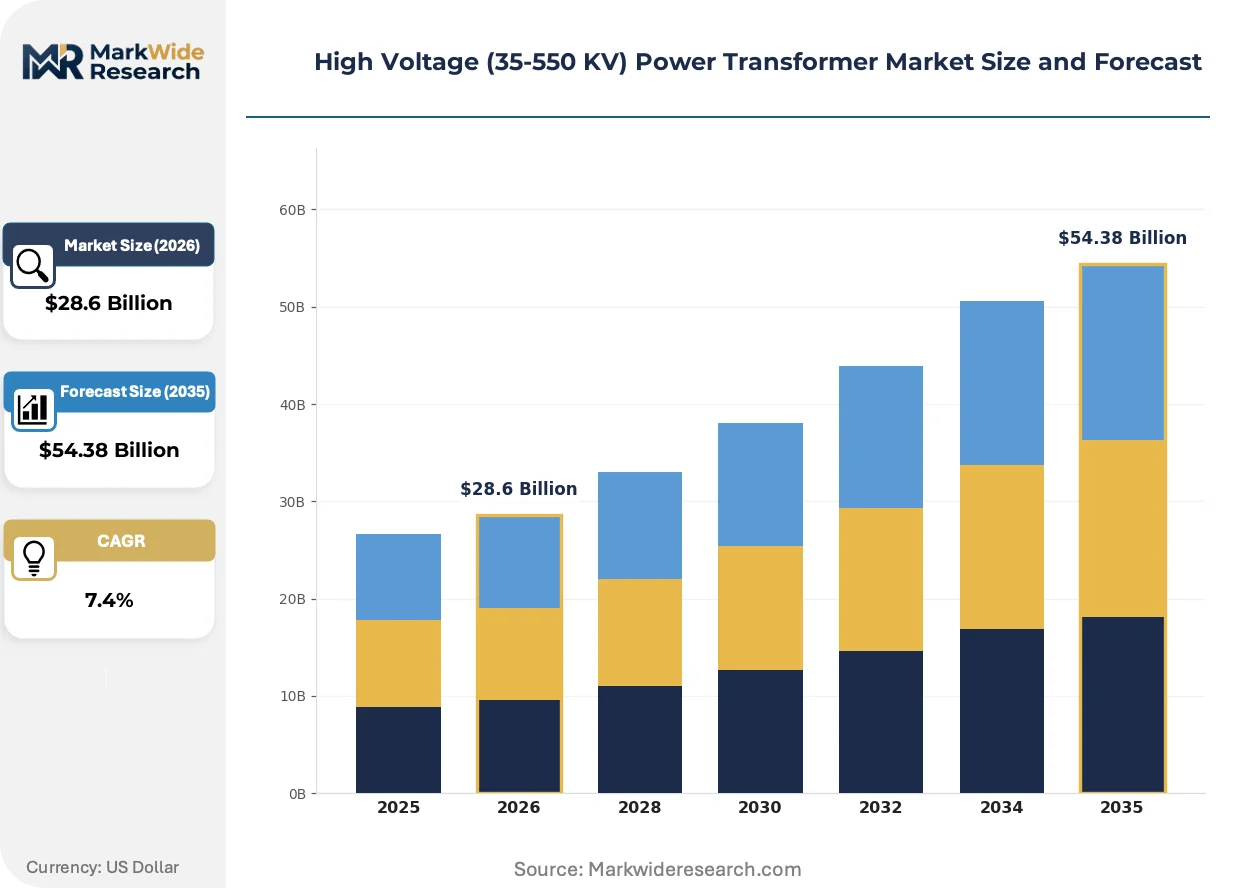
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $54.38 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Step-Up, Step-Down, Auto-Transformer, Isolation End User: Utilities, Industrial, Renewable Energy, Commercial Installation: Indoor, Outdoor, Substation, Overhead Cooling Method: Air-Cooled, Oil-Cooled, Water-Cooled, Others |
| Companies Covered | Siemens Energy, Hitachi Energy, General Electric, ABB, Toshiba Energy Systems & Solutions Corporation, Schneider Electric, Mitsubishi Electric Corporation, Hyundai Electric & Energy Systems, TBEA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Voltage (35-550 KV) Power Transformer Market Trends and Innovations
Transformer lifecycle economics are pivoting from capital expenditure optimization toward total cost of ownership models that monetize reliability and deferred replacement.
Digital twin platforms are virtualizing condition monitoring across transmission fleets by aggregating dissolved gas analysis, thermal imaging, and load tap changer operation data into predictive failure models. European TSOs including TenneT and National Grid ESO are deploying these systems at scale, compressing maintenance intervals from time-based to condition-triggered interventions. The technology is virtualizing traditional service contract structures by embedding software subscriptions into original equipment procurement.
EPA SF6 emission restrictions and the EU F-Gas Regulation are accelerating dry-type and fluoronitrile-insulated designs in environmentally sensitive substations. Manufacturers are redesigning 145 kV class units to eliminate gas-dependent switchgear co-location. North American utilities in California and New York are most affected, specifying SF6-free alternatives for urban corridor projects to preempt state-level phase-out mandates.
Asset performance guarantees are displacing conventional warranty terms in utility procurement frameworks. Buyers now demand liquidated damages clauses tied to availability metrics rather than defect coverage periods. This shift is most visible in offshore wind EPC contracts in the North Sea and Baltic markets, where transformer unavailability triggers cascade penalties across generation offtake agreements.
High Voltage (35-550 KV) Power Transformer Market Segmentation
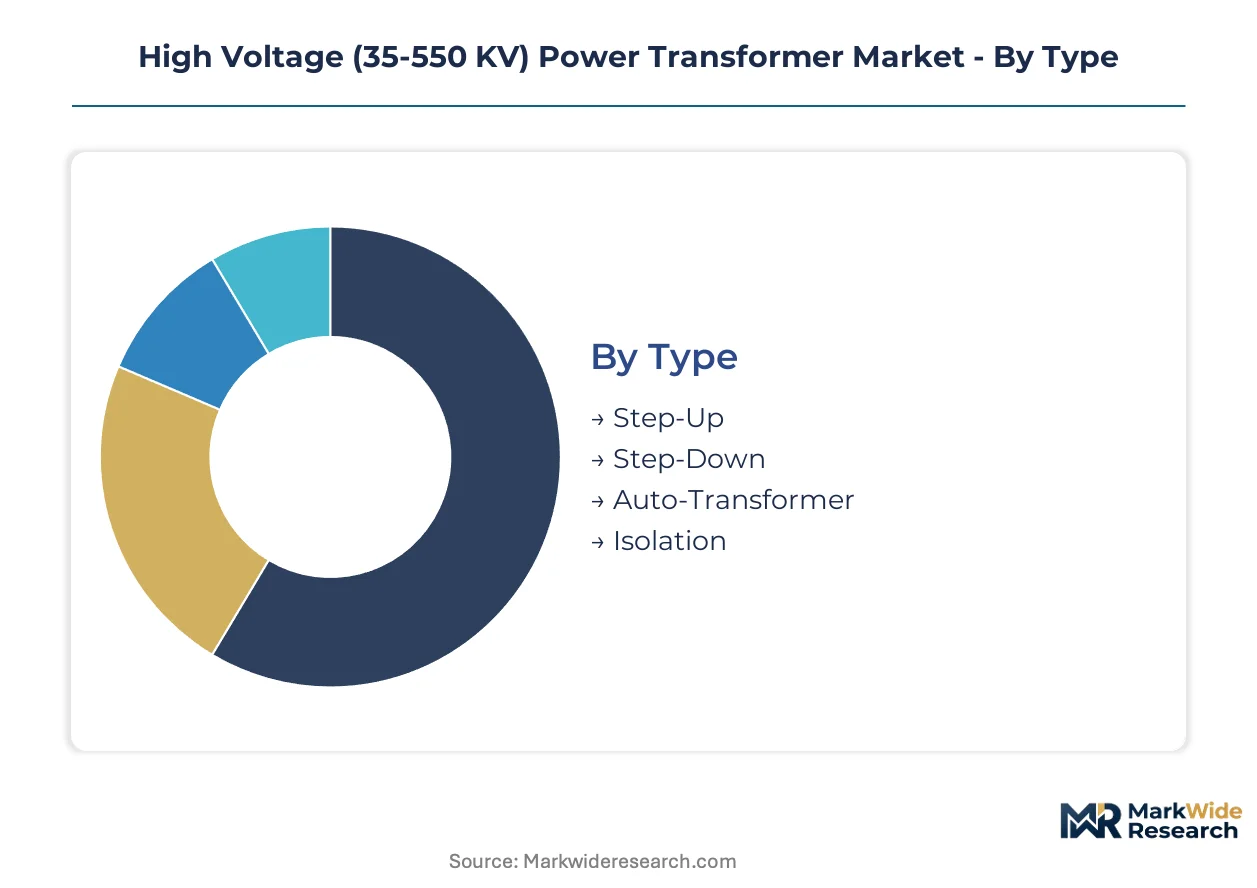
Segmentation in high voltage power transformers reveals divergent engineering requirements across voltage classes and cooling architectures. Service contract structures vary dramatically by installation environment and end-use criticality, with offshore wind assets commanding premium lifecycle support versus utility bulk transmission units.
Type:
After-sales-service intensity escalates with unit complexity and operational criticality, creating tiered vendor engagement models across transformer architectures.
- Step-Up:These units elevate generator output to transmission voltages for long-distance power transfer, typically installed at power plant switchyards and renewable energy collector stations. Demand concentrates in offshore wind clusters off Germany, Denmark, and the Netherlands where 66 kV to 220 kV step-up configurations integrate turbine arrays to onshore grids. Specialized dissolved gas analysis monitoring and load tap changer refurbishment dominate service spend.
- Step-Down:Voltage reduction units connect high-voltage transmission to sub-transmission and distribution networks, typically sited at bulk supply points and grid interconnection nodes. Procurement in India and China favors these assets for urban ring-main expansion and rural electrification corridors where IEC 60076 efficiency tiers mandate loss reduction. Service intervals focus on bushing replacement and core steel thermal monitoring.
- Auto-Transformer:Single-winding designs with electrical connection between primary and secondary achieve material savings in high-voltage intertie applications.
- Isolation:Galvanic separation units block DC offset and harmonic propagation between network segments, deployed in sensitive industrial feeds.
By volume, Step-Down leads. By growth pace, Step-Up is ahead.
End User:
Customer procurement authority shapes specification stringency, with regulated utilities enforcing standardized loss evaluation against industrial buyers prioritizing compact footprint.
- Utilities:State-grid and transmission system operator procurement dominates unit volume, governed by IEC 60076 and IEEE C57.12.00 testing protocols with mandatory short-circuit withstand certification. India's CEA and China's State Grid drive corridor buildouts for western province renewable absorption. Asset performance guarantees and availability-based liquidated damages clauses now standard in tender frameworks.
- Renewable Energy:Offshore wind developers and solar park operators represent the steepest expansion trajectory, requiring dedicated step-up transformers for grid injection at 66 kV and 132 kV collector voltages. North Sea lease rounds in Germany, the Netherlands, and Denmark generate concentrated demand for 220 kV+ offshore platform units with marine-grade corrosion protection and modular installation protocols.
- Industrial:Steel, aluminum, and chemical processing facilities specify ruggedized units for direct high-voltage feedstock power.
- Commercial:Data center campuses and large retail distribution centers drive mobile substation demand for rapid deployment.
Utilities anchor current installed base. Renewable Energy is expanding most quickly.
Installation:
Physical siting determines environmental protection specifications and fire-safety compliance burdens, with urban constraints accelerating fluid technology substitution.
- Outdoor:Open-air substation deployment retains majority share, utilizing mineral oil insulation with containment berms and fire suppression systems. India's transmission expansion and US grid hardening against extreme weather sustain procurement volume. EPA SF6 restrictions and EU F-Gas Regulation complicate switchgear co-location in environmentally sensitive corridors.
- Indoor:Enclosed installations in urban substations and commercial facilities mandate fire-safety codes that displace mineral oil with FR3 and MIDEL 7131 natural ester alternatives. California and New York utilities specify SF6-free designs to preempt state-level phase-out mandates, with dry-type and fluoronitrile-insulated units gaining specification share.
- Substation:Purpose-built switchyard configurations integrate transformer, switchgear, and protection systems as engineered packages.
- Overhead:Pole-mounted and platform-suspended units serve remote distribution and temporary construction feeds.
Outdoor dominates unit shipments. Indoor is gaining share fastest.
Cooling Method:
Thermal management architecture directly constrains MVA rating ceilings and maintenance cadence, with fluid selection increasingly regulated by environmental compliance.
- Oil-Cooled:Mineral oil and ester-based dielectric fluids deliver superior thermal performance at elevated MVA ratings above 100 MVA, retaining the largest installed base in bulk transmission. Nippon Steel and POSCO grain-oriented electrical steel concentration extends core procurement lead times to 18-24 months for these high-specification units. Dissolved gas analysis and filtration service contracts generate recurring vendor revenue.
- Air-Cooled:Dry-type designs eliminate fluid spill risk and fire hazard, capturing niche indoor and environmentally sensitive installations where fire safety constrains fluid selection. California urban corridor projects and European underground substations drive specification, though thermal limits restrict application below 63 MVA in most voltage classes.
- Water-Cooled:Forced water circulation achieves compact footprint in high-density industrial and offshore platform applications.
- Others:Hybrid and phase-change cooling architectures address specialized high-altitude and desert climate installations.
Oil-Cooled leads by installed capacity. Air-Cooled is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports ultra-high-voltage transformers along dedicated transmission corridors to Pakistan and Southeast Asian markets. Germany and Switzerland supply specialized insulation technologies to North Sea offshore wind clusters. India's domestic manufacturers struggle to meet 765 kV demand despite CEA localization mandates.
United States
Grid hardening investments against extreme weather drive replacement demand for 1970s-era oil-cooled units. EPA SF6 emission restrictions complicate switchgear co-location in California and New York urban corridors. ERCOT's Texas interconnection and PJM's Mid-Atlantic footprint concentrate procurement volume for 345 kV and 500 kV step-down assets.
China
State Grid Corporation accelerates ultra-high-voltage DC corridor buildouts to absorb western province renewable generation. MIIT domestic content requirements and dual carbon goals tighten efficiency specifications for 1000 kV class manufacturing. Xinjiang and Gansu wind-solar bases feed long-distance transmission to eastern load centers through TBEA-supplied converter stations.
Germany
North Sea offshore wind lease rounds generate concentrated demand for 220 kV+ platform-installed step-up transformers. EU F-Gas Regulation phase-down schedules force SF6-free switchgear redesigns in TenneT and 50Hertz transmission corridors. Hamburg and Bremerhaven marine fabrication clusters specialize in corrosion-resistant unit assembly for Baltic and North Sea installations.
India
CEA mandates 132 kV+ manufacturing localization as grid interconnection expands to accommodate western state solar parks. BIS efficiency standards and PLI scheme incentives attract joint ventures between domestic fabricators and European technology licensors. Gujarat and Rajasthan renewable zones drive step-up transformer demand for 765 kV corridor injection.
Japan
Metropolitan area underground substation constraints accelerate natural ester fluid adoption for fire-safety compliance. METI efficiency benchmarks and earthquake resilience codes shape 275 kV and 500 kV replacement cycles. Tokyo and Osaka urban rings concentrate indoor installation demand where dry-type and fluoronitrile-insulated designs displace conventional oil-cooled architectures.
High Voltage (35-550 KV) Power Transformer Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement frameworks that favor long-term service bundling over discrete equipment sales. The vendor base organizes into three tiers: integrated energy conglomerates with software-hardware convergence capabilities, regional scale manufacturers with cost-optimized production platforms, and niche technology specialists with advanced insulation or monitoring intellectual property. Dominant competitive moves include backward integration into grain-oriented electrical steel supply and technology licensing partnerships for natural ester fluid formulations.
Within the integrated conglomerate tier, Siemens Energy and Hitachi Energy exemplify platform-based competition through digital twin integration and lifecycle service anchoring. TBEA occupies a position among scale-driven manufacturers with concentrated ultra-high-voltage production capacity for long-distance transmission corridors. These three entities represent divergent strategic archetypes: software-embedded service models, advanced materials specialization, and manufacturing scale dominance.
| Leading Market Players |
|---|
| Siemens Energy |
| Hitachi Energy |
| General Electric |
| ABB |
| Toshiba Energy Systems & Solutions Corporation |
| Schneider Electric |
| Mitsubishi Electric Corporation |
| Hyundai Electric & Energy Systems |
| TBEA |
| Others |
Pricing and Supply Chain Analysis
Xinjiang and Gansu manufacturing clusters anchor ultra-high-voltage transformer production capacity, with their expansion dynamics directly transmitting into downstream pricing leverage for 1000 kV class units. State Grid procurement frameworks absorb cost volatility through multi-year offtake structures, while export markets face spot-price exposure to grain-oriented electrical steel fluctuations.
Pricing Analysis
Next-generation digital-twin-integrated transformer systems command substantial premiums over conventional IEC 60076 baseline units, while prior-generation oil-cooled designs face accelerated price erosion. Project-based contracting dominates utility procurement, with price differentiation driven by IEC 60076 loss-tier certification and bundled lifecycle service intensity. Cost compression in standard-efficiency tiers intensifies due to aluminum winding substitution, though copper-intensive specifications retain pricing resilience. Renewable energy developers exhibit highest price sensitivity, prioritizing capital expenditure minimization over availability guarantees.
Supply Chain Analysis
Grain-oriented electrical steel feedstock concentrates in Japan, South Korea, and China, with Nippon Steel and POSCO controlling premium high-permeability grades. Copper and aluminum winding conductors draw from Chilean mining operations and Chinese smelting capacity, while natural ester fluids source from North American and European agricultural processing. Single-source vulnerability in core steel extends procurement lead times, with distribution running through regional fabrication hubs in Germany, India, and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital twin platform economics are displacing discrete equipment sales with subscription-anchored service ecosystems, as interoperability standards between transformer monitoring systems and grid control software reshape vendor lock-in dynamics.
For Market Incumbents: Entrench position through backward integration into grain-oriented electrical steel supply and captive natural ester fluid formulation capacity. Siemens Energy and Hitachi Energy demonstrate platform-based defense through software-hardware convergence that embeds long-term service contracts. Prioritize certification investment at KEMA and CESI laboratories to bypass testing queue bottlenecks that constrain competitor delivery schedules. For New Entrants and Emerging Players: Sub-Saharan grid extension markets in Kenya, Ethiopia, and Nigeria represent the most penetrable entry point, given absent domestic 132 kV+ manufacturing capacity and import-dependent procurement frameworks. Modular mobile substations for data center campuses and disaster recovery applications bypass traditional 18-month installation timelines. Partner with European technology licensors for natural ester fluid expertise to differentiate on fire-safety compliance in urban substation specifications. For Investors and Strategic Acquirers: Long-term, this sits as a critical infrastructure replacement play because transmission asset age profiles across OECD networks mandate systematic renewal regardless of demand cyclicality. Acquisition targets should prioritize specialist winding technicians with vacuum pressure impregnation expertise and laboratories holding IEC 60076-5 short-circuit withstand certification. Monitor EPA SF6 emission restriction enforcement intensity and EU F-Gas Regulation phase-down schedules as regulatory inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Deployment | Siemens Energy leverages software-hardware convergence to anchor long-term service contracts across European TSO fleets. |
| Natural Ester Fluid Conversion | Hitachi Energy's advanced insulation technologies extend asset durability in California and New York urban substations facing fire-safety mandates. |
| Ultra-High-Voltage Capacity Expansion | TBEA dominates 1000 kV manufacturing scale for China's western province renewable absorption corridors. |
| Backward Integration into Core Steel | Captive grain-oriented electrical steel supply mitigates Nippon Steel and POSCO concentration risk extending lead times. |
| Modular Mobile Substation Development | Rapid-deployment skids bypass traditional installation timelines for data center campuses and disaster recovery applications. |
Research Methodology
The analysis maps step-up, step-down, auto-transformer, and isolation configurations, each validated through transmission system operator planning officers, EPC contractor procurement leads, utility asset managers, and aftermarket service heads. Primary interviews with grid operators across Germany, India, China, and the United States combined with secondary validation from IEC 60076 testing protocols, EPA emission filings, FERC interconnection queues, and State Grid procurement disclosures. Bottom-up unit shipment aggregation and top-down transmission investment flow triangulation anchored volume and value estimates.
Assumptions held grid interconnection mandates and IEC 60076 efficiency tier enforcement as fixed baseline conditions, while renewable energy penetration rates and grain-oriented electrical steel availability varied across sensitivity scenarios. Segmentation modeling spanned voltage class, cooling architecture, installation environment, and end-use criticality. CAGRs derived from regression against historical transmission capital expenditure patterns and utility fleet replacement schedules, with dissolved gas analysis adoption curves and natural ester fluid conversion rates as industry-specific forecast inputs across the projection horizon.
Macroeconomic conditions sit as an overlay; deviation in copper and aluminum LME pricing, central bank rate trajectories affecting utility capital access, or geopolitical disruption to Japanese and South Korean steel exports would shift the trajectory. Cross-checking against IEA transmission investment databases and national regulatory commission interconnection backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Air Cooled Transformer Market
Transformers
Asia-Pacific Power Transformer (Below 100 MVA) Market
Transformers
Latin America Transformer Market
Transformers
United Arab Emirates Transformer Market
Transformers
High Frequency Transformer Market
Transformers
India Distribution Transformer Market
Transformers
Transformer Core Market
Transformers
EHV & UHV (above 330KV) Power Transformers Market
Transformers
Middle-East Smart Transformer Market
Transformers
China Transformer Market
Transformers
Single Phase Power Transformer Market
Transformers
Distribution Transformer Market
Transformers
North America Smart Transformers Market
Transformers
Europe Telecom Transformers Market
Transformers
Green Transformer Market
Transformers
Green Power Transformers Market