
 Neon Transformer Market | 2026-2036
Neon Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Neon Transformer Market Insights
Skilled electrical technician availability is collapsing across mature manufacturing economies, forcing neon transformer producers to automate winding and testing operations or relocate production to technical training hubs. ACME Electric Corporation leverages its domestic coil-winding expertise to sustain shorter lead times for custom high-voltage orders. Siemens AG anchors European demand through captive supply relationships with municipal signage contractors. Toshiba Corporation competes on compact magnetic core designs that reduce copper content without sacrificing output stability.
A neon transformer is an electromagnetic device that converts standard mains voltage to the elevated potential required to ionize neon or noble gas mixtures within sealed glass tubing, typically delivering outputs between 2,000 and 15,000 volts at frequencies between 20 and 50 kHz. Its core function is sustaining continuous gas discharge for illuminated signage, architectural accent lighting, and industrial indicator systems. High-voltage product types dominate revenue due to their irreplaceable role in large-format outdoor installations where line losses would otherwise degrade luminance uniformity. Smart technology variants are gaining fastest traction as building automation protocols demand remote dimming, fault detection, and energy metering integration.
EPA efficiency standards and the EU F-Gas Regulation constrain legacy analog transformer designs while accelerating digital and wireless technology adoption. OSHA electrical safety mandates and IEC 61558 insulation requirements shape product certification barriers for cross-border market access. Stakeholders must monitor evolving building code electrification requirements and assess whether backward integration into ferrite core sourcing or forward integration into lighting system contracting offers superior margin protection.
Market Dynamics
Digital inverter technology is fragmenting the neon transformer value chain as solid-state electronics displace electromagnetic cores, forcing incumbent manufacturers to retool winding operations or exit high-frequency segments entirely.
Growth Catalysts
- EU Green Deal efficiency mandates:Tightening energy-performance standards under the EU Green Deal and EPA guidelines are accelerating replacement cycles for legacy magnetic-core units in commercial signage installations.
- Urban renewal procurement:Municipal signage contractors in the United States, Germany, and China are sourcing high-voltage transformers for transit hub and retail district revitalization projects.
- Smart building integration:BACnet and DALI protocol adoption is pulling demand for digitally addressable transformers with embedded fault detection and remote dimming capabilities.
Market Restraints
- Copper price volatility:Magnetic-core transformer production remains exposed to LME copper price swings, compressing margins on custom-wound high-voltage orders.
- Technical training hub concentration:Skilled coil-winding technician availability has collapsed across mature manufacturing economies, forcing automation capital expenditure or production relocation.
- LED substitution pressure:Solid-state LED signage systems are capturing budget allocations previously reserved for neon gas-discharge installations in cost-sensitive retail applications.
Strategic Opportunities
- Heritage restoration niche:Historic district preservation mandates in Germany and France are sustaining demand for authentic neon signage requiring electromagnetic transformer compatibility.
- Wireless mesh convergence:Integration of LoRaWAN and NB-IoT connectivity into transformer housings enables predictive maintenance subscriptions for large-format outdoor operators.
- Industrial indicator expansion:Process control and hazardous-area signaling applications in chemical and oil-and-gas facilities represent underpenetrated demand for explosion-rated high-voltage units.
Industry Challenges
- Certification timeline compression:IEC 61558 insulation testing and OSHA electrical safety validation cycles are extending time-to-revenue for new product variants by six to twelve months.
- Legacy system integration friction:Building automation retrofits require protocol bridging hardware that complicates transformer specification and raises total installed cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neon Transformer Market |
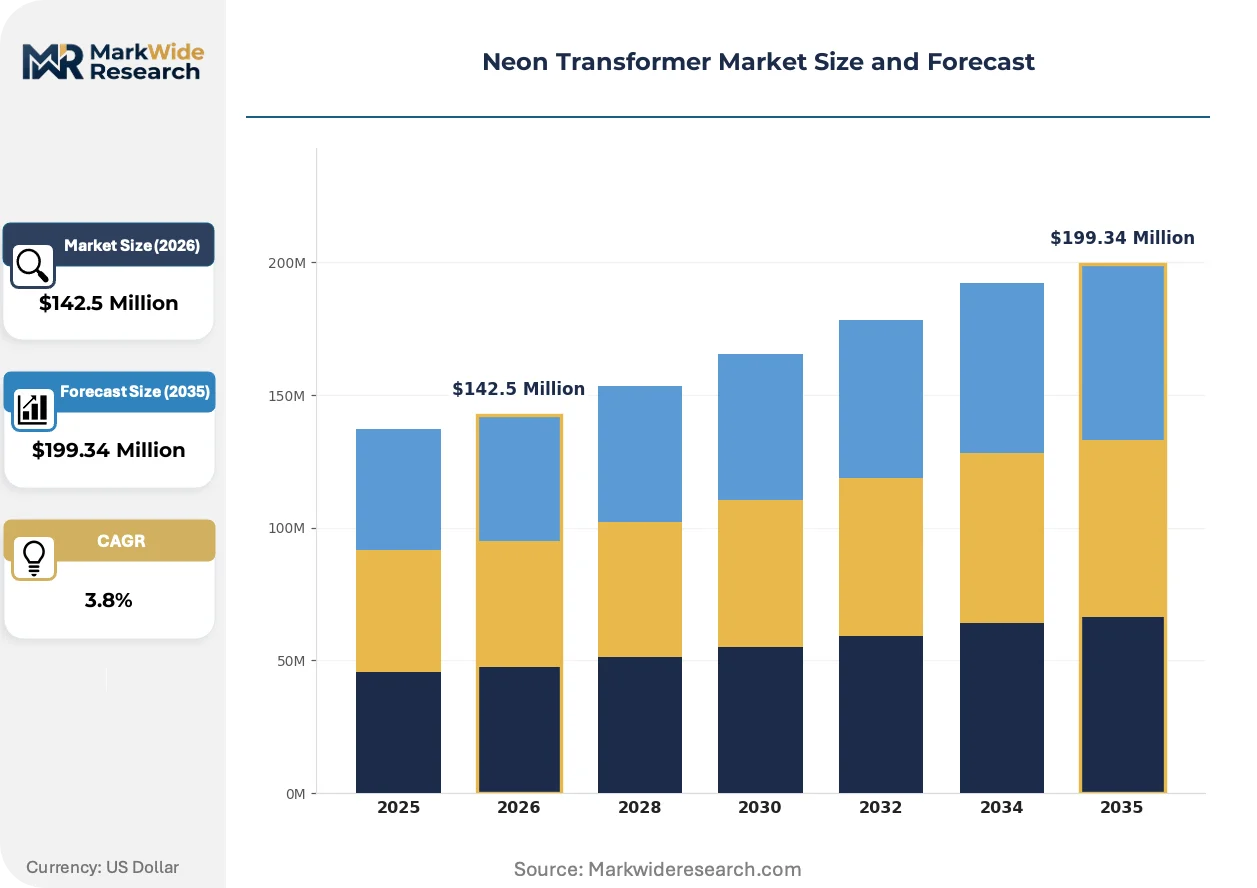
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $199.34 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Voltage, Low Voltage, Step-Up, Step-Down Application: Signage, Decorative Lighting, Industrial Lighting, Architectural Lighting End User: Retail, Hospitality, Entertainment, Manufacturing Technology: Analog, Digital, Wireless, Smart |
| Companies Covered | ACME Electric Corporation, ABB Ltd., Siemens AG, Schneider Electric, Eaton Corporation, GE Grid Solutions, Toshiba Corporation, Lecip Holdings Corp., West Coast Custom Designs LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neon Transformer Market Trends and Innovations
Solid-state power electronics are actively fragmenting established procurement patterns as buyers reassess total-cost-of-ownership calculations across electromagnetic and digital transformer architectures.
Resonant converter topologies are fragmenting the traditional magnetic-core transformer segment by enabling compact, lightweight high-voltage generation without laminated iron cores. Large-format outdoor signage contractors in the United States are specifying resonant units for rooftop installations where weight restrictions previously constrained electromagnetic options. This topology shift is fragmenting supplier tiers as power semiconductor vendors enter territory previously controlled by winding specialists.
The EU F-Gas Regulation is constraining dielectric gas selections in sealed transformer housings while accelerating dry-type resin-encapsulated designs. Manufacturers serving European municipal signage contracts are reformulating insulation systems to eliminate sulfur hexafluoride dependencies. High-voltage product categories face the steepest compliance redesign burden due to clearance and creepage distance requirements.
Specification authority is migrating from electrical contractors to facilities management platforms as building automation systems consolidate vendor selection. Property technology managers in commercial real estate are mandating transformer compatibility with centralized energy dashboards. This behavioral shift is most pronounced in Class-A office developments across China and Germany where LEED and BREEAM certification requirements prioritize metered subsystem integration.
Neon Transformer Market Segmentation
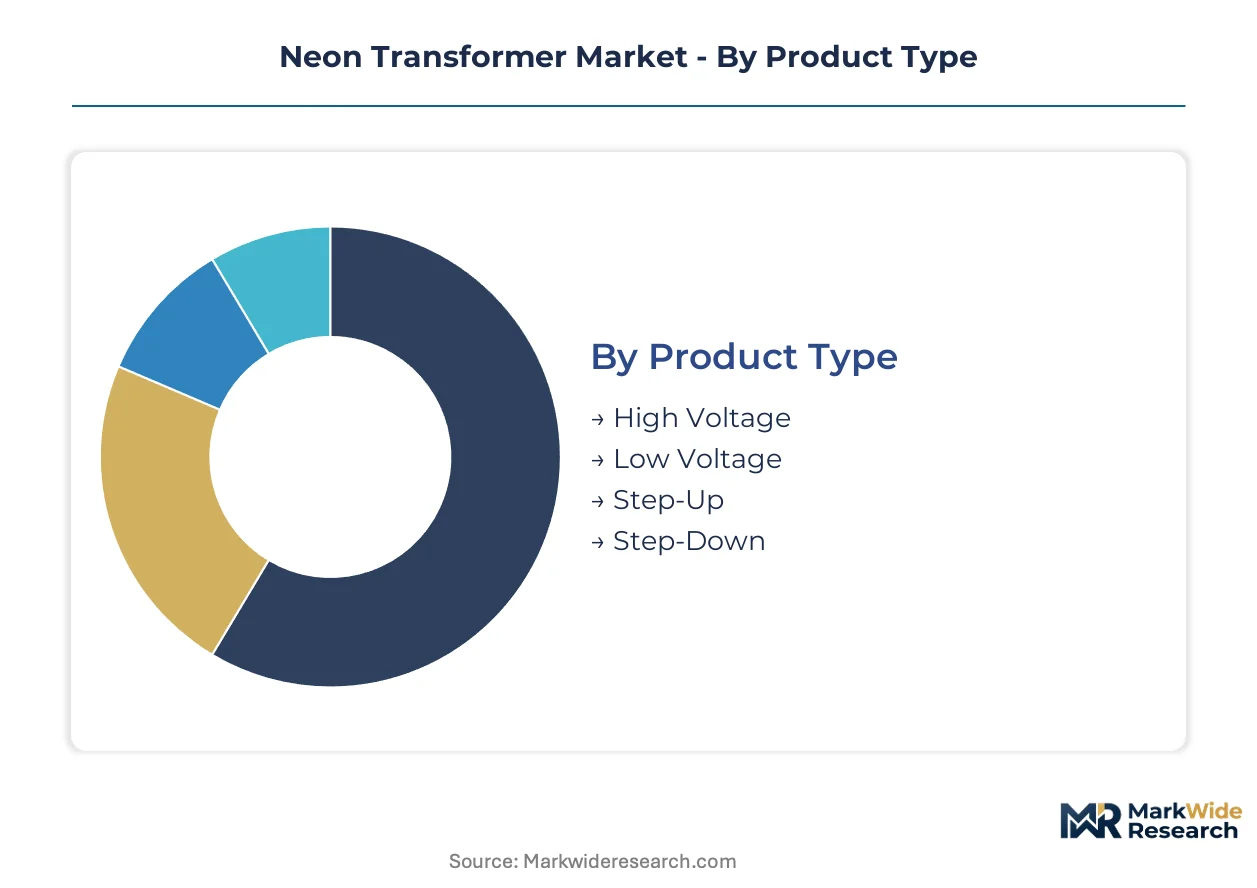
Neon transformer procurement patterns diverge sharply across voltage classes and control architectures, with specification authority migrating toward facilities managers who prioritize protocol compatibility over unit cost. Understanding where margin pools concentrate within each dimension enables suppliers to defend pricing power against solid-state substitution.
Product Type:
Margin pools concentrate in custom-wound high-voltage units where electromagnetic core expertise creates defensible differentiation against resonant converter alternatives.
- High Voltage:Electromagnetic devices delivering 2,000 to 15,000 volts through laminated iron cores sustain continuous gas discharge in large-format outdoor installations. Transit hub revitalization projects in the United States and Germany specify these units for luminance uniformity across extended tube runs where line losses would otherwise degrade performance.
- Low Voltage:Compact transformers operating below 2,000 volts serve interior accent lighting and confined signage applications with reduced clearance requirements. Retail fit-outs in cost-sensitive markets favor these units for shorter tube configurations where electromagnetic weight penalties matter less than procurement simplicity.
- Step-Up:Specialized winding configurations elevate standard mains voltage to ionization thresholds for noble gas mixtures.
- Step-Down:Voltage reduction variants support mixed lighting systems requiring secondary distribution at intermediate potentials.
High Voltage holds installed capacity. Smart-enabled variants are rotating up the share rankings.
Application:
Application-driven demand splits between heritage-mandated authenticity and building automation integration requirements.
- Signage:The dominant revenue channel spans illuminated channel letters, open-face tube configurations, and sculptural installations for commercial identity. Municipal contractors in Germany source electromagnetic transformers to satisfy historic district preservation mandates requiring authentic gas-discharge aesthetics.
- Architectural Lighting:Building-integrated accent systems specify digitally addressable units with BACnet compatibility for centralized energy dashboards. Class-A office developments across China mandate metered subsystem integration to achieve LEED and BREEAM certification thresholds.
- Decorative Lighting:Hospitality and entertainment venues deploy neon for atmospheric differentiation in bars, theaters, and themed retail environments.
- Industrial Lighting:Process control indicators and hazardous-area signaling in chemical facilities demand explosion-rated housings with extended temperature tolerance.
Signage retains the largest installed base. Architectural Lighting is expanding most quickly as property technology managers consolidate vendor selection authority.
End User:
End-user concentration follows commercial real estate development cycles and entertainment venue construction pipelines.
- Retail:Brick-and-mortar signage procurement splits between heritage brand authenticity requirements and budget-conscious LED substitution. Urban renewal districts in the United States sustain transformer demand through district-wide signage harmonization mandates.
- Hospitality:Hotels, restaurants, and entertainment venues prioritize atmospheric lighting for experiential differentiation. Rooftop installations in dense urban markets specify resonant converter units where structural load restrictions previously excluded electromagnetic options.
- Entertainment:Theaters, casinos, and themed attractions maintain dedicated procurement for custom sculptural installations.
- Manufacturing:Industrial facilities deploy neon indicators for process status visualization in harsh environments.
Retail commands the deepest installed capacity. Hospitality is climbing the fastest as post-pandemic venue construction accelerates.
Technology:
Technology segmentation reflects a fundamental architecture war between electromagnetic legacy and solid-state displacement.
- Smart:Embedded microcontrollers enable remote dimming, fault detection, and energy metering integration through BACnet and DALI protocols. Facilities management platforms in commercial real estate mandate these capabilities for centralized dashboard compatibility.
- Digital:Solid-state inverter designs eliminate laminated cores through resonant converter topologies, reducing weight and copper content. EPA efficiency standards and EU Green Deal mandates accelerate replacement cycles for legacy magnetic-core units.
- Wireless:LoRaWAN and NB-IoT connectivity enables predictive maintenance subscriptions for large-format outdoor operators.
- Analog:Conventional electromagnetic designs persist in heritage restoration and cost-sensitive retrofit applications.
Analog retains substantial installed capacity. Smart is gaining share fastest as specification authority migrates to building automation systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA efficiency standards and OSHA electrical safety mandates anchor procurement patterns in the United States, while the EU Green Deal and F-Gas Regulation redirect European specification authority toward digital architectures. Municipal signage contractors and commercial real estate developers across three continents sustain demand concentration.
United States
Transit hub revitalization projects in Chicago and New York City specify high-voltage electromagnetic units for district-wide signage harmonization. EPA guidelines under the National Emission Standards for Hazardous Air Pollutants constrain legacy analog transformer designs. Los Angeles-based fabricators supply custom-wound coils to entertainment venue developers prioritizing atmospheric differentiation.
Germany
Historic district preservation mandates in Berlin and Munich sustain demand for authentic gas-discharge aesthetics requiring electromagnetic compatibility. The EU Green Deal tightens energy-performance standards for commercial signage installations. Bavarian industrial clusters manufacture resin-encapsulated dry-type units eliminating sulfur hexafluoride dependencies.
China
Class-A office developments in Shanghai and Shenzhen mandate BACnet-compatible transformers for LEED certification thresholds. Municipal dual carbon goals accelerate replacement cycles for inefficient magnetic-core units. Pearl River Delta manufacturing hubs produce compact ferrite core designs reducing copper content without output instability.
Japan
Commercial real estate developers in Tokyo specify digitally addressable units with embedded fault detection for centralized energy dashboards. METI efficiency standards push manufacturers toward smart inverter technologies. Osaka-based specialists supply resonant converter topologies for rooftop installations with structural load restrictions.
France
Hospitality venue construction in Paris and Lyon prioritizes atmospheric lighting for experiential differentiation. The EU F-Gas Regulation constrains dielectric gas selections in sealed transformer housings. Île-de-France industrial zones reformulate insulation systems to comply with clearance and creepage distance requirements.
Neon Transformer Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer structure where scale-driven manufacturers compete on certification breadth while niche winders defend margin through custom coil expertise. Electromagnetic legacy specialists and solid-state inverter entrants represent distinct strategic archetypes, each targeting different specification authority migration patterns. Dominant competitive moves include automation capital expenditure to offset collapsing technician availability and strategic partnerships with building automation platform vendors.
Among integrated electrical conglomerates, Siemens AG and ABB Ltd. exemplify scale-driven archetypes with captive supply relationships across municipal and commercial segments. Toshiba Corporation occupies a position within the compact magnetic core specialist tier, representing Japanese manufacturing precision in ferrite-based designs. West Coast Custom Designs LLC anchors the North American custom-winding segment, exemplifying domestic coil expertise for shorter lead times on high-voltage orders.
| Leading Market Players |
|---|
| ACME Electric Corporation |
| ABB Ltd. |
| Siemens AG |
| Schneider Electric |
| Eaton Corporation |
| GE Grid Solutions |
| Toshiba Corporation |
| Lecip Holdings Corp. |
| West Coast Custom Designs LLC |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day lead times for custom-wound high-voltage coils concentrate pricing power with domestic winding specialists who maintain captive ferrite core inventories, while standard digital inverter units compress margins through commoditized power semiconductor sourcing.
Pricing Analysis
Price spreads between German heritage-certified electromagnetic units and Chinese-manufactured resonant converters span certification-grade differentiation rather than raw performance. Three-tier pricing structure across custom-wound heritage, standard industrial-grade, and economy digital inverter levels anchors the market. Cost compression in economy tiers intensifies because power semiconductor vendors are entering transformer territory previously controlled by winding specialists. Municipal signage contractors in Germany exhibit lowest price sensitivity due to historic district preservation mandates, while cost-sensitive retail fit-outs in emerging markets drive hardest bargain.
Supply Chain Analysis
Forty-five-day raw material inventory cycles at Japanese ferrite core specialists buffer against LME copper volatility but expose producers to rare earth magnet price swings. Manufacturing gravity centers on China, Germany, and the United States, with Pearl River Delta hubs producing compact magnetic cores and Bavarian clusters specializing in resin-encapsulated dry-type units. Copper winding wire, ferrite cores, and power semiconductors constitute the critical input trinity. Single-source vulnerability concentrates in rare earth ferrite formulations. Distribution runs through electrical contractor networks and building automation platform vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Building automation protocol consolidation is transforming neon transformer procurement into a platform-economics inflection, where BACnet and DALI interoperability determines vendor inclusion rather than unit specifications alone.
For Market Incumbents: Compound defensive positioning through backward integration into ferrite core sourcing and captive supply relationships with municipal signage contractors. Solid-state inverter entrants from power semiconductor vendors threaten electromagnetic legacy revenue pools. Certification breadth across IEC 61558 and OSHA electrical safety mandates creates switching costs that protect installed base. For New Entrants and Emerging Players: UL certification fast-track programs unlock the North American hospitality retrofit segment where rooftop weight restrictions favor resonant converter adoption. Industrial indicator applications in chemical facilities remain underpenetrated for explosion-rated units. Partner with building automation platform vendors for protocol-native specification inclusion. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because skilled coil-winding technician scarcity is collapsing across mature manufacturing economies. Acquisition targets should display custom-winding expertise with heritage restoration relationships or smart-enabled digital architectures with embedded fault detection capabilities. Watch for EPA efficiency standard acceleration as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferrite Core Sourcing | Captive supply of magnetic materials insulates margin from LME copper volatility and rare earth price swings. |
| Building Automation Platform Partnership | BACnet and DALI protocol native integration secures specification authority from facilities management platforms. |
| Heritage Restoration Certification Investment | Historic district preservation mandates in Germany and France sustain authentic electromagnetic transformer demand. |
| Resonant Converter Topology Development | Solid-state inverter designs capture rooftop installations where structural load restrictions previously excluded legacy options. |
| Predictive Maintenance Subscription Launch | LoRaWAN and NB-IoT connectivity enables recurring revenue from large-format outdoor signage operators. |
Research Methodology
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in this analysis. Conversations with electrical contractors, municipal signage procurement officers, facilities management platform engineers, and ferrite core manufacturing specialists informed demand-side dynamics. Secondary validation drew from EPA National Emission Standards documentation, EU F-Gas Regulation compliance databases, IEC 61558 certification registries, and commercial real estate development permits. Bottom-up unit economics triangulated against top-down energy-efficiency mandate penetration models.
Sensitivity analysis across copper price volatility scenarios, technician availability collapse rates, and LED substitution elasticity shaped the forecast framework. Segmentation dimensions modeled include voltage class, control architecture, application type, and end-user concentration across retail, hospitality, and industrial verticals. CAGRs were derived from replacement cycle acceleration under EPA and EU Green Deal efficiency mandates, cross-referenced with commercial real estate construction pipeline data.
Underlying assumptions cover sustained enforcement of energy-performance standards and stable rare earth magnet supply chains, with deviation risk concentrated in accelerated LED substitution in cost-sensitive retail segments and tariff exposure on Chinese-manufactured power semiconductors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Transformer Monitoring Systems (TMS) Market
Transformers
Step Up/Down Transformers Market
Transformers
Phase-Shifting Transformer Market
Transformers
United States Distribution Transformer Market
Transformers
Power Transformer Market
Transformers
India Transformer Market
Transformers
Asia-Pacific Power Transformer (Below 100 MVA) Market
Transformers
North America Smart Transformers Market
Transformers
Smart Transformer Market
Transformers
Canada Transformer Market
Transformers
Amorphous Core Transformers Market
Transformers
North America Oil Filled Transformer Market
Transformers
Distribution Transformer Market
Transformers
Uninhibited Transformer Oil Market
Transformers
Industrial Control Transformers Market
Transformers
Rectifier Transformers Market