
 Europe Distribution Transformer Market | 2026-2036
Europe Distribution Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Distribution Transformer Market Foresight
A widening capability gap between capital-intensive manufacturers and asset-light assemblers is redrawing competitive boundaries in the Europe distribution transformer sector. Siemens Energy AG leverages in-house grain-oriented electrical steel production to sustain margin control across medium-voltage portfolios. SGB-SMIT Group anchors its position through deep specialization in resin-cast transformers for urban underground installations.
Distribution transformers are static electromagnetic devices that step down voltage from medium-voltage primary networks to low-voltage levels suitable for end-user consumption, typically employing copper or aluminum windings around laminated silicon-steel cores to minimize hysteresis and eddy-current losses. Three-phase units dominate utility-scale deployments across Europe, while single-phase transformers occupy rural and residential fringe networks where load density remains sparse. Outdoor pole-mounted installations still represent the largest installed base, though underground configurations are capturing margin pools in dense German and Benelux city centers where aesthetic and reliability constraints intensify.
EU Ecodesign regulations and the F-Gas Directive enforce minimum efficiency tiers and restrict insulating fluid chemistries, compelling manufacturers to redesign core geometries and qualify alternative ester-based coolants. CE marking under the Low Voltage Directive and harmonized EN standards govern market access, with national regulators in France and Italy layering additional grid-code certifications for network-connected assets. Stakeholders must monitor how the EU Green Deal's accelerating decarbonization timelines reshape transformer procurement specifications before the next replacement cycle locks in technology choices.
Market Dynamics
EU Ecodesign tier upgrades and F-Gas phase-down schedules are compressing replacement cycles across European distribution networks, forcing utilities to pre-commit capital before 2030 efficiency deadlines lock in equipment specifications for decades.
Growth Catalysts
- EU Green Deal electrification mandates:National renewable integration targets in Germany and Spain are accelerating medium-voltage grid reinforcement programs that require higher-capacity distribution transformers.
- Industrial facility decarbonization:Steel and chemical plants in the Benelux region are driving demand for heavy-duty three-phase units capable of handling intermittent high-load cycles from electrified process heat.
- Amorphous metal core adoption:No-load loss reductions of up to 70% versus conventional silicon-steel are qualifying these advanced cores for premium tariff structures in France and Italy.
Market Restraints
- Grain-oriented electrical steel supply concentration:European mills in Germany and Austria control over 80% of regional high-grade core material output, exposing transformer manufacturers to input bottlenecks during energy price spikes.
- Ester fluid qualification timelines:Synthetic and natural ester coolants face extended type-testing protocols under EN 62770, delaying product launches by 18-24 months versus mineral oil equivalents.
- Copper price volatility:Winding material cost swings of 30-40% within single fiscal years are eroding margin predictability for build-to-order manufacturers serving utility procurement frameworks.
Strategic Opportunities
- Polish and Romanian grid expansion:EU cohesion fund allocations for rural electrification are creating tender pipelines for compact pole-mounted units in markets previously served by aging Soviet-era equipment.
- Digital twin integration:IoT sensor packages and predictive analytics are enabling transformer-as-a-service business models that monetize uptime guarantees rather than hardware sales alone.
- Urban underground retrofit cycles:Resin-cast dry-type transformers are capturing replacement demand in German city centers where fire-safety regulations now prohibit oil-filled units in tunnel and subway feeder stations.
Industry Challenges
- Magnetic core design engineering scarcity:Finite-element modeling expertise for optimizing amorphous metal joint geometries is concentrated among retiring specialists at established European manufacturers.
- Multi-standard certification complexity:Simultaneous compliance with IEC 60076, national grid codes, and utility-specific technical specifications fragments testing budgets across overlapping requirements.
- Legacy asset data interoperability:Utilities in France and Italy lack standardized digital records on installed base age and condition, complicating predictive replacement scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Distribution Transformer Market |
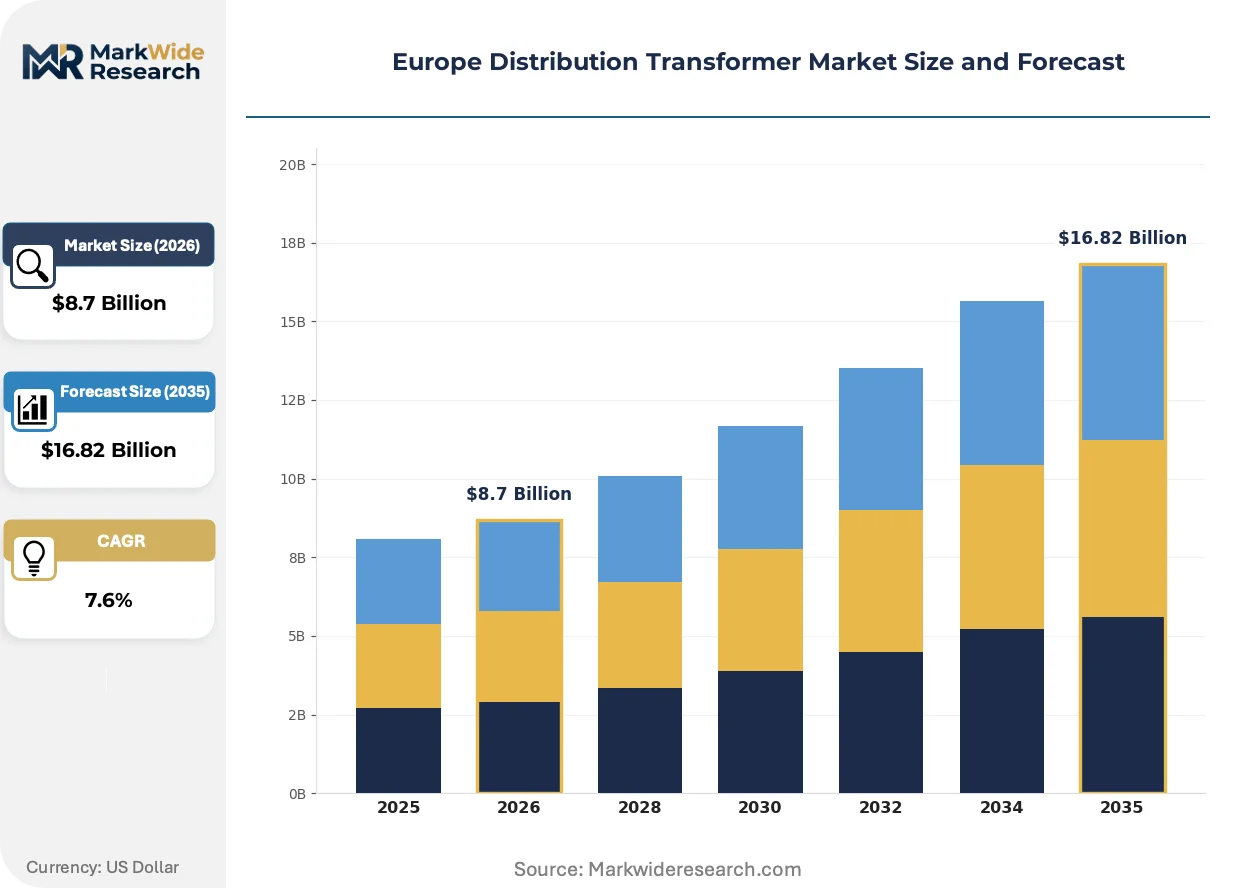
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $16.82 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Single-Phase, Three-Phase, Auto-Transformers, Specialty Transformers Installation: Indoor, Outdoor, Underground, Overhead End User: Residential, Commercial, Industrial, Utilities Voltage Rating: Low Voltage, Medium Voltage, High Voltage, Extra High Voltage |
| Companies Covered | Eaton Corporation plc, SGB-SMIT Group, Hitachi Energy Ltd., SEA SpA, CG Power Systems Belgium NV, Siemens Energy AG, GE Vernova, GBE SpA, Schneider Electric SE, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Distribution Transformer Market Shifts & Advancements
Transformer technology is splitting along efficiency-performance lines as regulatory minima harden and premium segments absorb advanced materials. Digitalization is overlaying hardware markets with data-service revenue layers.
Amorphous metal ribbon cores are bifurcating the efficiency tier structure of European distribution transformers. German utilities operating high-loss-factor rural networks have adopted these cores at twice the rate of urban operators since 2022. The technology is compressing no-load loss benchmarks industry-wide while segmenting procurement into standard and premium efficiency classes with widening price spreads.
F-Gas Regulation phase-down schedules are mandating synthetic ester and natural ester alternatives to mineral oil in new installations. Manufacturers face reformulated insulation system designs and accelerated aging test protocols to maintain warranty terms. French and Italian regulators are enforcing stricter leak-detection standards than harmonized EU baselines, creating sub-regional product configuration requirements.
Utility procurement departments are unbundling transformer supply from installation and long-term maintenance, creating discrete contract lots that favor specialized service providers. Engineering-procurement-construction firms are displacing direct manufacturer relationships in German distribution network tenders. This pattern is most pronounced in North Rhine-Westphalia, where municipal utilities have consolidated purchasing through regional energy associations.
Europe Distribution Transformer Market Segmentation
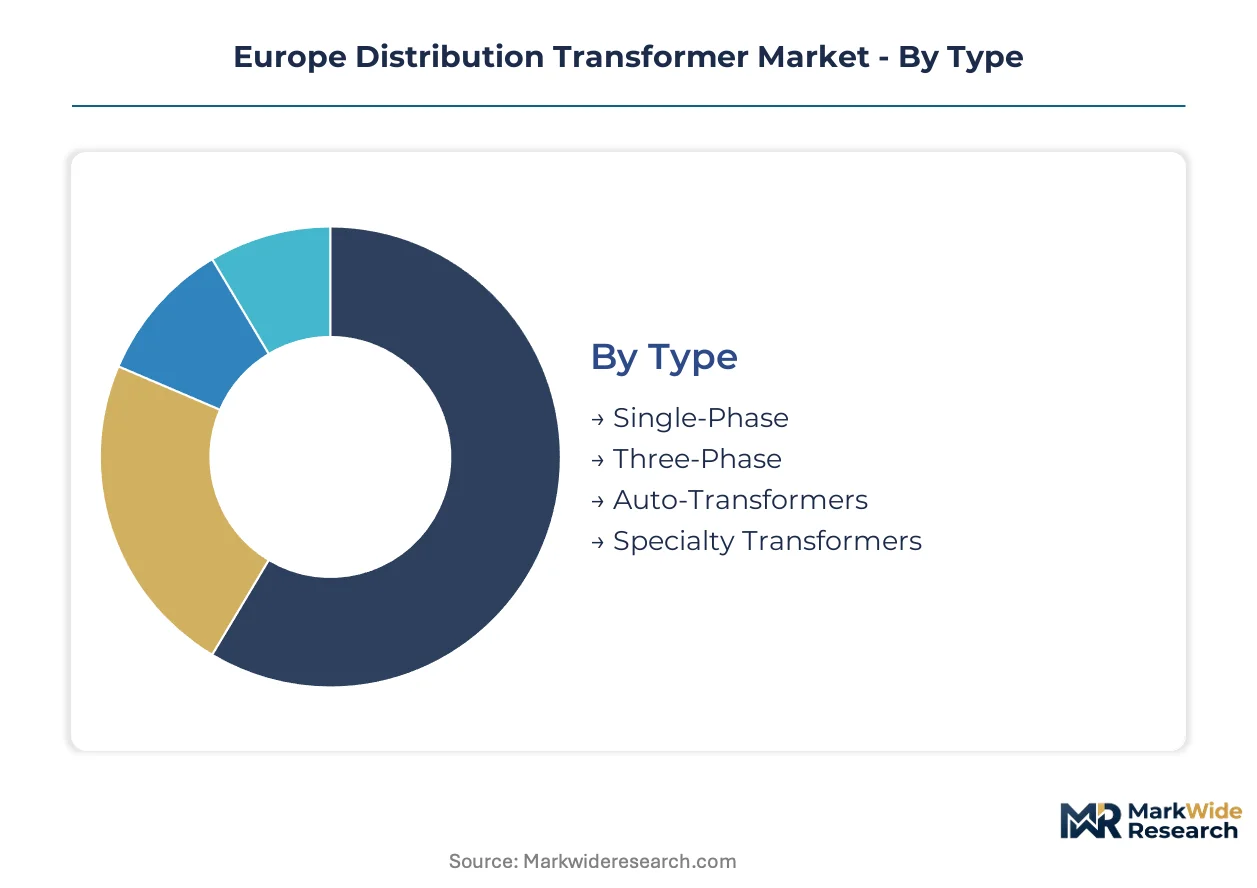
Transformer procurement specifications in Europe fragment across efficiency tiers, installation constraints, and voltage classes that determine material selection and regulatory compliance pathways. Procurement officers at German utilities and French grid operators weight these dimensions differently when scheduling replacement cycles against EU Ecodesign deadlines.
Type:
F-Gas Regulation phase-down schedules and EU Ecodesign tier upgrades are compressing technology choices, with efficiency mandates favoring core material innovations in higher-volume segments.
- Three-Phase:These units employ three interconnected magnetic circuits to handle balanced polyphase loads across utility-scale distribution networks. Demand concentrates in Germany's industrial Rhine-Ruhr corridor and Spain's renewable integration zones, where medium-voltage grid reinforcement programs require higher-capacity units capable of managing intermittent generation infeed.
- Single-Phase:Compact designs with one primary and one secondary winding serve low-density rural networks across Poland and Romania. Polish distribution operators are replacing Soviet-era single-phase banks with modern units as EU cohesion funds flow into rural electrification programs.
- Auto-Transformers:Single-winding configurations with tapped sections provide voltage step-down with reduced copper mass for specific industrial applications.
- Specialty Transformers:Custom electromagnetic designs address non-standard frequency or harmonic-rich environments in data centers and renewable converter stations.
Established volume favors Three-Phase; emerging adoption favors Specialty Transformers.
Installation:
Fire-safety regulations and aesthetic constraints in dense urban centers are reconfiguring deployment economics across mounting configurations.
- Outdoor:Pole-mounted and pad-mounted enclosures dominate installed base across European rural networks. Benelux steel and chemical plants specify heavy-duty outdoor units for electrified process heat applications requiring intermittent high-load cycle tolerance.
- Underground:Resin-cast dry-type configurations eliminate fire risk in tunnel and subway feeder stations. German city centers including Munich and Hamburg now prohibit oil-filled units in underground infrastructure, accelerating replacement demand for cast-resin alternatives.
- Indoor:Enclosed installations in commercial buildings and industrial facilities require compact footprints and reduced noise signatures.
- Overhead:Traditional pole-mounted deployments persist in Eastern European rural networks with lower load density and limited underground infrastructure.
Outdoor configurations retain the largest installed base; Underground installations are climbing the fastest on regulatory pressure.
End User:
Customer type determines warranty terms, maintenance scheduling, and the economic viability of premium efficiency tiers.
- Industrial:Steel, chemical, and automotive facilities in the Benelux region and Germany's industrial heartland specify heavy-duty three-phase units. Electrified process heat installations create intermittent high-load cycles that stress conventional core designs and accelerate adoption of amorphous metal alternatives.
- Utilities:Grid operators in France and Italy manage aging installed bases with limited digital records on asset condition. French regulators enforce stricter leak-detection standards than EU baselines, creating sub-regional procurement specifications for insulating fluid systems.
- Residential:Single-phase and small three-phase units serve low-voltage distribution to individual dwellings and small multi-family buildings.
- Commercial:Office buildings, retail complexes, and institutional facilities require compact indoor units with noise and thermal management priorities.
Utility procurement dominates unit volume; Industrial end-use is gaining share fastest on electrification mandates.
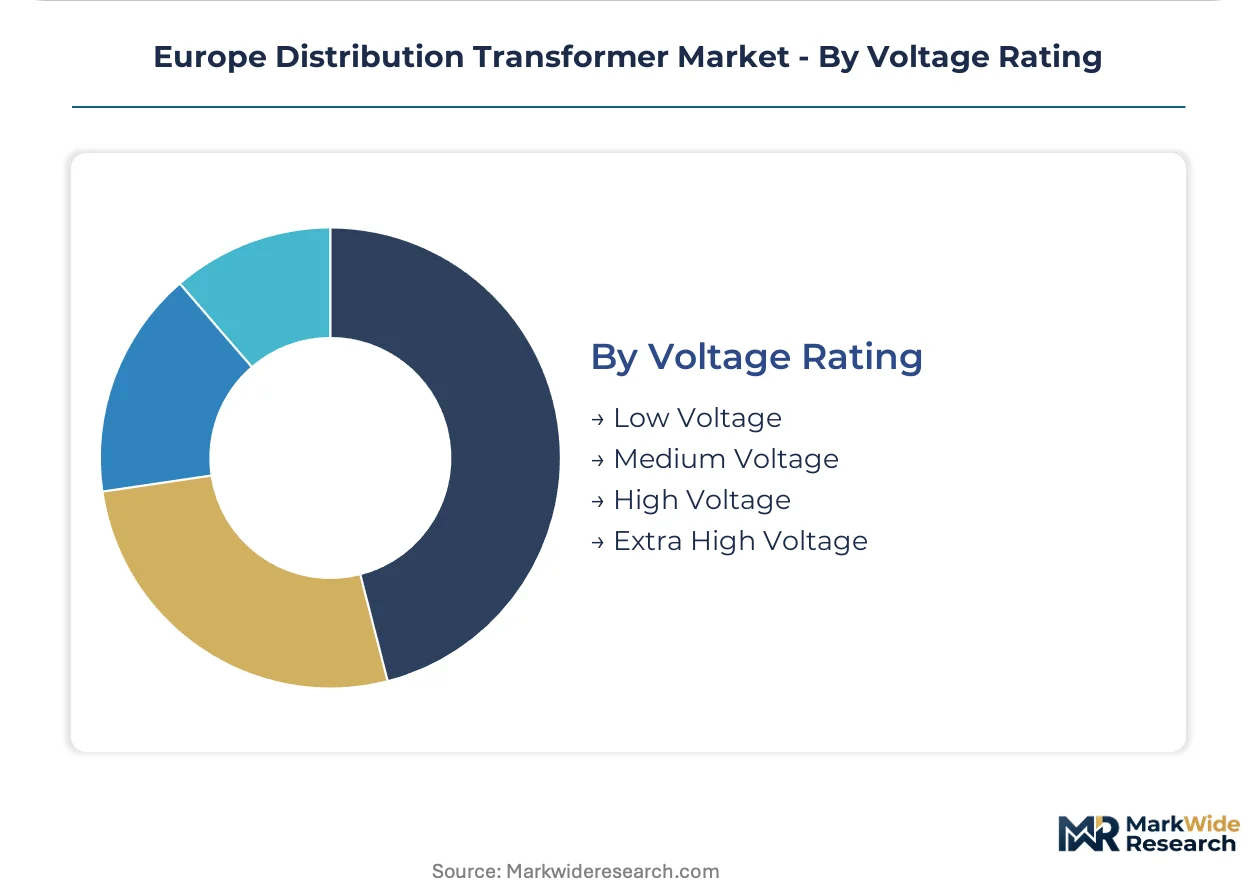
Voltage Rating:
Network position determines insulation system design, cooling requirements, and the applicability of EU Ecodesign efficiency tiers.
- Medium Voltage:Primary distribution interfaces stepping 10-35kV to low-voltage levels represent the procurement focus of European grid modernization. German utilities are accelerating replacement of aging medium-voltage assets ahead of 2030 efficiency deadlines that will lock in specifications for decades.
- Low Voltage:Final distribution stages at 230/400V serve end-user connection points across residential and commercial networks. Italian utilities lack standardized digital records on low-voltage transformer age and condition, complicating predictive replacement scheduling.
- High Voltage:Sub-transmission interfaces at 66-132kV require specialized insulation coordination and are less common in pure distribution applications.
- Extra High Voltage:Transmission-distribution boundaries above 220kV fall outside standard distribution transformer definitions in European regulatory frameworks.
Medium Voltage captures the steepest expansion trajectory on grid reinforcement investment; Low Voltage retains the largest replacement pipeline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polish utilities exhibit the highest price elasticity in procurement, squeezing margins on standard-efficiency units, while German industrial buyers absorb premium-tier pricing for amorphous-core configurations without volume contraction.
Germany
Industrial electrification in the Rhine-Ruhr corridor and renewable integration mandates are accelerating medium-voltage transformer replacements. The EU Green Deal's national implementation targets compress procurement timelines through 2030. Munich and Hamburg now prohibit oil-filled units in underground infrastructure, forcing rapid adoption of resin-cast alternatives.
France
Grid operators manage aging installed bases with limited digital asset records, complicating predictive maintenance scheduling. ANSM enforces stricter leak-detection standards for insulating fluids than harmonized EU baselines. The Île-de-France region concentrates underground retrofit demand where fire-safety regulations have eliminated mineral-oil configurations.
Italy
Utilities lack standardized digital records on low-voltage transformer age and condition, fragmenting replacement planning. CE marking under the Low Voltage Directive governs market access with additional national grid-code certifications. Northern industrial clusters around Milan and Turin specify heavy-duty three-phase units for electrified manufacturing processes.
Poland
EU cohesion fund allocations for rural electrification are creating tender pipelines for compact pole-mounted single-phase units. The F-Gas Regulation phase-down schedules are compressing technology choices ahead of efficiency deadlines. Distribution operators are replacing Soviet-era equipment banks across rural networks in Mazovia and Silesia.
Spain
Renewable integration targets are accelerating medium-voltage grid reinforcement programs requiring higher-capacity distribution transformers. ECHA compliance pathways for alternative ester coolants extend qualification timelines versus mineral oil. Andalusian solar farms and Catalan wind clusters are driving concentrated demand for units capable of managing intermittent generation infeed.
Europe Distribution Transformer Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale advantages concentrating in captive electrical steel supply and qualification-heavy insulating fluid systems. Siemens Energy AG leverages in-house grain-oriented electrical steel production to sustain margin control across medium-voltage portfolios. SGB-SMIT Group anchors its position through deep specialization in resin-cast transformers for urban underground installations. Dominant competitive moves include backward integration into core material supply and accelerated type-testing protocols for ester-based coolants under EN 62770.
Among Germany-based integrated manufacturers, Siemens Energy AG exemplifies the captive-supply archetype through controlled access to high-grade core materials. SGB-SMIT Group represents the installation-specialist tier with concentrated expertise in dry-type configurations for constrained urban environments. Hitachi Energy Ltd. occupies a position bridging scale and technology breadth across European utility procurement frameworks.
| Leading Market Players |
|---|
| Eaton Corporation plc |
| SGB-SMIT Group |
| Hitachi Energy Ltd. |
| SEA SpA |
| CG Power Systems Belgium NV |
| Siemens Energy AG |
| GE Vernova |
| GBE SpA |
| Schneider Electric SE |
| Others |
Supply & Pricing Matrix
Amorphous metal ribbon substitution for conventional silicon-steel cores is redrawing procurement geography toward Japanese and American alloy suppliers while compressing no-load loss premiums that once justified 40% price spreads over standard efficiency tiers. German utilities now negotiate amorphous-core contracts against volatile grain-oriented electrical steel futures, forcing manufacturers to hedge input exposure through captive Austrian and German mill relationships.
Pricing Analysis
After-sales service contracts and predictive maintenance subscriptions now drive lifetime value capture beyond hardware margins, with Siemens Energy and Hitachi Energy bundling IoT-enabled uptime guarantees into 15-year service agreements. Three-tier pricing structure across premium, standard, and economy levels segments on efficiency certification under EU Ecodesign tiers and amorphous-core qualification status. Cost compression in standard-efficiency segments is intensifying because Polish and Romanian utilities squeeze margins on pole-mounted single-phase units. Industrial buyers in the Benelux region exhibit lowest price sensitivity, absorbing premium-tier amorphous-core configurations without volume contraction.
Supply Chain Analysis
Strategic stockpiling of grain-oriented electrical steel dominates inventory strategy among European transformer manufacturers, with Siemens Energy maintaining six-month rolling coverage through captive ThyssenKrupp supply agreements. Manufacturing concentrates in Germany, Austria, and Poland, with core material dependencies on Japanese amorphous metal ribbon and Chinese copper winding stock. Single-source vulnerability to Austrian and German electrical steel mills exposes producers to energy price spike pass-throughs. Distribution runs through engineering-procurement-construction consortia in German municipal utility tenders and direct manufacturer relationships in French and Italian grid operator frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transformer-as-a-service business models are creating platform-economics inflection points, with digital twin interoperability standards enabling ecosystem competition between hardware vendors and predictive analytics providers.
For Market Incumbents: Compound defensive positioning through accelerated EN 62770 qualification of synthetic ester coolants and backward integration into amorphous metal core supply chains. Threat from asset-light assemblers in Eastern Europe demands certification investment in F-Gas-compliant insulation systems. Channel control through regional energy associations in North Rhine-Westphalia anchors procurement relationships against EPC firm displacement. For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in Poland and Romania opens white-space penetration of Soviet-era replacement pipelines. Target compact pole-mounted single-phase units in Mazovia and Silesia rural electrification programs. Go-to-market angle: EU cohesion fund tender alignment with standardized technical documentation packages. For Investors and Strategic Acquirers: The market sits at a regulatory-compression phase that favors specialty manufacturers with captive core material supply and ester fluid qualification depth. Long-term viability rests on amortization of type-testing investments across multi-standard certification portfolios. Acquisition target archetype: resin-cast dry-type specialists with German city center retrofit track records. Signal to watch: ANSM and Italian regulator divergence on leak-detection standards creating sub-regional product configuration fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Core Material Supply | Siemens Energy's captive grain-oriented electrical steel production insulates margin control against Austrian mill bottlenecks. |
| Ester Fluid Qualification Acceleration | EN 62770 type-testing compression closes 18-24 month launch gaps versus mineral oil equivalents for F-Gas compliance. |
| Digital Twin Platform Development | IoT sensor packages enable transformer-as-a-service monetization of uptime guarantees beyond hardware sales. |
| Resin-Cast Manufacturing Scale-Up | Munich and Hamburg underground prohibitions on oil-filled units create replacement demand capture in fire-safety-constrained environments. |
| Regional Energy Association Partnerships | North Rhine-Westphalia municipal utility consolidation favors EPC-aligned manufacturers with installation and maintenance bundling. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU Ecodesign regulatory filings, F-Gas Regulation implementation guidance, and harmonized EN standard documentation. Primary interviews engaged utility planning officers at German and French distribution network operators, transformer procurement leads at Benelux industrial facilities, and aftermarket service heads at resin-cast specialists. Secondary validation drew from ECHA chemical registration databases, CE marking notified body records, and customs trade data on grain-oriented electrical steel flows. Bottom-up unit economics triangulate against top-down grid investment forecasts.
Segmentation dimensions modeled span transformer type, installation configuration, end-user category, and voltage rating across the analysis window. The analytical framework projects value expansion through efficiency tier adoption curves and amorphous-core penetration rates. CAGRs derive from replacement cycle compression against EU Green Deal electrification mandates and F-Gas phase-down deadlines. Industry-specific inputs include German industrial electrification load profiles and Polish rural electrification tender pipelines.
Decision-makers should treat outputs as directional under base assumptions of sustained EU Ecodesign tier enforcement and electrical steel supply continuity; material deviation would warrant model refresh. Specific risk factors encompass Austrian energy cost volatility, ester fluid qualification timeline extensions, and utility digital asset record standardization gaps. Revision becomes warranted when ANSM-Italian regulator divergence on leak-detection standards crosses interoperability thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Latin America Transformer Market
Transformers
Asia-Pacific Transformer Market
Transformers
United States Distribution Transformer Market
Transformers
Locomotive Traction Transformer Market
Transformers
EHV & UHV (above 330KV) Power Transformers Market
Transformers
Oil Filled Transformer Market
Transformers
Current Transformer Market
Transformers
Global Large Power Transformers Market
Transformers
United States Power Transformer Market
Transformers
Global Transformer Market
Transformers
Renewable Energy Transformer Market
Transformers
Europe Transformer Market
Transformers
United States Dry-Type Transformer Market
Transformers
India Distribution Transformer Market
Transformers
Transformer Monitoring Systems (TMS) Market
Transformers
Transformer Steel Market