
 India Power Transformer Market | 2026-2036
India Power Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
India Power Transformer Market Foresight
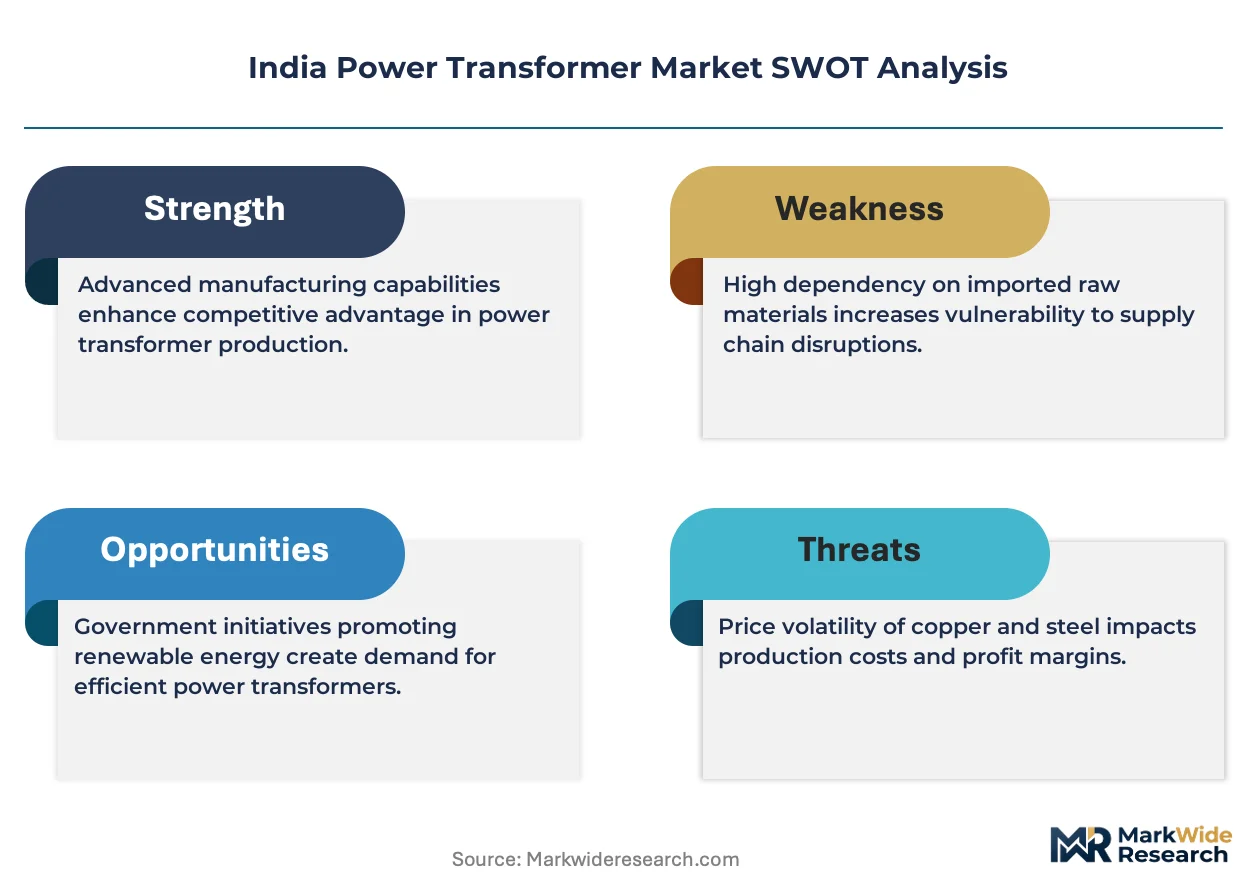
Asset-light leasing models for grid infrastructure is narrowing the competitive field to firms with balance-sheet depth. CG Power and Industrial Solutions leverages its manufacturing scale across western India to capture utility tenders. Bharat Heavy Electricals Limited (BHEL) anchors its position through captive steel and core material supply chains. Siemens India competes on digital monitoring integration bundled with transformer hardware.
India power transformers are electromagnetic devices that transfer electrical energy between circuits through magnetic induction, typically operating at voltage ratings from 33 kV to 765 kV for bulk power transmission. Oil-immersed technology dominates utility procurement due to superior thermal performance in tropical climates, while dry-type units gain share in urban substations where fire safety codes restrict flammable coolant use. Three-phase configurations lead volume owing to national grid architecture, though single-phase banks persist in remote Himalayan corridors where transport constraints apply.
BIS certification mandates and CEA grid standards enforce efficiency tiers and short-circuit withstand protocols that filter out non-compliant imports. The PLI scheme for electrical equipment manufacturing reshapes domestic capacity incentives, while state-level renewable purchase obligations from regulators like CERC and SERCs drive demand for step-up transformers at solar parks and wind clusters. Stakeholders must track evolving kVA rating thresholds in upcoming tariff regulations to align product portfolios with discom modernization cycles.
Market Dynamics
State transmission utilities in Gujarat, Maharashtra, and Tamil Nadu are consolidating procurement around high-capacity 765 kV units, compressing vendor qualification timelines and favoring manufacturers with captive core material supply chains and in-house testing infrastructure.
Growth Catalysts
- Green Energy Open Access Rules:The Ministry of Power's framework mandates grid modernization, accelerating tender releases for step-up transformers at solar parks and wind clusters.
- PLI scheme for electrical equipment:Domestic manufacturing incentives are expanding capacity for 33-765 kV units, reducing import dependence for critical core materials.
- Renewable Purchase Obligations:CERC and SERC mandates are driving discoms to upgrade interconnection infrastructure for variable renewable integration.
Market Restraints
- Oriented silicon steel import concentration:Core material supply chains remain concentrated among Japanese and South Korean mills, exposing domestic winding facilities to currency volatility and lead time extensions.
- BIS certification timelines:Efficiency tier testing and short-circuit withstand protocols extend product qualification cycles by 8-14 months for new market entrants.
- Dry-type transformer thermal limits:Air-cooled designs face kVA ceiling constraints above 10 MVA in tropical ambient conditions, restricting deployment in bulk transmission substations.
Strategic Opportunities
- Asset-light leasing models:Balance-sheet-constrained state utilities are piloting infrastructure-as-a-service contracts, opening recurring revenue streams for manufacturers with project finance capabilities.
- Digital monitoring convergence:Integration of dissolved gas analysis sensors with SCADA systems creates bundled hardware-software offerings for smart grid deployments.
- Himalayan corridor single-phase banks:Transport-constrained terrain in Jammu and Kashmir, Himachal Pradesh, and Uttarakhand favors modular single-phase configurations over three-phase units.
Industry Challenges
- Skilled winding technician scarcity:Precision core stacking and insulation papering expertise concentrates among aging workforces at legacy public sector facilities.
- Legacy substation retrofit complexity:220 kV and 400 kV yard reconfigurations require outage coordination with regional load dispatch centers, compressing installation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Power Transformer Market |
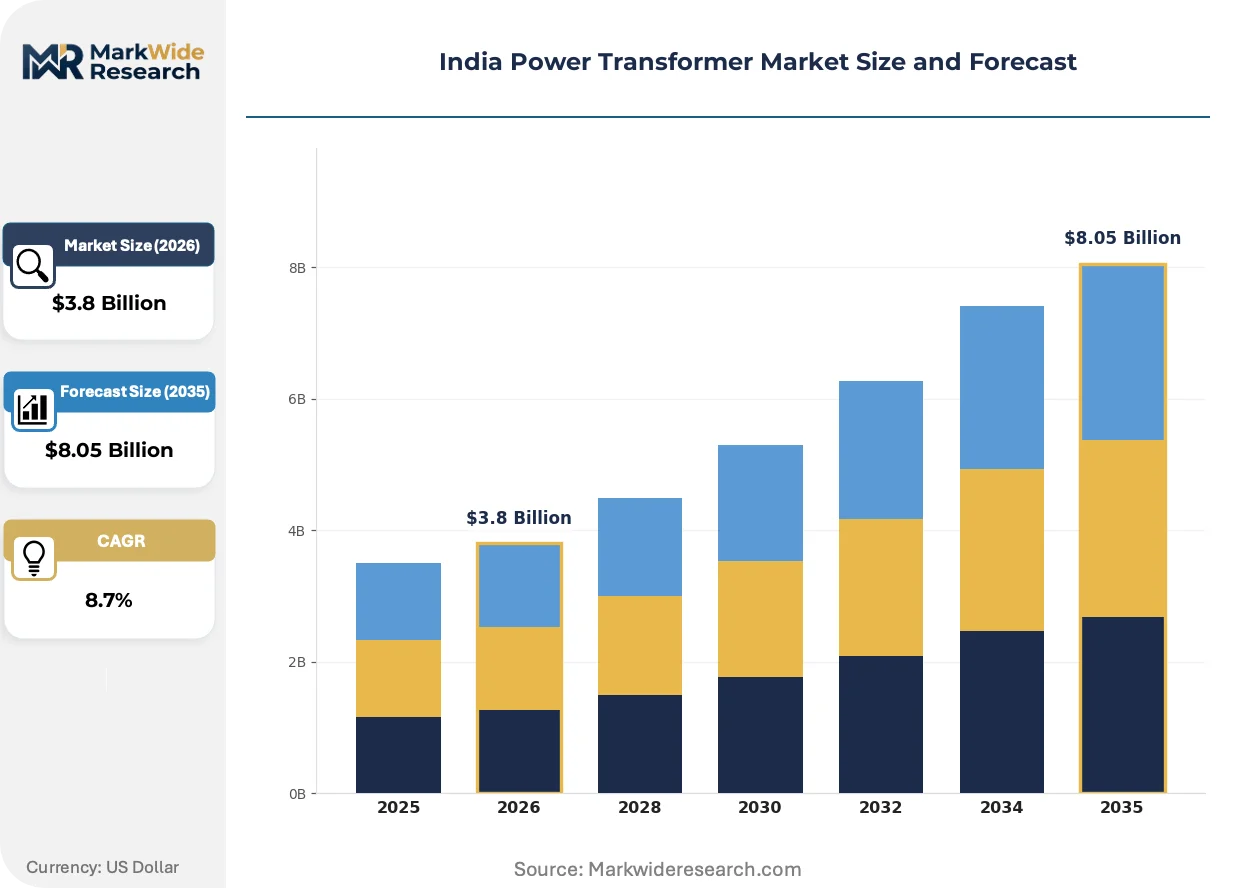
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Phase, Three-Phase, Autotransformer, Instrument Transformer Technology: Oil-Immersed, Dry Type, Vacuum, Gas-Insulated End User: Utilities, Industrial, Commercial, Renewable Energy Installation: Indoor, Outdoor, Substation, Transmission Line |
| Companies Covered | CG Power and Industrial Solutions, Transformers and Electricals Kerala (TELK), Bharat Heavy Electricals Limited (BHEL), Technical Associates, Gujarat Transformers, ABB India, Voltamp Transformers Limited, Uttam Bharat, Siemens India, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Power Transformer Market Shifts & Advancements
Transformer technology is bifurcating between ultra-high-voltage bulk transmission units and digitally instrumented distribution assets, with thermal management and predictive maintenance emerging as the primary innovation battlegrounds.
Amorphous metal core technology is collapsing no-load loss benchmarks in distribution transformers below 10 MVA. State utilities in Maharashtra and Gujarat are specifying amorphous cores for urban substation replacements where load cycles favor standby efficiency over peak capacity. This material transition is compressing the total cost of ownership calculus that previously favored conventional grain-oriented silicon steel.
The CEA's revised Technical Standards for Construction of Electrical Plants and Electric Lines are mandating efficiency tier upgrades for all new 33 kV and above installations. Manufacturers must now certify units against stricter no-load and load loss bands, disqualifying legacy designs from central sector tenders. Western and southern state discoms are responding by pre-qualifying only Tier-1 efficiency suppliers for upcoming 765 kV inter-regional corridor projects.
Utilities are unbundling transformer procurement from installation and commissioning contracts, creating separate vendor pools for hardware supply versus turnkey execution. This disaggregation is fragmenting the traditional EPC bundling that dominated state transmission utility tenders, allowing specialized manufacturers to compete without civil works capabilities. The pattern is most visible in Tamil Nadu and Karnataka where renewable park developers are sourcing units directly while outsourcing substation construction.
India Power Transformer Market Segmentation
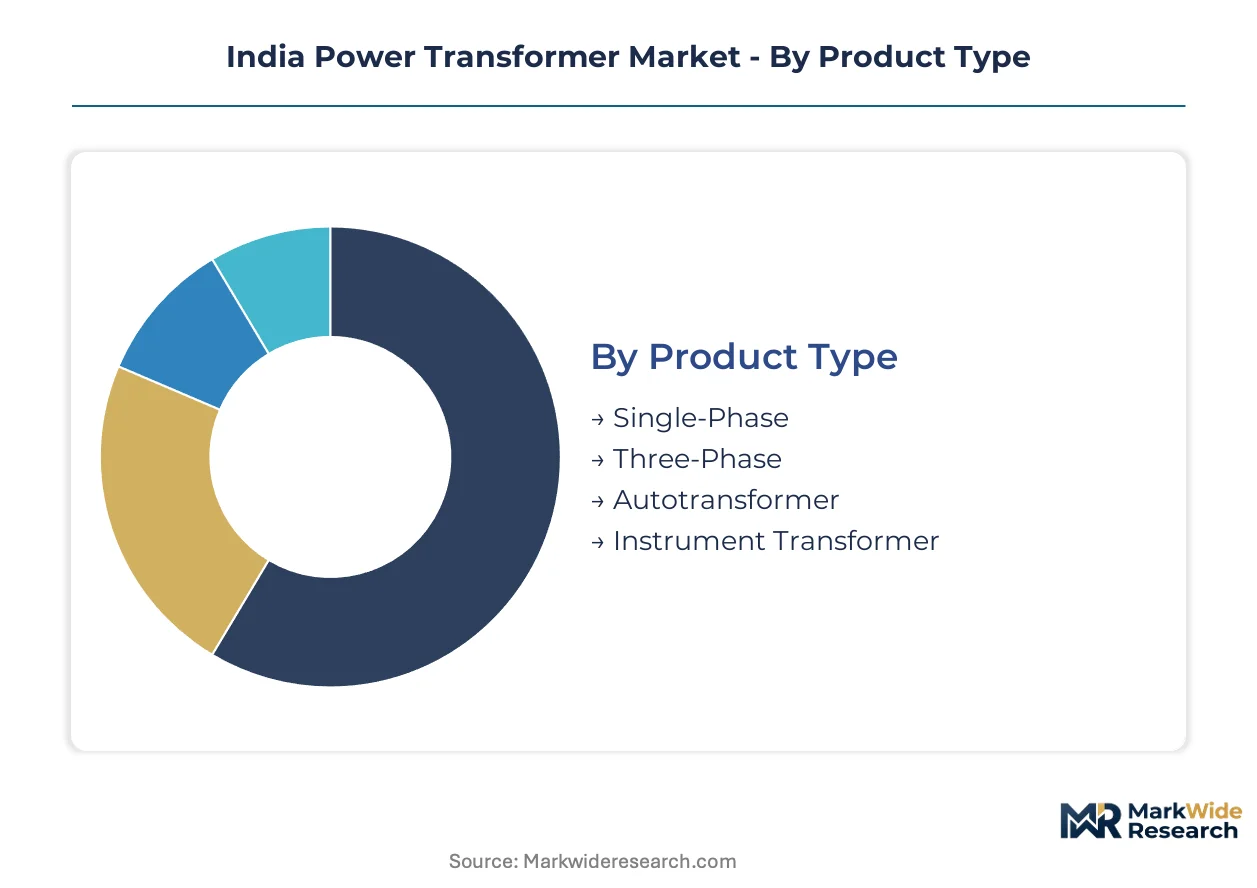
India's power transformer segmentation reflects divergent procurement logics across transmission utilities and renewable developers. Product architecture, cooling technology, and installation environment each create distinct competitive arenas with separate qualification barriers and margin profiles.
Product Type:
Mature configurations dominate bulk procurement while emerging designs address terrain-constrained deployments.
- Three-Phase:Standard core-and-coil assemblies transfer power across three alternating current phases simultaneously. State transmission utilities in Maharashtra and Gujarat specify these units for 765 kV inter-regional corridors where capacity density outweighs transport flexibility.
- Single-Phase:Modular banks allow component-wise transport through narrow Himalayan roads. Installations in Jammu and Kashmir, Himachal Pradesh, and Uttarakhand favor this configuration where three-phase unit dimensions exceed tunnel and bridge clearances.
- Autotransformer:Shared winding architecture reduces copper mass for voltage ratios below 3:1. CEA grid standards permit these units for 400/220 kV interconnections where material efficiency offsets insulation complexity.
- Instrument Transformer:Precision voltage and current sensing cores feed protection relays and revenue metering. These units accompany every 33 kV and above installation under CEA Technical Standards mandates.
Three-Phase retains volume leadership; Single-Phase holds the steepest expansion curve.
Technology:
Cost tier stratification separates premium thermal management from economy air-cooled alternatives.
- Oil-Immersed:Mineral or ester fluid fills dissipate heat through radiators and conservators. Tropical ambient conditions in Tamil Nadu and Gujarat sustain this technology's dominance above 10 MVA ratings where dry-type thermal ceilings constrain output.
- Dry Type:Cast resin or vacuum-impregnated windings eliminate fire and spill risks. Urban substations in Mumbai and Delhi specify these units where municipal codes restrict flammable coolant storage near dense commercial districts.
- Vacuum:Pressure-impregnated insulation eliminates voids that cause partial discharge. Premium industrial installations in Gujarat's chemical corridors specify this construction for reliability-critical process power.
- Gas-Insulated:Sulfur hexafluoride or fluoronitrile mixtures enable compact footprint substations. Metro rail traction systems and offshore wind platforms pilot this technology where space constraints override cost premiums.
Oil-Immersed commands the widest installed base; Dry Type gains share fastest in urban replacement cycles.
End User:
Customer type determines specification authority and procurement rhythm across the value chain.
- Utilities:State transmission companies and central sector entities like Power Grid Corporation drive 765 kV and 400 kV tender volumes. Green Energy Open Access Rules mandate their grid modernization investments.
- Renewable Energy:Solar park developers and wind cluster operators source step-up transformers for 33/132 kV collection systems. CERC renewable purchase obligations compel discoms to interconnect these assets.
- Industrial:Steel, cement, and petrochemical complexes procure dedicated substations for process reliability. Captive power plant regulations under the Electricity Act shape their interconnection transformer specifications.
- Commercial:Data centers and hospital complexes specify premium efficiency units for uninterrupted power. BIS IS 2026 efficiency tiers filter their procurement pools.
Utilities anchor annual procurement volumes; Renewable Energy climbs the fastest as park capacities multiply.
Installation:
Geography and civil works exposure differentiate environmental hardening requirements.
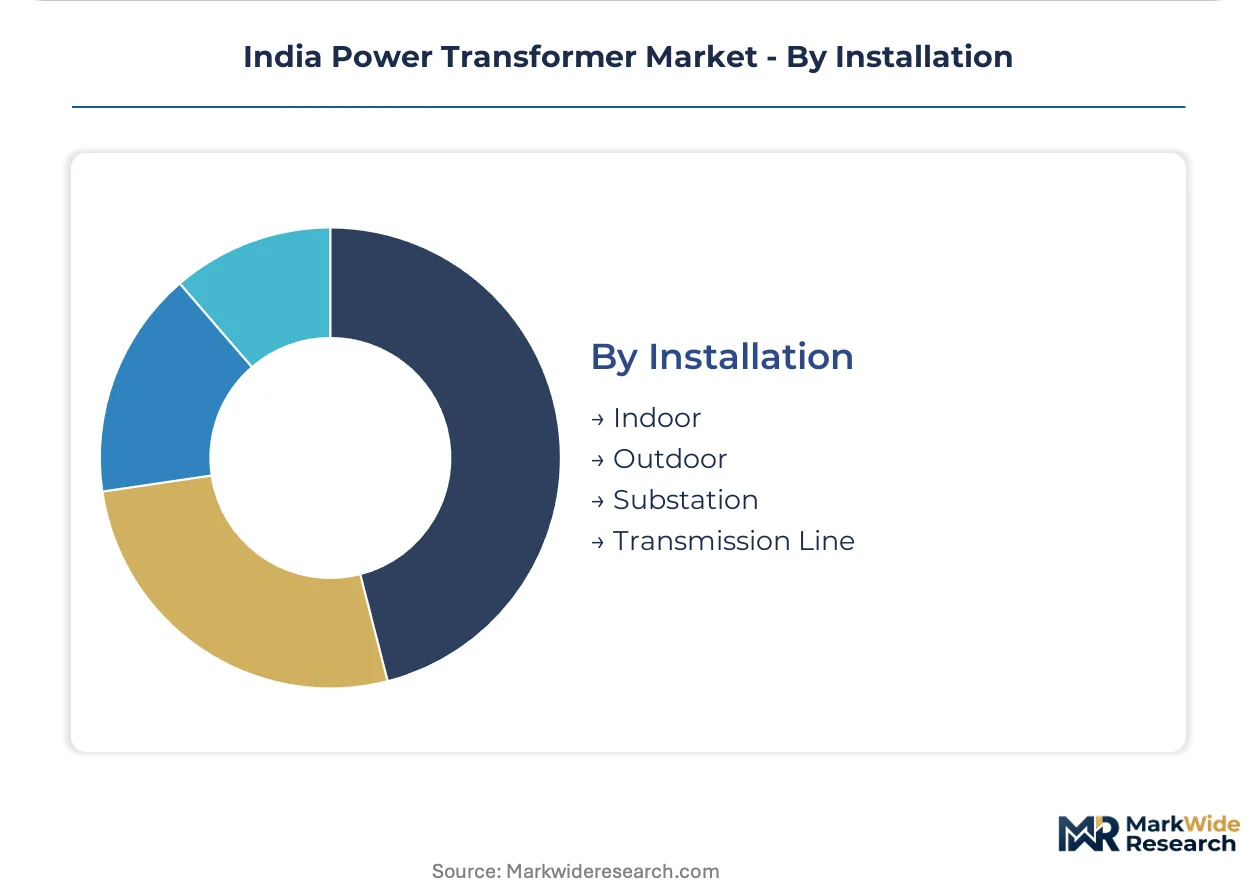
- Outdoor:Weatherproof enclosures and anti-corrosion finishes withstand monsoon humidity and saline coastal atmospheres. Gujarat's coastal wind farms and Tamil Nadu's solar parks specify this configuration exclusively.
- Substation:Yard-integrated assemblies with bushing connections to switchgear and circuit breakers. State transmission utilities unbundle these from civil works contracts in Karnataka and Tamil Nadu.
- Indoor:Climate-controlled buildings protect sensitive insulation systems. Urban metro rail traction substations and data center campuses in Delhi NCR favor this arrangement.
- Transmission Line:Mobile or semi-permanent units for emergency restoration and seasonal load relief. Northern grid operators deploy these during agricultural pumping peaks in Punjab and Haryana.
Outdoor claims the greatest unit count; Substation integration expands most quickly as renewable park developers direct-source hardware.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat commands pricing power on 765 kV tenders through captive port access for core material imports, while Himalayan states absorb freight premiums exceeding 15% for equivalent units. This asymmetry concentrates manufacturing investment in western coastal corridors.
Maharashtra
Maharashtra State Electricity Transmission Company releases the highest 400 kV and 765 kV tender volumes nationally. The state's Green Energy Open Access Rules implementation accelerates step-up transformer procurement for solar parks in Solapur and wind clusters in Satara. Mumbai's urban substation replacements specify dry-type units under municipal fire codes.
Gujarat
Gujarat Energy Transmission Corporation consolidates procurement around ultra-high-voltage units for inter-regional corridors. The state's coastal wind farms at Kutch and solar parks at Charanka drive outdoor oil-immersed specifications. Mundra and Hazira ports enable just-in-time oriented silicon steel delivery from Japanese mills.
Tamil Nadu
Tamil Nadu Generation and Distribution Corporation unbundles transformer supply from turnkey substation contracts. The state's renewable purchase obligations under CERC mandate 33/132 kV step-up units for solar parks in Kamuthi and wind estates in Tirunelveli. Chennai's manufacturing belt hosts winding facilities serving southern grid operators.
Karnataka
Karnataka Renewable Energy Development sources collection system transformers directly from manufacturers rather than through EPC intermediaries. The state's Pavagada and Koppal solar parks require 33 kV step-up configurations. Bangalore's technology corridor pilots gas-insulated units for metro rail traction substations.
Himachal Pradesh
Himachal Pradesh State Electricity Board favors single-phase transformer banks for terrain-constrained installations. The state's Himalayan road networks limit three-phase unit transport through tunnel and bridge clearances. Hydroelectric projects in Kinnaur and Chamba drive instrument transformer demand for protection relay integration.
India Power Transformer Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on material and testing capabilities. The vendor base stratifies between balance-sheet-heavy public sector undertakings and private manufacturers with captive core production. Three archetypes dominate: integrated steel-to-transformer producers, digital monitoring bundlers, and regional winding specialists serving state utilities. Capacity expansion and backward integration into grain-oriented silicon steel represent the primary competitive vectors.
Among integrated manufacturers, Bharat Heavy Electricals Limited anchors the public sector tier through captive steel and core material supply chains. CG Power and Industrial Solutions exemplifies scale-driven private positioning across western India manufacturing clusters. Siemens India occupies the digital convergence archetype, representing bundled hardware-software offerings for smart grid deployments.
| Leading Market Players |
|---|
| CG Power and Industrial Solutions |
| Transformers and Electricals Kerala (TELK) |
| Bharat Heavy Electricals Limited (BHEL) |
| Technical Associates |
| Gujarat Transformers |
| ABB India |
| Voltamp Transformers Limited |
| Uttam Bharat |
| Siemens India |
| Others |
Supply & Pricing Matrix
Japanese and South Korean oriented silicon steel mills command upstream pricing power, concentrating margin pools with domestic manufacturers possessing captive core-winding facilities and in-house testing infrastructure. State transmission utilities absorb freight premiums for Himalayan deployments while coastal access in Gujarat compresses landed costs for critical magnetic materials.
Pricing Analysis
Configured-to-order 765 kV units command 40-60% premiums over standard 33-132 kV catalog offerings. Three-tier pricing structure across premium efficiency, standard BIS-compliant, and economy import-replacement tiers filters procurement pools. Cost compression in standard ratings intensifies as PLI scheme beneficiaries expand domestic winding capacity. Renewable developers exhibit highest price sensitivity; central sector utilities prioritize efficiency certification over unit cost.
Supply Chain Analysis
Contract manufacturing concentrates at BHEL's integrated steel-to-transformer complexes and CG Power's western India winding clusters. Core material draws from Japan, South Korea, and limited domestic cold-rolling mills. Single-source vulnerability persists for grain-oriented silicon steel grades above 0.23 mm thickness. Distribution runs through state transmission utility tender channels and direct procurement by renewable park developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Grid modernization mandates under Green Energy Open Access Rules create platform-economics inflection as hardware-software bundles displace commodity transformer procurement. Interoperability between dissolved gas analysis sensors and SCADA systems redefines vendor qualification criteria.
For Market Incumbents: Insulate core material supply chains through backward integration into grain-oriented silicon steel cold-rolling or long-term offtake agreements with Japanese mills. Expand in-house short-circuit testing infrastructure to compress BIS certification cycles. Digital monitoring bundling represents the priority defensive lever against Siemens India's convergence play.
For New Entrants and Emerging Players: Pursue single-phase transformer banks for Himalayan corridor deployments where transport constraints filter incumbent competition. Target Karnataka and Tamil Nadu renewable park developers unbundling hardware from EPC contracts. Leasing-model project finance capabilities unlock infrastructure-as-a-service revenue streams.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated manufacturers with captive steel supply and testing infrastructure. Long-term viability hinges on PLI scheme extension and efficiency tier mandate tightening. Watch CEA Technical Standards revision timing as inflection indicator for Tier-1 supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Core Steel | Captive grain-oriented silicon steel supply insulates margin pools from currency volatility. |
| Digital Monitoring Convergence | Dissolved gas analysis sensor bundling with SCADA creates smart grid procurement preference. |
| Asset-Light Leasing Models | Infrastructure-as-a-service contracts unlock recurring revenue from balance-sheet-constrained state utilities. |
| Himalayan Single-Phase Specialization | Modular banks exploit terrain constraints that exclude three-phase unit competitors. |
| PLI Capacity Expansion | Domestic winding facility scale-up reduces import dependence for 33-765 kV ratings. |
Research Methodology
Cross-validation between utility procurement officers and renewable park developers anchors the qualitative findings. Primary interviews with state transmission planning heads, EPC contractor procurement leads, transformer plant managers, and CEA technical standards officials combined with secondary validation. Sources include CEA grid standards filings, state discom tender databases, BIS certification records, and customs import data for oriented silicon steel. Bottom-up unit shipment estimates triangulate against top-down infrastructure investment forecasts.
Calibration against historical tender award patterns and PLI scheme disbursement trajectories shapes the analytical framework. Segmentation dimensions span product architecture, cooling technology, end-user type, and installation environment across the projection horizon. CAGRs derive from capacity expansion pipelines, renewable purchase obligation trajectories, and grid modernization spend profiles. Forecast inputs incorporate Green Energy Open Access Rules implementation pace and BIS efficiency tier adoption curves.
Macroeconomic conditions sit as an overlay; deviation in rupee-yen exchange rates or oriented silicon steel spot pricing would shift the trajectory. Forecasts reflect assumptions on PLI scheme continuity and CEA mandate enforcement intensity. Quarterly review of state transmission utility tender releases and core material import volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Canada Transformer Market
Transformers
China Transformer Market
Transformers
Rectifier Transformers Market
Transformers
Oil Immersed Transformer and Dry Type Transformer Market
Transformers
Air Cooled Transformer Market
Transformers
Three Phase Transformer Market
Transformers
Power Transformer Market
Transformers
Transformer Core Market
Transformers
India Transformer Market
Transformers
US Oil Filled Distribution Transformer Market
Transformers
United States Distribution Transformer Market
Transformers
Green Power Transformers Market
Transformers
Transformer Oil Market
Transformers
Middle East and Africa Transformer Market
Transformers
Europe Oil Filled Distribution Transformer Market
Transformers
Liquid-Immersed Transformers Market