
 EHV & UHV (above 330KV) Power Transformers Market | 2026-2036
EHV & UHV (above 330KV) Power Transformers Market Size, Share, and Industry Trends Forecast 2026-2036
EHV & UHV (above 330KV) Power Transformers Market Insights
Chinese transformer manufacturers is rebalancing global supply chains after years of domestic capacity expansion. ABB leverages its technology leadership in UHVDC converter transformers to anchor premium contract flows across Europe and the Middle East. Siemens AG sustains engineering intensity through dedicated high-voltage laboratories in Germany. TBEA dominates captive demand from China's State Grid Corporation, while Hyundai Electric competes aggressively on Korean and Southeast Asian substation tenders.
EHV and UHV power transformers above 330 kV are electromagnetic devices engineered with grain-oriented electrical steel cores and mineral oil or synthetic ester insulation systems, designed to step voltage levels for bulk power transmission across distances exceeding 500 kilometers. These units typically operate at 400 kV, 765 kV, or 1100 kV and handle power ratings from 300 MVA to over 1000 MVA, serving as critical nodes in national backbone grids and cross-border interconnections. Three-phase configurations occupy the largest installed base due to economies of scale in high-capacity substations, while oil-immersed technology leads because of superior thermal management and dielectric strength at extreme voltages. Gas-insulated designs are gaining traction in offshore wind collector platforms and dense urban substations where footprint constraints override cost premiums.
FERC Order 2023 in the United States and the EU Green Deal's grid reinforcement targets are accelerating replacement cycles for aging EHV assets, while China's GB/T standards and India's CEA technical regulations mandate localized testing facilities for UHV imports. IEC 60076 and IEEE C57 govern insulation coordination and short-circuit withstand, creating compliance barriers that favor incumbents with certified in-house test bays. Stakeholders must monitor grid code harmonization between asynchronous power systems and assess converter transformer demand tied to expanding HVDC interconnector projects.
Market Dynamics
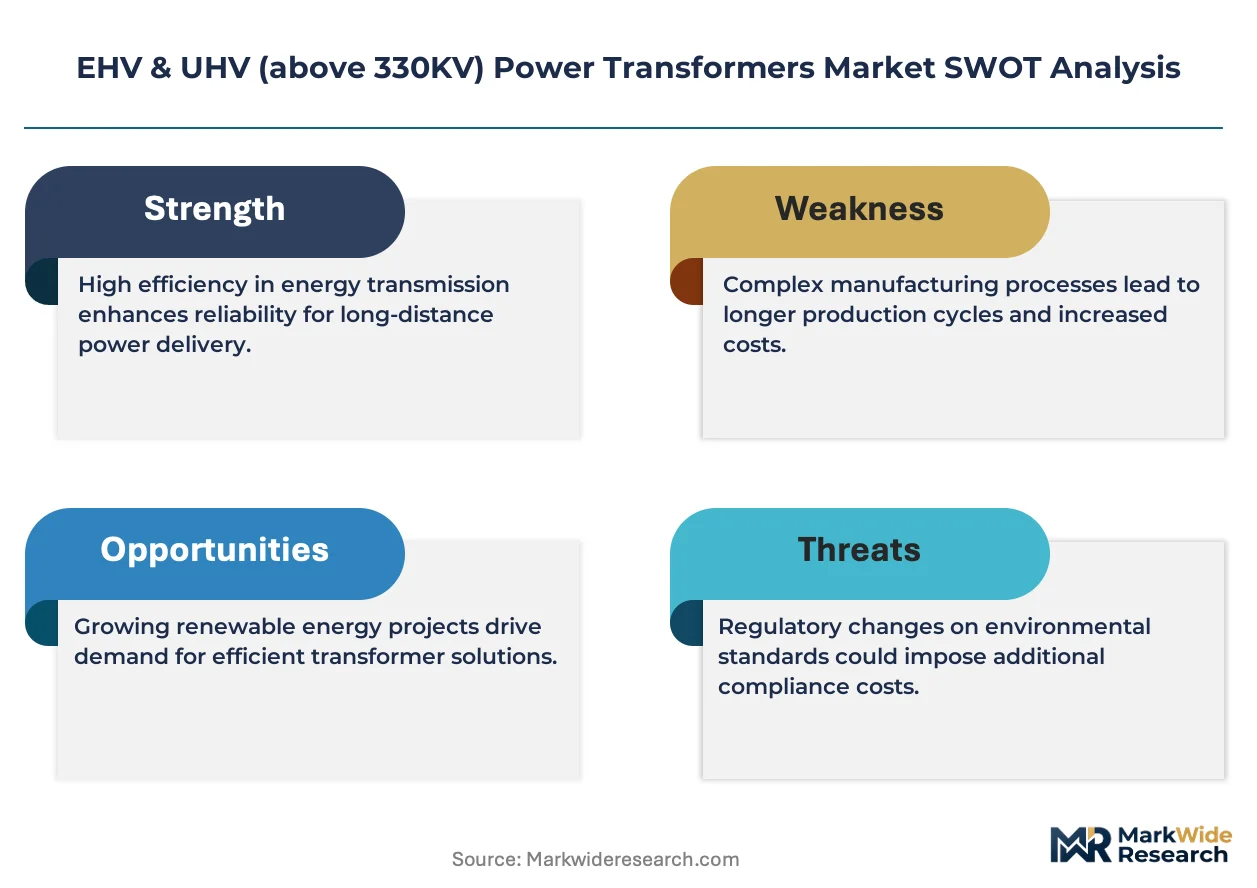
UHVDC transmission corridors spanning 500+ kilometers are reshaping procurement patterns as utilities consolidate orders around converter transformer specialists capable of integrating AC-DC conversion with voltage transformation.
Growth Catalysts
- Grid Interconnection Mandates:China's State Grid Corporation is expanding UHVDC links between western renewable zones and eastern load centers, creating captive demand for 1100 kV converter transformers.
- FERC Order 2023:The US Federal Energy Regulatory Commission is accelerating replacement cycles for aging EHV assets through reliability standards that mandate thermal performance upgrades.
- Synthetic Ester Fluids:Fire-resistant biodegradable insulation is penetrating densely populated substations where mineral oil leakage risks trigger environmental liability.
Market Restraints
- Grain-Oriented Electrical Steel Concentration:Six Japanese and European mills control 80% of high-permeability core steel supply, exposing transformer OEMs to alloying element volatility.
- IEC 60076 Testing Barriers:Certification requires in-house short-circuit test bays costing $50+ million, structurally excluding regional fabricators from UHV classes.
- Gas-Insulated Transformer Cost Premium:SF6-free designs for offshore wind platforms carry 40-60% price deltas versus oil-immersed equivalents, limiting adoption outside footprint-constrained sites.
Strategic Opportunities
- India's Green Energy Corridors:The Central Electricity Authority's transmission expansion plans target 66 GW renewable integration, opening UHV substation tenders in Rajasthan and Gujarat.
- EU Green Deal Grid Reinforcement:Cross-border HVDC interconnectors between Germany and Norway are stimulating converter transformer demand for asynchronous system coupling.
- Digital Twin Convergence:Asset health monitoring fused with predictive maintenance algorithms is creating service revenue streams separate from equipment sales.
Industry Challenges
- Specialized Winding Engineers:UHV transformer design requires expertise in impulse voltage distribution modeling that resides in fewer than 200 engineers across three continents.
- Legacy Substation Integration:Retrofitting 400 kV UHV units into 1960s-era switchyards forces custom bushing configurations and foundation modifications that extend project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EHV & UHV (above 330KV) Power Transformers Market |
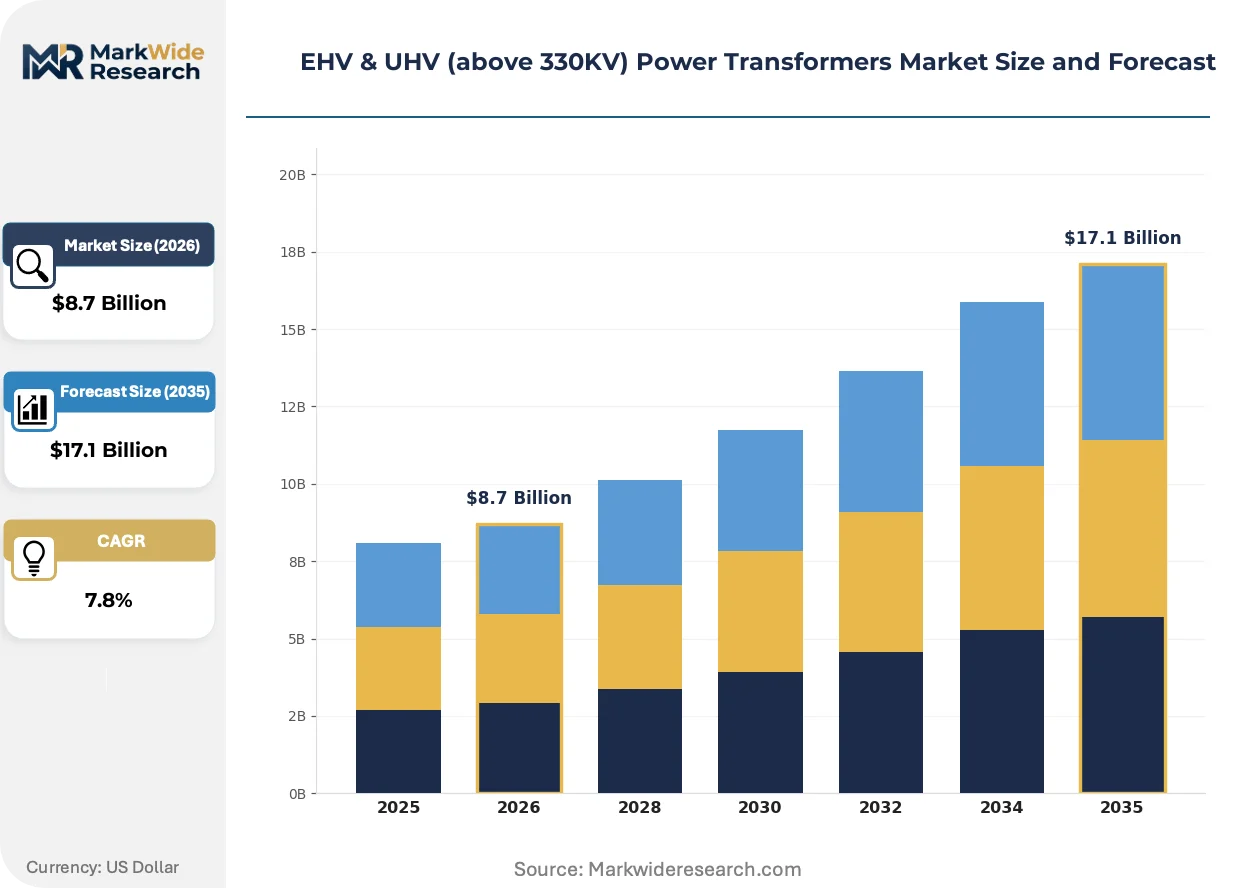
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Phase, Three-Phase, Autotransformer, Isolation Transformer Technology: Oil-Immersed, Dry-Type, Gas-Insulated, Hybrid End User: Utilities, Renewable Energy Sites, Industrial Facilities, Data Centers Installation: Onshore, Offshore, Substation, Mobile |
| Companies Covered | ABB, Siemens AG, General Electric, Toshiba Corporation, Mitsubishi Electric Corporation, Schneider Electric, Hyundai Electric, TBEA, China XD Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EHV & UHV (above 330KV) Power Transformers Market Trends and Innovations
Active materials substitution and digital instrumentation are compressing thermal margins while extending asset lifecycles beyond traditional 40-year design assumptions.
Amorphous metal core laminations are electrifying distribution-class efficiency benchmarks, though grain-oriented silicon steel retains dominance above 330 kV due to flux density requirements. Offshore wind developers in the North Sea are piloting amorphous inserts for collector platform step-up units where load variability is extreme. This hybrid approach is electrifying niche procurement specifications that previously excluded non-traditional core materials.
The EU F-Gas Regulation is phasing down sulfur hexafluoride use in switchgear and pressurized transformers, compelling OEMs to accelerate dry-type and nitrogen-insulated designs for urban installations. German transmission system operators now mandate SF6-free alternatives in tenders for inner-city substations. Converter transformer manufacturers are responding with vacuum-interrupter prototypes that eliminate gas dependence entirely.
Asset performance guarantees are displacing traditional capital purchase models as state-owned utilities in Asia-Pacific seek to transfer operational risk to OEMs. Siemens and ABB now offer 25-year service contracts bundled with UHV unit supply, capturing lifecycle value. This shift is most visible in Saudi Arabia and UAE grid expansion programs where sovereign wealth funds prioritize opex predictability over upfront capex minimization.
EHV & UHV (above 330KV) Power Transformers Market Segmentation
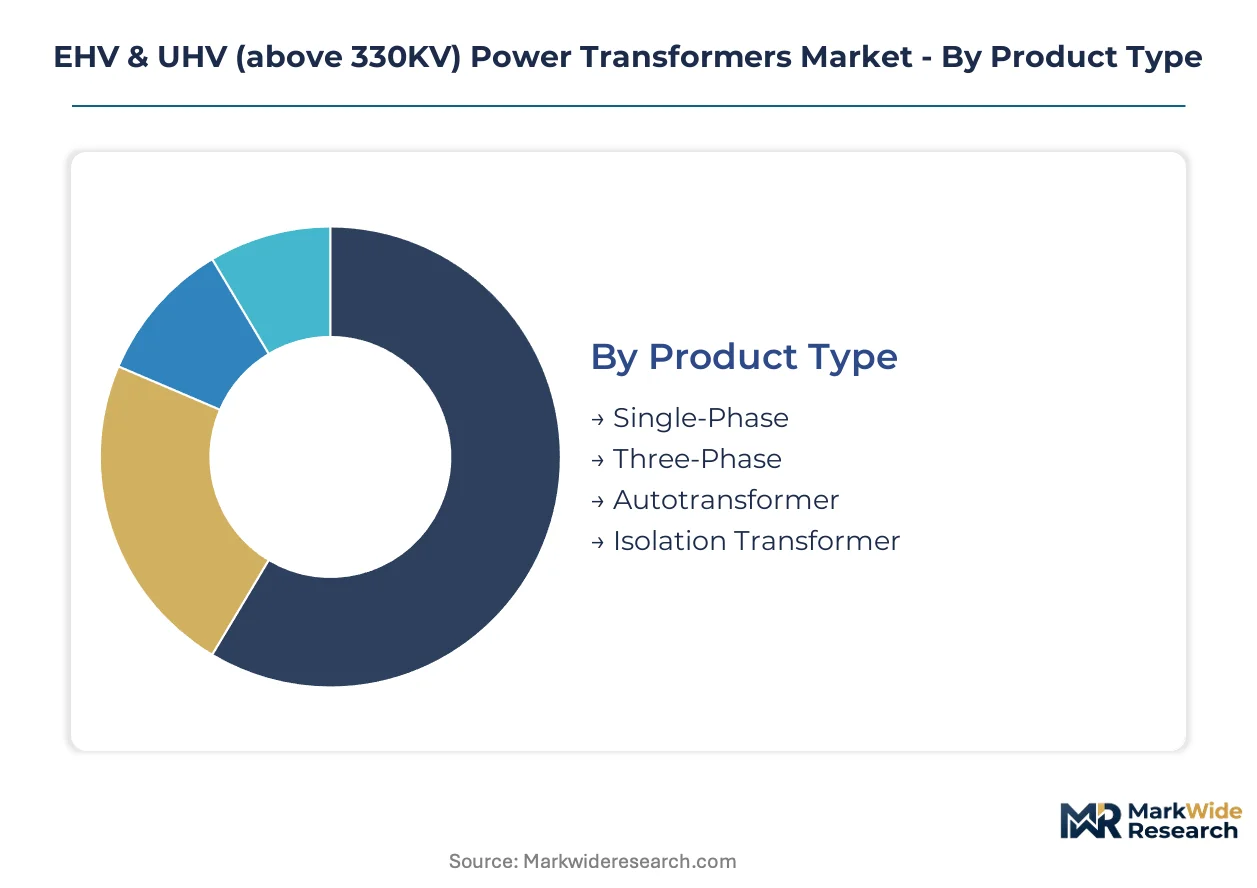
Segmentation in EHV and UHV power transformers reveals distinct procurement patterns tied to grid architecture choices. Technical specifications diverge sharply between bulk transmission corridors and distributed renewable integration nodes, with each segment commanding specialized manufacturing capabilities and testing protocols.
Product Type:
Integration depth varies dramatically across product architectures, with standalone units dominating bulk transmission while embedded configurations serve specialized grid functions.
- Three-Phase:These units consolidate three single-phase cores within one tank assembly, achieving economies of scale in 400 kV to 1100 kV substations. State Grid Corporation of China procures these exclusively for UHVDC converter stations linking western renewable zones to eastern load centers, where space constraints and capital efficiency override redundancy preferences.
- Single-Phase:Individual phase units permit transport by rail and road where weight limits restrict three-phase alternatives. Indian Railways and mountainous corridor projects in the Alps specify these for 765 kV lines where tunnel clearances and bridge load ratings constrain logistics.
- Autotransformer:Common winding designs reduce copper mass by 30-40% compared to conventional two-winding units. These dominate voltage step-down applications in dense European transmission networks where material efficiency offsets higher insulation complexity.
- Isolation Transformer:Galvanic separation between primary and secondary windings protects sensitive downstream equipment. Data center operators in Frankfurt and Singapore specify these for critical power conditioning despite 15-20% cost premiums.
Three-phase configurations lead volumes today; autotransformers are gaining share fastest in European grid reinforcement programs.
Technology:
Cost tiering separates mature oil-immersed platforms from emerging alternatives carrying 40-60% price deltas, with selection driven by fire safety regulations and footprint constraints rather than performance alone.
- Oil-Immersed:Mineral oil or synthetic ester dielectrics provide superior thermal conductivity and dielectric strength at extreme voltages above 500 kV. These units populate virtually all UHVDC corridors and 765 kV backbone substations, with IEC 60076 certification mandating in-house short-circuit test bays that exclude regional fabricators.
- Gas-Insulated:Sulfur hexafluoride or nitrogen pressurization enables 60% footprint reduction versus oil equivalents. German transmission system operators mandate SF6-free alternatives for inner-city Berlin and Munich substations under EU F-Gas Regulation phase-down schedules.
- Dry-Type:Epoxy resin or cast resin insulation eliminates liquid fire risk entirely. These penetrate underground urban installations in Tokyo and London where building codes prohibit oil-filled equipment.
- Hybrid:Combinations of gas and solid insulation address offshore wind collector platforms in the North Sea. Danish and German developers pilot these for 66 kV to 220 kV step-up duties where salt spray corrosion and space constraints coexist.
Oil-immersed technology leads volumes today; gas-insulated designs are expanding most quickly in offshore wind and dense urban substations.
End User:
Application context determines specification intensity, with utility procurement emphasizing 40-year asset lifecycles while industrial buyers prioritize modularity and rapid deployment.
- Utilities:National transmission system operators specify 1000+ MVA units with 25-year performance guarantees bundled into lifecycle service contracts. Saudi Arabia's sovereign wealth funds and UAE grid expansion programs now demand opex predictability over upfront capex minimization.
- Renewable Energy Sites:Wind and solar farms require step-up transformers for 33 kV to 400 kV conversion. Rajasthan and Gujarat renewable zones in India drive UHV substation tenders as the Central Electricity Authority targets 66 GW renewable integration.
- Industrial Facilities:Steel mills and aluminum smelters demand high-reliability units for direct grid connection. These installations emphasize short-circuit withstand and harmonic tolerance over efficiency optimization.
- Data Centers:Hyperscale operators in Northern Virginia and Dublin specify isolation transformers with active harmonic filtering. These prioritize uptime guarantees and fire safety over capital cost.
Utilities lead volumes today; renewable energy sites are climbing the fastest as grid interconnection mandates accelerate.
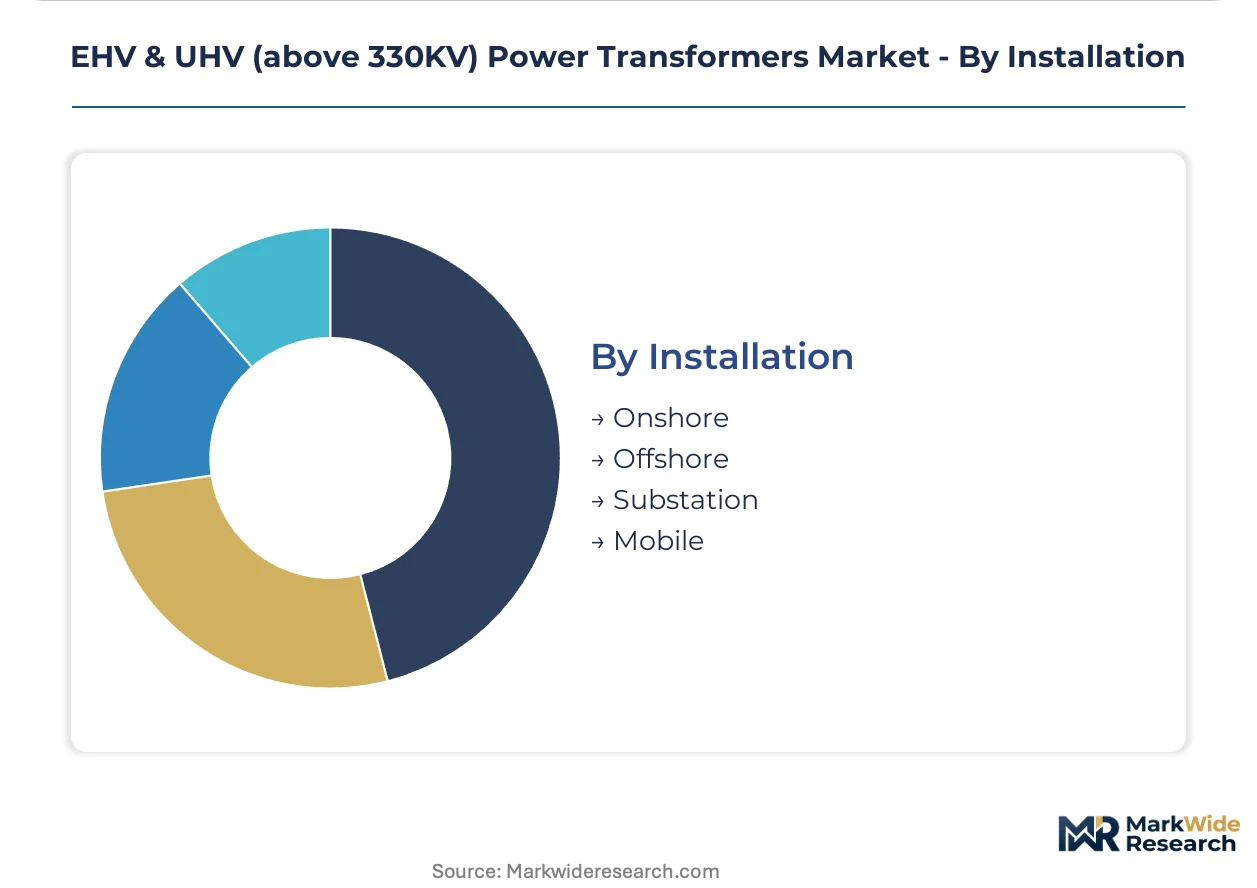
Installation:
Geography and mobility requirements split procurement between permanent infrastructure and deployable assets, with offshore specifications commanding specialized corrosion protection and marine logistics.
- Onshore:Concrete pad-mounted installations dominate 400 kV and 765 kV substations across continental grids. These permit heaviest transport weights and largest single-unit capacities, with foundation design standardized across Chinese western province corridors.
- Substation:Fixed switchyard integration requires custom bushing configurations and foundation modifications when retrofitting 1960s-era facilities. German and French operators face legacy integration challenges as they replace aging EHV assets under EU Green Deal targets.
- Offshore:Platform-mounted units require nitrogen inerting and stainless steel enclosures against salt spray. North Sea wind developers specify these for 220 kV collector platforms where helicopter access limits maintenance frequency.
- Mobile:Skid-mounted or trailer-mounted configurations enable rapid grid restoration after natural disasters. These serve emergency response protocols in Japan and California where seismic and wildfire risks demand deployable redundancy.
Onshore installations lead volumes today; offshore configurations are gaining share fastest in North Sea wind development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting transformer procurement as compliance-cost gaps between jurisdictions reshape where utilities source UHV equipment. Manufacturers face divergent certification burdens that concentrate premium production in economies with established test infrastructure.
China
State Grid Corporation's western province corridors drive 1100 kV converter transformer demand from Xinjiang and Gansu renewable zones. GB/T standards mandate localized testing facilities for UHV imports, protecting domestic fabricators. TBEA anchors production in Xinjiang's Urumqi industrial cluster, supplying captive demand for eastbound transmission links.
United States
FERC Order 2023 accelerates replacement cycles for aging 765 kV assets across PJM and ERCOT interconnections. Reliability standards mandate thermal performance upgrades that favor OEMs with certified short-circuit test bays. Texas Gulf Coast petrochemical clusters and California ISO nodes concentrate procurement for grid hardening against extreme weather.
Germany
EU Green Deal grid reinforcement targets stimulate cross-border HVDC interconnectors to Norway and Denmark. EU F-Gas Regulation phase-down schedules mandate SF6-free alternatives for Berlin and Munich inner-city substations. Siemens AG maintains engineering intensity through dedicated high-voltage laboratories in Nuremberg and Berlin.
India
CEA transmission expansion targets 66 GW renewable integration through Green Energy Corridors in Rajasthan and Gujarat. Central Electricity Authority technical regulations require localized testing facilities for UHV imports, structurally excluding regional fabricators. Ahmedabad and Vadodara industrial zones concentrate domestic transformer manufacturing capacity.
Saudi Arabia
Sovereign wealth fund grid expansion programs prioritize opex predictability over upfront capex minimization in UHV procurement. SFDA and national grid codes tighten efficiency standards for ultra-high voltage classes. Riyadh and Eastern Province industrial cities anchor substation deployment for renewable integration and desalination load growth.
EHV & UHV (above 330KV) Power Transformers Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue offshore wind and digital service revenue streams. The vendor base stratifies around three archetypes: integrated conglomerates with captive test infrastructure, regional specialists serving protected domestic markets, and technology licensors extracting value from IP portfolios. Consolidation pressure intensifies as IEC 60076 certification barriers exclude second-tier fabricators from UHV classes. Dominant competitive moves include strategic partnerships for HVDC converter technology and geographic expansion into India's renewable corridor tenders.
Among integrated European conglomerates, ABB and Siemens AG exemplify the premium-tier archetype through technology leadership in UHVDC converter transformers. TBEA represents the protected-domestic-market specialist, anchoring captive supply relationships with China's State Grid Corporation. These three occupy positions that reflect divergent strategic bets: ABB on cross-border interconnectors, Siemens on lifecycle service contracts, and TBEA on western province renewable integration corridors.
| Leading Market Players |
|---|
| ABB |
| Siemens AG |
| General Electric |
| Toshiba Corporation |
| Mitsubishi Electric Corporation |
| Schneider Electric |
| Hyundai Electric |
| TBEA |
| China XD Electric |
| Others |
Pricing and Supply Chain Analysis
State Grid Corporation of China and other national transmission system operators concentrate procurement power through consolidated tendering for 1100 kV converter transformers, anchoring contract-based long-term offtake as the dominant pricing model across the EHV and UHV power transformers market. This buyer concentration feeds directly into supply chain configuration, as OEMs with certified in-house short-circuit test bays command premium positioning while regional fabricators face structural exclusion from ultra-high voltage classes.
Pricing Analysis
Distributor margins in transformer procurement are compressed to single-digit percentages as direct-to-utility channels dominate high-voltage equipment sales. Three-tier pricing structure across premium, standard, and economy levels separates IEC 60076-certified units with full lifecycle service contracts from basic specifications lacking predictive maintenance integration. Cost compression in the economy tier is intensifying because Indian and Middle Eastern utilities are consolidating orders around converter transformer specialists capable of bundling AC-DC conversion with voltage transformation. Industrial facilities in aluminum smelting and steel production exhibit highest price sensitivity due to capital intensity pressures, while data center operators in Frankfurt and Singapore prioritize uptime guarantees over capital cost minimization.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from State Grid Corporation and Saudi sovereign wealth funds, bypassing traditional distribution layers entirely. Manufacturing gravity centers on China, Germany, and India, with TBEA anchoring production in Xinjiang's Urumqi industrial cluster and Siemens maintaining engineering intensity through dedicated high-voltage laboratories in Nuremberg. Raw material dependencies draw from Japanese and European mills for grain-oriented electrical steel, copper winding conductors, and synthetic ester dielectric fluids. Single-source vulnerability in high-permeability core steel supply exposes transformer OEMs to alloying element volatility. Distribution runs through project-specific logistics chains coordinated with EPC contractors for substation integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EHV and UHV power transformers market represents a late-cycle quality story where asset performance guarantees and 25-year service contracts are displacing traditional capital purchase models. State-owned utilities across Asia-Pacific and the Middle East are transferring operational risk to OEMs, elevating premium specifications that bundle predictive maintenance algorithms with equipment supply.
For Market Incumbents: Anticipate consolidation pressure as IEC 60076 certification barriers structurally exclude second-tier fabricators from ultra-high voltage classes. Defensive positioning requires deepening backward integration into grain-oriented electrical steel supply relationships to mitigate Japanese and European mill concentration risk. Capacity addition in India's Ahmedabad and Vadodara industrial zones captures Green Energy Corridor tenders while Saudi and UAE grid expansion programs prioritize opex predictability over upfront capex minimization.
For New Entrants and Emerging Players: The 40-60% price delta between gas-insulated and oil-immersed designs creates entry space for SF6-free alternatives in offshore wind collector platforms and dense urban substations. White-space targets concentrate on North Sea wind development and German inner-city substations under EU F-Gas Regulation phase-down schedules. Rajasthan and Gujarat renewable zones in India offer the most penetrable geography given CEA transmission expansion targeting 66 GW renewable integration. Go-to-market positioning should emphasize vacuum-interrupter prototypes that eliminate gas dependence entirely.
For Investors and Strategic Acquirers: Utility infrastructure funds and sovereign wealth vehicles are the most active acquirer in this space, prioritizing asset-heavy OEMs with captive test infrastructure and long-term service contract backlogs. Long-term viability over a 5-10 year window rests on converter transformer technology leadership and HVDC interconnector exposure. Acquisition target archetypes include regional specialists serving protected domestic markets with established grid code relationships. The signal to monitor is harmonization between asynchronous power systems and expanding HVDC interconnector project pipelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Core Steel Supply | Mitigates concentration risk from six Japanese and European mills controlling high-permeability grain-oriented electrical steel. |
| SF6-Free Alternative Development | Addresses EU F-Gas Regulation phase-down schedules mandating gas-insulated transformer alternatives for urban substations. |
| Lifecycle Service Contract Bundling | Captures recurring revenue from Saudi Arabia and UAE sovereign wealth funds prioritizing opex predictability. |
| Localized Testing Facility Investment | Satisfies GB/T standards in China and CEA technical regulations in India that mandate domestic certification for UHV imports. |
| Digital Twin Convergence | Creates predictive maintenance revenue streams separate from equipment sales through asset health monitoring algorithms. |
Research Methodology
Bottom-up utility procurement modeling reconciled against top-down transformer OEM capacity tracking forms the analytical core of this study. Primary interviews with utility planning officers, EPC contractors, grid operators, transformer design engineers, and aftermarket service heads were combined with secondary validation from IEC 60076 certification databases, FERC filings, SEC 10-K disclosures from listed electrical equipment manufacturers, and national grid code documentation from China, India, and Germany. Triangulation between demand-side tender analysis and supply-side manufacturing footprint mapping ensures consistency across volume and value estimates.
Historical trendline analysis of installed base replacement cycles and renewable integration project pipelines informs the projection framework. Segmentation dimensions modeled include product architecture, insulation technology, end-use application, and installation geography across the analysis window. CAGRs were derived from regression analysis of tender award volumes, capacity utilization rates at major production facilities, and grid interconnection mandate implementation timelines. Forecast inputs incorporate UHVDC corridor development schedules and offshore wind collector platform deployment trajectories.
Caveats apply where raw material alloying element volatility, regulatory harmonization delays between asynchronous power systems, or SF6 alternative technology maturation could materially shift the outlook. Forecasts reflect assumptions regarding continued grid code tightening and sovereign wealth fund prioritization of lifecycle service contracts over capital purchase models. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
United States Large Power Transformer Market
Transformers
Oil Immersed Transformer and Dry Type Transformer Market
Transformers
Saudi Arabia Transformer Market
Transformers
South America Transformer Market
Transformers
North America Oil Filled Transformer Market
Transformers
Auto Transformer Rectifier Unit (ATRU) Market
Transformers
Global Large Power Transformers Market
Transformers
United Arab Emirates Transformer Market
Transformers
India Distribution Transformer Market
Transformers
Latin America Transformer Market
Transformers
United States Distribution Transformer Market
Transformers
Asia-Pacific Transformer Market
Transformers
Liquid Filled Transformer Market
Transformers
North America Dry Type Transformer Market
Transformers
Transformer Bobbin Market
Transformers
Europe Telecom Transformers Market