
 Transformer Core Market | 2026-2036
Transformer Core Market Size, Share, and Industry Trends Forecast 2026-2036
Transformer Core Market Analysis
Utility procurement is broadening beyond traditional national grid operators to include independent power producers and large-scale renewable developers. Metglas Inc. anchors the amorphous metal segment with proprietary rapid-solidification technology. Fuji Electric Co. Ltd. dominates Asia-Pacific manufacturing scale for grain-oriented silicon steel cores. Vilas Transcore Ltd. specializes in toroidal and C-type configurations for distribution transformer OEMs.
A transformer core is a magnetic circuit element, typically laminated from grain-oriented silicon steel or cast from amorphous alloys, engineered to minimize eddy current losses while channeling magnetic flux between primary and secondary windings. Core loss performance, measured in watts per kilogram at specific flux densities and frequencies, determines operational efficiency across load cycles. Silicon steel laminations retain the largest installed base across power transformer applications, though amorphous steel cores command premium positioning in distribution networks where no-load losses dominate lifecycle cost. Ferrite cores occupy niche frequency domains in instrument transformers and specialty electronics, while plastic-encapsulated variants serve cost-sensitive, low-voltage instrumentation segments.
The US Department of Energy enforces minimum efficiency standards through NHTSA-aligned federal rulemaking on distribution equipment, while China's SAMR administers GB standards that mandate tiered core loss reductions. India's BIS certification framework requires domestic transformer cores to meet specified magnetic properties for grid-connected equipment. Stakeholders must monitor how regional efficiency mandates diverge in stringency and test methodology, as compliance fragmentation shapes material selection and factory location decisions.
Market Dynamics
GB standards tightening core loss requirements across China's distribution network is forcing manufacturers to retool laminations toward thinner-gauge silicon steel and amorphous alloys, compressing margins for legacy grain-oriented suppliers while opening premium positioning for rapid-solidification specialists.
Growth Catalysts
- Data Center Load Growth:Hyperscale facilities in Northern Virginia and Phoenix are procuring high-efficiency distribution transformers with amorphous steel cores to minimize no-load losses across 24/7 operations.
- Rural Electrification Mandates:India's CEA directives require state utilities to modernize distribution networks, concentrating transformer core demand in Maharashtra, Gujarat, and Tamil Nadu for amorphous steel deployments.
- EU F-Gas Regulation Phase-Down:The regulation is accelerating replacement cycles for distribution transformers, pulling forward core procurement timelines as utilities preempt efficiency compliance deadlines.
Market Restraints
- Amorphous Metal Supply Concentration:Rapid-solidification capacity concentrates with Metglas Inc. and limited Asian licensors, creating single-source risk for distribution transformer OEMs qualifying alternative suppliers.
- Grain-Oriented Silicon Steel Price Volatility:Iron ore and nickel input costs swing with Australian and Brazilian mining output, compressing core lamination margins unpredictably.
- Technical Thickness Limitations:Conventional rolling mills face physical constraints below 0.18mm gauge, capping loss reduction potential for traditional silicon steel architectures.
Strategic Opportunities
- India PLI Scheme for Manufacturing:The production-linked incentive framework subsidizes domestic amorphous core production, enabling cost-competitive positioning against imported Japanese and American supply.
- Offshore Wind Transformer Demand:Floating substation projects in the North Sea require compact, high-flux-density core designs that favor nanocrystalline and advanced ferrite configurations.
- Digital Twin Integration:Convergence of core thermal modeling with IoT sensor networks enables predictive maintenance contracts, unbundling hardware sales from lifecycle service revenue.
Industry Challenges
- Magnetic Properties Certification Delays:BIS testing protocols in India require 90-120 day validation cycles, throttling OEM qualification timelines for new core suppliers.
- Amorphous Alloy Handling Expertise:Rapid-solidified ribbons demand specialized annealing and winding equipment, constraining workforce scalability for tier-two transformer manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transformer Core Market |
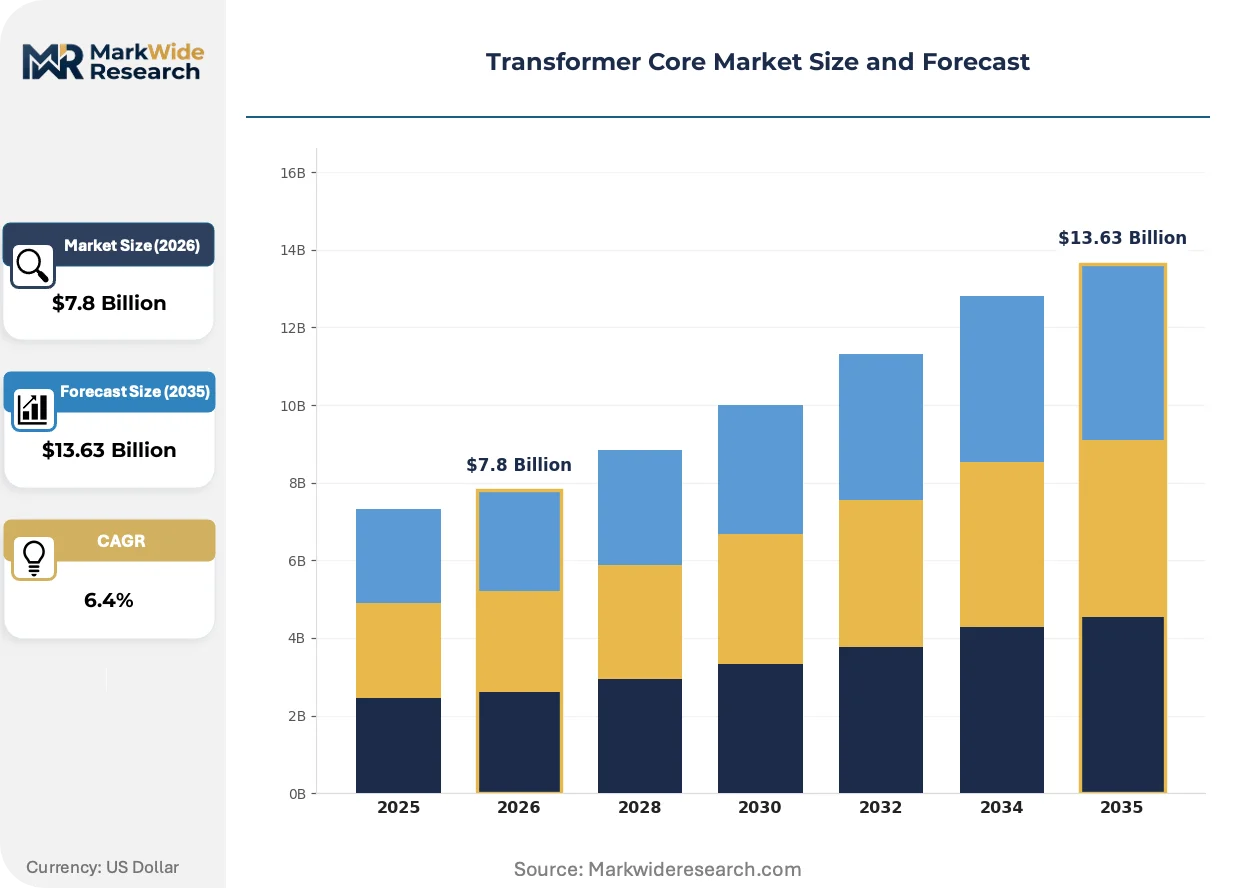
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Core Material: Silicon Steel, Amorphous Steel, Ferrite, Plastic Winding Type: Split Winding, Layered Winding, Circular Winding, Dual Winding Core Shape: Shell Type, EI Type, Toroidal, C-Type Application: Power Transformers, Distribution Transformers, Instrument Transformers, Specialty Transformers |
| Companies Covered | Arteche, Coefficient S.R.L., Eilor Magnetic Cores, Foshan Juli Electromechanical Co., Ltd., Corefficient S de RL de CV, Ferroxcube International Holding B.V., Fuji Electric Co. Ltd., Metglas Inc., Vilas Transcore Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transformer Core Market Emerging Trajectories
Active material substitution and digitalization of magnetic design are compressing traditional procurement cycles while elevating performance specifications that favor specialized alloy formulations over commodity silicon steel.
Amorphous metal ribbon is electrifying distribution transformer architectures through its near-zero hysteresis characteristics. Data center operators and urban utilities are specifying Hitachi-Metglas cores for new-build substations. This material shift is compressing the addressable market for conventional 0.23mm grain-oriented laminations in sub-10MVA applications.
China's SAMR is enforcing GB 20052-2020 tiered efficiency mandates that ratchet maximum core loss allowances downward through 2025. Domestic transformer OEMs are qualifying thinner-gauge silicon steel and hybrid amorphous-silicon configurations to maintain grid-connection eligibility. The policy is accelerating factory retooling in Jiangsu and Shandong provinces.
Integrated procurement platforms are consolidating transformer core sourcing through long-term offtake agreements with alloy producers. European utilities are bypassing traditional distributor networks to contract directly with Nippon Steel and Cogent Power for multi-year lamination supply. This channel compression is most visible in Germany and the Netherlands where TenneT and Stedin have centralized technical procurement functions.
Transformer Core Market Segmentation
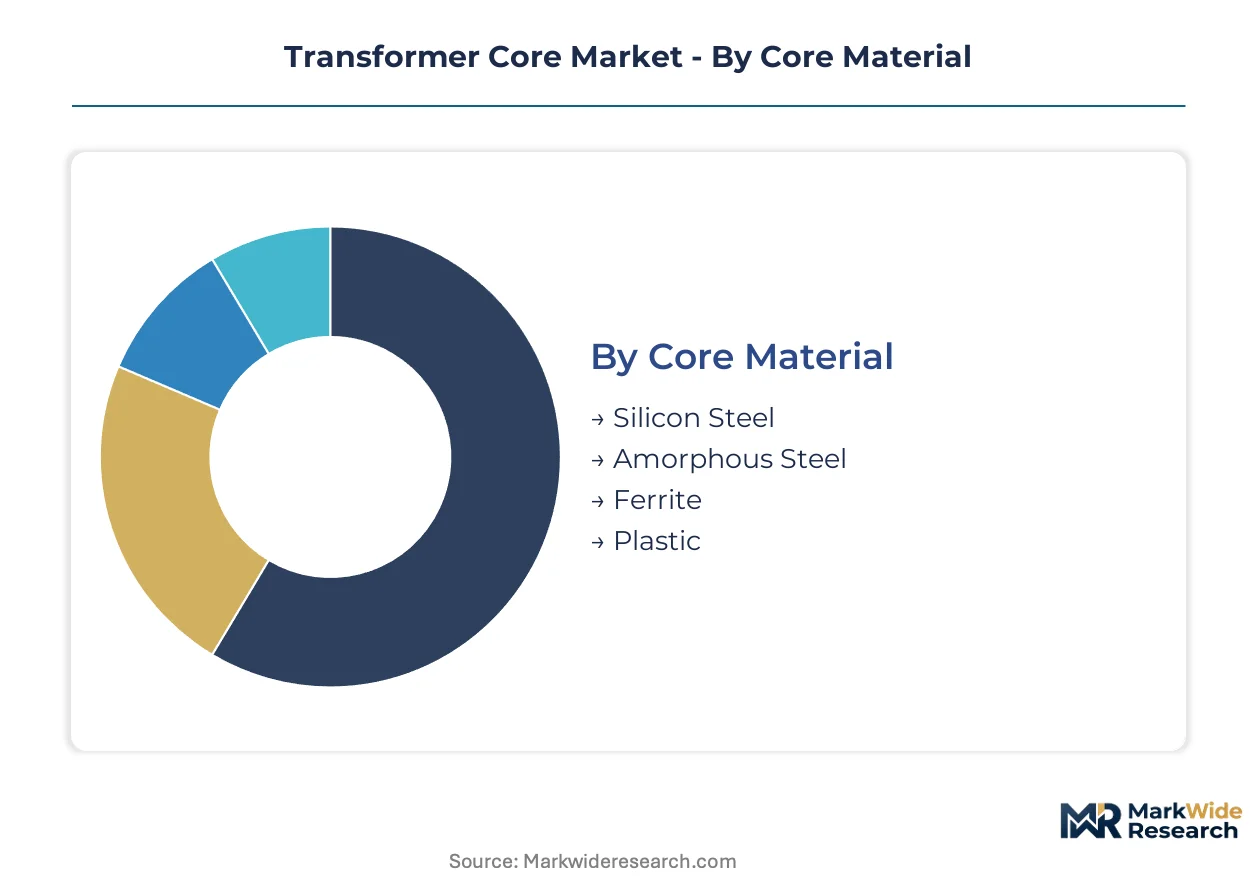
Transformer core procurement decisions pivot on loss-performance tradeoffs, installation footprint constraints, and regulatory efficiency mandates. Material selection and geometric configuration determine lifecycle economics across utility, industrial, and data center deployments.
Core Material:
Buyers weigh no-load loss coefficients against raw material premiums when specifying core alloys for grid-connected equipment.
- Silicon Steel:Grain-oriented laminations with 3% silicon content dominate power transformer ratings above 100 MVA. Procurement concentrates with state utilities in Maharashtra and Tamil Nadu for 0.23mm gauge standard-efficiency cores.
- Amorphous Steel:Rapid-solidified metal ribbons achieve 70-80% lower hysteresis losses than crystalline alternatives. Data center operators in Northern Virginia and Phoenix specify Hitachi-Metglas cores for 24/7 distribution transformer operations.
- Ferrite:Manganese-zinc and nickel-zinc ceramic compositions serve high-frequency instrument transformer applications above 10 kHz.
- Plastic:Encapsulated ferrite-polymer composites address cost-sensitive low-voltage instrumentation with reduced magnetic permeability requirements.
Volume sits with silicon steel; growth tilts toward amorphous steel.
Winding Type:
Manufacturing complexity and copper utilization rates separate procurement tiers across OEM supply chains.
- Split Winding:Dual-section primary configurations enable tap-changing flexibility in transmission-grade power transformers. Jiangsu province factories specialize in 220 kV+ split-winding core assemblies for China's State Grid tenders.
- Layered Winding:Concentric cylindrical conductors optimize fill factor in distribution transformers below 10 MVA. Indian OEMs in Gujarat deploy automated layering lines for rural electrification contracts.
- Circular Winding:Radial conductor arrangements minimize eddy current losses in high-current rectifier transformers.
- Dual Winding:Independent primary-secondary sections support phase-shifting and voltage regulation applications in industrial substations.
Layered winding commands unit volume; split winding captures margin concentration.
Core Shape:
Flux path geometry and winding accessibility determine manufacturing automation compatibility and field service requirements.
- Shell Type:Windings encircle the center leg with magnetic return paths on both sides, delivering high short-circuit strength. European utilities in Germany and the Netherlands specify shell-type cores for offshore wind substation transformers.
- Toroidal:Continuous ring-shaped magnetic paths eliminate air gaps and reduce stray flux. Vilas Transcore Ltd. supplies toroidal configurations for noise-sensitive urban distribution installations in Mumbai and Chennai.
- EI Type:Stacked I-section center with E-section end pieces enables economical core assembly for small distribution transformers.
- C-Type:Split-core designs facilitate retrofit installation around existing buswork in instrument transformer applications.
EI type dominates unit shipments; toroidal shapes gain share fastest in premium efficiency segments.
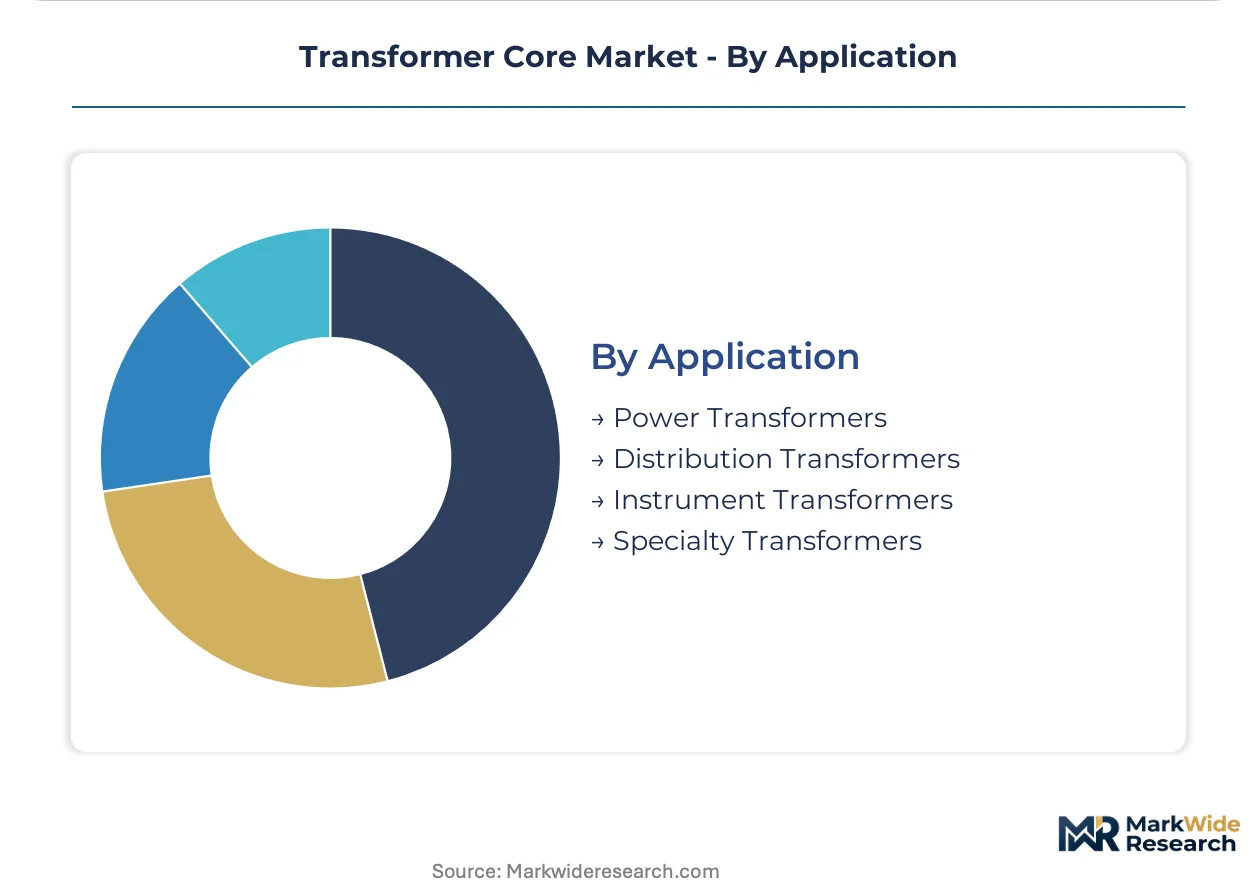
Application:
Load profile characteristics and regulatory compliance thresholds drive specification divergence across end-use categories.
- Distribution Transformers:Sub-10 MVA ratings serving last-mile grid connections prioritize no-load loss minimization. India's CEA mandates amorphous core deployment for new rural network expansions in Gujarat and Tamil Nadu.
- Power Transformers:Generation and transmission infrastructure above 100 MVA demands high flux density with controlled load losses. China's SAMR enforces GB 20052-2020 tiered efficiency standards on grid-connected power transformer cores.
- Instrument Transformers:Current and voltage sensing applications require precise ratio accuracy with minimal phase displacement.
- Specialty Transformers:Furnace, rectifier, and traction applications impose harmonic tolerance and thermal withstand specifications outside standard utility procurement.
Distribution transformers anchor installed base expansion; power transformer replacement cycles are accelerating under efficiency mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates transformer core procurement through state utility modernization programs, while China's efficiency mandates and US data center expansion create parallel demand centers across three continents.
United States
Hyperscale data center operators in Northern Virginia and Phoenix drive specification shifts toward amorphous steel cores. The US Department of Energy enforces minimum efficiency standards through NHTSA-aligned federal rulemaking. Transformer OEMs in Texas and Arizona are qualifying rapid-solidification ribbon supply for 24/7 distribution transformer deployments.
China
State Grid tenders and provincial distribution network upgrades sustain volume demand for grain-oriented silicon steel. SAMR administers GB 20052-2020 tiered efficiency mandates that ratchet maximum core loss allowances downward through 2025. Jiangsu and Shandong province factories are retooling laminations toward thinner-gauge silicon steel and hybrid amorphous-silicon configurations.
India
State utilities in Maharashtra, Gujarat, and Tamil Nadu modernize rural distribution networks with amorphous steel core specifications. The CEA mandates core loss performance standards for grid-connected equipment while BIS certification protocols govern domestic manufacturing. Gujarat-based OEMs deploy automated layering lines for rural electrification contracts under central government directives.
Germany
Offshore wind substation projects in the North Sea require compact, high-flux-density core designs. The EU F-Gas Regulation accelerates replacement cycles for distribution transformers, pulling forward procurement timelines. TenneT and Stedin have centralized technical procurement functions, contracting directly with alloy producers for multi-year lamination supply.
Japan
Advanced material research institutions collaborate with transformer OEMs on nanocrystalline core formulations for high-frequency applications. METI oversees industrial efficiency standards that influence export-oriented manufacturing. Tokyo and Osaka industrial corridors host rapid-solidification technology licensors serving Asian distribution transformer markets.
Transformer Core Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue amorphous alloy specialization and digital-integrated service models. The market structures around three tiers: rapid-solidification specialists commanding premium positioning, integrated steel mills defending volume in grain-oriented silicon steel, and regional fabricators serving distribution transformer OEMs with toroidal and C-type configurations. Strategic moves concentrate on backward integration into ribbon casting capacity and long-term offtake agreements with utility procurement platforms.
Among rapid-solidification specialists, Metglas Inc. and Vilas Transcore Ltd. exemplify divergent archetypes—Metglas anchors proprietary technology licensing while Vilas Transcore occupies toroidal configuration expertise for noise-sensitive urban installations. Fuji Electric Co. Ltd. represents the integrated industrial conglomerate model with manufacturing scale across Asia-Pacific markets. These three entities collectively illustrate how material specialization, geometric configuration mastery, and regional manufacturing footprint define competitive positioning in transformer core supply.
| Leading Market Players |
|---|
| Arteche |
| Coefficient S.R.L. |
| Eilor Magnetic Cores |
| Foshan Juli Electromechanical Co., Ltd. |
| Corefficient S de RL de CV |
| Ferroxcube International Holding B.V. |
| Fuji Electric Co. Ltd. |
| Metglas Inc. |
| Vilas Transcore Ltd. |
| Others |
Supply Flow & Price Mechanics
Backward integration into rapid-solidification ribbon casting anchors pricing power for amorphous steel specialists while compressing margins for grain-oriented silicon steel distributors dependent on Nippon Steel and POSCO mill supply. This integration choice separates OEMs who captive-produce core laminations from those exposed to iron ore and nickel input volatility.
Pricing Analysis
Volume concentrates in standard-efficiency grain-oriented silicon steel cores where pricing stratifies across premium, standard, and economy tiers based on gauge thickness and BIS certification grade. Amorphous steel cores command 40-60% raw material premiums but deliver lifecycle cost advantages through no-load loss reduction. Cost compression in conventional laminations is intensifying because Chinese OEMs are qualifying thinner-gauge silicon steel under GB 20052-2020 mandates. State utilities in India exhibit highest price sensitivity, while data center operators in Northern Virginia prioritize efficiency over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Metglas Inc.'s proprietary rapid-solidification capacity for amorphous metal ribbon, constraining alternative supplier qualification for distribution transformer OEMs. Manufacturing concentrates in China, Japan, and the United States for grain-oriented silicon steel, while amorphous alloy casting draws from limited rapid-solidification licensees in Japan and the United States. Supply chain risk centers on iron ore price volatility from Australian and Brazilian mining output. Distribution runs through long-term offtake agreements with European utilities bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The transformer core market is executing a technology-transition phase as amorphous steel displaces conventional grain-oriented silicon steel in distribution applications where no-load losses dominate lifecycle economics.
For Market Incumbents: Deploy certification investment as the primary lever to defend positioning. Accelerate BIS and GB standard compliance for core loss performance to maintain grid-connection eligibility in India and China. Pursue backward integration into thinner-gauge silicon steel rolling capacity or rapid-solidification ribbon casting to reduce exposure to Nippon Steel and POSCO pricing power. Counter the threat from amorphous specialists by qualifying hybrid amorphous-silicon configurations. For New Entrants and Emerging Players: Data center operators represent an underserved buyer archetype willing to specify premium amorphous cores for 24/7 operations. Target rural electrification mandates in Maharashtra and Gujarat where CEA directives concentrate procurement volume. Penetrate through direct contracting with state utilities rather than traditional OEM channels, leveraging PLI scheme subsidies for domestic amorphous production scale-up. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated steel mills seeking rapid-solidification technology. Long-term viability favors specialists with captive ribbon casting capacity and utility offtake agreements. The signal to watch is qualification timelines for alternative amorphous suppliers as Metglas licensing expands to Asian manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rapid-Solidification Casting | Captive amorphous ribbon production reduces single-source dependency on Metglas Inc. licensing. |
| GB 20052-2020 Compliance Certification | Chinese SAMR mandates tiered core loss reductions through 2025 for grid-connected equipment eligibility. |
| Direct Utility offtake Agreements | TenneT and Stedin centralized procurement functions bypass traditional distributor networks in Europe. |
| PLI-Subsidized Domestic Manufacturing | India's production-linked incentive framework enables cost-competitive amorphous core positioning against imports. |
| Digital Twin Integration Development | IoT sensor convergence with core thermal modeling enables predictive maintenance service revenue unbundling. |
Methodological Framework
Multi-period observation of transformer core procurement volumes, efficiency mandate adoption timelines, and alloy substitution rates anchored the trend analysis, supplemented by interviews with transformer OEM procurement directors, state utility planning officers, rapid-solidification technology licensors, and distribution network engineers. Secondary validation drew from EIA transformer efficiency filings, Nippon Steel and POSCO technical disclosures, BIS certification registries, and CEA rural electrification directives. Bottom-up core demand modeling triangulated against top-down grid infrastructure investment forecasts.
Segment-weighting applied material type, core geometry, and application voltage class as primary dimensions across the projection horizon. CAGRs derived from utility capital expenditure trajectories, data center load growth projections, and regulatory compliance deadline clustering. Industry-specific inputs included GB standard tiered implementation schedules, PLI scheme disbursement patterns, and offshore wind substation transformer specifications.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to amorphous metal supply expansion, iron ore price volatility, and divergence in regional efficiency test methodologies. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
India Power Transformer Market
Transformers
Latin America Transformer Market
Transformers
Saudi Arabia Transformer Market
Transformers
North America Power Transformer Market
Transformers
Green Transformer Market
Transformers
Liquid-Immersed Transformers Market
Transformers
Asia Pacific Smart Transformers Market
Transformers
Oil Immersed Transformer and Dry Type Transformer Market
Transformers
United States Dry-Type Transformer Market
Transformers
Transformer Bobbin Market
Transformers
North America Dry Type Transformer Market
Transformers
Current Transformer Market
Transformers
Asia-Pacific Transformer Market
Transformers
Liquid Filled Transformer Market
Transformers
Transformer Oil Market
Transformers
Middle East Distribution Transformer Market