
 Green Power Transformers Market | 2026-2036
Green Power Transformers Market Size, Share, and Industry Trends Forecast 2026-2036
Green Power Transformers Market Foresight
European transformer foundry capacity is shifting toward biodegradable ester fluids and nitrogen-based insulation systems. Schneider Electric leverages its European manufacturing base to dominate eco-friendly liquid-filled designs. Hitachi Energy anchors its position through advanced cooling R&D for offshore wind applications. Siemens Energy competes with integrated smart grid diagnostics embedded across utility-scale deployments.
Green power transformers are electromagnetic devices that transfer electrical energy between circuits through electromagnetic induction, typically operating at voltages from 11 kV to 765 kV with biodegradable or low-toxicity insulating media replacing mineral oil. These units enable grid integration of variable renewable generation while limiting environmental contamination risks from leaks or end-of-life disposal. Liquid-filled designs retain the largest installed base among product types, though dry-type segments command premium margins in urban substations and indoor commercial installations. Smart grid technology adoption is accelerating fastest among technology categories as utilities demand real-time thermal monitoring and predictive load management.
EPA regulations under the Clean Air Act and F-Gas Regulation in Europe mandate reduced greenhouse gas intensity in transformer insulation and cooling systems. India's BIS efficiency labeling and China's GB standards for distribution transformers further fragment compliance requirements across manufacturing footprints. Stakeholders must monitor evolving material certification timelines and regional carbon border adjustments to align procurement and capacity decisions.
Market Dynamics
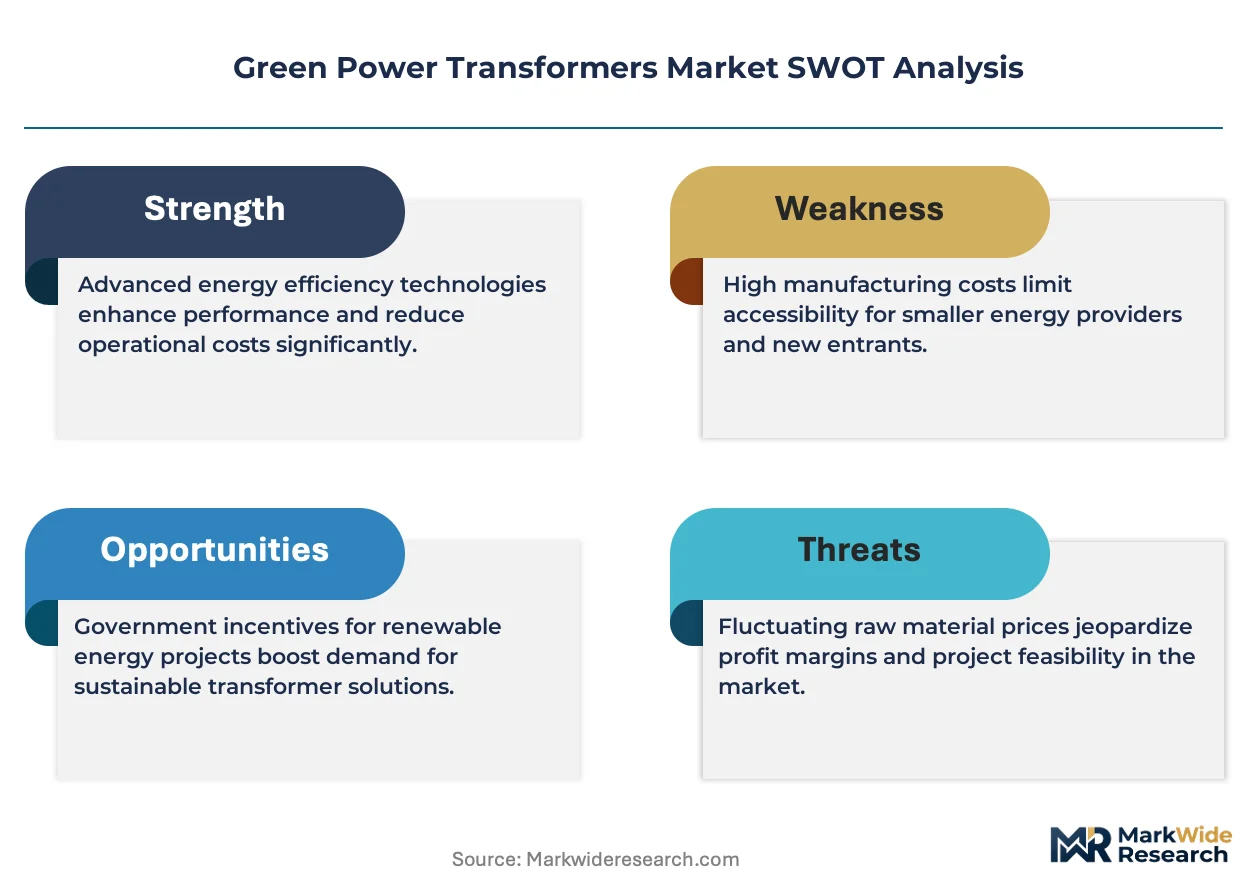
Grid operators face simultaneous pressure from EPA efficiency mandates and EU F-Gas Regulation while managing the technical complexity of integrating variable renewable generation at scale.
Growth Catalysts
- Biodegradable ester fluids:Utilities in Germany and India are accelerating replacement of mineral oil insulation to meet tightening environmental discharge standards and reduce spill liability exposure.
- Offshore wind buildout:North Sea and Atlantic coast projects require specialized liquid-filled units with advanced cooling architectures capable of handling salt-laden, high-humidity operating environments.
- F-Gas Regulation Phase-Down:European transformer procurement now prioritizes nitrogen-based and natural ester alternatives as synthetic fluorinated gas prices escalate and availability contracts.
Market Restraints
- Grain-oriented electrical steel concentration:Cold-rolled core material supply concentrates among Japanese and South Korean producers, exposing transformer OEMs to input cost volatility and extended lead times.
- Copper winding price sensitivity:Dry-type unit margins compress when London Metal Exchange copper benchmarks spike, forcing manufacturers to absorb costs or risk demand destruction in price-sensitive utility segments.
- Technical limitation in high-voltage dry-type:Above 72.5 kV, air-insulated designs face dielectric stress management constraints that preserve liquid-filled dominance in transmission-class applications.
Strategic Opportunities
- India's distribution grid overhaul:State electricity boards under CEA directives are tendering smart transformer replacements for aging 11-33 kV infrastructure, creating volume deployment windows for digital monitoring-integrated suppliers.
- Urban indoor substations:Fire-safety codes in dense German and US metropolitan zones favor dry-type installations where mineral oil leakage risks trigger prohibitive insurance and remediation costs.
- Digital twin convergence:Real-time thermal modeling fused with predictive analytics enables utilities to extend asset life and defer capital-intensive replacements, opening software-enabled service revenue streams.
Industry Challenges
- Specialized winding technician scarcity:Precision coil manufacturing for high-voltage units requires skills concentrated among aging European and Japanese workforces, constraining capacity expansion timelines.
- Multi-standard certification complexity:Simultaneous compliance with EPA efficiency tiers, EU ecodesign requirements, and India's BIS labeling demands parallel testing protocols that extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Power Transformers Market |
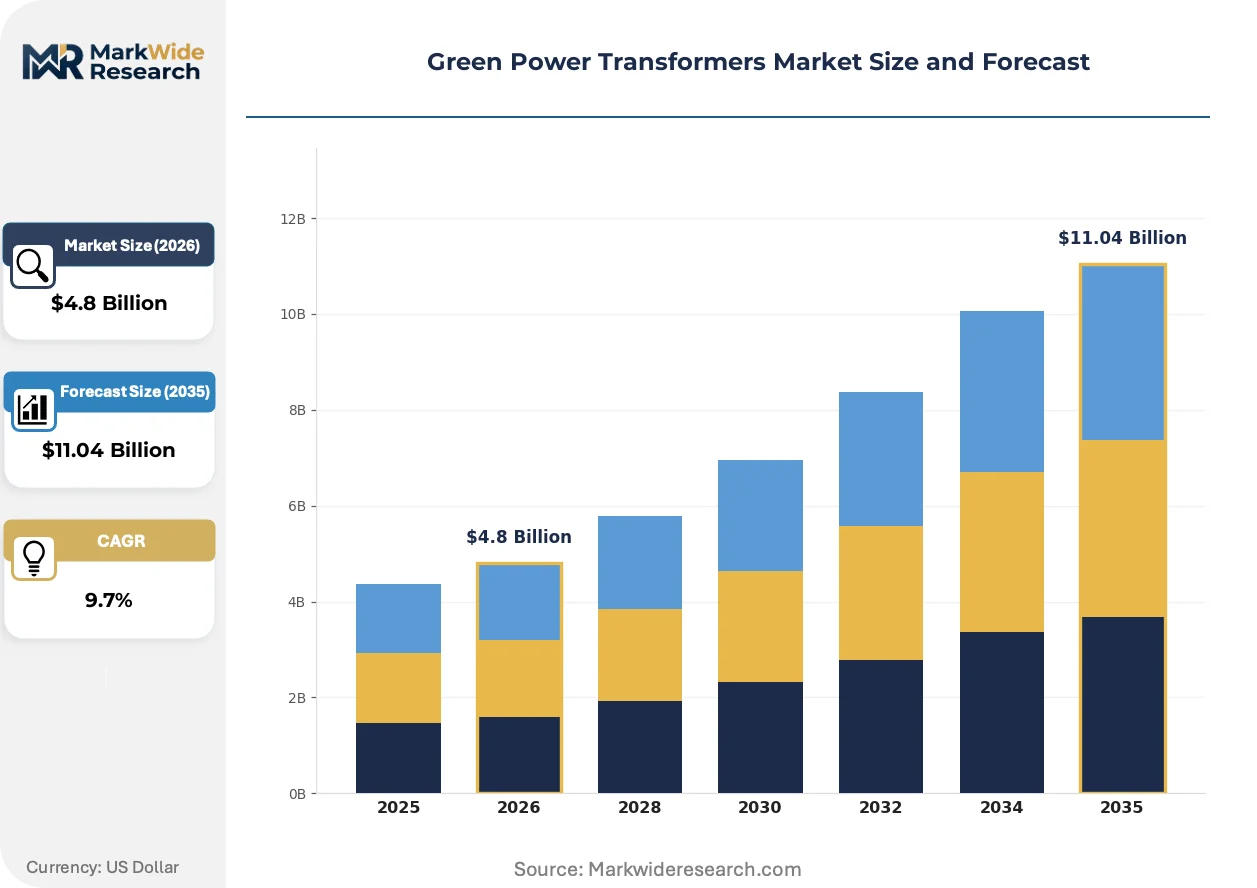
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid-Filled, Gas-Insulated, Dry-Type, Auto-Transformers Application: Renewable Energy Plants, Industrial Applications, Utilities, Commercial Buildings End User: Electric Utilities, Independent Power Producers, Manufacturing, Construction Technology: Smart Grid Technology, Advanced Cooling Systems, Eco-Friendly Insulation, High Voltage Direct Current |
| Companies Covered | Schneider Electric, Mitsubishi Electric, Hitachi Energy, ABB, Toshiba Energy Systems & Solutions, General Electric, Siemens Energy, TBEA, HD Hyundai Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Power Transformers Market Shifts & Advancements
Transformer technology is bifurcating between ultra-efficient liquid-filled designs for bulk power transfer and compact dry-type systems for space-constrained urban environments, with digital instrumentation becoming standard across both categories.
Natural ester fluids derived from vegetable oils are rewriting transformer lifecycle economics. These biodegradable insulants offer superior fire safety and environmental compatibility compared to mineral oil. European utilities are specifying ester-filled units for sensitive watershed installations. The technology is compressing insurance premiums and spill remediation reserves that previously burdened liquid-filled asset ownership.
EPA regulations under the Clean Air Act are tightening permissible greenhouse gas intensity in transformer cooling systems. Manufacturers must reformulate insulation media and redesign thermal management architectures to maintain compliance. US utility procurement specifications now embed these efficiency thresholds as mandatory bid qualifications, filtering supplier pools.
Asset ownership models are fragmenting across utility capital constraints. Power purchase agreement structures and independent power producer arrangements increasingly separate transformer ownership from generation asset control. This unbundling concentrates procurement influence with specialized grid infrastructure funds and energy service companies, particularly visible in German offshore wind and US utility-scale solar deployments.
Green Power Transformers Market Segmentation
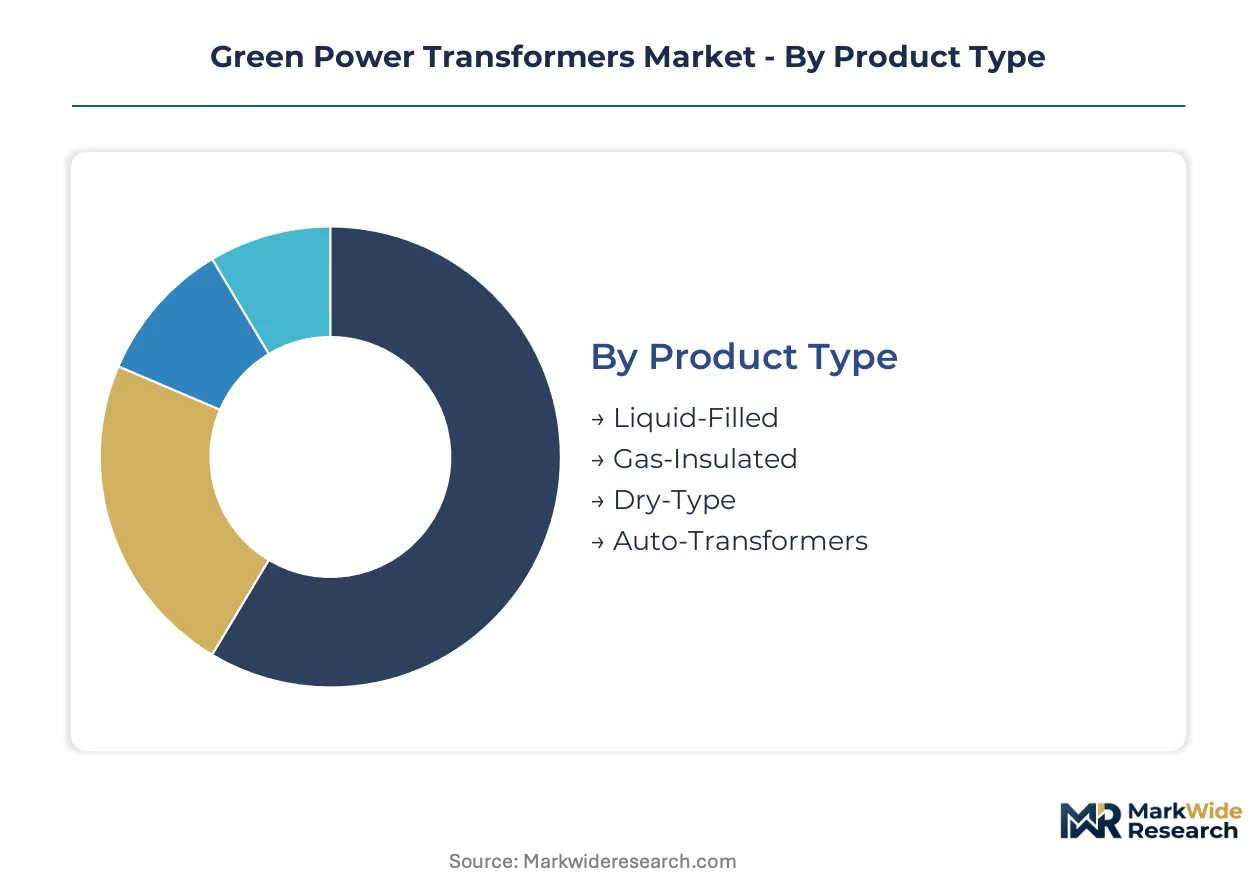
Green power transformer procurement hinges on matching insulation technology to environmental exposure, voltage class, and regulatory jurisdiction. Each segment carries distinct certification burdens that shape supplier qualification timelines and capital deployment patterns.
Product Type:
Liquid-filled units demand EPA spill prevention compliance and EU F-Gas Regulation alignment for synthetic coolant formulations, while dry-type installations trigger fire-safety codes from Germany's KBA-equivalent building authorities and India's BIS electrical safety standards.
- Liquid-Filled:Mineral oil or natural ester fluids circulate through wound core assemblies, providing superior dielectric strength and thermal conductivity for transmission-class voltages. German utilities specify these units for offshore wind collector platforms where salt-laden humidity stresses insulation integrity. EPA efficiency mandates and spill liability exposure accelerate ester fluid substitution across US utility fleets.
- Dry-Type:Cast resin or vacuum-impregnated windings eliminate liquid coolant, enabling indoor installation where fire codes prohibit oil-filled equipment. India's state electricity boards deploy 11-33 kV dry-type units in dense urban substations under CEA directives. Premium margins compress when copper LME benchmarks spike, forcing manufacturers to absorb volatility or risk demand destruction.
- Gas-Insulated:Sulfur hexafluoride or nitrogen-based dielectric media enable compact footprints for space-constrained installations.
- Auto-Transformers:Single-winding designs reduce material intensity for voltage step-up applications in bulk power transfer corridors.
Leading the category by volume: Liquid-Filled. Expanding most quickly: Dry-Type.
Application:
End-use concentration determines thermal cycling profiles and monitoring sophistication, with renewable integration demanding variable load tolerance and urban utilities prioritizing fire containment.
- Renewable Energy Plants:Wind and solar farms require transformers capable of handling intermittent generation ramps and harmonic distortion from inverter-fed sources. North Sea offshore projects specify liquid-filled units with advanced cooling architectures for salt-laden environments. Grid codes in Germany and India mandate reactive power capability and fault ride-through compliance.
- Utilities:Transmission and distribution operators deploy the largest unit volumes across voltage classes from 11 kV to 765 kV. US investor-owned utilities under FERC jurisdiction embed EPA efficiency tiers as mandatory bid qualifications. Smart grid integration accelerates as real-time thermal monitoring enables predictive load management and asset life extension.
- Industrial Applications:Manufacturing facilities demand ruggedized designs for heavy motor starting and process power quality.
- Commercial Buildings:Indoor installations in dense metropolitan zones favor dry-type configurations to satisfy insurance and fire-safety requirements.
Dominating procurement volume: Utilities. Steepest expansion trajectory: Renewable Energy Plants.
End User:
Capital ownership structures fragment procurement influence between rate-regulated utilities and independent developers, reshaping supplier relationships and service contract terms.
- Electric Utilities:Vertically integrated and distribution-only operators maintain captive engineering standards and approved vendor lists spanning decades of operational history. German transmission system operators specify natural ester fluids for watershed-sensitive corridors under EU environmental discharge frameworks. Rate-base regulation in the US creates capital deployment cycles tied to FERC-approved return thresholds.
- Independent Power Producers:Project finance structures separate transformer ownership from generation control, concentrating procurement with specialized grid infrastructure funds. Power purchase agreement tenors drive residual value calculations and maintenance escrow sizing. Offshore wind developments in the North Sea and Atlantic coast anchor specialized liquid-filled demand.
- Manufacturing:Industrial facilities prioritize power quality and short-circuit withstand for heavy process loads.
- Construction:Greenfield developments and infrastructure retrofits generate project-based demand with compressed procurement timelines.
Highest absolute spend: Electric Utilities. Procurement velocity climbing fastest: Independent Power Producers.
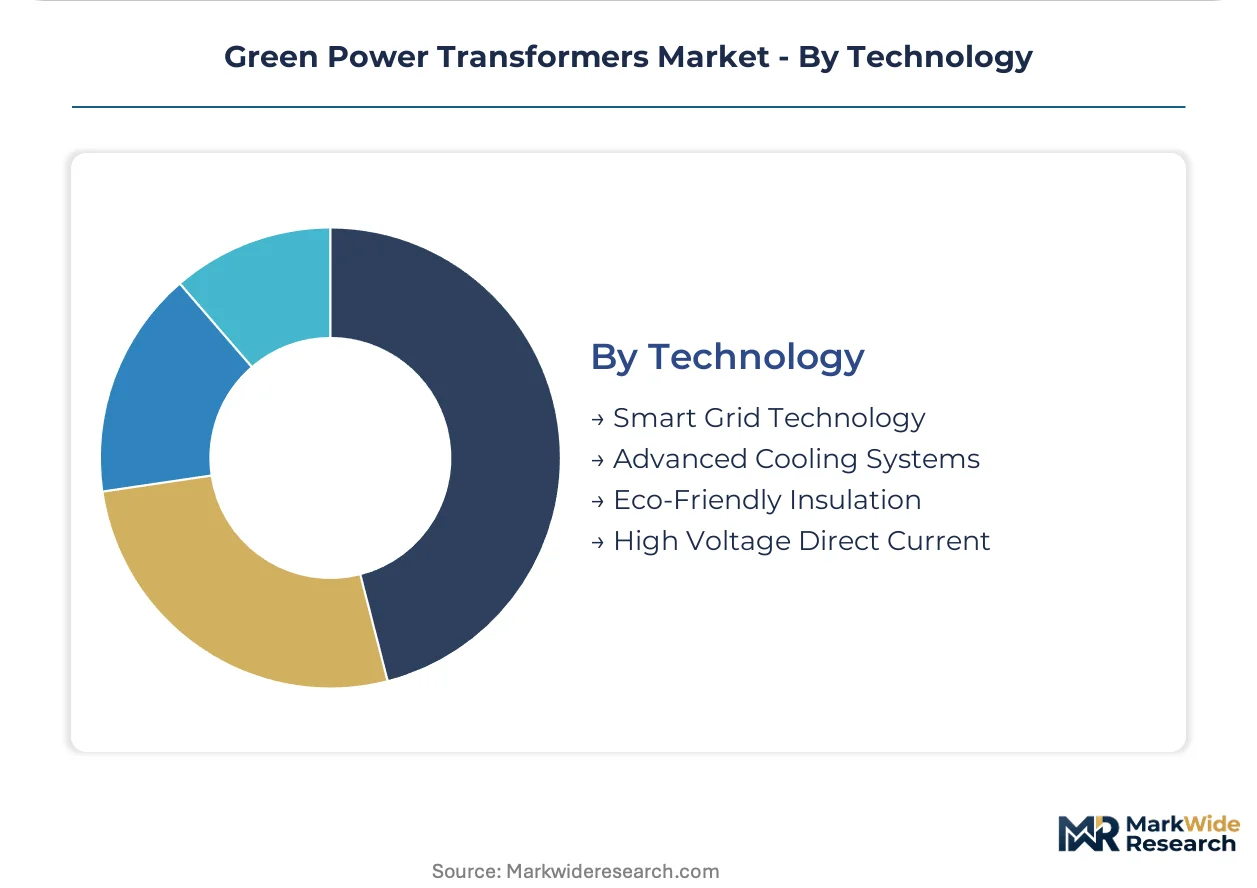
Technology:
Digital instrumentation and material science advances are rewriting lifecycle economics across all product categories, with software-enabled services emerging as a distinct revenue layer.
- Smart Grid Technology:Embedded sensors and communication modules enable real-time thermal monitoring, tap changer position tracking, and dissolved gas analysis. Predictive analytics platforms extend asset life and defer capital-intensive replacements. Indian state electricity boards under CEA mandates tender smart transformer replacements for aging distribution infrastructure.
- Eco-Friendly Insulation:Natural ester fluids derived from vegetable seeds offer biodegradability, fire safety, and moisture tolerance superior to mineral oil. European utilities specify these units for environmentally sensitive installations, compressing insurance premiums and spill remediation reserves.
- Advanced Cooling Systems:Forced oil, directed flow, and hybrid architectures manage thermal stress in high-load-factor applications.
- High Voltage Direct Current:Converter transformers enable long-distance bulk power transfer with reduced line losses for interregional and submarine corridors.
Widest installed base: Smart Grid Technology. Gaining share fastest: Eco-Friendly Insulation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grain-oriented electrical steel from Japanese and South Korean mills anchors transformer manufacturing economics across major demand centers. Renewable buildouts in Germany, India, and the United States concentrate procurement volumes. Regulatory fragmentation between EPA efficiency mandates, EU F-Gas Regulation, and India's BIS labeling shapes regional competitive positioning.
United States
Offshore wind lease auctions along the Atlantic coast drive specialized liquid-filled transformer demand for salt-laden environments. EPA regulations under the Clean Air Act mandate reduced greenhouse gas intensity in cooling systems, filtering supplier pools through mandatory bid qualifications. Texas and California grid operators tender smart transformer replacements for aging transmission corridors.
Germany
North Sea offshore wind collector platforms require advanced cooling architectures capable of withstanding high-humidity operating conditions. EU F-Gas Regulation phase-down prioritizes nitrogen-based and natural ester alternatives as synthetic fluorinated gas prices escalate. Bavarian and North Rhine-Westphalian utilities specify biodegradable ester fluids for watershed-sensitive installations.
India
State electricity boards under CEA directives tender smart transformer replacements for aging 11-33 kV distribution infrastructure. BIS efficiency labeling and GB standards for distribution transformers fragment compliance requirements across manufacturing footprints. Maharashtra and Gujarat concentrate procurement volumes for urban indoor substations where fire-safety codes favor dry-type configurations.
China
Dual carbon goals and GB standards accelerate domestic transformer efficiency upgrades across utility-scale solar and wind integration projects. MIIT directives prioritize smart grid technology adoption with real-time thermal monitoring capabilities. Yangtze River Delta and Shandong Peninsula industrial clusters concentrate manufacturing capacity for high-voltage direct current converter transformers.
Japan
METI efficiency standards and aging grid infrastructure drive replacement demand for eco-friendly insulation systems in dense metropolitan zones. JIS certification requirements and precision coil manufacturing expertise constrain capacity expansion timelines. Kanto and Kansai regions anchor technical workforce concentrations for high-voltage winding specialization.
Green Power Transformers Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital instrumentation and predictive analytics services. The vendor base stratifies across integrated energy conglomerates, specialized transformer manufacturers, and regional fabrication specialists. Three archetypes dominate: European engineering-driven OEMs, Asian scale-focused producers, and digital service integrators. Competitive moves concentrate on strategic partnerships for offshore wind qualification and capacity expansion into biodegradable ester fluid formulations.
Among European engineering-driven OEMs, Siemens Energy and ABB occupy positions exemplifying integrated smart grid diagnostics capabilities. Hitachi Energy anchors the advanced cooling R&D archetype for demanding offshore wind applications. These three represent distinct competitive vectors: utility-scale deployment integration, thermal management innovation, and renewable-specific qualification protocols.
| Leading Market Players |
|---|
| Schneider Electric |
| Mitsubishi Electric |
| Hitachi Energy |
| ABB |
| Toshiba Energy Systems & Solutions |
| General Electric |
| Siemens Energy |
| TBEA |
| HD Hyundai Electric |
| Others |
Supply & Pricing Matrix
Captive production of grain-oriented electrical steel by Japanese and South Korean mills anchors transformer manufacturing economics, concentrating pricing power among core material suppliers while forcing OEMs to absorb volatility or pass through costs to utility buyers. This upstream control shapes contract structures across liquid-filled and dry-type procurement, with long-term offtake agreements increasingly bundling core material reserves with finished unit pricing.
Pricing Analysis
Warranty and predictive maintenance bundling separates premium transformer suppliers from commodity competitors, with extended service contracts now standard for smart grid-integrated units. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and digital instrumentation depth, with EPA efficiency tier compliance commanding material premiums. Cost compression in standard dry-type segments is intensifying because copper LME benchmark volatility squeezes manufacturer margins. Municipal utilities exhibit highest price sensitivity, while offshore wind developers prioritize reliability over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and South Korean producers of grain-oriented electrical steel, which feeds from cold-rolling capacity concentrated in Kawasaki Steel and POSCO mill networks. Copper winding supply draws from Chilean mining output and Chinese smelter capacity, while natural ester fluid production rests on Malaysian and Indonesian palm oil plantations. Tariff exposure on electrical steel imports threatens North American transformer OEM cost structures. Distribution runs through utility-approved vendor lists and EPC contractor procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where multi-standard certification complexity and specialized winding technician scarcity force smaller fabricators toward acquisition or exit. Regulatory compliance burdens favor scaled producers with parallel testing capabilities.
For Market Incumbents: Anchor defensive positioning through backward integration into biodegradable ester fluid formulation and captive grain-oriented electrical steel inventory management. Expand smart grid diagnostics R&D to differentiate against emerging digital service integrators. Prioritize German and Indian offshore wind qualification protocols to lock out late entrants. For New Entrants and Emerging Players: Begin with India's 11-33 kV distribution replacement tender window, where CEA-mandated smart transformer deployment outruns incumbent capacity. Target urban indoor substation dry-type demand in German metropolitan zones where fire-safety codes favor new suppliers with rapid certification timelines. Pursue digital twin software partnerships to bypass capital-intensive manufacturing barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated energy conglomerates seeking offshore wind qualification and ester fluid manufacturing capabilities. Five-to-ten year viability hinges on smart grid technology integration depth and regional certification breadth. Monitor F-Gas Regulation phase-down velocity as inflection indicator for natural ester substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Ester Fluid Capacity Buildout | European utilities under EU F-Gas Regulation mandate natural ester alternatives for watershed-sensitive corridors. |
| Smart Grid Technology Licensing | Indian state electricity boards embed CEA-mandated digital monitoring in distribution transformer tenders. |
| Offshore Wind Qualification Partnership | North Sea and Atlantic coast projects require salt-laden environment certification from specialized suppliers. |
| Backward Integration into Core Steel | Japanese and South Korean mill concentration exposes OEMs to input cost volatility and extended lead times. |
| Predictive Analytics Service Launch | Real-time thermal modeling enables utilities to defer capital-intensive replacements and extend asset life. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with utility planning officers, IPP project developers, EPC contractors, and transformer OEM procurement leads. CIGRE working group publications, EPA Clean Air Act docket records, EU F-Gas Regulation implementation reports, and Indian CEA tender databases provided demand-side validation. Bottom-up unit deployment estimates triangulated against top-down grid investment forecasts.
Data-stream reconciliation across product type, voltage class, application, and regional regulatory framework dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segmented demand modeling incorporating renewable buildout pipelines, utility replacement cycles, and efficiency mandate compliance timelines. Grain-oriented electrical steel price indices and copper LME benchmarks fed material cost assumptions.
Regulatory enforcement delays, renewable project financing disruptions, and core material supply shocks are the dominant revision risks. Forecasts reflect documented assumptions about mandate implementation schedules and technology substitution elasticities. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Transformer Oil Market
Transformers
Gas Insulated Transformer Market
Transformers
High Voltage (35-550 KV) Power Transformer Market
Transformers
Smart Transformer Market
Transformers
Cast Resin Transformers Market
Transformers
Auto Transformer Rectifier Unit (ATRU) Market
Transformers
HVDC Converter Transformers Market
Transformers
Renewable Energy Transformer Market
Transformers
Latin America Transformer Market
Transformers
Transformer Steel Market
Transformers
Phase-Shifting Transformer Market
Transformers
EHV & UHV (above 330KV) Power Transformers Market
Transformers
Single Phase Power Transformer Market
Transformers
Middle-East Smart Transformer Market
Transformers
Electric Vehicle Charging Station Transformer Market
Transformers
Step Up/Down Transformers Market