
 Offshore Drilling Market | 2026-2036
Offshore Drilling Market Size, Share, and Industry Trends Forecast 2026-2036
Offshore Drilling Market Intelligence
The integration of automation and remote operations in drilling control systems is tilting the competitive landscape toward technology-forward contractors. Transocean leverages its fleet of high-specification deepwater rigs to secure long-term contracts for complex projects. Valaris sustains its market position through a diverse portfolio that includes both jack-ups and floating rigs. Seadrill specializes in harsh-environment drilling, commanding premium day rates for its advanced assets.
Offshore drilling involves the mechanical process of creating boreholes in the seabed to explore for and extract hydrocarbons. This process utilizes specialized mobile offshore drilling units capable of operating in water depths exceeding 10,000 feet and drilling to total depths of over 40,000 feet. Drillships and semi-submersible rigs dominate the high-margin deepwater and ultra-deepwater segments, while jack-up rigs remain the workhorses for shallow-water development wells. Exploration wells, though riskier, offer higher potential rewards and drive the need for the most advanced drilling platforms.
Operational standards are governed by a complex web of national and international bodies, including the U.S. Environmental Protection Agency (EPA), Norway's Petroleum Safety Authority, and guidelines influenced by the EU Green Deal. These regulations mandate stringent environmental impact assessments and well-control protocols, directly influencing rig design and operational costs. Contractors must now decide whether to invest in upgrading existing assets for stricter emissions compliance or to focus on newbuilds designed for a low-carbon operational future.
Market Dynamics
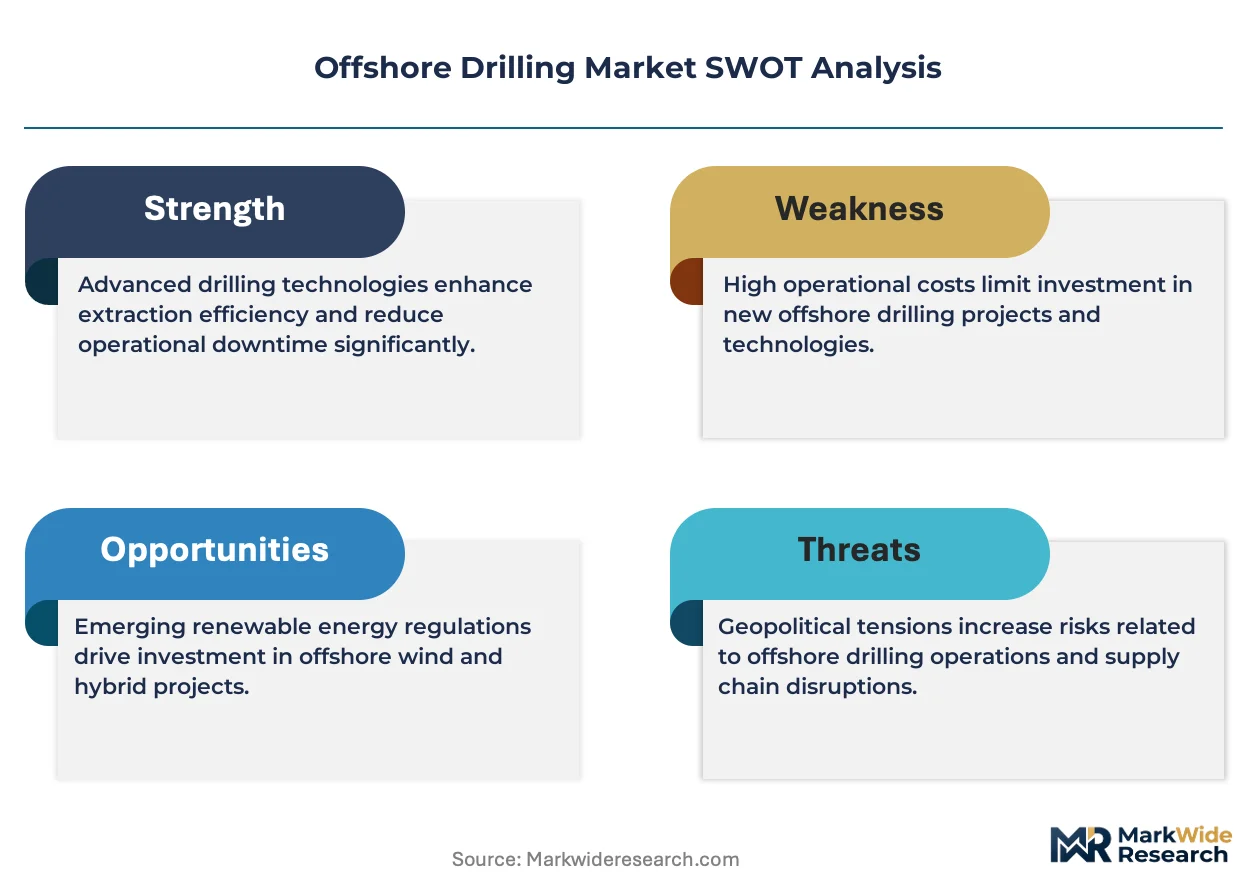
The central dynamic in the offshore drilling market is the tension between long-cycle investment decisions required for deepwater projects and the increasing pressure for capital discipline driven by energy transition uncertainties and shareholder return expectations.
Growth Catalysts
- National Oil Company Activity:Sustained project sanctioning by National Oil Companies, particularly in Brazil and the Middle East, continues to underpin demand for high-specification jack-ups and floating rigs to support national energy security and production targets.
- Advanced Drilling Technologies:The deployment of extended reach drilling and managed pressure drilling systems enables access to previously inaccessible or uneconomical hydrocarbon reservoirs, expanding the viable scope of offshore exploration and development projects.
- Significant Resource Discoveries:Major oil and gas finds in emerging deepwater basins, notably offshore Guyana and Namibia, are creating new multi-year development campaigns that require a sustained presence of advanced drillships and semi-submersibles.
Market Restraints
- High Capital Intensity:The immense cost of constructing and mobilizing ultra-deepwater rigs, coupled with long project payback periods, creates a significant barrier to entry and constrains fleet expansion, especially amid price volatility for key inputs like specialized steel.
- Stringent Regulatory Hurdles:A complex web of environmental and safety regulations, such as those from the U.S. Environmental Protection Agency and Norway's Petroleum Safety Authority, imposes substantial compliance costs and can delay project approvals.
- Energy Transition Headwinds:Long-term policy shifts toward decarbonization, including frameworks influenced by the EU Green Deal, create investor uncertainty and can deter financing for long-cycle fossil fuel projects, favoring shorter-cycle or renewable energy investments.
Strategic Opportunities
- Decommissioning Services:The growing portfolio of aging offshore platforms and subsea wells creates a substantial market for rig-based plug and abandonment (P&A) services, offering a counter-cyclical revenue stream for contractors with older, less competitive assets.
- Digital Twin Integration:Combining real-time drilling data with digital twin models of subsea equipment and reservoirs offers opportunities to optimize performance, predict maintenance needs, and reduce non-productive time, creating a new value proposition for technology-forward contractors.
- Frontier Basin Exploration:Under-explored regions in the Eastern Mediterranean and offshore Africa present opportunities for high-impact exploration campaigns, driven by regional energy demand and the potential for world-class discoveries that can attract supermajor investment.
Industry Challenges
- Specialized Talent Scarcity:The industry faces a critical shortage of experienced personnel, including subsea engineers and dynamic positioning operators, as an aging workforce retires and fewer new entrants join, drawn instead to the renewable energy or technology sectors.
- Asset Modernization Costs:Contractors must decide between expensive upgrades to existing rigs to meet new emissions standards and operational efficiencies, or committing even larger capital sums for newbuilds designed for a low-carbon future.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Offshore Drilling Market |
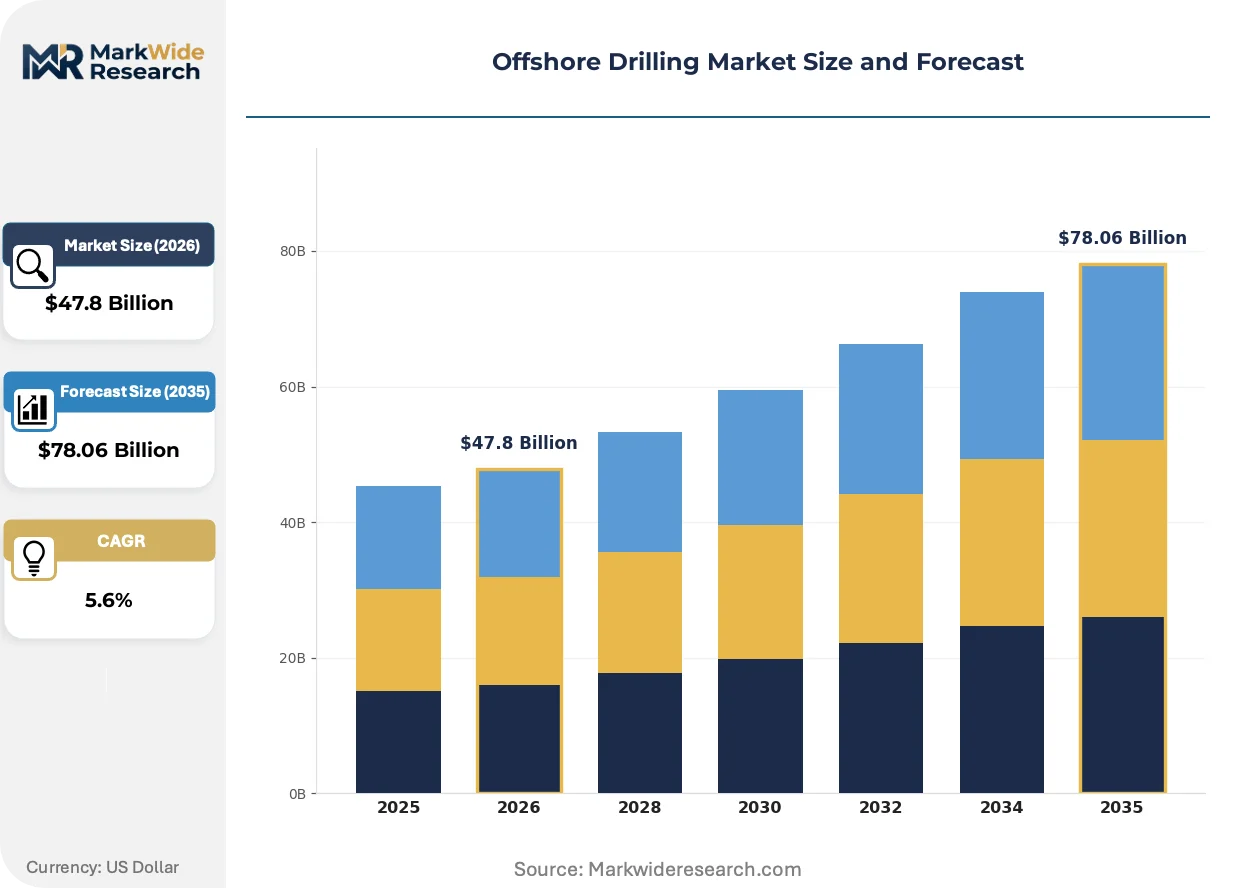
| Market Size in 2026 | $47.8 Billion |
| Market Size in 2035 | $78.06 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drilling Platform Type: Jack-Up Rig, Semi-Submersible Rig, Drillship, Platform Rig, Tender Assisted Rig Drilling Technique: Vertical Drilling, Directional Drilling, Horizontal Drilling, Extended Reach Drilling, Multilateral Drilling End User: Exploration Firms, National Oil Companies, Independent Operators, Drilling Contractors, Service Providers Well Type: Development Well, Exploration Well, Injection Well, Production Well, Observation Well |
| Companies Covered | Transocean Ltd, Valaris Ltd, Seadrill Ltd, Noble Corporation plc, Shelf Drilling Ltd, COSL, Borr Drilling, Diamond Offshore, Stena Drilling, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Offshore Drilling Market Strategic Shifts & Innovations
The industry's evolution is defined by a dual pursuit of enhanced operational efficiency and improved environmental performance. Digitalization and automation are being implemented to reduce costs and improve safety, while new hardware technologies address emissions reduction mandates.
Managed Pressure Drilling (MPD) systems are a key technological evolution in well construction. These closed-loop systems allow for more precise control of the wellbore pressure profile compared to conventional methods. Operators of complex deepwater and high-pressure, high-temperature (HPHT) wells are the primary adopters. The underlying philosophy of well control is migrating from a reactive approach to proactive, real-time pressure management, enabling safer drilling in challenging geological formations.
Stringent emissions regulations are altering fleet composition and investment priorities. Rules set by bodies like Norway's Petroleum Safety Authority and emissions-related guidelines influenced by the EU Green Deal are compelling rig owners to document and reduce their carbon footprint. This directly impacts operational costs and necessitates investment in hybrid power systems, battery storage, and advanced engine management. The North Sea market is most affected, where a rig's environmental credentials are a critical factor in contract awards.
A notable behavioral shift is occurring in how drilling services are contracted, moving away from simple day-rate agreements. Operators are increasingly adopting performance-based contracts that tie a contractor's financial incentives to specific key performance indicators, such as drilling speed or uptime. This model disrupts the traditional transactional relationship by creating a risk-and-reward sharing framework. This trend is most visible in large-scale development projects in the U.S. Gulf of Mexico and Brazil.
Offshore Drilling Market Segmentation
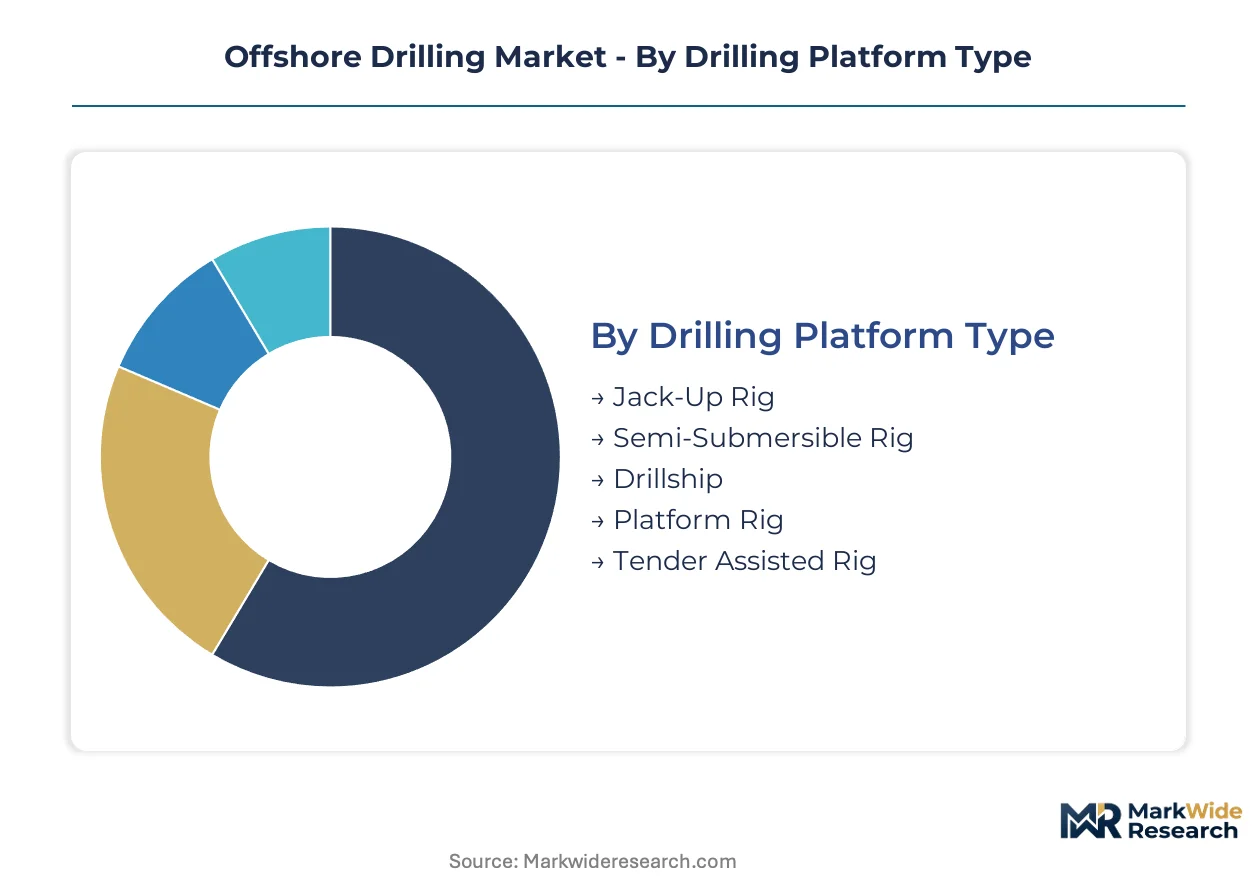
The segmentation of the offshore drilling market reflects the diverse operational environments, technological requirements, and strategic objectives of industry participants. Understanding these distinctions is crucial for assessing market dynamics, investment priorities, and the competitive landscape for specialized drilling assets.
Drilling Platform Type:
The operational cycle times for offshore drilling platforms vary significantly, influencing project duration and asset utilization across different water depths.
- Drillship:These dynamically positioned vessels are engineered for ultra-deepwater operations, capable of drilling in water depths exceeding 10,000 feet with high mobility. Demand concentrates in frontier basins like offshore Guyana and Brazil due to significant recent discoveries requiring advanced drilling capabilities.
- Semi-Submersible Rig:Characterized by high stability in harsh environments, semi-submersible rigs are suitable for deepwater and ultra-deepwater drilling where sea conditions can be challenging. Operators in the North Sea and the U.S. Gulf of Mexico utilize these rigs for complex well designs and severe weather conditions.
- Jack-Up Rig:Jack-up rigs are mobile, self-elevating platforms primarily used in shallow to moderate water depths, extending their legs to the seabed for stability.
- Platform Rig:These rigs are permanently installed on fixed production platforms, designed for long-term development drilling and workover operations over a producing field.
- Tender Assisted Rig:Tender assisted rigs provide support services to fixed platforms, including drilling equipment and personnel, offering a cost-effective solution for specific development projects.
Jack-Up Rigs anchor the volume base while Drillships gain share at the steepest rate.
Drilling Technique:
The array of drilling techniques reflects the increasing complexity and geological challenges encountered in hydrocarbon extraction.
- Extended Reach Drilling:This advanced technique creates wells with exceptionally long horizontal or deviated sections from a single surface location, accessing remote or difficult-to-reach reservoirs. Operators in the North Sea and Middle East utilize this for optimizing reservoir drainage and reducing surface footprint.
- Horizontal Drilling:Horizontal drilling involves turning the wellbore to run parallel to the reservoir bed, maximizing contact with the hydrocarbon-bearing formation to enhance production rates. Major projects in the U.S. Gulf of Mexico and Brazil employ this technique for improved recovery.
- Vertical Drilling:Vertical drilling is the most basic method, where the wellbore is drilled straight down into the earth to access conventional reservoirs.
- Directional Drilling:This technique allows for steering the wellbore in a specific direction to hit multiple targets from a single drilling location, optimizing field development.
- Multilateral Drilling:Multilateral drilling involves creating multiple branches or laterals from a single main wellbore, significantly increasing reservoir exposure and production potential.
Advanced drilling techniques are enabling access to previously uneconomical reservoirs, driving technological innovation.
End User:
End user categories delineate the strategic objectives and investment profiles driving offshore drilling activity globally.
- National Oil Companies:These state-owned entities prioritize national energy security and long-term production targets, often sanctioning large-scale, long-cycle deepwater projects. Activity from National Oil Companies in Brazil and the Middle East continues to underpin demand for high-specification rigs.
- Exploration Firms:Exploration firms are typically risk-tolerant entities focused on discovering new hydrocarbon reserves, often in frontier basins with high-impact potential. Companies active in offshore Guyana and Namibia drive demand for the most advanced drilling platforms for high-risk, high-reward campaigns.
- Independent Operators:Independent operators are generally smaller companies focused on specific regions or niche projects, often engaging in infill drilling or smaller-scale development.
- Drilling Contractors:These companies own and operate the drilling rigs, providing specialized services and personnel to various end-user clients.
- Service Providers:Service providers offer a wide range of specialized equipment, technologies, and technical personnel, supporting various aspects of drilling operations.
National Oil Companies provide a stable demand base, while Exploration Firms drive the need for cutting-edge technology.
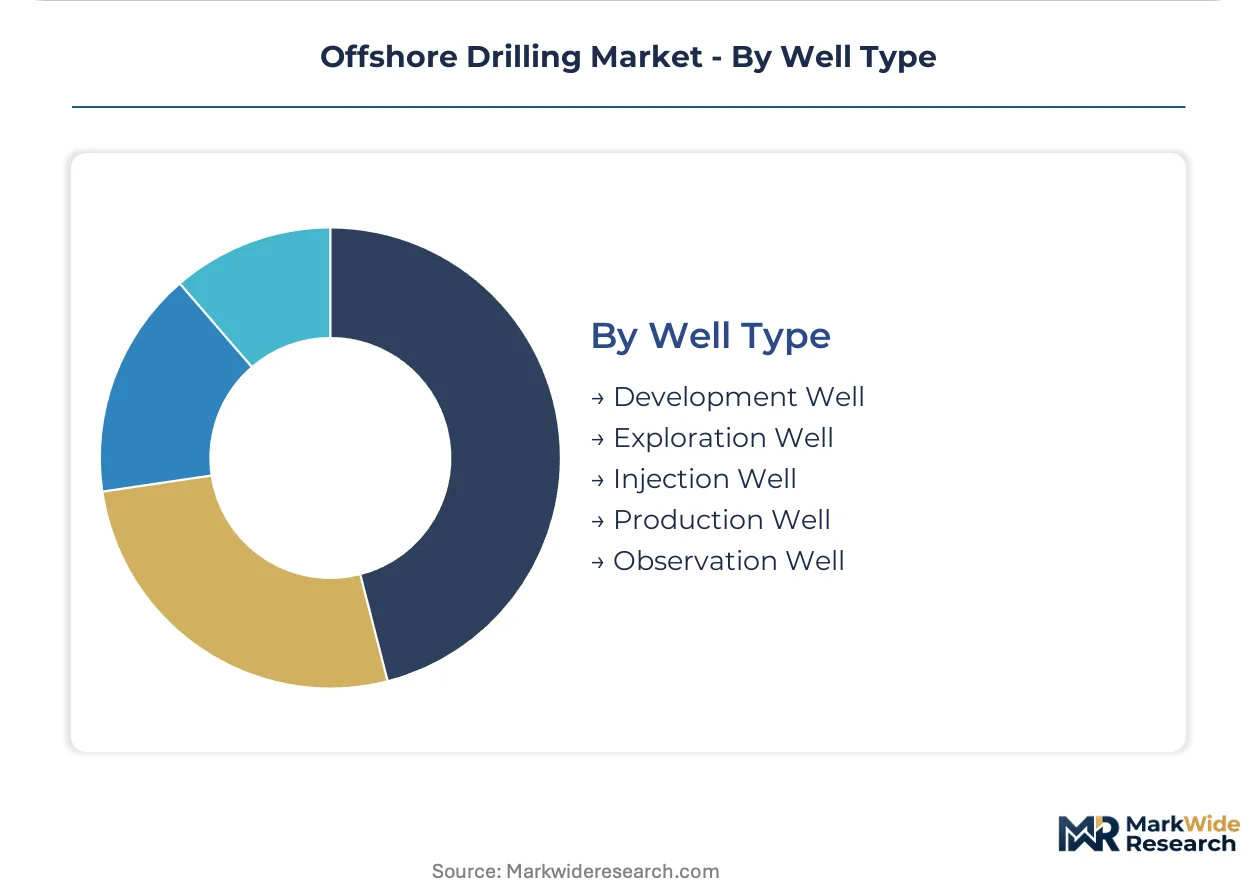
Well Type:
Each well type serves a distinct purpose within the hydrocarbon lifecycle, from initial discovery to sustained production and reservoir management.
- Exploration Well:Drilled to determine the presence, quantity, and quality of hydrocarbons in a previously unproven area or formation, these wells carry higher geological risk. Frontier basins in Namibia and the Eastern Mediterranean rely on exploration wells to define new resource potential.
- Development Well:Drilled within a proven field to extract hydrocarbons, these wells focus on optimizing reservoir drainage and maximizing production over the field's lifespan. Mature basins like the U.S. Gulf of Mexico and the North Sea see continuous development well activity.
- Production Well:A production well is specifically designed to bring hydrocarbons from the reservoir to the surface for processing and sale.
- Injection Well:These wells are used to inject fluids, such as water, gas, or chemicals, into the reservoir to maintain pressure or enhance hydrocarbon recovery.
- Observation Well:Observation wells are drilled to monitor reservoir behavior, including pressure changes, fluid movement, and temperature, providing critical data for reservoir management.
Exploration wells define future resource potential, while development wells ensure efficient hydrocarbon extraction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global offshore drilling market balances energy independence goals with the need to secure hydrocarbon supplies for domestic consumption. Countries with significant offshore reserves often aim to reduce import reliance, driving sustained investment in exploration and production. This dynamic directly influences regional activity levels and project sanctioning for advanced drilling assets.
Brazil
Brazil's pre-salt discoveries continue to fuel substantial demand for ultra-deepwater drilling, driven by Petrobras' long-term production targets. The country's ANP (National Agency of Petroleum, Natural Gas and Biofuels) oversees stringent environmental and operational standards for offshore projects, impacting rig specifications. The state of Rio de Janeiro concentrates significant offshore support infrastructure, facilitating complex deepwater development campaigns.
United States
Deepwater activity in the U.S. Gulf of Mexico remains a cornerstone of domestic energy production, attracting significant investment in advanced drilling platforms. The U.S. Environmental Protection Agency (EPA) and Bureau of Ocean Energy Management (BOEM) impose rigorous safety and environmental compliance costs. Houston, Texas, serves as a global hub for offshore technology and services, supporting extensive research and development in drilling innovation.
Norway
Norway's demanding North Sea environment drives demand for specialized harsh-environment rigs and advanced drilling technologies. The Petroleum Safety Authority (PSA) enforces some of the world's strictest safety and emissions regulations, influencing rig design and operations. Stavanger acts as a key operational center for offshore activity, hosting numerous drilling contractors and service providers focused on efficiency.
Guyana
Recent world-class discoveries offshore Guyana have created a multi-year development pipeline, attracting supermajor investment and advanced drillships. The Guyanese government is developing its regulatory framework to manage rapid oil and gas expansion, including local content requirements. Georgetown is experiencing rapid infrastructure development to support the burgeoning offshore industry, becoming a logistical hub for deepwater projects.
Saudi Arabia
Saudi Aramco's strategic focus on maintaining production capacity underpins consistent demand for high-specification jack-up rigs in the Arabian Gulf. The Ministry of Energy dictates long-term production strategies and environmental compliance for offshore operations. The Eastern Province, particularly around Dhahran, serves as the operational heart for Saudi Arabia's vast oil and gas sector, including offshore development.
Offshore Drilling Market Key Industry Players
On the supply side, the offshore drilling industry is characterized by a tiered structure, with a few large global players dominating the deepwater and ultra-deepwater segments. Mid-sized contractors often specialize in specific rig types or regional markets. Strategic archetypes include high-specification deepwater specialists, diverse fleet operators, and harsh-environment experts. Competitive moves frequently involve fleet modernization and securing long-term contracts.
Specialists in high-specification deepwater drilling include Transocean Ltd, which maintains a fleet of advanced rigs for complex projects. Valaris Ltd occupies a position as a diverse fleet operator, sustaining its market presence with both jack-ups and floating rigs. Seadrill Ltd exemplifies a contractor focused on harsh-environment operations, commanding premium day rates for its advanced assets.
| Leading Market Players |
|---|
| Transocean Ltd |
| Valaris Ltd |
| Seadrill Ltd |
| Noble Corporation plc |
| Shelf Drilling Ltd |
| COSL |
| Borr Drilling |
| Diamond Offshore |
| Stena Drilling |
| Others |
Cost & Logistics Intelligence
Houston's extensive offshore technology ecosystem and deepwater expertise directly influence pricing power for advanced drilling services globally. This concentration of specialized capacity and talent affects the cost structure for complex projects.
Pricing Analysis
The technology-generation pricing gap differentiates day rates significantly between advanced and conventional rigs. Performance-based contracts are increasingly common, tying contractor incentives to specific key performance indicators like drilling speed. Price differentiation stems from rig specifications, particularly for high-specification deepwater and harsh-environment assets. Pricing pressure stems from the high capital intensity of newbuilds and the cost of upgrading existing assets for emissions compliance. National Oil Companies and supermajors show lower price sensitivity for advanced drilling platforms.
Supply Chain Analysis
Extended payment terms and specialized supply-chain finance facilities are critical for managing the immense capital intensity of offshore drilling. Geographic supply for specialized components concentrates in hubs like Houston, Stavanger, and Rio de Janeiro. Raw material dependencies include specialized steel for rig construction and high-grade subsea equipment. Single-source vulnerability for advanced drilling components presents a structural supply chain risk. Distribution runs through a tiered structure of drilling contractors providing specialized services and personnel to end-user clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The offshore drilling market presents a fragmentation opportunity, driven by the increasing demand for specialized decommissioning services. This creates new niches for focused contractors.
For Market Incumbents: Harden core capabilities in deepwater and harsh-environment drilling to counter energy transition uncertainties. Invest in fleet modernization, focusing on hybrid power systems and advanced engine management for emissions compliance. Secure long-term performance-based contracts for complex projects to mitigate revenue volatility. Leverage digital twin integration to optimize operational efficiency and predict maintenance needs against talent scarcity.
For New Entrants and Emerging Players: Under-explored regions in the Eastern Mediterranean and offshore Africa represent significant white-space targets. Focus on providing specialized plug and abandonment (P&A) services for aging offshore platforms, offering a counter-cyclical revenue stream. A go-to-market angle emphasizing advanced drilling technologies like Managed Pressure Drilling can attract operators seeking enhanced safety and efficiency in challenging formations. Target niche markets requiring specialized environmental compliance solutions.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors technology-forward contractors with advanced fleet assets and strong environmental credentials. Long-term viability rests on securing exposure to deepwater basins with sustained National Oil Company activity and significant resource discoveries. Acquisition targets should include specialists in harsh-environment drilling or firms with proven digital twin integration capabilities. The signal to watch is the sanctioning of multi-year development campaigns in emerging deepwater basins.
| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Modernization | Enhances compliance with stringent emissions regulations and improves operational efficiency for existing assets. |
| Digital Twin Integration | Optimizes drilling performance, predicts maintenance needs, and reduces non-productive time for complex operations. |
| Target Frontier Basins | Capitalizes on high-impact exploration potential and world-class discoveries in underexplored regions. |
| Invest in Decommissioning Services | Secures counter-cyclical revenue streams from aging offshore infrastructure and strengthens market diversification. |
| Talent Development Programs | Mitigates specialized personnel scarcity and ensures operational continuity for advanced drilling platforms. |
Research Approach
Desk research of industry reports, government publications from bodies like the ANP and BOEM, and company financial filings preceded structured interviews with drilling contractors, National Oil Companies, exploration firms, and regulatory specialists. This approach combined bottom-up and top-down triangulation for robust data validation.
Assumptions regarding market growth drivers, such as new project sanctions and major resource discoveries, were held fixed across the analysis window, while others like regulatory compliance costs were varied. The analytical framework modeled segmentation dimensions including drilling platform type, drilling technique, end user, well type, and water depth. Compound annual growth rates were derived from projected market drivers and historical performance data.
The forecast holds incumbent behavior within observed patterns; aggressive moves by supermajors or technology-forward contractors would shift outcomes. Geopolitical stability, commodity price volatility, and unforeseen technological breakthroughs represent key risk factors. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
India Oil and Gas Upstream Market
Offshore Oil and Gas
Africa Oil and Gas Downstream Market
Offshore Oil and Gas
LNG Satellite Station Market
Offshore Oil and Gas
Offshore Rental Equipment Market
Offshore Oil and Gas
Gabon Oil and Gas Downstream Market
Offshore Oil and Gas
Denmark Oil and Gas Market
Offshore Oil and Gas
Argentina Oil and Gas Downstream Market
Offshore Oil and Gas
Canada Oil and Gas Downstream Market
Offshore Oil and Gas
Gulf of Mexico Subsea Systems Market
Offshore Oil and Gas
Marine Scrubber Market
Offshore Oil and Gas
Netherlands Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Nigeria Oil and Gas Downstream Market
Offshore Oil and Gas
South America Offshore Seismic Survey Market
Offshore Oil and Gas
Brazil Offshore Energy Market
Offshore Oil and Gas
Offshore Contract Drilling Market
Offshore Oil and Gas
Egypt Oil and Gas Upstream Market