
 India Oil and Gas Upstream Market | 2026-2036
India Oil and Gas Upstream Market Size, Share, and Industry Trends Forecast 2026-2036
India Oil and Gas Upstream Market Foresight
Production-sharing contract structures with escalating government-take provisions is hardening the commercial architecture of Indian exploration blocks. Oil and Natural Gas Corporation anchors domestic output through its commanding position in the Mumbai High and KG-DWN-98/2 deepwater developments. Reliance Industries Limited leverages its integrated refining-petrochemical complex to monetize KG-D6 gas through captive downstream channels. Vedanta Ltd (Cairn) dominates the onshore Rajasthan block with its Mangala processing terminal and pipeline infrastructure.
India oil and gas upstream encompasses the search, drilling, and extraction of hydrocarbons from subsurface reservoirs, with crude oil API gravities ranging from light sweet to heavy sour grades and natural gas requiring dehydration and sweetening before pipeline entry. The primary purpose is to supply feedstock to refineries, fertilizer plants, and city gas distribution networks. Offshore exploration leads capital deployment, particularly in ultradeepwater blocks where subsea tieback systems reduce surface facility costs. Enhanced Oil Recovery commands growing technology spend as mature fields in Assam and Gujarat face natural decline rates exceeding five percent annually. Conventional oil retains the largest resource base, though tight oil appraisal in the Vindhyan and Gondwana basins attracts niche service contracts.
The Directorate General of Hydrocarbons enforces production norms and field development plan approvals, while the Petroleum and Natural Gas Regulatory Board governs pipeline tariffs and city gas infrastructure standards. Environmental clearances from the Ministry of Environment, Forest and Climate Change constrain drilling timelines in ecologically sensitive zones including the Gulf of Mannar. The Open Acreage Licensing Policy and subsequent HELP regime shift fiscal terms toward revenue sharing, altering investor return profiles. Stakeholders must weigh exploration commitments against the compressed appraisal windows that new bidding rounds impose.
Market Dynamics
The Open Acreage Licensing Policy and HELP regime are compressing exploration timelines while shifting fiscal terms toward revenue sharing, forcing operators to front-load seismic surveys and accelerate drilling commitments to meet compressed appraisal windows.
Growth Catalysts
- City Gas Distribution Mandate:The Petroleum and Natural Gas Regulatory Board's expansion of CGD networks to 300+ districts is pulling natural gas offtake from Krishna-Godavari and Cambay Basin fields.
- Fertilizer Subsidy Linkage:Urea manufacturers must use domestic gas to qualify for import parity pricing, locking in baseload demand from Hazira and Dahej complexes.
- Enhanced Oil Recovery Incentives:Chemical flooding and CO2 injection technologies are unlocking stranded reserves in Assam's mature Barmer-Sanchori fields.
Market Restraints
- Import Equipment Dependence:Subsea trees, blowout preventers, and directional drilling assemblies face 18-24 month lead times from Houston and Aberdeen suppliers.
- Environmental Clearance Friction:The Ministry of Environment, Forest and Climate Change's coastal regulation zone restrictions delay seismic acquisition in the Gulf of Mannar and Andaman offshore blocks.
- Geological Complexity:High-pressure high-temperature reservoirs in the KG-DWN deepwater blocks require specialized metallurgy that triples well construction costs against standard offshore programs.
Strategic Opportunities
- Unconventional Appraisal:Tight sandstone and shale formations in the Vindhyan Basin await hydraulic fracturing pilots to prove commercial viability.
- CCUS Integration:Captured CO2 from Gujarat industrial clusters can extend field life through miscible flooding in declining Cambay Basin assets.
- Digital Twin Deployment:Real-time reservoir simulation is reducing unplanned downtime across Mumbai High's aging platform infrastructure.
Industry Challenges
- Deepwater Drilling Talent Gap:Subsea engineers and geoscientists with ultradeepwater experience command premium compensation that strains operator opex budgets.
- Legacy Pipeline Integration:New KG-D6 gas production must interface with 30-year-old Hazira-Bijaipur-Jagdishpur trunkline specifications, requiring compression and dehydration retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Oil and Gas Upstream Market |
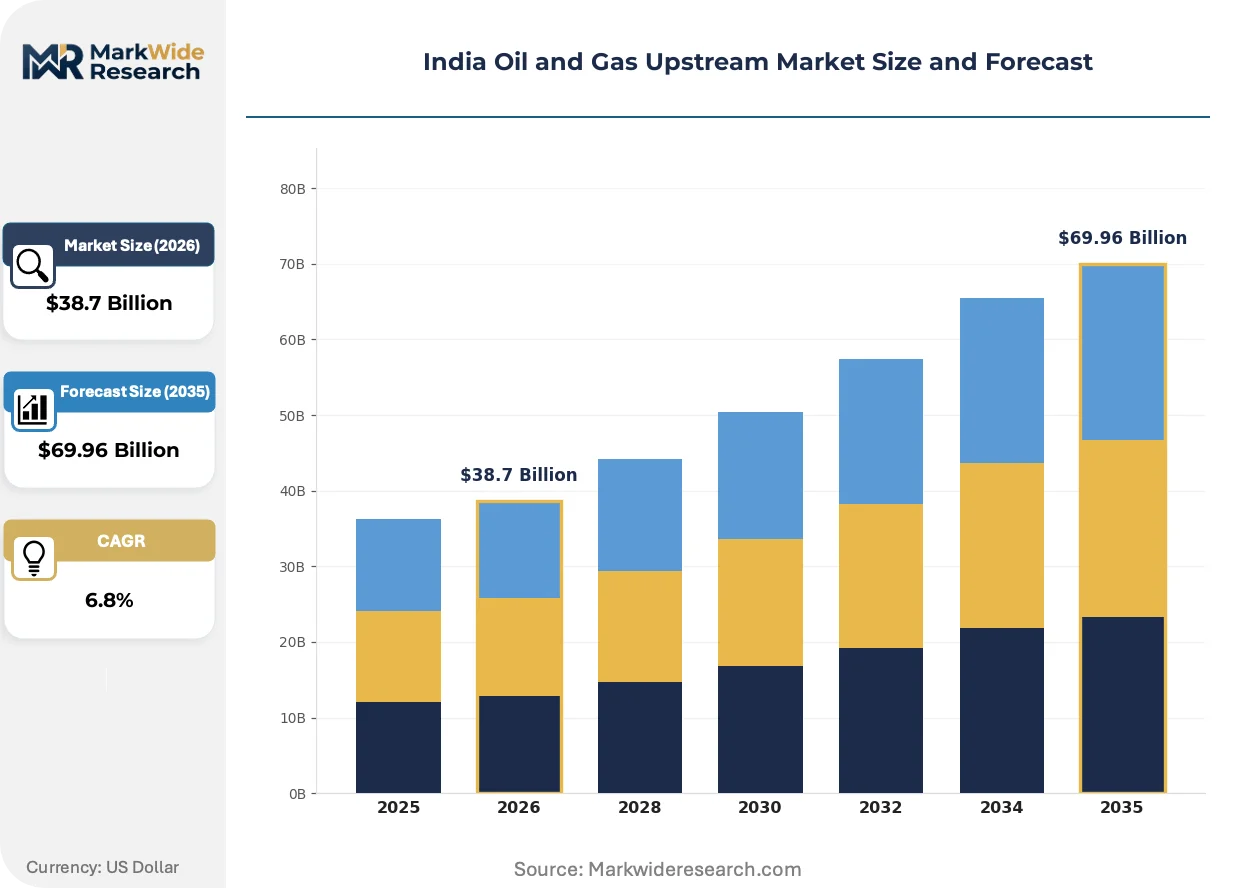
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Exploration Type: Offshore, Onshore, Deepwater, Shallow Water Technology: Seismic Survey, Drilling, Subsea Systems, Enhanced Oil Recovery Service Type: Drilling Services, Engineering Services, Construction, Logistics Services Resource Type: Conventional Oil, Natural Gas, Tight Oil, Shale Gas |
| Companies Covered | Oil and Natural Gas Corporation, Reliance Industries Limited, Oil India Limited, Vedanta Ltd (Cairn), Hindustan Oil Exploration Co., BP plc, Bharat PetroResources Ltd, Shell India (BG Exploration), Adani Welspun Exploration, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Oil and Gas Upstream Market Shifts & Advancements
Digital automation and subsea processing architectures are displacing conventional platform-based development models, while regulatory pressure on methane intensity and production efficiency is accelerating technology refresh cycles across mature basins.
Subsea multiphase pumping is integrating with subsea tieback systems to eliminate surface facility requirements in ultradeepwater Krishna-Godavari blocks. Reliance Industries and ONGC are deploying these systems at 1,500+ meter water depths. The technology is compressing development timelines from 48 months to 30 months for marginal field clusters.
The Directorate General of Hydrocarbons' revised production norms now mandate quarterly reservoir performance reporting and accelerated drilling obligations under HELP contracts. Operators face penalties for unexcused delays in minimum work program execution. Deepwater blocks and nomination fields alike are responding by front-loading 3D seismic reprocessing and slim-hole exploration wells.
Integrated service contracting is displacing discrete rig-and-service procurement across Rajasthan and Assam onshore operations. Cairn and ONGC now bundle directional drilling, logging, and completion services under single-source agreements with Halliburton and Schlumberger affiliates. This consolidation is most visible in the Mangala-Bhagyam-Aishwariya cluster, where drilling efficiency gains of 15-20 percent are being reported.
India Oil and Gas Upstream Market Segmentation
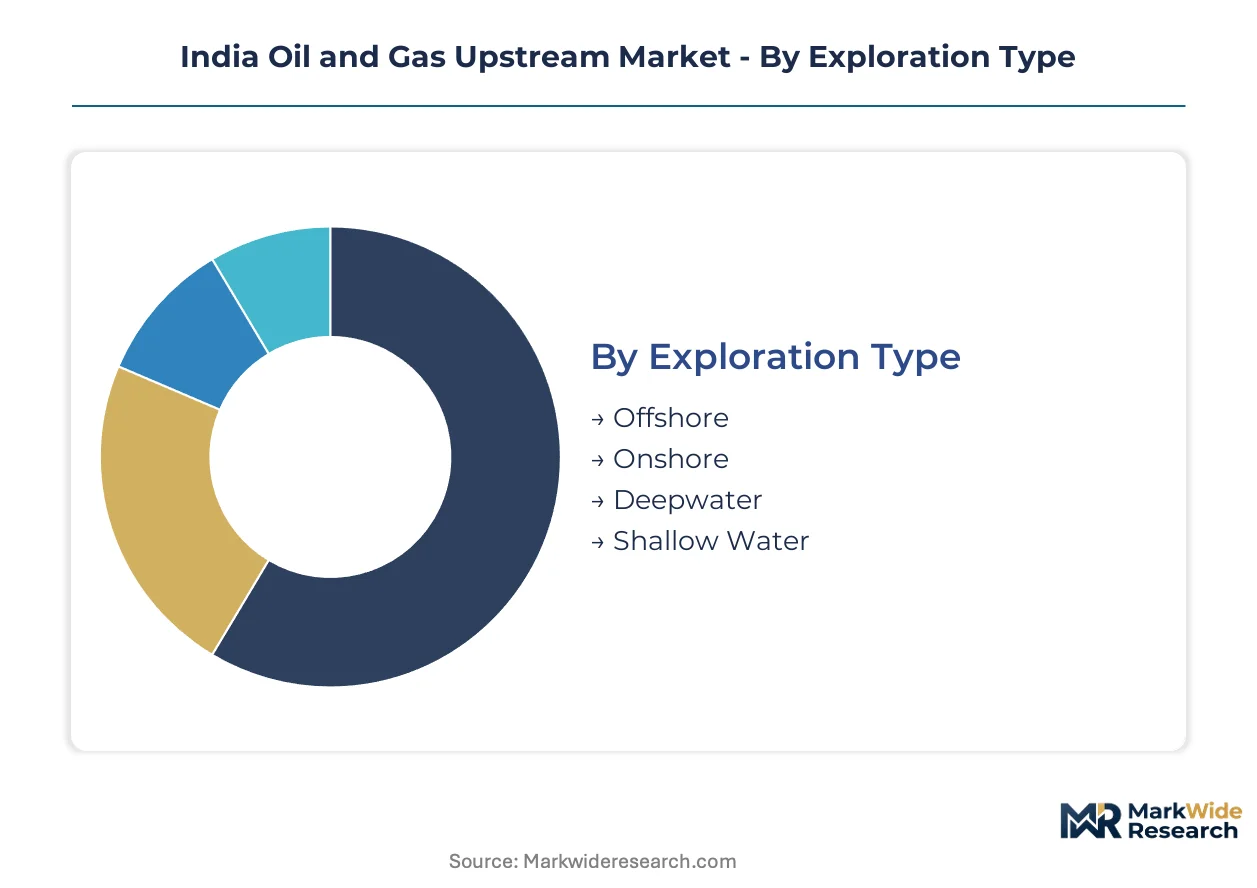
Segmentation in India's upstream market reveals how capital allocation, technical complexity, and regulatory exposure vary across operational modes. Understanding these divisions helps operators match capability to opportunity while navigating the Directorate General of Hydrocarbons' differentiated compliance requirements.
Exploration Type:
Standardization dominates shallow-water and onshore programs where rig specifications and environmental protocols follow established templates, while deepwater and frontier offshore blocks demand bespoke engineering and extended appraisal timelines.
- Offshore:Encompasses both shallow and deepwater developments in the Krishna-Godavari and Mumbai High basins. Gujarat's Cambay Basin shallow-water extensions anchor current production, though KG-DWN deepwater blocks absorb the majority of exploration capital due to their scale potential.
- Onshore:Rajasthan's Barmer-Sanchori fields and Assam's mature assets define this segment. Cairn's Mangala processing terminal demonstrates how integrated pipeline infrastructure can sustain economic viability despite natural decline rates exceeding five percent annually in aging reservoirs.
- Deepwater:Ultradeep blocks beyond 1,500 meters require subsea tieback architectures and specialized metallurgy for high-pressure high-temperature conditions.
- Shallow Water:Legacy Mumbai High platforms and Gujarat near-shore developments rely on conventional jackup rigs and established supply chains from Hazira and Dahej.
Leading the category by volume: Onshore. Growing fastest: Deepwater.
Technology:
Cost tiers separate mature seismic and drilling services from capital-intensive subsea and enhanced recovery systems that command premium pricing and longer contract durations.
- Seismic Survey:3D and 4D seismic acquisition underpins exploration commitments under HELP contracts. Operators front-load these surveys to meet compressed appraisal windows, with reprocessing of legacy data reducing new acquisition costs in the Krishna-Godavari basin.
- Drilling:Directional and horizontal drilling technologies unlock complex reservoir geometries in Rajasthan's tight formations. ONGC and Cairn report efficiency gains of 15-20 percent through integrated service contracts bundling logging and completion services.
- Subsea Systems:Multiphase pumping and processing equipment eliminates surface facility requirements at extreme depths.
- Enhanced Oil Recovery:Chemical flooding and CO2 injection extend field life in Assam's declining Barmer-Sanchori assets.
Widest deployment: Drilling. Steepest expansion trajectory: Subsea Systems.
Service Type:
Customer type differentiates this category — integrated operators favor bundled engineering-construction packages while independents unbundle drilling and logistics to preserve capital flexibility.
- Drilling Services:Rig procurement, directional drilling, and completion operations form the largest service expenditure category. Halliburton and Schlumberger affiliates dominate through single-source agreements covering the Mangala-Bhagyam-Aishwariya cluster.
- Engineering Services:Field development planning and reservoir simulation support DGH approval processes. Real-time digital twin deployment is reducing unplanned downtime across Mumbai High's aging platform infrastructure.
- Construction:Platform fabrication, pipeline laying, and processing terminal buildouts concentrate at Hazira and Dahej industrial corridors.
- Logistics Services:Offshore supply vessel chartering and helicopter transport support drilling campaigns in the Andaman and Gulf of Mannar blocks.
Highest revenue concentration: Drilling Services. Gaining share fastest: Engineering Services.
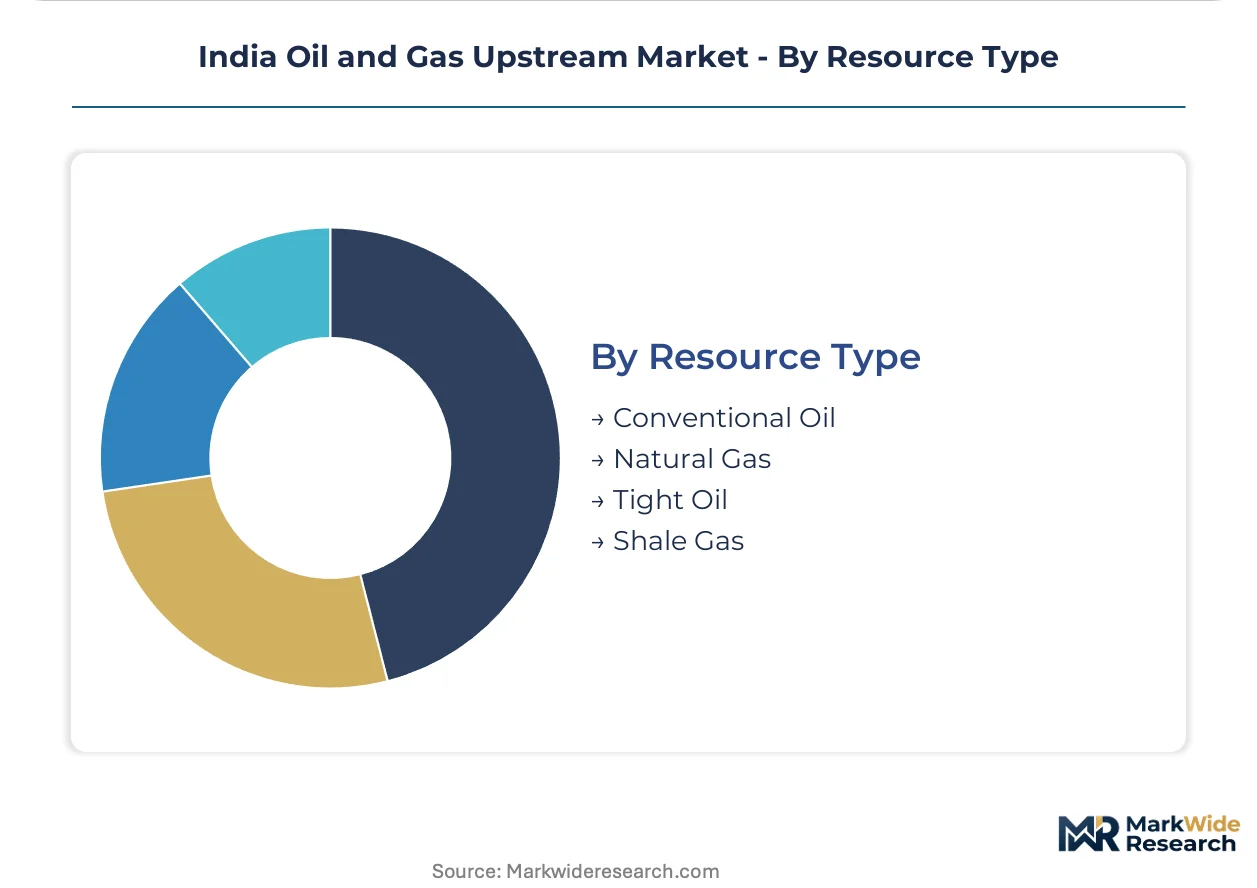
Resource Type:
Maturity curves separate established conventional production from unconventional resources awaiting commercial proof points through pilot fracturing programs.
- Conventional Oil:Light to heavy crude grades from Mumbai High, Rajasthan, and Assam fields supply domestic refineries. API gravities range from sweet light to sour heavy, with processing requirements varying across Reliance's Jamnagar complex and public sector facilities.
- Natural Gas:Dry and associated gas feeds fertilizer plants, CGD networks, and petrochemical complexes. The PNGRB's district expansion mandate to 300-plus districts is pulling offtake from Krishna-Godavari and Cambay Basin fields.
- Tight Oil:Low-permeability sandstone formations in the Vindhyan and Gondwana basins await hydraulic fracturing pilots to establish flow rates.
- Shale Gas:Organic-rich formations remain unproven at scale, with geological complexity and water availability constraining development timelines.
Dominant by output: Conventional Oil. Expanding most quickly: Natural Gas.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's domestic crude production meets roughly 15 percent of consumption, leaving an 85 percent import dependency that shapes upstream investment priorities. Natural gas output from the Krishna-Godavari and Cambay basins feeds fertilizer and city gas networks, yet supply gaps persist across industrial corridors.
Gujarat
Cambay Basin shallow-water fields and onshore extensions anchor western India's gas supply to Hazira and Dahej petrochemical complexes. The state's coastal regulation zones constrain seismic acquisition timelines under Ministry of Environment, Forest and Climate Change protocols. Ahmedabad-Vadodara industrial belt concentrates drilling service procurement and platform fabrication yards.
Maharashtra
Mumbai High offshore platforms generate the bulk of national crude output through mature field redevelopment programs. The Directorate General of Hydrocarbons enforces production norms and field development plan approvals across Bombay High South and Bassein assets. Navi Mumbai hosts engineering procurement centers for subsea equipment integration.
Andhra Pradesh
Krishna-Godavari deepwater blocks absorb the majority of exploration capital as ultradeepwater subsea tiebacks target 1,500-meter depths. The Petroleum and Natural Gas Regulatory Board's city gas distribution mandates pull KG-D6 gas into expanding district networks. Kakinada serves as the primary supply base for offshore drilling campaigns and pipeline landfall operations.
Rajasthan
Barmer-Sanchori onshore fields demonstrate integrated production-pipeline-terminal economics through enhanced oil recovery programs. The Open Acreage Licensing Policy compresses appraisal windows for operators holding nomination acreage. Mangala processing terminal and associated pipeline infrastructure sustain output from naturally declining reservoirs.
Assam
Mature fields in the northeastern basin face decline rates exceeding five percent annually, driving chemical flooding and CO2 injection pilots. Environmental clearances from the Ministry of Environment, Forest and Climate Change restrict drilling access in ecologically sensitive zones. Digboi and Naharkatiya industrial clusters maintain legacy refining and production support capabilities.
India Oil and Gas Upstream Market Competitive Landscape
Top-tier vendors anchor production-sharing contract holdings, while mid-tier independents and international joint venture partners occupy specialized exploration niches. State-controlled enterprises dominate nomination acreage and established producing assets. Strategic archetypes separate integrated operators with downstream refining linkages from pure-play exploration specialists and service-integrated technology providers. Competitive positioning hardens through production efficiency mandates and accelerated drilling obligations under HELP contract terms.
Among domestic operators, Oil and Natural Gas Corporation exemplifies the state-backed integrated archetype through its commanding position in Mumbai High and deepwater developments. Reliance Industries Limited occupies a position as the private integrated operator leveraging captive downstream channels. Vedanta Ltd represents the foreign-acquired domestic specialist archetype following its Rajasthan block consolidation.
| Leading Market Players |
|---|
| Oil and Natural Gas Corporation |
| Reliance Industries Limited |
| Oil India Limited |
| Vedanta Ltd (Cairn) |
| Hindustan Oil Exploration Co. |
| BP plc |
| Bharat PetroResources Ltd |
| Shell India (BG Exploration) |
| Adani Welspun Exploration |
| Others |
Supply & Pricing Matrix
Subsea engineering talent concentration in Mumbai and Aberdeen anchors labor-cost differentials that widen pricing-tier spreads between integrated service contracts and unbundled procurement models across Krishna-Godavari deepwater developments.
Pricing Analysis
Margin tightening in deepwater drilling services reflects premium metallurgy requirements for high-pressure high-temperature reservoirs. Three-tier pricing structure across premium, standard, and economy levels separates subsea specialists from conventional jackup rig operators. Price differentiation hinges on certification tier and geographic delivery cost to offshore blocks. Fertilizer manufacturers show highest price sensitivity due to subsidy-linked gas procurement, while integrated petrochemical complexes absorb premium pricing for supply security.
Supply Chain Analysis
Freight costs from Houston and Aberdeen inflate landed equipment prices for blowout preventers and subsea trees by 18-24 month lead time exposure. Manufacturing concentrates in the United States, the United Kingdom, and Singapore for critical drilling assemblies. Raw material dependencies span specialized steel alloys, high-performance elastomers, and directional drilling electronics. Single-source vulnerability around subsea multiphase pumping systems threatens project timelines. Distribution runs through Hazira and Kakinada supply bases to offshore drilling campaigns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital automation architectures are displacing conventional platform-based development models across India's upstream sector, compressing capital deployment timelines while reshaping operator technology procurement priorities.
For Market Incumbents: Deploy integrated service contracting to consolidate drilling, logging, and completion spend under single-source agreements with Halliburton and Schlumberger affiliates. Lock in 15-20 percent efficiency gains across Rajasthan's Mangala-Bhagyam-Aishwariya cluster. Counter emerging independent challengers through captive pipeline infrastructure control and accelerated field development plan submissions to the Directorate General of Hydrocarbons.
For New Entrants and Emerging Players: Enter via tight oil appraisal pilots in the Vindhyan Basin where hydraulic fracturing commercial proof points remain unestablished. Target the unconventional resource segment where legacy operators lack proven flow rate data. Pursue joint venture structures with state-controlled enterprises to access nomination acreage and share seismic acquisition costs under HELP contract terms.
For Investors and Strategic Acquirers: Re-rating potential sits with subsea technology specialists given accelerating ultradeepwater capital deployment in KG-DWN blocks beyond 1,500 meters. Five-to-ten year viability hinges on demonstrated execution of subsea tieback systems reducing surface facility requirements. Monitor quarterly reservoir performance reporting mandates as inflection indicator for operator compliance discipline and penalty exposure.
| Strategic Initiative | Industry Significance |
|---|---|
| Subsea Tieback Deployment | Reliance and ONGC compress development timelines from 48 months to 30 months for marginal KG-DWN fields. |
| Enhanced Oil Recovery Investment | Chemical flooding pilots in Assam's Barmer-Sanchori fields extend productive life of naturally declining reservoirs. |
| Digital Twin Integration | Real-time reservoir simulation reduces unplanned downtime across Mumbai High's aging platform infrastructure. |
| CCUS Infrastructure Buildout | Captured CO2 from Gujarat industrial clusters enables miscible flooding in declining Cambay Basin assets. |
| Integrated Service Contracting | Halliburton and Schlumberger affiliates bundle directional drilling and completion across Rajasthan operations. |
Research Methodology
Document review covered Directorate General of Hydrocarbons production norms, Petroleum and Natural Gas Regulatory Board tariff orders, and Ministry of Environment coastal regulation zone protocols, complemented by interviews with upstream asset managers, subsea procurement leads at ONGC and Reliance, drilling contractors operating in Krishna-Godavari blocks, and reservoir engineers at Cairn's Barmer-Sanchori fields. Secondary sources included Open Acreage Licensing Policy bidding round disclosures, HELP contract fiscal term analyses, and customs data on subsea equipment imports. Bottom-up field-level production estimates were triangulated against top-down basin-wide capacity assessments.
Historical production trajectories from Mumbai High, Rajasthan, and KG-D6 fields were cross-referenced against panel input from EPC contractors and subsea equipment suppliers to anchor growth assumptions across the analysis window. Segmentation dimensions modeled encompassed exploration type, technology tier, service category, and resource maturity curve. CAGRs were derived from production-sharing contract commitment schedules and announced field development timelines. Forecast inputs incorporated HELP contract drilling obligation acceleration and city gas distribution network expansion mandates.
Revisions become necessary when environmental clearance timelines extend beyond compressed appraisal windows or when subsea equipment lead times from Houston and Aberdeen suppliers deteriorate further. Forecasts reflect assumptions around regulatory enforcement consistency and technology deployment rates. Stakeholders should weight assumptions against their own operating context and supply chain exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Central Asia Oil and Gas Upstream Market
Offshore Oil and Gas
Offshore Equipment Market
Offshore Oil and Gas
Single Point Anchor Reservoir (SPAR) Market
Offshore Oil and Gas
Uzbekistan Oil and Gas Downstream Market
Offshore Oil and Gas
Kuwait Oil and Gas Downstream Market
Offshore Oil and Gas
Denmark Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
United Arab Emirates Oil and Gas Market
Offshore Oil and Gas
North Sea Oil and Gas Market
Offshore Oil and Gas
Brazil Oil and Gas Downstream Market
Offshore Oil and Gas
Asia-Pacific Floating Offshore Wind Power Market
Offshore Oil and Gas
United Kingdom LNG Bunkering Market
Offshore Oil and Gas
Brazil Offshore Oil & Gas Upstream Market
Offshore Oil and Gas
Offshore Rental Equipment Market
Offshore Oil and Gas
South America Offshore Energy Market
Offshore Oil and Gas
Brazil Oil and Gas Upstream Market
Offshore Oil and Gas
Europe Floating Offshore Wind Power Market