
 Offshore Contract Drilling Market | 2026-2036
Offshore Contract Drilling Market Size, Share, and Industry Trends Forecast 2026-2036
Offshore Contract Drilling Market Analytics
National oil companies are redrawing offshore contracting priorities, shifting day-rate exposure toward integrated service packages that bundle drilling with completions and subsea installation. Transocean Ltd anchors the ultra-deepwater drillship segment through a fleet weighted to 10,000-foot-plus capability. Seadrill Ltd specializes in harsh-environment jack-ups serving the North Sea and Norwegian continental shelf. Noble Corporation competes on operational efficiency metrics that reduce non-productive time for clients in the Gulf of Mexico.
Offshore contract drilling covers the provision of mobile offshore drilling units and crews to explore and develop hydrocarbon reservoirs beneath the seabed, with rigs rated by water depth capability, hookload capacity, and dynamic positioning class. The primary commercial purpose is to convert undeveloped offshore leases into producing assets through borehole creation and well construction. Drillships dominate margin pools in ultra-deepwater plays where day rates exceed other fleet categories by substantial multiples. Jack-up rigs sustain the largest deployed fleet count but face utilization pressure in shallow-water basins with mature prospect inventories. Managed pressure drilling technology is gaining fastest adoption in narrow-margin formations where conventional methods risk kicks or lost circulation.
The US Coast Guard and Bureau of Safety and Environmental Enforcement enforce structural and operational standards for rigs in federal waters, while Brazil's National Petroleum Agency mandates local content requirements that shape contractor procurement and crew composition. The International Association of Drilling Contractors maintains equipment certification protocols that influence fleet eligibility for operator tenders. Stakeholders must monitor how electrification mandates and well-control rule revisions alter capital deployment timelines for newbuild rigs versus refurbishment programs.
Market Dynamics
Dual-fuel propulsion mandates from the International Maritime Organization are forcing capital reallocation across the offshore drilling fleet, compressing refurbishment timelines and accelerating newbuild specifications toward hybrid-ready architectures.
Growth Catalysts
- Pre-salt basin development:Brazil's geological formations continue to attract capital deployment, with operators committing to multi-well drilling campaigns that sustain long-term rig demand.
- Carbon intensity regulations:The IMO's CII framework creates compliance-driven replacement cycles for older tonnage, pulling forward investment in next-generation assets.
- Managed pressure drilling:This technology reduces non-productive time in narrow-margin formations, expanding addressable reservoir categories for contractors.
Market Restraints
- Steel and alloy input volatility:Rig construction depends on specialized high-strength steel grades subject to commodity price swings and limited supplier base concentration.
- Specialized labor scarcity:Deepwater drilling requires certified dynamic positioning operators and subsea specialists with training pipelines that lag fleet expansion needs.
- Local content mandates:Brazil's National Petroleum Agency procurement rules impose cost and timeline friction on international contractors.
Strategic Opportunities
- Guyana offshore province:This emerging basin offers first-mover positioning for drillship operators as production scales toward multiple floating facilities.
- Electrification-ready rig specifications:Shore power connectivity and battery-hybrid architectures align with North Sea decarbonization pathways.
- Integrated service bundling:Contractors combining drilling with completions and subsea installation capture expanded revenue per well.
Industry Challenges
- Classification society recertification:Aging jack-up fleets face compressed survey windows and steel renewal requirements that strain maintenance budgets.
- Legacy control system integration:Digital automation upgrades must interface with existing well-control hardware without compromising safety certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Offshore Contract Drilling Market |
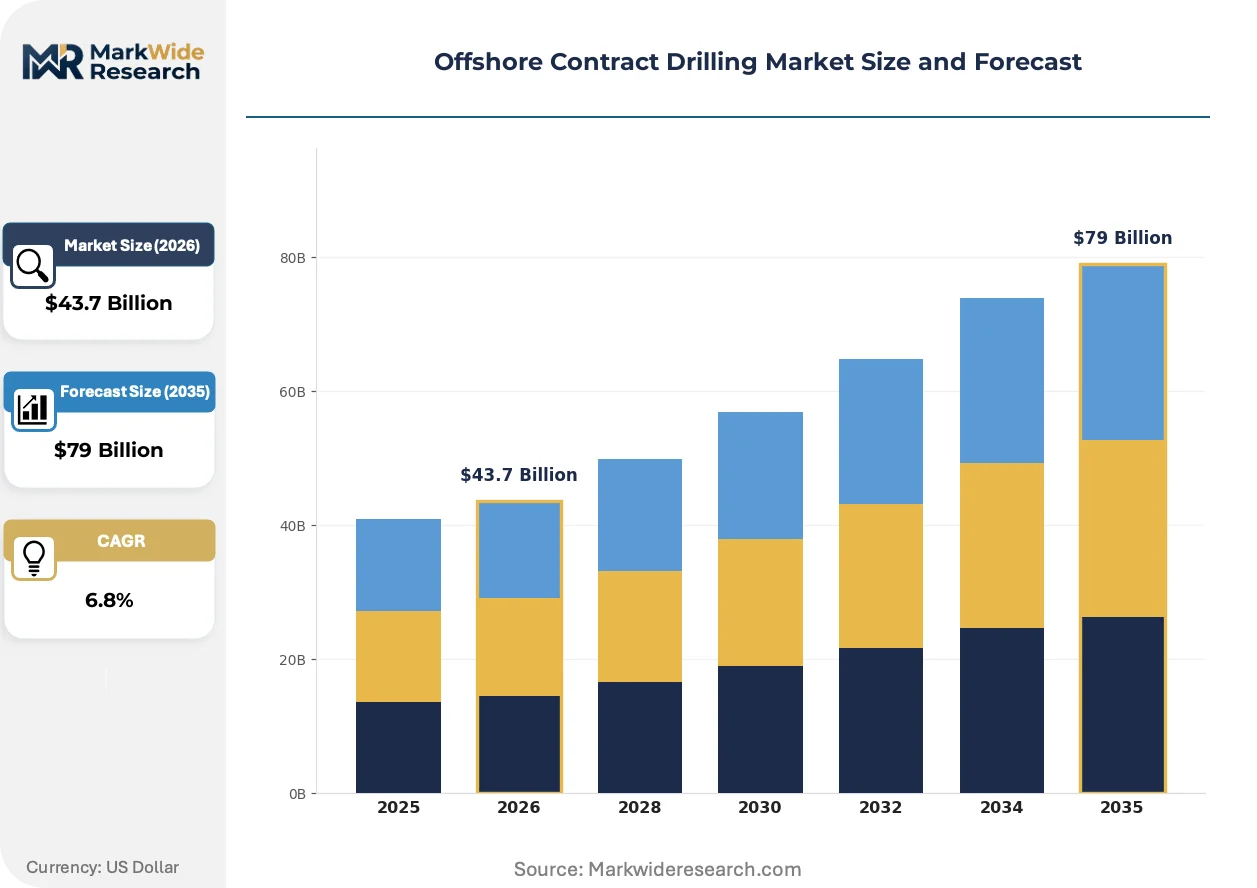
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $79 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drilling Technology: Rotary, Directional, Dual Gradient, Managed Pressure Contract Type: Day Rate, Turnkey, Lump Sum, Integrated Water Depth: Shallow Water, Deep Water, Ultra Deep Water, Transitional Fleet Type: Jack-up Rigs, Semi-submersibles, Drillships, Others |
| Companies Covered | Transocean Ltd, Seadrill Ltd, Diamond Offshore Drilling Inc, China Oilfield Services Limited, Saipem SpA, Valaris, Noble Corporation, ENSCO PLC, Maersk Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Offshore Contract Drilling Market Evolving Landscape
Automation and digital twin technologies are restructuring how drilling contractors optimize rig performance, shifting competitive advantage toward data-driven operational models rather than brute fleet scale.
Advanced blowout preventer monitoring systems is decomposing traditional maintenance schedules into condition-based interventions. Deepwater operators in the Gulf of Mexico are deploying these systems across drillship fleets to compress downtime windows. The technology is decomposing fixed-cost service contracts into variable performance arrangements tied to system reliability metrics.
Europe's F-Gas Regulation is phasing down hydrofluorocarbon use in offshore HVAC and refrigeration systems. This forces rig owners to retrofit or replace cooling infrastructure before mandated deadlines. The North Sea jack-up segment faces the most concentrated compliance burden due to aging platform specifications and harsh-environment operational demands.
Operator procurement departments are unbundling integrated drilling contracts into discrete service line awards. This fragmentation enables specialized contractors to compete against full-service incumbents in specific technical niches. The shift is most visible in Brazil, where national oil companies now tender managed pressure drilling as a standalone scope separate from rig provision.
Offshore Contract Drilling Market Segmentation
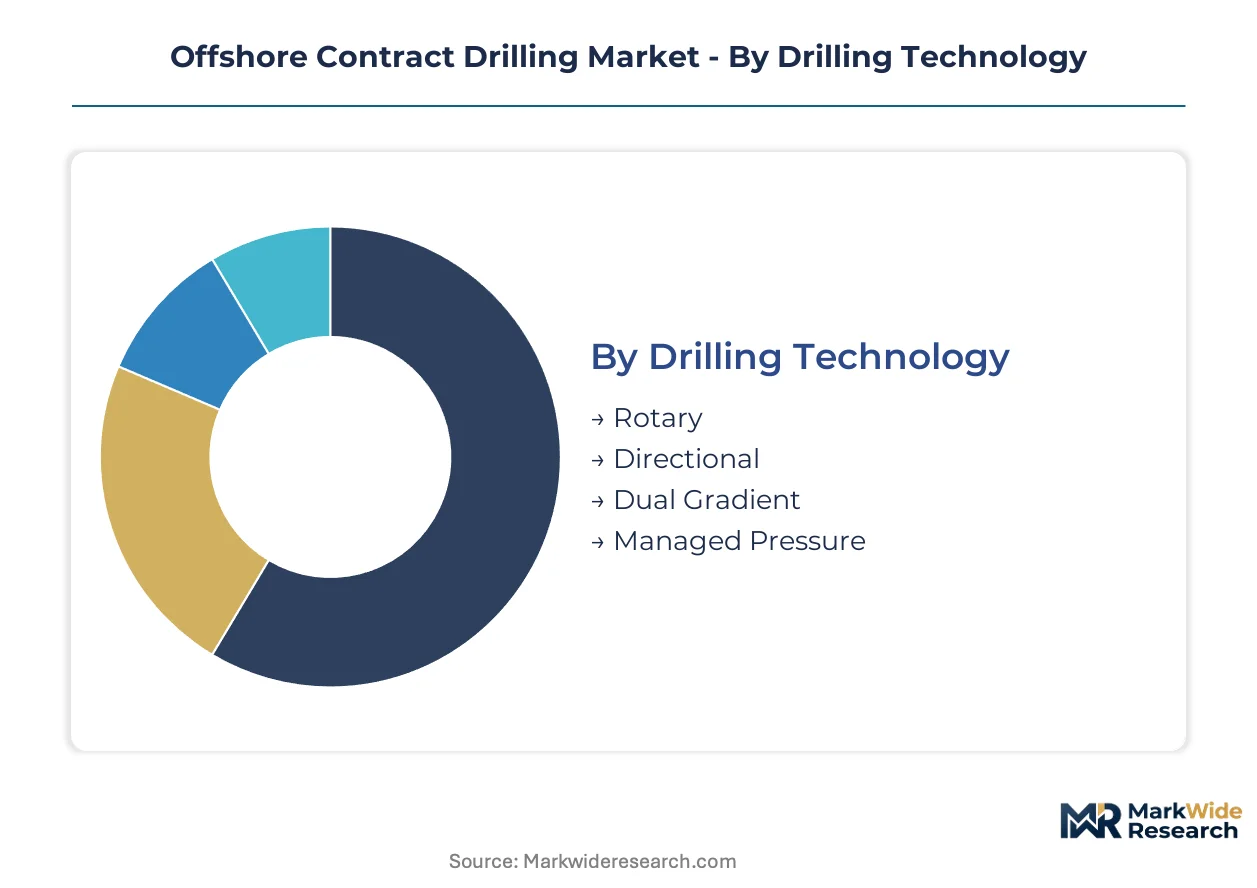
Segmentation in offshore contract drilling reveals how margin pools concentrate around water depth capability and technology sophistication. Contract structures and fleet specifications determine capital intensity and day-rate premiums across distinct operational environments.
Drilling Technology:
Margin pools concentrate in technologies that compress non-productive time and expand addressable reservoir categories.
- Managed Pressure:Precision-controlled annular pressure management enables drilling in narrow-margin formations where conventional methods risk kicks or lost circulation. Demand concentrates in Brazil's pre-salt basins where formation pressure regimes challenge standard approaches.
- Dual Gradient:Seawater-based mud weight management extends operational windows in ultra-deepwater plays. Operators in Guyana's offshore province deploy this technology to access reservoirs below complex salt layers.
- Rotary:Conventional rotary drilling dominates jack-up rig operations in shallow-water basins with predictable geological profiles.
- Directional:Steerable bottomhole assemblies enable multi-well pad development from single surface locations.
Managed pressure drilling holds installed capacity. Dual gradient systems are rotating up the share rankings.
Contract Type:
Commercial structures determine risk allocation between operators and contractors, with integrated models capturing expanded revenue per well.
- Integrated:Bundled drilling, completions, and subsea installation contracts reduce interface management for national oil companies. Saudi Aramco and Petrobras increasingly specify integrated scopes to compress project timelines.
- Day Rate:Time-based compensation remains standard for drillship and semi-submersible operations where operational complexity resists fixed-price commoditization.
- Turnkey:Fixed-price well delivery transfers geological risk to contractors in mature basins with predictable drilling parameters.
- Lump Sum:Single-price contracts for defined well counts suit exploration programs with standardized hole designs.
Day rate structures hold installed capacity. Integrated contracts are rotating up the share rankings.
Water Depth:
Depth ratings determine rig specifications, crew certification requirements, and day-rate tiering across the fleet.
- Ultra Deep Water:Operations below 7,500 feet require dynamically positioned drillships with 10,000-foot-plus hookload capacity. Brazil's pre-salt province and Gulf of Mexico Lower Tertiary trend sustain premium day rates for this segment.
- Deep Water:1,000 to 7,500-foot operations utilize semi-submersibles and advanced drillships in West Africa's mature basins.
- Shallow Water:Jack-up rigs dominate shelf operations where fixed platforms prove uneconomical for marginal field development.
- Transitional:Mid-depth zones between shelf and deepwater require specialized rig configurations with hybrid mooring systems.
Shallow water holds installed capacity. Ultra deep water is rotating up the share rankings.
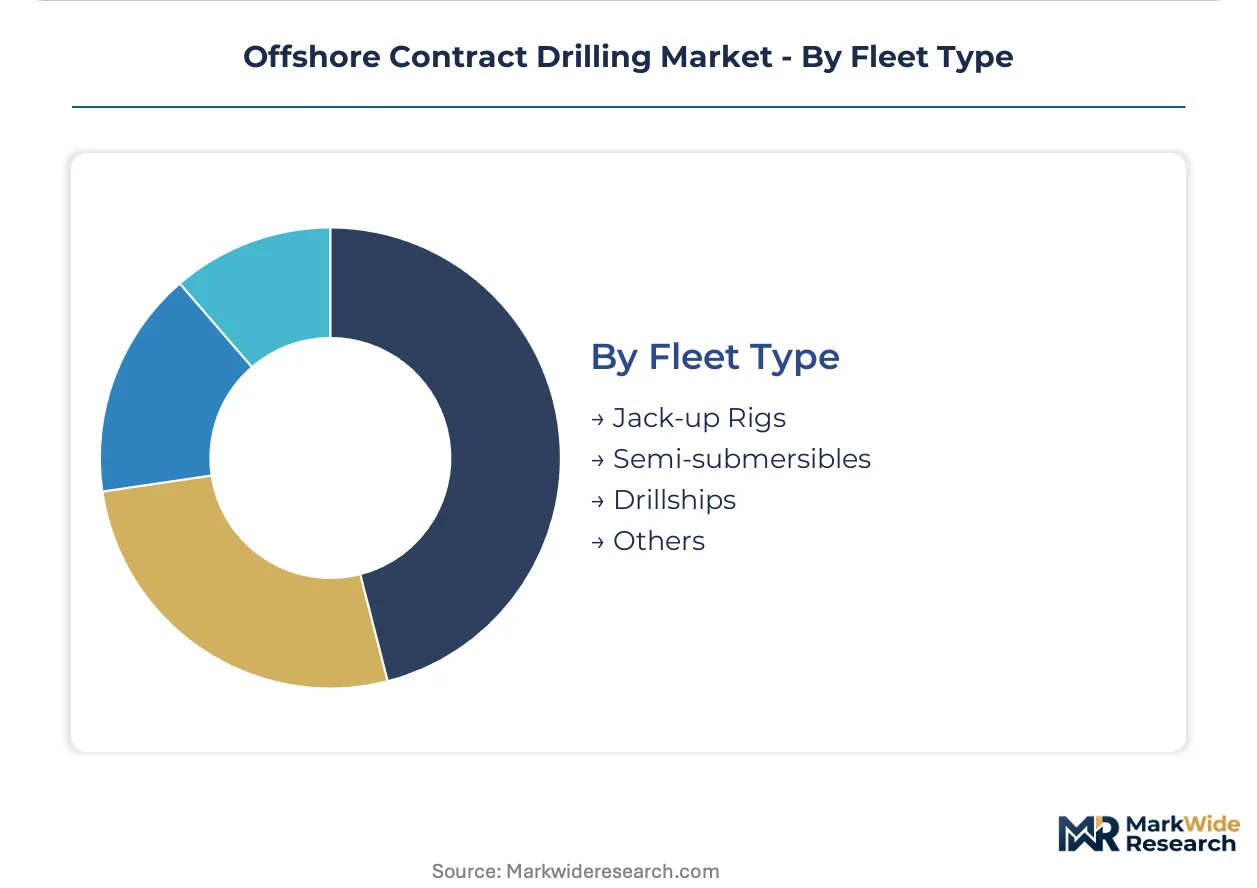
Fleet Type:
Physical platform architectures align with water depth, environmental conditions, and mobility requirements.
- Drillships:Self-propelled monohull vessels with dynamic positioning dominate ultra-deepwater margin pools. Dual-fuel propulsion mandates from the International Maritime Organization accelerate newbuild specifications toward hybrid-ready architectures.
- Jack-up Rigs:Self-elevating platforms sustain the largest deployed fleet count but face utilization pressure in shallow-water basins with mature prospect inventories. North Sea and Norwegian continental shelf operators specify harsh-environment designs.
- Semi-submersibles:Column-stabilized platforms offer superior motion characteristics in rough seas for deepwater drilling.
- Others:Tender-assisted drilling barges and platform rigs serve specific niche applications in benign environments.
Jack-up rigs hold installed capacity. Drillships are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rio de Janeiro anchors Latin America's offshore drilling logistics, while pipeline networks connecting Norway's Stavanger cluster to North Sea platforms sustain Europe's harsh-environment rig demand.
Brazil
Petrobras commits to multi-well campaigns in pre-salt formations beneath 2,000 meters of water and salt layers. ANP local content mandates require minimum Brazilian crew composition and domestic procurement quotas. The Santos Basin cluster near Rio de Janeiro concentrates drillship deployment for floating production facility tie-ins.
United States
Lower Tertiary trend discoveries in the Gulf of Mexico sustain ultra-deepwater drillship demand with day-rate premiums above other basins. The Bureau of Safety and Environmental Enforcement enforces well-control rule revisions that compress newbuild delivery timelines. Houston's Energy Corridor hosts contractor headquarters and subsea engineering centers serving federal lease rounds.
Norway
Johan Sverdrup field expansion and Arctic Barents Sea exploration sustain harsh-environment semi-submersible requirements. Petroleum Safety Authority Norway mandates electrification-readiness for rigs operating on the Norwegian continental shelf. Stavanger's Forus industrial park clusters drilling contractors, classification societies, and subsea equipment fabricators.
Saudi Arabia
Saudi Aramco's long-term rig programs target Red Sea frontier basins and Persian Gulf redevelopment. The country's national oil company increasingly specifies integrated drilling-completions packages to compress project timelines. Dhahran's King Fahd Industrial City concentrates rig maintenance yards and specialist training facilities.
Guyana
ExxonMobil-led consortiums scale production toward multiple floating production facilities in the Stabroek Block. The country's petroleum regulator issues exploration licenses with phased local content requirements. Georgetown serves as logistics hub for drillship provisioning and crew rotations to offshore installations.
Offshore Contract Drilling Market Competitive Landscape
Listed leaders compete with private specialists across fleet financing and contract risk allocation, creating a tiered structure where public drillship operators access capital markets for newbuild programs while private jack-up owners focus on regional utilization optimization. The market consolidates around three strategic archetypes: ultra-deepwater drillship specialists commanding premium day rates, harsh-environment jack-up operators serving North Sea regulatory requirements, and integrated service providers bundling drilling with completions scopes. Dominant competitive moves include fleet standardization to reduce spare parts inventory and strategic partnerships with national oil companies for multi-year rig commitments.
Within the drillship specialist tier, Transocean Ltd and Noble Corporation exemplify capital-intensive ultra-deepwater positioning through 10,000-foot-plus hookload capability. Among European-integrated contractors, Saipem SpA occupies a position spanning drilling, subsea installation, and offshore engineering. Seadrill Ltd represents the harsh-environment jack-up archetype with North Sea and Norwegian continental shelf specialization.
| Leading Market Players |
|---|
| Transocean Ltd |
| Seadrill Ltd |
| Diamond Offshore Drilling Inc |
| China Oilfield Services Limited |
| Saipem SpA |
| Valaris |
| Noble Corporation |
| ENSCO PLC |
| Maersk Group |
| Others |
Value Network & Pricing Analysis
Dual-fuel propulsion retrofits displacing conventional diesel-electric architectures are redrawing supply geography toward South Korean and Singaporean shipyards while compressing refurbishment economics for legacy jack-up owners. This substitution simultaneously concentrates Tier 1 rig construction in yards with hybrid-ready certification and fragments Tier 2 pricing for older tonnage facing accelerated obsolescence.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs offshore contracting. Premium drillships with 10,000-foot-plus hookload capability command spreads based on dynamic positioning class and dual-fuel readiness. Price differentiation reflects IMO carbon intensity compliance grades and local content fulfillment complexity. Cost compression in the standard jack-up tier is intensifying because Brazilian and Saudi national oil companies are unbundling integrated contracts into discrete scopes. Exploration-focused independents exhibit highest price sensitivity; pre-salt basin operators with multi-year campaigns show lowest.
Supply Chain Analysis
Strait of Malacca transit underwrites just-in-time delivery of high-strength steel plate from South Korean mills to Southeast Asian fabrication yards. Rig construction draws from specialized alloy suppliers in Japan and Germany for blowout preventer forgings. Single-source vulnerability concentrates in dynamic positioning thruster manufacturing dominated by a limited vendor set. Distribution runs through contractor-owned logistics hubs in Houston, Stavanger, and Singapore rather than third-party channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
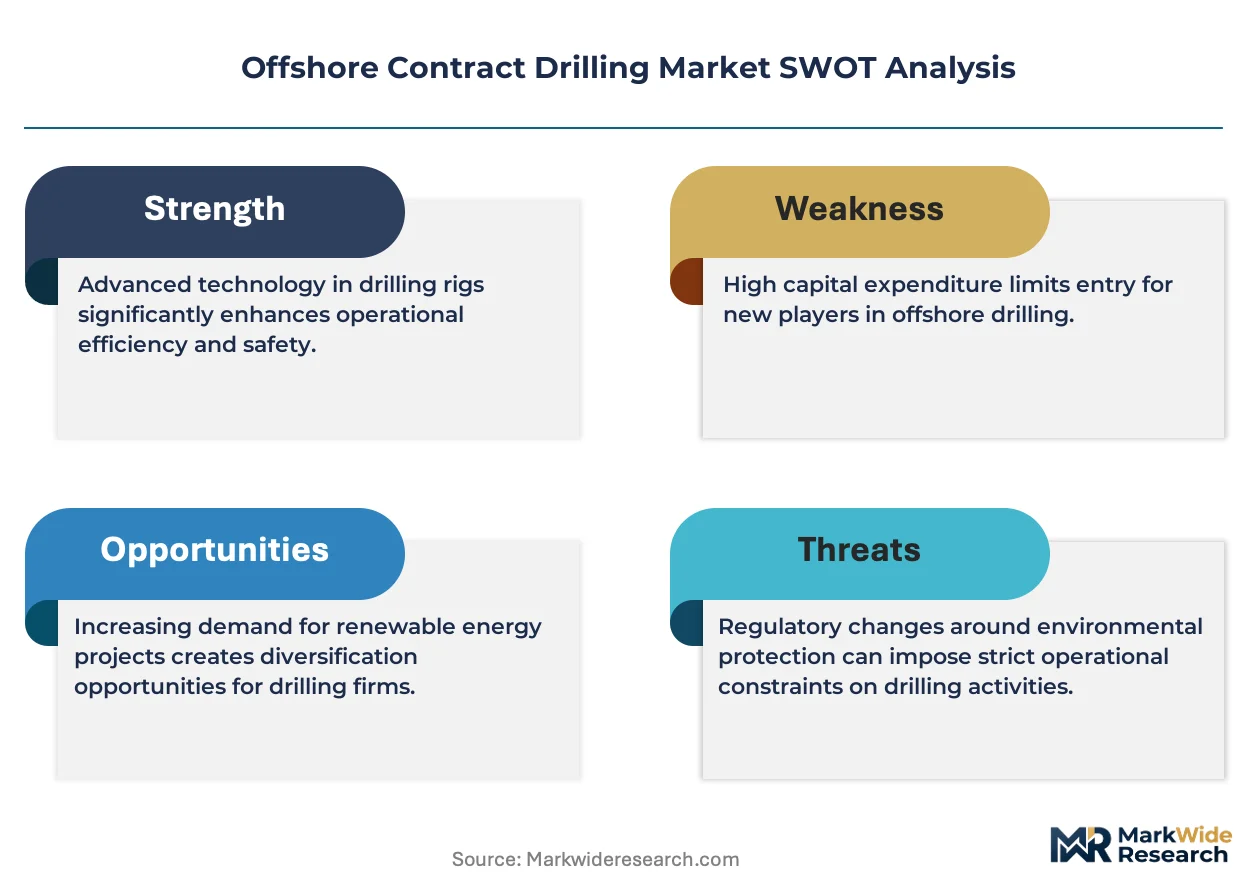
Offshore contract drilling operates as a regulatory-entrenchment defensive moat where IMO carbon intensity mandates and national local content rules create switching costs that lock operators into established contractor relationships.
For Market Incumbents: Shield fleet utilization through long-term rig commitments with Petrobras and Saudi Aramco that embed local content compliance. Accelerate backward integration into subsea installation capabilities to capture integrated contract scopes. Electrification-ready specifications represent the critical lever against emerging drillship entrants lacking hybrid-ready certification. For New Entrants and Emerging Players: Certification fast-track through the International Association of Drilling Contractors equipment protocols enables qualification for Guyana's emerging basin tenders. Target managed pressure drilling as a standalone service scope where Brazilian national oil companies have unbundled from rig provision. White-space exists in harsh-environment jack-up refurbishment for North Sea electrification mandates. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed drillship specialists holding 2014-vintage newbuilds. Long-term viability hinges on pre-salt basin commitment continuity and Guyana production scaling. Watch day-rate spreads between IMO-compliant and legacy tonnage as the inflection signal for replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Retrofit Program | IMO CII compliance preserves fleet eligibility for Petrobras and Saudi Aramco tenders. |
| Integrated Service Bundling | Combining drilling with completions captures expanded revenue per pre-salt well. |
| Managed Pressure Drilling Standalone | Unbundled Brazilian scopes create entry path for specialized technology providers. |
| Guyana Basin First-Mover Positioning | ExxonMobil-led consortium scaling supports multi-rig deployment commitments. |
| Electrification-Ready Newbuild Specification | North Sea Petroleum Safety Authority mandates align with Stavanger cluster demand. |
Research Methodology
A standing panel of rig fleet managers, national oil company procurement leads, shipyard project directors, and classification society surveyors provided ongoing calibration against field conditions. Primary interviews with drilling contractors, subsea equipment fabricators, and dynamic positioning system integrators combined with secondary validation through IADC equipment certification records, ANP local content compliance filings, and IMO marine environment regulatory updates. Bottom-up rig deployment tallies triangulated against top-down capital expenditure disclosures from listed contractors.
Consistency checks against Bureau of Safety and Environmental Enforcement rig activity databases and Petrobras quarterly fleet utilization reports validated volume and value outputs across the projection horizon. Segmentation modeling spanned water depth capability, contract structure, drilling technology sophistication, and regional regulatory framework. CAGRs derived from rig delivery timelines, refurbishment cycle compression, and basin-specific demand elasticity. Forecast inputs incorporated IMO carbon intensity implementation schedules and pre-salt basin development cadence.
The analysis sits within stated boundaries; outcomes outside sustained oil price bands supportive of deepwater sanctioning would require recalibration. Forecasts reflect assumptions regarding local content rule stability and hybrid propulsion technology maturation. Practitioners should keep alternative scenarios live as IMO enforcement stringency and national oil company capital allocation priorities evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Global Offshore Oil and Gas Seismic Equipment and Acquisitions Market
Offshore Oil and Gas
Argentina Oil and Gas Downstream Market
Offshore Oil and Gas
Uzbekistan Oil and Gas Downstream Market
Offshore Oil and Gas
Marine Scrubber Market
Offshore Oil and Gas
Norway Oil and Gas Market
Offshore Oil and Gas
Oman Oil and Gas Downstream Market
Offshore Oil and Gas
East Africa Oil and Gas Midstream Market
Offshore Oil and Gas
West Africa Oil and Gas Upstream Market
Offshore Oil and Gas
Middle East Offshore MRO Market
Offshore Oil and Gas
Abyssinian Oil Market
Offshore Oil and Gas
FPSO Market
Offshore Oil and Gas
Thailand Oil and Gas Downstream Market
Offshore Oil and Gas
Jack-Up Rigs Market
Offshore Oil and Gas
Offshore Drilling Riser Market
Offshore Oil and Gas
Brazil Offshore Energy Market
Offshore Oil and Gas
Oil and Gas Magnetic Ranging Market