
 Egypt Oil and Gas Upstream Market | 2026-2036
Egypt Oil and Gas Upstream Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Oil and Gas Upstream Market Foresight
Integrated service bundling across drilling and completion packages is realigning procurement patterns among Egyptian upstream operators. Eni SpA leverages its Zohr gas field infrastructure to sustain full-field development economics across multiple Mediterranean blocks. Egyptian General Petroleum Corporation anchors domestic production through joint venture structures with international partners. Chevron Corporation competes for deepwater exploration acreage in the Red Sea and Mediterranean concessions.
Egypt oil and gas upstream encompasses exploration, drilling, and production activities for crude oil and natural gas reservoirs, typically operating at depths from 1,500 to 4,500 meters across onshore and offshore geological formations, with primary purpose being hydrocarbon extraction for power generation, industrial feedstock, and export revenue. Crude oil segments dominate current production volumes though natural gas liquids are expanding fastest due to Zohr-scale offshore discoveries and associated gas processing investments. Enhanced oil recovery technology commands premium service margins as mature Western Desert fields require pressure maintenance and thermal stimulation to sustain decline rates.
Egyptian General Petroleum Corporation concession frameworks, EGAS licensing terms, and environmental compliance standards administered by the Egyptian Environmental Affairs Agency shape operator obligations around flaring reduction and offshore discharge protocols. The country's national petroleum regulator mandates local content requirements that influence contractor selection and equipment sourcing decisions. Stakeholders must monitor fiscal term negotiations and carbon intensity benchmarks as Egypt positions its upstream sector for long-term gas export competitiveness.
Market Dynamics
Integrated service bundling across drilling and completion packages is realigning procurement patterns among Egyptian upstream operators. EGAS licensing rounds are reshaping concession terms and contractor economics.
Growth Catalysts
- Zohr-scale offshore discoveries:Mediterranean deepwater gas finds are expanding natural gas liquids processing capacity and attracting infrastructure investment.
- Petrochemical feedstock demand:Egyptian refineries are expanding cracking capacity, pulling additional condensate and associated gas from upstream operations.
- Enhanced oil recovery mandates:The Egyptian Environmental Affairs Agency flaring reduction protocols are accelerating thermal stimulation and pressure maintenance deployments.
Market Restraints
- Service supply concentration:Integrated drilling and completion package providers dominate procurement, limiting price competition for specialized tool vendors.
- Mature field decline rates:Western Desert reservoirs require continuous artificial lift and waterflooding investment to maintain plateau production.
- Offshore discharge compliance costs:Egyptian Environmental Affairs Agency protocols for produced water and drilling waste management add operational overhead to Mediterranean developments.
Strategic Opportunities
- Nile Delta unexplored blocks:Underpenetrated concessions offer lower geological risk for gas-prone exploration with existing pipeline takeaway.
- Red Sea deepwater frontier:Unlicensed acreage in southern offshore zones presents material upside for operators with subsea production system expertise.
- Carbon capture readiness:EGAS fiscal term negotiations are beginning to incorporate CCUS investment credits for gas field developments.
Industry Challenges
- Subsea engineering talent scarcity:Deepwater Mediterranean developments require specialized installation and intervention capabilities that remain concentrated among international contractors.
- Legacy system integration:Brownfield Western Desert assets operate heterogeneous artificial lift and surface facility vintages that complicate digital twin deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Oil and Gas Upstream Market |
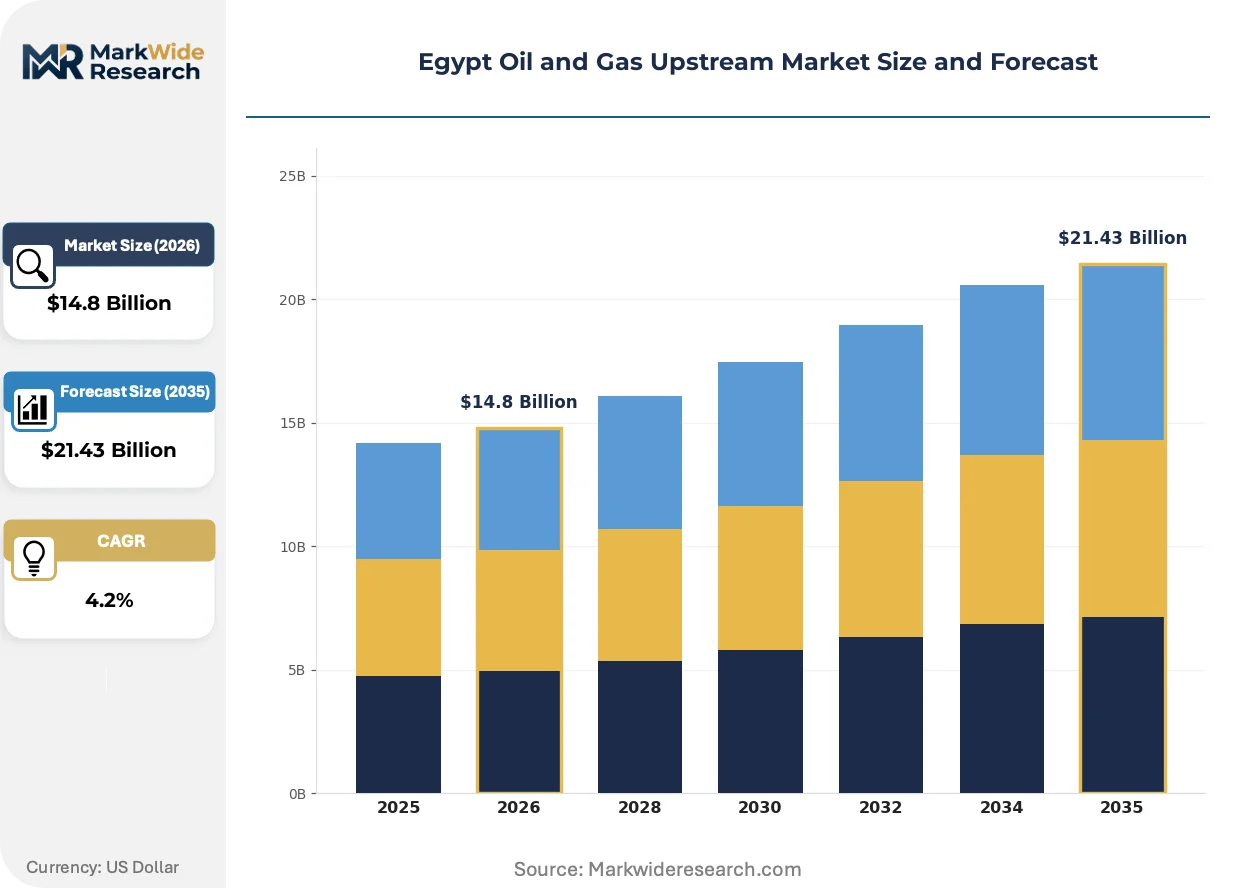
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $21.43 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crude Oil, Natural Gas, Natural Gas Liquids, Condensates Service Type: Drilling, Well Completion, Exploration, Production Optimization Technology: Offshore Platforms, Onshore Facilities, Enhanced Oil Recovery, Hydraulic Fracturing Client Type: National Oil Companies, Independent Producers, Oilfield Services, International Oil Companies |
| Companies Covered | Eni SpA, ExxonMobil Corp, Egyptian General Petroleum Corporation, Apache Corporation, Chevron Corporation, BP PLC, TotalEnergies SE, IPR Energy Group, Shell PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Oil and Gas Upstream Market Shifts & Advancements
Digitalization of reservoir characterization and remote operations is compressing exploration cycle times. Egyptian operators are deploying advanced analytics to optimize mature field performance.
Electrified rig packages are electrifying drilling operations across Western Desert and Nile Delta concessions. Eni SpA and joint venture partners are retrofitting grid-tied power systems to replace diesel generator sets. This shift is electrifying cost structures and enabling 24-hour continuous drilling campaigns previously constrained by fuel logistics.
Egyptian Environmental Affairs Agency flaring reduction mandates are tightening venting and combustion standards for associated gas. Operators must install vapor recovery units or face production curtailment. Offshore Mediterranean developments face the strictest compliance timelines due to proximity to coastal population centers.
Performance-based drilling contracts are displacing day-rate structures in Egyptian procurement. Egyptian General Petroleum Corporation joint ventures now tie contractor compensation to rate-of-penetration and non-productive time metrics. This shift is most advanced in Zohr field development where integrated project delivery models dominate.
Egypt Oil and Gas Upstream Market Segmentation
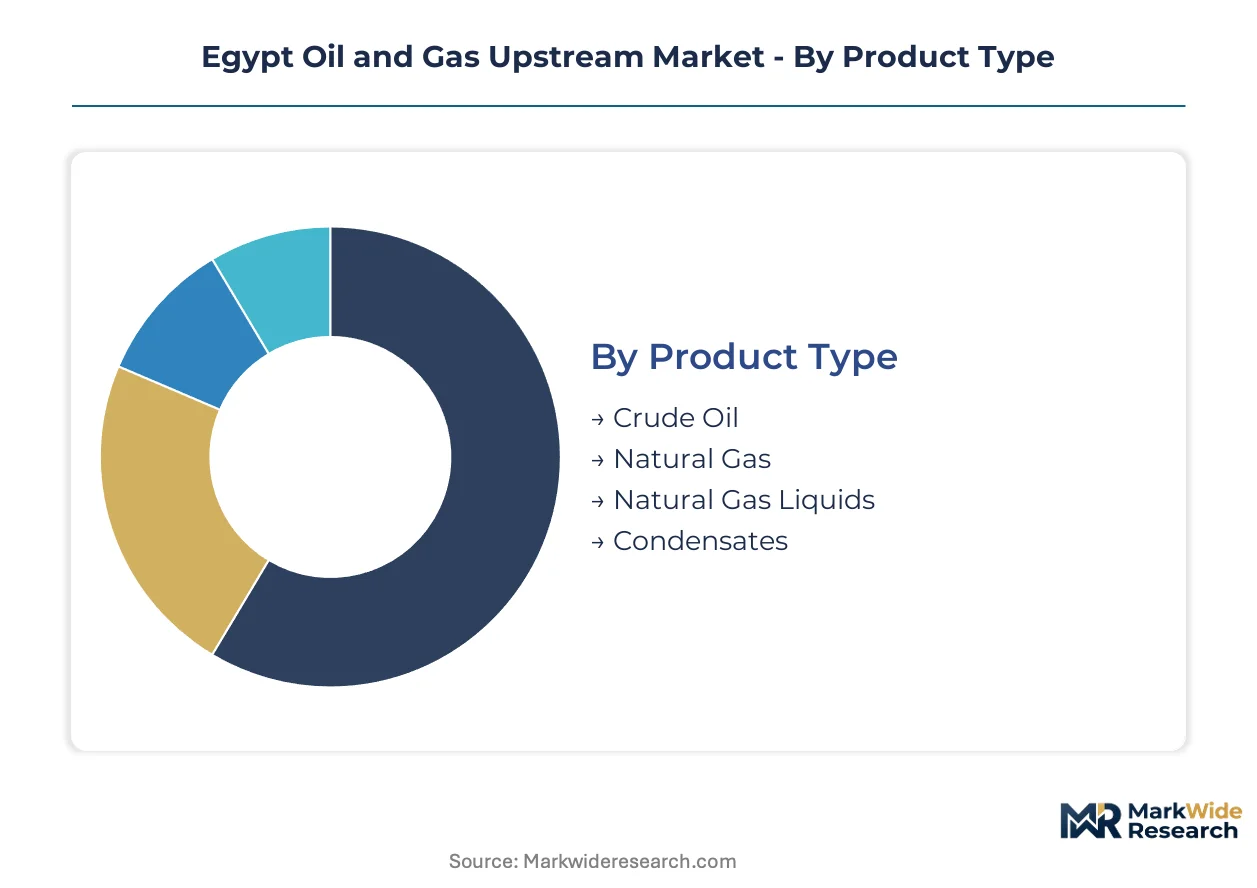
Upstream segmentation in Egypt reflects the tension between mature Western Desert crude operations and Mediterranean gas expansion. Operator procurement patterns diverge sharply across product and service categories, with EGAS licensing terms reshaping contractor economics by segment.
Product Type:
Crude oil volumes dominate current production while gas liquids command premium margins from petrochemical feedstock demand.
- Crude Oil:Sourced primarily from Western Desert and Gulf of Suez reservoirs at depths between 1,500 and 4,500 meters. Egyptian General Petroleum Corporation joint ventures anchor output here, though decline rates now require continuous artificial lift investment.
- Natural Gas:Zohr-scale offshore discoveries in the Mediterranean have reoriented upstream capital toward deepwater development. EGAS fiscal terms now prioritize gas-prone exploration blocks with pipeline takeaway to existing processing infrastructure.
- Natural Gas Liquids:Expanding most quickly as Egyptian refineries increase cracking capacity for petrochemical feedstock.
- Condensates:Associated production from Nile Delta gas fields supplies light hydrocarbon feedstock to domestic refiners.
Mature deployment sits with Crude Oil. Newer deployment is concentrated in Natural Gas.
Service Type:
Procurement patterns split between integrated package providers and specialized tool vendors, with performance-based contracts displacing day-rate structures.
- Drilling:Electrified rig packages now dominate Western Desert and Nile Delta concessions, replacing diesel generator sets with grid-tied power systems. Eni SpA and partners sustain 24-hour continuous campaigns through this infrastructure.
- Well Completion:Subsea engineering capabilities remain concentrated among international contractors for Mediterranean deepwater developments. Egyptian Environmental Affairs Agency discharge protocols add compliance overhead to completion design.
- Exploration:Digitalization of reservoir characterization is compressing cycle times across Nile Delta underpenetrated blocks.
- Production Optimization:Thermal stimulation and pressure maintenance deployments accelerate under flaring reduction mandates.
Integrated bundling concentrates in Drilling. Specialized procurement persists in Well Completion.
Technology:
Capital allocation splits between offshore frontier development and mature field rehabilitation, with carbon capture readiness emerging as a selection criterion.
- Offshore Platforms:Mediterranean deepwater production requires subsea tiebacks to onshore processing at Zohr and adjacent blocks. Egyptian Environmental Affairs Agency protocols impose strictest compliance timelines here due to coastal proximity.
- Onshore Facilities:Western Desert assets operate heterogeneous artificial lift and surface facility vintages that complicate digital twin deployment. Brownfield integration challenges dominate operator engineering priorities.
- Enhanced Oil Recovery:Thermal stimulation and waterflooding sustain plateau production from mature reservoirs.
- Hydraulic Fracturing:Limited application in conventional Egyptian reservoirs compared to unconventional shale plays elsewhere.
Frontier investment flows to Offshore Platforms. Rehabilitation spending concentrates in Onshore Facilities.
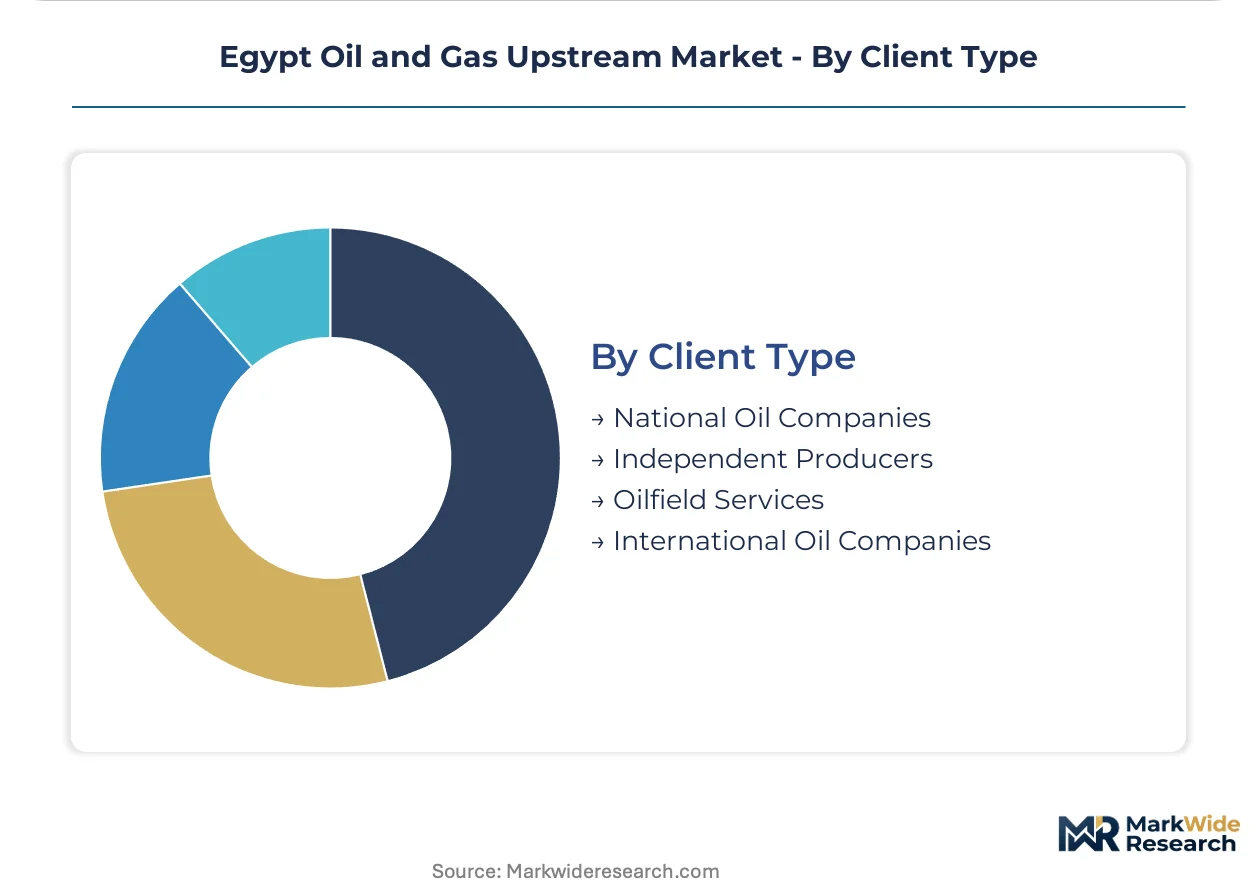
Client Type:
Contractor selection hinges on local content requirements and joint venture structuring under Egyptian General Petroleum Corporation frameworks.
- National Oil Companies:Egyptian General Petroleum Corporation anchors domestic production through joint venture structures with international partners. Concession terms mandate local content thresholds that influence equipment sourcing.
- International Oil Companies:Chevron Corporation competes for deepwater exploration acreage in Red Sea and Mediterranean concessions. These operators bring subsea production system expertise to frontier blocks.
- Independent Producers:Smaller operators focus on marginal field redevelopment and service partnerships.
- Oilfield Services:Integrated drilling and completion package providers dominate procurement, limiting price competition for specialized vendors.
Volume concentration rests with National Oil Companies. Capability investment concentrates with International Oil Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Egypt's domestic production lags behind consumption, creating persistent import dependency despite Mediterranean gas discoveries. The Nile Delta and Western Desert basins anchor upstream activity, while the Red Sea frontier remains underexplored. Sub-regional specialization drives divergent investment patterns across concession blocks.
Nile Delta
Shallow-water gas fields supply feedstock to Egyptian refineries expanding petrochemical cracking capacity. EGAS licensing rounds prioritize blocks with existing pipeline infrastructure. Damietta and Port Said clusters host gas processing facilities handling Zohr-scale offshore output.
Western Desert
Mature oil reservoirs require continuous artificial lift and waterflooding investment to combat decline rates. The Egyptian Environmental Affairs Agency mandates flaring reduction protocols that accelerate thermal stimulation deployments. Qattara Depression fields concentrate enhanced oil recovery service demand.
Gulf of Suez
Legacy offshore platforms operate heterogeneous facility vintages complicating digital twin integration. Egyptian General Petroleum Corporation joint ventures maintain plateau production through workover campaigns. Ras Gharib and Ras Shukheir terminals handle crude export logistics.
Red Sea Deepwater
Unlicensed southern offshore zones present material exploration upside for subsea production specialists. Chevron Corporation competes for frontier acreage requiring advanced drilling packages. Hurghada coastal infrastructure limits near-term development timelines.
Mediterranean Offshore
Zohr field infrastructure sustains full-field development economics across multiple deepwater blocks. Eni SpA leverages existing subsea tiebacks to onshore processing at Idku. Egyptian Environmental Affairs Agency discharge protocols impose strictest compliance timelines here due to coastal population proximity.
Egypt Oil and Gas Upstream Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Egyptian upstream procurement. Integrated service bundling concentrates drilling and completion contracts among package providers, limiting price competition for specialized tool vendors. Two strategic archetypes dominate: international majors with subsea engineering capabilities and national oil companies anchoring domestic production through joint venture structures. Competitive moves center on performance-based contracting and electrified rig package deployment.
Among Italy-based operators, Eni SpA exemplifies the integrated major archetype through its Zohr field infrastructure leverage. Egyptian General Petroleum Corporation anchors the national oil company tier through concession frameworks mandating local content thresholds. Chevron Corporation occupies a position representing deepwater frontier specialists competing for Red Sea and Mediterranean exploration acreage.
| Leading Market Players |
|---|
| Eni SpA |
| ExxonMobil Corp |
| Egyptian General Petroleum Corporation |
| Apache Corporation |
| Chevron Corporation |
| BP PLC |
| TotalEnergies SE |
| IPR Energy Group |
| Shell PLC |
| Others |
Supply & Pricing Matrix
Subsea engineering talent concentration in the Gulf of Mexico and North Sea labor pools widens pricing-tier spreads between integrated package providers and specialized tool vendors, as Egyptian operators absorb premium rates for deepwater Mediterranean deployments.
Pricing Analysis
Margin tightening in drilling services reflects performance-based contract displacement of day-rate structures across Egyptian General Petroleum Corporation joint ventures. Three-tier pricing structure across premium, standard, and economy levels segments procurement by project complexity and contractor capability depth. Price differentiation hinges on rate-of-penetration guarantees and non-productive time penalties. Independent producers exhibit highest price sensitivity, while Eni SpA-scale operators absorb premium integrated bundling for Zohr field continuity.
Supply Chain Analysis
Egyptian General Petroleum Corporation local content mandates are reshaping sourcing decisions, compelling international oil companies to establish in-country manufacturing partnerships for artificial lift equipment and surface facility components. Supply concentration sits with Italy, the United Arab Emirates, and the United States for subsea production systems and electrified rig packages. Raw material dependencies encompass high-grade steel forgings, subsea umbilical thermoplastics, and specialized drilling mud additives. Single-source vulnerability concentrates in subsea engineering capabilities for Mediterranean deepwater developments. Distribution runs through Port Said and Alexandria port clusters for offshore project logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's upstream market represents a consolidation play as integrated service bundling and performance-based contracting squeeze specialized tool vendors unable to scale package offerings.
For Market Incumbents: Anticipate margin compression from electrified rig package standardization by securing exclusive grid-tied power infrastructure partnerships across Western Desert concessions. Deepen backward integration into artificial lift manufacturing through Egyptian General Petroleum Corporation-mandated joint ventures, insulating procurement channels from international contractor competition. For New Entrants and Emerging Players: Launch via specialized well intervention services targeting mature Western Desert brownfields where legacy system integration complexity deters integrated package providers. Focus initial penetration on thermal stimulation and pressure maintenance deployments under Egyptian Environmental Affairs Agency flaring reduction mandates, leveraging technical partnerships with established artificial lift vendors. For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with subsea engineering capabilities transferable to Red Sea deepwater frontier blocks. Long-term viability rests on positioning ahead of EGAS licensing round acceleration and carbon capture readiness integration into fiscal terms. Monitor Chevron Corporation acreage competition intensity as the inflection signal for frontier block valuation resets.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Service Bundling | Consolidates drilling and completion procurement under Eni SpA-style full-field development economics. |
| Electrified Rig Deployment | Replaces diesel generator sets with grid-tied systems across Western Desert and Nile Delta concessions. |
| Local Content Partnership | Satisfies Egyptian General Petroleum Corporation mandates through in-country equipment sourcing. |
| Performance-Based Contracting | Ties contractor compensation to rate-of-penetration and non-productive time metrics. |
| Carbon Capture Readiness | Positions gas field developments for EGAS fiscal term credit integration. |
Research Methodology
Multi-period observation of EGAS licensing round outcomes, electrified rig deployment rates, and flaring reduction compliance timelines anchored the trend analysis, supplemented by interviews with upstream project managers at international oil companies, procurement leads at Egyptian General Petroleum Corporation joint ventures, subsea engineering directors, artificial lift specialists, and Egyptian Environmental Affairs Agency compliance officers. Secondary validation drew from EGAS concession documentation, Egyptian Ministry of Petroleum production statistics, SEC filings of listed operators, and regional EPC contractor project databases. Bottom-up field-level production estimates and top-down national supply-demand balances were triangulated.
Input-output matrices mapped drilling activity, completion intensity, and production optimization spending across product type, service category, technology deployment, and client archetype dimensions over the projection horizon. CAGRs were derived from elasticity-adjusted demand modeling and infrastructure investment pipeline analysis. Forecast inputs incorporated Nile Delta exploration success rates and Western Desert enhanced oil recovery deployment schedules.
Regulatory enforcement variance, EGAS fiscal term negotiation delays, and Mediterranean deepwater drilling cost inflation are the dominant revision risks to forecast assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
South Sudan Oil and Gas Downstream Market
Offshore Oil and Gas
Qatar Oil and Gas Upstream Market
Offshore Oil and Gas
Deepwater Subsea Structure Integrity Acoustic Test Platforms Market
Offshore Oil and Gas
Offshore Mooring Line Fatigue Monitoring and Test Equipment Market
Offshore Oil and Gas
Offshore Equipment Market
Offshore Oil and Gas
Oman Oil and Gas Market
Offshore Oil and Gas
Azerbaijan Oil and Gas Upstream Market
Offshore Oil and Gas
Asia Pacific Oil and Gas CAPEX Market
Offshore Oil and Gas
High Pressure Oil and Gas Separators Market
Offshore Oil and Gas
Europe LNG Bunkering Market
Offshore Oil and Gas
Subsea Production and Processing System Market
Offshore Oil and Gas
South America Oil and Gas Downstream Market
Offshore Oil and Gas
North America FLNG Market
Offshore Oil and Gas
Marine Seismic Equipment and Acquisition Market
Offshore Oil and Gas
Abyssinian Oil Market
Offshore Oil and Gas
Oil and Gas Fishing Market