
 Offshore Rental Equipment Market | 2026-2036
Offshore Rental Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Offshore Rental Equipment Market Outlook
Gulf of Mexico fabrication yards is recalibrating output schedules as deepwater project timelines stretch into longer development cycles. Motive Offshore leverages its specialized cable handling systems to anchor market position in North Sea offshore wind installation support. Atlas Copco Rental sustains compressor and power module availability across multiple basin operations through its mobile fleet architecture. Ashtead Technology competes in the subsea survey rental niche with focused sensor and ROV tooling packages.
Offshore rental equipment comprises temporarily leased mechanical, electrical, and hydraulic systems engineered for marine environments, typically rated for saltwater corrosion resistance, dynamic positioning compatibility, and load capacities exceeding 500 metric tons for heavy-lift operations. These assets serve oil and gas producers, marine contractors, and offshore wind developers seeking operational flexibility without permanent capital deployment. Lifting equipment dominates current rental revenue as decommissioning and installation projects multiply across mature basins. Survey equipment represents the fastest-expanding category, driven by seabed mapping requirements for floating offshore wind site characterization. Safety equipment maintains stable demand tied to mandatory personal protective and emergency response compliance on all manned installations.
The US Bureau of Safety and Environmental Enforcement mandates blowout preventer testing protocols that shape rental specification requirements for drilling contractors operating in federal waters. The UK's Offshore Petroleum Regulator for Environment and Decommissioning enforces asset removal timelines that directly convert into lifting and cutting equipment rental contracts. Brazil's national petroleum regulator imposes local content rules that redirect procurement toward domestically stationed rental fleets. Stakeholders must monitor regulatory calendar shifts for decommissioning deadlines, as compliance-driven rental spikes create capacity bottlenecks in specialized heavy-lift segments.
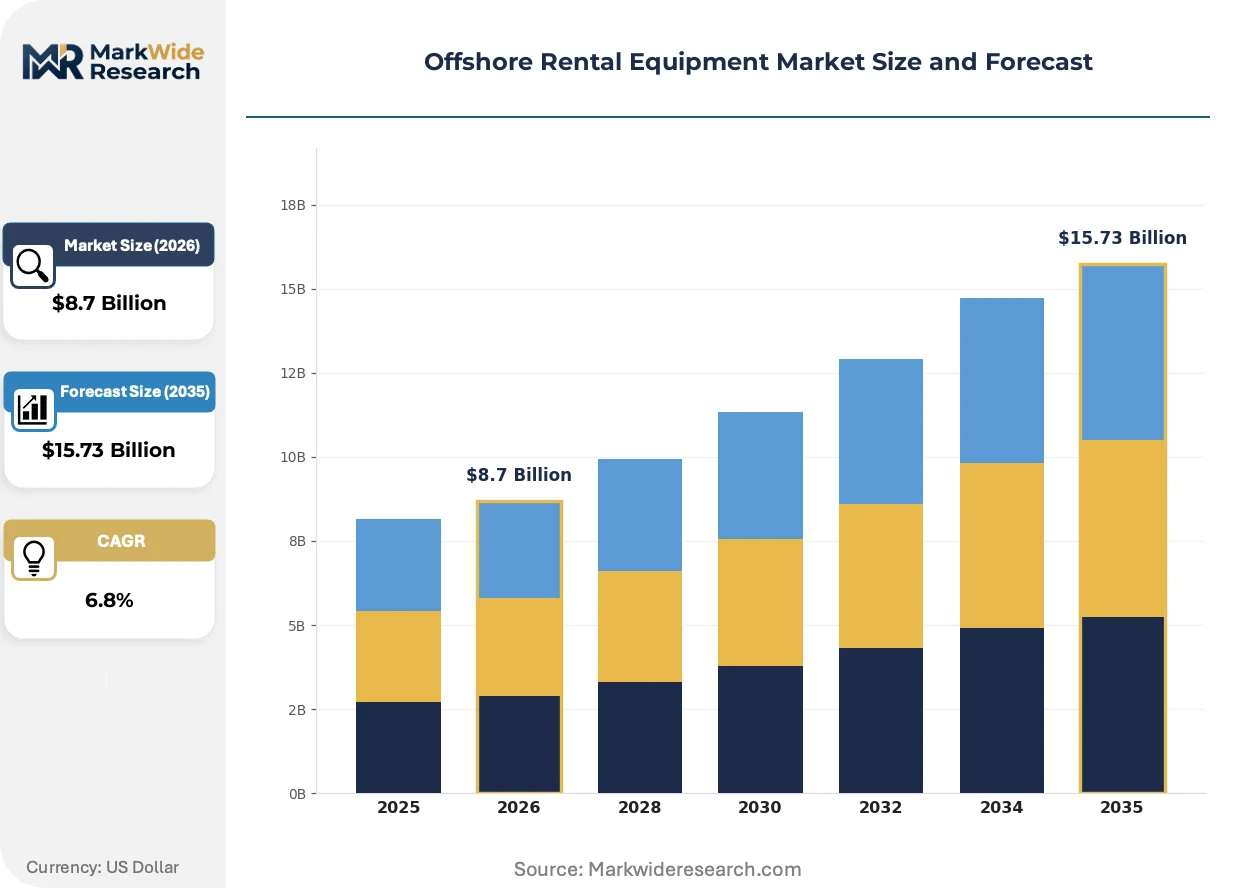
Market Dynamics
Capital discipline among oil majors and independent producers is permanently restructuring equipment procurement, converting ownership-heavy balance sheets into flexible rental obligations that transfer obsolescence risk to specialized lessors.
Growth Catalysts
- UK decommissioning mandates:The Offshore Petroleum Regulator for Environment and Decommissioning enforces strict asset removal timelines that convert directly into lifting and cutting equipment rental contracts across mature North Sea fields.
- Floating offshore wind seabed characterization:Survey equipment rentals are accelerating as developers require high-resolution geophysical mapping for mooring system design in deepwater wind sites.
- Brazil local content rules:ANVISA and national petroleum regulator requirements redirect procurement toward domestically stationed rental fleets, creating captive demand for locally registered equipment pools.
Market Restraints
- Specialized steel alloy volatility:High-strength offshore-grade steel prices fluctuate with energy-intensive smelting costs, compressing lessor margins on heavy-lift crane and jack-up system fleets.
- Gulf Coast fabrication concentration:Deepwater project fabrication capacity clusters in Louisiana and Texas yards, creating geographic supply bottlenecks when multiple operators synchronize rental returns.
- Dynamic positioning certification gaps:DP-3 rated vessel availability lags demand as classification society inspection backlogs extend equipment commissioning timelines.
Strategic Opportunities
- Norwegian offshore wind lease rounds:Emerging floating wind sites in the North Sea and Norwegian Sea create first-mover positioning for integrated installation and maintenance rental packages.
- Electrification of offshore platforms:Battery energy storage and shore-power connection systems represent new rental categories as operators pursue Scope 1 emission reductions.
- Subsea robotics-as-a-service:ROV tooling and autonomous underwater vehicle rentals bypass capital-intensive fleet ownership for inspection and intervention contractors.
Industry Challenges
- Marine technician specialization shortages:Experienced hydraulic system engineers and subsea electrical technicians command premium wages, constraining fleet expansion velocity for regional lessors.
- API and ISO dual certification complexity:Equipment must simultaneously satisfy American Petroleum Institute drilling standards and ISO 13628 subsea production system requirements, extending qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Offshore Rental Equipment Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Construction Equipment, Survey Equipment, Safety Equipment, Lifting Equipment Service Model: Installation Services, Maintenance Services, Training Services, Logistics Services Client Type: Oil & Gas Companies, Marine Contractors, Renewable Energy Firms, Research Institutions End Application: Exploration, Drilling, Installation, Decommissioning |
| Companies Covered | Motive Offshore, Oceanteam Solutions, Atlas Copco Rental, McDonough Marine Service, Maritime Developments Ltd, Ashtead Technology, STR Subsea, Stallion Infrastructure Services, Tiger Offshore Rentals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Offshore Rental Equipment Market Strategic Shifts
Digital fleet management and predictive maintenance systems are compressing equipment downtime and reshaping how rental providers price availability guarantees. Automation is penetrating traditionally labor-intensive offshore operations.
Condition-based monitoring via embedded IoT sensors is converging with cloud-based asset performance platforms. Offshore drilling contractors and wind installation vessels now demand real-time structural health data on rented cranes and tensioning systems. This convergence is compressing traditional time-based inspection intervals into continuous remote diagnostics.
The US Bureau of Safety and Environmental Enforcement mandates blowout preventer testing protocols that shape rental specification requirements for drilling contractors operating in federal waters. Equipment lessors must maintain certified BOP testing infrastructure to qualify for Gulf of Mexico contracts. Deepwater drillship operators bear the compliance burden most acutely, driving consolidation toward full-service rental providers.
Integrated service contracts now bundle equipment, personnel, and performance guarantees into single-source agreements. Traditional bareboat rentals are losing share to outcome-based arrangements where lessors assume operational risk. This model is most visible in North Sea decommissioning projects, where contractors prefer turnkey lifting and cutting solutions over equipment-only procurement.
Offshore Rental Equipment Market Segmentation
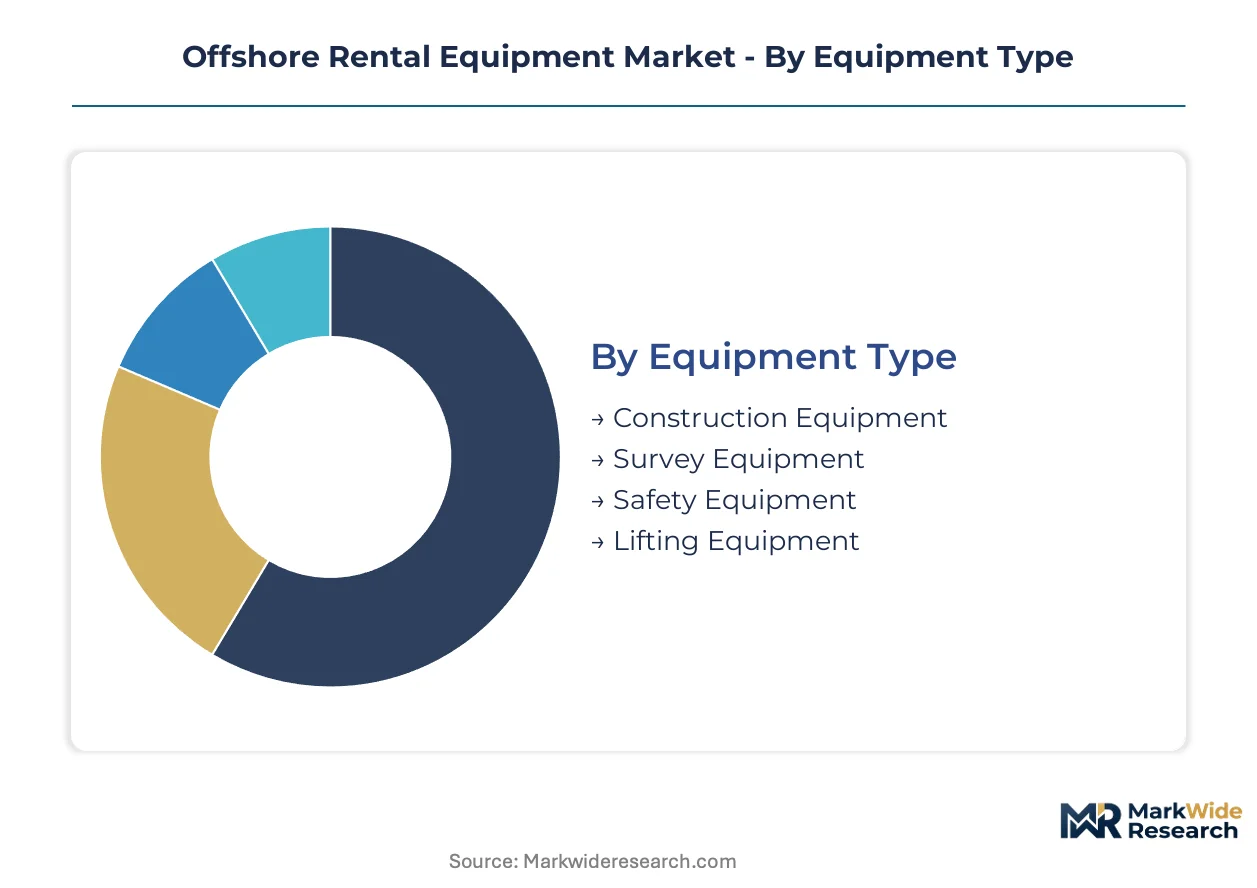
Equipment segmentation in offshore rentals determines capital allocation strategies for lessors and procurement flexibility for operators. Certification requirements, service intensity, and project lifecycle positioning vary sharply across categories, creating distinct margin profiles and competitive dynamics.
Equipment Type:
API 2C and EN 13852-1 certifications govern crane and lifting systems, while ISO 13628-8 applies to subsea survey tooling; safety equipment carries ATEX and IECEx hazardous area approvals.
- Lifting Equipment:Heavy-lift cranes, winches, and tensioning systems rated for dynamic positioning operations and loads exceeding 500 metric tons. North Sea decommissioning contractors in the UK and Norway drive contract concentration as regulatory deadlines compress project timelines.
- Survey Equipment:Multibeam echosounders, sub-bottom profilers, and magnetometer arrays for seabed characterization. Floating offshore wind developers in Brazil and Norway require high-resolution geophysical mapping for mooring system design in deepwater sites.
- Construction Equipment:Jack-up systems, pile driving hammers, and cable lay equipment for marine infrastructure installation.
- Safety Equipment:Blowout preventer test units, personal protective systems, and emergency response gear for manned platform compliance.
Lifting equipment sits at the top of the volume ranking, with survey equipment climbing the fastest.
Service Model:
Service bundling intensity correlates with project complexity — integrated contracts command premium pricing in decommissioning and floating wind installation.
- Installation Services:Turnkey equipment mobilization, deck loadout, and offshore positioning with operational risk transfer to the lessor. Marine contractors in Norway prefer single-source agreements that bundle lifting systems with marine warranty surveyors.
- Maintenance Services:Scheduled overhaul, hydraulic system refurbishment, and classification society recertification programs. UK North Sea operators require continuous availability guarantees that compress traditional time-based inspection intervals.
- Training Services:Crane operator certification, dynamic positioning familiarization, and subsea tooling competency programs.
- Logistics Services:Port coordination, heavy-haul transport, and international freight forwarding for project mobilization.
Installation services generate the highest revenue per contract, with maintenance services delivering the most predictable recurring streams.
Client Type:
Procurement sophistication varies — oil majors emphasize total cost of ownership models while renewable developers prioritize technology access without capital lock-in.
- Oil & Gas Companies:Integrated majors and independent producers seeking operational flexibility through rental obligations rather than balance-sheet ownership of specialized subsea assets.
- Marine Contractors:Installation and decommissioning specialists requiring surge capacity for project-specific equipment without fleet expansion.
- Renewable Energy Firms:Offshore wind developers with intermittent equipment needs across construction, commissioning, and maintenance phases.
- Research Institutions:Oceanographic and geoscience organizations renting survey and sampling equipment for expeditionary campaigns.
Marine contractors represent the largest addressable base, with renewable energy firms expanding most quickly.
End Application:
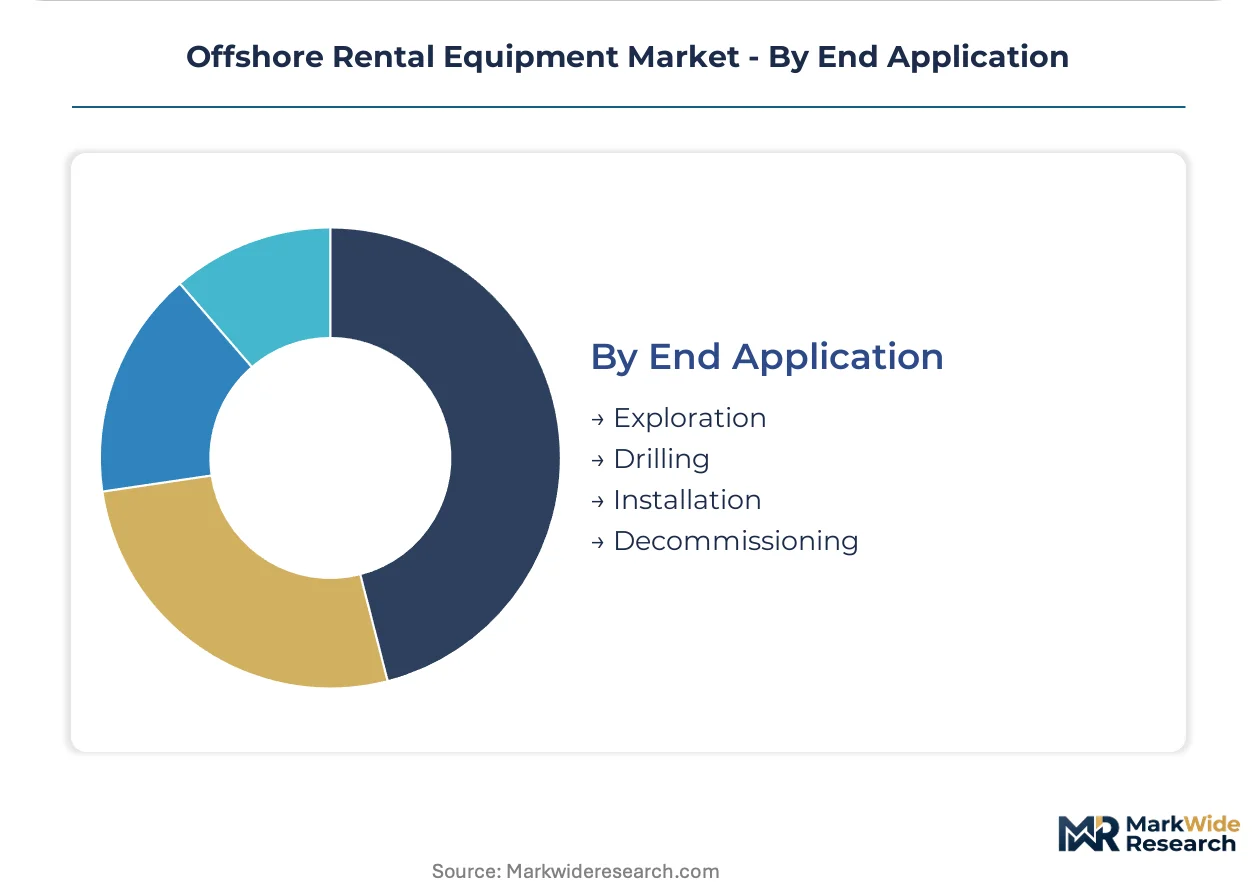
Application segments align with distinct regulatory calendars — decommissioning deadlines create demand spikes, while exploration cycles track oil price volatility.
- Decommissioning:Platform removal, well abandonment, and seabed clearance operations requiring specialized cutting and lifting rentals. The UK's Offshore Petroleum Regulator for Environment and Decommissioning enforces asset removal timelines that convert directly into equipment contracts.
- Installation:Subsea infrastructure deployment, wind turbine foundation placement, and cable lay operations. Norwegian floating wind lease rounds drive demand for integrated installation packages in the North Sea and Norwegian Sea.
- Drilling:Blowout preventer testing, riser handling, and wellhead connector systems for deepwater drillships.
- Exploration:Seismic source arrays, ocean bottom nodes, and geophysical survey spreads for frontier basin evaluation.
Decommissioning commands the highest equipment day-rates, with installation applications gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil concentrates floating wind lease activity while the United Kingdom dominates decommissioning-driven rental demand. Norway anchors subsea technology deployment. Regional regulatory calendars and basin maturity levels create divergent equipment procurement patterns across offshore markets.
Norway
Equinor-led floating offshore wind projects in the North Sea and Norwegian Sea drive integrated installation rental packages. The Norwegian Petroleum Directorate enforces stringent safety standards for subsea operations. Bergen and Stavanger host specialized lessor clusters serving North Sea contractors.
United Kingdom
North Sea platform decommissioning deadlines compress timelines for heavy-lift crane and cutting system rentals. The Offshore Petroleum Regulator for Environment and Decommissioning mandates asset removal schedules that convert directly into equipment contracts. Aberdeen maintains Europe's densest concentration of offshore rental service providers.
Brazil
Pre-salt field development and floating wind site characterization accelerate survey equipment rentals. ANVISA and national petroleum regulator local content rules redirect procurement toward domestically registered fleets. Rio de Janeiro anchors the primary rental equipment staging and certification hub.
United States
Gulf of Mexico deepwater project timelines stretch fabrication yard schedules and synchronize rental return bottlenecks. The Bureau of Safety and Environmental Enforcement mandates blowout preventer testing protocols that shape drilling contractor specifications. Louisiana and Texas yards cluster the majority of heavy-lift system mobilization capacity.
Offshore Rental Equipment Market Competitive Environment
North Sea specialists anchor one tier; Gulf of Mexico operators hold surge-capability positions. The market structures around three strategic archetypes: integrated full-service providers, niche subsea technology lessors, and regional surge-capacity operators. Consolidation pressures favor lessors with captive certification infrastructure and multi-basin fleet mobility. Dominant competitive moves include integrated service contract bundling and predictive maintenance capability investments.
Among North Sea-anchored specialists, Motive Offshore and Oceanteam Solutions exemplify the integrated service model. Atlas Copco Rental occupies a position representing mobile fleet architecture across multiple basin operations. Ashtead Technology sits within the subsea survey rental niche, anchoring sensor and ROV tooling specialization.
| Leading Market Players |
|---|
| Motive Offshore |
| Oceanteam Solutions |
| Atlas Copco Rental |
| McDonough Marine Service |
| Maritime Developments Ltd |
| Ashtead Technology |
| STR Subsea |
| Stallion Infrastructure Services |
| Tiger Offshore Rentals |
| Others |
Value Chain & Pricing Dynamics
High-strength offshore-grade steel price indices cascade through fabrication yards in Louisiana and Texas, compressing lessor margins on heavy-lift crane fleets while amplifying price stratification between API-certified premium tiers and standard equipment pools.
Pricing Analysis
Direct-to-OEM contract discounts dominate equipment procurement, with project-based rental agreements commanding premium positioning over bareboat charters. Price differentiation hinges on DP-3 dynamic positioning certification grade and integrated maintenance bundling. Cost compression in standard-tier lifting equipment is intensifying because fabrication yard backlogs synchronize rental return bottlenecks. Marine contractors exhibit highest price sensitivity, while integrated oil majors prioritize availability guarantees over rate negotiation.
Supply Chain Analysis
Dual-sourcing mandates from UK and Norwegian operators require lessors to qualify secondary fabrication partners for critical subsea components. Supply concentrates in South Korea, Norway, and Brazil for specialized steel alloys, hydraulic control systems, and subsea electrical packages. Raw material dependencies draw from high-strength offshore-grade steel, synthetic mooring fibers, and corrosion-resistant coating chemistries. Single-source vulnerability runs through DP-3 rated vessel certification backlogs at classification societies. Distribution runs through Aberdeen, Stavanger, and Rio de Janeiro staging hubs serving basin-specific demand clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
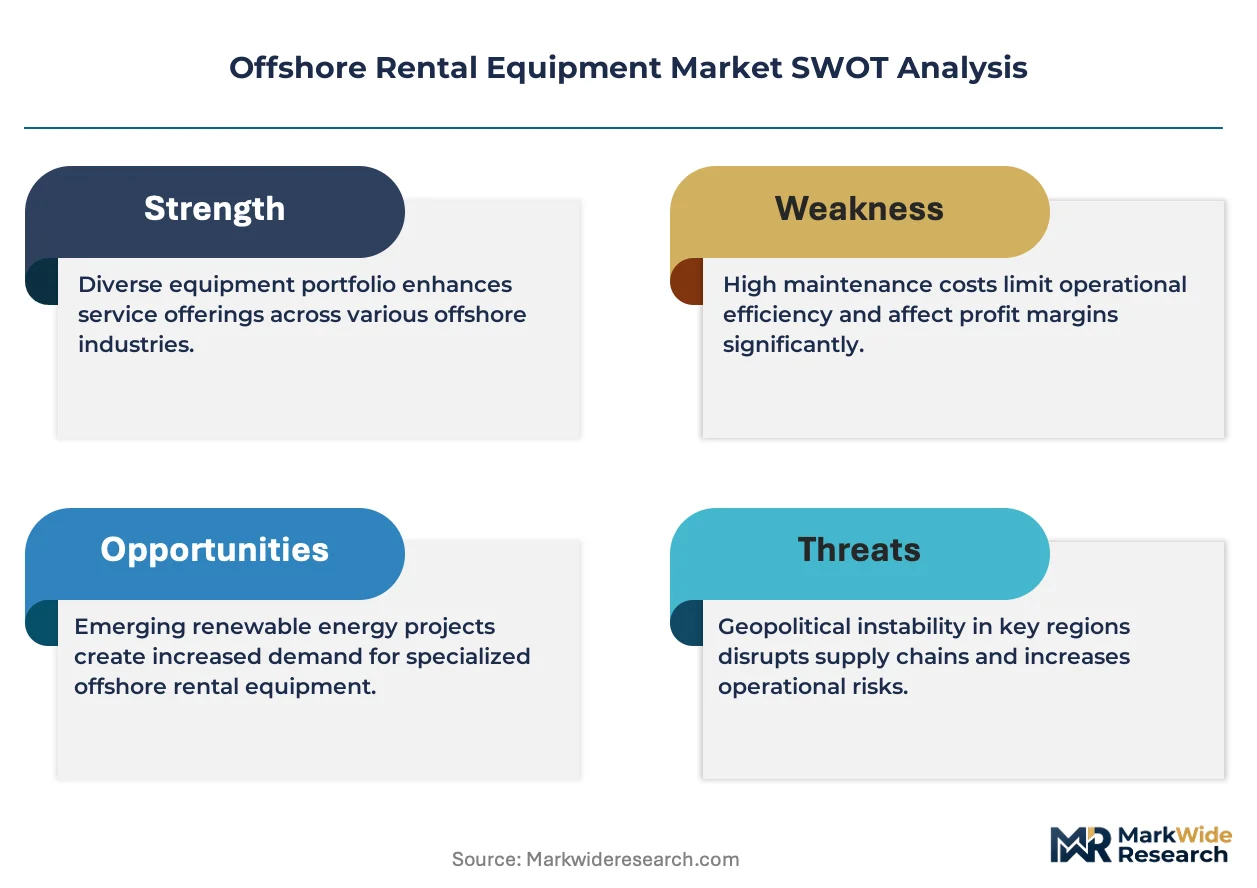
This market compounds returns through regulatory enforcement calendars, with the UK's Offshore Petroleum Regulator for Environment and Decommissioning asset removal timelines converting directly into multi-year equipment contracts.
For Market Incumbents: Cement market position through captive certification infrastructure investment and backward integration into hydraulic system refurbishment capabilities. Threat from emerging robotics-as-a-service entrants demands defensive patent positioning in autonomous underwater vehicle tooling. Priority lever centers on predictive maintenance platform deployment to compress equipment downtime and justify premium rate structures.
For New Entrants and Emerging Players: The premium-to-economy pricing gap in survey equipment rentals opens white-space positioning for mid-tier sensor package providers targeting Brazilian floating wind characterization demand. Target decommissioning support services in the UK North Sea where integrated contract bundling remains underdeveloped. Go-to-market angle should emphasize rapid mobilization guarantees through port-side equipment staging partnerships.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized lessors holding multi-basin fleet mobility and captive DP-3 certification infrastructure. Long-term viability over the coming decade rests on electrification rental category expansion and floating wind installation package integration. Signal to watch is Norwegian offshore wind lease round award velocity as inflection indicator for integrated service contract demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Infrastructure Investment | Captive API and ISO dual-certification capability locks in Gulf of Mexico drilling contractor contracts. |
| Predictive Maintenance Platform Deployment | IoT-enabled structural health monitoring compresses inspection intervals for North Sea decommissioning fleets. |
| Backward Integration into Refurbishment | In-house hydraulic system overhaul capacity insulates margins from marine technician wage inflation. |
| Electrification Rental Category Buildout | Battery energy storage and shore-power systems capture platform decarbonization procurement. |
| Floating Wind Installation Package Integration | Combined lifting, survey, and cable lay bundling secures Norwegian Sea lease round positioning. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with offshore equipment procurement managers, marine contractor project directors, classification society surveyors, and subsea engineering leads with secondary validation through Bureau of Safety and Environmental Enforcement filings, UK Offshore Petroleum Regulator decommissioning schedules, ANVISA local content registries, and customs trade data on offshore-grade steel imports. Bottom-up equipment fleet sizing and top-down contract value triangulation anchored market estimates.
Comparable historical reference periods spanning equipment utilization cycles and regulatory deadline clustering anchored the projection framework across the analysis window. Segmentation dimensions modeled encompassed equipment type, service model intensity, client procurement sophistication, and end-application regulatory calendar positioning. CAGRs derived from equipment day-rate trajectory analysis and fleet expansion velocity assumptions, with floating offshore wind seabed characterization intensity and decommissioning deadline enforcement rigor serving as sector-specific demand inputs.
Caveats apply where steel alloy price volatility, classification society inspection backlogs, or floating wind lease round delays could materially shift the outlook. Deviation in UK or Norwegian regulatory enforcement timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Subsea Production and Processing System Market
Offshore Oil and Gas
Gulf of Mexico Oil and Gas Market
Offshore Oil and Gas
Floating Storage and Regasification Unit Market
Offshore Oil and Gas
Brazil Oil and Gas Downstream Market
Offshore Oil and Gas
Africa Oil and Gas Downstream Market
Offshore Oil and Gas
Offshore Oilfield Services Market
Offshore Oil and Gas
Indonesia Oil and Gas Downstream Market
Offshore Oil and Gas
Offshore Contract Drilling Market
Offshore Oil and Gas
Global Offshore Oil and Gas Seismic Equipment and Acquisitions Market
Offshore Oil and Gas
Argentina Oil and Gas Downstream Market
Offshore Oil and Gas
Offshore Decommissioning Services Market
Offshore Oil and Gas
Global Floating LNG Power Vessel Market
Offshore Oil and Gas
Kuwait Oil and Gas Downstream Market
Offshore Oil and Gas
South America Offshore Seismic Survey Market
Offshore Oil and Gas
Subsea Equipment Market
Offshore Oil and Gas
Marine Scrubber Market