
 Africa Oil and Gas Downstream Market | 2026-2036
Africa Oil and Gas Downstream Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Oil and Gas Downstream Market Outlook
The EU Green Deal's carbon border adjustment mechanism is recalibrating fuel quality standards for African exporters serving European offtake markets. TotalEnergies leverages its integrated refining and retail network across Senegal and Côte d'Ivoire to sustain supply continuity. Dangote Petroleum Refinery & Petrochemicals anchors Nigeria's push toward refined product self-sufficiency, while Sonatrach dominates North African LPG and gasoline output from its Skikda and Arzew complexes.
Africa oil and gas downstream encompasses the refining, processing, storage, and distribution of crude oil into finished fuels and petrochemical feedstocks, with typical refinery complexity measured by the Nelson Complexity Index ranging from 2.0 for simple topping units to 12.0 for deep conversion facilities. The primary purpose is transforming imported or domestically produced crude into transportation fuels, heating oils, and chemical precursors that power industrial and consumer economies. Diesel and gasoline product categories command the largest volume shares, reflecting heavy reliance on road freight and personal vehicle ownership. Jet fuel represents the fastest-growing product segment as intra-African aviation routes multiply under liberalized air service agreements.
Nigeria's Department of Petroleum Resources enforces gasoline sulfur limits and refinery licensing standards that shape investment timelines for greenfield projects. Egypt's Environmental Affairs Agency and South Africa's National Energy Regulator coordinate emissions benchmarks that influence fuel import specifications and storage infrastructure design. Stakeholders must monitor how AfCFTA rules of origin and local content requirements interact with national subsidy regimes to determine viable entry strategies.
Market Dynamics
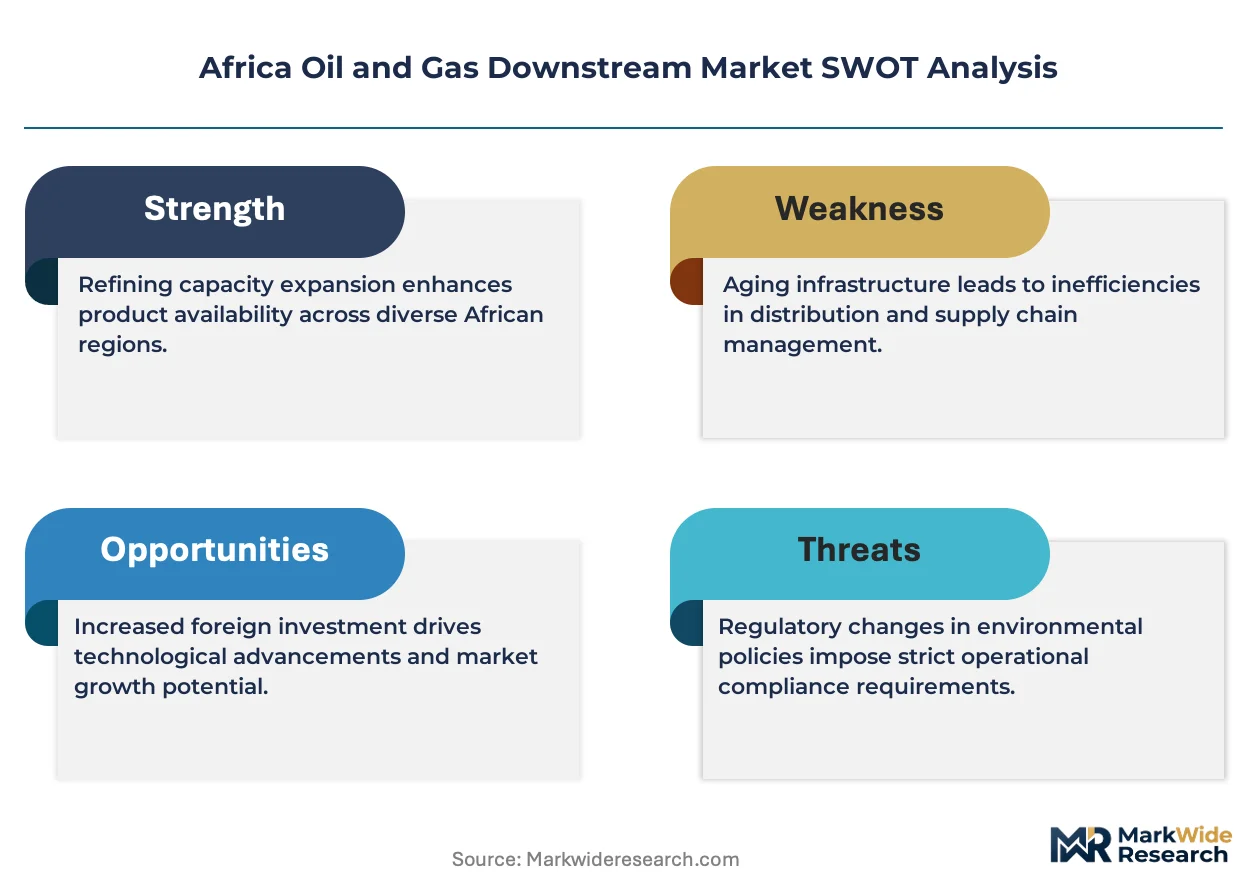
AfCFTA tariff reductions are rerouting refined product flows across West African corridors, compressing traditional coastal import dependencies while forcing inland storage infrastructure upgrades.
Growth Catalysts
- Jet fuel demand:Liberalized air service agreements under the Yamoussoukro Decision are multiplying intra-African aviation routes. Airlines are expanding fleet capacity between Lagos, Nairobi, and Addis Ababa.
- EU Green Deal carbon border adjustments:European offtake markets now require cleaner fuel specifications. Nigerian and Algerian exporters are upgrading hydrotreating capacity to maintain access.
- LPG substitution:Urban households in Ghana and Senegal are displacing charcoal and kerosene with bottled gas for cooking. Distribution networks are extending into peri-urban zones.
Market Restraints
- Crude import dependency:Most African refineries lack captive domestic supply. Freight and forex exposure from dollar-denominated crude purchases erodes margin stability.
- Simple refinery configuration:Nelson Complexity Index readings below 4.0 limit output slate flexibility. Simple topping units cannot meet evolving gasoline sulfur specifications without costly retrofits.
- Subsidy distortion:Nigeria's petrol price controls suppress wholesale margins. Private sector investment hesitates where state-set prices prevent cost recovery.
Strategic Opportunities
- East African bunkering:Djibouti and Mombasa are positioning as marine fuel hubs for Red Sea and Indian Ocean shipping lanes. Storage and blending terminals are expanding berth capacity.
- Petrochemical integration:Dangote's Lagos complex is adding polypropylene and polyethylene units. Downstream plastics feedstock supply will reduce polymer import bills.
- Renewable diesel co-processing:Hydroprocessed esters and fatty acids can substitute 5-20% of crude feedstock in existing hydrotreaters. South Africa's National Energy Regulator is reviewing biofuel blending mandates.
Industry Challenges
- Specialized refinery engineering talent:Deep conversion unit design and catalyst selection expertise concentrates with aging expatriate workforces. Local technical institutes lack hydrocracking simulation capacity.
- Product import parity pricing:Landlocked markets in Burkina Faso and Mali face delivered costs that swing with Singapore and Rotterdam benchmark volatility. Inventory hedging instruments remain underdeveloped.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Oil and Gas Downstream Market |
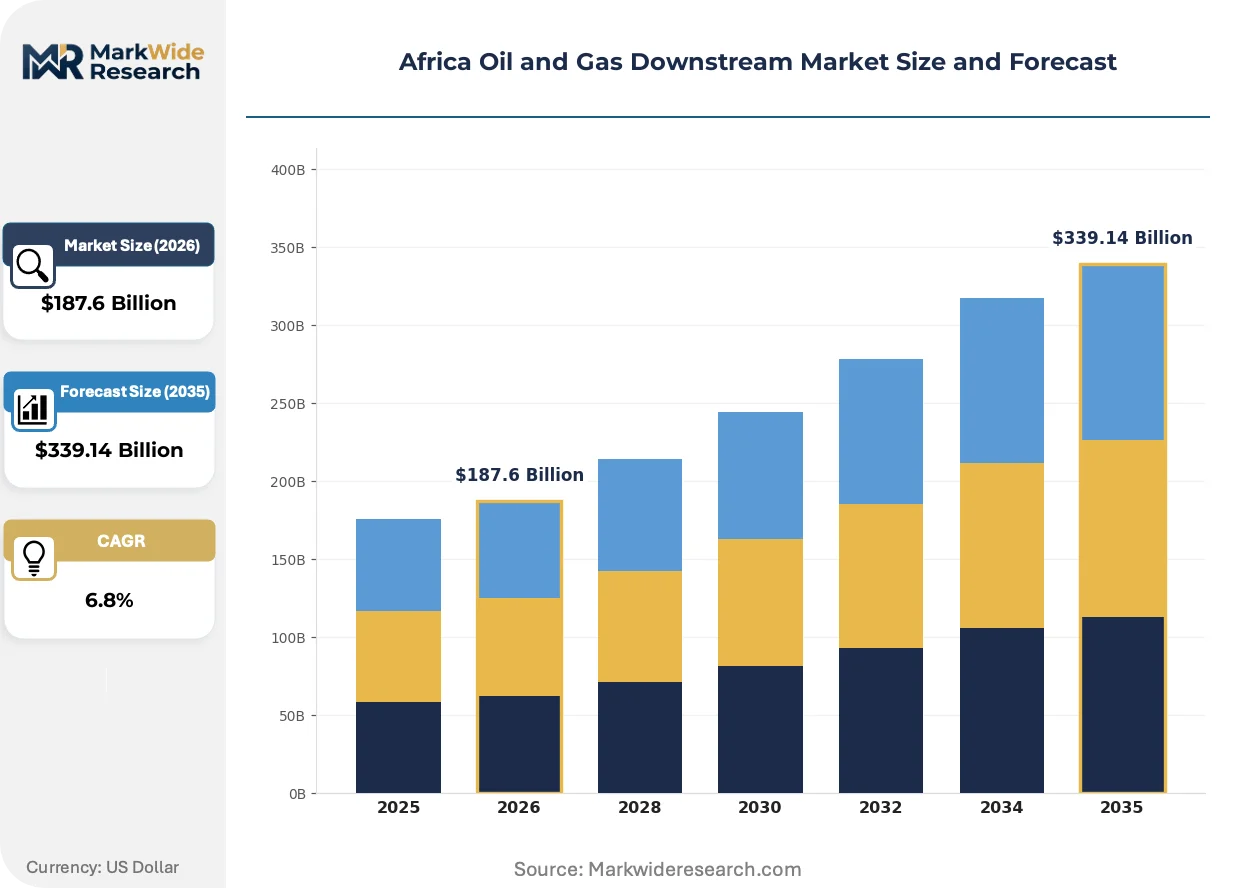
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $339.14 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline, Diesel, Jet Fuel, Liquefied Petroleum Gas Distribution Channel: Retail Pumps, Bulk Distribution, Wholesalers, Online Sales End User: Transportation, Petrochemical Industry, Residential, Industrial Storage Type: Tanks, Underground Storage, Above Ground Storage, Terminals |
| Companies Covered | TotalEnergies, Shell PLC, ExxonMobil Corporation, Nigerian National Petroleum Company Limited, Egyptian General Petroleum Corporation, Eni S.p.A, Sonatrach, PetroSA, Dangote Petroleum Refinery & Petrochemicals, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Oil and Gas Downstream Market Strategic Shifts
Digital metering and automated tank gauging are compressing working capital cycles for independent fuel marketers. Real-time inventory visibility is reshaping supply security calculations.
Modular refinery construction is expanding into remote production zones. Smaller-scale skid-mounted units with 10,000-30,000 barrel per day capacity are attracting mining and agricultural off-takers in Zambia and Mozambique. These distributed facilities reduce product haul distances from coastal import terminals.
Egypt's Environmental Affairs Agency is tightening marine fuel sulfur limits for vessels transiting the Suez Canal. Ship operators must now document compliant bunkering or face canal transit restrictions. Alexandria and Damietta storage terminals are expanding very low sulfur fuel oil blending capacity.
Fleet operators in South Africa are consolidating procurement through contracted supply agreements with integrated oil companies. Long-term offtake contracts with fixed differentials are displacing spot market purchases for logistics and mining customers. This concentration is visible in the Gauteng industrial corridor around Johannesburg.
Africa Oil and Gas Downstream Market Segmentation
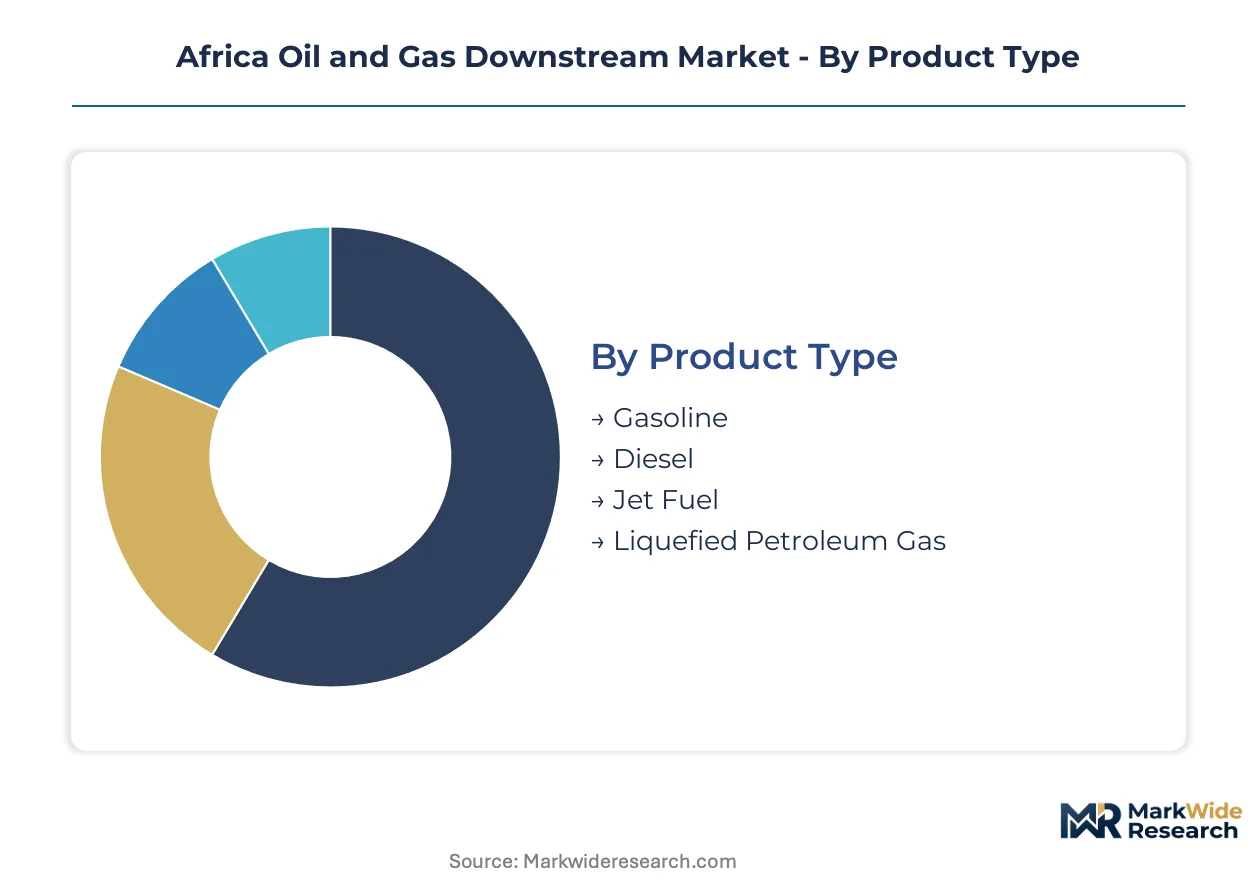
Segmentation in Africa's downstream oil and gas market reveals how product flows, channel economics, and storage infrastructure interact across vastly different operating environments. Understanding these divisions exposes where margin capture concentrates and where infrastructure gaps create competitive vulnerability.
Product Type:
Integration depth varies sharply across fuel categories, with some products moving through fully embedded supply chains while others operate in fragmented, standalone distribution networks.
- Gasoline:Blended to meet national sulfur specifications, typically 150-500 ppm across West African markets. Nigerian consumption dominates regional volume, though subsidy distortions suppress legitimate wholesale margins and incentivize cross-border smuggling into Benin and Togo.
- Diesel:Serves as the primary fuel for road freight and backup power generation, with demand concentrating in mining corridors and urban logistics hubs. Dangote's Lagos refinery is displacing Atlantic basin imports with domestically produced 50 ppm ultra-low sulfur diesel.
- Jet Fuel:Supplied through airport hydrant systems or into-plane contractors at major hubs. Ethiopian Airlines and Kenya Airways procurement volumes anchor East African demand.
- Liquefied Petroleum Gas:Distributed via cylinder retail networks and bulk truck delivery to industrial accounts. Ghana's LPG promotion program is accelerating household penetration in Accra and Kumasi.
Volume placements concentrate in diesel; the faster expansion belongs to LPG as urban households substitute bottled gas for solid fuels.
Distribution Channel:
Channel selection maps directly onto customer scale and creditworthiness, with integrated majors controlling high-throughput routes while independents serve fragmented retail.
- Retail Pumps:Branded service stations with automated tank gauging and wetstock management systems. TotalEnergies and Vivo Energy maintain network density advantages in Senegal, Côte d'Ivoire, and Kenya.
- Bulk Distribution:Direct tanker truck delivery to mining, manufacturing, and agricultural off-takers bypassing retail markup. Contracts typically run 12-36 months with volume-commitment clauses.
- Wholesalers:Independent marketers purchasing ex-refinery or import parity and reselling to smaller retailers. Working capital intensity limits viable participants to established trading houses with forex hedging capacity.
- Online Sales:Emerging digital platforms connecting fleet operators with certified fuel suppliers, particularly visible in South Africa's Gauteng logistics corridor.
Margin capture favors bulk distribution; the steepest expansion trajectory sits with online sales as fleet procurement digitizes.
End User:
End-use segmentation exposes how fuel quality specifications, delivery reliability requirements, and price sensitivity diverge across economic sectors.
- Transportation:Road freight operators consume diesel in 10,000+ liter increments, demanding consistent supply security across corridor routes. Nigerian haulage fleets face payment delays from cargo owners that strain fuel credit terms.
- Petrochemical Industry:Naphtha and feedstock buyers require dedicated pipeline or rail connections to integrated complexes. Dangote's polypropylene units will absorb increasing domestic refinery output.
- Residential:Kerosene and LPG demand tracks urbanization and electrification gaps. Dakar and Abidjan peri-urban zones show rapid cooking fuel transition.
- Industrial:Cement, steel, and food processing plants operate captive power generation running on diesel or fuel oil. Egypt's industrial zones around Alexandria and Suez anchor heavy fuel oil offtake.
Demand scale concentrates in transportation; industrial applications are climbing the fastest as manufacturing capacity expands.
Storage Type:
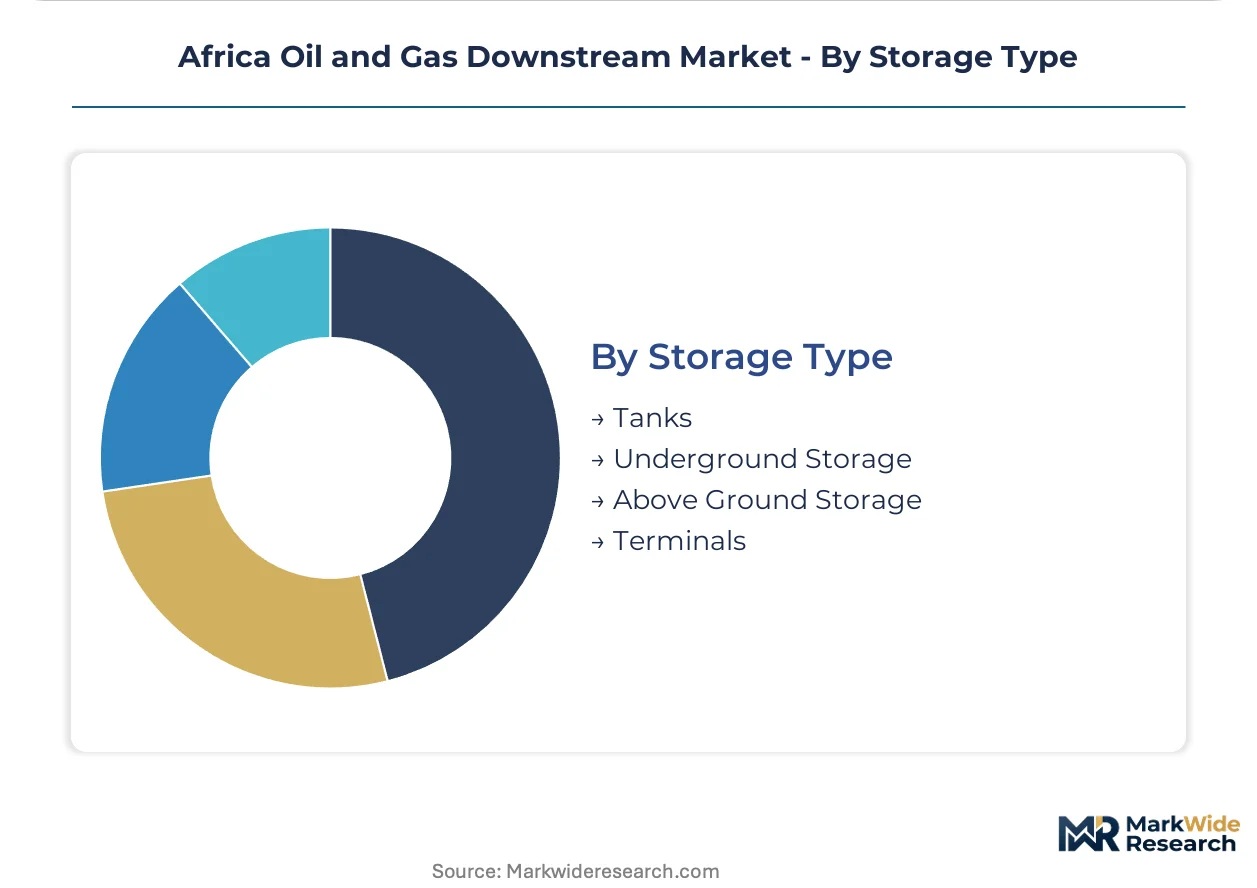
Storage configuration determines working capital efficiency, product security, and regulatory compliance burden across downstream operations.
- Tanks:Horizontal cylindrical vessels for intermediate product holding at depots and terminals. Nigerian independent marketers operate tank farms in Apapa and Calabar with combined capacity exceeding 500 million liters.
- Underground Storage:Buried tanks at retail stations reducing fire risk and land use footprint. South Africa's petroleum licensing regime mandates double-wall construction and leak detection systems.
- Above Ground Storage:Large-capacity fixed roof or floating roof tanks at import terminals and refinery tank farms. Djibouti's Horizon Terminal expansion added 410,000 cubic meters for regional bunkering supply.
- Terminals:Integrated storage, blending, and vessel loading facilities at coastal hubs. Mombasa's Kipevu Oil Terminal handles 80% of Kenya's petroleum imports.
Capacity concentration sits with terminals; above ground storage is gaining share fastest as coastal import dependency persists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Africa's downstream sector displays a stark production-consumption divide: North African refineries export surplus volumes while Sub-Saharan markets absorb Atlantic basin imports to cover structural deficits. This imbalance shapes infrastructure investment patterns across the continent.
Nigeria
Dangote's Lagos refinery complex is displacing gasoline and diesel imports that previously supplied West African markets. The Department of Petroleum Resources enforces gasoline sulfur limits and licensing standards that determine greenfield project timelines. Apapa and Calabar tank farms anchor independent marketer storage capacity exceeding 500 million liters combined.
Egypt
Alexandria and Suez industrial zones consume heavy fuel oil for captive power generation at cement and steel plants. The Environmental Affairs Agency tightened marine fuel sulfur limits for Suez Canal transits, forcing vessel operators to document compliant bunkering. Damietta storage terminals are expanding very low sulfur fuel oil blending capacity to capture this regulatory shift.
South Africa
Gauteng's logistics corridor around Johannesburg concentrates fleet procurement through contracted supply agreements with integrated oil companies. The National Energy Regulator coordinates emissions benchmarks that influence fuel import specifications and storage infrastructure design. Coastal import dependency persists through Durban and Cape Town terminals.
Algeria
Skikda and Arzew refining complexes dominate North African LPG and gasoline output for regional export markets. Sonatrach leverages integrated production to supply Mediterranean offtake agreements. Hydrotreating capacity upgrades are progressing to maintain European market access under EU Green Deal carbon border adjustments.
Kenya
Mombasa's Kipevu Oil Terminal handles 80 percent of national petroleum imports, serving as the gateway for East African bunkering demand. Ethiopian Airlines and Kenya Airways procurement volumes anchor regional jet fuel consumption. Djibouti and Mombasa are positioning as marine fuel hubs for Red Sea and Indian Ocean shipping lanes.
Africa Oil and Gas Downstream Market Competitive Environment
The competitive structure tilts toward integrated national oil companies and multinational majors with captive refining and retail networks. Market concentration varies sharply: North African markets display oligopolistic supply patterns around state-controlled complexes, while West African downstream segments host fragmented independent marketers competing on working capital efficiency. Two archetypes dominate: vertically integrated majors controlling import terminals and retail networks, and specialized storage operators monetizing tank farm capacity. Capacity expansion and strategic partnerships constitute the primary competitive moves, with players securing long-term offtake contracts to lock in volume commitments.
Among integrated majors, TotalEnergies and Shell PLC exemplify the network-density archetype through branded service station portfolios across Senegal, Côte d'Ivoire, and Kenya. Dangote Petroleum Refinery & Petrochemicals occupies a distinctive position as a domestic refinery operator integrating into polypropylene and polyethylene production. State-controlled entities including Nigerian National Petroleum Company Limited and Egyptian General Petroleum Corporation represent the national champion archetype, balancing commercial operations with supply security mandates.
| Leading Market Players |
|---|
| TotalEnergies |
| Shell PLC |
| ExxonMobil Corporation |
| Nigerian National Petroleum Company Limited |
| Egyptian General Petroleum Corporation |
| Eni S.p.A |
| Sonatrach |
| PetroSA |
| Dangote Petroleum Refinery & Petrochemicals |
| Others |
Value Chain & Pricing Dynamics
Fleet procurement concentration in South Africa's Gauteng corridor anchors contract-based long-term offtake as the dominant pricing model. State subsidy regimes in Nigeria distort wholesale gasoline margins, compressing legitimate trading economics while amplifying cross-border arbitrage incentives.
Pricing Analysis
Margin tightening in retail gasoline traces to Nigeria's petrol price controls and the Dangote refinery's displacement of Atlantic basin imports. Three-tier pricing structure across premium, standard, and economy levels differentiates sulfur specifications and delivery reliability. Cost-down pressure on independent marketers accelerates because forex exposure from dollar-denominated crude purchases erodes working capital efficiency. Industrial bulk buyers exhibit lowest price sensitivity; peri-urban LPG households face highest.
Supply Chain Analysis
Direct-to-refinery channels handle national oil company procurement volumes across North African state complexes. Geographic supply concentrates in Nigeria, Egypt, and Algeria as refining hubs, with South Africa and Kenya as coastal import terminals. Feedstock dependencies rest on Brent-linked crude cargoes, hydrotreating catalysts, and specialized engineering services. Single-source vulnerability sits with aging expatriate workforces for deep conversion unit design. Distribution runs through coastal import terminals, inland tank farms, and retail station networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Downstream players are racing to secure captive refining capacity and polypropylene integration as the decisive upstream lever. Control over import terminal access and storage infrastructure determines margin capture in fragmented West African markets.
For Market Incumbents: Acquire coastal storage terminal capacity to lock in import parity economics before Dangote's full ramp displaces Atlantic basin volumes. Integrate backward into hydrotreating catalyst supply chains to hedge forex exposure on specialty inputs. State subsidy policy shifts and modular refinery entrants in Zambia and Mozambique threaten established margin structures. For New Entrants and Emerging Players: Enter via peri-urban LPG cylinder distribution in Ghana and Senegal where household substitution from charcoal creates penetrable white space. Target East African bunkering infrastructure at Djibouti and Mombasa as marine fuel hubs for Red Sea traffic. Digital fleet procurement platforms in South Africa's logistics corridor offer the clearest go-to-market angle for technology-enabled supply aggregation. For Investors and Strategic Acquirers: The window for entry favors storage terminal operators with berth expansion capacity and blending infrastructure. Long-term viability hinges on positioning for EU Green Deal carbon border adjustments and AfCFTA tariff harmonization. Watch hydrotreating upgrade announcements at Algerian and Egyptian complexes as the signal for European offtake access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Dangote's Lagos complex anchors Nigeria's refined product self-sufficiency push. |
| Backward Integration | Sonatrach's Skikda upgrades secure European market access under carbon border rules. |
| Long-term Supply Agreement | Ethiopian Airlines procurement volumes anchor East African jet fuel demand. |
| Joint Venture | TotalEnergies leverages retail network density across Senegal and Côte d'Ivoire. |
| Green Certification Program | Egypt's Environmental Affairs Agency marine sulfur limits reshape bunkering infrastructure. |
Study Parameters
Trade statistics from national customs authorities, refinery throughput disclosures from state oil companies, and AfCFTA tariff schedule documentation formed the secondary backbone. Primary interviews with fuel supply specialists, refinery operations managers, independent storage terminal operators, and fleet procurement directors validated demand assumptions. Bottom-up and top-down triangulation cross-checked product flow estimates against import parity pricing models.
Bottom-up modeling built volume projections from refinery capacity additions, product slate yields, and end-use consumption patterns across transportation, industrial, and residential segments. Top-down verification anchored aggregate market sizing to macroeconomic fuel intensity benchmarks and regional GDP trajectories. CAGRs were derived from regression analysis of historical consumption elasticities and infrastructure investment pipelines. Nelson Complexity Index thresholds and sulfur specification timelines served as industry-specific forecast inputs.
Revisions become necessary when subsidy regime changes, refinery commissioning delays, or EU carbon border adjustment enforcement timelines materialize differently than modeled. Forecasts reflect documented assumptions regarding AfCFTA implementation pace and crude price corridor stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Gulf of Mexico Oil and Gas Market
Offshore Oil and Gas
Gabon Oil and Gas Downstream Market
Offshore Oil and Gas
Iran Oil and Gas Downstream Market
Offshore Oil and Gas
Uzbekistan Oil and Gas Upstream Market
Offshore Oil and Gas
South Sudan Oil and Gas Market
Offshore Oil and Gas
United Arab Emirates Oil and Gas Upstream Market
Offshore Oil and Gas
East Africa Oil and Gas Upstream Market
Offshore Oil and Gas
United Arab Emirates Oil and Gas Market
Offshore Oil and Gas
Asia-Pacific Floating Production Systems Market
Offshore Oil and Gas
Offshore Decommissioning Services Market
Offshore Oil and Gas
Europe Offshore Energy Market
Offshore Oil and Gas
Uzbekistan Oil and Gas Downstream Market
Offshore Oil and Gas
India Oil and Gas Downstream Market
Offshore Oil and Gas
Equatorial Guinea Oil and Gas Downstream Market
Offshore Oil and Gas
Asia-Pacific Offshore Energy Market
Offshore Oil and Gas
Kuwait Oil and Gas Downstream Market