
 AC Coupled Solar Battery System Market | 2026-2036
AC Coupled Solar Battery System Market Size, Share, and Industry Trends Forecast 2026-2036
AC Coupled Solar Battery System Market Insights
A capital-intensity divergence between vertically integrated battery manufacturers and modular inverter specialists is reorganizing competitive tiers in the AC coupled solar battery system market. Tesla leverages its integrated cell-to-system manufacturing to control cost structures across residential and utility-scale deployments. SMA Solar Technology anchors European market presence through decades of inverter engineering heritage and established certification pathways. Enphase Energy differentiates via microinverter architecture that simplifies retrofit installations on existing solar arrays.
An AC coupled solar battery system connects energy storage to the alternating-current side of a solar installation through a separate grid-tied battery inverter, typically operating at 400V three-phase or 230V single-phase with power ratings from 3 kW to 20 kW for residential applications. The architecture preserves existing solar inverters while adding storage capability, making it the dominant retrofit pathway for the millions of households that installed solar PV without batteries during prior subsidy eras. LFP chemistry now leads technology segmentation due to superior cycle life and thermal stability versus NMC alternatives, though NMC retains share in space-constrained commercial installations where energy density matters more. Residential end users represent the deepest margin pool as homeowner willingness to pay for energy independence and backup power exceeds price sensitivity in utility procurement, where AC coupled systems compete against direct-current alternatives in greenfield projects.
FCC interconnection standards in the United States, CE marking and IEC 62109 safety requirements in Europe, and AS/NZS 4777 grid connection rules in Australia collectively shape product certification costs and market access timelines for AC coupled system vendors. California's NEM 3.0 tariff structure and the European Union's Electricity Market Reform are accelerating self-consumption business models that favor AC coupled retrofits over full system replacements. Stakeholders must monitor evolving inverter efficiency mandates and battery recycling regulations as these rules will determine which technology configurations qualify for installation incentives and grid services revenue streams.
Market Dynamics
The AC coupled solar battery system market is being fundamentally restructured by the retrofit imperative, as millions of existing solar PV installations without storage capacity create a locked-in customer base seeking battery augmentation without inverter replacement.
Growth Catalysts
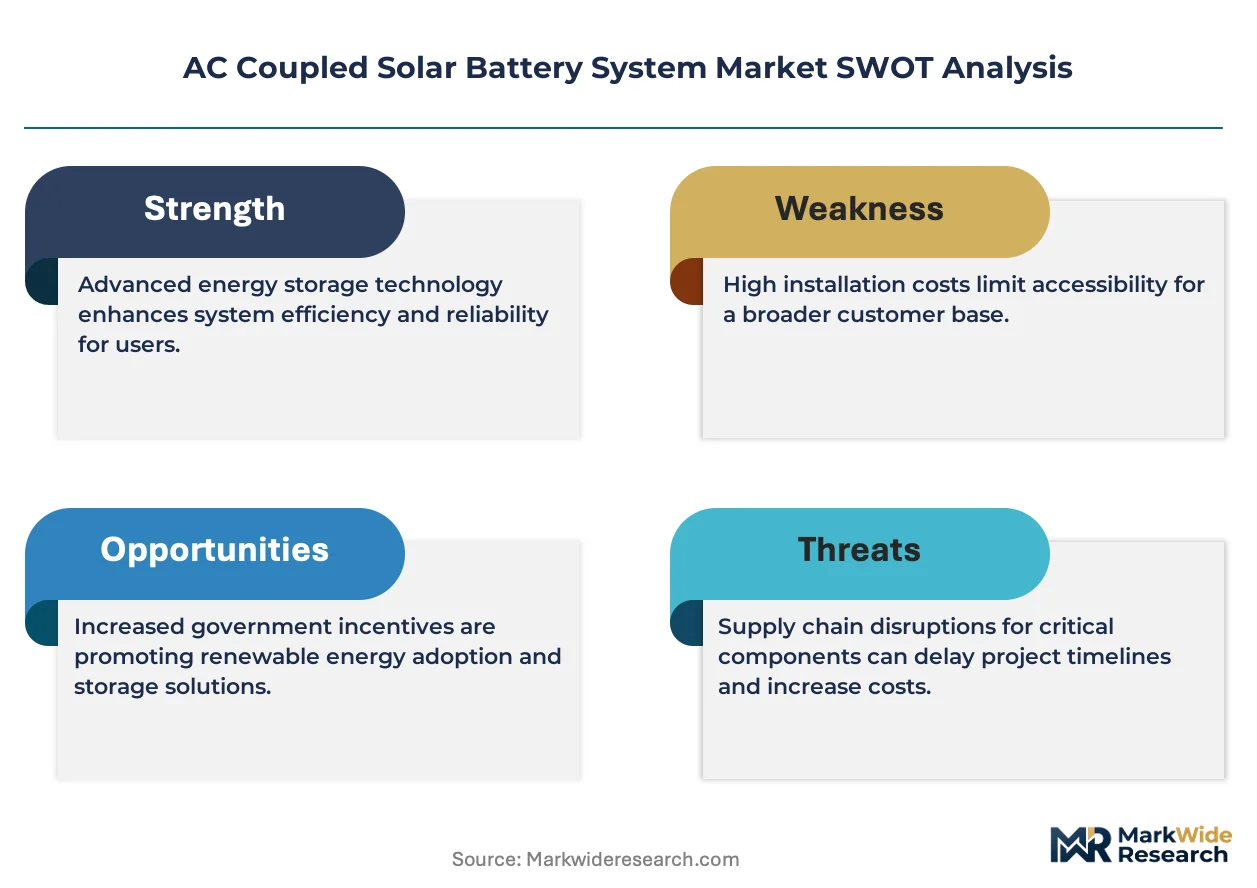
- California NEM 3.0 tariff collapse:Slashed net metering compensation rates force households toward self-consumption optimization through AC coupled retrofits rather than grid export dependency.
- Australian sunbelt tariff economics:Queensland and South Australia combine high retail electricity rates with mature rooftop solar penetration, creating ideal conditions for battery retrofits.
- LFP chemistry maturation:Superior cycle life and thermal stability versus NMC alternatives now dominates residential technology segmentation and reduces system lifetime cost.
Market Restraints
- Grid interconnection friction:FCC Part 15 and IEEE 1547 compliance timelines in the United States extend product certification cycles by six to eighteen months.
- Semiconductor supply concentration:Power electronics manufacturing clusters in Taiwan and South Korea create vulnerability to geopolitical disruption.
- DC-coupled greenfield competition:New solar-plus-storage installations increasingly favor direct-current architectures with higher round-trip efficiency.
Strategic Opportunities
- Spanish residential retrofit wave:Post-sun-tax regulatory environment and high solar penetration create underexploited battery augmentation demand.
- Virtual power plant aggregation:AC coupled systems with grid-forming inverters enable household participation in frequency regulation and peak shaving services.
- Installer channel consolidation:National electrical contractors are acquiring regional solar installers to capture recurring service revenue from battery retrofits.
Industry Challenges
- Legacy inverter compatibility mapping:Hundreds of solar inverter models across fifteen years of installations require individualized integration protocols.
- Certification cost escalation:AS/NZS 4777.2:2020 grid connection rule revisions in Australia force expensive retesting for battery inverter compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AC Coupled Solar Battery System Market |
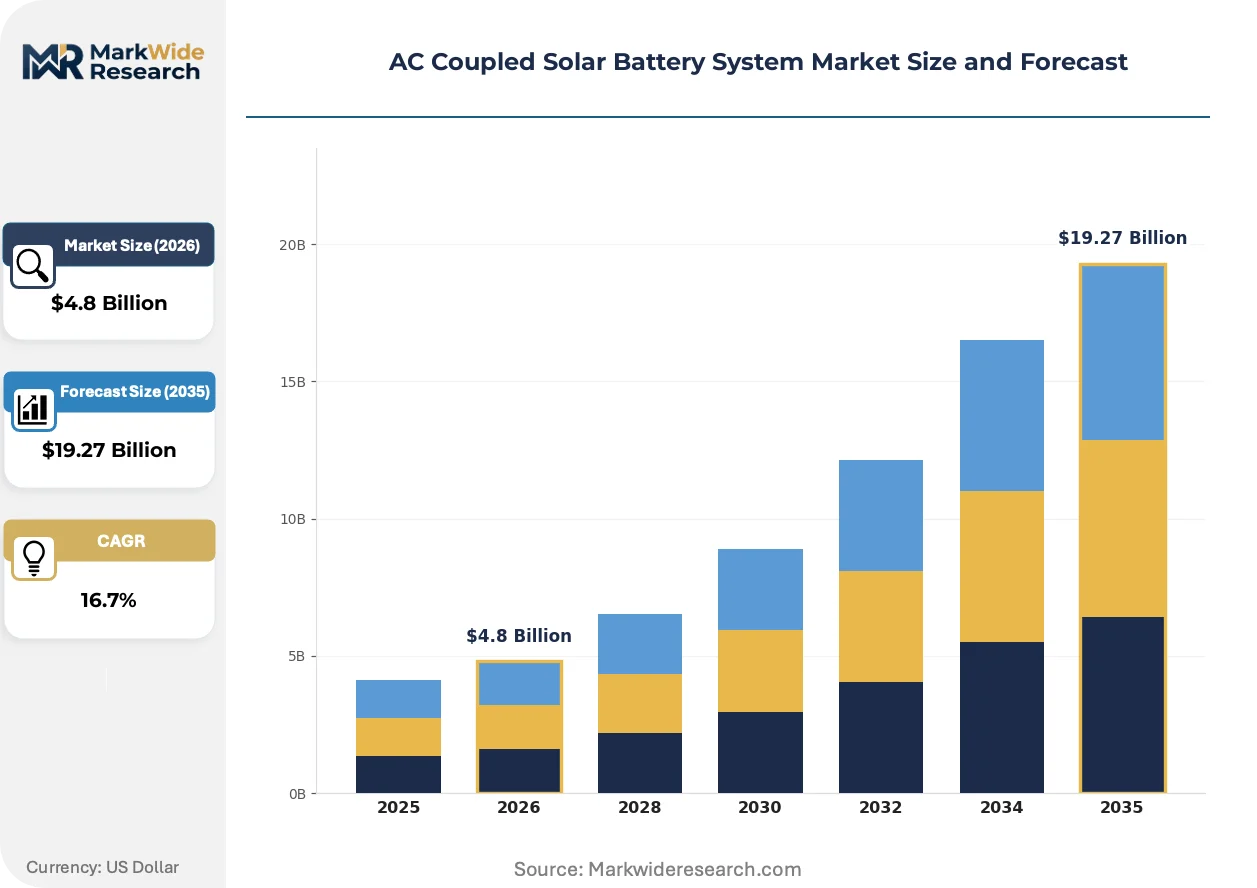
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
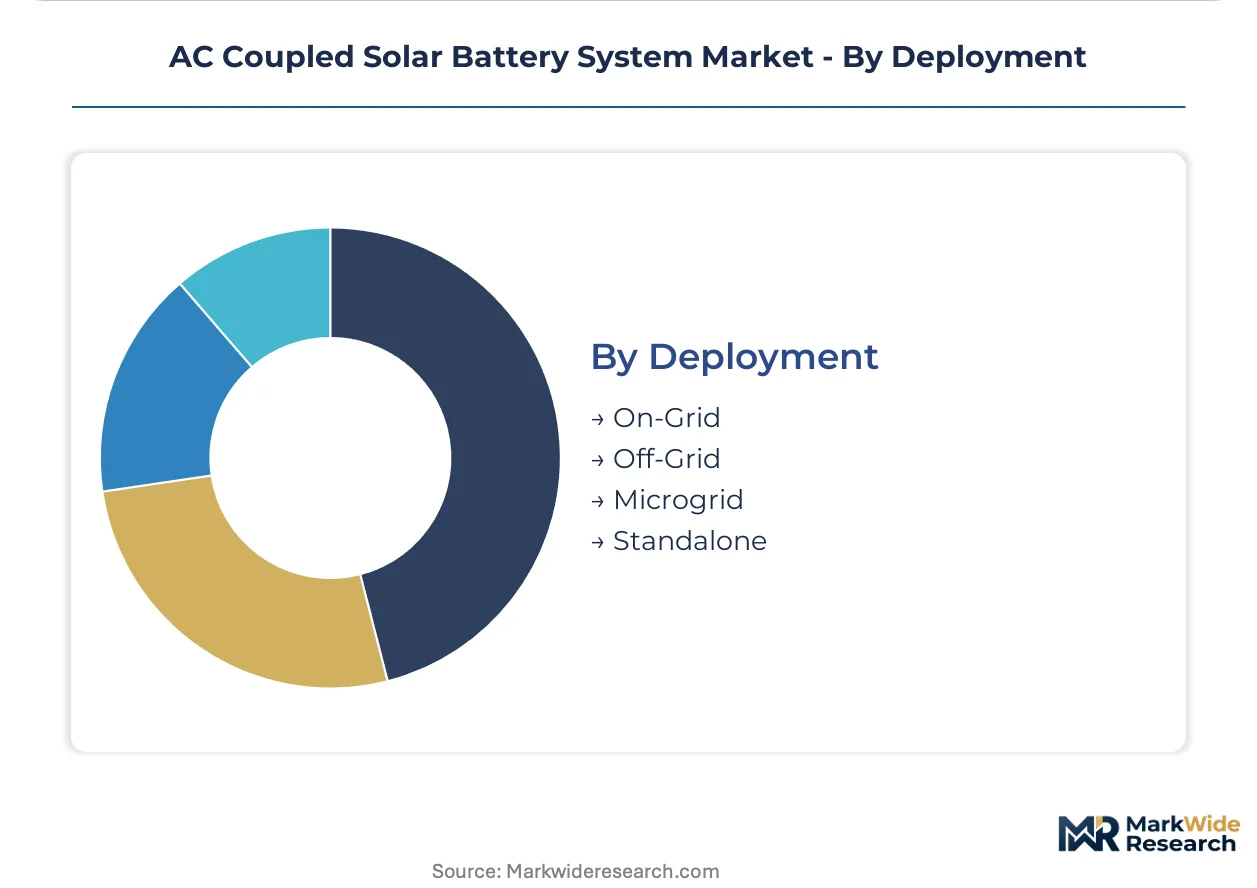
| Segmentation | Product Type: Inverter Systems, Storage Solutions, Hybrid Systems, Smart Controllers Technology: LFP, NMC, Lead-Acid, Flow Batteries End User: Residential, Commercial, Industrial, Utility Deployment: On-Grid, Off-Grid, Microgrid, Standalone |
| Companies Covered | Tesla, SMA Solar Technology, Sungrow Power Supply, Enphase Energy, Huawei Technologies, LG Energy Solution, SolarEdge, Sonnen, Alpha ESS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AC Coupled Solar Battery System Market Trends and Innovations
Technology convergence and regulatory recalibration are compressing installation timelines while elevating performance requirements for AC coupled systems. Three developments are commanding strategic attention.
Bi-directional EV charging hardware is supplanting standalone residential battery inverters in early-adopter segments. Vehicle-to-home capability allows electric vehicles to function as mobile storage assets, reducing the economic case for fixed battery retrofits among dual-asset households. Automakers including Ford and Hyundai are bundling this functionality with new EV sales, compressing addressable market scope for traditional AC coupled battery vendors.
REACH substance restrictions and the EU Battery Regulation are mandating recycled content minimums and supply chain due diligence for energy storage systems sold in Europe. Industrial consequence includes forced restructuring of cell sourcing contracts and accelerated investment in European battery recycling infrastructure. Residential system vendors serving Germany and Spain face the steepest compliance cost escalation as certification documentation requirements expand.
Homeowner procurement behavior is fragmenting between price-optimized web-direct channels and full-service installer relationships. The segment being disrupted is the traditional solar specialty retailer, replaced by electrical wholesalers adding battery SKUs and direct-to-consumer platforms with remote system design tools. This shift is most visible in Australia's mature markets, where online configurators now handle thirty percent of residential battery inquiries without site visits.
AC Coupled Solar Battery System Market Segmentation
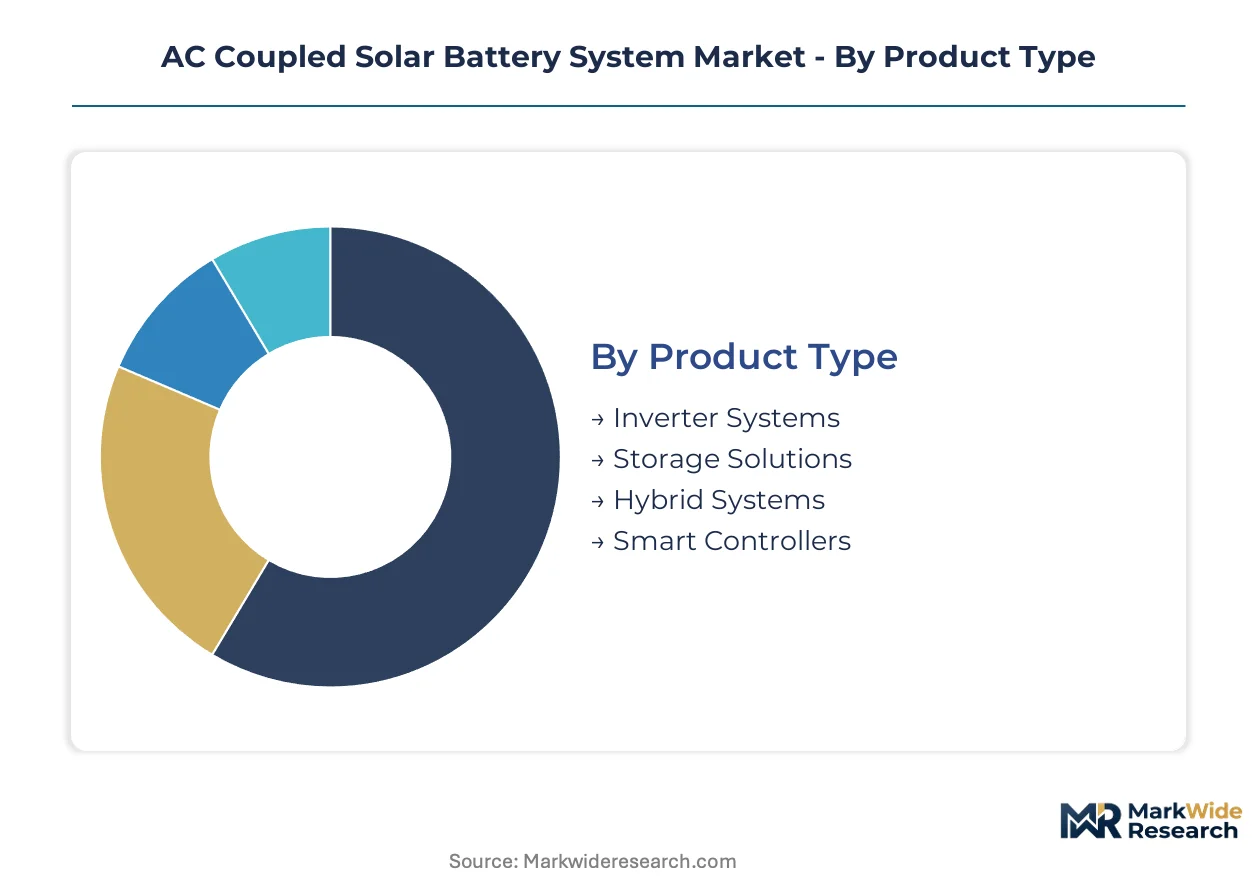
Segmentation in the AC coupled solar battery system market reveals how retrofit economics and installation channel preferences reshape product positioning across customer tiers. Channel strategy varies sharply between residential direct-to-consumer platforms and utility-scale procurement frameworks.
Product Type:
Inverter Systems flow predominantly through electrical wholesaler channels, while Storage Solutions concentrate in installer-direct relationships where site assessment drives specification.
- Inverter Systems:Grid-tied battery inverters operating at 230V single-phase or 400V three-phase convert DC battery output to AC for household consumption. Demand clusters in German and Australian retrofit markets where homeowners preserve existing solar inverters. NEM 3.0 self-consumption economics in California accelerate specification of 5-10 kW residential units.
- Storage Solutions:Battery modules with integrated battery management systems and thermal management enclosures. Australian sunbelt states and Spanish residential post-sun-tax environments dominate procurement volumes as homeowners seek 10-15 kWh usable capacity for tariff arbitrage.
- Hybrid Systems:Pre-integrated inverter-battery combinations reduce installation labor and commissioning complexity for electrical contractors entering solar retrofits.
- Smart Controllers:Energy management software and hardware enabling virtual power plant aggregation and automated self-consumption optimization.
By volume, Storage Solutions leads. By growth pace, Smart Controllers are expanding most quickly.
Technology:
Cost tier stratification separates premium chemistry investments from budget-conscious procurement, with thermal stability and cycle life determining residential versus commercial positioning.
- LFP:Lithium iron phosphate cells deliver 6,000+ cycle life and superior thermal runaway resistance versus alternatives. Residential end users in Germany and Australia pay premiums for 15-year operational lifespans and reduced fire insurance complications.
- NMC:Nickel manganese cobalt chemistry offers higher energy density per kilogram. Space-constrained commercial installations in urban California and Spanish commercial retrofits specify NMC where footprint restrictions override cycle life economics.
- Lead-Acid:Flooded and sealed lead-acid batteries serve off-grid rural applications with lowest capital entry points.
- Flow Batteries:Vanadium redox systems enable 20+ year calendar life for utility-scale long-duration storage.
By installed base, LFP dominates. By application breadth, NMC retains commercial relevance.
End User:
Customer type determines margin structure and sales cycle length, with residential homeowners showing highest willingness to pay for energy independence and backup power.
- Residential:Single-family and multi-family households retrofitting battery storage onto existing rooftop solar arrays. Australian Queensland and South Australia lead volume, with California NEM 3.0 households driving fastest specification growth for self-consumption optimization.
- Commercial:Small and medium enterprises seeking demand charge reduction and backup power for critical operations. Spanish commercial buildings with high solar penetration represent underexploited retrofit potential.
- Industrial:Manufacturing facilities and warehouses with large roof areas and high electricity consumption.
- Utility:Grid-scale storage projects procured through competitive bidding for frequency regulation and renewable integration services.
By revenue contribution, Residential leads. By project scale, Utility deployments are climbing the fastest.
Deployment:
Application maturity varies by grid infrastructure reliability and regulatory treatment of behind-the-meter assets across target geographies.
- On-Grid:AC coupled systems connected to utility distribution networks for net metering, self-consumption, and grid services participation. California, Germany, and Australia represent the three largest national markets for grid-tied residential retrofits.
- Off-Grid:Standalone systems without utility connection, typically paired with diesel generators for rural electrification.
- Microgrid:Campus-scale systems with multiple generation sources and islanding capability for resilience.
- Standalone:Single-purpose backup power installations without solar coupling.
By installation count, On-Grid leads. By resilience premium capture, Microgrid configurations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Australian households prioritize tariff arbitrage through retrofit installations, while German purchasers emphasize energy independence and backup resilience. California buyers respond to NEM 3.0 export rate collapse with self-consumption optimization.
United States
California's NEM 3.0 tariff restructuring eliminated net metering compensation, forcing 1.5 million existing solar households toward battery retrofits. The California Public Utilities Commission mandated time-of-use rate structures that reward self-consumption. Installer networks in Los Angeles and San Diego counties report AC coupled system inquiries tripling since April 2023.
Germany
Residential battery attachment rates exceeded 80% for new solar installations in 2024, with retrofit demand accelerating in Bavaria and Baden-Württemberg. The Bundesnetzagentur streamlined grid connection procedures for behind-the-meter storage under the EnWG framework. Munich and Stuttgart industrial clusters host inverter engineering centers serving Central European retrofit markets.
Australia
Queensland and South Australia combine 35-45 cent retail electricity tariffs with 30%+ rooftop solar penetration, creating the world's most favorable battery retrofit economics. The Australian Energy Market Commission's 2024 rule changes enabled faster grid connection approvals for AC coupled systems. Brisbane and Adelaide installer channels now process 40% of national battery retrofit volume.
Spain
The 2019 elimination of the "sun tax" on self-consumption unlocked retrofit demand among 4 million existing solar households. The Instituto para la Diversificación y Ahorro de la Energía extended subsidies for residential storage under the PERTE ERHA program. Andalusian and Valencian communities lead installation growth as solar cooperatives aggregate battery procurement.
China
Domestic demand concentrates in wealthy coastal provinces where grid instability and power rationing drive backup power investment. The National Energy Administration's 14th Five-Year Plan mandated energy storage deployment targets for distributed solar. Jiangsu and Zhejiang manufacturing clusters supply 60% of global battery inverter componentry.
AC Coupled Solar Battery System Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the AC coupled solar battery system market. Tesla and LG Energy Solution control cell-to-system manufacturing, while SMA Solar Technology and Enphase Energy anchor inverter engineering specialization. Three archetypes dominate: vertically integrated battery manufacturers, modular inverter specialists, and hybrid system integrators. Capacity expansion and installer channel consolidation represent the primary competitive moves as firms race to capture retrofit installation flows.
Within the integrated manufacturing tier, Tesla exemplifies the cell-to-system cost control archetype through its Nevada and Shanghai production complexes. SMA Solar Technology, a German Aktiengesellschaft, anchors European market presence through decades of inverter engineering heritage. Enphase Energy, a California-based corporation, represents the microinverter retrofit simplification strategy that reduces installation complexity on existing solar arrays.
| Leading Market Players |
|---|
| Tesla |
| SMA Solar Technology |
| Sungrow Power Supply |
| Enphase Energy |
| Huawei Technologies |
| LG Energy Solution |
| SolarEdge |
| Sonnen |
| Alpha ESS |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between cell manufacturers and inverter assemblers lock in lithium supply access and price visibility across eighteen-to-thirty-six month horizons, insulating residential system vendors from spot volatility in Australian and German procurement cycles.
Pricing Analysis
After-sales service contracts and extended warranty tiers drive lifetime value differentiation among residential AC coupled system vendors. Three-tier pricing structure across premium, standard, and economy levels stratifies by inverter efficiency certification and battery cycle life guarantees. Cost compression in economy-tier battery modules intensifies because Chinese cell oversupply is pressuring module integrators. Utility-scale EPC contractors exhibit highest price sensitivity, while German homeowners seeking energy independence show least.
Supply Chain Analysis
Inventory buffers for power semiconductor components stretch to sixteen-to-twenty-four weeks as IGBT and SiC module lead times remain elevated. Manufacturing concentrates in China, Taiwan, and South Korea for battery cells and power electronics. Raw material flows draw from Chilean lithium, Indonesian nickel, and Australian spodumene concentrate. Single-source vulnerability in Taiwanese wafer fabrication creates tariff exposure risk. Distribution runs through electrical wholesaler networks in Europe and installer-direct channels in Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward national electrical contractors consolidating regional installer networks, concentrating procurement volume among fewer downstream decision-makers.
For Market Incumbents: Shield retrofit market share through backward integration into battery cell production and exclusive certification partnerships with German TÜV Rheinland for AS/NZS 4777 compliance. Bi-directional EV charging substitution threatens standalone battery inverter demand. Channel control through captive installer financing programs represents the critical defensive lever. For New Entrants and Emerging Players: Installer training and remote commissioning support gaps in Spanish and Italian markets present white-space entry points. Spanish residential retrofits remain underexploited relative to solar penetration depth. Direct-to-consumer platform launches with automated system configurators offer the most penetrable go-to-market angle against established wholesaler relationships. For Investors and Strategic Acquirers: Capital is best deployed toward inverter engineering specialists with established grid-code certification libraries and VPP software integration capabilities. Long-term viability hinges on virtual power plant aggregation revenue streams displacing hardware-only margins. Watch California CPUC rate case proceedings as the inflection signal for self-consumption economics expansion or contraction.| Strategic Initiative | Industry Significance |
|---|---|
| Virtual Power Plant Software Integration | Enables household participation in Australian FCAS markets and California demand response programs. |
| LFP Cell Manufacturing Scale-Up | Captures cost advantage as residential cycle life requirements displace NMC alternatives. |
| Installer Certification Program Expansion | Accelerates Spanish and Italian market penetration through trained electrical contractor networks. |
| Grid-Forming Inverter Development | Qualifies systems for IEEE 1547-2018 compliance and European grid services revenue. |
| Battery Recycling Infrastructure Partnership | Anticipates EU Battery Regulation recycled content mandates for German and Spanish deployments. |
Research Methodology
The analysis maps inverter system, storage solution, hybrid system, and smart controller sub-sectors, each validated through battery procurement managers at EPC contractors, electrical contractor installation heads, utility distributed resource planners, and inverter product engineering directors. Primary interview insights triangulate against EIA battery storage databases, IEA renewable integration reports, AS/NZS 4777.2 certification registries, and California CPUC interconnection queue filings. Bottom-up installation volume estimates reconcile with top-down battery cell shipment data.
Consistency checks validate model outputs against external benchmarks including national renewable energy agency deployment statistics and grid operator behind-the-meter storage registration databases. The analytical framework segments by product type, battery chemistry, end-user category, and deployment configuration across the projection horizon. CAGRs derive from logistic adoption curves fitted to historical retrofit penetration rates and tariff structure elasticity assumptions. Forecast inputs incorporate NEM 3.0 rate impact modeling and Australian sunbelt retail tariff trajectories.
Forecasts assume regulatory continuity in California NEM structures, EU Electricity Market Reform implementation, and Australian AEMC connection rule frameworks; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Management System
EV Battery Management Market
Battery Management System
Automotive Energy Storage System Market
Battery Management System
DC Coupled Solar Battery System Market
Battery Management System
Electric Two-Wheeler Lithium-Ion Battery Management System Market
Battery Management System
Energy Storage Market
Battery Management System
Battery Fuel Gauge Market
Battery Management System
Battery Monitoring Unit Market
Battery Management System
India Stationary Battery Energy Storage System Market
Battery Management System
South America Battery Energy Storage System Market
Battery Management System
Automotive Lithium-Ion Battery Management System Market
Battery Management System
Renewable Battery Storage Market
Battery Management System
North America Battery Management System Market
Battery Management System
Smart Battery Maintainer Market
Battery Management System
Battery Systems for Electric Vehicle Market
Battery Management System
India Battery Energy Storage Systems Market
Battery Management System
Asia-Pacific Battery Energy Storage System Market