
 Marine Scrubber Market | 2026-2036
Marine Scrubber Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Scrubber Market Outlook
Buyer concentration among container shipping lines is expanding as fleet operators consolidate procurement decisions across larger vessel portfolios. Wärtsilä leverages its integrated power and propulsion platform to bundle scrubber offerings with engine service contracts. Alfa Laval anchors its position through extensive aftermarket service networks in major bunkering hubs. Yara Marine Technologies specializes in compact scrubber designs tailored to retrofit-constrained engine rooms.
Marine scrubbers are exhaust gas cleaning systems that remove sulfur oxides from vessel engine emissions through wet chemical absorption, typically achieving sulfur reduction from 3.5% to 0.1% fuel oil equivalent. These systems enable ship operators to continue burning high-sulfur fuel oil while complying with emission limits, avoiding premium low-sulfur fuel costs. Hybrid scrubber configurations now lead new order intake as operators seek operational flexibility between open-loop seawater and closed-loop alkali injection modes across varying port discharge regulations. Retrofit deployment commands the largest current revenue pool, though new installation attach rates rise with shipyard integration capabilities.
The International Maritime Organization's MARPOL Annex VI framework mandates sulfur oxide emission limits, while the EU MRV and FuelEU Maritime initiatives impose additional reporting and carbon intensity requirements on vessels calling at European ports. The US EPA enforces parallel emission control area standards through its diesel engine certification programs, creating overlapping compliance obligations for transoceanic operators. Stakeholders must monitor pending amendments to IMO greenhouse gas strategies that could redirect capital from scrubber investments toward alternative fuel propulsion systems.
Market Dynamics
Fleet operators now face a capital allocation pivot as MARPOL Annex VI enforcement tightens and alternative fuel pathways compete for scrubber retrofit budgets. The regulatory compliance window is compressing decision timelines across container shipping and bulk carrier segments.
Growth Catalysts
- IMO Sulfur Cap Enforcement:MARPOL Annex VI mandates drive scrubber installation on existing high-sulfur fuel oil fleets, particularly among Panamax and Capesize bulk carriers operating outside emission control areas.
- High-Sulfur Fuel Oil Price Arbitrage:The persistent cost gap between HSFO and very low sulfur fuel oil sustains scrubber payback economics for operators with heavy fuel consumption profiles.
- Hybrid System Flexibility:Dual-mode open-loop and closed-loop configurations allow vessels to switch between seawater scrubbing and alkali injection based on port discharge restrictions.
Market Restraints
- Corrosion-Resistant Alloy Supply:Super duplex stainless steel procurement bottlenecks from Nordic and Japanese metallurgical suppliers extend shipyard installation queues.
- Port Reception Facility Gaps:Inadequate washwater treatment infrastructure at secondary bunkering hubs limits open-loop scrubber operability and triggers regulatory non-compliance risk.
- Ammonia Fuel Substitution Threat:Accelerated ammonia dual-fuel engine development by MAN Energy Solutions and Wärtsilä redirects capital from exhaust treatment toward propulsion system replacement.
Strategic Opportunities
- Indonesia Archipelago Deployment:Domestic cabotage fleets serving Jakarta-Surabaya routes remain underpenetrated for scrubber retrofit as local shipyards develop installation capabilities.
- FuelEU Maritime Integration:The EU's carbon intensity index creates service contract bundling potential between scrubber maintenance and voyage optimization software providers.
- Digital Twin Convergence:Real-time exhaust monitoring systems paired with predictive washwater chemistry algorithms enable outcome-based service pricing models.
Industry Challenges
- Marine Chemist Certification Bottlenecks:Qualified washwater testing personnel shortages delay commissioning schedules at Singapore and Rotterdam service hubs.
- Legacy Engine Room Spatial Constraints:Pre-2010 vessel designs lack vertical clearance for vertical inline scrubber towers, forcing costly structural modifications or capacity-limited compact unit selection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Scrubber Market |
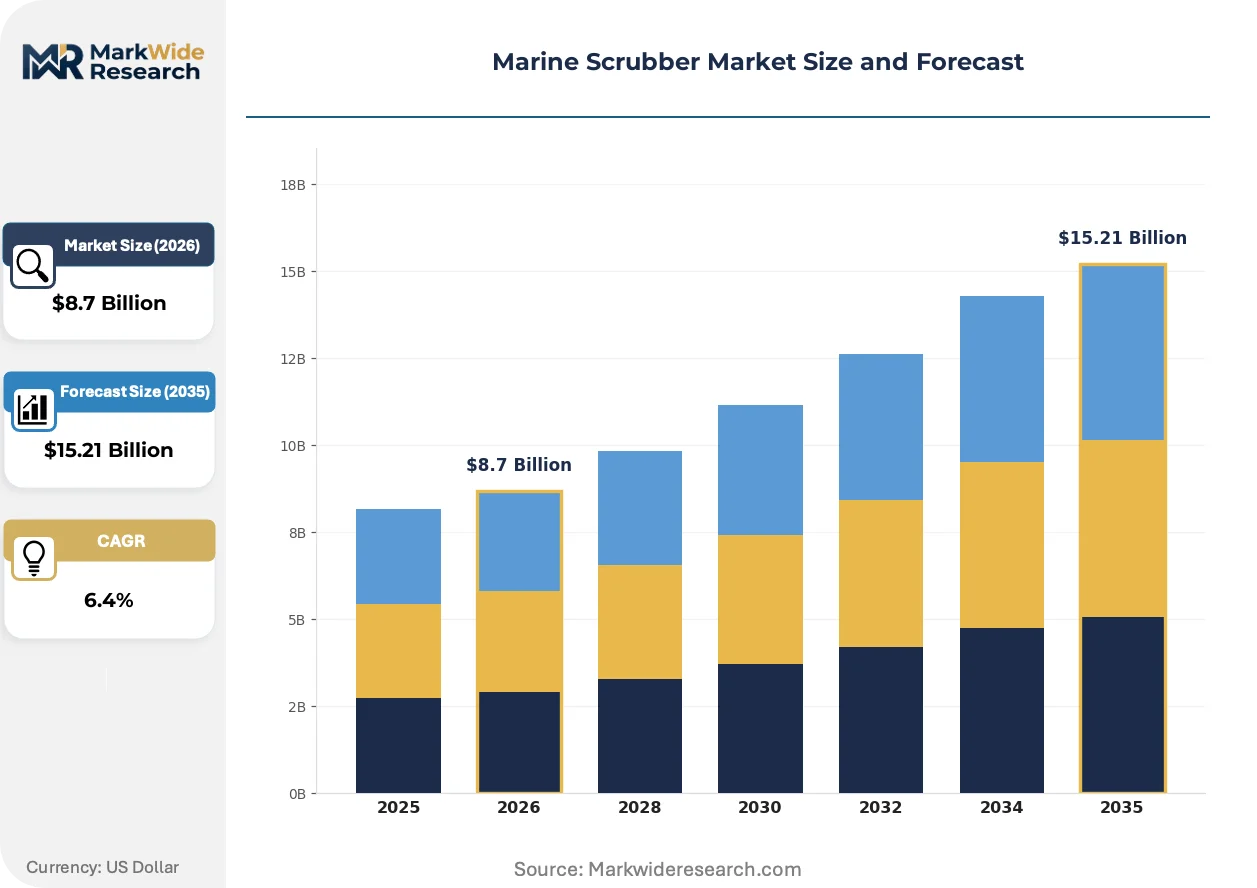
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Open Loop, Closed Loop, Hybrid, Others Technology: Alkali Injection, Seawater, Freshwater, Absorption Deployment: Onboard, Land-based, Retrofit, New Installation End User: Commercial Vessels, Cargo Ships, Tankers, Passenger Ships |
| Companies Covered | Alfa Laval, Wärtsilä, ANDRITZ, Mitsubishi Heavy Industries, Fuji Electric, Valmet, Yara Marine Technologies, CR Ocean Engineering, Kwang Sung, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Scrubber Market Strategic Shifts
Exhaust gas cleaning technology is bifurcating between mature wet scrubber optimization and emerging dry scrubber alternatives, while regulatory fragmentation across port states accelerates system complexity requirements.
Hybrid wet scrubber architecture is consolidating market preference as the dominant technology pathway for newbuild and retrofit applications. Container shipping lines with 10,000+ TEU vessels favor these dual-mode systems to maintain route flexibility between open-loop seawater operation on deep-sea legs and closed-loop alkali injection in restricted discharge zones. This configuration compression is reducing pure open-loop system order intake to niche coastal trades with predictable regulatory environments.
The EU FuelEU Maritime regulation is tightening carbon intensity benchmarks for vessels calling at European ports, creating overlapping compliance obligations with existing sulfur oxide limits. Ship operators must now balance scrubber capital deployment against alternative fuel investments that address both sulfur and greenhouse gas mandates. This regulatory layering most heavily affects Mediterranean short-sea shipping routes where vessels face multiple control regimes within single voyages.
Long-term service contracting is displacing transactional equipment sales as the dominant commercial model in major bunkering hubs. Fleet operators with 50+ vessel portfolios now negotiate ten-year maintenance and chemical supply agreements that bundle scrubber uptime guarantees with regulatory compliance certification. This shift is most pronounced among Greek and German shipowners operating Capesize bulk carriers on Brazil-China iron ore routes.
Marine Scrubber Market Segmentation
Scrubber procurement decisions diverge sharply across vessel types and operational profiles. Fleet operators weigh capital recovery timelines against route flexibility and port-state discharge restrictions when selecting system configurations.
Type:
Route predictability determines whether operators prioritize simplicity or operational hedging.
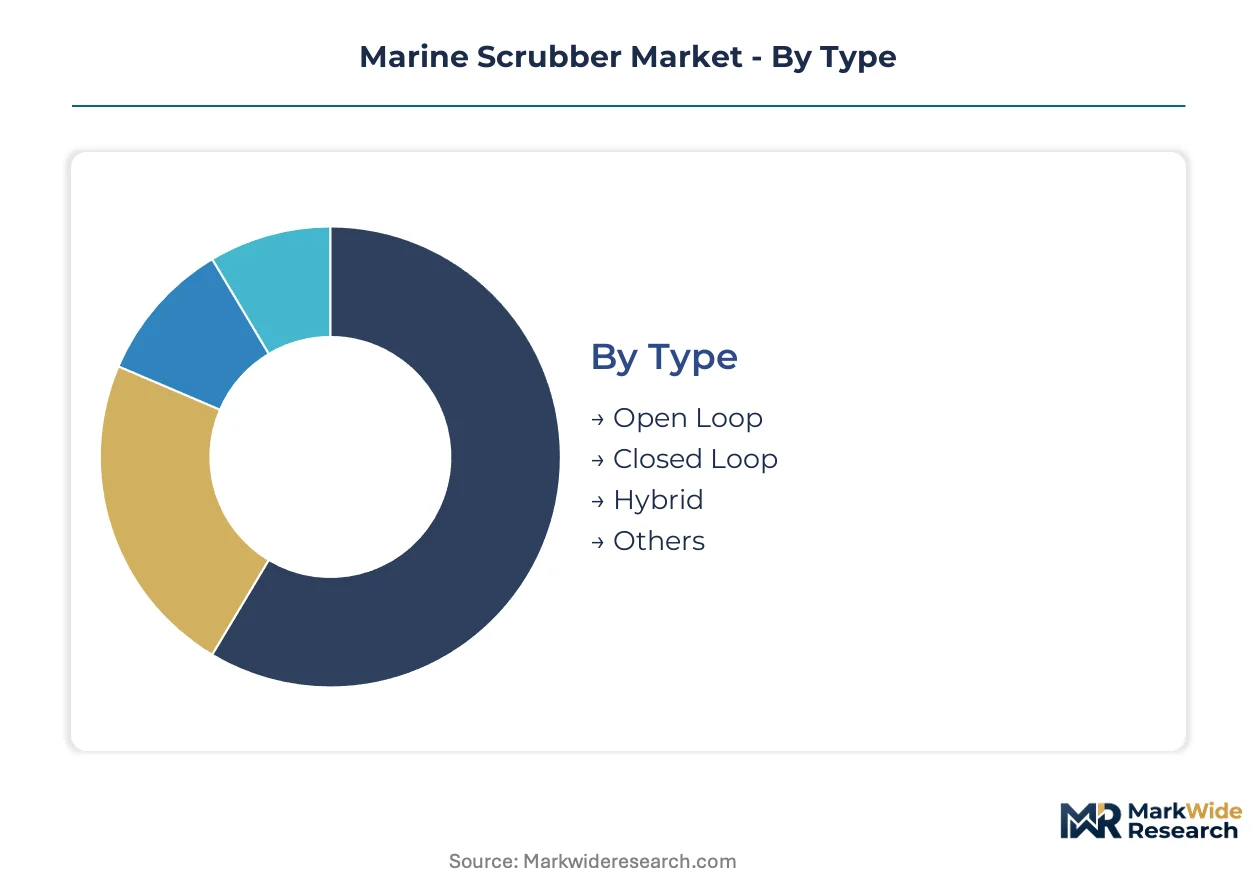
- Hybrid:Dual-mode architecture switches between open-loop seawater scrubbing and closed-loop alkali injection based on port discharge regulations. Container shipping lines operating Asia-Europe trades favor this configuration to maintain compliance flexibility across Singapore, Rotterdam, and Shanghai regulatory environments.
- Open Loop:Direct seawater contact systems offer lower capital cost and simpler maintenance for vessels on predictable deep-sea routes with limited emission control area exposure. Panamax bulk carriers on Brazil-China iron ore circuits concentrate demand where washwater discharge restrictions remain permissive.
- Closed Loop:Self-contained alkali circulation enables operation in zero-discharge zones but demands higher chemical logistics coordination.
- Others:Dry scrubber alternatives and emerging plasma treatment systems occupy niche applications in specialized vessel categories.
Volume sits with Open Loop; growth tilts toward Hybrid.
Technology:
Chemical handling infrastructure at bunkering hubs shapes technology adoption patterns.
- Seawater:Natural alkalinity extraction from continuous seawater flow eliminates chemical procurement complexity. Operators with established Singapore and Rotterdam port rotations favor this approach where reception facilities support open-loop discharge.
- Alkali Injection:Sodium hydroxide or magnesium oxide dosing achieves sulfur reduction independent of seawater chemistry. Mediterranean short-sea operators adopt this method to comply with overlapping EU MRV and port-state discharge bans.
- Freshwater:Distilled water circulation with chemical additive control suits vessels with limited engine room spatial tolerance.
- Absorption:Dry sorbent contact systems using lime or activated carbon address specialized retrofit constraints.
Seawater dominates installed base; alkali injection gains share fastest in regulated European trades.
Deployment:
Shipyard queue availability and vessel age profiles split capital allocation between newbuild and aftermarket channels.
- Retrofit:Installation aboard existing vessels commands the largest revenue pool as pre-2020 fleets face MARPOL Annex VI compliance deadlines. Greek and German shipowners with Capesize bulk carriers drive contract volume through ten-year service bundling agreements.
- New Installation:Factory-integrated systems at shipyards achieve cleaner spatial optimization and lower installation risk. Korean and Chinese shipbuilders attach scrubbers to 10,000+ TEU container vessel newbuilds with hybrid configurations as standard.
- Onboard:Modular skid-mounted units for vessels with severe engine room constraints.
- Land-based:Shore-side exhaust treatment for vessels at berth in ports with stringent emission control requirements.
Retrofit absorbs current spending; new installation attach rates climb with shipyard integration capabilities.
End User:
Fuel consumption intensity and route predictability segment buyer economics.
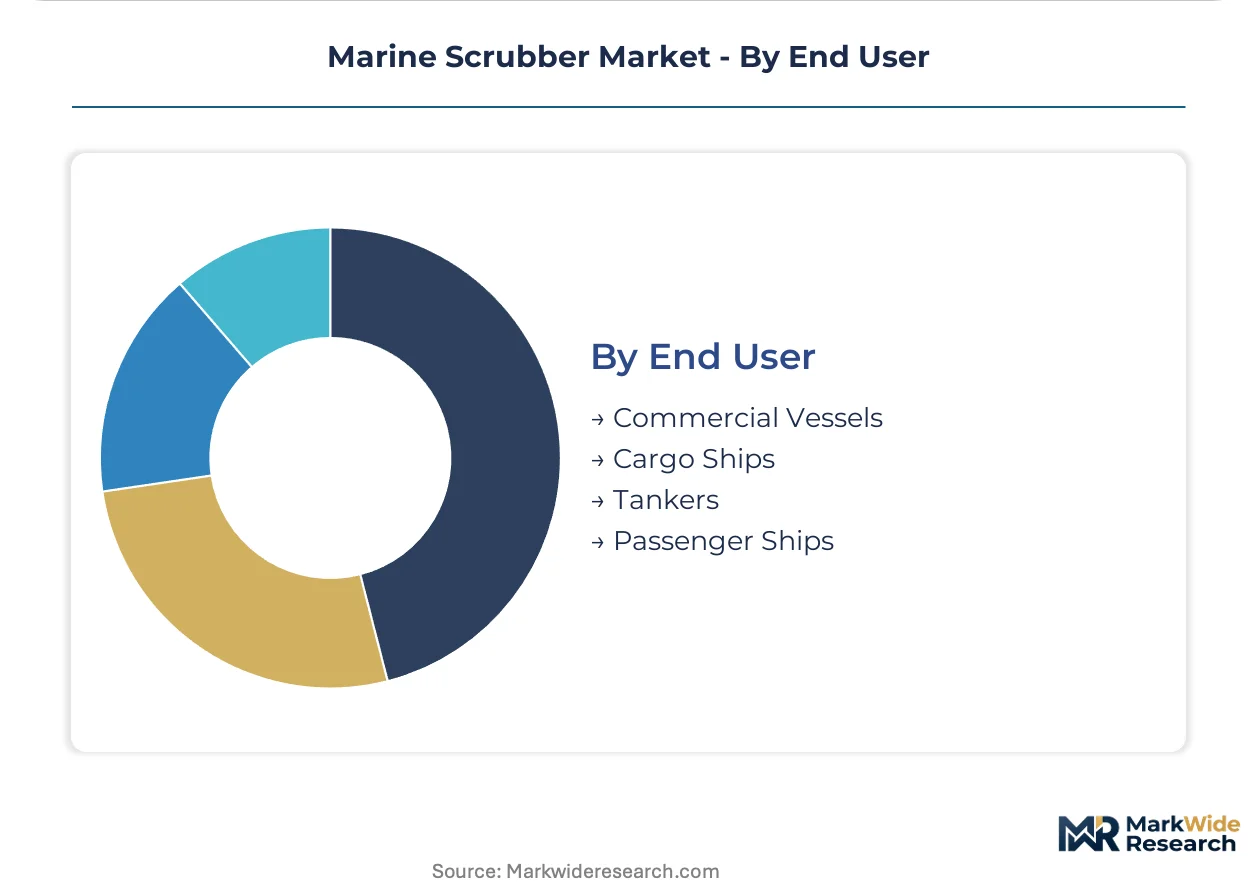
- Cargo Ships:Container lines with heavy fuel oil exposure and fixed liner schedules achieve scrubber payback through consistent high-sulfur fuel oil arbitrage. 10,000+ TEU vessels on Asia-Europe loops concentrate procurement decisions among consolidated fleet operators.
- Tankers:Crude oil and product tankers with variable voyage patterns favor hybrid flexibility to navigate disparate port-state regulations across Atlantic and Pacific basins.
- Commercial Vessels:General cargo and multipurpose vessels with fragmented ownership and lower utilization rates face compressed payback timelines.
- Passenger Ships:Cruise operators with high-profile environmental compliance exposure prioritize closed-loop systems in sensitive coastal zones.
Cargo ships anchor volume; tankers show steepest expansion trajectory as product carrier fleets retrofit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Container shipping lines and bulk carriers concentrate procurement decisions in port clusters where bunkering infrastructure supports scrubber installation and servicing at scale.
Singapore
The Maritime and Port Authority of Singapore enforces strict washwater discharge standards that favor hybrid scrubber configurations. Container vessels on Asia-Europe loops anchor demand at the Tuas mega-port development. Shipyards at Jurong and Sembcorp Marine facilities handle retrofit queues for Greek and German-owned Capesize fleets.
Netherlands
Rotterdam's reception facility network enables open-loop scrubber operation for Panamax bulk carriers on Brazil-China iron ore circuits. The Dutch Human Environment and Transport Inspectorate aligns with EU MRV reporting requirements. Waalhaven and Botlek industrial zones cluster aftermarket service providers for ten-year maintenance contracting.
China
Shanghai's Yangshan deep-water port drives newbuild scrubber attach rates on 10,000+ TEU vessels constructed at Jiangnan and Hudong-Zhonghua shipyards. The Ministry of Ecology and Environment implements emission control area standards along the Yangtze River Delta. Ningbo-Zhoushan port complex supplements installation capacity for domestic and international fleet operators.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries integrate hybrid scrubbers as standard equipment on ultra-large container vessels. The Korean Register of Shipping certifies compliance with MARPOL Annex VI amendments. Busan Newport Authority manages reception infrastructure for open-loop discharge in Korea Strait transit corridors.
Germany
Hamburg's port authority coordinates closed-loop scrubber operation for Mediterranean short-sea operators facing overlapping FuelEU Maritime obligations. The Federal Maritime and Hydrographic Agency enforces stringent washwater monitoring protocols. Bremerhaven and Wilhelmshaven service hubs support North Atlantic container line fleets with chemical logistics coordination.
Marine Scrubber Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue compact retrofit solutions for engine-room-constrained vessels. The vendor base stratifies between integrated power system bundlers and standalone exhaust treatment specialists. Three archetypes dominate: full-service platform providers anchoring long-term service contracts, compact design specialists targeting spatial constraints, and regional fabricators serving secondary bunkering hubs. Competitive moves concentrate on strategic partnerships for aftermarket chemical supply and geographic expansion into underpenetrated archipelago trades.
Among Nordic integrated platform providers, Wärtsilä and Alfa Laval exemplify the full-service archetype through bundled power and propulsion offerings. Yara Marine Technologies occupies a position within the compact specialization tier. ANDRITZ, Valmet, and Mitsubishi Heavy Industries represent diversified industrial conglomerates with cross-sector pollution control capabilities. Fuji Electric and CR Ocean Engineering sit within the regional fabrication segment serving Pacific Basin and North American retrofit demand respectively.
| Leading Market Players |
|---|
| Alfa Laval |
| Wärtsilä |
| ANDRITZ |
| Mitsubishi Heavy Industries |
| Fuji Electric |
| Valmet |
| Yara Marine Technologies |
| CR Ocean Engineering |
| Kwang Sung |
| Others |
Value Chain & Pricing Dynamics
MARPOL Annex VI certification tiers gate both qualified supply and premium-tier pricing access for marine scrubber manufacturers, bifurcating the vendor base between full-service platform providers commanding long-term service premiums and regional fabricators competing on equipment-only transactions. This regulatory filtering concentrates pricing power among Nordic and Japanese metallurgical suppliers while compressing margins for second-tier installers lacking shipyard integration capabilities.
Pricing Analysis
Volume sits with standardized open-loop systems while margins concentrate in hybrid configurations bundled with ten-year chemical supply contracts. Price differentiation separates IMO-certified full-service providers from uncertified regional fabricators, with after-sales service bundling representing the primary margin expansion lever. Pricing pressure stems from ammonia dual-fuel engine development redirecting capital away from exhaust treatment investments. Container shipping lines with consolidated 50-plus vessel portfolios exhibit lowest price sensitivity due to fuel arbitrage payback certainty, while fragmented general cargo operators face compressed procurement timelines.
Supply Chain Analysis
Super duplex stainless steel supply rests on Nordic and Japanese specialty metallurgical producers, with sodium hydroxide and magnesium oxide chemical sourcing anchored in German and Chinese industrial chemical networks. Raw material dependencies include corrosion-resistant alloys, alkali reagents, and specialized pump components. Single-source vulnerability concentrates in super duplex procurement queues extending shipyard installation timelines. Distribution runs through major bunkering hub service networks in Singapore, Rotterdam, and Shanghai, with aftermarket chemical logistics coordinated via port-adjacent storage facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine scrubber vendors face a vertical-integration race into alkali chemical supply and predictive maintenance software, with service contract bundling emerging as the decisive margin lever against propulsion technology substitution threats.
For Market Incumbents: Extend long-term service contract coverage to capture chemical logistics coordination revenue currently leaking to third-party suppliers. Lock in exclusive alkali supply agreements with Mediterranean and Southeast Asian port storage operators before regional competitors consolidate reception infrastructure. Ammonia dual-fuel engine development by MAN Energy Solutions and Wärtsilä threatens scrubber retrofit capital allocation; defend position through outcome-based uptime guarantees tied to FuelEU Maritime compliance certification. For New Entrants and Emerging Players: Capture Indonesia archipelago cabotage fleet retrofit demand as domestic shipyards develop installation capabilities for Jakarta-Surabaya route vessels. Target compact scrubber designs for pre-2010 vessels lacking vertical clearance for standard tower configurations, where spatial constraints force costly structural modifications or capacity-limited unit selection. Go-to-market angle: modular skid-mounted systems with rapid commissioning protocols bypassing marine chemist certification bottlenecks. For Investors and Strategic Acquirers: Accelerated ammonia engine order intake at Korean and Chinese shipyards is the leading indicator that scrubber retrofit capital is redirecting toward propulsion replacement, compressing the viable investment window for pure-play exhaust treatment exposure. Target acquisition archetype: compact design specialists with proven retrofit installation protocols for engine-room-constrained vessels, where technical differentiation sustains pricing power against commoditized open-loop competition. Watch IMO greenhouse gas strategy amendments as the signal for long-term scrubber demand trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alkali Chemical Supply | Captures chemical logistics margins currently extracted by third-party reagent suppliers at Rotterdam and Singapore hubs. |
| Digital Twin Platform Development | Enables predictive washwater chemistry algorithms supporting outcome-based service pricing for Greek and German Capesize operators. |
| Indonesia Archipelago Expansion | Establishes first-mover installation capability in domestic cabotage fleets serving Jakarta-Surabaya routes before regional shipyard competition intensifies. |
| FuelEU Maritime Compliance Bundling | Positions scrubber maintenance contracts within integrated carbon intensity management offerings for Mediterranean short-sea operators. |
| Compact Retrofit System R&D | Addresses legacy engine room spatial constraints limiting standard vertical tower deployment on pre-2010 vessel designs. |
Study Parameters
IMO regulatory filings, Lloyd's List vessel equipment databases, and MARPOL Annex VI compliance records formed the secondary backbone, cross-referenced against primary interviews with fleet technical superintendents, shipyard project managers, and marine chemist certification bodies. Shipowner procurement directors at Greek and German Capesize operators, alongside chemical supply coordinators at Rotterdam and Singapore bunkering hubs, provided operational validation. Bottom-up installation volume data triangulated against top-down fleet compliance requirement modeling.
Bottom-up vessel-by-vessel retrofit pipeline analysis anchored the analytical lens, with top-down IMO enforcement timeline scenarios providing boundary conditions across the projection horizon. Segmentation dimensions modeled include scrubber type configuration, technology chemistry, deployment channel, and end-use vessel category, with regional regulatory cluster intensity applied as a cross-cutting modifier. CAGRs derived from installation queue visibility at major shipyards and chemical consumption trajectory at bunkering hubs, with fuel price arbitrage spreads and alternative fuel engine development pace serving as scenario-weighting inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to IMO greenhouse gas strategy amendments and ammonia dual-fuel engine commercialization pace that could redirect capital from scrubber investments. Forecasts reflect documented assumptions regarding MARPOL Annex VI enforcement consistency, super duplex alloy supply normalization, and port reception facility buildout timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Oman Oil and Gas Downstream Market
Offshore Oil and Gas
Enhanced Oil Recovery Market
Offshore Oil and Gas
Brazil Offshore Energy Market
Offshore Oil and Gas
Europe LNG Bunkering Market
Offshore Oil and Gas
Gulf of Mexico Oil & Gas Decommissioning Market
Offshore Oil and Gas
India Oil and Gas Downstream Market
Offshore Oil and Gas
United Kingdom Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Equatorial Guinea Oil and Gas Midstream Market
Offshore Oil and Gas
Middle East Offshore MRO Market
Offshore Oil and Gas
North Sea Oil and Gas Market
Offshore Oil and Gas
North America FLNG Market
Offshore Oil and Gas
Denmark Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Denmark Oil and Gas Market
Offshore Oil and Gas
Asia-Pacific Floating Offshore Wind Power Market
Offshore Oil and Gas
United Kingdom LNG Bunkering Market
Offshore Oil and Gas
Asia-Pacific Floating Production Systems Market